
 Two Wheeler Crash Guard Market | 2026-2036
Two Wheeler Crash Guard Market Size, Share, and Industry Trends Forecast 2026-2036
Two Wheeler Crash Guard Market Analytics
Aftermarket subscription-based protection packages and software-integrated crash detection services are hardening into a distinct revenue layer beyond hardware sales. AltRider leverages its premium positioning in adventure touring segments to sustain higher margins on expedition-grade guards. Zana International Pvt Ltd anchors South Asian supply chains through extensive distributor networks across India and neighboring markets. Aadit Industries specializes in cost-efficient steel variants that dominate fleet procurement channels for delivery services.
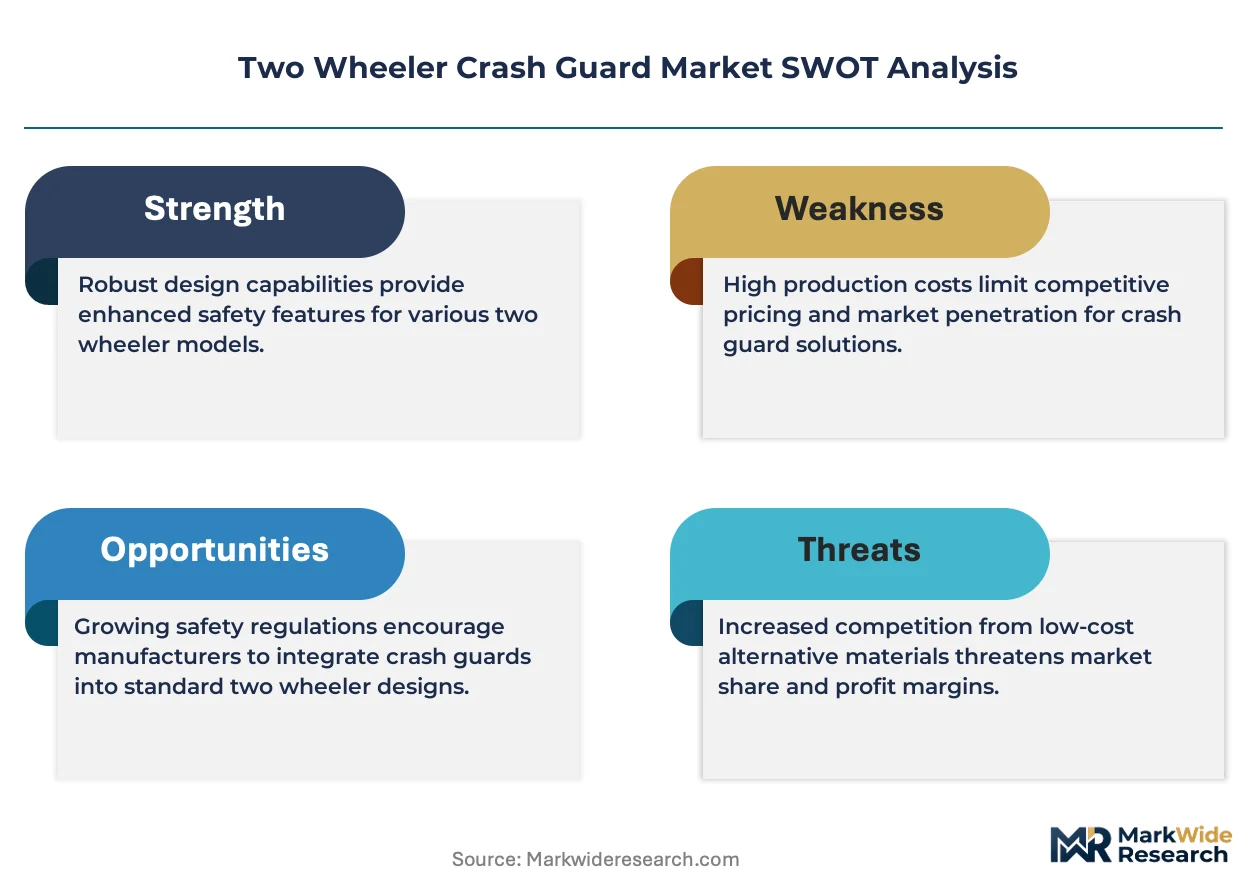
A two-wheeler crash guard is a protective frame-mounted barrier, typically fabricated from tubular steel, extruded aluminum, or fiber-reinforced polymer composites, engineered to absorb impact energy and shield critical components such as engines, fairings, and fuel tanks during low-speed collisions or tip-over events. The device serves commercial and consumer applications by reducing repair costs, minimizing downtime for fleet operators, and satisfying insurer requirements for reduced premium exposure. Steel frame guards occupy the largest volume share due to their durability and repairability, though aluminum and composite materials represent the fastest-expanding category as OEMs pursue weight reduction targets. Custom and sporty design configurations command premium positioning among enthusiast segments, while standard minimalistic variants capture bulk orders from delivery services and rental operators seeking fleet uniformity.
India's BIS mandates crash guard dimensional and load-bearing standards for aftermarket fitment, while Brazil's ANVISA coordinates with transit authorities on accessory safety notifications for commercial two-wheeler operators. The EU's REACH framework governs surface coating chemistries on metal guards exported into European markets, adding compliance cost layers for Asian manufacturers. Stakeholders must monitor evolving material certification requirements and fleet electrification timelines, as electric two-wheeler chassis architectures demand redesigned mounting geometries and impact load distributions that legacy guard platforms cannot accommodate.
Market Dynamics
India's BIS certification mandate for two-wheeler safety accessories is compressing supply-side fragmentation by disqualifying uncertified fabricators, forcing capital investment into testing infrastructure and standardized load-bearing geometries.
Growth Catalysts
- Steel durability preference:Fleet operators in Brazil prioritize tubular steel guards for repairability and extended service intervals, sustaining volume demand despite weight penalties.
- ANVISA safety coordination:Brazil's health and transit authority alignment on commercial two-wheeler accessory notifications creates compliance clarity that accelerates fleet upgrade cycles.
- Aluminum-composite hybridization:Material innovation targeting OEM weight reduction specifications is opening premium positioning channels previously dominated by steel fabricators.
Market Restraints
- Aluminum price volatility:Input cost swings for extruded aluminum profiles compress margin buffers for mid-tier fabricators lacking long-term supply contracts.
- REACH coating compliance:EU surface chemistry regulations add certification layers and testing expenditure for Asian exporters targeting European aftermarket channels.
- Electric chassis incompatibility:Legacy guard mounting geometries fail to accommodate battery placement and revised impact load paths on emerging electric two-wheeler platforms.
Strategic Opportunities
- Vietnam manufacturing expansion:Underpenetrated assembly capacity in Southeast Asian clusters offers cost-advantaged export positioning for India and Thailand distributors.
- Software-integrated detection:Convergence of impact sensors with telematics platforms enables subscription-based damage alerting services beyond hardware margins.
- PLI scheme leverage:India's production-linked incentive framework for auto components subsidizes capital equipment for certified safety accessory manufacturers.
Industry Challenges
- Homologation timeline compression:BIS testing queue congestion delays product launch windows, requiring parallel certification investments across multiple facilities.
- Weld qualification scarcity:Certified aluminum TIG welders command premium wages, constraining capacity expansion for hybrid material fabricators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Two Wheeler Crash Guard Market |
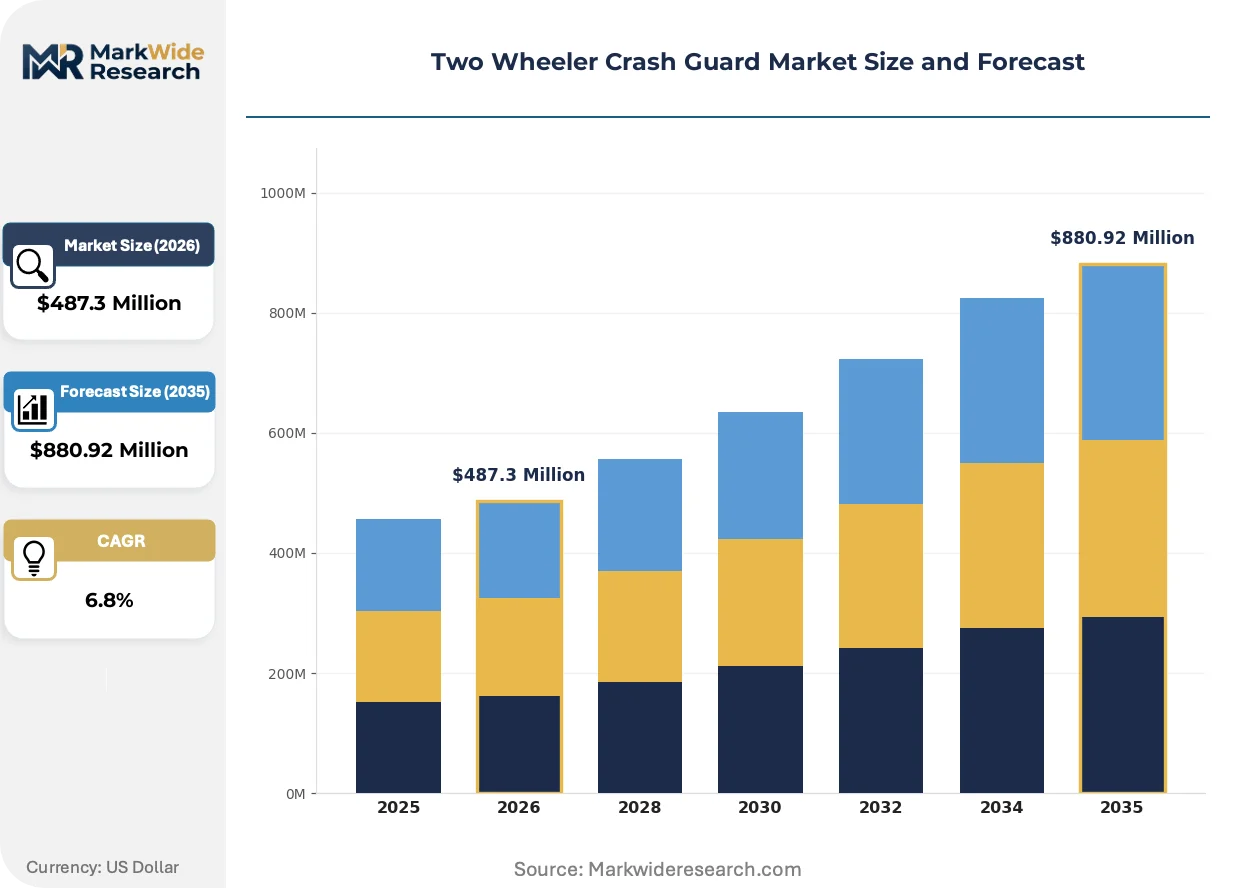
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $880.92 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Frame Guard, Engine Guard, Side Support, Bumper Guard Material: Steel, Aluminum, Plastic, Composite Design: Standard, Custom, Sporty, Minimalistic End User: Motorcycle Owners, Delivery Services, Rentals, Enthusiasts |
| Companies Covered | AltRider, Zana International Pvt Ltd, Aadit Industries, Hogworkz, Lincoln Industries, Kuryakyn, Cobra USA, LEMANS Corporation, Outback Motortek, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Two Wheeler Crash Guard Market Evolving Landscape
Material substitution and regulatory tightening are compressing traditional supply hierarchies while creating openings for integrated hardware-software protection platforms. Three developments merit particular attention.
Aluminum-composite hybrid crash guards are consolidating market positioning across premium motorcycle segments. These structures combine extruded aluminum load-bearing members with fiber-reinforced polymer impact surfaces to achieve weight reductions exceeding pure steel alternatives. Adventure touring manufacturers and high-performance OEMs are adopting hybrid configurations at accelerating rates, compressing the addressable market for conventional tubular steel fabricators unable to retool for multi-material bonding processes.
REACH surface coating protocols are reshaping export economics for Asian manufacturers. The EU framework restricts hexavalent chromium and specific solvent-based finishes on metal guards entering European markets, forcing reformulation of pretreatment and topcoat chemistries. Indian and Chinese fabricators serving EU distributors are responding by relocating finishing operations to certified third-party facilities or investing in compliant in-house powder coating lines, adding per-unit cost but preserving market access.
Fleet procurement centralization is displacing fragmented dealer-channel purchasing for commercial two-wheeler operators. Delivery services and rental platforms in São Paulo, Jakarta, and Bangalore are consolidating guard procurement through direct manufacturer contracts with standardized specifications and volume pricing. This channel compression squeezes traditional aftermarket distributors while rewarding fabricators with certified production scale and logistics integration capabilities.
Two Wheeler Crash Guard Market Segmentation
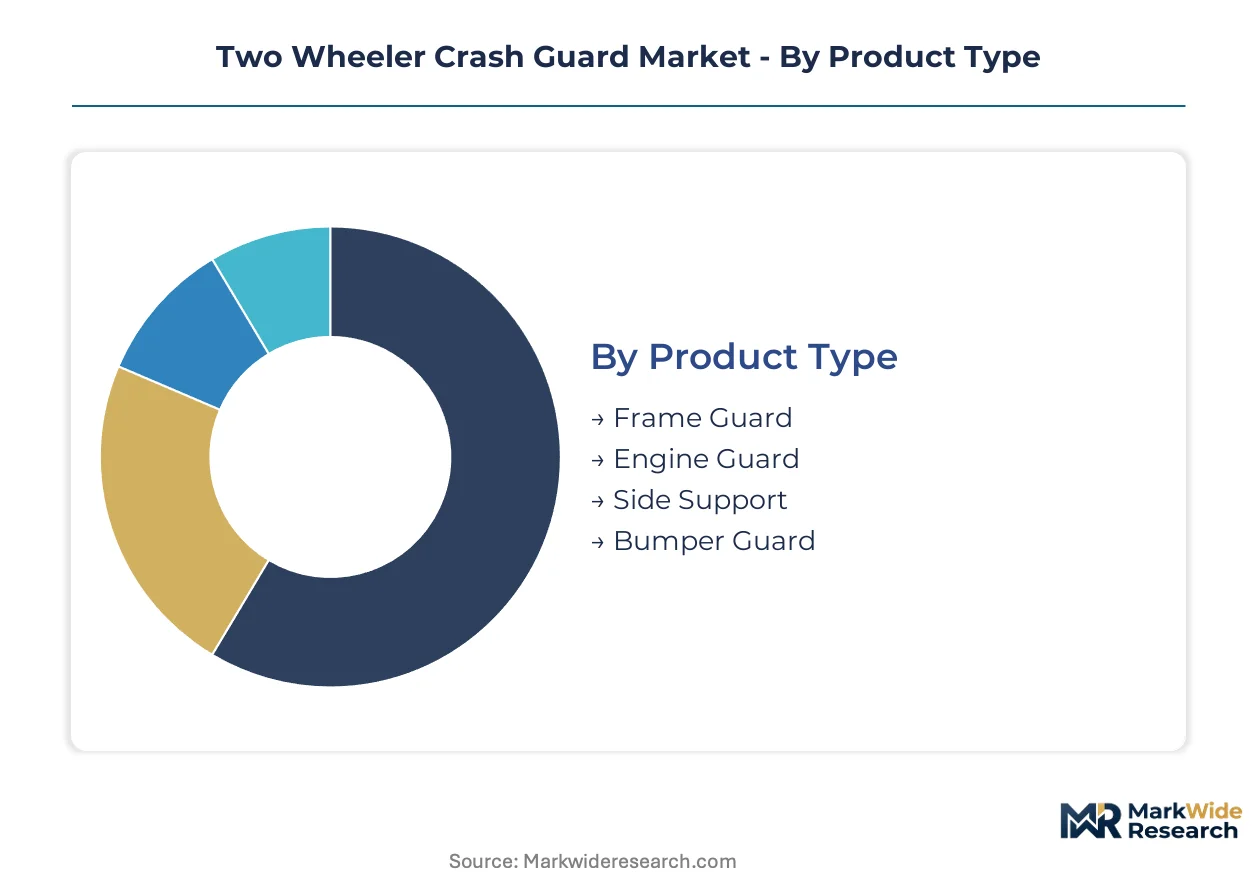
Crash guard purchasing splits sharply between fleet buyers demanding standardized, repairable configurations and individual owners seeking aesthetic differentiation. Understanding these divides clarifies where margin pools concentrate versus where volume scales.
Product Type:
Customization-to-standardization tension runs strongest here, with fleet procurement favoring modular, interchangeable geometries while enthusiast segments demand integrated, model-specific fitments.
- Frame Guard:Tubular structures mounted to the main chassis rails absorb primary impact loads during tip-over events. Delivery fleets in São Paulo and Jakarta specify frame guards with standardized mounting brackets to simplify field repairs and reduce parts inventory. BIS load-testing mandates for frame-mounted accessories compress supplier qualification timelines.
- Engine Guard:Lower-positioned barriers shield crankcases and oil pans from road debris and collision contact. Adventure touring motorcycle owners in India and Thailand prioritize engine guards with integrated skid plates for unpaved surface protection. ANVISA safety notifications for commercial operators accelerate replacement cycles on engine-damaged fleet units.
- Side Support:Lateral stabilizers prevent low-speed drops from reaching critical lean angles. Rental operators specify side support configurations with quick-release mechanisms for parking convenience.
- Bumper Guard:Front-mounted impact surfaces protect fairings and headlight assemblies. Urban commuter segments in dense Southeast Asian traffic favor bumper guards with integrated turn signal relocation.
Most installed capacity flows through Frame Guard. Expansion is steepest in Engine Guard.
Material:
Cost tier stratification dominates material selection, with procurement budgets determining whether durability premiums justify weight and corrosion trade-offs.
- Steel:Carbon and alloy tubular constructions deliver maximum impact absorption and field weldability. Brazilian fleet operators anchor procurement on steel variants for extended service intervals and roadside repair capability. Input price stability relative to aluminum sustains volume contracts for mid-tier fabricators.
- Aluminum:Extruded and cast aluminum profiles achieve weight reductions critical for OEM fuel efficiency targets. Premium motorcycle manufacturers in India specify aluminum guards with hybrid composite impact surfaces to meet BIS dimensional standards without steel mass penalties. REACH coating compliance adds finishing cost layers for EU-bound exports.
- Plastic:Injection-molded polymer guards serve cost-sensitive replacement markets with limited load-bearing requirements. Southeast Asian aftermarket channels stock plastic variants for scooter segments.
- Composite:Fiber-reinforced polymer and carbon fiber configurations target hyper-premium segments with strength-to-weight optimization. Electric two-wheeler startups specify composite guards for battery protection with minimal range impact.
Steel commands the largest production footprint. Aluminum-composite hybridization is gaining share fastest.
Design:
Customer type segmentation directly determines design complexity, with procurement centralization favoring stripped-down geometries and enthusiast channels rewarding aesthetic differentiation.
- Standard:Universal-fit geometries with adjustable mounting hardware serve multi-model fleet deployments. Rental platforms in Bangalore and São Paulo specify standard designs to eliminate model-year compatibility headaches.
- Custom:Model-specific fabrications with integrated lighting mounts, luggage attachment points, or color-matched finishes. Adventure touring specialists commission custom guards with expedition-grade protection ratings.
- Sporty:Aerodynamic profiles with minimal frontal area for performance motorcycles. Enthusiast segments in Thailand prioritize sporty configurations that preserve lean angles.
- Minimalistic:Reduced-coverage guards meeting regulatory minimums with lowest unit cost. Delivery services deploying high-turnover vehicle pools favor minimalistic designs for procurement efficiency.
Standard designs absorb the heaviest procurement volumes. Custom configurations carry the steepest margin premiums.
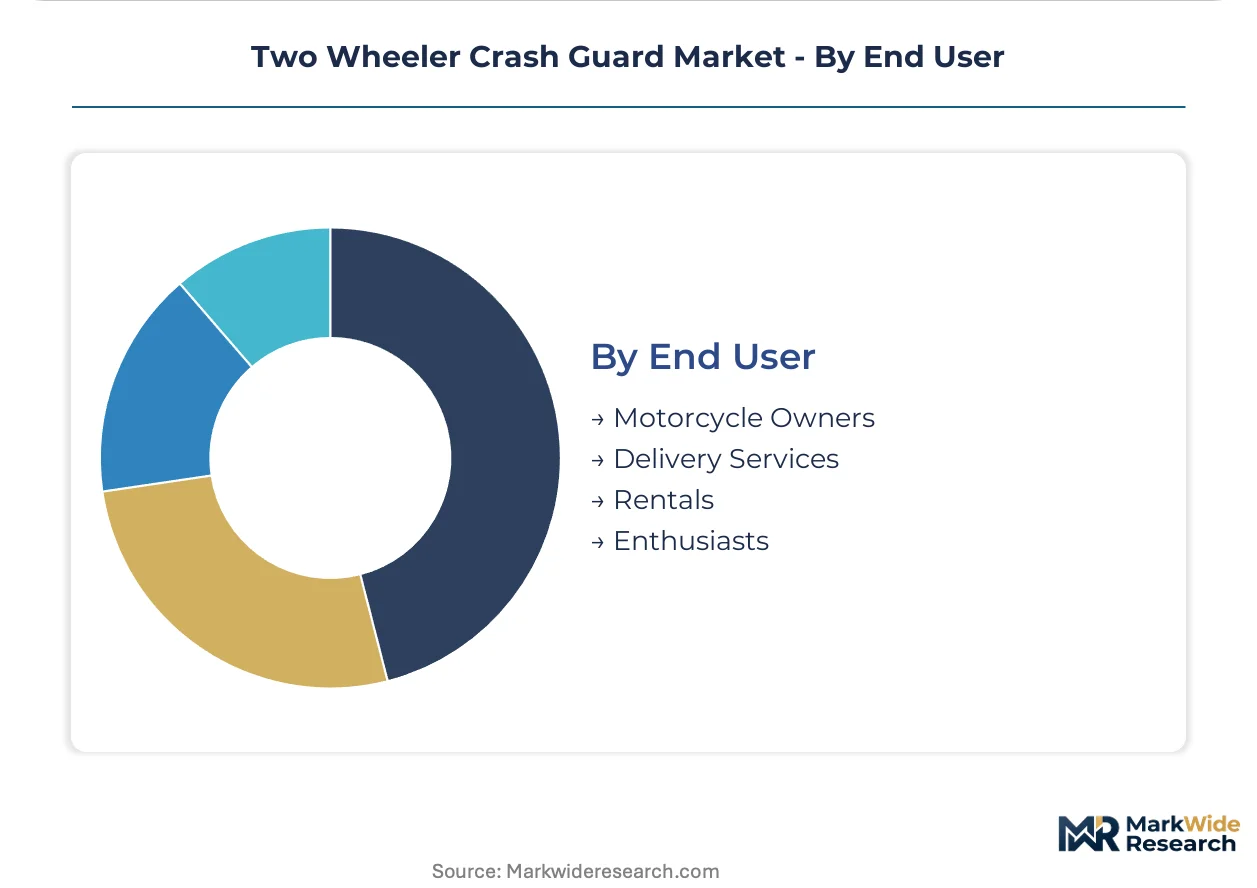
End User:
Application context separates repair-cost-minimizing commercial operators from protection-premium-paying individual owners.
- Motorcycle Owners:Individual purchasers balancing aesthetic preferences with insurance premium reduction incentives. Indian owners navigating BIS-certified aftermarket channels face compressed supplier options.
- Delivery Services:Fleet operators with centralized procurement, standardized specifications, and volume pricing leverage. Last-mile logistics platforms in Jakarta and São Paulo consolidate guard purchasing through direct manufacturer contracts.
- Rentals:High-utilization operators prioritizing damage containment and rapid turnaround. Shared mobility services specify guards with quick-release features for maintenance efficiency.
- Enthusiasts:Performance and adventure segments demanding expedition-grade protection with premium positioning. Touring communities in India and Thailand drive specification complexity for remote-terrain readiness.
Delivery Services channel the greatest procurement tonnage. Enthusiast segments generate the highest per-unit margins.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India commands the largest installed base of two-wheeler crash guard fabrication capacity, while Brazil's fleet upgrade cycles accelerate faster due to ANVISA safety coordination. Southeast Asian manufacturing clusters in Vietnam and Thailand are capturing export share through cost-advantaged assembly positioning.
India
BIS certification mandates for aftermarket safety accessories compress supplier qualification timelines and disqualify uncertified fabricators. The PLI scheme subsidizes capital equipment for certified manufacturers, accelerating consolidation toward standardized production. Manufacturing clusters in Pune and Chennai concentrate frame guard fabrication for domestic fleet operators and export channels.
Brazil
Delivery fleet operators in São Paulo prioritize tubular steel guards for field repairability and extended service intervals. ANVISA coordinates with transit authorities on commercial two-wheeler accessory safety notifications, creating compliance clarity that accelerates replacement cycles. Fabrication capacity concentrates in São Bernardo do Campo and surrounding ABC Paulista industrial zones.
Vietnam
Underpenetrated assembly capacity offers cost-advantaged export positioning for India and Thailand distributors seeking supply chain diversification. The country's national standards body governs dimensional specifications for safety accessories entering regional markets. Ho Chi Minh City and Binh Duong Province anchor emerging fabrication clusters serving ASEAN distribution networks.
Thailand
Adventure touring motorcycle owners drive specification complexity for engine guards with integrated skid plate protection. The country's industrial standards institute maintains alignment with ASEAN harmonized technical regulations for vehicle accessories. Manufacturing activity concentrates in Rayong and Chonburi provinces within the Eastern Economic Corridor.
Indonesia
Rental operators in Jakarta consolidate guard procurement through direct manufacturer contracts with standardized specifications and volume pricing. The national standardization agency implements load-bearing test protocols for frame-mounted accessories. Bekasi and Tangerang industrial zones host fabrication facilities serving domestic fleet operators and re-export channels.
Two Wheeler Crash Guard Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with premium positioning concentrated among adventure touring specialists and volume scale dominating fleet procurement channels. The vendor base organizes into three tiers: certified fabricators serving OEM supply chains, aftermarket specialists with distributor network depth, and unbranded contract manufacturers competing on unit economics. Two competitive moves define current positioning: geographic expansion into underpenetrated Southeast Asian assembly clusters, and portfolio diversification toward aluminum-composite hybrid configurations that satisfy weight reduction specifications.
Among India-based fabricators, Zana International Pvt Ltd and Aadit Industries occupy positions reflecting divergent strategic archetypes. Zana International Pvt Ltd exemplifies the distributor-network-anchored model with extensive coverage across South Asian markets. Aadit Industries represents the cost-efficient steel specialist serving centralized fleet procurement channels. AltRider sits within the premium-tier adventure touring segment, sustaining higher margin positioning through expedition-grade specifications.
| Leading Market Players |
|---|
| AltRider |
| Zana International Pvt Ltd |
| Aadit Industries |
| Hogworkz |
| Lincoln Industries |
| Kuryakyn |
| Cobra USA |
| LEMANS Corporation |
| Outback Motortek |
| Others |
Value Network & Pricing Analysis
Aluminum-composite hybrid fabrication methods are simultaneously compressing per-unit material costs and concentrating production among fabricators with multi-material bonding capabilities. BIS certification mandates in India and REACH compliance requirements for EU exports are forcing capital investments that favor scaled manufacturers over fragmented job shops, reshaping where pricing power accumulates.
Pricing Analysis
Capacity additions in Vietnam are reshaping price floors for standard steel frame guards serving Southeast Asian fleet operators. Three-tier pricing structure across premium, standard, and economy levels separates expedition-grade aluminum-composite hybrids from certified steel variants and uncertified economy imports. Price differentiation hinges on BIS certification status and volume procurement scale, with delivery services extracting steepest discounts through centralized contracts. Cost compression in the economy tier is intensifying because Indonesian and Vietnamese contract manufacturers are expanding tubular steel welding capacity.
Supply Chain Analysis
Direct-to-fleet channels handle hyperscale buyer demand from delivery platforms in São Paulo, Jakarta, and Bangalore. Manufacturing concentrates in India, Brazil, and Vietnam, with raw material sourcing drawing from Chinese aluminum extruders, Indian alloy steel producers, and Southeast Asian polymer composite suppliers. Single-source vulnerability runs through certified TIG welding labor pools, where qualified technicians command premium wages. Distribution runs through OEM accessory programs, aftermarket distributor networks, and direct manufacturer contracts with rental operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate among certified fabricators capturing aluminum-composite hybrid premiums, while cost-down pressure from Vietnamese assembly expansion compresses returns for undifferentiated steel specialists.
For Market Incumbents: Acquire certified testing infrastructure to compress BIS homologation timelines and defend against Southeast Asian cost competitors. Secure captive supply of extruded aluminum profiles through long-term offtake agreements with Chinese and Indian smelters. Expand in-house powder coating lines to preserve EU market access under REACH surface chemistry protocols. For New Entrants and Emerging Players: Fleet procurement managers represent the most penetrable channel partner type for uncertified fabricators seeking volume scale. Target Vietnam-based assembly for cost-advantaged export positioning into India and Thailand distribution networks. Pursue white-label manufacturing contracts with delivery platforms seeking direct sourcing relationships. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-tier steel fabricators lacking aluminum-composite hybrid capabilities or BIS certification. Long-term viability favors certified manufacturers with integrated finishing operations and fleet logistics partnerships. Watch electric two-wheeler platform launches as the inflection signal for guard redesign demand.| Strategic Initiative | Industry Significance |
|---|---|
| Aluminum-Composite Hybrid Platform Development | Enables BIS-compliant weight reduction for premium motorcycle OEM supply chains. |
| REACH-Compliant Finishing Line Investment | Preserves EU aftermarket access as surface chemistry regulations tighten. |
| Direct Fleet Procurement Contracting | Bypasses distributor margins for delivery services in São Paulo and Jakarta. |
| Vietnam Manufacturing Footprint Expansion | Captures cost advantages for export positioning into ASEAN distribution networks. |
| Software-Integrated Impact Detection Launch | Creates subscription revenue layer beyond hardware margins for rental operators. |
Research Methodology
Coverage spans India, Brazil, Vietnam, Thailand, and Indonesia, with primary inputs from each market cluster. The research combines structured interviews with fabrication plant managers, fleet procurement directors at delivery platforms, aftermarket distributor principals, and BIS certification auditors with secondary validation from customs trade data, vehicle production databases, and national standardization agency filings. Bottom-up volume estimates from certified manufacturer capacity and top-down demand triangulation from fleet operator procurement disclosures were reconciled.
Rate-of-change decomposition separates volume growth from value growth across the projection horizon. The analytical framework models segmentation dimensions including material tier, product type, design complexity, and end-user category alongside electric two-wheeler platform compatibility as an industry-specific dimension. CAGRs were derived from fitted trend analysis of historical procurement patterns and regulatory implementation timelines, incorporating BIS certification queue dynamics and ANVISA safety notification cycles as forecast inputs.
Revisions become necessary when electric two-wheeler platform architectures materially alter chassis mounting specifications or when BIS testing capacity constraints extend homologation timelines beyond modeled assumptions. Forecasts reflect documented assumptions regarding aluminum price stability and fleet electrification penetration rates. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Safety and Security Systems
Automotive Black Boxes Market
Automotive Safety and Security Systems
Automotive Collision Avoidance Systems Market
Automotive Safety and Security Systems
Vehicle Occupancy Detection System Market
Automotive Safety and Security Systems
Automotive Anti Lock Braking System and Electronic Stability Control Market
Automotive Safety and Security Systems
Video Event Data Recorder Market
Automotive Safety and Security Systems
Electronic Stability Control System Market
Automotive Safety and Security Systems
Automotive Surge Absorber Market
Automotive Safety and Security Systems
Automotive Fusion Sensors Market
Automotive Safety and Security Systems
Seat Belt Pretensioner and Load Limiter Market
Automotive Safety and Security Systems
Automotive Seat Belt System Market
Automotive Safety and Security Systems
Automotive Personal Assistance System Market
Automotive Safety and Security Systems
Germany Airbag Systems Market
Automotive Safety and Security Systems
Automotive Biometric Identification Market
Automotive Safety and Security Systems
Global Automotive Fog Lights Market
Automotive Safety and Security Systems
Airbag Market
Automotive Safety and Security Systems
Automotive TPMS Market