
 Satellite Communication Terminal Market | 2026-2036
Satellite Communication Terminal Market Size, Share, and Industry Trends Forecast 2026-2036
Satellite Communication Terminal Market Insights
Defense forces are reorganizing procurement priorities toward mobile and portable satellite terminals for expeditionary operations. Cobham Satcom dominates ruggedized maritime and military terminal design through decades of NATO supply relationships. Viasat, Inc. competes across broadband mobility with integrated Ka-band antenna systems for government and commercial aviation. L3Harris Technologies anchors classified military programs with frequency-hopping and anti-jam waveform capabilities.
A satellite communication terminal is a ground-based transceiver system comprising antenna assemblies, radio frequency units, modems, and power subsystems engineered to establish bidirectional links with orbiting spacecraft across L-band through Ka-band spectra. These terminals enable voice, data, and video transmission in locations lacking terrestrial infrastructure, serving defense, maritime, and emergency response missions. Fixed terminals still occupy the largest installed base for enterprise and broadcast backhaul, though mobile terminals represent the fastest-expanding category as militaries and airlines pursue uninterrupted connectivity in motion. VSAT technology leads commercial deployments for its cost-efficiency in hub-spoke networks, while LEO-compatible terminals command premium pricing as Starlink and OneWeb constellations mature.
The FCC governs terminal type certifications and spectrum licensing within the United States, while the ITU coordinates cross-border frequency assignments and orbital slot registrations that determine market access. ETSI and MIL-STD-810G establish environmental and electromagnetic compatibility baselines that differentiate qualified suppliers from commodity assemblers. Stakeholders must track evolving LEO constellation interoperability standards and national spectrum reallocation decisions that could obsolete legacy GEO-terminal inventories.
Market Dynamics
LEO constellation deployment is fragmenting procurement patterns as defense buyers and commercial airlines demand flat-panel antennas capable of tracking multiple orbital shells simultaneously.
Growth Catalysts
- LEO Terminal Interoperability Mandates:The FCC's streamlined equipment authorization process accelerates certification timelines for multi-orbit terminals, compressing vendor time-to-market by eliminating redundant testing cycles.
- Tactical Military Modernization:Expeditionary warfare doctrine in Germany and Australia prioritizes man-portable SATCOM for dismounted soldiers operating beyond line-of-sight.
- ITU Spectrum Harmonization:Cross-border Ka-band coordination agreements reduce interference risk for maritime vessels traversing multiple regulatory zones.
Market Restraints
- Gallium Nitride Supply Concentration:RF power amplifier fabrication depends on substrate suppliers concentrated in East Asian foundries, exposing terminal manufacturers to export control volatility.
- Antenna Aperture Physics:Gain requirements for military anti-jam waveforms impose minimum dish diameters that conflict with airborne SWaP constraints.
- Dual-Use Technology Controls:ITAR and EAR licensing thresholds delay commercialization of terminals derived from classified military programs.
Strategic Opportunities
- Rural Broadband Subsidies:India's Universal Service Obligation Fund allocates capital for remote village connectivity using VSAT backhaul where fiber deployment remains uneconomical.
- Aviation IFC Retrofit Cycles:Narrow-body fleet modernization creates demand for low-profile fuselage-mounted antennas on aging Boeing 737 and Airbus A320 platforms.
- Emergency Response Pre-positioning:FEMA and equivalent agencies in Japan and Italy stockpile fly-away terminals for disaster recovery scenarios requiring immediate network restoration.
Industry Challenges
- Phased Array Calibration Expertise:Electronically steered antenna production requires RF engineers proficient in beamforming algorithm development, a skill pool concentrated at defense contractors.
- Multi-Constellation Certification Burden:Terminal vendors must validate interoperability across Starlink, OneWeb, and legacy GEO systems, multiplying test matrix complexity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Satellite Communication Terminal Market |
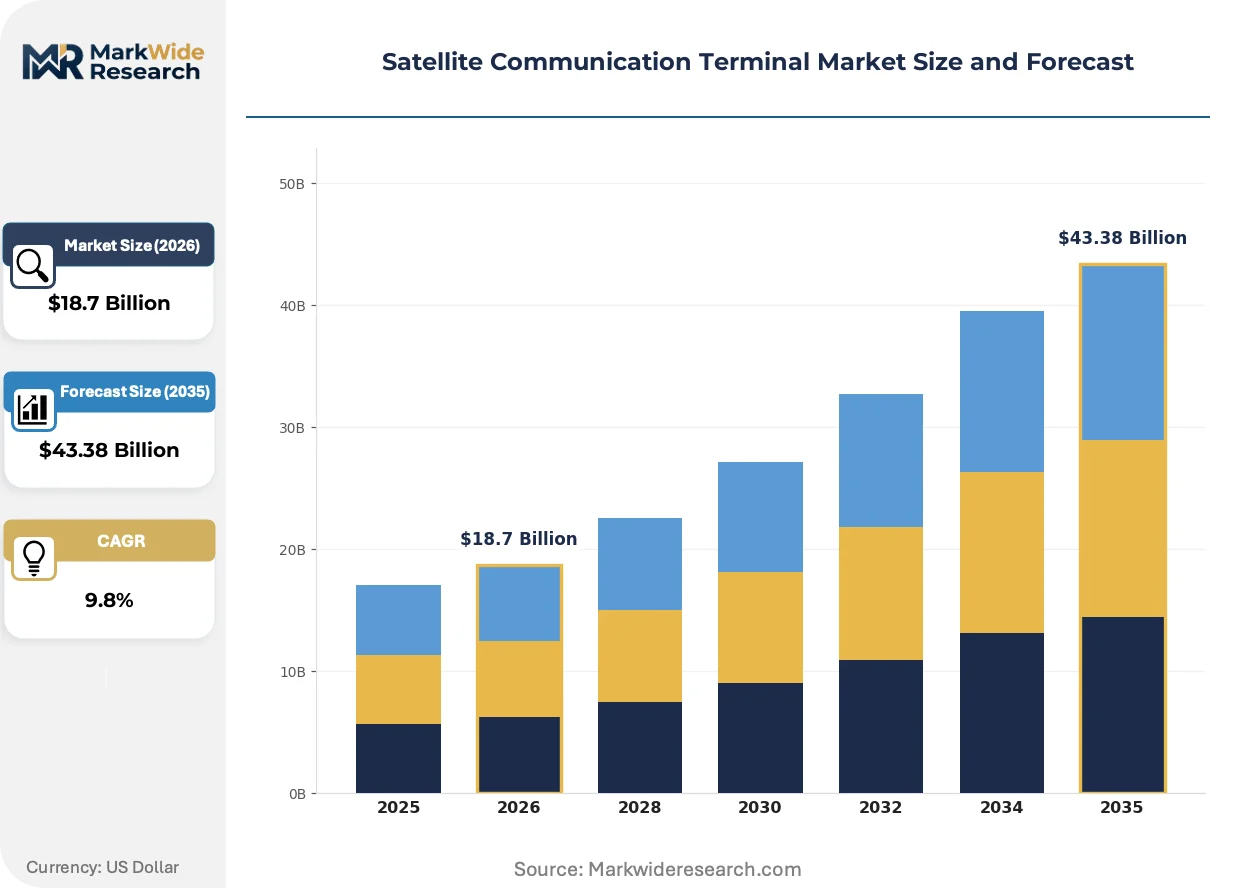
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $43.38 Billion |
| CAGR (2026 – 2036) | 9.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fixed Terminals, Mobile Terminals, Portable Terminals, Maritime Terminals Technology: VSAT, BGAN, LEO, GEO, MEO Application: Maritime Communications, Military Operations, Emergency Services, Broadcasting End User: Defense Forces, Telecommunication Providers, Media Companies, Disaster Management Agencies |
| Companies Covered | Cobham Satcom, Intelsat, Viasat, Inc., TESAT-Spacecom, Thales Alenia Space, Hughes Network Systems, L3Harris Technologies, Mynaric, Gilat Satellite Networks, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Satellite Communication Terminal Market Trends and Innovations
Flat-panel electronically steered arrays are collapsing the mechanical gimbal supply chain while software-defined modems enable waveform reconfiguration without hardware swaps.
Phased array architectures utilizing silicon CMOS beamformer chips is supplanting traditional parabolic dishes in mobility applications. Airlines and maritime operators are adopting these solid-state antennas for continuous connectivity during vehicle motion. This transition is compressing the addressable market for motorized pedestal manufacturers.
The EU's Radio Equipment Directive now mandates cybersecurity certification for satellite terminals handling critical infrastructure traffic. Equipment vendors must demonstrate resistance to spoofing and jamming attacks before CE marking approval. Maritime and energy sector buyers in Norway and the Netherlands are prioritizing compliant suppliers in tender evaluations.
Defense procurement offices are unbundling terminal hardware from waveform licensing agreements. Military buyers now acquire antennas and modems separately, then source encryption and anti-jam software through classified channels. This pattern is most pronounced in United States Special Operations Command and United Kingdom Strategic Command acquisitions.
Satellite Communication Terminal Market Segmentation
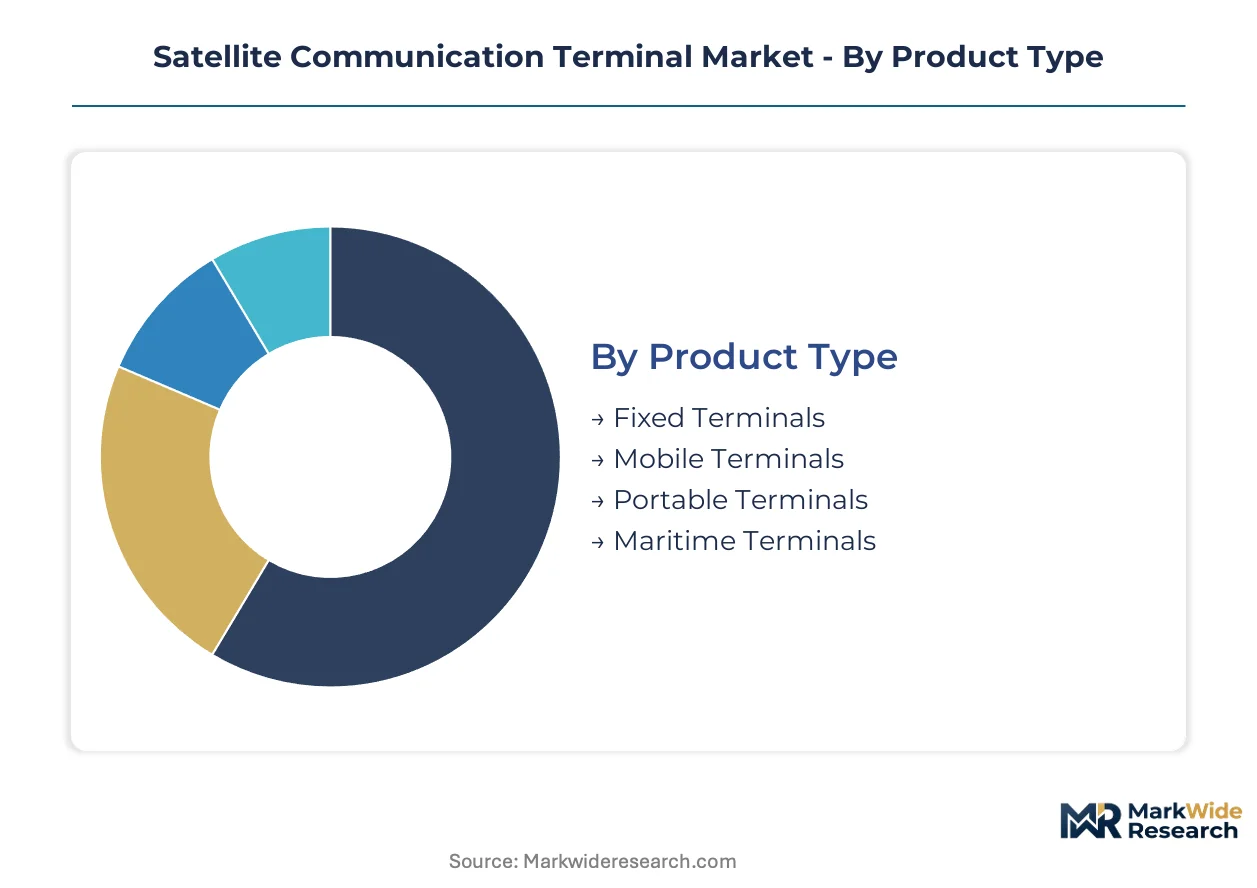
Terminal procurement patterns diverge sharply across use cases, with mobility requirements dictating antenna architecture and power specifications. Understanding segment boundaries clarifies why defense buyers prioritize SWaP-optimized hardware while broadcasters favor fixed-installation economics.
Product Type:
Fixed terminals face intensifying substitution pressure from fiber and 5G backhaul in urban corridors, forcing vendors to defend position in remote enterprise and broadcast relay niches.
- Fixed Terminals:Parabolic dish assemblies mounted at permanent ground stations with high-gain amplifiers for enterprise backhaul and broadcast contribution feeds. Demand concentrates in Germany and rural United States where terrain blocks terrestrial alternatives, though fiber overbuilds threaten replacement in accessible zones.
- Mobile Terminals:Vehicle-mounted or airborne transceiver systems with motorized or electronic beam steering for continuous connectivity in motion. Military vehicle programs in Australia and commercial aviation retrofit cycles in the United States concentrate procurement, with LEO interoperability now a mandatory specification.
- Portable Terminals:Man-packable fly-away kits with integrated batteries and rapid-deploy tripods for expeditionary communications. Disaster management agencies in Japan stockpile these units for earthquake response scenarios.
- Maritime Terminals:Stabilized antenna platforms engineered for vessel motion compensation across merchant and naval fleets. IMO safety mandates and crew welfare connectivity requirements drive replacement cycles on container ships.
Fixed terminals retain volume leadership; mobile terminals hold the steepest expansion curve.
Technology:
Cost tiers separate legacy GEO hardware from premium LEO-compatible electronics, with pricing stratifying across orbital-generation capabilities.
- VSAT:Hub-spoke network architecture using small aperture terminals for cost-efficient multicast distribution. Telecommunication providers in India deploy VSAT for rural broadband backhaul under Universal Service Obligation subsidies.
- BGAN:Inmarsat's L-band IP broadband service delivering 492 kbps to briefcase-sized terminals for remote journalism and diplomatic missions. Media companies operating in conflict zones rely on BGAN for guaranteed connectivity independent of local infrastructure.
- LEO:Low Earth Orbit terminals tracking Starlink, OneWeb, and emerging constellations with electronically steered flat panels. Defense forces in the United States and Germany prioritize these for tactical resilience against GEO jamming threats.
- GEO:Geostationary terminals with fixed pointing angles and proven reliability for broadcast distribution and maritime safety. Established installed base in energy sector offshore platforms sustues replacement demand.
- MEO:Medium Earth Orbit systems bridging latency and coverage gaps, notably SES's O3b mPOWER constellation for cellular backhaul in equatorial regions.
GEO technology retains installed-base dominance; LEO terminals are gaining share fastest.
Application:
Customer-type concentration varies by mission criticality, with military and emergency segments tolerating premium pricing for anti-jam capabilities unavailable to commercial users.
- Maritime Communications:Vessel-to-shore connectivity spanning crew internet, operational telemetry, and GMDSS safety alerts. Fleet operators in Norway mandate cybersecurity-certified terminals under EU Radio Equipment Directive compliance.
- Military Operations:Classified and unclassified tactical networks requiring frequency-hopping waveforms and low-probability-of-intercept signatures. United States Special Operations Command unbundles hardware from encryption licensing.
- Emergency Services:First-responder communications restoration when terrestrial networks fail. FEMA pre-positions fly-away terminals at regional logistics centers for hurricane response.
- Broadcasting:Contribution and distribution links for live event coverage and program syndication. Media companies in Italy maintain satellite backup for fiber-primary news gathering operations.
Broadcasting retains revenue concentration; military operations demonstrate the steepest technology refresh rate.
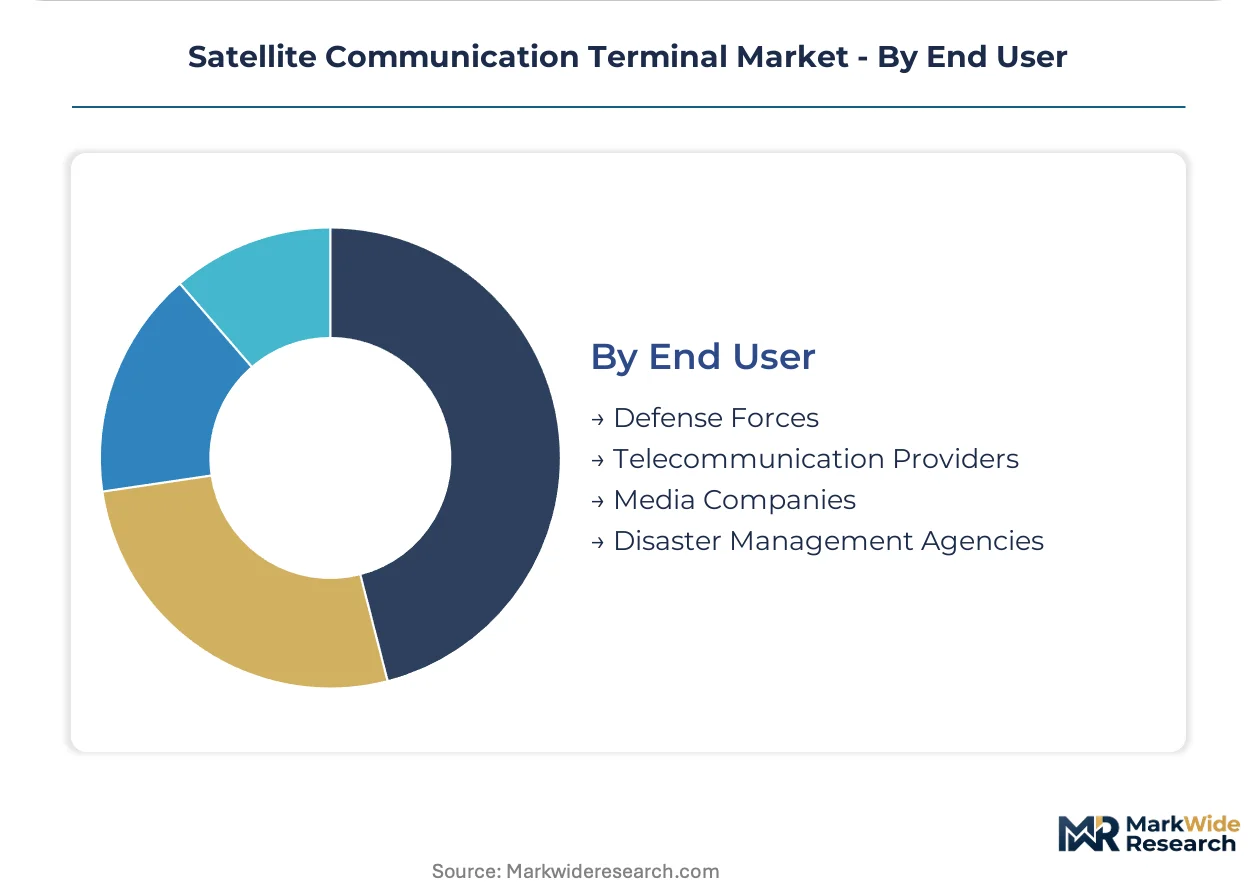
End User:
Maturity gradients separate defense procurement with decade-long certification cycles from commercial buyers adopting consumer-electronics refresh timelines.
- Defense Forces:Classified program offices with MIL-STD-810G environmental requirements and ITAR-controlled supply chains. Procurement in the United Kingdom Strategic Command emphasizes modular terminals with software-definable waveforms.
- Telecommunication Providers:Licensed operators deploying satellite backhaul for universal service mandates and rural 5G extension. India's BSNL and private operators compete for USOF-funded VSAT deployments.
- Media Companies:Broadcasters and news agencies prioritizing rapid-deploy field units for breaking coverage. Premium pricing tolerance for guaranteed bandwidth during live events.
- Disaster Management Agencies:Government emergency response coordinators with stockpiling and surge-activation protocols. Japan's Cabinet Office maintains terminal caches at prefectural emergency operations centers.
Defense forces anchor procurement value; disaster management agencies show the most volatile demand spikes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States Space Force's Eastern Range at Cape Canaveral underwrites American launch capacity that seeds terminal demand across defense and commercial aviation verticals. Fiber backhaul gaps in the Mountain West sustain rural VSAT deployment against terrestrial overbuild pressure.
United States
Defense procurement from USSOCOM and Army Futures Command drives man-portable SATCOM requirements for expeditionary units. The FCC's streamlined equipment authorization process compresses multi-orbit terminal certification timelines. Colorado Springs anchors military terminal integration activity near Space Command headquarters.
Germany
Bundeswehr tactical modernization prioritizes vehicle-mounted and dismounted satellite links for NATO expeditionary operations. ITU-coordinated Ka-band harmonization agreements reduce cross-border interference for maritime terminals traversing the North Sea. Munich-Stuttgart corridor hosts RF subsystem suppliers serving both civilian and classified programs.
China
MIIT spectrum allocation frameworks govern domestic terminal type approval while state-owned operators deploy VSAT backhaul for western provincial broadband coverage. The national satellite internet constellation program stimulates flat-panel antenna development for consumer and maritime applications. Beijing-Tianjin-Hebei corridor concentrates phased array research institutes and GaN foundry partnerships.
India
TRAI's Universal Service Obligation Fund capitalizes rural VSAT deployment where Himalayan terrain and desert regions block fiber extension. BSNL and private operators compete for remote village backhaul contracts under subsidized tender mechanisms. Bangalore-Hyderabad corridor hosts system integrators adapting foreign terminal designs for tropical environmental requirements.
Japan
METI coordinates disaster-resilient communication infrastructure including pre-positioned fly-away terminals at prefectural emergency centers. The Cabinet Office stockpiles satellite equipment for earthquake and tsunami response scenarios where terrestrial networks fail within hours. Tokyo-Yokohama industrial base supplies stabilized maritime antennas for domestic shipbuilders and export markets.
Satellite Communication Terminal Market Competitive Landscape
Listed leaders compete with private specialists across defense contracting access and commercial aviation certification pathways. The vendor base stratifies between consolidated prime contractors holding classified program clearances and fragmented component suppliers competing on cost. Three archetypes dominate: integrated defense primes with waveform licensing control, commercial broadband specialists with airline relationships, and RF subsystem vendors with GaN amplifier expertise. Competitive moves center on unbundling hardware from software licensing and securing multi-constellation interoperability certifications ahead of LEO network maturation.
Among defense-anchored primes, L3Harris Technologies and Thales Alenia Space exemplify the classified program tier where ITAR-controlled supply chains and MIL-STD environmental qualification create structural barriers. Cobham Satcom occupies a distinct position bridging ruggedized maritime requirements with NATO military specifications, while Viasat, Inc. represents the commercial broadband vector where integrated antenna-modem systems compete for aviation and government mobility contracts. These three anchors illustrate how terminal procurement splits between security-cleared and commercially certifiable supply channels.
| Leading Market Players |
|---|
| Cobham Satcom |
| Intelsat |
| Viasat, Inc. |
| TESAT-Spacecom |
| Thales Alenia Space |
| Hughes Network Systems |
| L3Harris Technologies |
| Mynaric |
| Gilat Satellite Networks |
| Others |
Pricing and Supply Chain Analysis
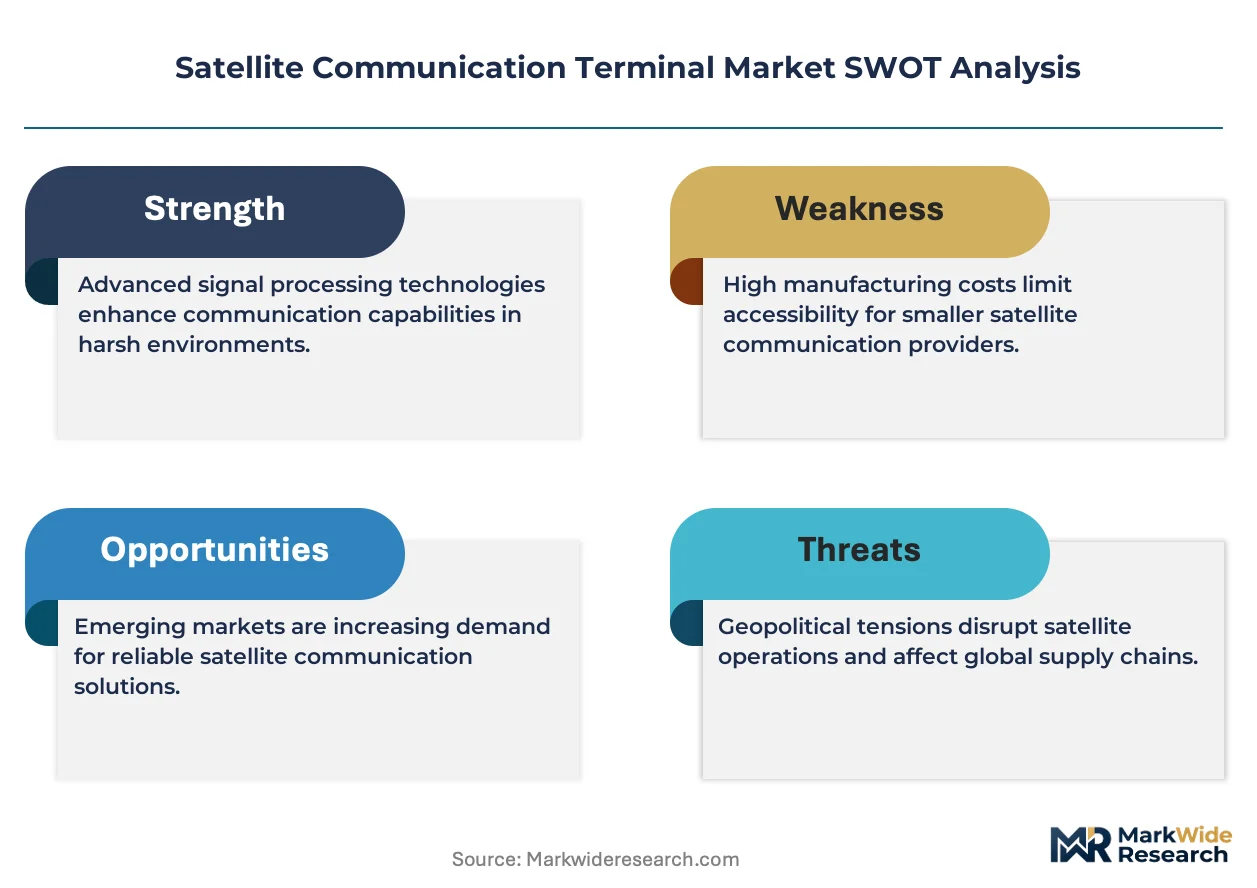
Silicon CMOS beamformer chips replacing traditional gallium arsenide MMICs simultaneously shifts RF subsystem sourcing toward East Asian foundry clusters and collapses pricing premiums for electronically steered arrays. This substitution dynamic compresses cost structures for LEO-compatible terminals while concentrating supply leverage among semiconductor fabricators.
Pricing Analysis
Volume-discount tiering structures separate defense procurement contracts from commercial spot purchases, with three-tier pricing stratification across MIL-STD-certified, aviation-qualified, and uncertified economy tiers. Price differentiation hinges on ITAR compliance grade and waveform licensing bundling. Cost compression in commercial aviation tiers is intensifying because Starlink's direct-to-consumer pricing sets reference points. Disaster management agencies exhibit highest price sensitivity; classified military buyers tolerate premium multiples for anti-jam capabilities.
Supply Chain Analysis
Inbound logistics costs for gallium nitride substrates from East Asian ports face recurring congestion on transpacific lanes, elevating working capital requirements for RF amplifier manufacturers. Terminal assembly draws from China, South Korea, and Germany for phased array components, GaN foundry output, and precision machining. Single-source vulnerability concentrates in substrate suppliers. Distribution runs through defense prime contractors holding cleared facility status and commercial integrators serving aviation retrofit channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market constitutes a regulatory-entrenchment defensive moat where FCC type certifications and ITAR facility clearances create structural barriers requiring multi-year investment cycles to replicate.
For Market Incumbents: Fortify waveform licensing control through modular hardware-software unbundling that locks military buyers into proprietary encryption ecosystems. Deepen backward integration into GaN substrate supply through captive partnerships with South Korean foundries to offset export control volatility. Counter emerging flat-panel specialists by accelerating multi-constellation certification timelines ahead of LEO network maturation. For New Entrants and Emerging Players: FCC streamlined equipment authorization fast-tracks offer entry velocity for commercial aviation retrofit segments underserved by defense-anchored primes. Target India's Universal Service Obligation rural broadband deployments where foreign terminal adaptation for tropical environments creates white-space. Pursue fly-away kit standardization for FEMA-equivalent agencies as the go-to-market angle. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed RF subsystem specialists holding GaN amplifier expertise but lacking terminal integration capabilities. Five-to-ten-year viability favors acquiring phased array calibration engineering teams concentrated at defense contractors. Watch LEO constellation interoperability mandate timing as inflection signal for legacy GEO terminal obsolescence risk.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Constellation Certification | FCC authorization for Starlink-OneWeb-GEO interoperability compresses vendor time-to-market. |
| GaN Substrate Backward Integration | Captive supply from South Korean foundries insulates against export control disruption. |
| Modular Waveform Unbundling | Hardware-software separation aligns with USSOCOM procurement patterns for encryption sourcing. |
| Aviation Retrofit Channel Partnership | Boeing 737 and Airbus A320 fleet modernization creates narrow-body antenna replacement demand. |
| Disaster Response Pre-Positioning Contract | FEMA and Japan Cabinet Office stockpiling protocols generate surge-activated revenue visibility. |
Research Methodology
Cross-validation between primary defense procurement officer interviews and secondary ITU spectrum allocation filings anchors the qualitative findings in this study. Terminal manufacturer executives, RF subsystem engineers, aviation certification specialists, and disaster management logistics coordinators provided operational perspective. Regulatory databases from the FCC, ETSI, and MIIT supplemented customs records and satellite operator capex disclosures. Bottom-up segment sizing triangulated against top-down constellation deployment forecasts.
Sensitivity analysis across LEO constellation launch cadence scenarios and gallium nitride export control severity bands stress-tested projection robustness. Segmentation modeling incorporated product type, orbital generation technology, application mission profile, and end-user procurement authority. CAGRs derived from unit shipment trajectories and average selling price evolution across certification tiers. Military modernization program timelines and rural broadband subsidy allocation cycles served as industry-specific demand inputs.
Underlying assumptions cover sustained ITAR enforcement stringency and LEO constellation operational continuity, with deviation risk concentrated in spectrum reallocation decisions and GaN supply chain disruptions. Recalibration cycles align with material shifts in FCC equipment authorization frameworks and ITU coordination agreement timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telecom Hardware
Subscriber Identity Module (SIM) Market
Telecom Hardware
Telecom Equipment Market
Telecom Hardware
Laser Communications Terminals (Lcts) Market
Telecom Hardware
Point-To-Point Antenna Market
Telecom Hardware
Base Station Antenna Market
Telecom Hardware
DWDM Transceiver Market
Telecom Hardware
Microwave Antenna Market
Telecom Hardware
5G Temperature-Compensated Crystal Oscillator (TCXO) Market
Telecom Hardware
4G Equipment Market
Telecom Hardware
Global Volte Market
Telecom Hardware
Synchronous Optical Network (SONET) Market
Telecom Hardware
Global Time Sensitive Networking Market
Telecom Hardware
Commercial Antennas Market
Telecom Hardware
Global Virtualized Evolved Packet Core (VEPC) Market
Telecom Hardware
Repeaters Market
Telecom Hardware
Land Mobile Radio System Market