
 Broadcast Antenna Market | 2026-2036
Broadcast Antenna Market Size, Share, and Industry Trends Forecast 2026-2036
Broadcast Antenna Market Outlook
The gap between premium beamforming arrays and commodity passive antennas is expanding as broadcasters face divergent capital constraints and spectrum efficiency requirements. TE Connectivity leverages its connector integration expertise to anchor high-reliability outdoor installations for major network operators. CommScope competes through deep manufacturing scale across both digital and analogue product lines. Jampro Antennas Inc. specializes in custom directional systems for television broadcasters navigating complex terrain coverage challenges.
Broadcast antennas are radio-frequency transducers engineered to radiate electromagnetic waves across VHF and UHF bands with specified gain patterns, typically fabricated from aluminum alloys or copper-clad steel with precision-tuned element spacing. Their primary commercial purpose is enabling over-the-air television and radio signal distribution to receiver populations. Directional antennas command premium positioning in spectrum-constrained markets where beam shaping maximizes coverage per allocated frequency block. Digital technology segments are displacing legacy analogue installations as nations complete terrestrial transition mandates. Smart antenna architectures with embedded remote monitoring represent the fastest-growing margin pool as broadcasters prioritize reduced tower-climb maintenance.
The FCC enforces stringent radiation pattern certification under its antenna performance specifications, while ETSI standards in Europe mandate electromagnetic compatibility testing that shapes product development timelines for export-bound manufacturers. Japan's MIC coordinates regional frequency coordination rules that directly determine antenna specification requirements for metropolitan Tokyo and Osaka deployments. India's WPC imposes import licensing and type-approval protocols that condition market access timelines for foreign suppliers. Stakeholders must monitor spectrum auction calendars and repack completion schedules across multiple regulatory jurisdictions to align capital deployment with infrastructure replacement cycles.
Market Dynamics
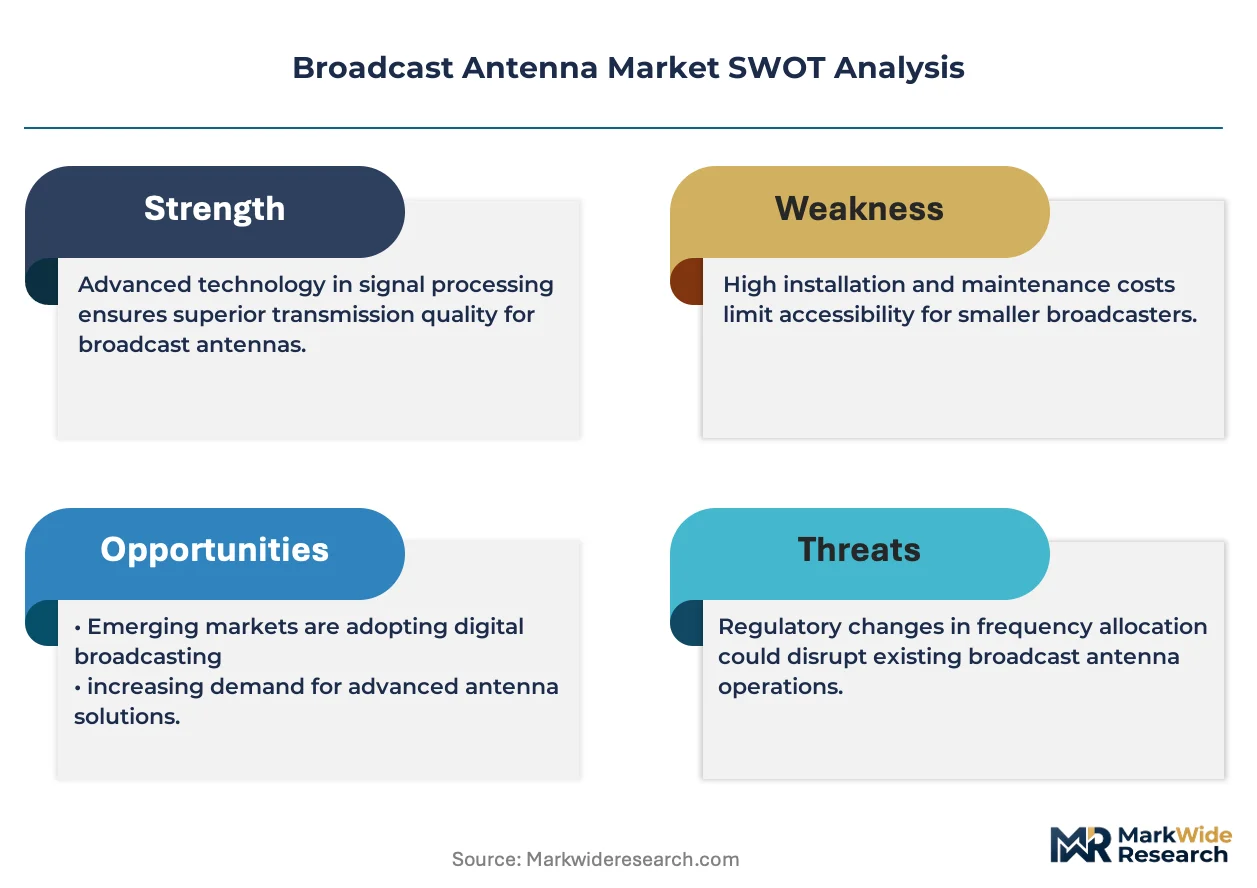
Spectrum repacking mandates across multiple jurisdictions are forcing accelerated replacement cycles for broadcast transmission infrastructure, compressing capital deployment timelines while elevating technical performance requirements for antenna systems.
Growth Catalysts
- Digital transition mandates:Terrestrial television broadcasters in Germany and Japan face government-mandated analogue switch-off deadlines requiring complete transmission infrastructure overhaul.
- FCC post-incentive auction repack:The United States continues channel reassignment programs that obligate major metropolitan broadcasters to replace or retune existing antenna installations.
- Beamforming adoption:High-density urban deployments increasingly specify active array architectures that maximize spectrum efficiency through precise radiation pattern control.
Market Restraints
- Aluminum alloy price volatility:Raw material cost fluctuations for precision-tuned antenna elements compress manufacturer margins and complicate long-term contract pricing.
- Tower infrastructure concentration:Limited qualified installation contractors in major metropolitan markets create bottleneck risks for deployment schedules.
- Legacy system interoperability:Existing transmission plant compatibility requirements constrain architectural freedom for next-generation antenna designs.
Strategic Opportunities
- Smart antenna architectures:Embedded remote monitoring capabilities command premium positioning as broadcasters prioritize reduced tower-climb maintenance regimes.
- India WPC type-approval pathways:Import licensing protocols create first-mover advantages for suppliers establishing local certification relationships.
- ATSC 3.0 transition:Next-generation broadcast standards enable converged fixed-mobile service models requiring upgraded transmission infrastructure.
Industry Challenges
- RF engineering talent scarcity:Specialized electromagnetic design expertise for VHF-UHF beam pattern optimization remains concentrated among aging practitioner cohorts.
- ETSI electromagnetic compatibility certification:European testing timelines extend product development cycles for export-bound manufacturers targeting multiple jurisdictions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Broadcast Antenna Market |
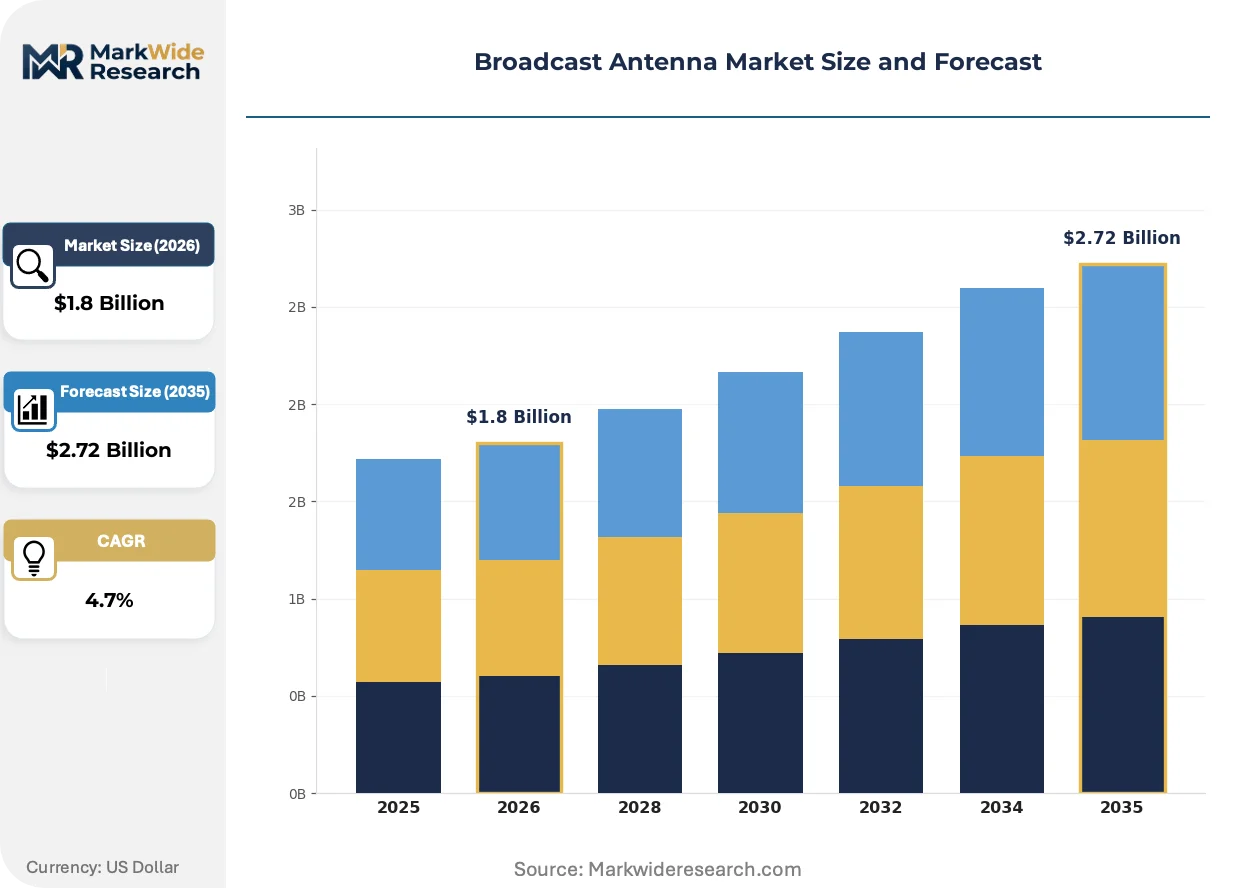
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Directional, Omnidirectional, Yagi, Parabolic Technology: Analogue, Digital, Smart, Beamforming End User: Television Broadcasters, Radio Stations, Telecommunications, Public Safety Installation Type: Indoor, Outdoor, Fixed, Mobile |
| Companies Covered | TE Connectivity Ltd., Jampro Antennas Inc., Propagation Systems Inc., TCI International Inc., Twin Engineers Private Limited, Harris Communications, Nexion Technology, CommScope, Antennas Direct, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Broadcast Antenna Market Strategic Shifts
Active electronic beam steering is displacing mechanical antenna positioning across premium broadcast installations, while embedded sensor networks transform maintenance economics for tower-mounted equipment.
Adaptive beamforming arrays with software-defined radiation patterns are converging with broadcast transmitter systems to enable real-time coverage optimization. Major network operators in spectrum-constrained markets specify these architectures for metropolitan deployments. This convergence is compressing demand for legacy passive antenna designs while elevating supplier technical qualification requirements.
Japan's MIC regional frequency coordination rules now mandate interference analysis documentation for all Tokyo and Osaka metropolitan antenna installations. Broadcast equipment suppliers must embed compliance verification into pre-deployment engineering workflows. Tower-mounted systems in these designated markets face extended approval timelines compared to rural installations.
Broadcasters increasingly unbundle antenna procurement from integrated transmission system contracts, creating direct vendor relationships for RF hardware. Network operators now specify antenna performance independently from transmitter equipment, shifting specification authority from system integrators to broadcast engineering departments. This pattern is most visible in United States markets where FCC antenna performance specifications enable standardized comparison shopping.
Broadcast Antenna Market Segmentation
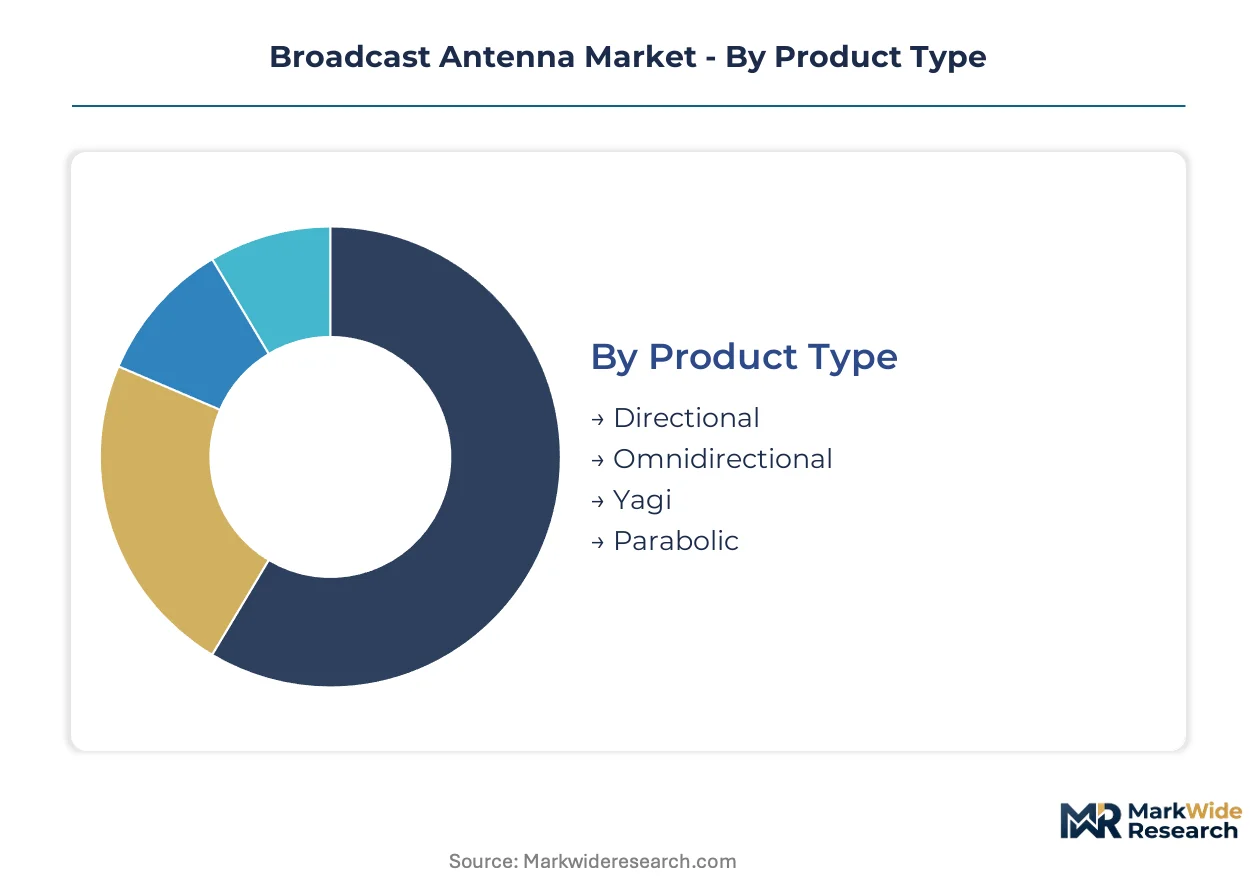
Antenna specification authority has shifted from system integrators to broadcast engineering departments, creating direct procurement relationships across product categories. This unbundling trend elevates the commercial significance of granular segment positioning for component suppliers.
Product Type:
Customization intensity varies sharply across this category, from precision-engineered directional systems to commodity omnidirectional designs.
- Directional:These antennas employ precisely tuned element arrays with specified azimuth and elevation patterns to maximize coverage per frequency block. Demand concentrates in spectrum-constrained metropolitan markets across Germany and Japan where beam shaping compliance with MIC and ETSI mandates drives specification authority. FCC antenna performance specifications in the United States enable standardized comparison shopping for these premium systems.
- Omnidirectional:Radiating uniformly in the horizontal plane, these designs serve rural coverage extensions and gap-filling applications with lower engineering overhead. Radio stations in less densely populated regions specify these configurations where terrain permits simpler deployment economics.
- Yagi:Log-periodic dipole arrays deliver cost-effective directional performance for secondary market television broadcasters with moderate spectrum efficiency requirements.
- Parabolic:Reflector-based architectures with high gain and narrow beamwidth serve point-to-point relay links and specialized telecommunications backhaul.
Most installed capacity flows through Directional antennas. Expansion is steepest in Parabolic configurations for emerging telecommunications applications.
Technology:
Margin structures diverge across maturity stages, from declining analogue maintenance to premium smart architectures with embedded monitoring.
- Digital:Terrestrial television infrastructure across Germany and Japan mandates complete digital transition, displacing legacy transmission plant. Government-imposed analogue switch-off deadlines compress replacement timelines while elevating technical performance specifications for new installations.
- Beamforming:Active electronic beam steering with software-defined radiation patterns enables real-time coverage optimization in high-density urban deployments. Network operators in the United States specify these architectures for metropolitan markets where FCC post-incentive auction repack demands maximum spectrum efficiency.
- Analogue:Maintenance-driven demand persists for existing transmission plant compatibility, though new procurement has ceased in regulated markets.
- Smart:Embedded sensor networks with remote monitoring capabilities transform maintenance economics for tower-mounted equipment, commanding premium positioning as broadcasters prioritize reduced tower-climb regimes.
Digital systems anchor current revenue concentration. Beamforming arrays are gaining share fastest as spectrum constraints intensify.
End User:
Procurement scale and specification sophistication separate national network operators from local service providers.
- Television Broadcasters:Major metropolitan operators in the United States, Germany, and Japan drive premium demand for spectrum-efficient architectures. FCC, ETSI, and MIC regulatory mandates directly shape antenna specification requirements, with compliance documentation extending approval timelines in designated markets.
- Telecommunications:Converged fixed-mobile service models under ATSC 3.0 standards require upgraded transmission infrastructure with hybrid broadcast-broadband capabilities.
- Radio Stations:Audio-focused deployments with narrower bandwidth requirements specify simpler antenna configurations, though digital radio transition is accelerating specification complexity.
- Public Safety:Mission-critical reliability standards with redundant coverage requirements command specialized engineering for emergency communication networks.
Television broadcasters command the largest procurement volumes. Telecommunications applications show the steepest expansion trajectory as convergence accelerates.
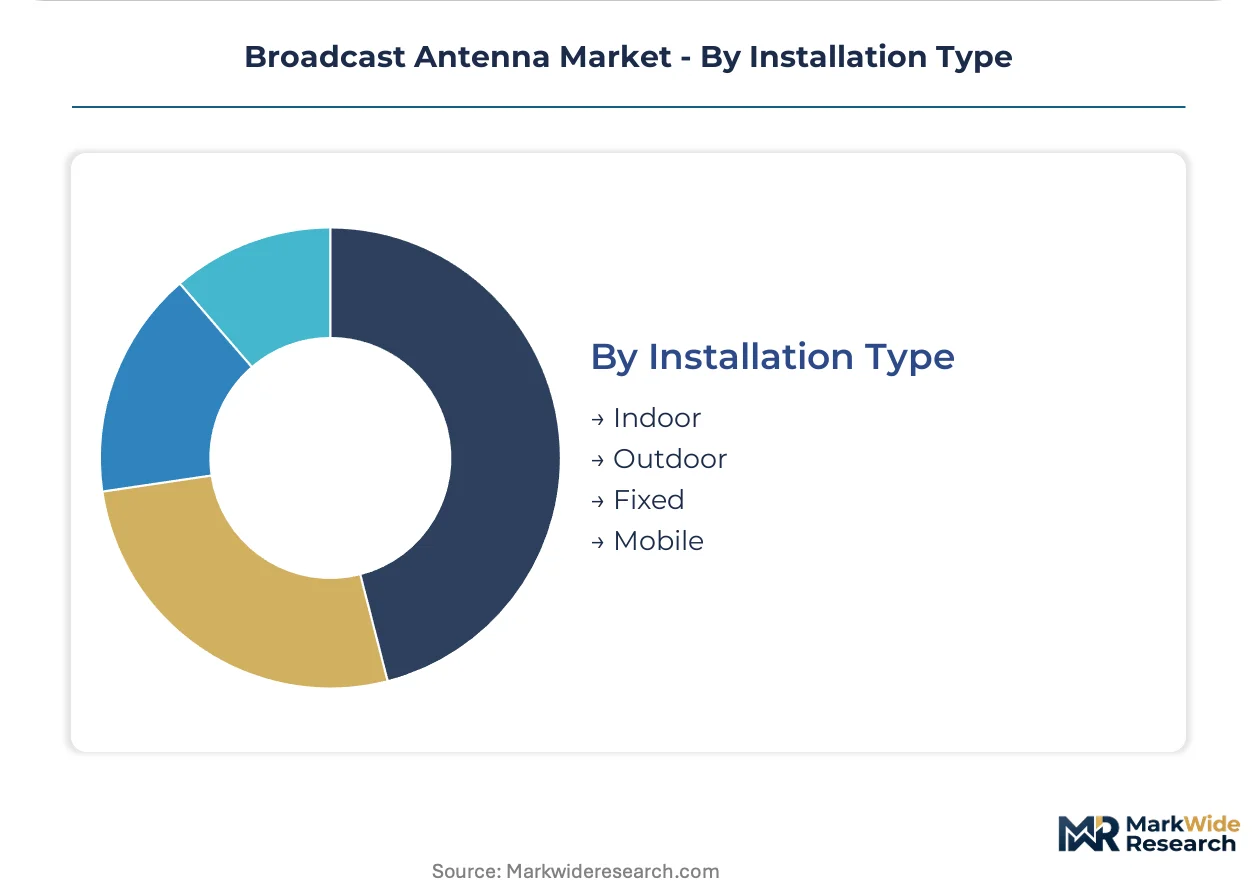
Installation Type:
Environmental exposure severity and accessibility constraints determine engineering requirements and maintenance economics.
- Outdoor:Tower-mounted systems face aluminum alloy price volatility and limited qualified installation contractor availability in major metropolitan markets. TE Connectivity leverages connector integration expertise for high-reliability installations in these exposed environments.
- Fixed:Permanent installations dominate broadcast transmission infrastructure, with embedded remote monitoring capabilities prioritizing reduced maintenance access requirements.
- Indoor:Controlled-environment deployments for studio and head-end applications specify lower weatherization grades with corresponding cost structures.
- Mobile:Rapid-deploy configurations serve emergency broadcasting and temporary event coverage with trade-offs in gain and pattern stability.
Fixed outdoor installations represent the dominant configuration. Mobile systems are expanding most quickly for emergency preparedness applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
RF engineering talent for VHF-UHF beam pattern optimization concentrates in Germany, Japan, and the United States, anchoring antenna design capabilities for terrestrial television infrastructure worldwide.
United States
Major metropolitan broadcasters in New York, Los Angeles, and Chicago drive replacement cycles following FCC post-incentive auction repack mandates. The FCC's antenna performance specifications enable standardized comparison shopping for spectrum-efficient architectures. Tower infrastructure in these designated markets faces extended deployment timelines due to limited qualified installation contractor availability.
Germany
Digital terrestrial television broadcasters in Berlin, Munich, and Hamburg upgrade transmission infrastructure under government-mandated analogue switch-off deadlines. ETSI electromagnetic compatibility certification requirements extend product development cycles for export-bound manufacturers. The country's precision engineering clusters in Bavaria and Baden-Württemberg anchor aluminum alloy fabrication capabilities for precision-tuned antenna elements.
Japan
Metropolitan operators in Tokyo and Osaka specify beamforming array architectures to maximize spectrum efficiency in high-density urban deployments. MIC regional frequency coordination rules mandate interference analysis documentation, extending approval timelines compared to rural installations. The Kanto and Kansai industrial corridors concentrate embedded sensor network development for smart antenna remote monitoring capabilities.
India
Television broadcasters in Maharashtra, Karnataka, and Tamil Nadu navigate WPC import licensing and type-approval protocols that condition market access timelines for foreign suppliers. The country's national telecommunications regulator imposes certification requirements that create first-mover advantages for suppliers establishing local relationships. Mumbai and Bangalore clusters increasingly specify ATSC 3.0-ready infrastructure for converged fixed-mobile service models.
Broadcast Antenna Market Competitive Environment
Capital-heavy producers compete with asset-light designers across the broadcast antenna market, with integrated manufacturing facilities in aluminum alloy regions facing off against specialized RF engineering boutiques. The vendor base organizes into three tiers: connector-integrated system suppliers, scale-driven diversified manufacturers, and custom directional specialists. Consolidation pressures intensify as broadcasters unbundle antenna procurement from integrated transmission contracts. Dominant competitive moves include backward integration into precision-tuned element fabrication and strategic partnerships for embedded remote monitoring capabilities.
Among connector-integrated suppliers, TE Connectivity Ltd. occupies a position exemplifying high-reliability outdoor installation expertise. CommScope represents the scale-driven diversified archetype across digital and analogue product lines. Jampro Antennas Inc. anchors the custom directional specialist tier, with its company structure suggesting focused engineering capabilities for terrain-specific coverage challenges.
| Leading Market Players |
|---|
| TE Connectivity Ltd. |
| Jampro Antennas Inc. |
| Propagation Systems Inc. |
| TCI International Inc. |
| Twin Engineers Private Limited |
| Harris Communications |
| Nexion Technology |
| CommScope |
| Antennas Direct |
| Others |
Value Chain & Pricing Dynamics
Aluminum alloy price volatility for precision-tuned antenna elements feeds directly into three-tier pricing structure across premium, standard, and economy levels, with FCC-certified beamforming arrays commanding substantial premiums over commodity passive designs while raw material surges compress margins at the mid-market tier.
Pricing Analysis
The bundled-vs-unbundled service split separates integrated transmission system contracts from direct antenna procurement relationships. Price differentiation hinges on certification grade for FCC antenna performance specifications and customization level for terrain-specific coverage requirements. Pricing pressure stems from aluminum alloy cost compression in the standard tier, where commodity passive designs face margin erosion. Local radio stations exhibit the highest price sensitivity, while major metropolitan television broadcasters prioritize spectrum efficiency over unit cost.
Supply Chain Analysis
Single-source vulnerability sits with qualified installation contractors in major metropolitan markets, where tower infrastructure concentration creates bottleneck risks for deployment schedules. Manufacturing draws from Germany, Japan, and the United States for precision-tuned element fabrication. Raw material dependencies center on aluminum alloys, copper-clad steel, and precision connectors. Supply chain risk manifests through regulatory restriction from ETSI electromagnetic compatibility certification extending product development cycles. Distribution runs through direct vendor relationships with broadcast engineering departments and system integrator partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a late-cycle quality story where broadcaster specification authority has shifted toward premium beamforming architectures with embedded remote monitoring capabilities.
For Market Incumbents: Deepen backward integration into precision-tuned element fabrication to defend against aluminum alloy price volatility and capture margin pool expansion in smart antenna architectures. Prioritize certification investment for FCC antenna performance specifications and ETSI electromagnetic compatibility testing to maintain specification authority as broadcasters unbundle procurement from integrated transmission contracts.
For New Entrants and Emerging Players: Launch via direct relationships with broadcast engineering departments in India, where WPC type-approval protocols create first-mover advantages for suppliers establishing local certification relationships. Target white-space opportunities in ATSC 3.0-ready infrastructure for converged fixed-mobile service models, penetrating through embedded sensor network partnerships that reduce tower-climb maintenance regimes.
For Investors and Strategic Acquirers: Consolidation pressure builds where RF engineering talent scarcity concentrates among aging practitioner cohorts in VHF-UHF beam pattern optimization. Long-term viability favors acquisition of custom directional specialists with terrain-specific engineering capabilities and established MIC compliance documentation workflows. Monitor spectrum auction calendars and repack completion schedules across FCC, ETSI, and MIC jurisdictions as inflection indicators for infrastructure replacement cycle timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precision Element Fabrication | Captures aluminum alloy margin compression and secures supply continuity for FCC-certified installations. |
| Embedded Remote Monitoring Capability Development | Commands premium positioning as broadcasters prioritize reduced tower-climb maintenance regimes in urban deployments. |
| ETSI and MIC Compliance Documentation Investment | Accelerates market access timelines for Tokyo, Osaka, and European metropolitan antenna installations. |
| Direct Broadcast Engineering Department Relationships | Captures specification authority shift from system integrators in United States unbundling trend. |
| ATSC 3.0 Infrastructure Partnership Formation | Enables converged fixed-mobile service models requiring hybrid broadcast-broadband transmission upgrades. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with broadcast engineering directors, RF design specialists, tower installation contractors, and network operator procurement leads with secondary validation from FCC filing databases, ETSI certification registries, MIC regional coordination documentation, and customs trade records for aluminum alloy and copper-clad steel imports. Bottom-up antenna shipment estimates and top-down infrastructure replacement cycle analysis provided cross-verification.
Segment-weighting approaches modeled product type, technology maturity, end-user scale, and installation environment across the analysis window, with CAGRs derived from spectrum repack completion schedules and digital transition mandate timelines. Forecast inputs incorporated aluminum alloy price indices, qualified contractor availability by metropolitan market, and regulatory approval timeline differentials between rural and designated urban coordination zones.
Several conditions sit outside the modeled scope, including force majeure disruptions to tower infrastructure, radical spectrum reallocation decisions beyond announced repack programs, and breakthrough wireless technologies obsoleting terrestrial broadcast architectures. Forecasts reflect documented assumptions regarding regulatory schedule adherence and material cost stabilization. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telecom Hardware
Global Microwave Transmission Equipment Market
Telecom Hardware
Point-To-Point Microwave Antenna Market
Telecom Hardware
LPWAN Market
Telecom Hardware
Digital Smart Set-Top Box (STB) Market
Telecom Hardware
Global LTE Modems Market
Telecom Hardware
Europe Zero-Touch Provisioning Market
Telecom Hardware
Commercial Antennas Market
Telecom Hardware
Europe Set-Top Box Market
Telecom Hardware
Telecom Electronic Manufacturing Services (EMS) Market
Telecom Hardware
Parabolic Antenna Market
Telecom Hardware
Point-To-Point Antenna Market
Telecom Hardware
Laser Communications Terminals (Lcts) Market
Telecom Hardware
5G Temperature-Compensated Crystal Oscillator (TCXO) Market
Telecom Hardware
Base Station Antenna Market
Telecom Hardware
Subscriber Identity Module (SIM) Market
Telecom Hardware
Set-Top Box Market