
 Room Cell Module Market | 2026-2036
Room Cell Module Market Size, Share, and Industry Trends Forecast 2026-2036
Room Cell Module Market Analysis
China's Yangtze River Delta is reshaping regional supply dynamics for room cell module fabrication. Panasonic Corporation leverages integrated semiconductor-to-module manufacturing across Osaka and Suzhou facilities. Samsung Electronics anchors display-integrated active module production with captive chip supply from Pyeongtaek. Siemens AG controls building automation system interfaces that lock in module specification standards across European commercial installations.
A room cell module is a prefabricated electromechanical enclosure integrating climate control, power distribution, and sensor networks into a standardized structural frame, typically rated for IP54 environmental sealing and operating between -20°C and 50°C ambient conditions; it serves as a deployable infrastructure unit for data centers, cleanrooms, and modular construction. Passive modules dominate volume shipments in residential and light commercial segments where thermal mass and natural ventilation suffice, while active modules with embedded compressor-based cooling capture the margin pool in industrial and data center applications. Hybrid modules are gaining traction in educational institutions seeking seasonal flexibility without full HVAC retrofit commitments.
China's GB standards for modular building components and the EU Energy Performance of Buildings Directive jointly constrain thermal transmittance coefficients and refrigerant selection, forcing manufacturers to redesign insulation cores and phase out high-GWP coolants. Japan's METI enforces JIS standards for seismic isolation in prefabricated units, which elevates structural engineering costs but opens premium positioning for certified suppliers. Stakeholders must track divergence between Asian GB/JIS compliance pathways and European REACH-F-Gas regulatory bundles to avoid stranded certification investments.
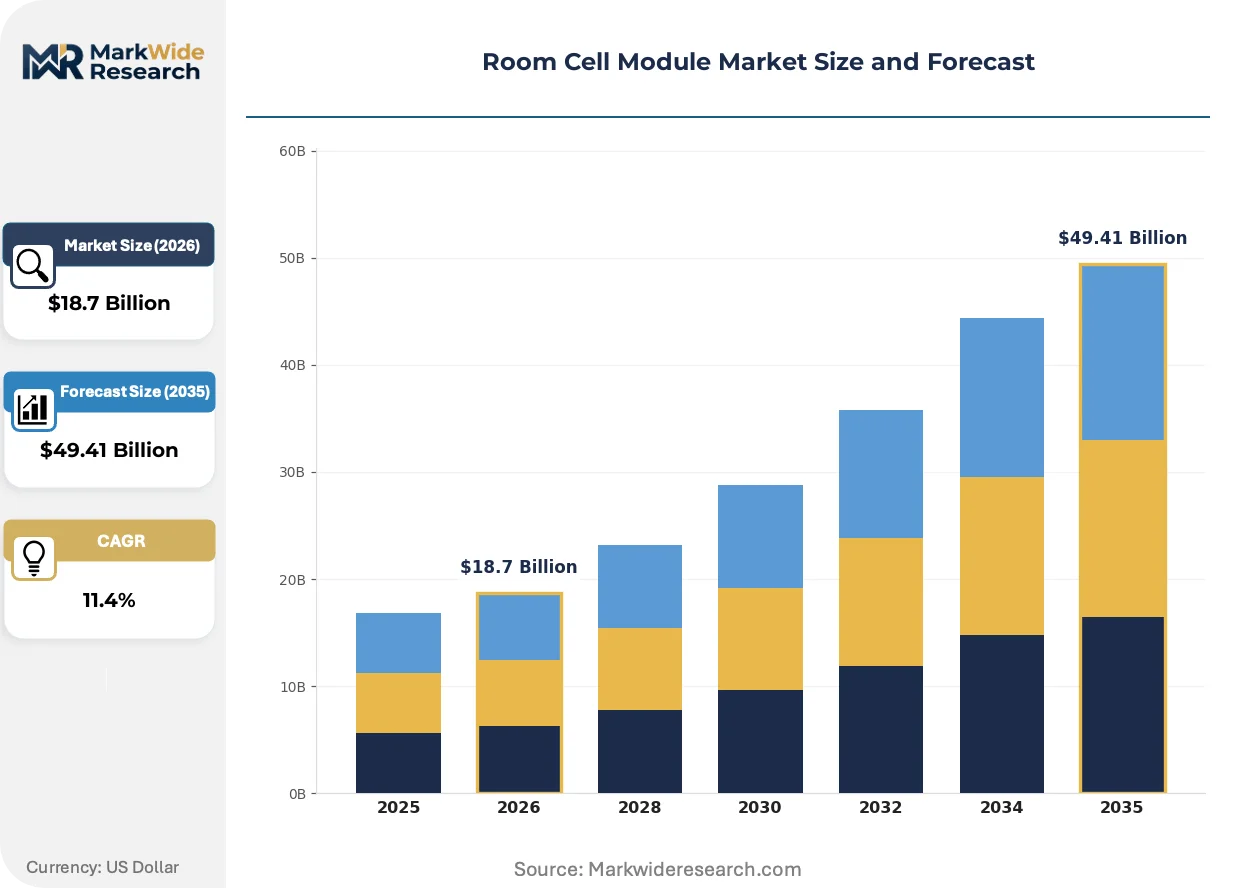
Market Dynamics
Data center operators in Germany are scaling modular cooling deployments as thermal loads from AI infrastructure exceed legacy HVAC capacity. The EU Energy Performance of Buildings Directive tightens efficiency mandates for prefabricated building envelopes, forcing manufacturers to redesign insulation cores and phase out high-GWP coolants.
Growth Catalysts
- Earthquake-resilient urban corridors:Japan's METI enforces JIS standards for seismic isolation in prefabricated units, which elevates structural engineering costs but opens premium positioning for certified suppliers in the Tokyo-Osaka corridor.
- AI-driven thermal density:Hyperscale data centers require compressor-based active modules with embedded cooling to manage rack power densities above 50kW per cabinet.
- EU F-Gas Regulation:The phasedown of high-GWP refrigerants accelerates R&D investment in CO2 and hydrocarbon-based climate control systems for industrial module applications.
Market Restraints
- Structural engineering cost inflation:Seismic certification requirements under Japan's METI add 15-25% to module fabrication costs without commensurate price elasticity in residential segments.
- Refrigerant supply concentration:Captive production of low-GWP alternatives concentrates among chemical majors in Germany and Japan, creating input bottlenecks for mid-tier assemblers.
- Passive module substitution ceiling:Thermal mass-based passive modules face hard performance limits above 35°C ambient, constraining deployment in subtropical data center markets.
Strategic Opportunities
- Educational institution hybridization:Universities in the US and EU seek seasonal flexibility through hybrid modules without full HVAC retrofit commitments, creating a price-insensitive niche.
- China's dual carbon goals:National targets for net-zero buildings drive provincial subsidies for GB-certified modular components in Yangtze River Delta manufacturing zones.
- Edge computing micro-data centers:Telecom infrastructure operators require IP54-rated outdoor modules for 5G base station enclosures in remote terrain.
Industry Challenges
- Cross-certification timeline compression:Manufacturers face 18-24 month validation cycles to secure concurrent GB, JIS, and REACH-F-Gas compliance for multi-region tenders.
- Building automation system lock-in:Siemens AG controls interface specifications that fragment module interoperability across European commercial installations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Room Cell Module Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $49.41 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Passive Modules, Active Modules, Hybrid Modules, Management Systems End User: Residential, Commercial, Industrial, Educational Institutions Installation Type: Indoor, Outdoor, Mobile, Fixed Connectivity: Wired, Wireless, Bluetooth, NFC |
| Companies Covered | Panasonic Corporation, Sharp Corporation, Samsung Electronics, Honeywell International Inc., Philips, LG Electronics, Toshiba Corporation, Siemens AG, Sony Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Room Cell Module Market Emerging Trajectories
Thermal management architectures are fragmenting across passive, active, and hybrid configurations as end-use requirements diverge. Regulatory pressure on refrigerants and seismic performance is accelerating material and structural innovation cycles.
Phase-change material (PCM) thermal storage is hybridizing conventional compressor-based cooling with passive thermal mass buffering. Data center operators in Frankfurt and Singapore are piloting PCM-integrated active modules to shave peak cooling loads during thermal transients. This convergence is compressing the performance gap between full active systems and lower-cost hybrid configurations.
The EU F-Gas Regulation mandates an 80% phasedown of hydrofluorocarbon refrigerants by 2030, forcing module OEMs to qualify CO2 transcritical and propane systems. Industrial cleanroom applications face the steepest compliance costs due to stringent leak detection requirements. German manufacturers are responding by consolidating refrigerant circuit fabrication in-house to protect margin structures.
Colocation providers are unbundling module procurement from long-term service contracts, shifting toward capital-sale models with third-party maintenance. This disintermediation pressures incumbent HVAC-integrated vendors who historically captured annuity revenue streams. The pattern is most visible in Northern Virginia's hyperscale corridor, where lease structures favor equipment ownership over managed services.
Room Cell Module Market Segmentation
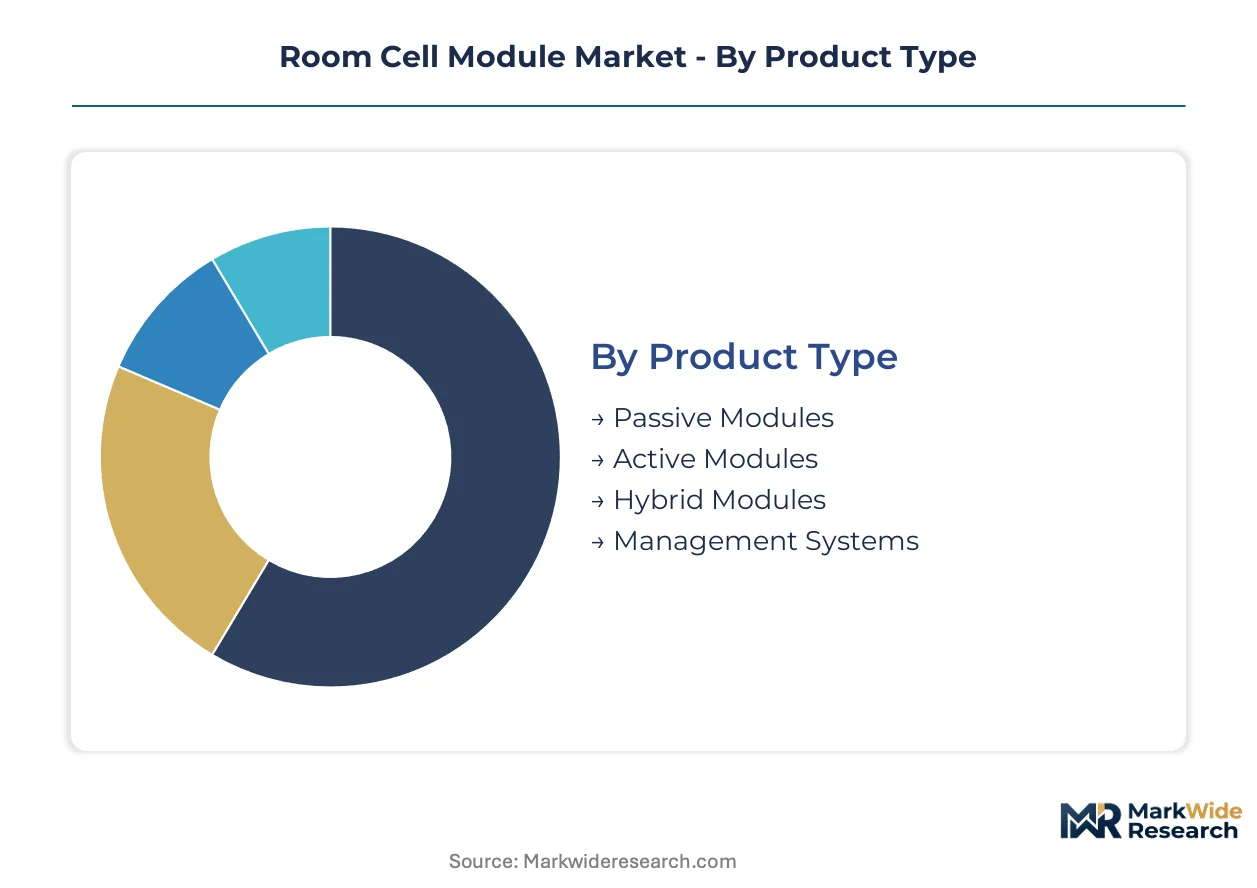
Room cell module segmentation reflects divergent thermal performance requirements across deployment contexts. Product architecture determines capital intensity and operational energy profiles, while end-use verticals impose distinct regulatory and structural certification burdens.
Product Type:
Mature passive configurations coexist with emerging active and hybrid architectures as thermal density requirements fragment across applications.
- Passive Modules:These units rely on thermal mass and natural ventilation without compressor-based cooling, typically achieving IP54 sealing through insulated panel construction. Residential developers in Germany favor passive modules for light commercial retrofits where EU Energy Performance of Buildings Directive compliance must balance capital constraints against envelope efficiency mandates.
- Active Modules:Embedded compressor-based cooling enables operation across -20°C to 50°C ambient ranges with precise humidity control. Hyperscale data center operators in Northern Virginia and Frankfurt deploy active modules to manage rack power densities exceeding 50kW per cabinet as AI infrastructure thermal loads exceed legacy HVAC capacity.
- Hybrid Modules:Seasonal flexibility configurations combine passive thermal buffering with selective active cooling activation. Universities in the US Northeast seek hybrid modules to avoid full HVAC retrofit commitments while maintaining laboratory-grade environmental stability during peak summer loads.
- Management Systems:Building automation interfaces integrate sensor networks, power distribution monitoring, and climate control optimization into centralized command architectures. Siemens AG specification control over European commercial installations creates interoperability constraints for third-party module OEMs.
Passive Modules retain volume leadership in residential and light commercial segments; Active Modules hold the steepest expansion curve as data center thermal density requirements intensify.
End User:
Cost tier stratification separates premium-certified industrial deployments from price-sensitive residential procurement.
- Residential:Single-family and multi-unit housing applications prioritize passive thermal management with minimal operational complexity. Japanese suppliers face 15-25% cost inflation from METI seismic certification requirements that lack price elasticity in consumer segments.
- Commercial:Office buildings and retail environments demand modular envelope solutions compatible with existing building automation infrastructure. EU F-Gas Regulation compliance costs concentrate in commercial retrofits requiring refrigerant circuit replacement.
- Industrial:Cleanroom and manufacturing applications specify active modules with stringent leak detection and contamination control. German manufacturers consolidate refrigerant circuit fabrication in-house to protect margins against phasedown of hydrofluorocarbon coolants.
- Educational Institutions:Universities and research facilities seek hybrid configurations for seasonal flexibility without capital-intensive permanent infrastructure commitments. US and EU procurement patterns favor capital-sale ownership models over historical managed service arrangements.
Commercial applications dominate current procurement volume; Educational Institutions are climbing the fastest as capital-sale disintermediation reshapes vendor relationships.
Installation Type:
Volume concentration favors fixed indoor deployments while mobility requirements expand addressable use cases.
- Indoor:Climate-controlled building envelope integration with standardized utility connections. Data center white space deployments in the Tokyo-Osaka corridor specify JIS-certified seismic isolation for indoor module arrays.
- Outdoor:IP54-rated enclosures with enhanced weatherproofing and thermal insulation for exposed deployment. Telecom infrastructure operators require outdoor modules for 5G base station enclosures in remote terrain.
- Mobile:Trailer-mounted or skid-based configurations for temporary or relocatable infrastructure. Emergency response and military applications drive specification for rapid-deployment mobile units.
- Fixed:Permanent foundation-mounted installations with hard utility connections and structural integration. Fixed installations capture the majority of industrial cleanroom and data center deployments.
Fixed installations retain structural preference for permanent infrastructure; Mobile configurations are gaining share fastest in telecom and emergency response verticals.
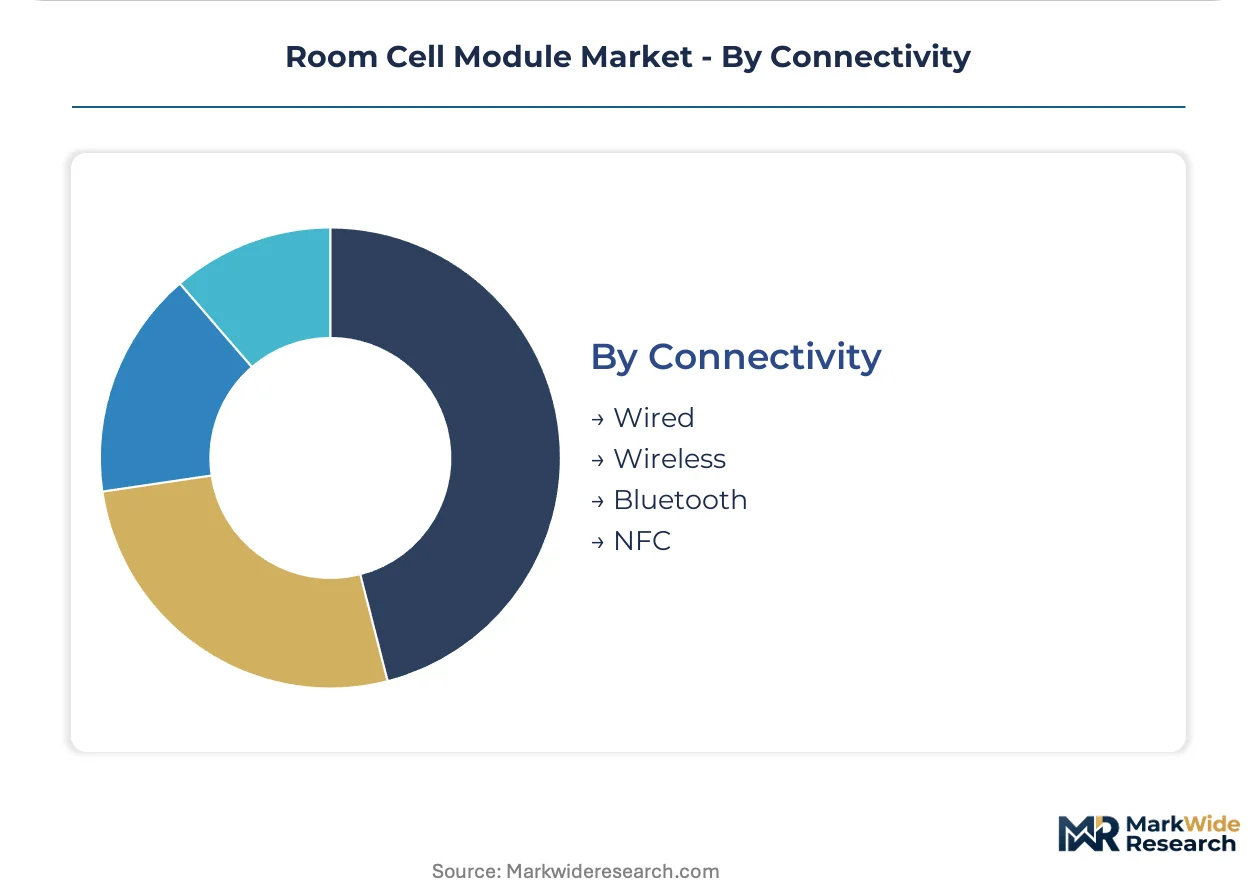
Connectivity:
Customer type differentiation separates hardwired industrial reliability from flexible wireless consumer interfaces.
- Wired:Ethernet and dedicated control cable architectures for high-reliability industrial applications. Wired connectivity dominates cleanroom and data center deployments where electromagnetic interference tolerance is critical.
- Wireless:Wi-Fi and cellular-enabled remote monitoring for distributed asset management. Wireless adoption accelerates in outdoor and mobile deployments where cable routing proves impractical.
- Bluetooth:Short-range device pairing for maintenance technician access and localized diagnostics. Bluetooth enables secure credential-based access without network infrastructure dependency.
- NFC:Near-field communication for physical asset identification and rapid configuration transfer. NFC tags streamline commissioning workflows in multi-module deployments.
Wired architectures maintain reliability leadership in industrial settings; Wireless connectivity shows the steepest expansion trajectory as distributed asset management requirements proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing of room cell modules clusters in East Asian electronics corridors and German industrial zones, with certification requirements fragmenting procurement patterns across regulatory jurisdictions. Module fabricators must navigate divergent compliance pathways spanning seismic codes, refrigerant phasedowns, and building efficiency mandates.
Germany
Hyperscale data center operators in Frankfurt and Berlin drive active module procurement for AI infrastructure thermal loads. The EU F-Gas Regulation mandates 80% hydrofluorocarbon phasedown by 2030, forcing refrigerant circuit redesigns. Bavarian manufacturers consolidate in-house production of CO2 transcritical systems to protect margin structures against compliance cost inflation.
Japan
METI enforces JIS seismic isolation standards for prefabricated units deployed across the Tokyo-Osaka earthquake-resilient corridor. Certified suppliers capture premium positioning as structural engineering costs inflate module fabrication by 15-25%. Nagoya-based fabricators anchor supply for industrial cleanroom applications requiring contamination control.
China
Provincial subsidies under dual carbon goals accelerate GB-certified modular component adoption in Yangtze River Delta manufacturing zones. Suzhou facilities integrate semiconductor-to-module production for display-integrated active modules. Shanghai regulators enforce thermal transmittance coefficients stricter than national baselines for commercial building envelopes.
United States
Universities in the Northeast seek hybrid modules for seasonal laboratory flexibility without permanent HVAC retrofits. Northern Virginia's hyperscale corridor favors capital-sale procurement models over managed service contracts. Telecom infrastructure operators require IP54-rated outdoor modules for 5G base station enclosures in remote terrain.
South Korea
Pyeongtaek anchors captive chip supply for display-integrated active module production serving domestic and export markets. Seoul Capital Area data center operators specify compressor-based cooling for rack densities exceeding 50kW per cabinet. Busan-Ulsan industrial zones fabricate structural frames for earthquake-resilient export configurations.
Room Cell Module Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream supplying climate control cores and sensor networks. The vendor base separates into three strategic archetypes: diversified electronics conglomerates with captive semiconductor supply, dedicated building automation specialists controlling interface specifications, and regional fabricators competing on seismic certification speed. Competitive moves concentrate on backward integration into refrigerant circuit production and geographic expansion through multi-region certification investments.
Among diversified Japanese electronics manufacturers, Panasonic Corporation and Sharp Corporation occupy positions spanning integrated semiconductor-to-module fabrication. Toshiba Corporation anchors the industrial cleanroom specialist tier with legacy expertise in contamination-controlled environments. These three exemplify the conglomerate archetype leveraging captive component supply to compress certification timelines across GB, JIS, and REACH-F-Gas compliance pathways.
| Leading Market Players |
|---|
| Panasonic Corporation |
| Sharp Corporation |
| Samsung Electronics |
| Honeywell International Inc. |
| Philips |
| LG Electronics |
| Toshiba Corporation |
| Siemens AG |
| Sony Corporation |
| Others |
Supply Flow & Price Mechanics
The Yangtze River Delta freight corridor compresses logistics costs for module fabricators while amplifying price differentiation between seismic-certified and baseline configurations. Supply concentration in East Asian electronics manufacturing clusters feeds downstream pricing power toward buyers with multi-region certification requirements, forcing mid-tier assemblers to absorb margin erosion or exit premium tenders.
Pricing Analysis
The EU F-Gas Regulation dictates the pricing tier structure across European procurement, separating CO2 transcritical system premiums from legacy refrigerant configurations facing compliance penalties. Three-tier pricing structure across premium seismic-certified, standard active-cooled, and economy passive modules reflects JIS certification costs and thermal performance differentials. Cost compression in economy passive tiers is intensifying because residential buyers in Germany and Japan lack price elasticity for premium features. Data center operators show least price sensitivity due to thermal density requirements, while residential developers represent the most price-constrained segment.
Supply Chain Analysis
Foxconn and Flex hold contract manufacturing capacity for climate control core assembly, with regional fabricators in Suzhou and Nagoya retaining captive production of structural frames and sensor networks. Supply concentrates in China, Japan, and Germany for finished modules, with South Korea anchoring display-integrated active component supply. Raw material dependencies span aluminum extrusions for seismic frames, phase-change materials for thermal buffering, and low-GWP refrigerants from German and Japanese chemical majors. Single-source vulnerability in refrigerant supply creates bottlenecks for mid-tier assemblers lacking backward integration. Distribution runs through building automation system integrators in Europe and direct OEM relationships in Asia-Pacific data center corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity emerges as thermal density requirements diverge across AI infrastructure, educational hybridization, and edge computing verticals, creating distinct certification and performance niches that resist commoditization.
For Market Incumbents: Build certification moats through concurrent GB, JIS, and REACH-F-Gas compliance investments that compress 18-24 month validation timelines below competitor reach. Siemens AG interface specification control and Panasonic captive semiconductor supply represent defensible positions against modular HVAC-integrated vendors facing disintermediation from capital-sale procurement shifts. Prioritize in-house refrigerant circuit production to protect margins against F-Gas phasedown cost inflation.
For New Entrants and Emerging Players: Pursue educational institution hybrid modules in the US Northeast and EU university corridors where seasonal flexibility requirements meet price-insensitive procurement. Edge computing micro-data centers for 5G base station enclosures in remote terrain offer penetrable white space with lower certification burden than hyperscale data center tiers. Go-to-market through telecom infrastructure operators seeking IP54-rated outdoor modules bypasses building automation system lock-in.
For Investors and Strategic Acquirers: Regional fabricators with seismic certification speed and Yangtze River Delta manufacturing access represent acquisition targets with defensible positioning in China-Europe dual-market tenders. Long-term viability hinges on refrigerant technology transition completion and building automation interface interoperability. Watch colocation provider procurement model shifts from managed services to capital-sale as inflection signal for vendor margin structure compression.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Refrigerant Circuits | Bavarian manufacturers consolidate CO2 transcritical production to protect margins against F-Gas compliance costs. |
| Concurrent Multi-Region Certification Investment | Panasonic and Sharp compress 18-24 month GB-JIS-REACH validation timelines to capture premium positioning. |
| Educational Institution Hybrid Module Launch | US Northeast universities seek seasonal flexibility without permanent HVAC retrofit capital commitments. |
| Edge Computing Micro-Data Center Expansion | Telecom operators require IP54 outdoor modules for 5G base station enclosures in remote terrain deployment. |
| Building Automation Interface Partnership | Third-party OEMs seek interoperability pathways around Siemens AG specification control in European commercial installations. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of EU F-Gas Regulation filings, METI JIS certification databases, and GB standards documentation for modular building components. Primary interviews engaged data center thermal infrastructure directors, building automation system integrators, and prefabricated construction procurement managers across Frankfurt, Tokyo, and Shanghai corridors. Secondary validation drew from customs trade data, SEC 10-K disclosures of diversified electronics conglomerates, and provincial subsidy records under China's dual carbon goals. Bottom-up module shipment aggregation and top-down infrastructure investment flow analysis provided cross-check triangulation.
Forecast inputs span product type segmentation across passive, active, and hybrid thermal architectures; end-user verticals from residential through educational institutions; and installation type differentiation between fixed indoor and outdoor IP54-rated deployments. CAGRs were derived from regression against data center power density trajectories and EU building efficiency mandate implementation schedules across the analysis window. Industry-specific inputs include AI infrastructure thermal load curves and seismic certification cost inflation rates under METI enforcement.
Macroeconomic conditions sit as an overlay; deviation in construction investment cycles, refrigerant raw material pricing, or cross-border certification timeline politics would shift the trajectory. Forecasts reflect assumptions around F-Gas phasedown adherence and dual carbon goal provincial subsidy continuity. Quarterly review of hyperscale data center capex announcements and METI certification backlog indicators is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telecom Hardware
Digital Smart Set-Top Box (STB) Market
Telecom Hardware
Broadcast Antenna Market
Telecom Hardware
Commercial Antennas Market
Telecom Hardware
4G Equipment Market
Telecom Hardware
Low Power Wide Area Network (LPWAN) Market
Telecom Hardware
LTE IoT Devices Market
Telecom Hardware
Global Microwave Transmission Equipment Market
Telecom Hardware
Point-To-Point Antenna Market
Telecom Hardware
OTN Hardware Market
Telecom Hardware
Digital TV Soc Market
Telecom Hardware
SATCOM Transceivers Market
Telecom Hardware
DWDM Transceiver Market
Telecom Hardware
Asia Pacific Enterprise Routers Market
Telecom Hardware
Voice Communication Equipment Market
Telecom Hardware
Global FPGA in Telecom Sector Market
Telecom Hardware
Industrial Transceivers Market