
 Commercial Antennas Market | 2026-2036
Commercial Antennas Market Size, Share, and Industry Trends Forecast 2026-2036
Commercial Antennas Market Outlook
Telecom operator procurement is restructuring commercial antenna demand as 5G network densification displaces legacy 4G-centric buying patterns. Amphenol Corporation leverages its connector-antenna integration capabilities to capture integrated system contracts. TE Connectivity sustains manufacturing scale across multi-band base station architectures. Molex anchors its position through specialized high-frequency interconnect solutions for mmWave deployments.
Commercial antennas are electromagnetic transducers engineered to radiate or receive radio waves across specified frequency bands, with gain patterns, impedance matching, and polarization characteristics determining system performance. Panel antennas dominate telecommunications infrastructure deployments due to their directional beamforming efficiency and compact form factors for urban cell towers. 5G technology segments are expanding fastest as massive MIMO arrays and beam-steering requirements multiply unit volumes per site. IoT application demand concentrates in low-power wide-area networks where omni-directional antennas with minimal power budgets command specialized design expertise.
The FCC governs spectrum allocation and equipment authorization under Part 15 and Part 27 rules, while the EU Radio Equipment Directive mandates CE marking for electromagnetic compatibility and efficient spectrum use. China's MIIT enforces GB standards for radio transmission equipment, creating divergent certification pathways that fragment supplier compliance investments. Stakeholders must monitor spectrum auction timelines and evolving national security review frameworks for antenna sourcing decisions.
Market Dynamics
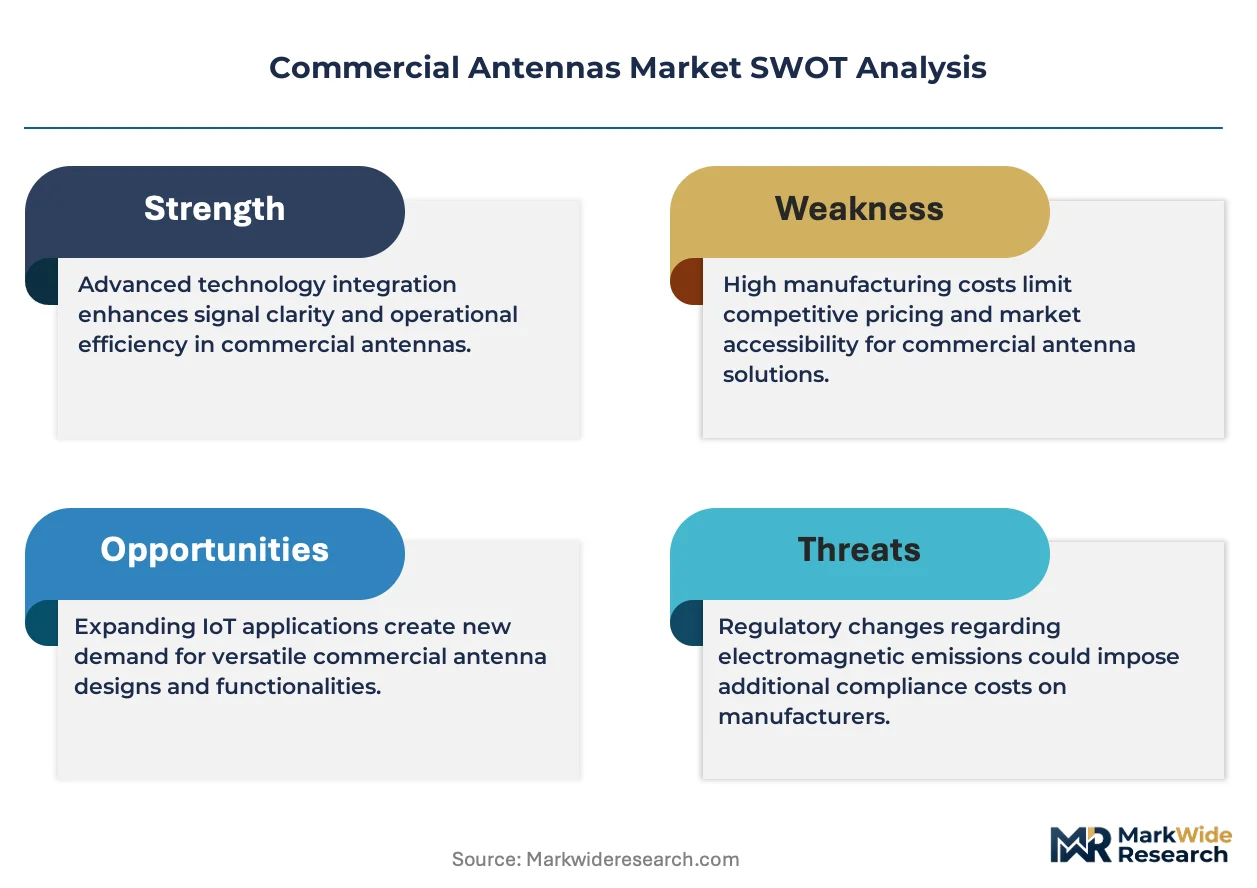
5G massive MIMO deployment is compressing procurement cycles while multiplying antenna counts per cell site, forcing suppliers to reconfigure manufacturing footprints for higher-frequency, lower-lot-size production.
Growth Catalysts
- MIIT spectrum allocation:China's accelerated base station buildouts under Ministry of Industry and Information Technology policies are absorbing panel antenna volumes at scale.
- Beam-steering silicon:Integration of active antenna systems with RF front-end modules is collapsing passive component layers into unified radiating elements.
- Telecom densification mandates:Urban small-cell requirements in United States metropolitan clusters are sustaining demand for compact, multi-band panel configurations.
Market Restraints
- Sub-6 GHz spectrum congestion:Limited contiguous bandwidth in mid-band allocations constrains channel bonding for enhanced mobile broadband deployments.
- Raw material concentration:High-purity copper and specialized dielectric substrates source predominantly from constrained Asian refining corridors.
- Electromagnetic compatibility testing:FCC Part 27 equipment authorization timelines extend lead times for new product introductions.
Strategic Opportunities
- Private 5G networks:Industrial campuses and logistics hubs in Germany are deploying localized massive MIMO arrays outside carrier infrastructure.
- Reconfigurable intelligent surfaces:Programmable metamaterials are converging with antenna arrays to enable dynamic propagation environment control.
- Open RAN disaggregation:Interface standardization is opening procurement channels to specialized antenna suppliers outside incumbent system integrators.
Industry Challenges
- mmWave calibration expertise:Phased array alignment and over-the-air testing require scarce RF engineering capabilities concentrated in defense-aerospace labor pools.
- Legacy 4G integration:Multi-standard base stations demand backward-compatible antenna architectures that complicate beam management firmware.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Commercial Antennas Market |
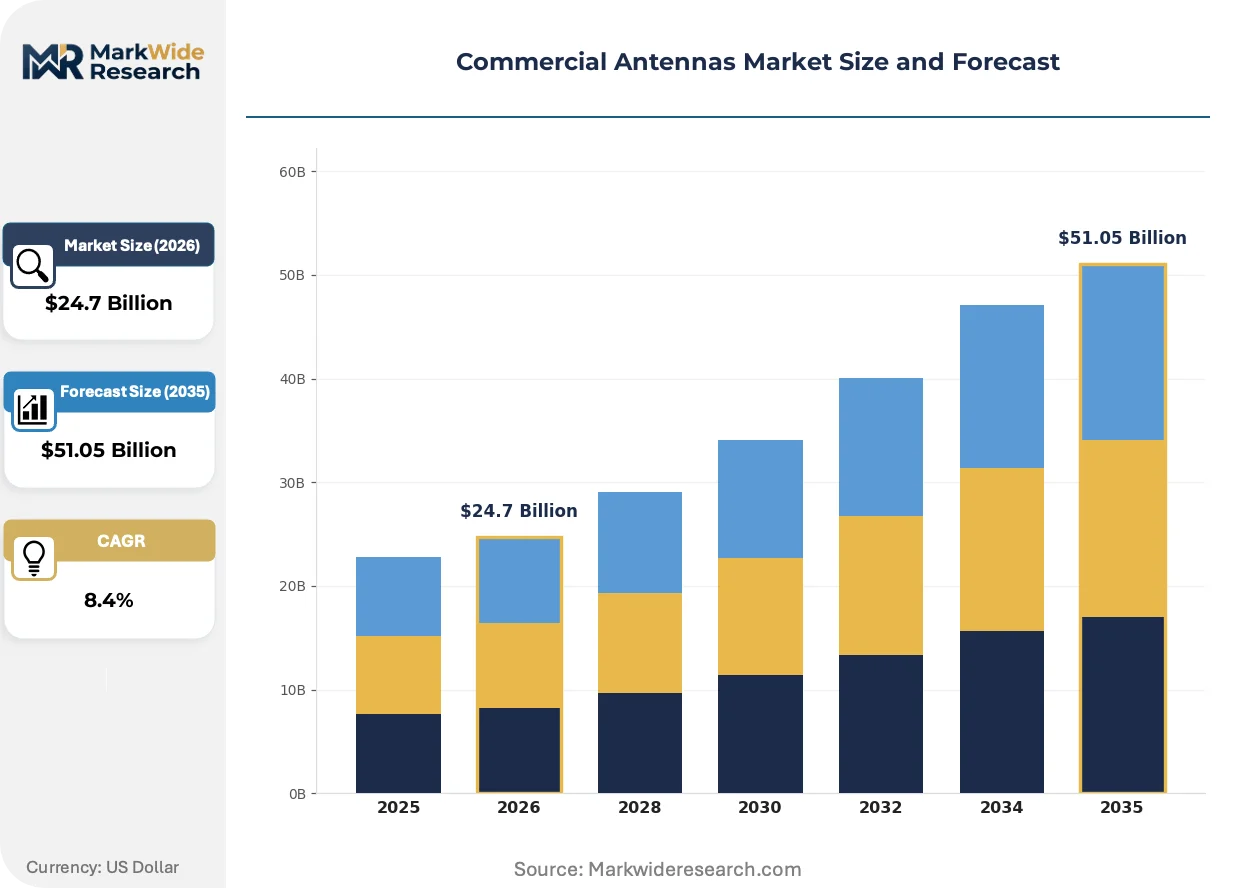
| Market Size in 2026 | $24.7 Billion |
| Market Size in 2035 | $51.05 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Panel Antennas, Dipole Antennas, Yagi Antennas, Omni-Directional Antennas Technology: 5G, LTE, Wi-Fi, Bluetooth Application: Telecommunications, Broadcasting, IoT, Public Safety End User: Telecom Operators, Government Agencies, Broadcasting Companies, Enterprises |
| Companies Covered | Amphenol Corporation, Molex, TE Connectivity, Murata Manufacturing, Airgain, Antenova, Taoglas, Linx Technologies, PCTEL, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Commercial Antennas Market Strategic Shifts
Antenna systems are transitioning from passive radiating elements to software-defined apertures, with AI-driven beam management and materials science breakthroughs compressing physical size while expanding functional bandwidth.
Metamaterial-engineered surfaces are automating electromagnetic response tuning without mechanical steering apparatus. Base station OEMs are embedding these substrates into urban small-cell housings to reduce wind load and visual footprint. The technology is automating real-time impedance matching across fragmented spectrum assignments, collapsing the need for discrete tuning circuits.
The EU Radio Equipment Directive's 2024 electromagnetic efficiency amendments are tightening spurious emission limits for base station equipment. Manufacturers serving European telecom operators must redesign filter architectures and retest existing product lines. mmWave backhaul units face the steepest compliance burden, with some suppliers withdrawing legacy SKUs rather than absorbing recertification costs.
Consolidated procurement through carrier-led infrastructure consortia is displacing fragmented equipment sourcing. Tier-1 operators in South Korea and Japan are mandating antenna-integrated radio units from approved vendor lists, squeezing standalone antenna suppliers. This concentration is most pronounced in urban 5G rollouts, where single-source accountability for RF performance reduces field integration risk.
Commercial Antennas Market Segmentation
Network infrastructure refresh cycles are fragmenting antenna demand across multiple performance tiers and deployment contexts. Procurement teams now specify products against discrete technology roadmaps rather than universal compatibility requirements.
Product Type:
Upgrade cycles for base station equipment are compressing replacement intervals while expanding the variety of form factors deployed per site.
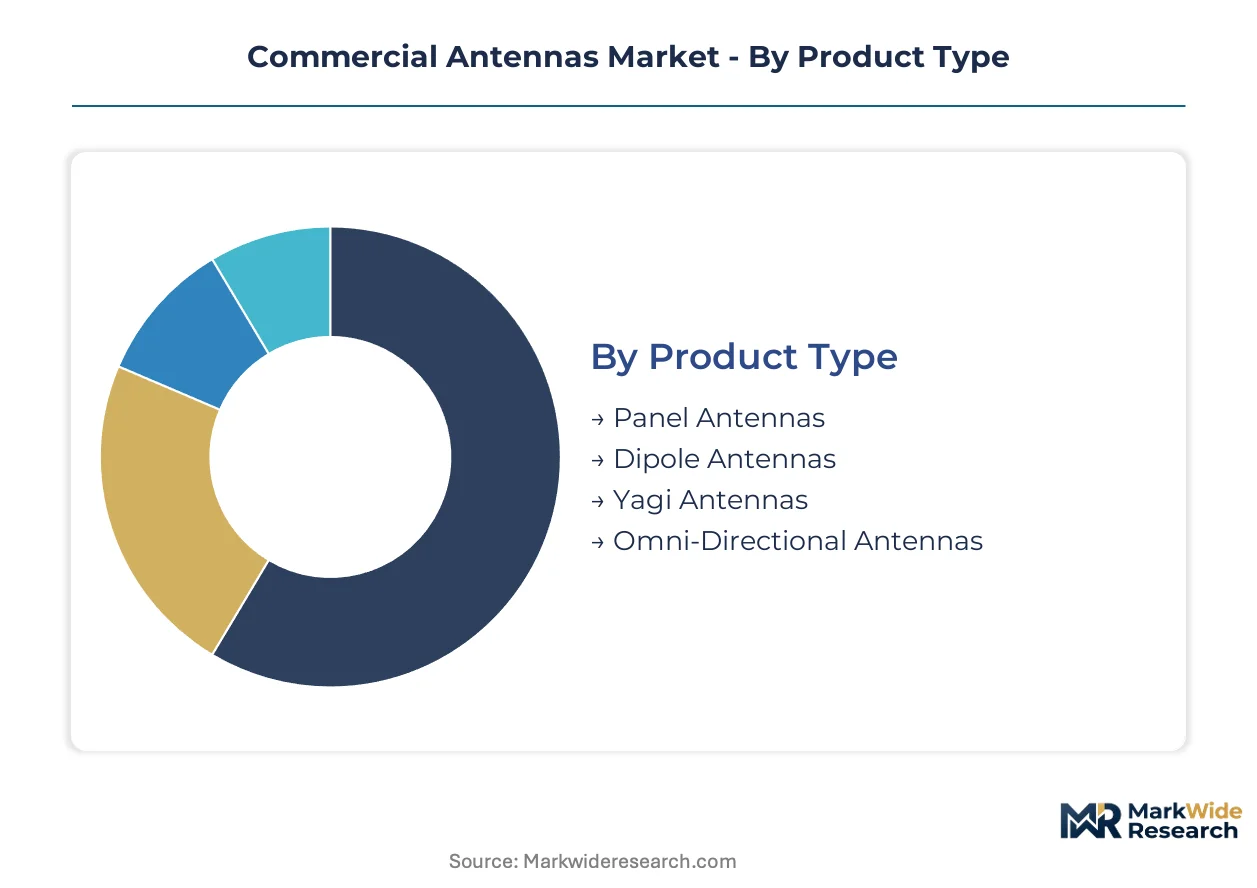
- Panel Antennas:Directional radiating elements with planar configurations enable precise beam steering for urban macro-cell coverage. Telecom operators in China are absorbing concentrated volumes as MIIT-directed base station buildouts accelerate. The compact footprint suits tower-sharing arrangements where wind loading and visual impact face municipal scrutiny.
- Dipole Antennas:Simple balanced radiators with omnidirectional azimuth patterns serve distributed antenna systems and indoor coverage solutions. Enterprises in Germany are deploying these for private 5G campus networks outside carrier infrastructure. The minimal manufacturing complexity supports rapid customization for non-standard frequency allocations.
- Yagi Antennas:Directional arrays with parasitic elements concentrate gain for point-to-point backhaul links.
- Omni-Directional Antennas:Uniform radiation patterns in the horizontal plane support IoT gateway deployments and mobile vehicle communications.
Volume placements concentrate in panel antennas; the faster expansion belongs to omni-directional configurations for IoT density.
Technology:
Cost tier differentiation separates premium active antenna systems from legacy passive architectures as carrier procurement tightens performance specifications.
- 5G:Massive MIMO arrays with active beamforming integrate RF front-end modules directly into radiating elements. South Korean operators are mandating these integrated units through approved vendor lists for urban densification. The technology collapses traditional passive component layers while multiplying unit counts per cell site.
- LTE:Established macro-cell infrastructure continues absorbing replacement volumes as carriers optimize sub-6 GHz spectrum efficiency. Rural buildouts in India under TRAI-directed universal service obligations sustain demand for backward-compatible configurations. Multi-standard base stations require these antennas to maintain legacy service during transition periods.
- Wi-Fi:Enterprise access point ecosystems drive high-volume demand for compact dual-band configurations.
- Bluetooth:Low-power protocols command specialized miniature antenna designs for wearable and sensor applications.
Cost tier separation is most pronounced between 5G active systems and legacy LTE passive units; steepest unit growth is climbing the fastest in Wi-Fi 6E and 7 enterprise deployments.
Application:
Application-specific performance requirements are fragmenting supplier portfolios as end-use divergence widens between consumer and industrial demand patterns.
- Telecommunications:Carrier-grade base station equipment demands rigorous environmental sealing and passive intermodulation control. Urban small-cell mandates in United States metropolitan clusters are sustaining demand for multi-band panel configurations. FCC Part 27 equipment authorization timelines extend lead times for new product introductions in this category.
- IoT:Low-power wide-area networks require minimal power budgets and omni-directional coverage patterns for sensor density. China's MIIT spectrum allocations for NB-IoT and Cat-M1 are concentrating module demand in domestic manufacturing corridors. Battery-constrained designs prioritize impedance matching efficiency over peak gain performance.
- Broadcasting:High-power terrestrial transmission systems require specialized thermal management and lightning protection.
- Public Safety:Mission-critical communications demand ruggedized enclosures and interoperability across fragmented frequency assignments.
Application divergence is widest between telecommunications volume scale and IoT unit fragmentation; public safety is gaining share fastest as FirstNet-style dedicated networks expand.
End User:
Customer type concentration is restructuring procurement channels as carrier-led infrastructure consortia displace fragmented equipment sourcing.
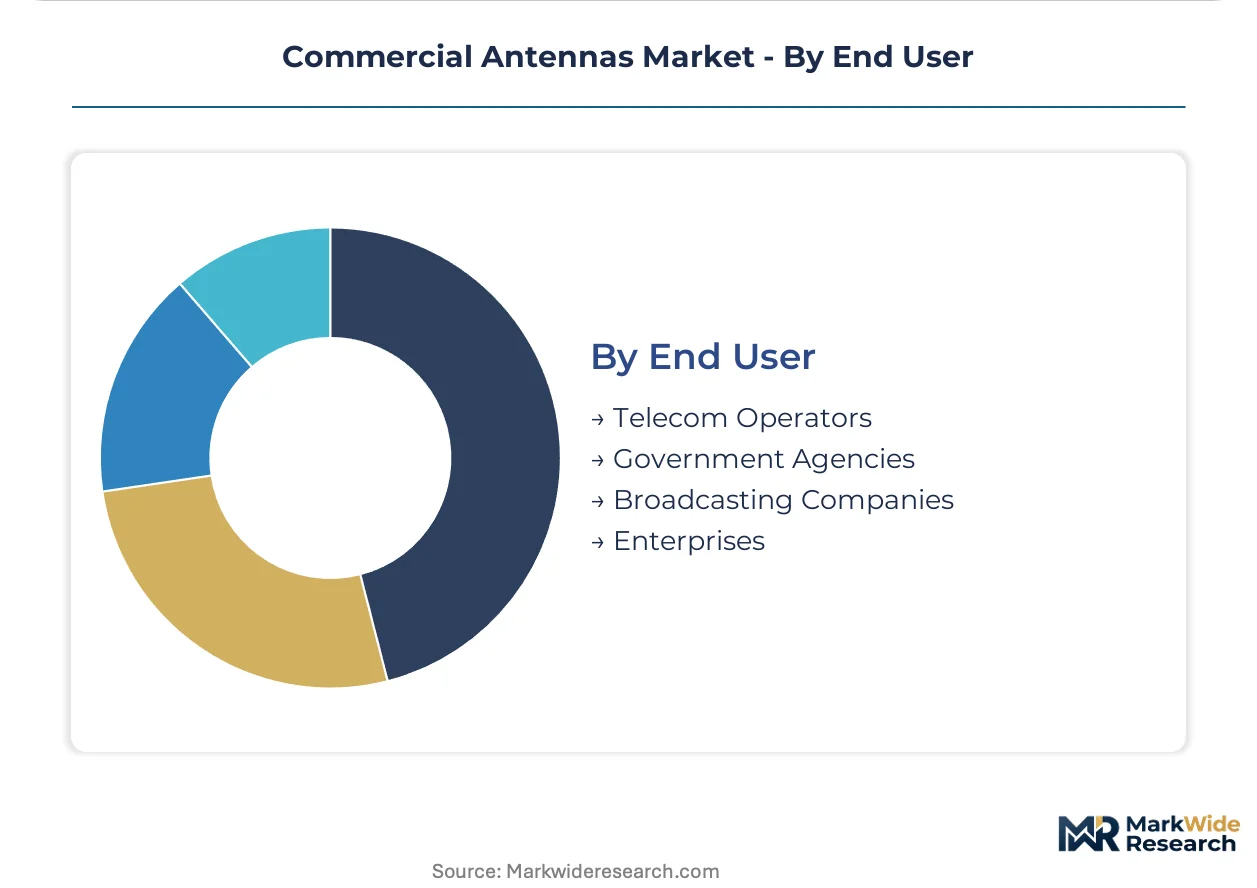
- Telecom Operators:Tier-1 carriers in Japan and South Korea are consolidating procurement through antenna-integrated radio unit specifications. Single-source accountability for RF performance reduces field integration risk in dense urban 5G rollouts. Approved vendor lists are squeezing standalone antenna suppliers outside incumbent system integrators.
- Government Agencies:Defense and public safety authorities require specialized ruggedization and secure supply chain documentation. Saudi Arabia's communications infrastructure investments under Vision 2030 are absorbing定向 antenna volumes for critical infrastructure protection. National security review frameworks complicate sourcing decisions for foreign equipment.
- Broadcasting Companies:Terrestrial television and radio operators sustain replacement demand for high-power transmission systems.
- Enterprises:Industrial campuses and logistics hubs are deploying localized massive MIMO arrays outside traditional carrier infrastructure.
Customer concentration favors telecom operator scale; enterprise direct procurement is expanding most quickly as private 5G networks bypass carrier intermediation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in Shenzhen and Dongguan concentrate panel antenna manufacturing capacity, drawing component suppliers into clustered supply corridors that serve both domestic Chinese deployments and export markets.
United States
FCC Part 27 equipment authorization timelines shape procurement cadences for urban small-cell densification. Tier-1 carriers in New York and Los Angeles metropolitan clusters specify multi-band panel configurations under municipal aesthetic mandates. The National Telecommunications and Information Administration coordinates federal spectrum repurposing that opens mid-band allocations for commercial 5G.
Germany
Industrial campuses in Bavaria deploy private 5G networks outside traditional carrier infrastructure, absorbing massive MIMO arrays for manufacturing automation. The EU Radio Equipment Directive's electromagnetic efficiency amendments force filter architecture redesigns for base station equipment. Munich and Stuttgart host system integrators specializing in campus network RF planning.
China
MIIT-directed base station buildouts under 5G spectrum allocation policies concentrate panel antenna demand in domestic manufacturing corridors. GB standards for radio transmission equipment create certification pathways that favor local suppliers. The Yangtze River Delta anchors production scale, with Suzhou and Shanghai facilities supplying integrated antenna-radio units.
South Korea
Approved vendor lists from tier-1 operators in Seoul mandate antenna-integrated radio specifications that compress standalone supplier margins. The Ministry of Science and ICT coordinates spectrum auctions that prioritize millimeter-wave allocations for urban hotspots. Busan-Ulsan industrial zones host testing facilities for over-the-air calibration of phased arrays.
India
TRAI-directed universal service obligations sustain rural LTE replacement demand alongside emerging 5G tenders. The Department of Telecommunications enforces mandatory testing and certification for imported radio equipment through designated labs. Bengaluru and Hyderabad concentrate RF engineering talent pools for base station antenna design services.
Commercial Antennas Market Competitive Environment
Top-tier vendors anchor carrier-grade infrastructure contracts, while mid-tier specialists occupy private network and IoT application niches. The market exhibits tiered concentration with three to five integrated suppliers commanding telecommunications operator procurement, and fragmented competition below that threshold. Connector-integrators, substrate specialists, and RF module houses represent the dominant strategic archetypes. Consolidation through approved vendor list mandates and capacity expansion into higher-frequency production lines constitute the primary competitive vectors.
Within the connector-integrator tier, Amphenol Corporation and TE Connectivity occupy positions that exemplify system-level contract capture through component-antenna integration capabilities. Molex anchors the specialized interconnect segment, representing the archetype of high-frequency solution providers for millimeter-wave deployment contexts.
| Leading Market Players |
|---|
| Amphenol Corporation |
| Molex |
| TE Connectivity |
| Murata Manufacturing |
| Airgain |
| Antenova |
| Taoglas |
| Linx Technologies |
| PCTEL |
| Others |
Value Chain & Pricing Dynamics
London Metal Exchange copper price volatility cascades through commercial antenna manufacturing, compressing margins on high-purity conductor assemblies while amplifying cost differentials between integrated RF module suppliers and standalone antenna vendors serving price-sensitive IoT module makers.
Pricing Analysis
Lead-time-driven pricing stratification separates urgent procurement premiums from spot inventory discounts across carrier infrastructure contracts. Three-tier pricing structure across premium, standard, and economy levels reflects FCC Part 27 certification status, with CE-marked active antenna systems commanding sustained premiums over uncertified alternatives. Price erosion runs through legacy LTE passive units as Chinese panel manufacturers absorb volume concentration. Telecom operators exhibit lowest price sensitivity for urban densification projects, while enterprise private 5G deployments show acute cost consciousness on per-site economics.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale carrier procurement, while distribution partners serve fragmented enterprise and IoT demand. Manufacturing concentrates in China, South Korea, and Taiwan, with Suzhou and Shanghai anchoring panel antenna fabrication and Kaohsiung hosting specialized dielectric substrate production. High-purity copper, liquid crystal polymer substrates, and gallium arsenide RF components feed from constrained Asian refining corridors. Single-source vulnerability in specialized dielectric materials threatens continuity for millimeter-wave array production. Distribution runs through carrier-approved vendor lists that compress standalone supplier access to tier-1 infrastructure contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Commercial antenna supply remains structurally constrained by scarce mmWave calibration expertise concentrated in defense-aerospace labor pools, propping pricing power for qualified suppliers despite raw material cost compression elsewhere.
For Market Incumbents: Deepen backward integration into specialized dielectric substrate production to secure supply continuity for active antenna systems. Add captive calibration capacity in Busan-Ulsan industrial zones to reduce dependency on defense-aerospace labor pools. Consolidate procurement channel control through antenna-integrated radio unit specifications that squeeze standalone competitors. For New Entrants and Emerging Players: Capture private 5G campus network opportunities in German industrial corridors where carrier infrastructure bypass creates procurement openness. Target IoT module antenna customization for China's NB-IoT and Cat-M1 deployments under MIIT spectrum allocations. Pursue Open RAN disaggregation as the primary go-to-market angle to circumvent incumbent system integrator lock-in. For Investors and Strategic Acquirers: Distressed-cycle entries favor specialized high-frequency interconnect suppliers in South Korea where approved vendor list compression creates consolidation pressure. Five-to-ten year viability hinges on millimeter-wave capability depth rather than legacy sub-6 GHz scale. Monitor FCC Part 27 equipment authorization timeline extensions as the inflection signal for supplier margin stress.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Dielectric Substrates | Captive supply of liquid crystal polymer materials insulates against Asian refining corridor disruptions. |
| Calibration Capacity Expansion | Busan-Ulsan testing facilities reduce phased array alignment bottlenecks for mmWave deployments. |
| Open RAN Interface Certification | Standardized procurement channels open access to disaggregated carrier infrastructure contracts. |
| Private 5G Campus Network Partnerships | Bavarian industrial automation demand bypasses tier-1 carrier intermediation. |
| EU Radio Equipment Directive Compliance Investment | Spurious emission limit adherence preserves European base station equipment market access. |
Study Parameters
Independent corroboration across RF engineering directors, carrier procurement leads, base station OEM technical teams, and regulatory affairs specialists underwrites the qualitative findings. Primary interviews with antenna system architects and manufacturing operations heads combined with secondary validation from FCC equipment authorization databases, MIIT GB standard filings, EU Radio Equipment Directive implementation notices, and customs trade data. Bottom-up demand modeling across deployment scenarios triangulates against top-down infrastructure investment tracking.
Comparable-period anchoring to historical base station buildout cycles informs the projection horizon's demand trajectory assumptions. Segmentation dimensions span product type, technology generation, application context, and end-user procurement channel. CAGRs derive from unit volume elasticity against spectrum allocation timelines and infrastructure densification mandates. Forecast inputs incorporate MIIT-directed buildout cadences and FCC Part 27 authorization velocity.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to millimeter-wave spectrum auction delays and raw material supply corridor disruptions. Forecasts reflect documented assumptions on carrier densification commitments and regulatory authorization efficiency. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telecom Hardware
United States Set-Top Box Market
Telecom Hardware
Infiniband Market
Telecom Hardware
Parabolic Antenna Market
Telecom Hardware
Global Microwave Transmission Equipment Market
Telecom Hardware
Synchronous Optical Network (SONET) Market
Telecom Hardware
Very Small Aperture Terminal (VSAT) Market
Telecom Hardware
Point-To-Point Microwave Antenna Market
Telecom Hardware
Microwave Antenna Market
Telecom Hardware
Europe Set-Top Box Market
Telecom Hardware
Global Time Sensitive Networking Market
Telecom Hardware
Land Mobile Radio System Market
Telecom Hardware
Low Power Wide Area Network (LPWAN) Market
Telecom Hardware
5G Temperature-Compensated Crystal Oscillator (TCXO) Market
Telecom Hardware
Global Mobile Phone Loudspeaker Market
Telecom Hardware
Subscriber Identity Module (SIM) Market
Telecom Hardware
Laser Communications Terminals (Lcts) Market