
 Point-To-Point Microwave Antenna Market | 2026-2036
Point-To-Point Microwave Antenna Market Size, Share, and Industry Trends Forecast 2026-2036
Point-To-Point Microwave Antenna Market Outlook
The capital-intensity gap between integrated radio manufacturers and pure-play antenna specialists is collapsing as silicon integration and software-defined radio platforms commoditize discrete RF front-end components. CommScope leverages its cable and connectivity infrastructure to bundle antenna solutions with fiber backhaul, sustaining pricing power across integrated deployments. Huawei Technologies anchors its position through in-house semiconductor and antenna design, while Nokia competes on Open RAN interoperability and multi-vendor orchestration capabilities.
A point-to-point microwave antenna is a directional aperture antenna engineered for line-of-sight transmission in the 1 GHz to 90 GHz range, typically fabricated from aluminum or composite substrates with precision-machined reflector surfaces and waveguide feed assemblies to achieve gain values from 30 dBi to 50 dBi. These antennas establish high-capacity wireless bridges between fixed locations, serving as critical backhaul infrastructure where fiber deployment proves economically or physically impractical. Parabolic designs dominate installed base volume due to established performance benchmarks and field-proven reliability across decades of terrestrial link operation. Licensed spectrum technology commands premium positioning as carriers prioritize interference protection for long-haul routes, while flat panel configurations are gaining traction in urban 5G small cell densification where wind loading and aesthetic constraints limit traditional dish footprints.
The Federal Communications Commission governs microwave spectrum allocation and licensing in the United States, with recent rulemakings expanding E-band availability to accelerate 5G backhaul deployment. European operators navigate the Radio Spectrum Decision framework alongside national regulatory authorities implementing the European Electronic Communications Code harmonization. India's Wireless Planning and Coordination Wing manages microwave frequency coordination for telecom infrastructure under Department of Telecommunications oversight. Stakeholders must monitor spectrum reframing timelines and equipment authorization pathways as regulatory bodies reallocate legacy bands toward higher-capacity digital modulation schemes.
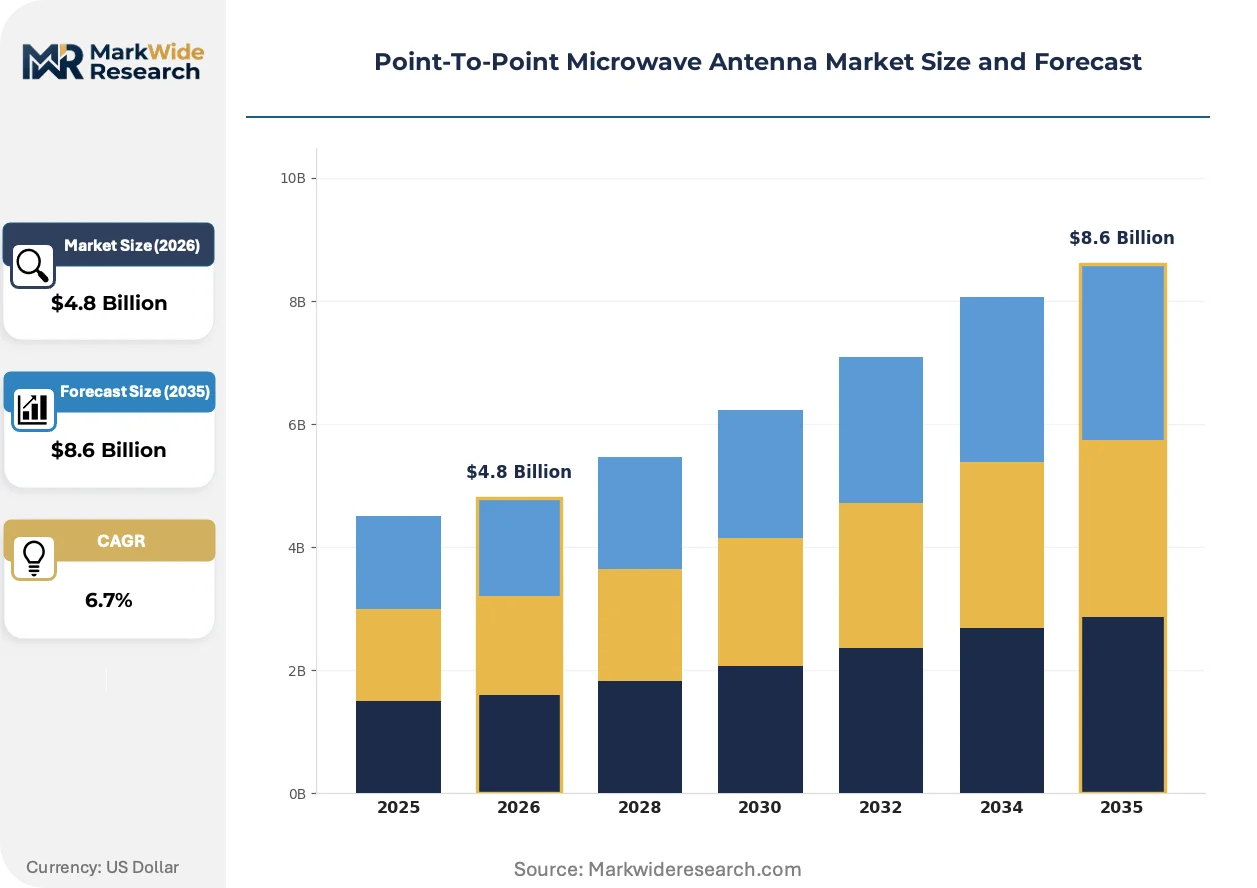
Market Dynamics
Spectrum liberalization at E-band and V-band frequencies is compressing the cost-per-bit economics of wireless backhaul, forcing infrastructure planners to reassess fiber-first deployment strategies across dense urban corridors and remote rural links alike.
Growth Catalysts
- 5G Densification Mandates:Mobile network operators in India are expanding microwave backhaul to support small cell deployments under TRAI's connectivity directives for underserved districts.
- E-Band Spectrum Liberalization:The FCC's recent rulemakings in the United States have unlocked 70/80 GHz bands for high-capacity links, reducing licensing friction for metro backhaul.
- Composite Reflector Materials:Precision-machined aluminum alternatives are lowering antenna weight profiles, enabling faster tower mounting and reducing structural load requirements.
Market Restraints
- Line-of-Sight Obligation:Terrestrial microwave links require unobstructed transmission paths, rendering the technology impractical for heavily forested or mountainous terrain without costly relay infrastructure.
- Fiber Substitution Threat:Submarine and terrestrial fiber deployments in coastal India and Gulf Cooperation Council states are capturing backhaul volume that microwave previously dominated.
- Input Cost Volatility:Aluminum feedhorn and waveguide assemblies face price pressure from energy-intensive smelting operations concentrated in specific mining jurisdictions.
Strategic Opportunities
- Flat Panel Form Factor Adoption:Urban 5G small cell deployments in wind-sensitive locations are creating demand for low-profile antennas that reduce aesthetic objections and permitting delays.
- Rural India Connectivity Gaps:Bharat Sanchar Nigam Limited's rural infrastructure programs present white space for cost-optimized microwave links where fiber trenching remains uneconomical.
- Software-Defined Radio Convergence:Integration of digital modulation platforms with antenna systems is enabling dynamic capacity allocation and spectrum agility for licensed band operators.
Industry Challenges
- RF Engineering Talent Scarcity:Specialized expertise in millimeter-wave propagation modeling and antenna pattern optimization remains concentrated among legacy equipment specialists, constraining deployment velocity.
- Multi-Vendor Interoperability Complexity:Open RAN orchestration requirements are forcing antenna suppliers to validate performance across disaggregated radio platforms, extending certification timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Point-To-Point Microwave Antenna Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Parabolic, Flat Panel, Offset Feed, Horn Technology: Analog, Digital, Unlicensed, Licensed End User: Telecommunications, Broadcasting, Military, Enterprise Installation: Fixed, Mobile, Portable, Temporary |
| Companies Covered | CommScope, Ericsson, Huawei Technologies, Cambium Networks, Ceragon Networks, Aviat Networks, Nokia, Radio Frequency Systems, mWAVE Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Point-To-Point Microwave Antenna Market Strategic Shifts
Antenna architecture is splitting between high-gain parabolic designs for long-haul routes and compact flat-panel configurations for urban densification, with material science and digital beamforming driving divergence in engineering priorities.
Parabolic reflector technology is bifurcating as traditional aluminum dish designs retain dominance in licensed long-haul applications while composite substrate alternatives penetrate urban small cell deployments. Bharat Sanchar Nigam Limited and private Indian carriers are adopting hybrid procurement strategies that match dish size to link distance. This split is compressing the addressable market for mid-size aperture antennas as buyers polarize toward either maximum gain or minimum footprint.
The European Electronic Communications Code harmonization is mandating spectrum reframing timelines that accelerate migration from legacy frequency bands toward higher-capacity digital modulation schemes. National regulatory authorities within EU member states are coordinating equipment authorization pathways to reduce cross-border interference. Microwave link planners in Germany and France are responding by front-loading capital deployment ahead of anticipated band reallocation deadlines.
Buyer concentration among tier-one mobile network operators is compressing vendor negotiation cycles and unbundling after-sales service contracts from hardware procurement. Infrastructure procurement teams in India are migrating toward framework agreements that specify performance-based availability targets rather than equipment specifications. This behavioral shift is most visible in Maharashtra and Gujarat states, where Reliance Jio and Bharti Airtel have consolidated supplier panels.
Point-To-Point Microwave Antenna Market Segmentation
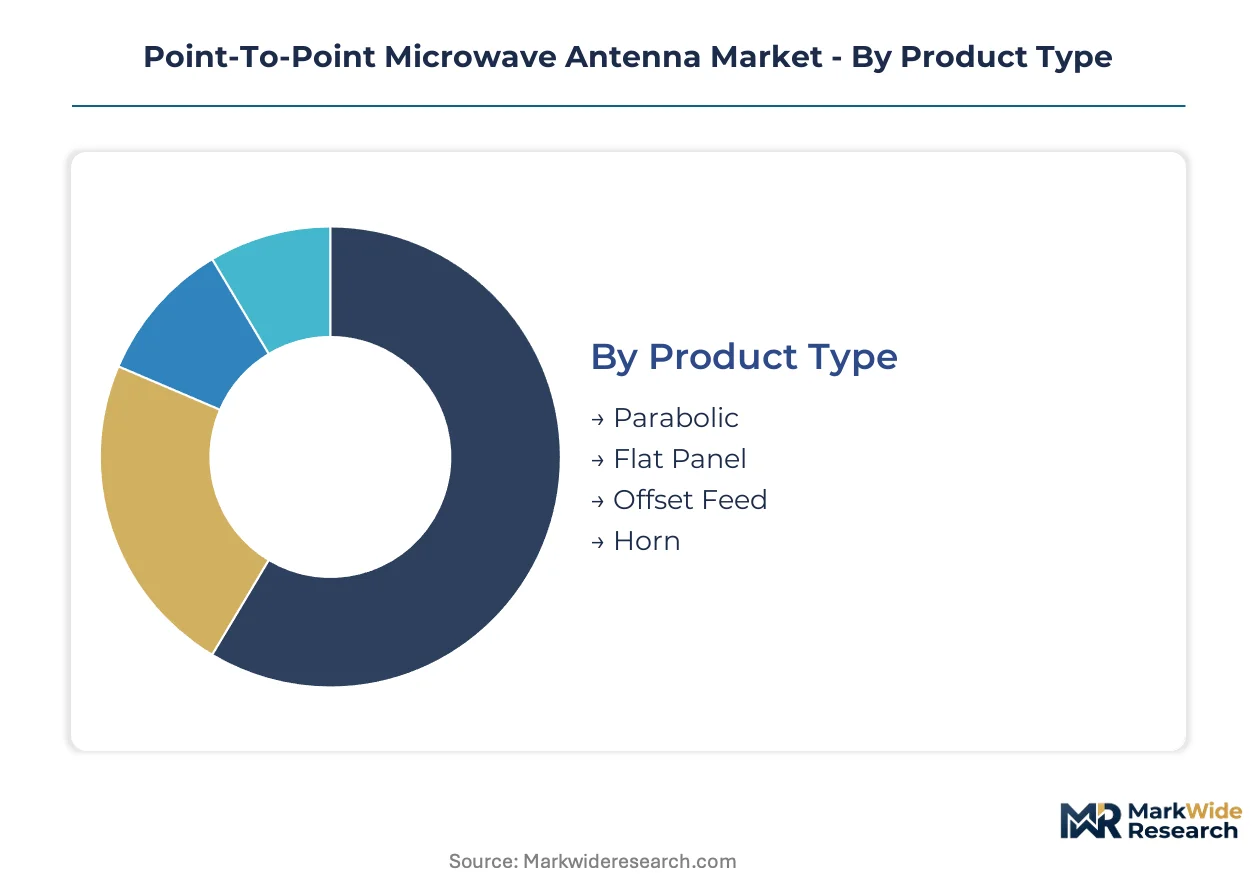
Antenna procurement patterns diverge sharply across deployment contexts, with spectrum licensing status and physical form factor commanding disproportionate margin capture relative to raw production costs. Infrastructure planners weight total cost of ownership calculations differently across rural long-haul versus urban small cell applications.
Product Type:
Margin pools concentrate in precision-machined reflector assemblies where surface accuracy tolerances below 0.5 millimeters create manufacturing moats.
- Parabolic:Aluminum or composite reflector dishes achieve gain values from 30 dBi to 50 dBi through precision-machined surfaces and waveguide feed assemblies. Bharat Sanchar Nigam Limited deploys these for rural backhaul across Maharashtra and Gujarat where link distances exceed 10 kilometers. Licensed spectrum mandates favor parabolic designs for interference protection on long-haul routes.
- Flat Panel:Low-profile aperture antennas utilizing phased array or printed circuit board architectures reduce wind loading and visual footprint. Urban 5G densification in wind-sensitive locations drives procurement, with aesthetic constraints accelerating permitting approvals. Composite substrates lower structural load requirements on existing tower infrastructure.
- Offset Feed:Asymmetric reflector geometry positions the feedhorn outside the primary radiation path to minimize blockage losses. Compact tower mounting configurations suit constrained rooftop deployments.
- Horn:Waveguide-fed aperture antennas deliver broadband performance without reflector assemblies for short-range links. Simplified manufacturing reduces unit costs for enterprise campus applications.
The dominant share belongs to Parabolic configurations, while Flat Panel is closing the gap fastest.
Technology:
Cost tier stratification separates premium licensed spectrum equipment from commodity unlicensed alternatives.
- Analog:Legacy frequency modulation systems dominate installed base maintenance cycles. Indian operators retain analog links in remote districts where digital migration capital remains constrained.
- Digital:Advanced modulation schemes including 4096-QAM compress bandwidth requirements and enable spectrum refarming. German and French carriers front-load capital deployment ahead of European Electronic Communications Code deadlines.
- Unlicensed:5.8 GHz and 24 GHz band equipment avoids licensing fees for enterprise and temporary deployments. Interference exposure limits reliability for carrier-grade backhaul.
- Licensed:Coordinated frequency assignments through national regulators guarantee interference protection. FCC E-band rulemakings in the United States unlocked 70/80 GHz bands for high-capacity metro links.
Licensed technology captures premium positioning, with Digital climbing fastest as spectrum refarming accelerates.
End User:
Customer type determines procurement scale and service contract bundling intensity.
- Telecommunications:Mobile network operators represent concentrated demand volume, with Reliance Jio and Bharti Airtel consolidating supplier panels across framework agreements. Performance-based availability targets now supersede equipment specifications in Indian procurement.
- Broadcasting:Television and radio distribution networks utilize microwave for studio-transmitter links. Regulatory mandates for rural coverage sustain niche demand.
- Military:Secure tactical communications require ruggedized antennas with electronic counter-countermeasures. Procurement cycles extend through defense authorization pathways.
- Enterprise:Campus interconnect and private 5G networks drive mid-volume procurement with shorter sales cycles. Manufacturing facilities favor rapid deployment over maximum spectral efficiency.
Telecommunications commands volume leadership, with Enterprise expanding most quickly through private network buildouts.
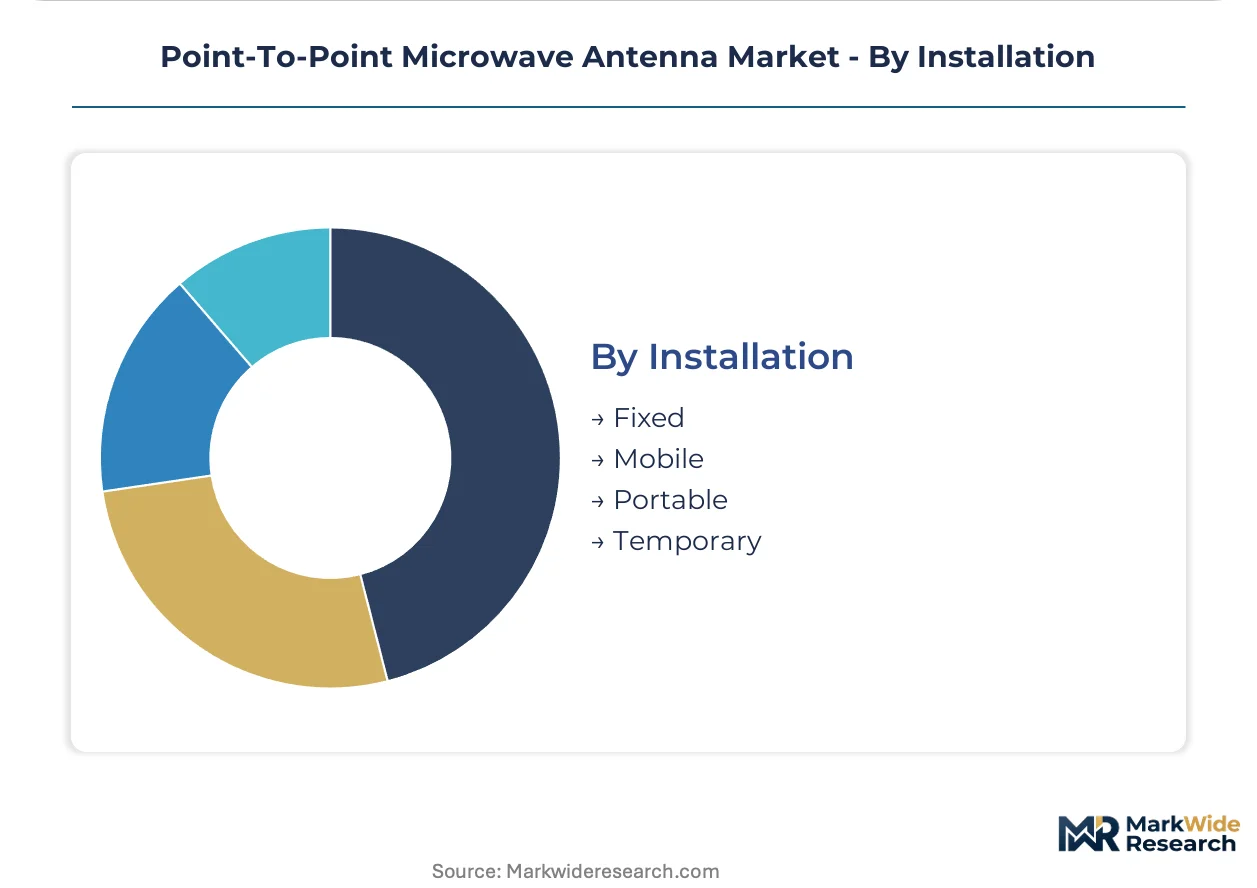
Installation:
Volume distribution skews toward permanent infrastructure despite temporary deployment growth in emergency response.
- Fixed:Permanent tower or rooftop mounting dominates carrier backhaul deployment. Structural engineering surveys and permitting timelines extend project durations.
- Mobile:Vehicle-mounted configurations serve broadcast news gathering and military field operations. Rapid repositioning requires stabilized antenna pointing systems.
- Portable:Man-transportable units deploy for disaster recovery and temporary event coverage. Battery power constraints limit transmit power and link distance.
- Temporary:Rapid-deployment links bridge construction periods or fiber cut restoration. Rental models reduce capital commitment for short-duration requirements.
Fixed installation retains structural dominance, with Temporary gaining share fastest through disaster resilience planning.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Import dependence for precision-machined aluminum reflector assemblies tilts toward Chinese and German suppliers, while India and the United States absorb the majority of finished antenna system exports for backhaul deployment.
United States
FCC E-band rulemakings unlocked 70/80 GHz spectrum for high-capacity metro links, accelerating 5G backhaul procurement by Verizon and T-Mobile. Tower companies in Texas and California front-load antenna orders ahead of permitting deadlines. Dallas-Fort Worth anchors deployment velocity for urban small cell densification.
India
Bharat Sanchar Nigam Limited and Reliance Jio expand microwave backhaul across Maharashtra and Gujarat under TRAI rural connectivity mandates. The Wireless Planning and Coordination Wing expedites frequency coordination for telecom infrastructure. Tower infrastructure in Gujarat concentrates procurement for links exceeding 10 kilometers.
Germany
Deutsche Telekom and Vodafone Germany front-load capital deployment ahead of European Electronic Communications Code spectrum reframing deadlines. The Bundesnetzagentur coordinates cross-border interference protocols with French and Polish regulators. The Rhine-Ruhr industrial corridor concentrates precision machining capacity for waveguide feed assemblies.
China
MIIT spectrum allocations prioritize millimeter-wave backhaul for 5G-Advanced networks in the Yangtze River Delta. State-owned carriers consolidate procurement panels under framework agreements specifying availability targets. Shenzhen and Dongguan anchor manufacturing clusters for composite substrate antenna components.
United Arab Emirates
Etisalat and du deploy E-band links for smart city infrastructure across Dubai and Abu Dhabi under TDRA spectrum harmonization directives. The country's fiber-microwave hybrid strategy preserves wireless backhaul for critical resilience pathways. Dubai South logistics corridor concentrates staging for African and South Asian export markets.
Point-To-Point Microwave Antenna Market Competitive Environment
Concentration sits with integrated radio-access-network vendors that bundle antenna systems with baseband and radio units, compressing margin pools for pure-play antenna specialists. The vendor base stratifies across three tiers: semiconductor-integrated platform owners, connectivity infrastructure bundlers, and regional fabrication specialists. Competitive moves center on Open RAN interoperability certification and composite material sourcing partnerships.
Among platform-integrated vendors, Huawei Technologies and Nokia occupy positions that exemplify divergent strategic postures—one anchored in captive semiconductor design, the other in multi-vendor orchestration capabilities. CommScope represents the infrastructure-bundling archetype, leveraging cable and connectivity assets to sustain pricing power across integrated deployments. These three entities collectively illustrate how vertical scope, rather than antenna specialization alone, determines competitive position in procurement cycles governed by tier-one mobile network operators.
| Leading Market Players |
|---|
| CommScope |
| Ericsson |
| Huawei Technologies |
| Cambium Networks |
| Ceragon Networks |
| Aviat Networks |
| Nokia |
| Radio Frequency Systems |
| mWAVE Industries |
| Others |
Value Chain & Pricing Dynamics
Long-term framework agreements with tier-one mobile network operators lock in supply access for precision-machined reflector assemblies while anchoring price visibility across multi-year deployment cycles. These contracts bundle antenna hardware with performance-based availability guarantees, compressing margin negotiation into total cost-of-ownership calculations rather than unit pricing.
Pricing Analysis
Industrial OEM buyers anchor three-tier pricing structure across premium, standard, and economy levels in antenna procurement. Premium tiers capture licensed spectrum configurations with FCC and TRAI certification, while economy tiers serve unlicensed enterprise deployments. Price differentiation rests on surface accuracy tolerances below 0.5 millimeters and composite substrate material grades. Cost compression in standard-tier parabolic dishes is intensifying because silicon integration commoditizes discrete RF front-end components. Mobile network operators in India exhibit highest price sensitivity through consolidated supplier panels, whereas military procurement demonstrates lowest sensitivity due to electronic counter-countermeasures requirements.
Supply Chain Analysis
Inventory lead times for precision-machined aluminum reflector assemblies extend through energy-intensive smelting operations concentrated in Chinese and German mining jurisdictions. Supply draws from China for composite substrate components, Germany for waveguide feed precision machining, and India for tower infrastructure integration. Raw material dependencies include aluminum feedstock, carbon-fiber composites, and gallium nitride semiconductors. Single-source vulnerability concentrates in E-band and V-band semiconductor foundry capacity. Distribution runs through state-owned carrier procurement panels in India and tower company aggregators in the United States.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward consolidated mobile network operators in India and the United States, fragmenting vendor negotiation leverage across framework agreements that prioritize availability targets over equipment specifications.
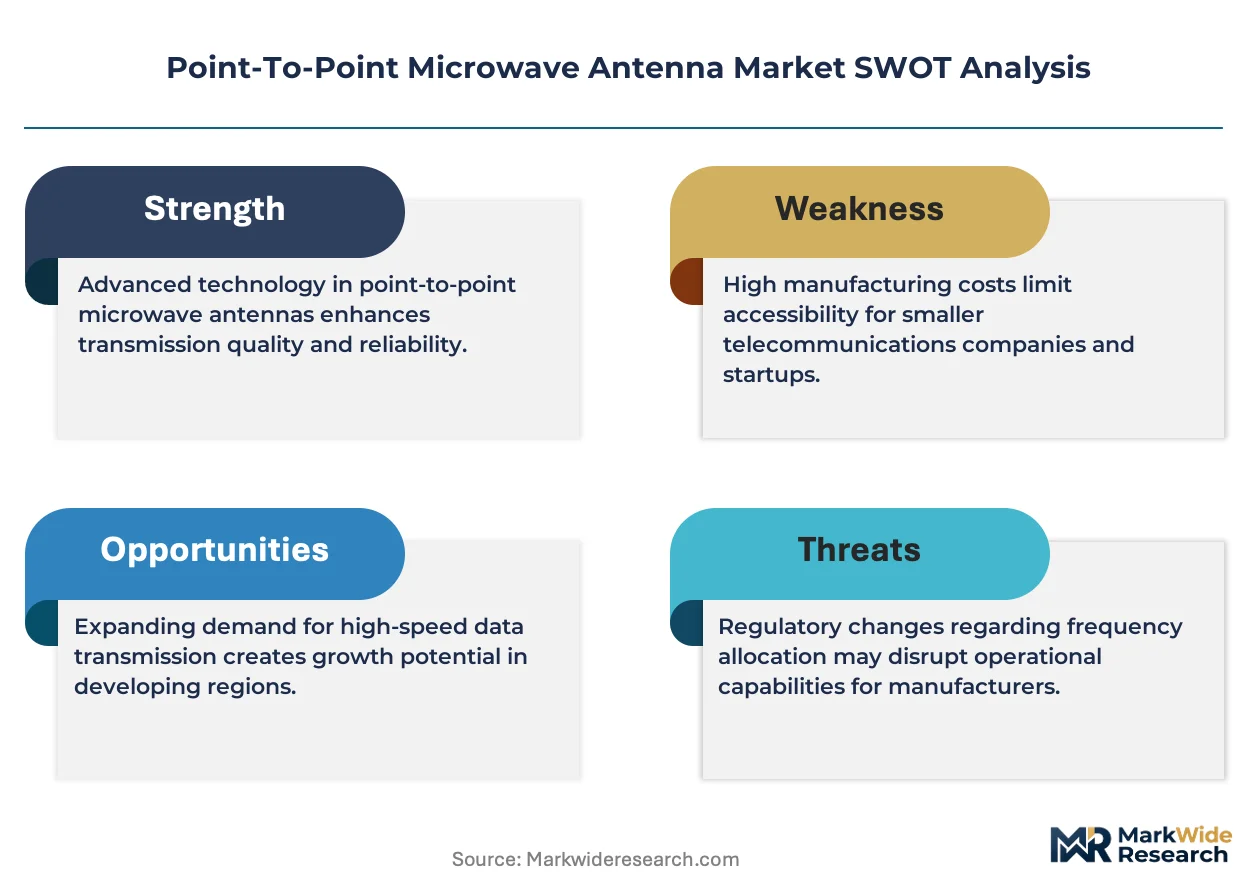
For Market Incumbents: Shield margin pools by deepening backward integration into composite substrate manufacturing and captive semiconductor design. The threat from pure-play antenna specialists demands certification investment for Open RAN interoperability across disaggregated radio platforms. Capacity addition in Gujarat and Maharashtra tower clusters secures geographic anchoring against regional fabrication competitors. For New Entrants and Emerging Players: Anchor in rural India connectivity gaps where Bharat Sanchar Nigam Limited programs sustain cost-optimized procurement for links exceeding 10 kilometers. Flat panel form factors for urban 5G small cell densification present the most penetrable segment, with aesthetic constraints accelerating permitting approvals. A go-to-market angle through tower infrastructure bundlers bypasses direct carrier procurement panel barriers. For Investors and Strategic Acquirers: Software-defined radio convergence specialists with antenna-integrated digital modulation platforms represent the priority acquisition archetype. Long-term viability across the next decade hinges on spectrum agility and dynamic capacity allocation capabilities. The signal to monitor is FCC and European Electronic Communications Code reframing timelines that accelerate migration from legacy frequency bands.| Strategic Initiative | Industry Significance |
|---|---|
| Composite Material Sourcing Partnership | Reduces antenna weight profiles for faster tower mounting in wind-sensitive urban corridors. |
| Open RAN Interoperability Certification | Validates performance across disaggregated radio platforms for Reliance Jio and Bharti Airtel procurement. |
| E-Band Spectrum Equipment Authorization | Unlocks 70/80 GHz deployment for Verizon and T-Mobile metro backhaul under FCC rulemakings. |
| Rural India Framework Agreement | Captures Bharat Sanchar Nigam Limited volume through performance-based availability targets. |
| Software-Defined Radio Integration | Enables dynamic capacity allocation for licensed band operators facing spectrum refarming deadlines. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through primary interviews with RF engineering directors at mobile network operators, procurement leads at tower infrastructure companies, antenna system product managers, and regulatory affairs specialists at equipment manufacturers. Secondary validation drew from FCC equipment authorization databases, TRAI connectivity directive filings, European Electronic Communications Code implementation timelines, and SEC disclosures from integrated radio-access-network vendors. Bottom-up antenna shipment estimates triangulated against top-down backhaul capital expenditure projections across telecommunications infrastructure.
Across the analysis window, the forecasting framework modeled volume and value outputs through segmentation across parabolic, flat panel, offset feed, and horn product types; analog, digital, unlicensed, and licensed technology tiers; telecommunications, broadcasting, military, and enterprise end users; and fixed, mobile, portable, and temporary installation modes. CAGRs were derived from link distance requirements, spectrum liberalization trajectories, and fiber substitution elasticity in coastal versus inland geographies. Industry-specific inputs included E-band and V-band regulatory adoption curves and composite substrate cost reduction trajectories.
Material uncertainties — spectrum reframing timeline delays, aluminum feedstock price volatility, and Open RAN interoperability certification bottlenecks — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding carrier backhaul deployment schedules and regulatory authorization pathways. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telecom Hardware
United States Set-Top Box Market
Telecom Hardware
Europe Zero-Touch Provisioning Market
Telecom Hardware
Base Station Antenna Market
Telecom Hardware
Land Mobile Radio System Market
Telecom Hardware
Satellite Communication Terminal Market
Telecom Hardware
4G Equipment Market
Telecom Hardware
Repeaters Market
Telecom Hardware
Digital Smart Set-Top Box (STB) Market
Telecom Hardware
Telecom Electronic Manufacturing Services (EMS) Market
Telecom Hardware
LPWAN Market
Telecom Hardware
Global Mobile Phone Loudspeaker Market
Telecom Hardware
SATCOM Transceivers Market
Telecom Hardware
Global Ultra Portable Internet Device Market
Telecom Hardware
5G BTS Antenna Market
Telecom Hardware
Room Cell Module Market
Telecom Hardware
Broadcast Antenna Market