
 3D Printing Materials and Services Market | 2026-2036
3D Printing Materials and Services Market Size, Share, and Industry Trends Forecast 2026-2036
3D Printing Materials and Services Market Outlook
Skilled additive manufacturing technicians is reorganizing how industrial service providers scale production capacity across North America and Europe. EOS GmbH leverages its laser sintering expertise to dominate high-performance metal powder segments for aerospace and medical implants. Materialise sustains a dense network of certified production facilities that anchors its position in patient-specific healthcare applications. BASF competes through backward integration into polymer chemistry, controlling proprietary filament formulations for automotive tooling.
3D printing materials and services encompass engineered feedstocks and production capabilities that transform digital designs into physical objects through layer-by-layer deposition, typically achieving tolerances of 50-200 microns depending on process modality. These systems serve industrial prototyping, direct manufacturing, and distributed supply chain replacement by reducing lead times from weeks to hours. Fused Deposition Modeling filaments occupy the highest volume tier due to low equipment cost and material accessibility, though Selective Laser Sintering powders capture disproportionate margin pools in aerospace and medical certification regimes. Stereolithography resins lead dental and jewelry applications where surface finish precision determines commercial viability, while Binder Jetting metal systems are scaling fastest in automotive tooling replacement cycles.
FDA device regulations and EU MDR certification requirements shape market access for healthcare-oriented service bureaus, forcing material traceability and process validation investments that smaller providers cannot absorb. EPA emissions standards and REACH chemical restrictions in Europe filter permissible resin chemistries, redirecting R&D toward bio-derivable photopolymers and recycled powder streams. ISO 9001 and AS9100 quality frameworks function as de facto gating mechanisms for aerospace and defense procurement channels. Stakeholders must monitor evolving certification timelines for flight-critical metal alloys and biocompatible implant polymers to calibrate capacity commitments against qualification bottlenecks.
Market Dynamics
Flight certification regimes for metal additive manufacturing are compressing qualification timelines while fragmenting supplier tiers between aerospace-qualified and general industrial service bureaus.
Growth Catalysts
- EU Green Deal bio-feedstock mandates:REACH chemical restrictions are redirecting R&D budgets toward bio-derivable photopolymers and recycled powder streams, opening new material categories for automotive and consumer goods tooling.
- Aerospace flight-critical part adoption:FAA and EASA certification pathways for laser-sintered titanium alloys are enabling direct manufacturing of bracketry and ducting previously machined from billet.
- Patient-specific healthcare workflows:EU MDR and FDA device regulations are mandating material traceability that only certified service bureaus can provide, concentrating surgical planning and implant production in qualified facilities.
Market Restraints
- Metal powder supply concentration:Spherical titanium and nickel superalloy feedstock production clusters in Germany and the United States, exposing buyers to single-source risk and volatile spot pricing.
- Post-processing labor intensity:Support removal, heat treatment, and surface finishing for metal parts adds 40-60% to total production cost, eroding the unit economics advantage over conventional machining at scale.
- Photopolymer resin toxicity constraints:EPA emissions standards and ECHA substance restrictions are delisting high-performance acrylate formulations, forcing reformulation cycles that delay product launches.
Strategic Opportunities
- Binder Jetting automotive tooling replacement:Sand and metal binder systems are penetrating foundry pattern and core production, displacing traditional tooling lead times from weeks to days for powertrain castings.
- India PLI scheme manufacturing localization:Production-linked incentives for medical devices and aerospace components are attracting service bureau investments to serve domestic OEMs with reduced import duty exposure.
- Continuous fiber composite printing:Automated fiber placement hybrid systems are opening structural applications in sporting goods and drones where isotropic metals previously dominated.
Industry Challenges
- AS9100 and ISO 13485 certification timelines:Aerospace and medical quality framework audits require 12-18 months of documented process control, freezing capacity expansion for mid-tier service providers.
- Multi-material workflow integration:Combining polymers, metals, and ceramics in single patient-specific implants demands software interoperability that current CAD-to-print pipelines fail to deliver.
- Post-build non-destructive testing bottlenecks:Computed tomography inspection capacity for internal defect detection lags print throughput, creating queue delays for flight-critical components.
Report Scope
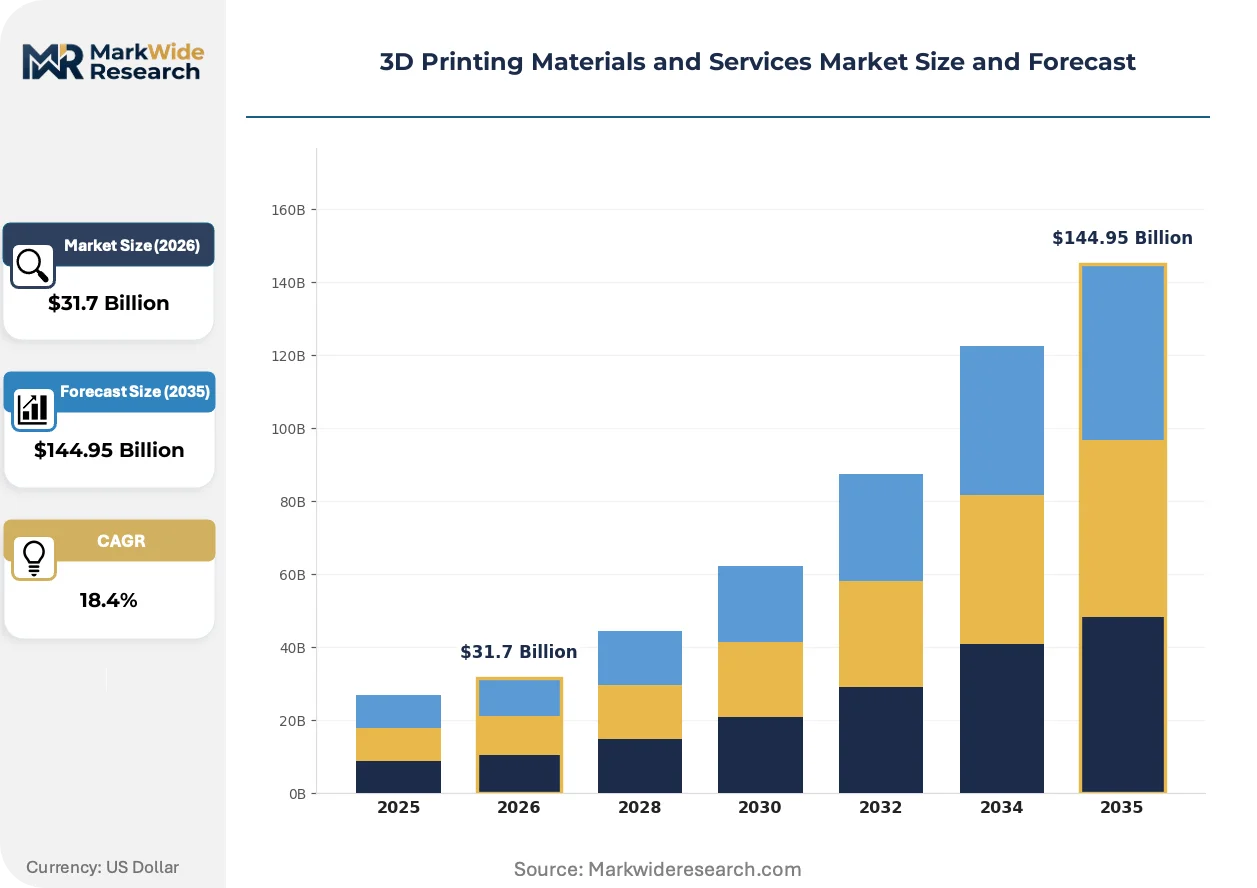
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | 3D Printing Materials and Services Market |
| Market Size in 2026 | $31.7 Billion |
| Market Size in 2035 | $144.95 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Filaments, Resins, Powders, Pastes Technology: Fused Deposition Modeling, Stereolithography, Selective Laser Sintering, Binder Jetting End User: Aerospace, Healthcare, Automotive, Consumer Goods Application: Prototyping, Tooling, Production Parts, Education |
| Companies Covered | Stratasys, 3D Systems, Inc., EOS GmbH, HP Development Company, Materialise, General Electric Company, Arkema, BASF, Evonik Industries AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
3D Printing Materials and Services Market Strategic Shifts
Process modality diversification is splitting the market between commodity filament systems and certified industrial platforms, with software-defined workflow orchestration emerging as the primary differentiation vector.
Multi-laser powder bed fusion is fragmenting throughput economics in aerospace and medical implant production. Tier-one suppliers are adopting 12-laser systems to amortize chamber costs across higher build volumes, while smaller bureaus retreat to single-laser configurations for prototyping. This divergence is compressing mid-scale equipment vendors into niche specialty alloys or exit.
EU MDR and FDA 21 CFR Part 820 harmonization efforts are tightening material traceability requirements for implantable devices. Manufacturers must now document powder lot genealogy through entire process chains, forcing IT system upgrades that disqualify paper-based quality systems. Dental and orthopedic segments are consolidating procurement around bureaus with validated digital thread capabilities.
Hospital-based point-of-care manufacturing is disrupting traditional central fabrication models for surgical guides and anatomical models. Academic medical centers in Germany and the United States are deploying in-house sterilizable photopolymer systems, bypassing external service contracts. This channel compression threatens volume-based pricing for regional production networks.
3D Printing Materials and Services Market Segmentation
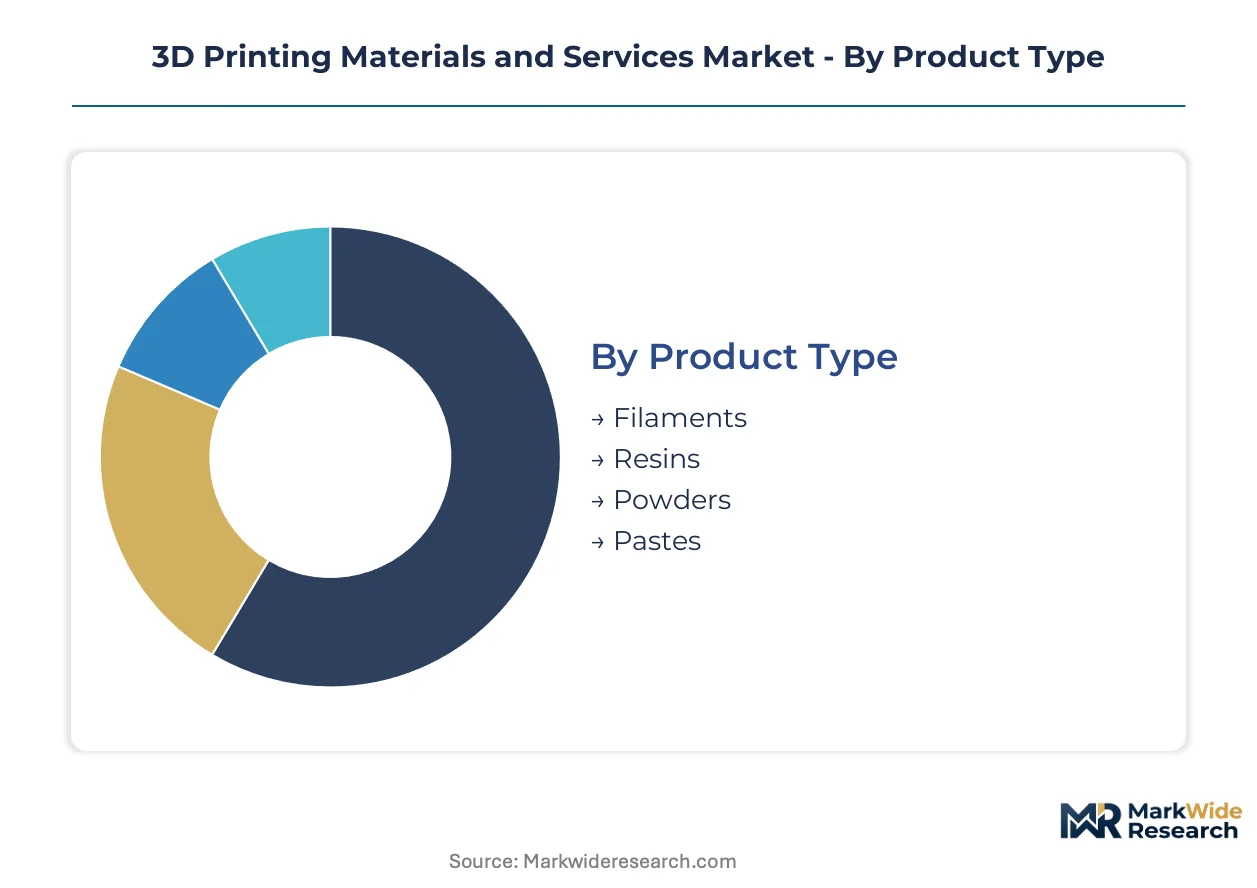
Segmentation in the 3D Printing Materials and Services Market reveals how certification requirements and supply chain geography fragment procurement patterns. Buyers source commodity filaments domestically while qualifying aerospace powders through concentrated German and American supply clusters.
Product Type:
Geographic concentration varies sharply across material categories, with polymer feedstocks produced locally and metal powders traded internationally.
- Filaments:Thermoplastic polymers including PLA, ABS, and PETG extruded into standardized diameters for fused deposition systems. Demand clusters in North American and European consumer goods prototyping, driven by low equipment barriers and distributed maker networks.
- Resins:Photocurable acrylate and epoxy formulations polymerized under UV light for stereolithography and digital light processing. Dental laboratories in Germany and jewelry manufacturers in Italy dominate procurement, constrained by ECHA substance restrictions on monomer toxicity.
- Powders:Spherical metal and polymer particles optimized for laser sintering and binder jetting.
- Pastes:Highly viscous ceramic and metal-loaded materials extruded through large-nozzle systems.
Filaments command the established base. The steepest expansion runs through aerospace-qualified powders.
Technology:
Cost stratification separates entry-level prototyping platforms from certified production systems requiring six-figure capital commitments.
- Fused Deposition Modeling:Thermoplastic extrusion through heated nozzles building parts layer-by-layer with 100-300 micron resolution. Desktop systems serve education and consumer prototyping, while industrial configurations produce tooling fixtures for automotive plants in Michigan and Bavaria.
- Selective Laser Sintering:CO2 or fiber lasers fusing polymer or metal powder beds without support structures. Medical implant manufacturers in Belgium and aerospace suppliers in Texas concentrate demand here, absorbing lengthy FDA and EASA qualification protocols.
- Stereolithography:UV laser or projector curing liquid resin vats for sub-50 micron surface finishes.
- Binder Jetting:Liquid binding agents deposited onto powder beds followed by sintering or infiltration.
Fused Deposition Modeling anchors volume throughput. Selective Laser Sintering captures the steepest margin expansion in qualified industrial channels.
End User:
Customer type determines whether procurement flows through centralized service bureaus or captive in-house production cells.
- Aerospace:Tier-one manufacturers and their supply chains producing flight-critical bracketry, ducting, and engine components. FAA certification for laser-sintered titanium in the United States and EASA parallel pathways in Europe concentrate spending at qualified bureaus in Germany and Texas.
- Healthcare:Hospitals, device manufacturers, and dental laboratories requiring biocompatible materials and sterilizable workflows. EU MDR traceability mandates and FDA 21 CFR Part 820 quality systems filter procurement toward certified providers with validated digital thread capabilities.
- Automotive:OEMs and tier suppliers producing tooling fixtures and limited production runs.
- Consumer Goods:Product designers and hobbyists accessing desktop systems and online fabrication services.
Aerospace commands the premium tier through certification barriers. Healthcare is expanding most quickly as point-of-care manufacturing penetrates hospital networks.
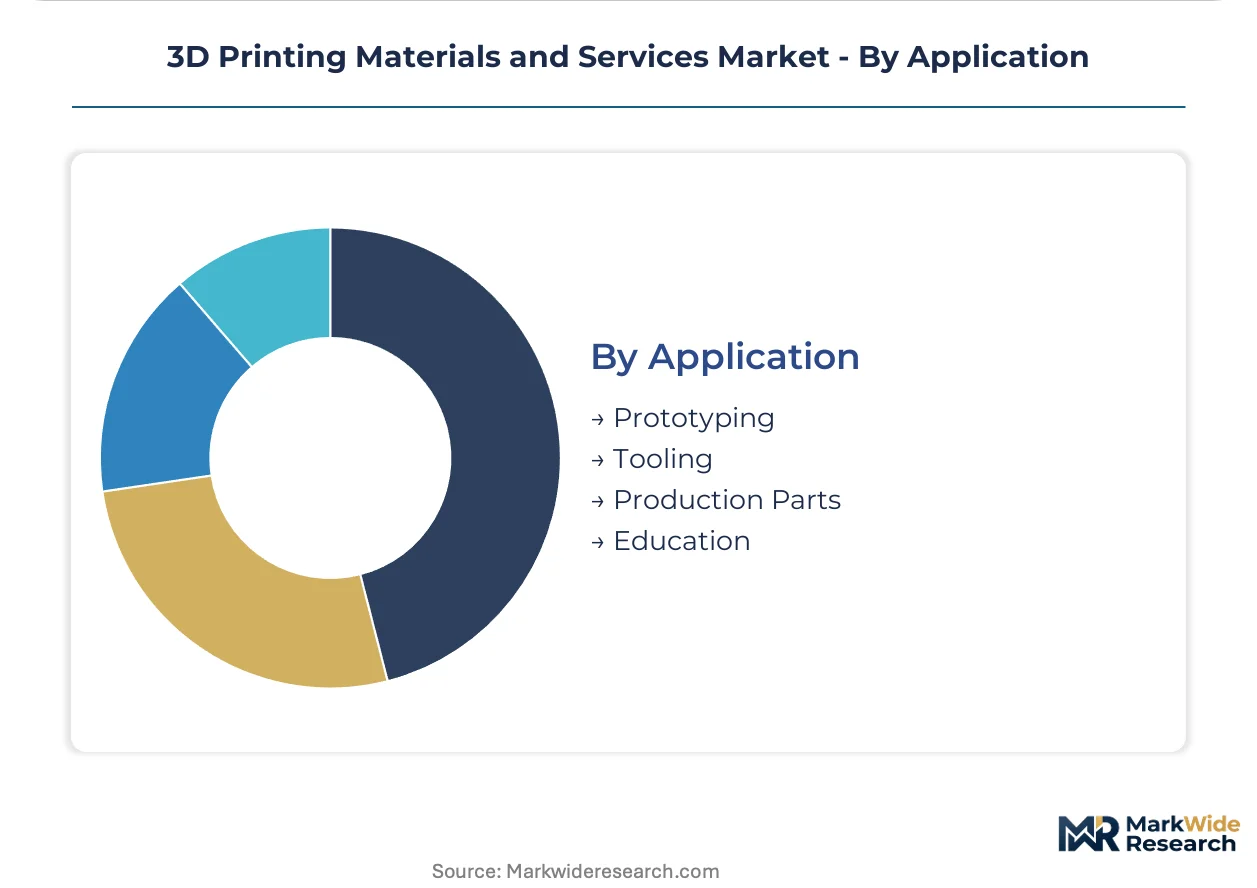
Application:
Maturity gradients separate established prototyping workflows from emerging production-scale deployments.
- Prototyping:Rapid iteration of design concepts before tooling commitment. Consumer electronics firms in California and design studios in Milan drive filament and resin consumption, with lead time compression from weeks to days displacing traditional machining for early-stage validation.
- Production Parts:Direct manufacturing of end-use components in qualified materials. Aerospace bracketry and patient-specific orthopedic implants in Germany and the United States define this segment, with material traceability and process validation gating market access.
- Tooling:Jigs, fixtures, and patterns for conventional manufacturing processes.
- Education:University and secondary school programs training additive manufacturing technicians.
Prototyping holds the installed base. Production Parts is gaining share fastest as certification timelines compress for metal additive systems.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany consumes aerospace-grade metal powders at a rate unmatched elsewhere, while the United States channels demand through hospital-based point-of-care installations and China scales binder jetting for automotive tooling replacement.
United States
FAA flight certification for laser-sintered titanium alloys drives aerospace procurement toward qualified service bureaus in Texas and California. EPA emissions standards filter permissible resin chemistries, redirecting formulation R&D toward bio-derivable photopolymers. Academic medical centers in Boston and Cleveland deploy sterilizable photopolymer systems for surgical guide production.
Germany
EOS GmbH and Materialise anchor industrial service clusters serving EU MDR-mandated medical implant traceability. REACH chemical restrictions accelerate bio-based feedstock development for automotive tooling applications. The Bavarian aerospace corridor concentrates laser sintering capacity for flight-critical bracketry and ducting components.
China
Domestic OEMs scale binder jetting systems for powertrain casting patterns, compressing foundry lead times from weeks to days. MIIT industrial additive manufacturing directives channel subsidy support toward metal powder production localization. Yangtze River Delta manufacturing hubs integrate continuous fiber composite printing for drone structural applications.
India
PLI scheme incentives for medical devices and aerospace components attract service bureau investments to reduce import duty exposure. CDSCO medical device regulations mandate material traceability systems that filter procurement toward certified providers. Karnataka and Maharashtra host emerging production networks serving domestic orthopedic implant demand.
Japan
METI advanced manufacturing initiatives support metal additive adoption for precision tooling in automotive supply chains. PMDA quality frameworks for patient-specific implants concentrate procurement around validated digital thread capabilities. Nagoya-area industrial clusters integrate hybrid automated fiber placement for sporting goods structural components.
3D Printing Materials and Services Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier, with chemical conglomerates controlling proprietary formulations and equipment pure-plays dominating certified production channels. The structure splits between backward-integrated material suppliers and forward-integrated service bureaus. Three archetypes define positioning: polymer chemistry specialists, laser sintering equipment manufacturers, and certified healthcare fabrication networks. Competitive moves center on AS9100 and ISO 13485 qualification investments and multi-laser system capacity expansion.
Among German-origin industrial specialists, EOS GmbH exemplifies the laser sintering equipment archetype, while Materialise occupies a position within certified healthcare service networks. BASF represents the backward-integrated chemical conglomerate tier, anchoring proprietary filament formulation control for automotive tooling applications.
| Leading Market Players |
|---|
| Stratasys |
| 3D Systems, Inc. |
| EOS GmbH |
| HP Development Company |
| Materialise |
| General Electric Company |
| Arkema |
| BASF |
| Evonik Industries AG |
| Others |
Value Chain & Pricing Dynamics
Long-term offtake contracts for aerospace-grade titanium and nickel superalloy powders lock in both supply access and price visibility for tier-one manufacturers, insulating qualified bureaus in Germany and Texas from spot market volatility while exposing smaller service providers to raw material cost spikes.
Pricing Analysis
Long-term offtake agreements dominate aerospace and medical implant procurement, with pricing stratifying across AS9100-certified premium tiers, ISO 13485-validated standard tiers, and uncertified economy tiers for prototyping filaments. Cost compression in metal powder segments is intensifying because post-processing labor adds forty to sixty percent to total production cost, eroding margin advantages over conventional machining. Automotive tooling buyers exhibit the highest price sensitivity due to volume scale requirements, while patient-specific healthcare procurement shows the lowest sensitivity given regulatory-mandated traceability premiums.
Supply Chain Analysis
Gas atomization capacity for spherical titanium and nickel superalloy powders concentrates in Germany, the United States, and China, creating single-source vulnerability for buyers dependent on flight-certified feedstock. Production draws from mineral concentrates processed through plasma rotating electrode and induction plasma atomization systems, with downstream distribution running through qualified service bureaus rather than commodity distributors. REACH chemical restrictions and EPA emissions standards filter permissible resin chemistries, forcing reformulation cycles that delay product launches and concentrate procurement around backward-integrated chemical suppliers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among tier-one aerospace OEMs and hospital purchasing committees, with procurement consolidation favoring qualified service bureaus that can absorb multi-year certification investments and material traceability mandates.
For Market Incumbents: Shield AS9100 and ISO 13485 certification moats through continuous audit documentation and multi-laser capacity expansion in Bavaria and Texas manufacturing corridors. Deepen backward integration into proprietary polymer formulations to defend margin position against commodity filament price erosion from Chinese equipment manufacturers. For New Entrants and Emerging Players: Differentiate on point-of-care sterilizable photopolymer workflows for academic medical centers in Germany and the United States, where hospital-based manufacturing bypasses external service contracts. Target India's PLI scheme incentives for medical device localization, leveraging CDSCO material traceability requirements to establish certified production networks in Karnataka and Maharashtra before import duty exposure hardens. For Investors and Strategic Acquirers: Capital is best deployed toward laser sintering equipment pure-plays with validated digital thread capabilities and dense networks of certified production facilities serving EU MDR-mandated healthcare applications. Watch FDA and EASA harmonization timelines for flight-critical metal alloys as the inflection signal for aerospace-qualified capacity scarcity premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Laser Capacity Expansion | Twelve-laser powder bed fusion systems amortize chamber costs across higher build volumes for aerospace bracketry in Texas. |
| Backward Integration into Polymer Chemistry | Proprietary filament formulation control defends margin position against commodity price erosion in automotive tooling. |
| EU MDR Digital Thread Validation | Material lot genealogy documentation through entire process chains qualifies bureaus for orthopedic implant procurement consolidation. |
| Point-of-Care Sterilizable System Deployment | Hospital-based photopolymer installations in Boston and Cleveland bypass external service contracts for surgical guide production. |
| Binder Jetting Foundry Pattern Production | Sand and metal binder systems displace traditional tooling lead times from weeks to days for powertrain castings in Yangtze River Delta hubs. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted across primary interviews with additive manufacturing technicians, aerospace procurement managers, biomedical engineers at academic medical centers, and regulatory affairs specialists at notified bodies. Secondary validation drew from FDA 510(k) filings, EASA certification documentation, EU MDR technical files, and SEC disclosures by listed equipment manufacturers. Bottom-up capacity estimates from individual service bureaus were triangulated against top-down spending patterns from hospital procurement databases and aerospace OEM supply chain disclosures.
Across the analysis window, the forecast framework models volume and value outputs through segmentation by material type, process modality, end-use industry, and certification tier. CAGRs were derived from installed base growth rates, equipment utilization assumptions, and material consumption intensity per qualified part category. Industry-specific inputs include flight certification timeline compression for laser-sintered titanium alloys and EU Green Deal bio-feedstock mandate penetration rates for automotive tooling applications.
The analysis sits within stated boundaries; outcomes outside sustained FAA and EASA qualification pathway acceleration or REACH chemical restriction enforcement would require recalibration. Practitioners should keep alternative scenarios live as hospital-based point-of-care manufacturing adoption and India PLI scheme localization incentives evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
3D Printing Materials
Industrial 3D Printing Plastic Market
3D Printing Materials
Polyamide 12 Powder for High-Performance 3D Printing Market
3D Printing Materials
3D Printing Plastics Market
3D Printing Materials
Vat Photopolymerization 3D Printing Technology Market
3D Printing Materials
3D Printing Coating Market
3D Printing Materials
Global Metal Additive Manufacturing Market
3D Printing Materials
Stainless Steel 3D Printing Market
3D Printing Materials
3D Printing Powder Market
3D Printing Materials
Global 3D Printing Ceramics Market
3D Printing Materials
LAMEA 3D Graphene Market
3D Printing Materials
Thermoformed Plastics for Printing Market
3D Printing Materials
Polypropylene in 3D Printing Market
3D Printing Materials
Low-Temperature Flow Improver Additives for 3D Printing Resins Market
3D Printing Materials
3D Printing Photopolymers Market
3D Printing Materials
3D Printing Polymers Market
3D Printing Materials
Medical 3D Printing Plastics Market