
 3D Printing Photopolymers Market | 2026-2036
3D Printing Photopolymers Market Size, Share, and Industry Trends Forecast 2026-2036
3D Printing Photopolymers Market Outlook
Photopolymer formulation chemist availability is bifurcating the competitive landscape between vertically integrated resin producers and hardware-dependent platforms. Stratasys anchors its position through captive supply of proprietary resins matched to its printer ecosystems. BASF SE competes by leveraging its polymer science heritage to develop high-temperature grades for automotive underhood applications. Carbon differentiates through its programmable liquid resin approach that merges hardware and chemistry control.
3D printing photopolymers are light-curable liquid compositions containing oligomers, monomers, photoinitiators, and functional additives that solidify upon exposure to specific UV or visible wavelengths, typically 385–405 nm, to produce dimensionally precise polymer parts. SLA resins occupy the established prototyping segment where layer resolution below 50 microns commands premium positioning among design firms. Biocompatible grades represent the fastest-expanding margin pool as dental and surgical guide applications expand beyond research institutions into production workflows. Medical devices applications concentrate demand for certified formulations that meet ISO 10993 biocompatibility standards.
FDA clearance pathways for 510(k) medical devices and EPA scrutiny of acrylate monomer emissions are shaping product development priorities and manufacturing site selection. The EU MDR and REACH chemical restrictions are forcing reformulation investments that favor larger resin producers with regulatory affairs capacity. Stakeholders must monitor how biocompatibility certification requirements evolve across jurisdictions to determine whether to build in-house formulation expertise or source through qualified suppliers.
Market Dynamics
Photopolymer supply chains are restructuring around captive resin production tied to printer hardware ecosystems, compressing margins for standalone formulation houses while rewarding integrated platforms with recurring revenue streams.
Growth Catalysts
- ISO 10993 biocompatibility certification:Dental laboratories in the United States and Germany are accelerating adoption of certified surgical guide resins, converting research workflows into production-scale deployments.
- China's dual carbon goals:Domestic contract manufacturers in Shenzhen and Dongguan are prioritizing low-VOC photopolymers to meet municipal emissions targets while serving consumer electronics prototyping demand.
- Same-day crown fabrication:Chairside CAD/CAM integration is driving resin consumption in North American dental practices, eliminating traditional lab turnaround delays.
Market Restraints
- Acrylate monomer price volatility:Petrochemical feedstock fluctuations are squeezing formulation margins, particularly for standard-grade prototyping resins.
- REACH Article 33 compliance costs:European manufacturers face reformulation expenses to reduce restricted monomer content below 0.1% weight thresholds.
- Thermoplastic substitution in automotive:Polyamide powder bed fusion is capturing underhood temperature applications above 150°C where photopolymers degrade.
Strategic Opportunities
- India's PLI scheme for medical devices:Domestic manufacturing incentives are attracting resin producers to establish formulation facilities near Ahmedabad and Hyderabad clusters.
- Multi-material jetting convergence:Hardware advances enabling simultaneous deposition of rigid and elastomeric photopolymers are opening soft robotics prototyping applications.
- Direct-to-lab distribution platforms:E-procurement channels are disintermediating traditional dental supply distributors in Brazil and Mexico.
Industry Challenges
- Photopolymer formulation chemist scarcity:Specialized expertise in free-radical kinetics and oligomer architecture commands premium compensation, constraining mid-tier producer expansion.
- 510(k) clearance timeline compression:FDA review periods for Class II surgical guides are extending to 180 days, delaying product launches and freezing R&D budgets.
- Legacy ERP integration:Resin batch tracking systems must interface with printer fleet management software, creating IT implementation bottlenecks for hybrid hardware-chemistry vendors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | 3D Printing Photopolymers Market |
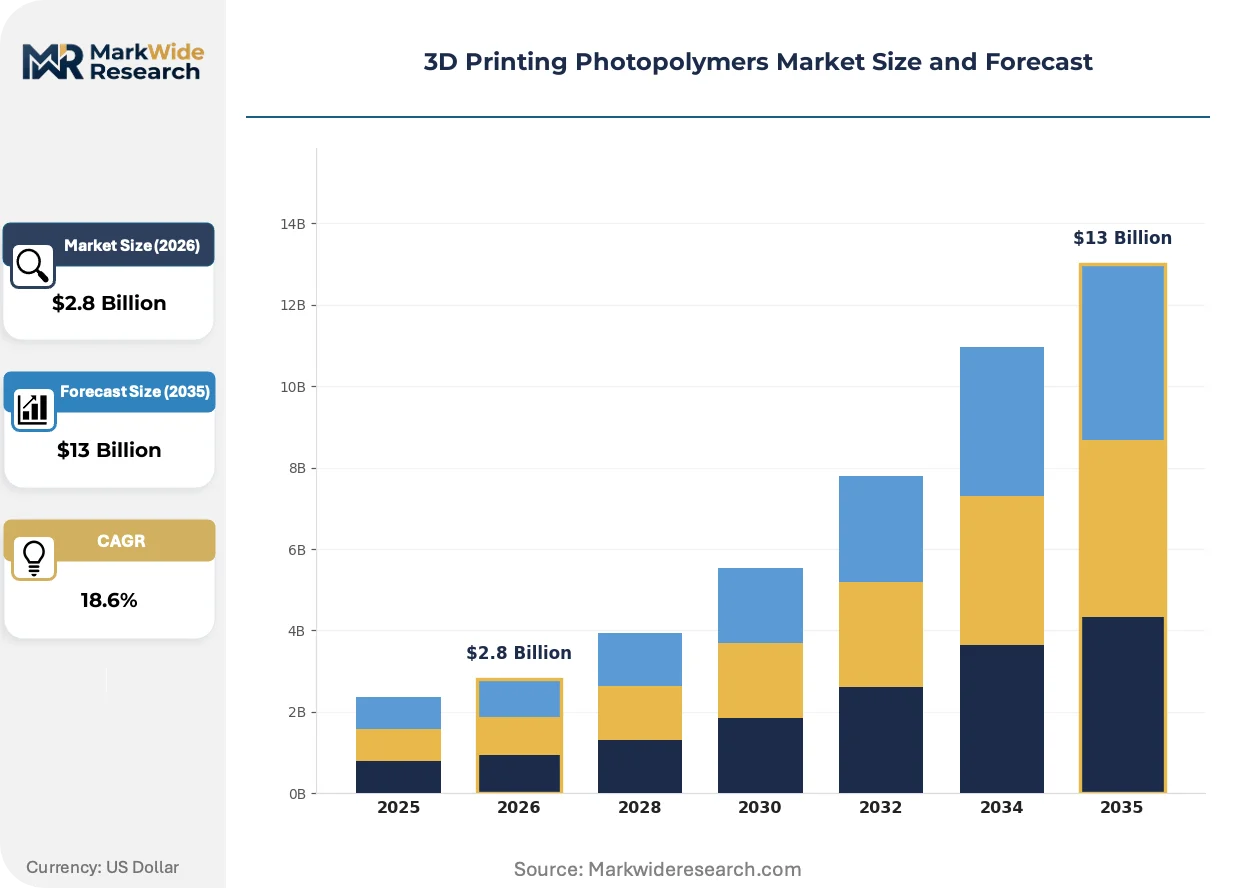
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $13 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: SLA Resins, DLP Resins, LCD Resins, Hybrid Resins Application: Aerospace, Automotive, Medical Devices, Prototyping Grade: Standard, High-Temperature, Biocompatible, Flexible End User: Manufacturers, Designers, Research Institutions, Educational Institutions |
| Companies Covered | Stratasys, 3D Systems, Formlabs, Henkel AG & Co. KGaA, Arkema, BASF SE, Carbon, Evonik Industries AG, Keystone Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
3D Printing Photopolymers Market Strategic Shifts
Programmable chemistry control is displacing static resin formulations, enabling real-time property modulation during the print process rather than post-cure modification.
Continuous liquid interface production is bifurcating the prototyping segment. Dental laboratories in Germany and Japan are adopting oxygen-permeable membrane systems to eliminate layer lines in aesthetic restorations. This technology is compressing demand for conventional vat polymerization hardware while expanding addressable applications into transparent orthodontic aligner molds.
REACH Annex XVII restrictions on acrylate esters are forcing reformulation investments across European supply chains. Manufacturers are substituting bio-based methacrylate alternatives derived from lignin feedstocks to maintain market access. Medical device resin producers with existing ECHA registration dossiers are capturing displaced volume from smaller competitors lacking regulatory affairs capacity.
Buying patterns are consolidating around certified supplier programs. Large dental service organizations in the United States are mandating single-source resin agreements to simplify compliance documentation and reduce lot-to-lot variability audits. This preference shift is marginalizing regional formulation houses and concentrating procurement leverage with vertically integrated platform vendors.
3D Printing Photopolymers Market Segmentation
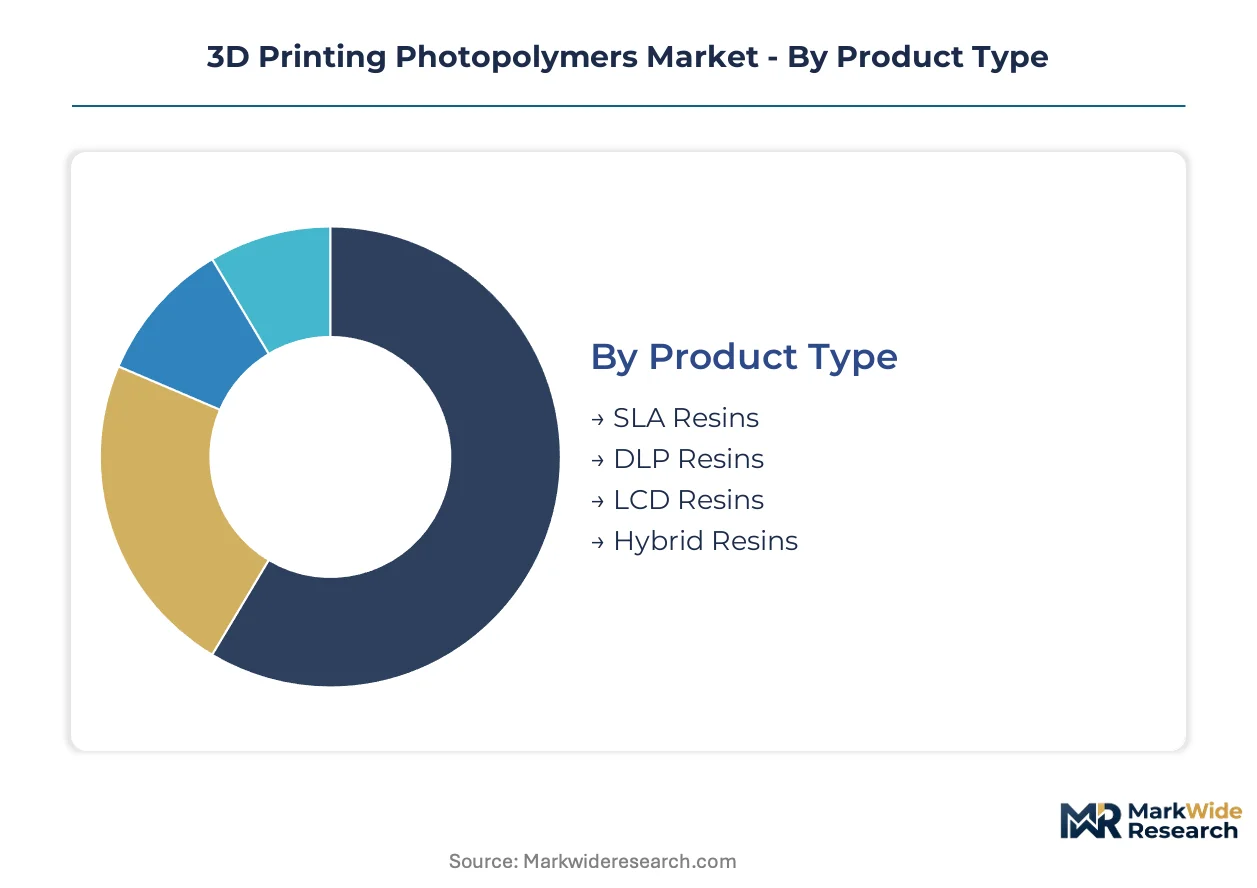
Photopolymer segmentation separates hardware-matched formulations from application-specific grades, with regulatory certification acting as the primary commercial gatekeeper. Buyers select across product type, application, grade, and end user based on ISO 10993 compliance status, thermal performance thresholds, and printer ecosystem compatibility.
Product Type:
FDA 510(k) clearance pathways and REACH Article 33 monomer restrictions differentiate resin categories by regulatory burden and reformulation flexibility.
- SLA Resins:Laser-cured formulations with sub-50-micron layer resolution dominate dental laboratory workflows in Germany and the United States. Demand concentrates among chairside CAD/CAM operators seeking same-day crown production, constrained by acrylate monomer price volatility from petrochemical feedstock fluctuations.
- DLP Resins:Digital light projection systems cure entire layers simultaneously, enabling faster throughput for orthodontic aligner mold production. Adoption is accelerating in Japan's dental service organizations where oxygen-permeable membrane systems eliminate visible layer lines in aesthetic restorations.
- LCD Resins:Masked stereolithography leverages LCD panels for cost-efficient vat polymerization in Shenzhen contract manufacturing clusters serving consumer electronics prototyping.
- Hybrid Resins:Dual-cure formulations combining photoinitiation with thermal post-processing address applications requiring elevated glass transition temperatures.
Established volume favors SLA Resins; emerging adoption favors DLP Resins.
Application:
End-use thermal requirements and biocompatibility certification needs stratify pricing and supplier qualification barriers.
- Aerospace:Lightweight lattice structures for cabin interior components utilize flame-retardant photopolymers meeting FAA smoke and toxicity standards. Demand clusters in Toulouse and Seattle manufacturing corridors where airframers qualify resin suppliers through multi-year certification programs.
- Automotive:Underhood temperature environments above 150°C are ceding ground to polyamide powder bed fusion, compressing photopolymer addressable market to interior trim and lighting housings.
- Medical Devices:ISO 10993 certified surgical guide resins command premium positioning as dental laboratories convert research workflows into production-scale deployments.
- Prototyping:Design validation applications prioritize speed and cost over mechanical performance, concentrating procurement with standalone resin houses lacking regulatory affairs capacity.
Medical Devices commands margin expansion; Prototyping absorbs volume compression from continuous liquid interface production displacement.
Grade:
Performance tier and certification status determine supplier switching costs and customer lock-in duration.
- Standard:General-purpose prototyping formulations face commoditization pressure from Chinese manufacturers in the Pearl River Delta, squeezing margins for Western producers lacking captive printer ecosystems.
- High-Temperature:Automotive underhood specifications above 120°C service temperature require specialized oligomer architectures, with BASF SE leveraging polymer science heritage to defend positioning against thermoplastic substitution.
- Biocompatible:ECHA-registered formulations meeting EU MDR requirements are capturing displaced volume from smaller competitors lacking REACH Annex XVII compliance dossiers.
- Flexible:Elastomeric grades enabling soft robotics prototyping are gaining share fastest through multi-material jetting hardware advances permitting simultaneous rigid and elastic deposition.
Biocompatible grades steepen margin trajectories; Standard grades confront pricing pressure from low-VOC alternatives.
End User:
Procurement scale and technical sophistication determine distribution channel selection and support service intensity.
- Manufacturers:Contract electronics producers in Dongguan and Shenzhen prioritize low-VOC photopolymers to meet municipal emissions targets under China's dual carbon goals.
- Designers:Industrial design studios in Milan and Copenhagen select resins based on aesthetic surface finish and color stability rather than mechanical certification.
- Research Institutions:University laboratories in Boston and Cambridge drive experimental formulation demand for programmable liquid resin approaches merging hardware and chemistry control.
- Educational Institutions:Technical training centers in India source through direct-to-lab distribution platforms disintermediating traditional supply chains.
Manufacturers consolidate procurement leverage; Research Institutions seed next-generation technology adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany consumes photopolymers primarily for certified dental and medical applications, while China deploys them for high-volume consumer electronics prototyping, creating divergent specification demands across supplier portfolios.
United States
Dental laboratories in California and Texas are accelerating same-day crown production using chairside CAD/CAM systems. FDA 510(k) clearance pathways for Class II surgical guides are extending review timelines, compressing product launch schedules. Boston-area research institutions are driving experimental demand for programmable liquid resin approaches that merge hardware control with real-time chemistry modulation.
Germany
Dental service organizations in Bavaria and North Rhine-Westphalia are mandating single-source resin agreements to simplify ISO 10993 compliance documentation. REACH Annex XVII restrictions on acrylate esters are forcing reformulation investments toward bio-based methacrylate alternatives. Stuttgart manufacturing corridors host airframers qualifying flame-retardant photopolymers for cabin interior lattice structures through multi-year certification programs.
China
Contract manufacturers in Shenzhen and Dongguan are prioritizing low-VOC photopolymers to meet municipal emissions targets under dual carbon goals. NMPA regulatory harmonization with international standards is streamlining medical device resin approvals. Pearl River Delta clusters serve consumer electronics brands with rapid prototyping services, concentrating demand for cost-efficient LCD-based vat polymerization systems.
Japan
Dental laboratories in Tokyo and Osaka are adopting oxygen-permeable membrane systems to eliminate visible layer lines in aesthetic restorations. METI industrial policy is supporting domestic resin formulation capabilities for high-value medical applications. Nagoya manufacturing belts are integrating continuous liquid interface production for transparent orthodontic aligner mold fabrication.
India
Domestic medical device manufacturers near Ahmedabad and Hyderabad are expanding photopolymer adoption under PLI scheme incentives. CDSCO regulatory alignment with ISO 10993 standards is accelerating biocompatible grade approvals. Technical training centers in Karnataka are sourcing resins through direct-to-lab distribution platforms that disintermediate traditional supply chains.
3D Printing Photopolymers Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier, with captive resin production tied to printer hardware ecosystems compressing margins for standalone formulation houses. The market structure rewards platforms with recurring revenue streams from proprietary material lock-in. Three archetypes dominate: vertically integrated printer-resin platforms, polymer science heritage suppliers leveraging oligomer architecture expertise, and programmable chemistry specialists merging hardware control with formulation. Competitive moves center on regulatory affairs capacity investments for REACH and FDA compliance, plus strategic partnerships to secure bio-based feedstock supply chains.
Among integrated hardware-chemistry platforms, Stratasys and Carbon exemplify the captive supply model, while BASF SE represents polymer science heritage suppliers defending positioning through specialized oligomer architectures for elevated temperature applications. These three anchors illustrate how competitive advantage increasingly depends on regulatory dossier depth and printer ecosystem integration rather than formulation chemistry alone.
| Leading Market Players |
|---|
| Stratasys |
| 3D Systems |
| Formlabs |
| Henkel AG & Co. KGaA |
| Arkema |
| BASF SE |
| Carbon |
| Evonik Industries AG |
| Keystone Industries |
| Others |
Value Chain & Pricing Dynamics
Bio-based methacrylate alternatives derived from lignin feedstocks are displacing conventional acrylate esters across European supply chains, simultaneously shifting procurement geography toward Nordic biorefinery clusters and compressing formulation margins for petrochemical-dependent producers. This substitution dynamic rewards resin houses with captive biopolymer supply agreements while penalizing standalone formulators exposed to volatile petrochemical monomer costs.
Pricing Analysis
Contract structures favor long-term offtake agreements between dental service organizations and vertically integrated platform vendors, locking in volume commitments that insulate premium-tier biocompatible grades from spot-market volatility. Price differentiation separates ISO 10993-certified formulations from uncertified prototyping resins, with FDA 510(k) clearance status commanding substantial premiums. Cost compression in standard-grade prototyping tiers is intensifying because Chinese manufacturers in the Pearl River Delta are flooding export markets with low-VOC alternatives. Small dental laboratories exhibit highest price sensitivity, while large hospital systems prioritize certification compliance over unit economics.
Supply Chain Analysis
Inventory strategies favor just-in-time delivery for high-turnover prototyping resins, whereas biocompatible grades require strategic stockpiling to manage ECHA registration dossier complexity and lot-to-lot variability audits. Manufacturing concentrates in Germany, China, and the United States, with formulation expertise clustering around Stuttgart, Shenzhen, and Boston metropolitan areas. Feedstock supply draws from petrochemical complexes in the US Gulf Coast and emerging lignin biorefineries in Scandinavia. Single-source vulnerability persists for specialized photoinitiators produced by limited European chemical houses. Distribution runs through direct-to-lab platforms disintermediating traditional dental supply distributors in emerging markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized expertise in free-radical kinetics and oligomer architecture commands premium compensation that constrains mid-tier expansion, creating persistent capability scarcity that shapes competitive returns. Formulation chemist availability gaps determine which players can execute REACH-compliant reformulations versus surrendering market share.
For Market Incumbents: Compound regulatory affairs capacity investments to capture displaced volume from smaller competitors lacking ECHA registration dossiers for bio-based methacrylate alternatives. Deepen captive resin production tied to printer hardware ecosystems to compress margins for standalone formulation houses. Defend positioning against thermoplastic substitution in automotive underhood applications by accelerating high-temperature oligomer architecture R&D in partnership with Stuttgart-area airframers. For New Entrants and Emerging Players: Anchor in India's PLI scheme medical device clusters near Ahmedabad and Hyderabad, where domestic manufacturing incentives attract formulation facilities lacking established incumbents. Target direct-to-lab distribution platforms in Brazil and Mexico that disintermediate traditional dental supply chains. Pursue soft robotics prototyping applications enabled by multi-material jetting hardware advances permitting simultaneous rigid and elastic photopolymer deposition. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors vertically integrated platforms with recurring revenue streams from proprietary material lock-in. Long-term viability over the next decade hinges on regulatory dossier depth rather than formulation chemistry alone. Acquisition candidates should demonstrate existing ISO 10993 certification infrastructure and printer ecosystem integration. Watch for FDA 510(k) review timeline compression beyond current administrative thresholds as the signal indicating regulatory capacity scarcity has reached critical inflection.| Strategic Initiative | Industry Significance |
|---|---|
| REACH Annex XVII Compliance Investment | ECHA-registered producers capture displaced volume from smaller competitors lacking reformulation capacity. |
| Backward Integration into Bio-Based Feedstocks | Lignin-derived methacrylate supply agreements insulate margins from petrochemical price volatility. |
| Printer Ecosystem Captive Supply | Proprietary resin lock-in generates recurring revenue streams that standalone formulators cannot replicate. |
| ISO 10993 Certification Infrastructure | Biocompatible grade positioning commands premium pricing in dental and surgical guide applications. |
| Direct-to-Lab Distribution Platform | E-procurement channels disintermediate traditional supply chains in Brazil, Mexico, and Indian technical training centers. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with dental laboratory technicians, resin formulation chemists, biomedical engineers at hospital purchasing committees, and procurement leads at contract electronics manufacturers in Shenzhen and Dongguan. Secondary validation drew from FDA 510(k) clearance databases, ECHA registration dossiers, NMPA medical device approvals, customs trade data for photopolymer resin imports, and SEC filings of publicly traded 3D printing platform vendors. Bottom-up volume estimates triangulated against top-down market sizing across hardware installation bases and resin consumption rates.
Across the analysis window, the forecasting framework modeled demand trajectories by product type, application grade, certification status, and regional regulatory cluster. Segmentation dimensions included SLA versus DLP versus LCD resin chemistries, biocompatible versus standard versus high-temperature performance tiers, and captive printer-matched versus standalone formulation supply models. CAGRs were derived from regression analysis of historical adoption curves in dental CAD/CAM integration, adjusted for regulatory timeline risks and feedstock substitution dynamics. Industry-specific inputs incorporated oxygen-permeable membrane technology penetration rates and municipal emissions enforcement intensity under China's dual carbon goals.
Decision-makers should treat outputs as directional under base assumptions of sustained FDA 510(k) review timelines and stable petrochemical feedstock pricing; material deviation would warrant model refresh. Forecasts reflect assumptions regarding REACH Annex XVII enforcement consistency and NMPA regulatory harmonization progress. Revision becomes warranted when biocompatible grade certification backlogs cross administrative capacity thresholds or when lignin-derived methacrylate cost parity disrupts established supply economics.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
3D Printing Materials
3D Printing Iron Powder Market
3D Printing Materials
Vat Photopolymerization 3D Printing Technology Market
3D Printing Materials
3D Printed Nanocellulose Market
3D Printing Materials
Metal Jet 3D Printing Technology Market
3D Printing Materials
Additive Manufacturing and Materials Market
3D Printing Materials
Polyamide 12 Powder for High-Performance 3D Printing Market
3D Printing Materials
Polypropylene in 3D Printing Market
3D Printing Materials
Advanced Materials for 3D Printing Market
3D Printing Materials
Global Metal Additive Manufacturing Market
3D Printing Materials
Global Arf Dry and Immersion Resist Materials Market
3D Printing Materials
Rapid Prototyping Materials Market
3D Printing Materials
3D Printing Materials and Services Market
3D Printing Materials
Non-Metal 3D Printing Market
3D Printing Materials
Global Biocompatible 3D Printing Materials Market
3D Printing Materials
LAMEA 3D Graphene Market
3D Printing Materials
Global 3D Printing Filament Market