
 Vat Photopolymerization 3D Printing Technology Market | 2026-2036
Vat Photopolymerization 3D Printing Technology Market Size, Share, and Industry Trends Forecast 2026-2036
Vat Photopolymerization 3D Printing Technology Market Insights
Prototyping departments at consumer electronics firms is collapsing as a share of total vat photopolymerization equipment purchases, while dental service organizations and hearing aid manufacturers capture a rising proportion of new installations. 3D Systems leverages its decades of SLA patent depth to anchor high-margin medical workflows in North America. Formlabs competes through desktop-format accessibility that sustains adoption among independent dental labs with limited capital budgets. Carbon Inc. differentiates via its proprietary CLIP architecture that dominates continuous liquid interface production for end-use elastomeric components.
Vat photopolymerization encompasses additive manufacturing processes where a photosensitive liquid resin cures selectively under patterned ultraviolet or visible light exposure, achieving layer resolutions between 25 and 100 micrometers depending on projection engine pixel density and optical configuration. The technology serves precision applications requiring smooth surface finishes, intricate internal geometries, or biocompatible material properties that exceed fused deposition modeling capabilities. SLA systems occupy the mature premium tier where margin pools concentrate in service contracts and proprietary resin formulations, while LCD-based platforms represent the fastest-expanding hardware category as Chinese manufacturers drive unit economics toward sub-thousand-dollar price points. Dental applications lead end-use revenue generation due to regulatory-validated workflows for surgical guides and clear aligner models, whereas jewelry prototyping remains structurally constrained by post-processing labor intensity.
FDA 510(k) clearance requirements for biocompatible resins shape product development timelines and limit market access for uncertified material suppliers, while EU MDR compliance obligations force European dental device manufacturers toward validated production equipment with full traceability documentation. ISO 10993 biocompatibility testing standards create additional certification barriers that favor established resin formulators with dedicated regulatory affairs capacity. Stakeholders must monitor evolving EPA and REACH restrictions on acrylate monomer chemistries, as substitution mandates could disrupt existing supply chains and reshape competitive advantage toward bio-based resin innovators.
Market Dynamics
FDA 510(k) clearance requirements for biocompatible resins are compressing product development timelines and forcing dental device manufacturers toward validated production equipment with full traceability documentation, reshaping competitive advantage toward established resin formulators with dedicated regulatory affairs capacity.
Growth Catalysts
- ISO 10993 biocompatibility testing standards:These certification pathways create defensible moats for resin suppliers serving surgical guide and dental aligner workflows in regulated cleanroom environments.
- LCD-based hardware platforms:Chinese manufacturers are driving unit economics toward sub-thousand-dollar price points, expanding accessibility among independent dental laboratories with limited capital budgets.
- Germany's precision manufacturing corridor:Medical device clusters in this geography integrate vat photopolymerization into regulated workflows, concentrating demand for high-resolution optical configurations.
Market Restraints
- Acrylate monomer supply volatility:EPA and REACH restrictions on specific chemistries create substitution mandates that disrupt existing supply chains and force reformulation investments.
- Post-processing labor intensity:Jewelry prototyping applications remain structurally constrained by manual support removal and surface finishing requirements that resist automation.
- Projection engine pixel density limitations:Optical hardware constraints cap achievable layer resolutions between 25 and 100 micrometers, blocking entry into sub-micron precision markets.
Strategic Opportunities
- Hearing aid manufacturing:This emerging application segment captures a rising proportion of new installations as elastomeric component demand accelerates for custom-fit earpieces.
- EU MDR compliance obligations:These regulatory tailwinds force European dental device manufacturers toward validated production equipment, expanding addressable market for traceability-integrated systems.
- Continuous liquid interface production:Convergence of photochemistry and programmable resin chemistry enables end-use elastomeric components that exceed traditional prototyping boundaries.
Industry Challenges
- Biocompatible resin certification timelines:FDA 510(k) pathways extend development cycles by 18-24 months, straining working capital for material innovators without diversified revenue streams.
- Cleanroom workflow integration complexity:Dental laboratories face operational friction when embedding vat photopolymerization into existing ISO 13485 quality management systems.
- Photosensitive resin handling expertise:Talent scarcity in photochemistry formulation and optical system calibration limits scaling capacity for contract manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vat Photopolymerization 3D Printing Technology Market |
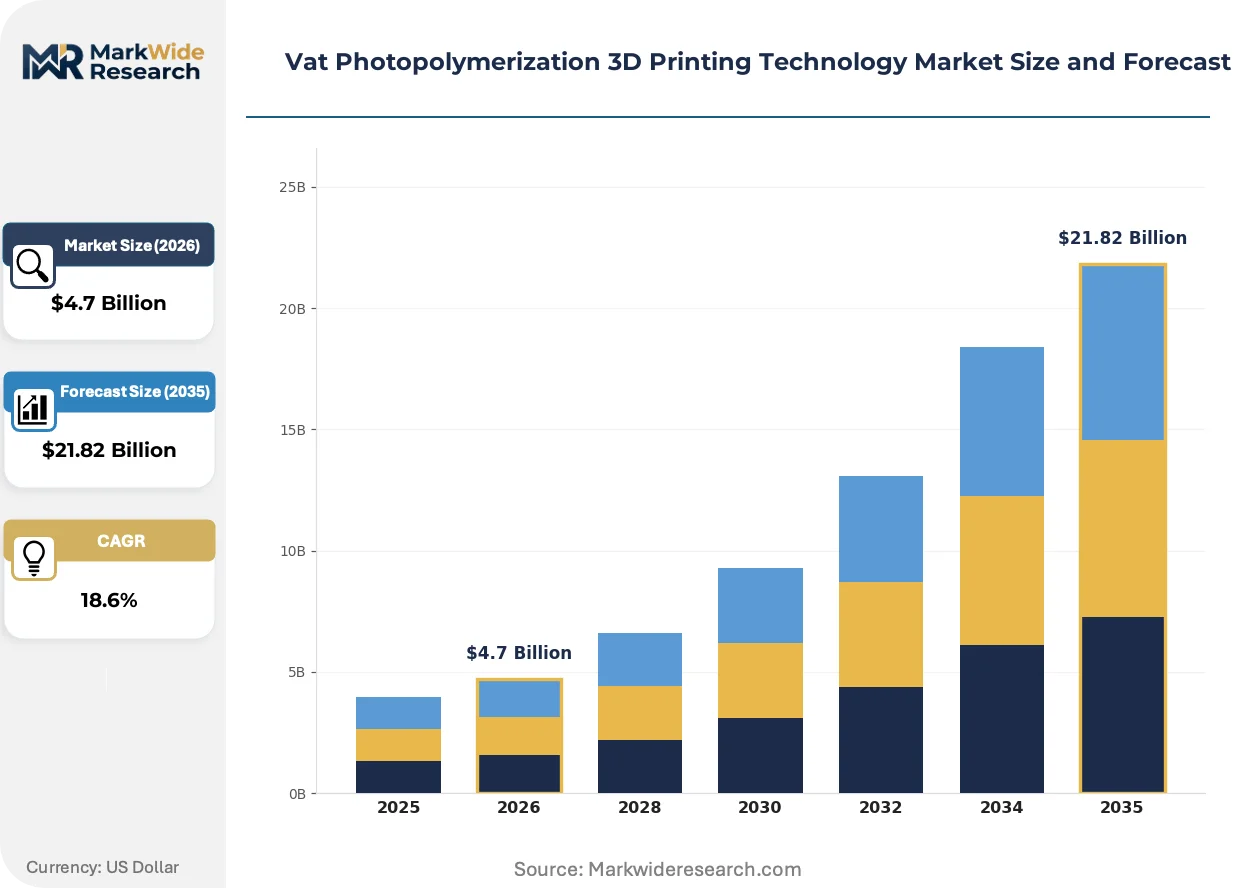
| Market Size in 2026 | $4.7 Billion |
| Market Size in 2035 | $21.82 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: SLA, DLP, LCD, CLIP End User: Aerospace, Automotive, Healthcare, Consumer Goods Material Type: Resin, Thermoplastic, Elastomer, Composite Application: Prototyping, Manufacturing, Dental, Jewelry |
| Companies Covered | 3D Systems, Formlabs, Stratasys, Carbon Inc., Nexa3D, Asiga, Peopoly, Anycubic, Phrozen, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vat Photopolymerization 3D Printing Technology Market Trends and Innovations
Photopolymer resin chemistry is actively fragmenting across application-specific formulations, while regulatory pressure on monomer safety and hardware miniaturization reshape competitive positioning in dental and medical workflows.
LCD-based vat photopolymerization is fragmenting the hardware market into distinct performance tiers. Chinese optical engine suppliers now dominate sub-thousand-dollar system categories, compressing margins for legacy SLA architecture providers while expanding installed base among price-sensitive independent dental laboratories. This fragmentation is enabling new service bureau entrants to compete on speed rather than capital intensity.
EU MDR traceability documentation requirements are forcing resin suppliers toward validated manufacturing records. The regulation mandates full batch history for biocompatible materials used in permanent patient contact devices, accelerating consolidation toward formulators with dedicated quality systems. German dental device clusters are responding by integrating production equipment with automated data logging capabilities.
Device manufacturers now specify certified resin workflows rather than sourcing hardware and materials separately. This bundled procurement pattern displaces independent material sourcing among orthodontic service organizations, concentrating purchasing authority with integrated solution providers. The shift is most visible in North American clear aligner production networks where FDA-validated workflows reduce regulatory risk exposure.
Vat Photopolymerization 3D Printing Technology Market Segmentation
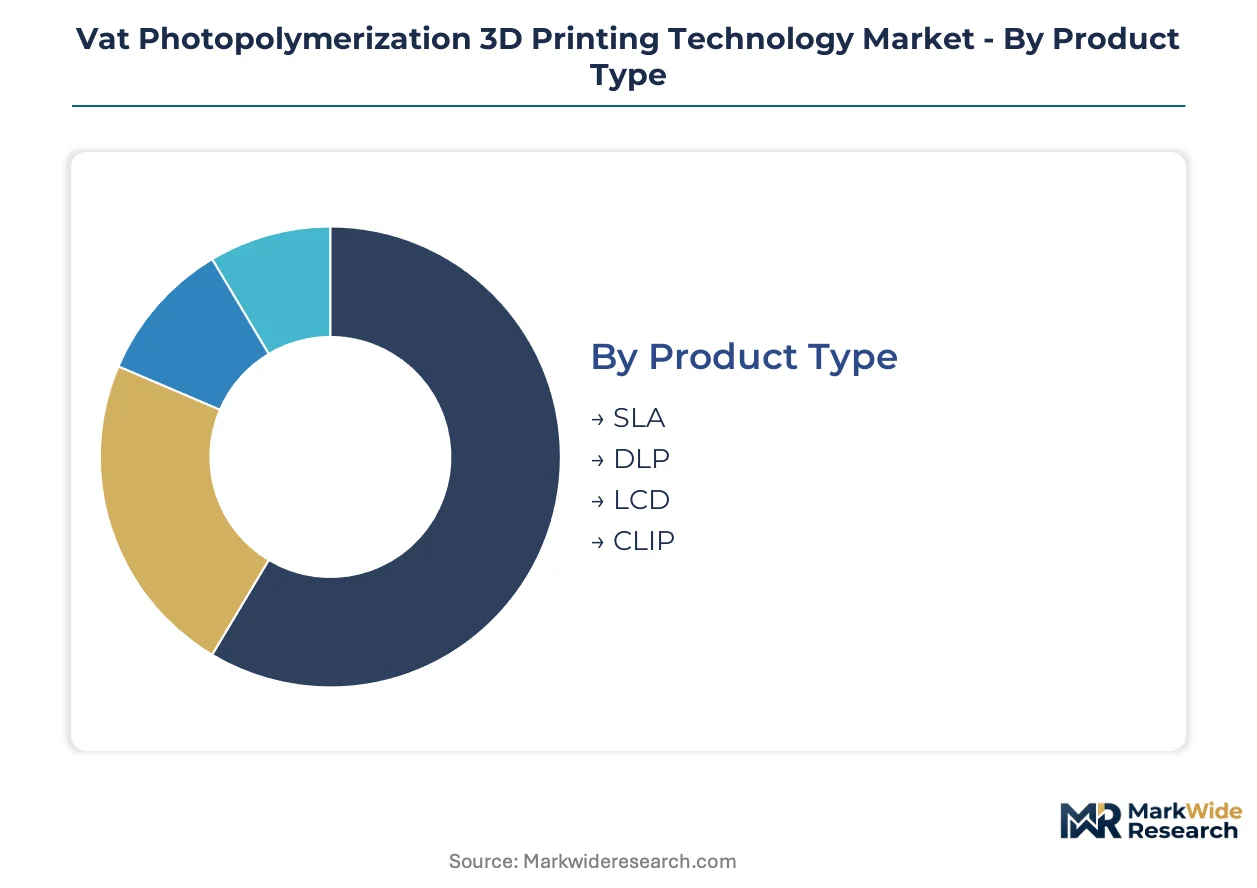
Segmentation in vat photopolymerization reveals how hardware architecture, material chemistry, and end-use requirements fragment purchasing authority across distinct channel configurations. Each dimension shapes margin pools differently—product type determines service contract value, while application focus dictates regulatory compliance burdens.
Product Type:
Channel mix varies sharply by hardware architecture, with premium SLA systems flowing through direct sales and service-integrated channels while LCD platforms penetrate via e-commerce and distributor networks.
- SLA:Laser-based stereolithography systems achieve sub-50-micron resolution through galvanometer-directed UV sources. Dental laboratories in Germany's precision manufacturing corridor anchor demand for these premium configurations where FDA-validated workflows command service-intensive procurement relationships.
- LCD:Masked stereolithography leverages commodity LCD panels as photomasks, compressing hardware costs toward accessible price points. Chinese manufacturers dominate this expanding category, penetrating independent dental laboratories with limited capital budgets through online direct-to-lab distribution.
- DLP:Digital light processing systems deploy micromirror array projection engines for rapid layer exposure. These occupy a mid-tier channel position balancing resolution and throughput for jewelry prototyping service bureaus.
- CLIP:Continuous liquid interface production eliminates layer boundaries through oxygen-permeable membranes. Carbon Inc.'s proprietary architecture dominates elastomeric end-use applications via subscription-based resin supply agreements rather than equipment sales.
SLA dominates installed base through decades of regulatory validation. LCD is where expansion concentrates as unit economics democratize access.
End User:
Customer type segmentation aligns procurement sophistication with application criticality, from regulated medical device manufacturing to iterative consumer product development.
- Healthcare:Dental laboratories and hearing aid manufacturers drive biocompatible resin demand through FDA 510(k) and EU MDR compliance pathways. These end users prioritize validated workflows with full traceability documentation over hardware acquisition cost.
- Consumer Goods:Electronics prototyping departments historically anchored equipment purchases but now capture shrinking share as medical applications expand. Budget constraints here favor desktop-format accessibility and limited post-processing infrastructure.
- Aerospace:Precision component validation for non-structural applications requires optical configurations achieving 25-micron layer resolution. Procurement flows through specialized additive manufacturing service providers with AS9100 quality certifications.
- Automotive:Elastomeric seal and grommet prototyping leverages CLIP architecture for end-use mechanical properties. Tier suppliers integrate these systems into advanced product development centers rather than production environments.
Healthcare commands premium pricing through regulatory moats. Consumer Goods is where volume erosion concentrates as share shifts to medical end uses.
Material Type:
Material chemistry determines margin structure, with certified biocompatible formulations capturing recurring revenue streams while commodity resins compete on unit cost.
- Resin:Acrylate and epoxy-based photopolymers constitute the foundational material platform. ISO 10993 certification pathways for surgical guide applications create defensible moats for established formulators with dedicated regulatory affairs capacity.
- Elastomer:Programmable polyurethane and silicone-modified chemistries enable end-use flexibility exceeding traditional prototyping boundaries. Carbon Inc.'s proprietary resin library anchors this fastest-climbing segment through subscription supply models.
- Thermoplastic:Limited compatibility with vat photopolymerization chemistry constrains this material category to experimental formulations. Research-stage development occurs primarily in German university-industry consortia.
- Composite:Ceramic-filled and glass fiber-loaded resins enhance mechanical properties for dental crown and bridge applications. These specialized formulations command 3-4x premium over standard resins through ceramic particle loading ratios.
Standard resin dominates material volume through installed base breadth. Elastomer formulations are where formulation investment concentrates.
Application:
Application focus segments the market by workflow maturity, from established dental production to constrained jewelry prototyping.
- Dental:Surgical guide and clear aligner model production represents the most penetrated application with regulatory-validated workflows. FDA 510(k) clearance requirements compress development timelines and limit market access for uncertified material suppliers.
- Prototyping:Consumer electronics and automotive design verification historically anchored equipment purchases. This segment faces structural pressure as medical manufacturing captures rising installation share.
- Manufacturing:End-use elastomeric component production through CLIP architecture exceeds traditional prototyping boundaries. Hearing aid custom-fit earpieces exemplify this transition from verification to production workflows.
- Jewelry:Lost-wax casting patterns and direct precious metal printing remain constrained by post-processing labor intensity. Manual support removal and surface finishing requirements resist automation, capping scalability.
Dental dominates revenue generation through regulatory validation. Manufacturing is where application expansion concentrates as photochemistry enables production-grade properties.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Hamburg's container throughput underwrites Germany's precision manufacturing corridor, where medical device clusters integrate vat photopolymerization into regulated cleanroom workflows. This infrastructure anchors European demand for biocompatible resin production systems.
United States
FDA 510(k) clearance pathways for biocompatible resins compress development timelines for dental device manufacturers. The agency's quality system regulation mandates full traceability documentation for permanent patient contact devices. Minneapolis-St. Paul medical technology clusters anchor demand for validated SLA production equipment serving orthodontic workflows.
Germany
EU MDR compliance obligations force dental device manufacturers toward production equipment with automated data logging capabilities. REACH restrictions on acrylate monomer chemistries create substitution mandates that reshape supply chains toward bio-based resin innovators. Stuttgart's precision manufacturing corridor concentrates demand for high-resolution optical configurations in ISO 13485-certified facilities.
China
NMPA medical device registration requirements for dental applications tighten material certification standards under revised Class II device pathways. LCD panel manufacturing infrastructure in Shenzhen and Dongguan enables sub-thousand-dollar hardware production for price-sensitive independent laboratories. Yangtze River Delta medical device clusters integrate vat photopolymerization into export-oriented production workflows.
Japan
PMDA pharmaceutical and medical device agency guidelines for 3D-printed patient-specific devices establish biocompatibility testing requirements aligned with ISO 10993 standards. METI industrial policy supports additive manufacturing adoption in precision component sectors. Nagoya's automotive-adjacent manufacturing belt deploys CLIP architecture for elastomeric prototyping in advanced product development centers.
South Korea
MFDS medical device safety standards for dental materials create certification barriers favoring established resin formulators with dedicated regulatory affairs capacity. Government-backed additive manufacturing R&D consortia in Daejeon-Sejong accelerate photochemistry formulation capabilities. Seoul Capital Area hearing aid manufacturers capture rising installation share for custom-fit earpiece production.
Vat Photopolymerization 3D Printing Technology Market Competitive Landscape
Concentration sits with diversified additive manufacturing incumbents and specialized resin-chemistry developers. The market structure fragments across hardware architecture tiers rather than consolidating around dominant platforms. Three archetypes define competitive positioning: legacy SLA patent holders with service-intensive direct sales, LCD platform disruptors with e-commerce distribution, and continuous liquid interface production specialists with subscription resin models. Dominant competitive moves include strategic partnerships between hardware OEMs and certified resin formulators, plus geographic expansion into German medical device clusters with localized regulatory support.
Within the diversified incumbent tier, 3D Systems and Stratasys occupy positions anchored by decades of additive manufacturing infrastructure. Carbon Inc. exemplifies the chemistry-first archetype through its proprietary CLIP architecture and resin subscription approach. Among desktop-format specialists, Formlabs represents accessibility-driven positioning that sustains adoption among capital-constrained independent laboratories. These three anchors illustrate how competitive advantage fragments across patent depth, material chemistry control, and distribution format rather than consolidating around scale.
| Leading Market Players |
|---|
| 3D Systems |
| Formlabs |
| Stratasys |
| Carbon Inc. |
| Nexa3D |
| Asiga |
| Peopoly |
| Anycubic |
| Phrozen |
| Others |
Pricing and Supply Chain Analysis
Acrylate monomer substitution mandates under REACH regulations simultaneously relocate resin formulation capacity toward bio-based suppliers in Germany and compress pricing power for legacy petroleum-dependent formulators serving price-sensitive Chinese LCD hardware manufacturers.
Pricing Analysis
Volume-discount tiering separates FDA-validated biocompatible resin subscriptions from commodity acrylate formulations sold through e-commerce channels. Three-tier pricing structure across premium certified, standard industrial, and economy desktop tiers reflects ISO 10993 certification investment and optical resolution performance. Cost compression in economy LCD hardware is intensifying because Shenzhen panel manufacturers achieve sub-thousand-dollar production economics. Independent dental laboratories in China's Yangtze River Delta exhibit highest price sensitivity, whereas German precision manufacturing clusters prioritize traceability documentation over acquisition cost.
Supply Chain Analysis
Inventory lead times for optical projection engines stretch 12-16 weeks, constraining hardware OEMs to pre-position LCD panel stockpiles ahead of Chinese New Year manufacturing pauses. Photopolymer resin supply concentrates in Germany, China, and the United States, with formulation expertise anchored in Stuttgart's chemical corridor. Raw material dependencies span acrylate monomers from BASF Ludwigshafen, LCD panels from BOE and Tianma, and oxygen-permeable membranes for CLIP systems. Single-source vulnerability sits with Japanese micromirror array suppliers serving DLP architecture providers. Distribution runs through direct sales for premium SLA systems and Alibaba/Taobao marketplace channels for desktop LCD platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market demands substitution defense against powder-bed fusion and material extrusion technologies encroaching on dental production workflows previously dominated by vat photopolymerization.
For Market Incumbents: Shield proprietary resin formulations through backward integration into acrylate monomer production, particularly in Germany's chemical corridor where REACH substitution mandates favor captive supply chains. Deepen regulatory moats by accelerating FDA 510(k) pathway investments for next-generation biocompatible materials before powder-bed fusion sintering achieves comparable surface finish quality. For New Entrants and Emerging Players: ISO 10993 certification fast-track through partnership with established German dental device clusters offers the most penetrable entry vector for resin formulators lacking dedicated regulatory affairs capacity. Target independent hearing aid manufacturers in South Korea's Seoul Capital Area with elastomeric material solutions for custom-fit earpieces, leveraging desktop-format accessibility that incumbents underweight. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors chemistry-first specialists with proprietary photochemistry libraries over hardware-centric equipment vendors facing margin compression. Long-term viability hinges on material subscription revenue durability rather than capital equipment cyclicality. Monitor NMPA registration timeline acceleration in China as the inflection signal indicating regulatory barrier reduction for Western resin formulators.| Strategic Initiative | Industry Significance |
|---|---|
| Resin Chemistry Acquisition | Proprietary photochemistry libraries anchor recurring subscription revenue against hardware commoditization. |
| EU MDR Traceability Integration | Automated batch logging capabilities capture German dental device manufacturer procurement authority. |
| LCD Panel Supply Agreement | Long-term BOE contracts secure sub-thousand-dollar hardware economics for price-sensitive laboratory segments. |
| FDA 510(k) Fast-Track Partnership | Collaborative regulatory submissions compress biocompatible material certification timelines for surgical guide applications. |
| Hearing Aid Manufacturing Expansion | Elastomeric component production capacity addresses rising installation demand in Seoul and Minneapolis-St. Paul clusters. |
Research Methodology
A spread of perspectives from resin formulation chemists, dental laboratory operations managers, FDA regulatory consultants, and LCD hardware procurement officers converged on the working assumptions driving this analysis. Primary field engagement combined structured interviews with secondary validation against EPA REACH filings, NMPA medical device registration databases, ISO 10993 certification records, and customs trade data for photopolymer resin imports. Bottom-up triangulation across hardware shipment volumes, resin consumption metrics, and end-user installation surveys was cross-checked against top-down market sizing derived from equipment manufacturer revenue disclosures.
Segmentation dimensions modeled include hardware architecture tier, material chemistry certification status, end-use application criticality, and geographic regulatory cluster across the analysis window. CAGRs were derived from regression analysis of historical installation data projected against regulatory pathway timelines and substitution elasticity parameters. Industry-specific forecast inputs incorporated biocompatible resin approval velocity and Chinese LCD panel manufacturing capacity expansion schedules.
The analysis sits within stated boundaries; outcomes outside sustained FDA 510(k) clearance timelines or abrupt REACH acrylate substitution mandates would require recalibration. Forecasts reflect documented assumptions regarding regulatory stability and raw material supply continuity. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
3D Printing Materials
3D Printing Elastomers Market
3D Printing Materials
Advanced Materials for 3D Printing Market
3D Printing Materials
Medical 3D Printing Plastics Market
3D Printing Materials
Global Metal Additive Manufacturing Market
3D Printing Materials
3D Printing Plastics Market
3D Printing Materials
Global Biocompatible 3D Printing Materials Market
3D Printing Materials
3D Printing Materials Market
3D Printing Materials
Non-Metal 3D Printing Market
3D Printing Materials
Stainless Steel 3D Printing Market
3D Printing Materials
Global 3D Printing Filament Market
3D Printing Materials
3D Printed Nanocellulose Market
3D Printing Materials
Middle East 3D Printing Materials Market
3D Printing Materials
3D Printing Resin Market
3D Printing Materials
Low-Temperature Flow Improver Additives for 3D Printing Resins Market
3D Printing Materials
Metal Jet 3D Printing Technology Market
3D Printing Materials
Aerospace 3D Printing Materials Market