
 3D Modeling Software Market | 2026-2036
3D Modeling Software Market Size, Share, and Industry Trends Forecast 2026-2036
3D Modeling Software Market Insights
The capital-intensity divergence between cloud-native platforms and legacy on-premises suites is redrawing competitive boundaries in 3D modeling software. Autodesk Inc. leverages its subscription infrastructure to sustain recurring revenue across architecture and entertainment verticals. Dassault Systèmes anchors high-end manufacturing accounts through deep CAE integration and industry-specific workbenches. Siemens PLM Software Inc. competes on digital-twin convergence, bundling CAD with IoT analytics for factory-floor deployments.
3D modeling software encompasses digital tools that construct, manipulate, and render volumetric representations through polygonal meshes, NURBS surfaces, or voxel grids, typically supporting parametric constraint solving and real-time shader compilation. Its primary commercial purpose spans product visualization, engineering validation, and immersive content creation across manufacturing, AEC, and entertainment supply chains. CAD Applications dominate enterprise procurement budgets due to ISO 10303 interoperability mandates and PLM system lock-in, while Cloud-Based deployment gains share as studios prioritize distributed collaboration over local hardware capex. Mesh Modeling Tools occupy a mature niche among indie game developers, though margin pools increasingly shift toward SaaS bundles incorporating AI-assisted topology optimization.
ISO standards for product data exchange, the EU AI Act's algorithmic disclosure requirements, and FDA 21 CFR Part 11 digital-traceability rules collectively shape software certification burdens and cross-border market access. EMA documentation standards further extend regulatory reach into pharmaceutical facility design workflows, forcing vendors to embed audit-trail capabilities. Stakeholders must monitor how generative-AI training-data liability frameworks reshape feature roadmaps and customer indemnification terms.
Market Dynamics
Real-time rendering pipelines are compressing development cycles across game studios and industrial design houses, forcing vendors to rearchitect core engines for GPU-native computation rather than CPU-bound mesh operations.
Growth Catalysts
- EU AI Act transparency mandates:Algorithmic disclosure requirements for generative design tools are accelerating procurement of audit-ready platforms among automotive and aerospace suppliers seeking regulatory pre-approval.
- Industrial automation clusters:Germany's Rhineland and Bavaria manufacturing corridors are consolidating demand for digital-twin-enabled CAD suites as factory-floor IoT deployments scale.
- Neural radiance fields (NeRF):Photogrammetry workflows are absorbing this volumetric reconstruction technique for rapid asset prototyping in virtual production environments.
Market Restraints
- GPU supply concentration:Foundry capacity constraints in Taiwan and South Korea are inflating hardware refresh cycles for on-premises rendering farms.
- ISO 10303 certification friction:STEP AP242 compliance timelines for PLM interoperability are extending enterprise sales cycles by 8-14 months in regulated verticals.
- Subscription cost compression:Per-seat SaaS pricing for professional-grade suites is squeezing indie studio budgets and driving piracy resurgence in emerging markets.
Strategic Opportunities
- India PLI scheme for electronics:Domestic manufacturing incentives are spawning greenfield facility design demand requiring localized CAD deployment and training infrastructure.
- Digital-twin convergence:Bundling IoT analytics with parametric modeling is opening factory-floor budgets previously reserved for standalone SCADA systems.
- EMA pharmaceutical facility standards:Audit-trail mandates for cleanroom design documentation are creating specialized module opportunities for compliance-embedded modeling tools.
Industry Challenges
- Mesh topology expertise scarcity:Studios report 6-9 month hiring timelines for technical artists proficient in quadrilateral remeshing and UV optimization for real-time engines.
- Legacy PLM integration complexity:On-premises Siemens Teamcenter and Dassault ENOVIA deployments resist API-level connectivity with cloud-native collaborative platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | 3D Modeling Software Market |
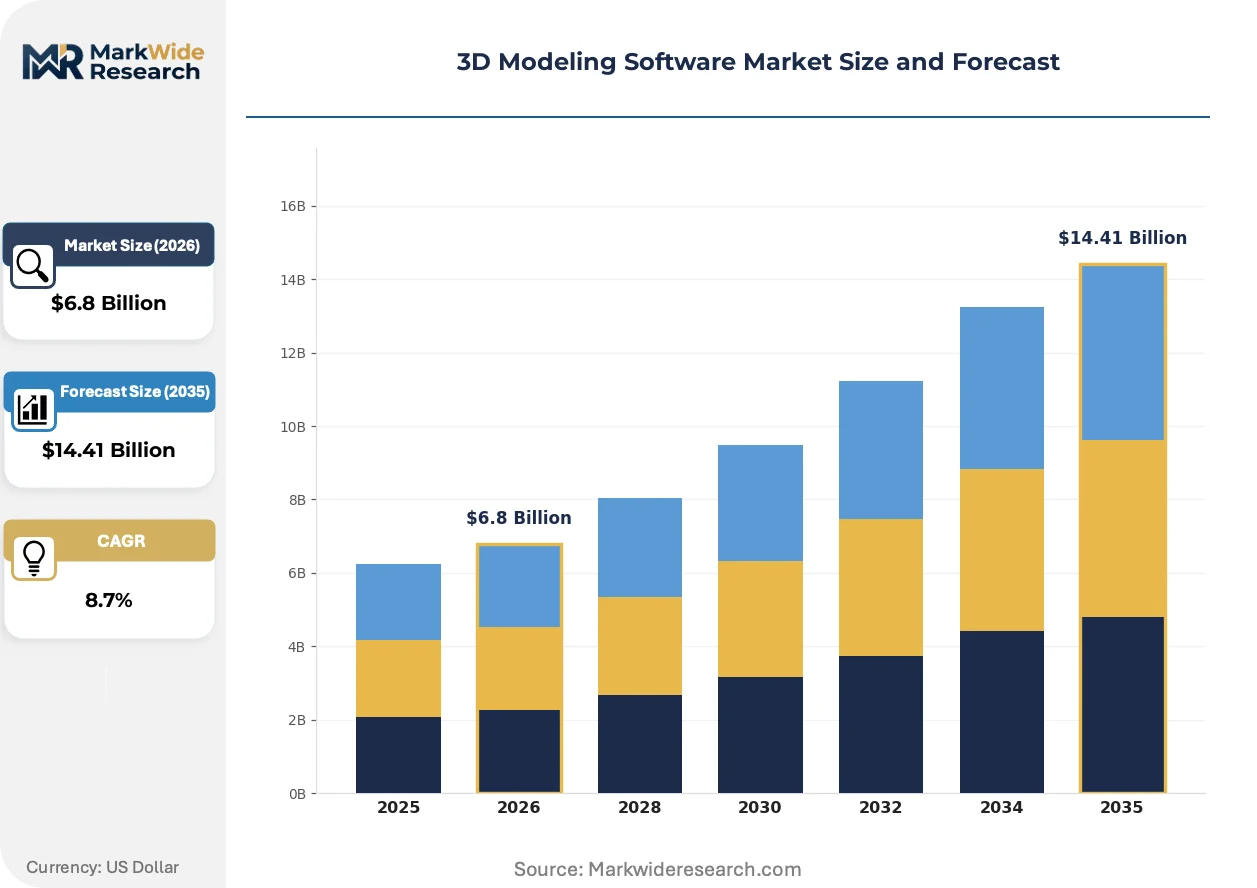
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $14.41 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rendering Software, Mesh Modeling Tools, Sculpting Software, CAD Applications Deployment: Cloud-Based, On-Premises, Hybrid, SaaS End User: Architects, Game Developers, Film Makers, Industrial Designers Feature: Animation Tools, Simulation Capabilities, Texturing Options, VR Integration |
| Companies Covered | Autodesk Inc., Dassault Systèmes, Siemens PLM Software Inc, PTC Inc., Bentley Systems, Hexagon AB, Bricsys NV, Oracle Corporation, CAXA Technology Co., Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
3D Modeling Software Market Trends and Innovations
Generative AI is rewriting asset creation workflows while regulatory disclosure mandates and procurement model shifts are simultaneously reshaping vendor roadmaps and customer contracting structures.
Neural topology optimization is fragmenting traditional manual retopology service markets. Game studios with 200+ headcounts are deploying AI-assisted mesh reduction for character assets, cutting production time by half for secondary NPC models. Boutique outsourcing shops in Eastern Europe are losing retopology contracts to in-house tool adoption, compressing the addressable market for manual labor.
REACH substance restrictions and EU AI Act algorithmic transparency rules are tightening certification burdens for materials databases embedded in CAD platforms. Vendors must now document training data provenance for generative fill features and substance property predictions. Automotive OEMs in Stuttgart and Wolfsburg are demanding third-party audit trails before approving AI-assisted design tools for production use.
Consumption patterns among mid-market AEC firms are rotating toward usage-based licensing rather than perpetual seats. Subscription fatigue is driving procurement teams to negotiate consumption caps with overage forgiveness clauses. This behavioral shift is most visible in Nordic markets where Danish and Swedish architecture collectives have formed purchasing cooperatives to negotiate pooled licensing terms.
3D Modeling Software Market Segmentation
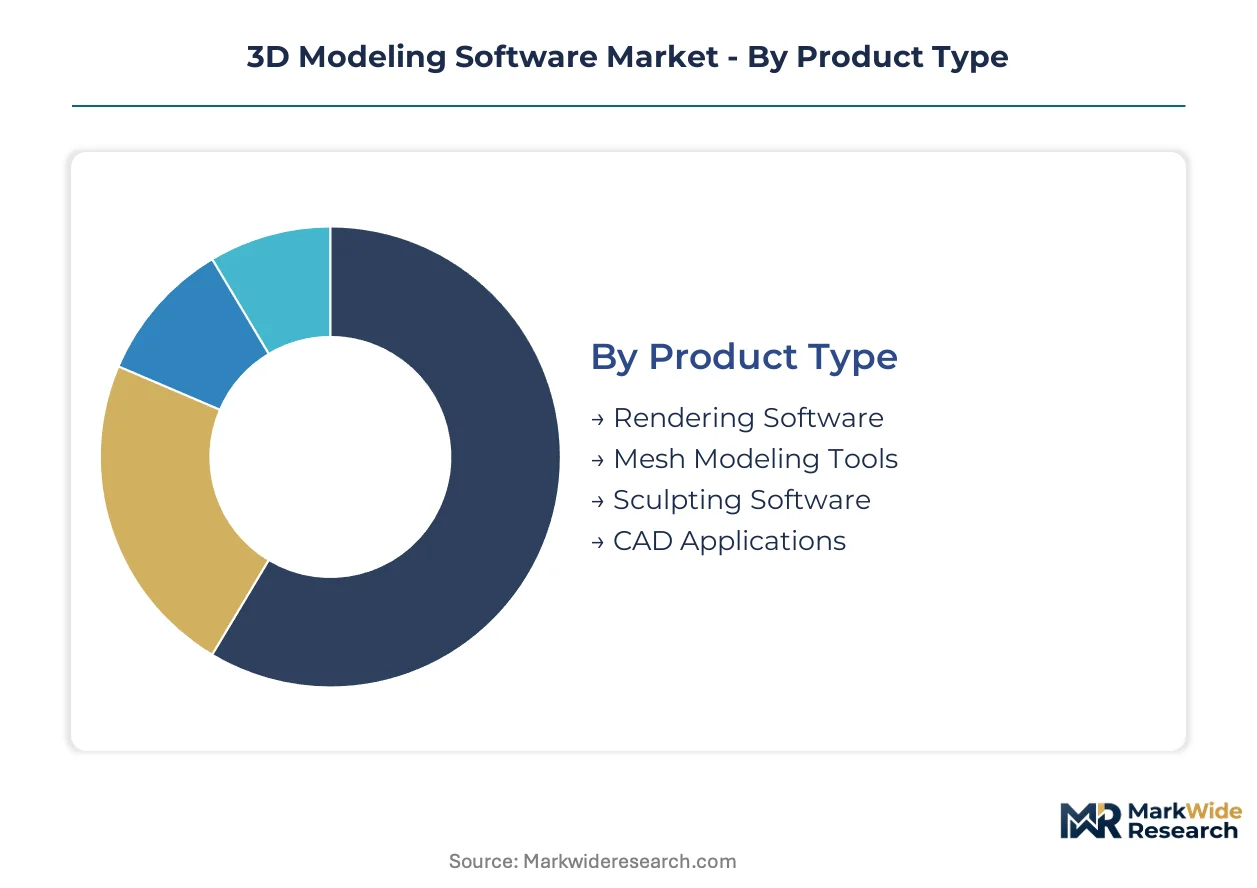
Segmentation in 3D modeling software reveals divergent procurement patterns across technical sophistication tiers and infrastructure maturity. Buyers sort themselves by rendering pipeline complexity, data sovereignty requirements, and integration depth with adjacent PLM ecosystems.
Product Type:
Geographic demand spreads unevenly: CAD Applications concentrate in Germany's industrial automation corridors, while Rendering Software and Mesh Modeling Tools serve export-led entertainment hubs in California and British Columbia.
- CAD Applications:Parametric constraint-solving engines dominate enterprise manufacturing procurement due to ISO 10303 interoperability mandates. Demand clusters in Stuttgart and Wolfsburg automotive OEMs seeking STEP AP242 compliance for supplier integration.
- Rendering Software:Real-time shader compilation and GPU-native ray tracing serve virtual production studios. Game developers in Montreal and Los Angeles drive adoption as LED volume stages displace green-screen workflows.
- Mesh Modeling Tools:Polygonal and NURBS surface manipulation for indie developers and rapid prototyping studios.
- Sculpting Software:High-resolution digital clay workflows for character artists in film and premium game assets.
CAD Applications hold the largest share; momentum sits with Rendering Software.
Deployment:
Cost-tier stratification separates capital-intensive on-premises farms from OpEx-light SaaS subscriptions, with Hybrid deployments capturing mid-market AEC firms seeking burst rendering without full cloud migration.
- Cloud-Based:Distributed GPU clusters enable real-time collaboration across dispersed teams. Nordic architecture collectives in Copenhagen and Stockholm pioneered pooled licensing cooperatives to negotiate consumption-capped terms.
- SaaS:Per-seat subscription models with automatic feature updates attract indie studios avoiding hardware refresh cycles. India's PLI electronics manufacturing incentives are spawning greenfield SaaS procurement for facility design.
- On-Premises:Air-gapped installations for defense and classified aerospace workflows requiring data sovereignty.
- Hybrid:Local preprocessing with cloud-based final rendering for mid-tier industrial design houses managing variable compute loads.
SaaS is expanding most quickly; On-Premises retains the largest installed base in regulated verticals.
End User:
Volume concentration varies by project scale: Industrial Designers and Architects drive seat counts, while Film Makers and Game Developers generate per-project revenue spikes through specialized pipeline modules.
- Industrial Designers:Digital-twin integration with factory-floor IoT analytics. Germany's Rhineland and Bavaria manufacturing corridors consolidate demand for Siemens PLM and Dassault Systèmes suites.
- Game Developers:Real-time engine compatibility and AI-assisted topology optimization. Studios with 200+ headcounts deploy neural mesh reduction for secondary NPC assets.
- Architects:BIM-compliant parametric modeling with clash detection for AEC consortiums.
- Film Makers:Virtual production toolchains integrating with LED volumes and camera tracking systems.
Industrial Designers hold the largest share; Game Developers are climbing the fastest on generative AI adoption.
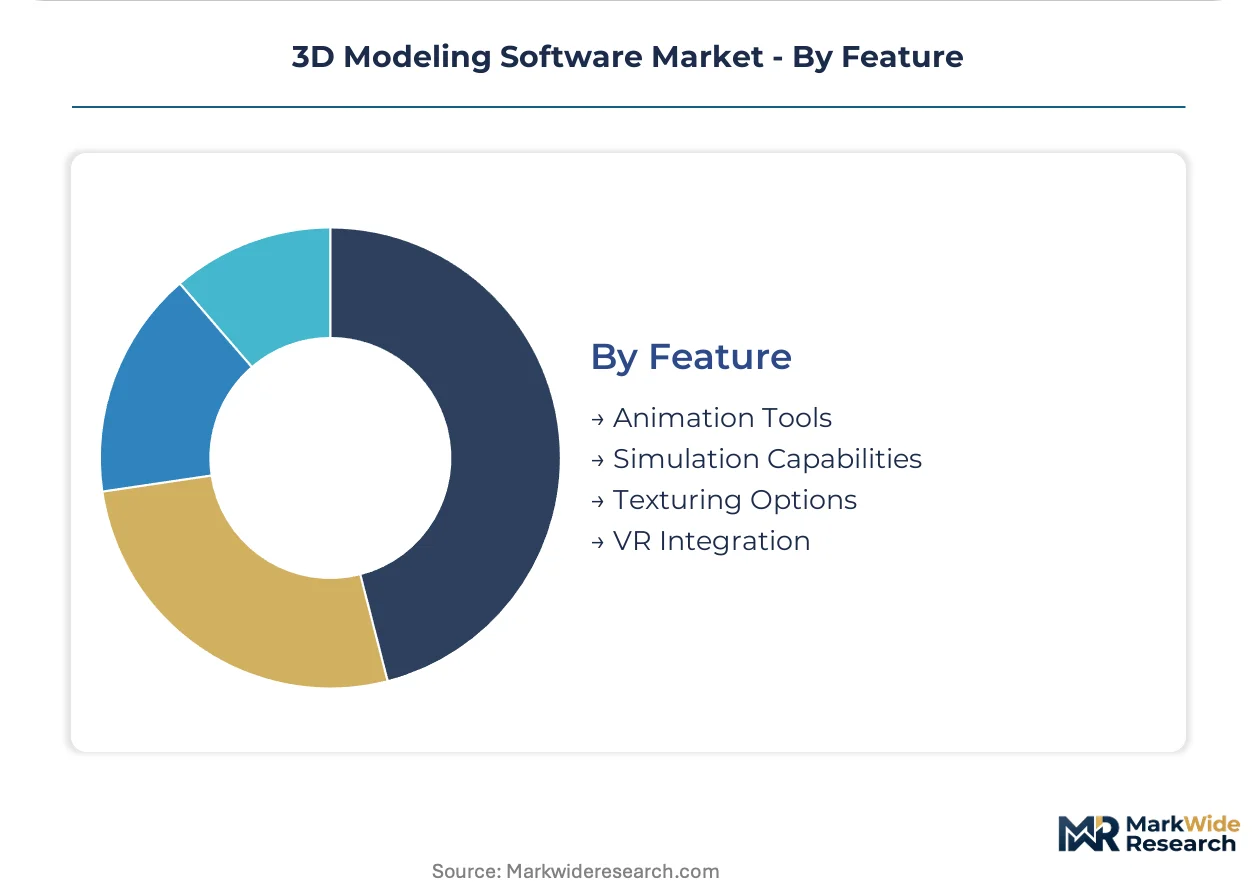
Feature:
Customer type determines feature bundling: enterprise manufacturing prioritizes Simulation Capabilities, while entertainment verticals weight Animation Tools and VR Integration for immersive previsualization.
- Simulation Capabilities:Finite element analysis and computational fluid dynamics embedded within CAD workflows. Automotive suppliers in Stuttgart demand third-party audit trails for AI-assisted generative design under EU AI Act transparency mandates.
- VR Integration:Immersive design review and spatial prototyping for AEC clients. Danish architecture firms use VR walkthroughs to reduce client revision cycles.
- Animation Tools:Rigging, keyframing, and motion capture pipelines for character-driven content.
- Texturing Options:PBR material authoring and procedural substance generation for asset libraries.
Simulation Capabilities hold the largest share; VR Integration shows the steepest expansion trajectory as headset hardware commoditizes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity for 3D modeling software varies sharply by geography. Indian indie studios exhibit extreme price sensitivity, driving piracy resurgence and consumption-capped SaaS negotiations. German automotive OEMs show inelastic procurement, absorbing premium perpetual licenses for ISO-certified CAD suites.
United States
Game developers in Los Angeles and Montreal-adjacent Canadian studios drive real-time rendering adoption for LED volume stages. FDA 21 CFR Part 11 rules shape digital-traceability requirements for medical device design workflows. California's virtual production clusters absorb neural radiance field tools for rapid asset prototyping.
Germany
Automotive OEMs in Stuttgart and Wolfsburg consolidate demand for digital-twin-enabled CAD suites with IoT analytics integration. EU AI Act transparency mandates accelerate procurement of audit-ready generative design platforms. Bavaria and Rhineland manufacturing corridors anchor factory-floor PLM deployments.
India
Electronics manufacturing incentives under the PLI scheme spawn greenfield facility design demand requiring localized CAD training infrastructure. BIS standards and CDSCO documentation rules extend into pharmaceutical cleanroom modeling workflows. Karnataka and Tamil Nadu industrial zones drive SaaS procurement for capital-light deployment.
China
Domestic MIIT standards and GB certification requirements shape software localization for state-linked manufacturing accounts. Dual carbon goals accelerate digital-twin adoption for energy-intensive industrial facilities. Yangtze River Delta and Pearl River Delta clusters concentrate demand for cloud-native collaborative platforms.
Japan
Precision manufacturing in the Chubu/Nagoya corridor sustains demand for high-fidelity simulation-embedded CAD. METI industrial digitization programs subsidize SME adoption of parametric modeling tools. Tokyo-based entertainment studios drive sculpting software procurement for premium character assets.
3D Modeling Software Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in 3D modeling software. The upper tier bundles CAD with adjacent PLM, IoT analytics, and compliance infrastructure to capture enterprise manufacturing accounts. Mid-tier specialists concentrate on vertical-specific workbenches for AEC or entertainment workflows. Competitive moves center on digital-twin convergence partnerships and AI-assisted topology optimization licensing.
Among North American and European platform vendors, Autodesk Inc. and Dassault Systèmes occupy positions exemplifying the integrated-suite archetype, while Siemens PLM Software Inc. anchors the digital-twin convergence tier. These three represent divergent strategic postures: subscription infrastructure leverage, deep CAE integration, and factory-floor IoT bundling respectively.
| Leading Market Players |
|---|
| Autodesk Inc. |
| Dassault Systèmes |
| Siemens PLM Software Inc |
| PTC Inc. |
| Bentley Systems |
| Hexagon AB |
| Bricsys NV |
| Oracle Corporation |
| CAXA Technology Co., Ltd |
| Others |
Pricing and Supply Chain Analysis
Per-seat SaaS subscriptions with consumption-capped overage clauses lock in recurring revenue visibility while capping buyer exposure to GPU hardware volatility. This contract structure concentrates pricing power with cloud-native vendors serving Nordic architecture collectives and Indian PLI electronics manufacturers.
Pricing Analysis
After-sales training and certification revenue tiers now drive lifetime value for enterprise CAD suites. Autodesk and Dassault Systèmes monetize through three-tier pricing structure across premium, standard, and economy levels differentiated by ISO 10303 certification grade and PLM integration depth. Cost compression in indie studio SaaS tiers intensifies because subscription fatigue triggers piracy resurgence in price-sensitive markets like India. Game developers with sub-50 headcounts exhibit highest price sensitivity; German automotive OEMs absorb premium perpetual licenses with minimal negotiation.
Supply Chain Analysis
Inventory lead times for GPU accelerator cards now stretch 16-24 weeks, forcing studios to reserve cloud burst capacity rather than refresh on-premises farms. Hardware supply concentrates in Taiwan, South Korea, and the United States for NVIDIA and AMD silicon. Software development draws from open-source geometry libraries, proprietary rendering engines, and AI training datasets licensed from photogrammetry providers. Single-source vulnerability in Taiwan foundry capacity exposes rendering pipeline costs to geopolitical disruption. Distribution runs through direct vendor sales teams for enterprise accounts and digital marketplaces for indie subscriptions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Early-cycle expansion characterizes this market as real-time rendering pipelines displace green-screen workflows across virtual production studios. NeRF adoption and generative AI mesh reduction are accelerating seat expansion beyond traditional CAD replacement rates.
For Market Incumbents: Shield recurring revenue by embedding audit-trail capabilities for EU AI Act compliance before automotive OEMs mandate third-party verification. Deepen backward integration into GPU cloud infrastructure to offset foundry concentration risk in Taiwan. Prioritize certification investment for EMA pharmaceutical facility documentation standards to capture cleanroom design module demand. For New Entrants and Emerging Players: Anchor in India's PLI electronics manufacturing zones where greenfield facility design lacks localized training infrastructure. Target mid-market AEC firms in Nordic markets seeking consumption-capped cooperative licensing. Pursue a vertical specialist go-to-market angle around neural topology optimization for indie game studios losing Eastern European outsourcing contracts. For Investors and Strategic Acquirers: Cloud-native collaborative platforms with API-level PLM connectivity represent the priority acquisition archetype as legacy on-premises deployments resist integration. Long-term viability hinges on generative AI feature roadmaps that indemnify customers against training-data liability. Watch for inflection when Stuttgart and Wolfsburg OEMs publish approved vendor lists for AI-assisted design tools.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Bundling IoT analytics with parametric modeling captures factory-floor budgets from standalone SCADA systems. |
| Acquisition of Specialist Firm | Neural radiance field startups accelerate virtual production toolchains for LED volume stage deployments. |
| Strategic Partnership | GPU cloud providers secure burst rendering capacity for hybrid deployment mid-market AEC firms. |
| Product Launch | Audit-embedded modules address EMA pharmaceutical facility standards for cleanroom documentation workflows. |
| Geographic Expansion | Localized CAD training infrastructure captures India's PLI electronics manufacturing greenfield demand. |
Research Methodology
Operator-level perspectives from CTOs at game studios, IT procurement officers at automotive OEMs, platform engineers at cloud rendering providers, and integration specialists at PLM consultancies anchored the qualitative base. Secondary validation drew from SEC filings, hyperscaler capex disclosures, ISO certification registries, and EU regulatory documentation. Bottom-up seat-count estimates triangulated against top-down vendor revenue attribution across deployment models and vertical segments.
Sensitivity analysis tested forecast robustness across GPU supply scenarios, EU AI Act implementation timelines, and PLM interoperability adoption curves. Segmentation dimensions modeled include deployment architecture, organization size tier, end-use vertical, integration complexity level, and regional regulatory cluster. CAGRs were derived from trend-line extrapolation of seat expansion rates and average revenue per user movements. Industry-specific inputs incorporated neural rendering adoption curves and digital-twin deployment penetration in German manufacturing corridors.
Decision-makers should treat outputs as directional under assumptions of sustained GPU cloud capacity expansion and stable EU regulatory timelines; material deviation in foundry output or AI liability frameworks would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Cloud-Based ERP Software Market
Software & Services
RFP Software Market
Software & Services
EDA Tools Market
Software & Services
Smartphone OS Market
Software & Services
Global Gamification Software Market
Software & Services
Global Demand Planning Software Market
Software & Services
Collaborative Applications Market
Software & Services
Global Recipe Apps Market
Software & Services
Sourcing Software Market
Software & Services
Russian IT Software and Services Market
Software & Services
Skills Management Software Market
Software & Services
Global Accounts Receivable Software Market
Software & Services
Camera Tracking Software Market
Software & Services
Binary Drivers Market
Software & Services
Global Fixed Asset Management Software Market
Software & Services
Lab Automation Software Market