
 ASEAN Online Accommodation Market | 2026-2036
ASEAN Online Accommodation Market Size, Share, and Industry Trends Forecast 2026-2036
ASEAN Online Accommodation Market Outlook
Platform commission revenue is fragmenting between online travel agencies and direct booking channels. Booking Holdings leverages its multi-brand architecture to sustain rate parity leverage across Southeast Asian markets. Traveloka anchors Indonesia's domestic travel recovery through localized payment integrations and inventory depth. Agoda differentiates via its Bangkok-based supply team that controls pricing relationships with independent hoteliers.
The ASEAN online accommodation sector encompasses digitally intermediated lodging transactions across hotels, hostels, vacation rentals, and apartments, where booking engines match inventory to travelers through real-time availability APIs and dynamic pricing algorithms. The primary commercial purpose is reducing friction in cross-border leisure and business travel procurement while enabling property operators to optimize yield per available room. Hotels command the largest transaction volume but vacation rentals capture expanding margin pools as extended-stay demand lengthens average booking values. Mobile apps represent the fastest-growing distribution channel, displacing desktop-based third-party websites as smartphone penetration deepens across Indonesia, the Philippines, and Vietnam.
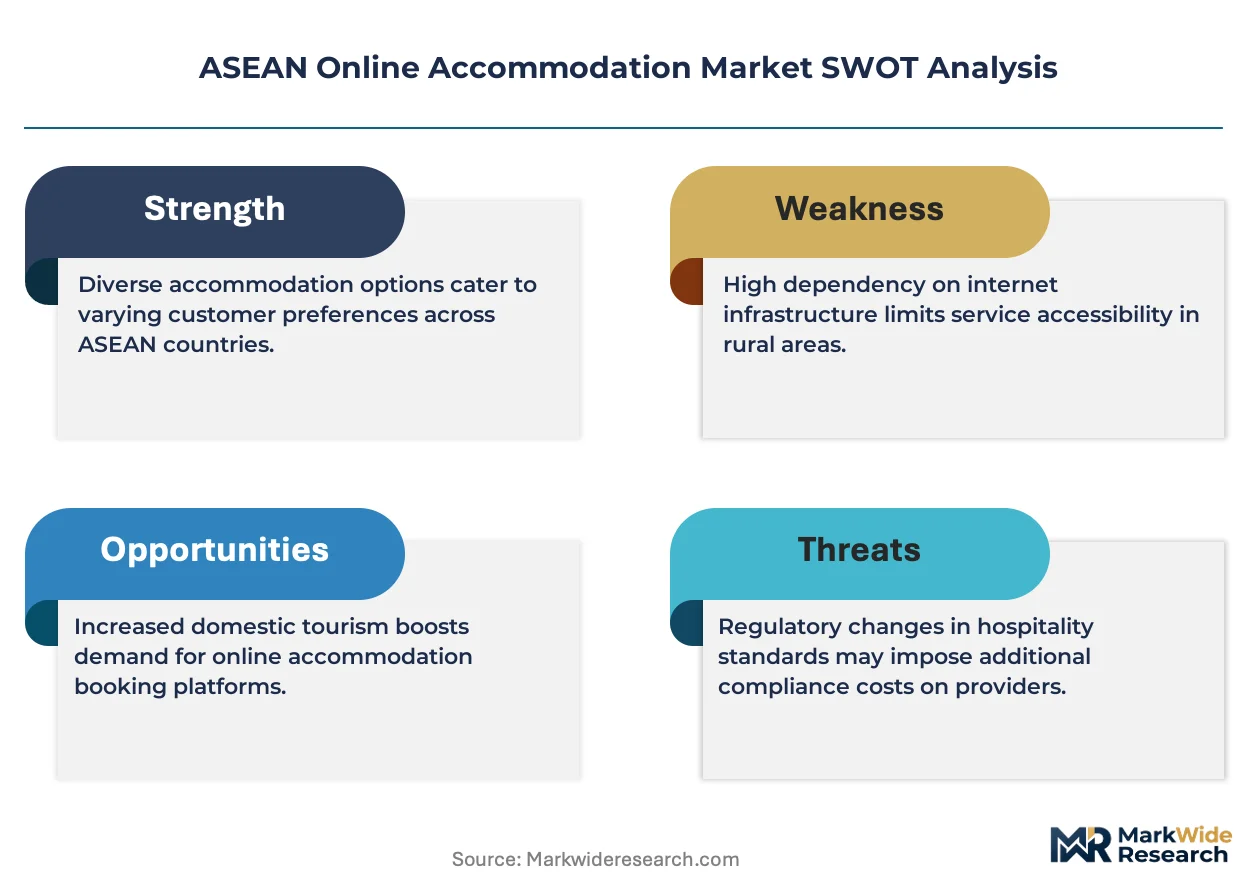
Indonesia's Ministry of Tourism and Creative Economy enforces digital platform registration rules that shape market access for foreign booking engines. Thailand's Personal Data Protection Act, modeled on GDPR principles, imposes consent requirements on guest data handling that raise compliance costs for online travel agencies. Vietnam's Decree on E-Commerce mandates licensing for cross-border accommodation platforms, creating operational barriers for unregistered intermediaries. Stakeholders must monitor whether ASEAN member states harmonize data localization requirements or pursue divergent national frameworks that fragment platform architecture.
Market Dynamics
Mobile-first booking behavior is compressing commission structures across ASEAN accommodation platforms, forcing intermediaries to rebalance revenue models toward subscription services and ancillary travel products.
Growth Catalysts
- Digital Nomad Visa Liberalization:Indonesia's Ministry of Tourism and Creative Economy has streamlined extended-stay permits, directly expanding average booking durations for serviced apartments in Bali and Jakarta.
- Real-Time Pricing APIs:Dynamic yield algorithms now synchronize inventory across metasearch engines, reducing vacancy rates for independent hoteliers in Vietnam and Thailand.
- Chinese Leisure Recovery:Post-pandemic outbound travel from mainland China is concentrating on Phuket and Da Nang, restoring premium vacation rental occupancy in these coastal clusters.
Market Restraints
- Data Localization Mandates:Vietnam's Decree on E-Commerce requires cross-border platforms to store guest transaction data within national borders, raising server infrastructure costs.
- Payment Fragmentation:Indonesia's archipelago geography sustains hyperlocal e-wallet dominance, complicating unified checkout experiences for foreign booking engines.
- Rate Parity Enforcement:Thailand's Personal Data Protection Act constrains how platforms leverage guest history for personalized pricing, limiting margin expansion tactics.
Strategic Opportunities
- Extended-Stay Supply Gap:The Philippines' secondary cities lack branded serviced apartment inventory, creating first-mover advantages for platforms with localized leasing operations.
- Direct Booking Incentives:Loyalty program integration with airline miles is enabling property operators in Malaysia to bypass aggregator commissions.
- Cross-Border Regulatory Harmonization:ASEAN member states are negotiating mutual recognition of digital platform licenses, potentially reducing compliance duplication costs.
Industry Challenges
- Legacy Property Management System Integration:Independent hoteliers in Cambodia and Laos operate on fragmented software stacks, complicating real-time inventory synchronization.
- Multilingual Content Operations:Platforms must maintain localized descriptions across Thai, Vietnamese, Bahasa Indonesia, and Mandarin variants, straining editorial workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | ASEAN Online Accommodation Market |
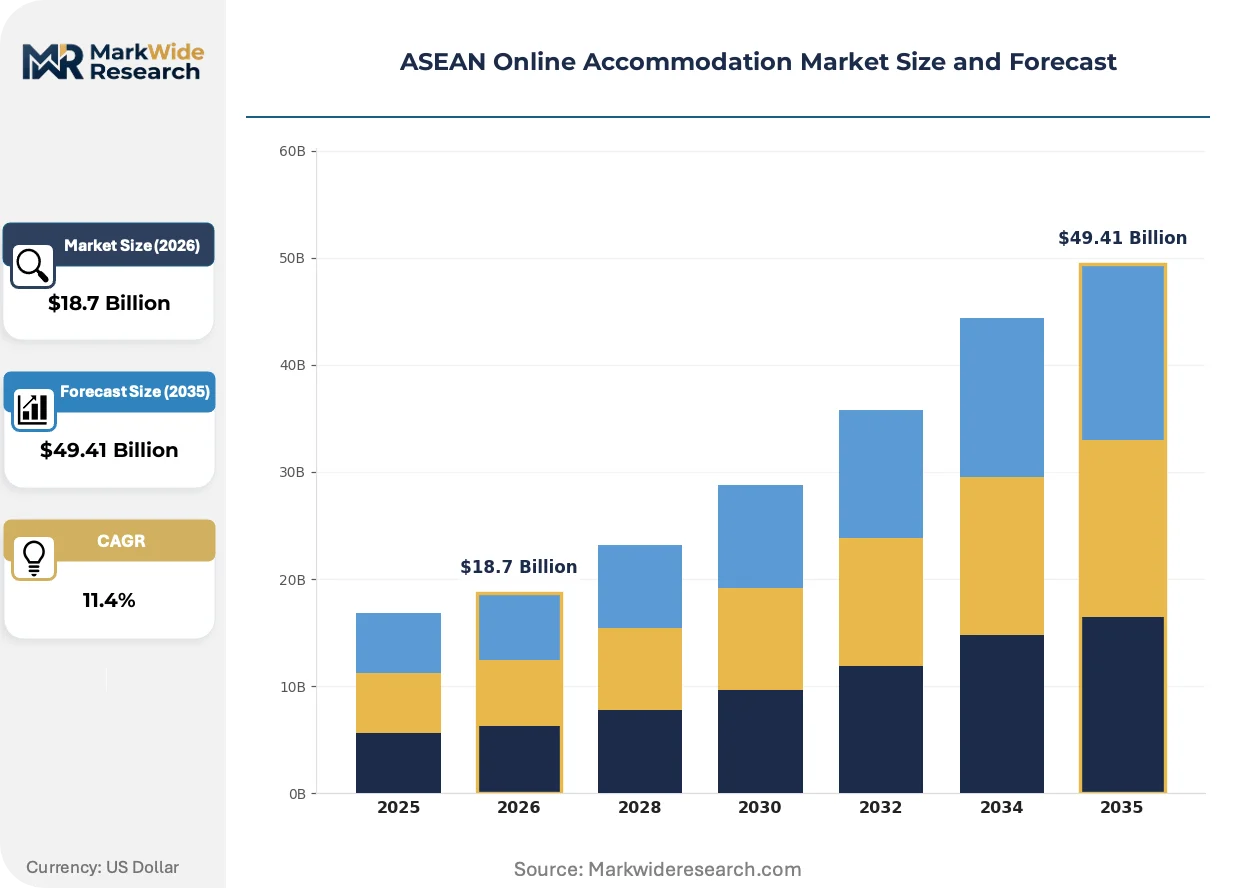
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $49.41 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hotels, Hostels, Vacation Rentals, Apartments Price Tier: Luxury, Mid-Range, Budget, Economy Customer Type: Business Travelers, Leisure Travelers, Families, Couples Distribution Channel: Online Travel Agencies, Direct Bookings, Third-Party Websites, Mobile Apps |
| Companies Covered | Booking Holdings, Traveloka, Expedia Group, Agoda, Trip.com Group, Airbnb, Hotels.com, Trivago, TripAdvisor, Others |
| Regions Covered | Southeast Asia: Indonesia, Thailand, Vietnam, Philippines, Malaysia, Singapore, Myanmar, Cambodia, Rest of Southeast Asia |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
ASEAN Online Accommodation Market Strategic Shifts
Platform architecture across ASEAN accommodation markets is pivoting from transaction facilitation toward embedded financial services and predictive demand modeling.
Artificial intelligence-driven pricing engines are migrating from rule-based yield management toward reinforcement learning models that ingest competitor rates, local event calendars, and flight search data simultaneously. Boutique hotel chains in Bangkok and Singapore are piloting these systems to compress price-update cycles from hours to minutes. The structural consequence is rate parity erosion between direct and third-party channels.
Thailand's Personal Data Protection Act is tightening consent requirements for guest data retention, forcing platforms to rebuild analytics pipelines around anonymized behavioral cohorts rather than individual profiles. Property operators now face higher compliance costs for personalized marketing automation. The mid-market hotel segment is responding by outsourcing data governance to specialized hospitality technology vendors.
Extended-stay travelers from South Korea are consolidating booking decisions around mobile super-apps that bundle accommodation, ground transport, and restaurant reservations. This behavior is displacing desktop-based comparison shopping for stays exceeding fourteen nights. The shift is most visible in Phuket and Bali, where Korean-language interface optimization now determines platform market penetration.
ASEAN Online Accommodation Market Segmentation
Segmentation across ASEAN's online accommodation market reveals how booking behavior fragments by trip purpose, price sensitivity, and device preference. Platforms must architect separate inventory and pricing strategies for each slice to capture margin without alienating adjacent demand pools.
Product Type:
The use-case spectrum spans overnight business stops to month-long remote work residencies, each requiring distinct property configurations and amenity bundles.
- Hotels:Full-service and limited-service properties with standardized room configurations and on-site amenities dominate transaction volume across Jakarta, Bangkok, and Singapore. Business travelers from South Korea and China concentrate demand in central business districts where cancellation flexibility and loyalty points drive platform selection.
- Vacation Rentals:Entire homes and villas listed by individual owners or professional managers capture extended-stay premiums in Phuket and Da Nang. Indonesia's digital nomad visa liberalization is lengthening average booking durations for coastal inventory with workspace amenities.
- Hostels:Dormitory and private-room formats target price-sensitive solo travelers and backpacker segments in Ho Chi Minh City and Kuala Lumpur.
- Apartments:Serviced and unserviced residential units appeal to relocating professionals and medical tourists seeking kitchen facilities in Manila and Bangkok medical districts.
The dominant share belongs to Hotels, while Vacation Rentals is closing the gap fastest.
Price Tier:
Cost stratification maps directly to booking channel preference, with luxury segments favoring direct relationships and budget tiers defaulting to aggregator comparison.
- Luxury:Properties commanding premium nightly rates above $200 emphasize concierge services and exclusive experiences. Singapore's Marina Bay and Bali's Seminyak cluster concentrate this inventory where direct booking incentives with airline partnerships displace third-party commissions.
- Mid-Range:Three- and four-star properties with standardized amenities capture the largest addressable demand across ASEAN business corridors. Vietnam's Da Nang and Thailand's Chiang Mai see mid-range supply expanding fastest to accommodate Chinese leisure recovery.
- Budget:Clean, functional accommodations below $50 nightly target domestic travelers and regional backpackers in Indonesia's secondary cities.
- Economy:Minimal-service properties with shared facilities serve price-sensitive segments in Philippine provincial destinations.
Mid-Range properties generate the highest platform commission volume, though Luxury is expanding most quickly as premium vacation rental supply deepens.
Customer Type:
Traveler composition determines length-of-stay patterns, cancellation flexibility requirements, and ancillary product attach rates.
- Leisure Travelers:Discretionary vacationers booking 3-14 night stays drive seasonal demand spikes around Thai New Year and Indonesian school holidays. Chinese and South Korean outbound recovery is concentrating this segment in Phuket and Bali coastal clusters.
- Business Travelers:Corporate-account road warriors with expense policies prioritize central locations and invoice-ready billing in Jakarta, Bangkok, and Singapore financial districts.
- Families:Multi-room bookings with child-specific amenity requirements concentrate in vacation rental inventory during European and Australian holiday periods.
- Couples:Romantic getaway seekers with experience-oriented spending patterns favor boutique hotels and private villas in Ubud and Hoi An.
Leisure Travelers anchor the largest booking volume, while Families are gaining share fastest as multi-generational travel formats expand.
Distribution Channel:
Platform architecture must accommodate divergent technical requirements across legacy web interfaces and native mobile experiences.
- Mobile Apps:Native iOS and Android applications with biometric checkout and localized payment wallets now process the majority of bookings in Indonesia and Vietnam. Korean-language super-app bundling is displacing standalone accommodation platforms in Phuket and Bali.
- Online Travel Agencies:Multi-brand aggregators with metasearch integration maintain rate parity leverage across Thailand and Malaysia hotel inventory.
- Direct Bookings:Property-operated websites with loyalty program integration capture margin-rich repeat stays in Singapore and Kuala Lumpur.
- Third-Party Websites:Desktop comparison engines retain relevance for complex multi-city itineraries among European source markets.
Mobile Apps command the steepest expansion trajectory, while Online Travel Agencies defend the largest transaction share through supply exclusivity contracts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Indonesia processes the highest mobile booking volume across the region, while Thailand and Vietnam concentrate premium vacation rental demand from Chinese leisure travelers. Singapore and Malaysia operate more mature direct-booking channels with loyalty program penetration exceeding neighboring markets.
Indonesia
Domestic leisure travelers and South Korean digital nomads drive extended-stay demand in Bali and Jakarta. The Ministry of Tourism and Creative Economy enforces digital platform registration rules that shape market access for foreign booking engines. Lombok and Yogyakarta secondary markets see fastest supply growth as inventory diversifies beyond traditional resort corridors.
Thailand
Phuket and Bangkok capture the bulk of Chinese outbound recovery and Korean-language super-app bundling. The Personal Data Protection Act imposes consent requirements on guest data handling that raise compliance costs for online travel agencies. Chiang Mai's boutique hotel cluster pilots AI-driven pricing engines to compress rate-update cycles.
Vietnam
Da Nang leads premium vacation rental inquiries from Chinese and Australian source markets. Decree on E-Commerce mandates licensing for cross-border accommodation platforms, creating operational barriers for unregistered intermediaries. Ho Chi Minh City's serviced apartment supply expands to capture relocating regional headquarters staff.
Singapore
Business travelers from South Korea and China concentrate demand in Marina Bay and Orchard Road corridors. The Personal Data Protection Act constrains personalized pricing tactics through strict consent frameworks. Sentosa and Changi precincts develop integrated hospitality-residential formats for extended-stay medical tourists.
Philippines
Secondary cities lack branded serviced apartment inventory, creating first-mover opportunities for platforms with localized leasing operations. The central bank's e-wallet interoperability initiatives gradually reduce payment fragmentation across the archipelago. Cebu and Davao emerge as testbeds for extended-stay supply targeting business process outsourcing relocations.
ASEAN Online Accommodation Market Competitive Environment
Capability concentration sits with specialized supply teams that control pricing relationships with independent hoteliers; scale advantage sits with multi-brand aggregators sustaining rate parity leverage across fragmented inventory pools. The market structure tiers between global OTAs with metasearch integration and regional champions with localized payment depth. Strategic archetypes include supply-heavy intermediaries, mobile-first super-apps, and direct-booking enablers. Dominant competitive moves encompass loyalty program airline partnerships and backward integration into property management software.
Within the multi-brand aggregator tier, Booking Holdings and Expedia Group represent scale-driven platform architecture, while Agoda exemplifies supply-team capability concentration through its Bangkok-based operations. Traveloka anchors the mobile-first super-app archetype with Indonesia-focused payment localization. These three entities collectively illustrate how competitive positioning fragments between global reach and national-market depth across Southeast Asian accommodation distribution.
| Leading Market Players |
|---|
| Booking Holdings |
| Traveloka |
| Expedia Group |
| Agoda |
| Trip.com Group |
| Airbnb |
| Hotels.com |
| Trivago |
| TripAdvisor |
| Others |
Value Chain & Pricing Dynamics
The Malacca Strait shipping corridor's container rate volatility directly compresses margin pools for vacation rental operators importing furnishings and smart-home hardware from China, while simultaneously enabling platform pricing power in premium inventory clusters where supply scarcity concentrates.
Pricing Analysis
Long-term offtake contracts between branded hotel chains and online travel agencies dominate rate-setting mechanisms across Jakarta and Bangkok, though spot-market pricing prevails in Bali's fragmented villa supply. Price differentiation hinges on cancellation flexibility tiers and loyalty program integration depth. Cost compression in budget-tier inventory is intensifying because Indonesian hyperlocal e-wallet fragmentation raises checkout abandonment rates. Domestic leisure travelers exhibit highest price sensitivity, while South Korean digital nomads booking extended stays demonstrate lowest elasticity.
Supply Chain Analysis
Vietnam's Decree on E-Commerce data localization requirements function as export-control analogs, restricting cross-border platform architecture flows and raising server infrastructure barriers for unregistered intermediaries. Supply concentration centers on Thailand for hospitality technology vendors, Singapore for financial services integration, and Indonesia for property management software localization. Raw material dependencies include cloud computing capacity, payment gateway APIs, and multilingual content production labor. Single-source vulnerability sits with Bangkok-based supply teams controlling independent hotelier pricing relationships. Distribution runs through mobile super-apps displacing desktop comparison engines.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Direct booking channels represent the substitution threat that incumbent platforms must neutralize, as property operators in Singapore and Malaysia leverage airline loyalty partnerships to bypass aggregator commissions.
For Market Incumbents: Build data governance moats around anonymized behavioral cohorts compliant with Thailand's Personal Data Protection Act consent frameworks. Consolidate pricing relationships with independent hoteliers in Vietnam and Cambodia through exclusive supply contracts. Defensive moves must counter Airbnb's vacation rental supply expansion and Traveloka's Indonesia-focused payment localization. For New Entrants and Emerging Players: Secondary Philippine cities lacking branded serviced apartment inventory represent the most penetrable entry point for platforms with localized leasing operations. Indonesian digital nomad visa liberalization creates extended-stay demand white-space in Lombok and Yogyakarta. Go-to-market execution should anchor on biometric checkout integration with GCash and Maya e-wallet interoperability. For Investors and Strategic Acquirers: Regional champions with supply-team capability concentration and backward integration into property management software represent the priority acquisition archetype. Long-term viability over the next decade hinges on regulatory harmonization progress across ASEAN member states. Watch for mutual recognition of digital platform licenses as the inflection signal reducing compliance duplication costs.| Strategic Initiative | Industry Significance |
|---|---|
| AI-Driven Pricing Engine Deployment | Chiang Mai boutique hotels pilot reinforcement learning models compressing rate-update cycles from hours to minutes. |
| Biometric Checkout Integration | Indonesian mobile apps leverage fingerprint and facial recognition to reduce booking abandonment in hyperlocal e-wallet environments. |
| Supply Team Geographic Expansion | Bangkok-based pricing relationship controllers extend into Ho Chi Minh City to capture Vietnamese independent hotelier inventory. |
| Loyalty Program Airline Partnership | Malaysian property operators bypass aggregator commissions through direct booking incentives linked to Malaysia Airlines Enrich points. |
| Extended-Stay Supply Acquisition | Platforms with localized leasing operations secure first-mover advantage in Philippine secondary cities lacking branded serviced apartment inventory. |
Study Parameters
Initial hypotheses were tested against primary input from online travel agency supply team directors, independent hotelier association representatives, property management system vendors, and Indonesian Ministry of Tourism officials and refined through secondary validation against SEC 10-K filings, Singapore Personal Data Protection Commission enforcement notices, Vietnam E-Commerce regulatory decrees, and ASEAN tourism arrival statistics. Bottom-up property-level inventory counts were triangulated with top-down platform transaction value estimates.
Demand-supply balance framing anchored the analytical framework across the analysis window, with segmentation modeled across product type, price tier, customer type, and distribution channel dimensions plus platform regulatory registration status as an industry-specific overlay. CAGRs were derived from curve-fitting historical booking volume trajectories against smartphone penetration and digital nomad visa policy shifts as forecast inputs.
Stress conditions across Chinese outbound travel recovery velocity, ASEAN data localization harmonization progress, and e-wallet interoperability implementation were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions around mobile-first booking behavior persistence and extended-stay demand elasticity. Material shifts in Indonesia's digital platform registration enforcement posture would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Accommodation
Asia-Pacific Student Accommodation Market
Accommodation
United Kingdom Hospitality Market
Accommodation
Netherlands Hospitality Industry Market
Accommodation
Italy Online Accommodation Market
Accommodation
China Tourism and Hotel Market
Accommodation
Japan Hospitality Market
Accommodation
India Online Accommodation Market
Accommodation
Switzerland Hospitality Market
Accommodation
Asia-Pacific Travel Accommodation Market
Accommodation
Alternative Accommodation Market
Accommodation
Peer to Peer Accommodation Market
Accommodation
United States Online Accommodation Market
Accommodation
UK Student Accommodation Market
Accommodation
Sweden Hospitality Market
Accommodation
Hong Kong Hospitality Industry Market
Accommodation
Underwater Hotels Market