
 Yoga Mat Market | 2026-2036
Yoga Mat Market Size, Share, and Industry Trends Forecast 2026-2036
Yoga Mat Market Analysis
The EU REACH regulation restricting phthalates in PVC consumer goods is shifting demand toward natural rubber and TPE yoga mat formulations across European distribution channels. Manduka leverages its closed-cell manufacturing process to sustain premium positioning in specialty retail. Jade Yoga anchors its competitive stance through domestic U.S. production of natural rubber mats. Liforme differentiates via patented alignment systems embedded in polyurethane surfaces.
A yoga mat is a portable, non-slip exercise surface typically constructed from foamed polymers or natural rubber compounds in densities ranging from 3 mm to 6 mm, engineered to provide cushioning and grip during bodyweight movement sequences. Natural rubber and TPE segments are capturing margin pools as consumers reject petroleum-derived PVC alternatives. Thickness specifications cluster around 1/4 inch for general studio use while travel-size formats occupy the fastest-growing size category.
EPA oversight of synthetic rubber manufacturing emissions and California Proposition 65 labeling requirements for chemical disclosures are tightening compliance thresholds for imported mats. The EU Green Deal's circular economy action plan is pressuring brands to demonstrate recyclability across product lifecycles. Stakeholders must monitor evolving chemical restriction lists and invest in transparent supply chain documentation to maintain market access.
Market Dynamics
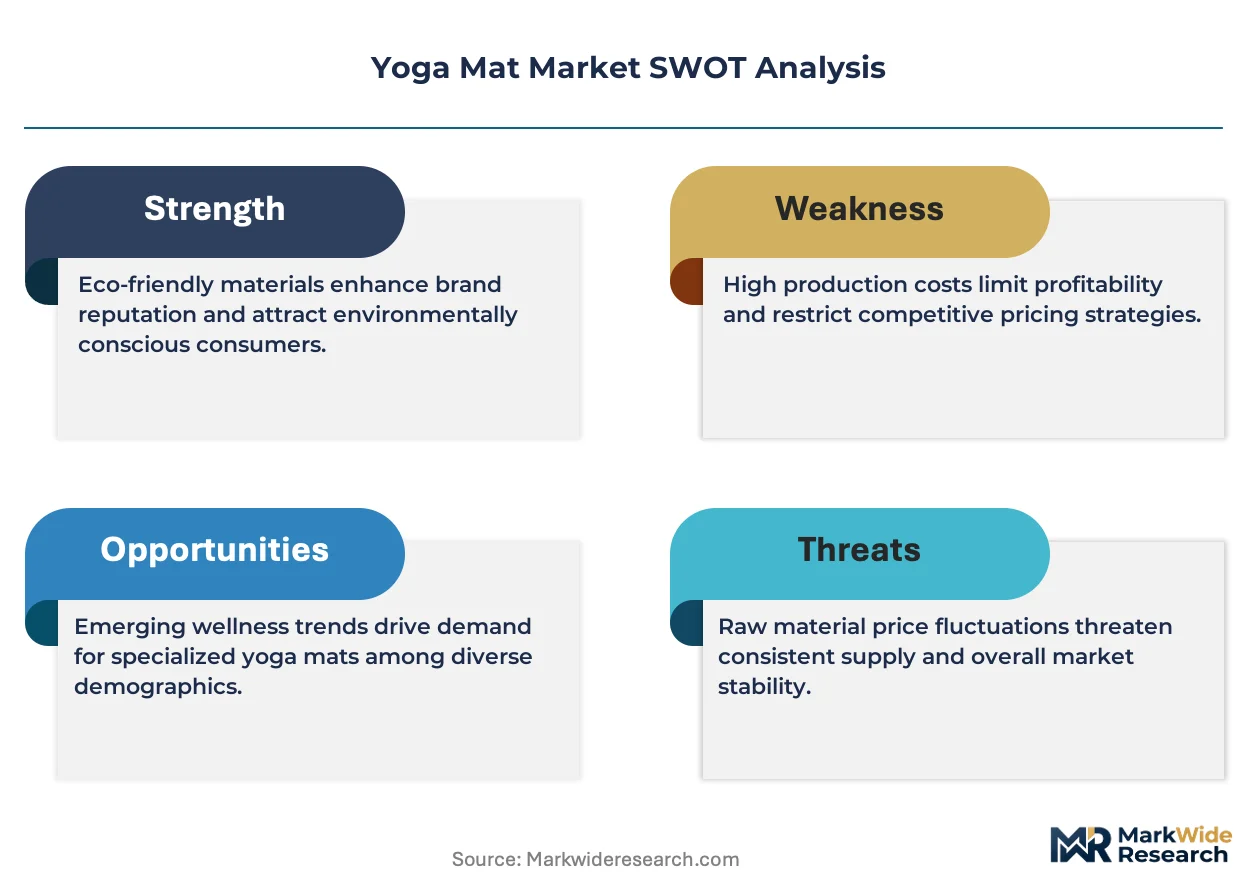
EU REACH phthalate restrictions on PVC consumer goods are accelerating raw material substitution toward TPE and natural rubber formulations, compressing legacy petroleum-based supply chains while elevating compliance costs across European distribution channels.
Growth Catalysts
- Boutique Fitness Studio Expansion:Specialized yoga and Pilates studios in Germany, France, and the United Kingdom are expanding mat procurement budgets as class frequency and membership density rise.
- REACH Chemical Migration:ECHA's tightening substance restrictions on phthalates and heavy metals in PVC products is redirecting formulation investment toward closed-cell TPE and sustainably harvested natural rubber alternatives.
- Corporate Wellness Integration:Employer-sponsored movement programs in the United States and Canada are standardizing mat provision as a baseline amenity, creating institutional volume demand distinct from retail replacement cycles.
Market Restraints
- Natural Rubber Price Volatility:Hevea brasiliensis latex supply concentration in Southeast Asian plantation regions exposes manufacturers to climate-driven harvest variability and commodity price swings.
- REACH Compliance Burden:ECHA registration, evaluation, and authorization requirements impose fixed-cost barriers on small-scale importers seeking European market access, consolidating distribution toward larger compliance-capable suppliers.
- Polyurethane Surface Durability Limits:Premium alignment-grip polyurethane top layers exhibit accelerated wear under high-frequency hot yoga conditions, constraining product lifecycle assumptions and warranty exposure.
Strategic Opportunities
- India Domestic Manufacturing:BIS certification alignment and domestic rubber availability position Indian production for cost-competitive export to Middle Eastern and African markets with limited local supply.
- EU Green Deal Circular Economy Mandates:Recyclability documentation requirements and extended producer responsibility frameworks create first-mover advantage for brands demonstrating closed-loop material recovery.
- Travel-Format Product Line Extension:Ultralight foldable and segmented mat designs are capturing airline-carryon-compatible demand from remote workers and destination retreat participants.
Industry Challenges
- Polymer Chemist Talent Scarcity:Formulation expertise spanning TPE compounding, natural rubber vulcanization, and polyurethane surface adhesion remains concentrated among a narrow cohort of specialized suppliers.
- Multi-Jurisdiction Labeling Complexity:Simultaneous compliance with California Proposition 65 warning requirements, EU CLP hazard classification, and emerging state-level chemical disclosure laws fragments packaging and documentation workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Yoga Mat Market |
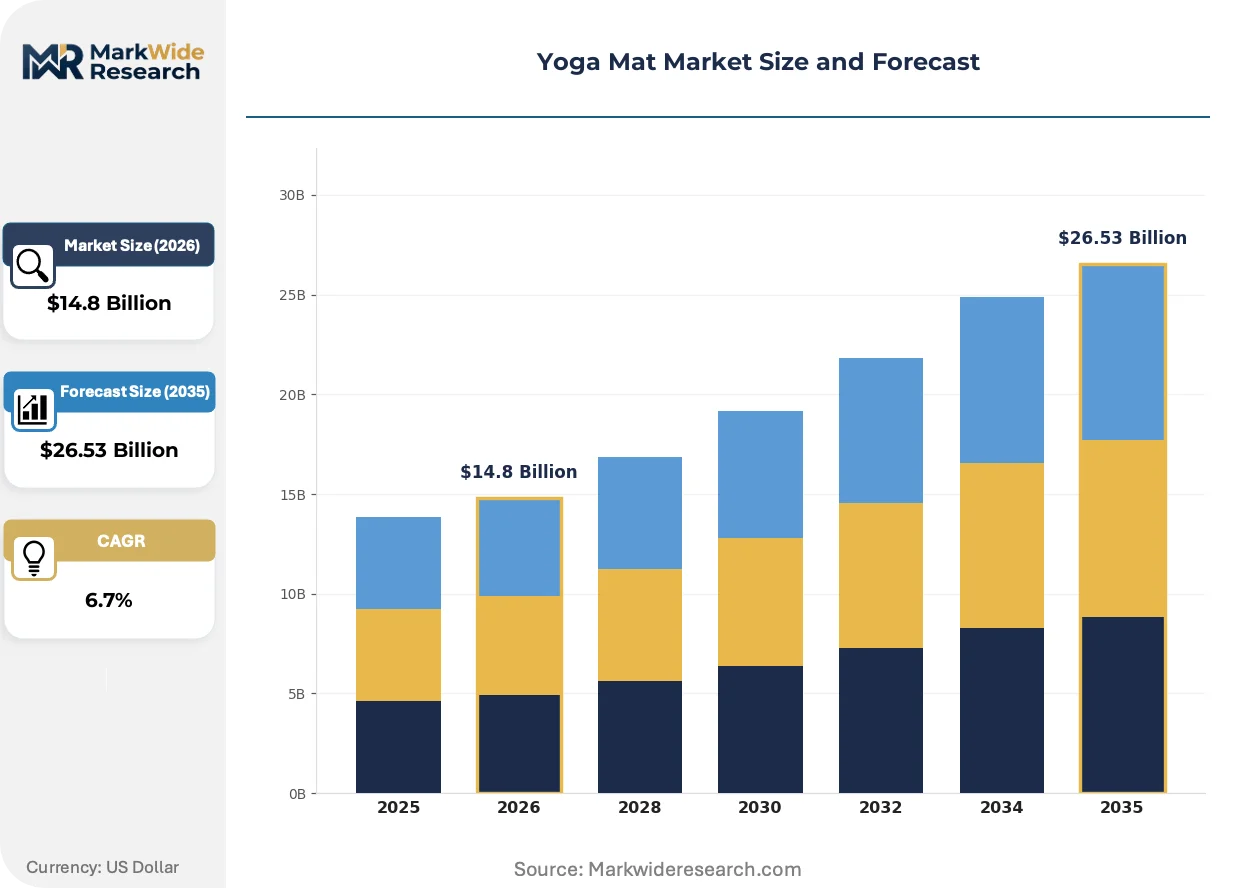
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $26.53 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Natural Rubber, PVC, TPE, Cotton Thickness: 1/16 inch, 1/4 inch, 1/2 inch, 3/8 inch Usage Type: Fitness, Meditation, Training, Outdoor Size: Standard, Extra Long, Travel, Mini |
| Companies Covered | Lululemon Athletica, Manduka, Adidas AG, Jade Yoga, Ecoyoga Ltd., Liforme, prAna, Hugger Mugger, Gaiam, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Yoga Mat Market Emerging Trajectories
Material science convergence with digital manufacturing is compressing product development cycles while regulatory chemical restrictions are locking in formulation trajectories that favor bio-based and recyclable alternatives over petroleum-derived standards.
Laser-guided surface texturing is automating precision groove and alignment mark application on polyurethane and TPE substrates. Premium studios in Germany and the Netherlands are adopting these enhanced grip configurations for advanced vinyasa and inversion-heavy class formats. The technology is automating quality consistency previously dependent on manual die-cutting processes, reducing defect rates and enabling micro-batch customization.
California Proposition 65 enforcement actions against phthalate-containing PVC mats are tightening labeling and reformulation timelines for products entering the United States market. Manufacturers are accelerating migration toward TPE and natural rubber substrates to eliminate warning label requirements that degrade retail shelf appeal. Specialty retailers in Los Angeles and San Francisco are responding by delisting non-compliant SKUs and demanding third-party certified alternative documentation.
Direct-to-consumer subscription models for mat replacement and accessory bundling are displacing traditional retail replacement cycles among committed practitioners. Urban millennials in New York, London, and Berlin are gravitating toward quarterly delivery services that combine mat refresh with block, strap, and cleaning product integration. Studio partnerships in these metropolitan clusters are piloting white-label subscription fulfillment as a retention and ancillary revenue mechanism.
Yoga Mat Market Segmentation
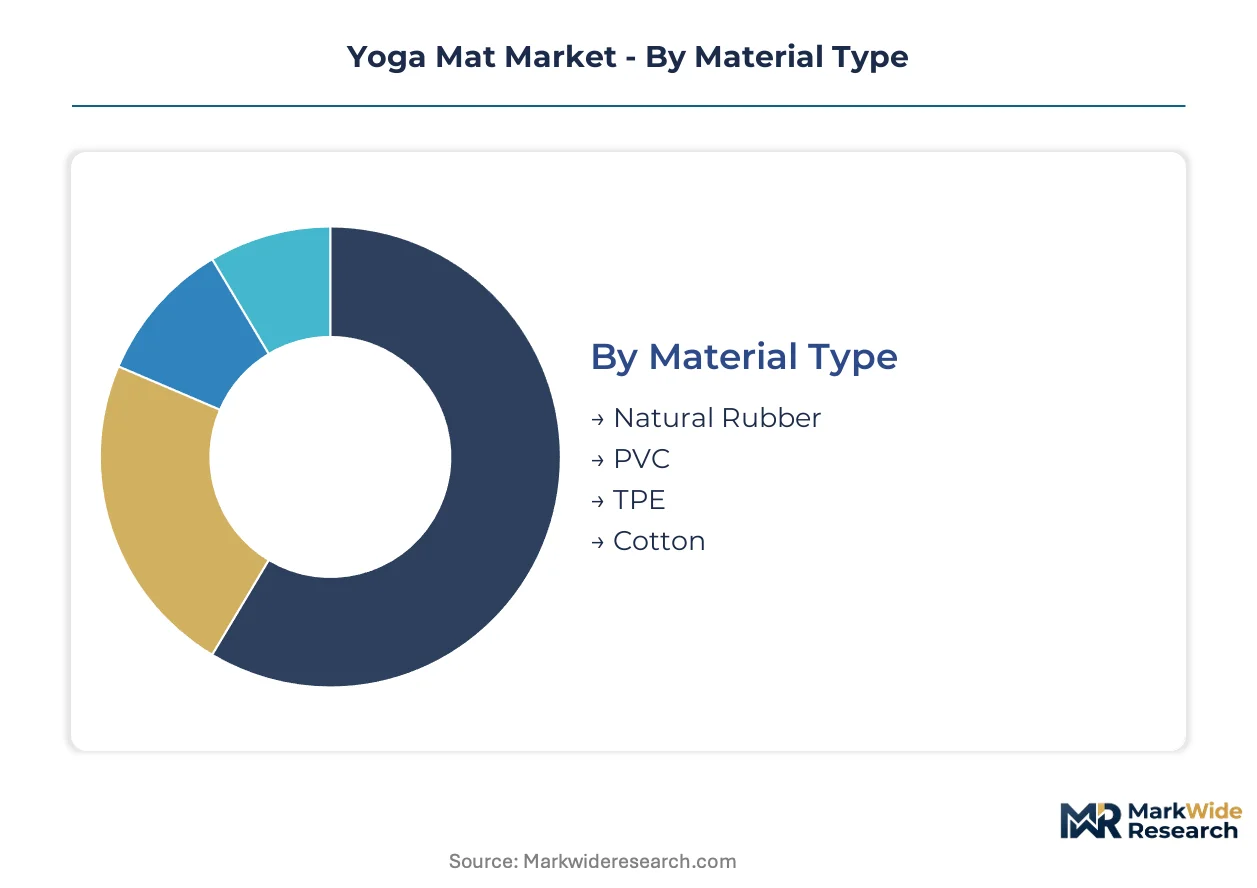
Yoga mat purchasing decisions fragment across material chemistry preferences, dimensional requirements, and intensity of use. Studio procurement managers, individual practitioners, and corporate wellness coordinators each prioritize distinct specification bundles that reshape supplier product roadmaps.
Material Type:
Buyers in this category separate into sustainability-motivated premium purchasers and cost-conscious volume acquirers with divergent tolerance for petroleum-derived inputs.
- Natural Rubber:Harvested from Hevea brasiliensis latex and vulcanized into open-cell or closed-cell structures. German boutique studios and Netherlands premium retailers concentrate demand here as ECHA REACH phthalate restrictions eliminate PVC alternatives from shelves.
- PVC:Petroleum-derived polyvinyl chloride with plasticizer additives for flexibility. Price-sensitive gym chains in Eastern Europe and institutional bulk buyers continue procurement despite regulatory headwinds in Western European markets.
- TPE:Thermoplastic elastomer compounds offering closed-cell moisture resistance without latex proteins. California Proposition 65 enforcement is accelerating reformulation investment toward this segment among U.S.-focused manufacturers.
- Cotton:Woven or felted natural fiber constructions, typically 3-5 mm thickness, washable and biodegradable. Ayurveda retreat centers in Kerala and Rishikesh anchor niche demand for traditional practice surfaces.
PVC leads volumes today; TPE is gaining share fastest.
Thickness:
Joint protection requirements and portability trade-offs divide practitioners across density specifications.
- 1/4 inch:The 6 mm general-purpose standard balancing cushioning density with stability for standing poses. German franchise studios standardize on this specification for mixed-level vinyasa programming.
- 1/2 inch:Maximum cushioning for restorative and yin practices, joint rehabilitation, and senior practitioner segments. Physical therapy clinics in Berlin and Munich are expanding procurement for clinical movement programs.
- 1/16 inch:Ultra-thin travel formats at 1.5 mm, foldable to document-size for luggage compliance. Remote worker segments in London and New York are driving airline-carryon-compatible demand.
- 3/8 inch:Intermediate 5 mm specification for home practitioners seeking upgrade from entry-level mats without 1/2 inch bulk.
1/4 inch dominates installed base; 1/16 inch shows steepest expansion trajectory.
Usage Type:
Application intensity and environmental exposure determine durability specifications and surface engineering priorities.
- Fitness:High-frequency dynamic movement including HIIT-infused yoga, Pilates fusion, and boot camp formats. Los Angeles and New York boutique studios require polyurethane grip layers resistant to accelerated wear from hot yoga conditions.
- Training:Skill acquisition contexts including inversion practice, arm balance progression, and teacher certification programs. Alignment-marked polyurethane surfaces from specialized manufacturers concentrate here.
- Meditation:Static seated practice with minimal grip demands, favoring cotton or thin natural rubber for ground connection. Corporate wellness programs in Toronto and Vancouver standardize these for mindfulness room provisioning.
- Outdoor:UV-resistant and moisture-shedding constructions for beach, park, and retreat use. Australian coastal markets and California outdoor fitness communities drive specification requirements.
Fitness commands the largest revenue pool; Outdoor is climbing the fastest as destination retreat participation expands.
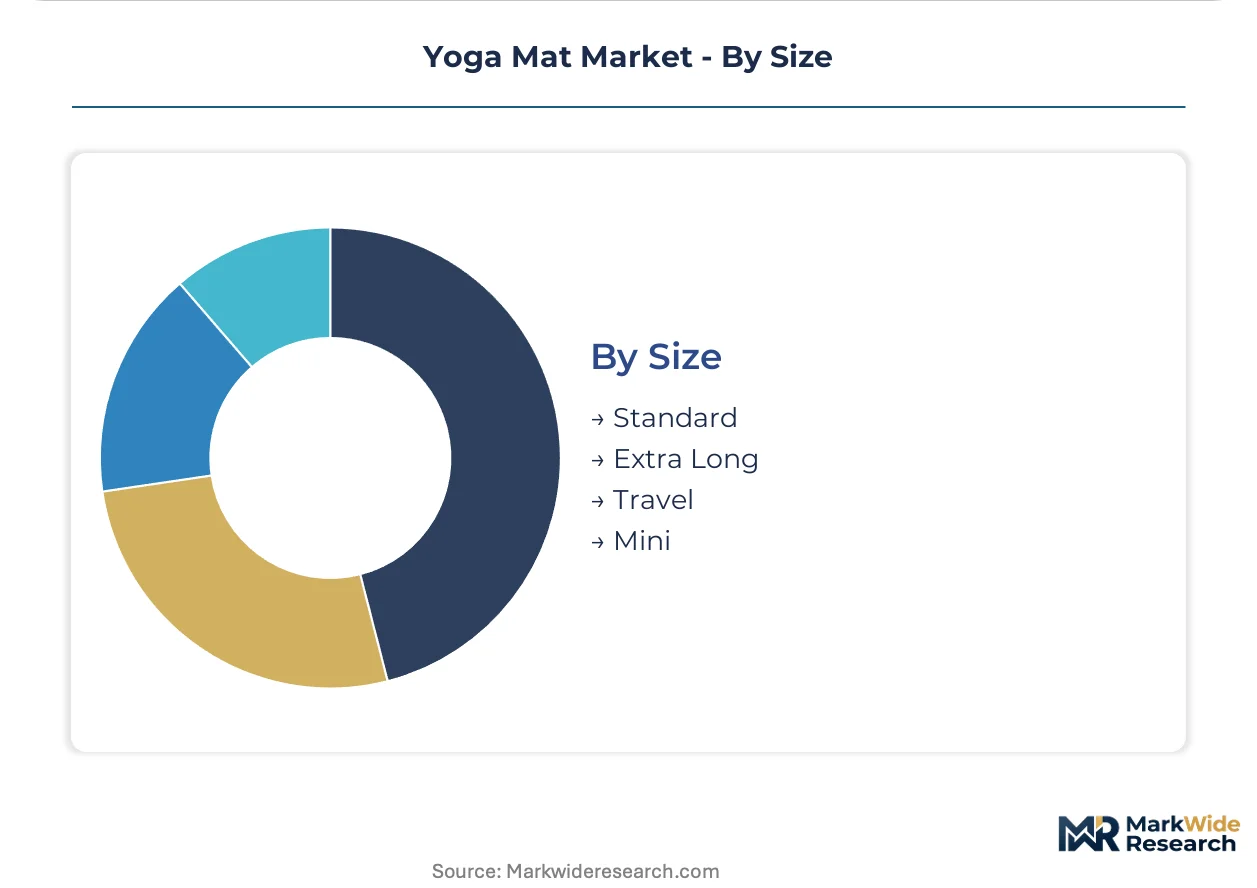
Size:
Body dimensions, practice location constraints, and storage logistics segment buyers across dimensional formats.
- Standard:68-72 inch length accommodating practitioners up to 6 feet, the baseline studio and retail specification. German yoga participation growth concentrates volume demand in this segment.
- Travel:Foldable, rollable, or segmented designs under 24 inches packed length. Digital nomad corridors in Lisbon, Bali, and Mexico City are expanding addressable market for ultralight formats.
- Extra Long:74-84 inch lengths for practitioners over 6 feet 2 inches, formerly custom-order now standard SKU at specialty retailers in Netherlands and United Kingdom.
- Mini:Knee-pad and seated-meditation formats at 24x10 inches, often sold as accessories or children's introductory products.
Standard maintains volume leadership; Travel is expanding most quickly among format variants.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Certified yoga instructors and studio entrepreneurs concentrate in Germany, the United States, and India, anchoring regional demand clusters that reshape procurement patterns and formulation standards across their respective markets.
Germany
Boutique fitness studios in Berlin and Munich are expanding mat procurement budgets as class frequency rises. ECHA REACH phthalate restrictions on PVC consumer goods are redirecting formulation investment toward TPE and natural rubber alternatives. The North Rhine-Westphalia industrial corridor hosts compounders supplying closed-cell TPE substrates to domestic mat manufacturers.
United States
Corporate wellness coordinators in New York and Los Angeles are standardizing mat provision as baseline amenities for employer-sponsored movement programs. California Proposition 65 enforcement actions are tightening labeling timelines for phthalate-containing imports. Los Angeles specialty retailers are delisting non-compliant SKUs and demanding third-party certified alternative documentation.
India
Ayurveda retreat centers in Kerala and Rishikesh anchor niche demand for traditional cotton practice surfaces. BIS certification alignment positions domestic production for cost-competitive export to Middle Eastern markets. The Tamil Nadu rubber belt supplies Hevea brasiliensis latex to regional vulcanization facilities serving mat fabricators.
United Kingdom
Urban millennials in London are gravitating toward direct-to-consumer subscription models for mat replacement and accessory bundling. The country's national chemical regulator enforces EU CLP hazard classification standards for imported fitness equipment. Specialty retailers in Greater London are piloting white-label subscription fulfillment as ancillary revenue mechanisms.
Australia
Outdoor fitness communities along the Queensland and New South Wales coasts are driving UV-resistant and moisture-shedding mat specifications. The country's national chemical regulator administers REACH-aligned substance restrictions on imported consumer goods. Sydney boutique studios are adopting laser-guided surface texturing for advanced vinyasa programming.
Yoga Mat Market Vendor Landscape
Capital-heavy producers compete with asset-light designers across a bifurcated structure where vertically integrated compounders control substrate supply while brand marketers focus on surface engineering and channel access. The vendor base separates into three strategic archetypes: premium alignment-system specialists, natural rubber domestic producers, and mass-market PVC volume players. Consolidation pressures are intensifying as ECHA REACH compliance costs favor larger registration-capable suppliers. Dominant competitive moves include backward integration into TPE compounding capacity and geographic expansion through studio partnership networks.
Within the premium-tier vector, Lululemon Athletica and Manduka exemplify brand positioning anchored in specialty retail channel control and closed-cell manufacturing differentiation. Jade Yoga occupies a position representing domestic U.S. production of natural rubber alternatives. These three entities collectively illustrate how formulation chemistry, manufacturing location, and distribution channel selection stratify competitive positioning in a market where regulatory compliance is displacing legacy petroleum-based supply chains.
| Leading Market Players |
|---|
| Lululemon Athletica |
| Manduka |
| Adidas AG |
| Jade Yoga |
| Ecoyoga Ltd. |
| Liforme |
| prAna |
| Hugger Mugger |
| Gaiam |
| Others |
Supply Flow & Price Mechanics
ECHA REACH phthalate restrictions on PVC consumer goods are forcing procurement managers at German boutique studios and U.S. corporate wellness programs to specify TPE and natural rubber alternatives, which compresses legacy petroleum-based supply chains and elevates landed costs across premium and mid-tier product lines.
Pricing Analysis
Bundled subscription services combining mat replacement with block, strap, and cleaning product integration are displacing unbundled transactional purchases among committed practitioners in New York, London, and Berlin. Three-tier pricing structure across premium alignment-system mats, standard closed-cell TPE products, and economy PVC volume tiers separates buyers by certification grade and after-sales service inclusion. Pricing pressure stems from natural rubber price volatility driven by climate-driven harvest variability in Southeast Asian plantation regions. Cost-conscious gym chains in Eastern Europe exhibit highest price sensitivity, while German boutique studios and Netherlands premium retailers demonstrate lowest sensitivity due to sustainability-motivated procurement mandates.
Supply Chain Analysis
Direct-to-consumer channels and studio partnership networks are displacing traditional retail distribution for subscription-format buyers, while specialty retailers in Los Angeles and San Francisco remain gatekeepers for premium alignment-system products. Manufacturing concentrates in China for TPE compounding, India for natural rubber vulcanization, and Germany for closed-cell polyurethane surface finishing. Raw material flows draw from Hevea brasiliensis latex plantations in Tamil Nadu, petroleum-derived polymer feedstocks in East Asian refining corridors, and polyurethane precursor chemicals in North Rhine-Westphalia. Single-source vulnerability in Southeast Asian latex supply exposes producers to climate-driven harvest disruption. Distribution runs through direct-to-consumer platforms, studio white-label partnerships, and specialty retail channels in metropolitan wellness clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Yoga Mat Market functions as a stable compounder anchored by structural regulatory migration toward bio-based and recyclable formulations that locks in sustained replacement demand across institutional and retail channels.
For Market Incumbents: Extend formulation leadership by accelerating backward integration into captive TPE compounding capacity in North Rhine-Westphalia and securing long-term offtake agreements with Tamil Nadu latex processors. Manduka and Liforme should deepen studio partnership networks in Germany and the Netherlands to defend shelf space against emerging natural rubber specialists. ECHA REACH registration cost barriers favor consolidation toward compliance-capable suppliers with existing substance dossiers. For New Entrants and Emerging Players: Begin with white-label subscription fulfillment partnerships for London and Berlin urban millennials, where direct-to-consumer infrastructure remains underdeveloped relative to demand density. Target travel-format ultralight segments for remote worker corridors in Lisbon, Bali, and Mexico City, where airline-carryon-compatible specifications face limited incumbent specialization. Pursue BIS-certified Indian manufacturing for cost-competitive export to Middle Eastern and African markets with limited local supply. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-scale TPE compounders possessing ECHA REACH registration capabilities and studio distribution relationships in Germany. Long-term viability hinges on regulatory compliance moats widening as chemical restriction lists expand across the analysis window. Monitor ECHA substance authorization timelines as inflection indicators for formulation investment returns, particularly for phthalate-free alternatives gaining shelf space in California and EU markets.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into TPE Compounding | Captive substrate supply secures margin control against petroleum feedstock volatility and REACH compliance cost escalation. |
| Studio Partnership Network Expansion | White-label subscription fulfillment in Berlin and London locks in recurring revenue and displaces retail replacement cycles. |
| Travel-Format Product Line Extension | Ultralight foldable designs capture airline-carryon-compatible demand from remote workers in Lisbon and Mexico City corridors. |
| REACH-Compliant Natural Rubber Sourcing | Sustainably harvested Hevea brasiliensis latex from Tamil Nadu satisfies ECHA substance restrictions and California Proposition 65 enforcement. |
| Laser-Guided Surface Texturing Adoption | Automated precision groove application reduces defect rates and enables micro-batch customization for advanced vinyasa studios in Sydney. |
Methodological Framework
Coverage spans Germany, the United States, India, the United Kingdom, and Australia, with primary inputs from each market combining interviews with studio procurement managers, corporate wellness coordinators, TPE compounder technical directors, and natural rubber plantation supply chain leads. Secondary validation drew from ECHA substance restriction databases, U.S. EPA synthetic rubber manufacturing emission disclosures, BIS certification registries, customs and trade flow records, and SEC filings from publicly traded fitness equipment retailers. Bottom-up mat volume estimates by material type and thickness specification were triangulated against top-down market value reconstructions.
Rate-of-change decomposition across the projection horizon segmented growth drivers by material chemistry substitution effects, regional regulatory enforcement intensity, and channel shift acceleration toward subscription models. The analytical framework modeled demand across material type, thickness specification, usage intensity, and dimensional format dimensions. CAGRs were derived from fitted growth curves incorporating ECHA authorization timeline probabilities, natural rubber price elasticity estimates, and studio expansion rates in metropolitan clusters. Forecast inputs included boutique fitness studio class frequency data and corporate wellness program mat provisioning standards.
Several conditions sit outside the modeled scope, including abrupt climate events disrupting Southeast Asian latex harvests, unilateral tariff impositions on Chinese TPE imports, and breakthrough biodegradable polymer technologies displacing current formulations. Forecasts reflect assumptions regarding regulatory enforcement consistency and substitution elasticity parameters that could revise materially. Periodic stress-testing of base assumptions against ECHA substance authorization progress and California Proposition 65 enforcement actions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fitness Equipment
Global Commercial Fitness Equipment Market
Fitness Equipment
Gym Fitness Accessories Market
Fitness Equipment
Recumbent Stationary Bikes Market
Fitness Equipment
Home Fitness Market
Fitness Equipment
Exercise Bike Market
Fitness Equipment
Personal Exercise Mats Market
Fitness Equipment
Gymnastics Equipment Market
Fitness Equipment
Pilates Reformer Market
Fitness Equipment
Lateral Fitness Equipment Market
Fitness Equipment
Pilates Equipment and Gears Market
Fitness Equipment
BMI Machine Market
Fitness Equipment
Weight Training Benches Market
Fitness Equipment
Lung Exercise Machine Market
Fitness Equipment
South Africa Gym Accessories Market
Fitness Equipment
Europe Fitness Equipment Market
Fitness Equipment
Exercise Band Market