
 Pilates Equipment and Gears Market | 2026-2036
Pilates Equipment and Gears Market Size, Share, and Industry Trends Forecast 2026-2036
Pilates Equipment and Gears Market Analytics
Aftermarket service revenue for reformer maintenance and component replacement is fragmenting across a dispersed base of regional technicians and original equipment manufacturers. Balanced Body, Inc. leverages its domestic manufacturing footprint to control spare parts fulfillment timelines. Merrithew Corporation anchors its competitive stance through instructor certification programs that lock in recurring equipment purchases from affiliated studios.
Pilates equipment and gears encompass mechanically engineered apparatus designed for controlled resistance training, low-impact rehabilitation, and core conditioning, typically incorporating steel spring systems, hardwood frames, and polymer cushioning rated for repetitive load cycles. Reformers command the largest installed base and replacement parts economy, while resistance bands represent the fastest-expanding product type due to minimal storage requirements and entry-level price accessibility across home user and physiotherapy center segments. Steel-framed units dominate commercial installations for durability under high-frequency studio use, whereas wood-construction models capture premium positioning in boutique and residential settings.
The Consumer Product Safety Commission monitors spring mechanism integrity and entrapment hazards for U.S.-distributed apparatus, while EU CE marking requirements under the Machinery Directive enforce load-testing protocols for commercial reformer systems. Germany's Federal Institute for Occupational Safety and Health influences ergonomic design standards that propagate across European manufacturing specifications. Stakeholders must track evolving flammability and chemical content regulations for foam padding materials as California's Department of Toxic Substances Control and the EU REACH framework independently tighten restricted substance lists.
Market Dynamics
Boutique fitness studios are consolidating procurement power through multi-unit franchise networks, concentrating equipment purchasing decisions into fewer hands while demanding extended warranty terms and white-label customization from manufacturers.
Growth Catalysts
- EU Machinery Directive:CE marking requirements for commercial reformer systems are standardizing safety protocols across member states, reducing cross-border compliance friction for equipment exporters.
- Physiotherapy center expansion:Clinical rehabilitation facilities are integrating Pilates apparatus into post-surgical recovery protocols, creating institutional demand for load-rated steel-framed units.
- Home fitness permanence:Residential users who adopted resistance bands during studio closures are upgrading to compact reformer systems, sustaining direct-to-consumer channel momentum.
Market Restraints
- Hardwood supply concentration:Premium frame manufacturers depend on North American and European beech and maple suppliers, exposing margins to lumber futures volatility and kiln-drying capacity constraints.
- Spring steel import dependence:High-tensile coil springs for commercial reformers concentrate production in German and Japanese specialty mills, creating single-source vulnerability for North American fabricators.
- REACH substance restrictions:Evolving EU limits on isocyanates and flame retardants in foam padding are forcing reformulations that extend R&D timelines and compress material supplier options.
Strategic Opportunities
- India studio underpenetration:Metropolitan fitness markets in Mumbai and Bangalore show low reformer density relative to yoga mat saturation, creating first-mover positioning for equipment distributors.
- Digital-physical convergence:Sensor-embedded reformers streaming biomechanical data to physiotherapist dashboards are unlocking subscription revenue layers atop hardware sales.
- California DTSC alignment:Early compliance with the state's escalating foam chemical restrictions positions suppliers for seamless export to jurisdictions adopting similar standards.
Industry Challenges
- Certified technician scarcity:Spring mechanism recalibration and frame alignment require specialized training that outpaces vocational program output, extending service response times for studio operators.
- Multi-jurisdiction compliance stacking:Manufacturers serving both EU and US markets must maintain parallel testing documentation for CE marking and CPSC requirements, inflating quality assurance overhead.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pilates Equipment and Gears Market |
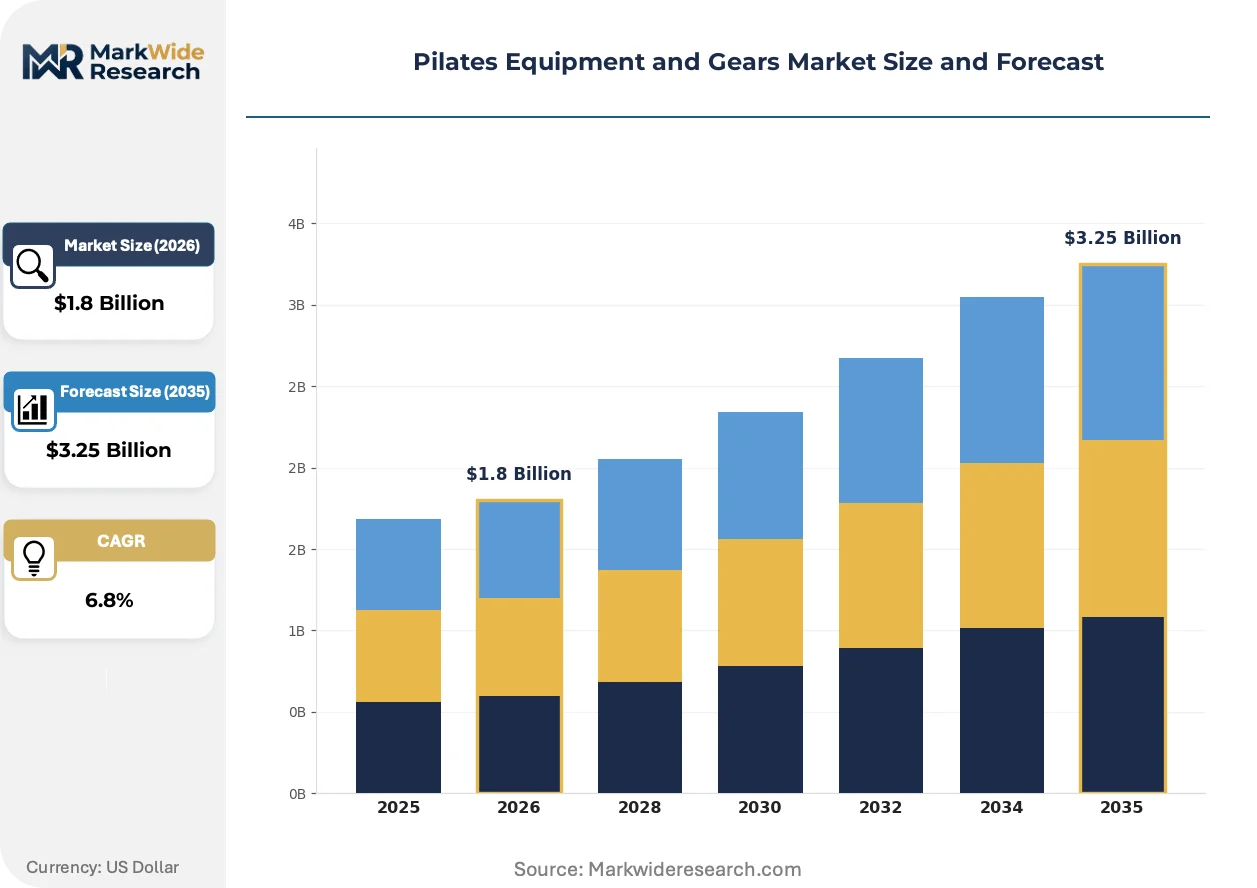
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.25 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Reformers, Mat, Stability Balls, Resistance Bands End User: Fitness Studios, Home Users, Gyms, Physiotherapy Centers Material: Wood, Steel, Foam, Rubber Brand: Liforme, Balanced Body, Stott Pilates, Merrithew |
| Companies Covered | Balanced Body, Inc., Merrithew Corporation, Gratz Industries, LLC, Stamina Products, Inc., Align-Pilates Equipment Ltd., Peak Pilates, Mad Dogg Athletics, Inc., Decathlon S.A., BASI Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pilates Equipment and Gears Market Evolving Landscape
Connected fitness architecture is penetrating resistance training equipment, embedding sensors and software layers that transform mechanical apparatus into data-generating platforms for both users and instructors.
Reformer-mounted force plates and angle sensors are virtualizing the instructor-student relationship by transmitting real-time resistance curves and alignment metrics to remote coaching interfaces. Boutique chains with distributed membership bases are piloting these systems to maintain continuity across locations. The technology is compressing the addressable market for purely mechanical reformers by embedding subscription dependencies into hardware procurement decisions.
REACH chemical restrictions on persistent organic pollutants in polymer cushioning are compelling foam suppliers to accelerate bio-based polyurethane development. Manufacturers sourcing padding components must now validate alternative chemistries against 100,000-cycle durability benchmarks previously met by conventional formulations. German fabricators are responding fastest, leveraging proximity to ECHA technical guidance and domestic testing laboratories to maintain supply continuity.
Studio procurement committees are unbundling equipment purchases from mandatory maintenance contracts, forcing OEMs to compete with independent service networks on parts pricing and response speed. Franchise operators in Texas and Florida are driving this behavior, leveraging multi-location scale to negotiate à la carte warranty terms. The shift is most pronounced among reformer fleets exceeding twenty units, where in-house technician training becomes economically viable.
Pilates Equipment and Gears Market Segmentation
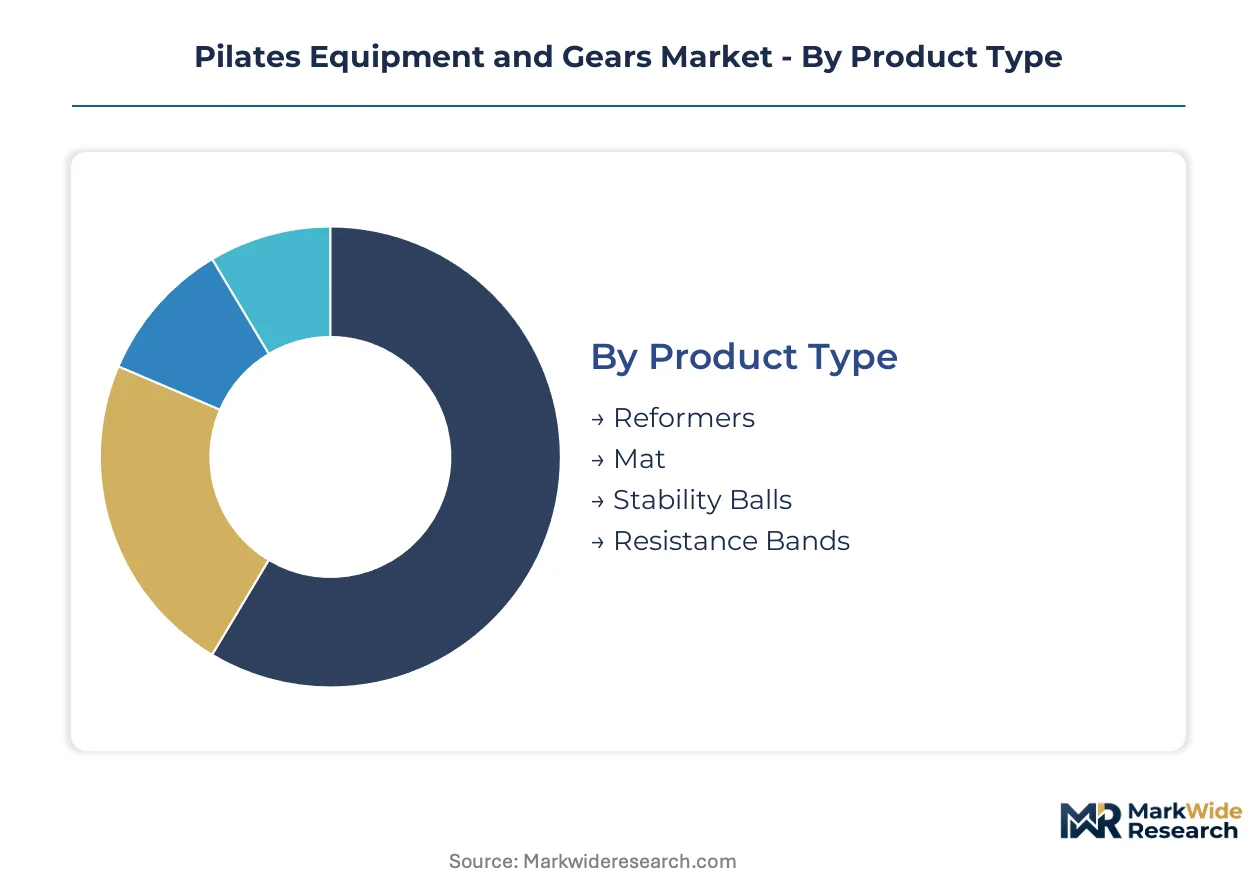
Equipment replacement cycles vary dramatically across Pilates apparatus categories, with high-use studio reformers demanding annual spring recalibration while home resistance bands face minimal service requirements. Understanding these velocity differences shapes inventory planning, warranty pricing, and aftermarket revenue capture for manufacturers and distributors.
Product Type:
Reformers compress capital deployment into extended amortization schedules, whereas resistance bands convert instantly to recurring consumable purchases with negligible maintenance overhead.
- Reformers:Steel-spring resistance systems mounted on wheeled carriages within hardwood or metal frames, engineered for load ratings exceeding commercial studio duty cycles. Demand concentrates in California, New York, and Texas metropolitan studio clusters where franchise operators negotiate fleet pricing and extended warranty terms. The Consumer Product Safety Commission monitors spring mechanism integrity, adding compliance documentation burdens to North American shipments.
- Resistance Bands:Elastic polymer strips or loops providing variable resistance through tensile deformation, requiring minimal storage footprint and zero installation. Home users who adopted these during studio closures continue replenishing inventory through direct-to-consumer channels, while physiotherapy centers integrate bands into post-surgical rehabilitation protocols for portability advantages.
- Mat:Dense polymer foam or natural rubber cushioning surfaces for floor-based Pilates sequences, positioned as entry-level equipment with replacement driven by surface degradation rather than mechanical failure.
- Stability Balls:Inflatable PVC or burst-resistant polymer spheres for core activation and balance training, experiencing elevated replacement frequency due to puncture vulnerability and air retention degradation.
Reformers anchor the volume base while resistance bands gain share at the steepest rate.
End User:
Purchasing authority consolidates differently across customer types, with franchise networks centralizing equipment decisions while home users fragment across direct-to-consumer platforms.
- Fitness Studios:Boutique operators in North America and Western Europe drive premium equipment procurement, leveraging multi-unit scale to extract white-label customization and service contract unbundling from manufacturers.
- Physiotherapy Centers:Clinical rehabilitation facilities in Germany and the United States specify load-rated steel-framed reformers for post-surgical recovery protocols, with procurement governed by institutional purchasing committees rather than individual practitioners.
- Home Users:Residential consumers who sustained Pilates practice after studio closures now upgrade from resistance bands to compact reformer systems, sustaining e-commerce channel momentum.
- Gyms:Multi-purpose fitness facilities allocate floor space to reformer zones alongside traditional strength equipment, with procurement cycles tied to broader facility renovation schedules.
Fitness studios command the highest per-account revenue while physiotherapy centers expand most quickly as clinical integration accelerates.
Material:
Raw material selection determines compliance exposure, with foam padding facing escalating chemical restrictions while steel and wood contend with supply concentration risks.
- Steel:High-tensile carbon or alloy formulations for reformer frames and spring coils, with commercial-grade specifications demanding German or Japanese specialty mill sourcing that creates single-source vulnerability for North American fabricators.
- Wood:North American and European beech and maple hardwoods for premium frame construction, with kiln-drying capacity constraints and lumber futures volatility compressing margins for boutique-positioned manufacturers.
- Foam:Polyurethane or bio-based polymer cushioning for mat surfaces and reformer headrests, with EU REACH restrictions on isocyanates and California DTSC flame retardant limits forcing reformulation timelines.
- Rubber:Natural or synthetic elastomer compounds for mat surfaces and resistance band cores, with durability specifications varying across commercial and residential use cases.
Steel dominates commercial installations while foam faces the steepest regulatory-driven substitution pressure.
Brand:
Brand positioning stratifies across certification ecosystem control, domestic manufacturing footprint, and instructor training program penetration.
- Balanced Body:Domestic U.S. manufacturing infrastructure enabling spare parts fulfillment timeline control and aftermarket service network density.
- Merrithew:Instructor certification programs locking in recurring equipment purchases from affiliated studios through training curriculum standardization.
- Stott Pilates:Rehabilitation-focused methodology attracting physiotherapy center procurement through clinical outcome documentation.
- Liforme:Yoga mat heritage extending into Pilates accessories through sustainability positioning and polymer chemistry differentiation.
Balanced Body and Merrithew anchor studio procurement decisions while Liforme penetrates fastest among sustainability-conscious home users.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German and Japanese specialty mills dominate high-tensile spring steel supply for commercial reformers, while North American and European hardwood suppliers anchor premium frame production. This concentration shapes equipment availability and compliance pathways across major demand centers.
United States
Metropolitan studio clusters in California, New York, and Texas drive reformer fleet procurement through franchise networks. The Consumer Product Safety Commission enforces spring mechanism integrity standards and entrapment hazard protocols for domestically distributed apparatus. Boutique operators in Los Angeles and Manhattan negotiate white-label customization and extended warranty terms from manufacturers.
Germany
The Federal Institute for Occupational Safety and Health influences ergonomic design standards that propagate across European manufacturing specifications. REACH chemical restrictions on isocyanates and flame retardants in foam padding force accelerated bio-based polyurethane development. Fabricators in Bavaria and North Rhine-Westphalia leverage proximity to ECHA technical guidance to maintain supply continuity.
United Kingdom
Clinical rehabilitation facilities in London and Manchester integrate Pilates apparatus into post-surgical recovery protocols, creating institutional demand for load-rated steel-framed units. CE marking requirements under the EU Machinery Directive standardize safety protocols for commercial reformer systems. Boutique fitness expansion in the Southeast concentrates equipment procurement decisions through multi-unit franchise networks.
Japan
Specialty steel mills in Osaka and Nagoya supply high-tensile coil springs for commercial reformer manufacturers worldwide. METI industrial standards influence equipment durability benchmarking across Asia-Pacific distribution channels. Physiotherapy centers in Tokyo and Osaka specify load-rated apparatus for rehabilitation protocols.
Australia
Home fitness permanence sustains direct-to-consumer channel momentum for compact reformer systems and resistance bands. The Therapeutic Goods Administration monitors equipment safety claims for clinical rehabilitation applications. Studio operators in Sydney and Melbourne unbundle equipment purchases from mandatory maintenance contracts, negotiating à la carte warranty terms.
Pilates Equipment and Gears Market Competitive Landscape
Domestic manufacturers and certification-anchored specialists split the market between supply-chain control and instructor ecosystem lock-in. The vendor base concentrates around three strategic archetypes: vertically integrated fabricators with captive parts fulfillment, methodology-driven certifiers converting training relationships into equipment purchases, and mass-market distributors leveraging retail scale for home fitness penetration. Competitive moves center on geographic expansion into underpenetrated studio markets and sensor-embedded hardware development for subscription revenue attachment.
Within the certification-anchored tier, Merrithew Corporation and BASI Systems exemplify methodology-driven positioning that converts instructor training standardization into recurring equipment procurement from affiliated studios. Among domestic U.S. fabricators, Balanced Body, Inc. occupies a position emphasizing manufacturing footprint control over spare parts fulfillment timelines. Gratz Industries, LLC represents heritage-focused craftsmanship positioning in premium frame construction.
| Leading Market Players |
|---|
| Balanced Body, Inc. |
| Merrithew Corporation |
| Gratz Industries, LLC |
| Stamina Products, Inc. |
| Align-Pilates Equipment Ltd. |
| Peak Pilates |
| Mad Dogg Athletics, Inc. |
| Decathlon S.A. |
| BASI Systems |
| Others |
Value Network & Pricing Analysis
Single-source dependency on German and Japanese specialty mills for high-tensile spring steel compresses pricing power for North American fabricators while forcing tiered cost structures across reformer categories. This concentration simultaneously widens premium-to-economy price spreads and locks supply chain configuration into transoceanic sourcing patterns with limited nearshoring alternatives.
Pricing Analysis
CE marking requirements under the EU Machinery Directive dictate the pricing tier structure by imposing compliance documentation burdens that stratify equipment costs across certification levels. Three-tier pricing structure across premium, standard, and economy levels separates studio-grade steel-framed units with extended warranties from entry-level home systems. Cost compression in the mid-tier is intensifying because franchise operators in Texas and Florida leverage fleet scale to unbundle maintenance contracts and negotiate à la carte terms. Boutique fitness studios show the highest price sensitivity due to capital deployment constraints, while physiotherapy centers prioritize load ratings over unit economics.
Supply Chain Analysis
Contract manufacturing capacity for reformer frames concentrates among Bavarian metal fabricators and North American hardwood specialists with captive kiln-drying operations. Geographic supply concentration centers on Germany for precision spring components, Japan for specialty steel alloys, and North American Great Lakes regions for beech and maple hardwoods. Raw material dependencies rest on high-tensile coil steel, polymer cushioning formulations, and certified hardwood stock. Single-source vulnerability in spring steel creates exposure to trade policy shifts. Distribution runs through OEM direct sales for studio fleets, supplemented by e-commerce platforms for home user segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Boutique fitness franchise consolidation across California, New York, and Texas has shifted procurement leverage toward multi-unit operators, fragmenting manufacturer pricing power and unbundling traditional equipment-service bundles.
For Market Incumbents: Entrench certification ecosystem control by deepening instructor training program penetration and accelerating sensor-embedded reformer development to embed subscription dependencies. Lock in spare parts fulfillment timelines through domestic manufacturing footprint expansion. Defend against independent service network encroachment by offering competitive component pricing for fleets exceeding twenty units. For New Entrants and Emerging Players: Metropolitan India studio underpenetration offers first-mover positioning for equipment distributors seeking white-space expansion beyond saturated North American and Western European markets. Target Mumbai and Bangalore reformer density gaps relative to yoga mat saturation. Enter through physiotherapy center channels with load-rated steel-framed units, then bridge to boutique studio segments. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors certification-anchored specialists with recurring revenue streams from affiliated studio networks. Long-term viability hinges on digital-physical convergence capabilities and aftermarket service network density. Monitor sensor-embedded equipment penetration rates as the inflection indicator for subscription revenue attachment maturity.| Strategic Initiative | Industry Significance |
|---|---|
| Sensor-Embedded Hardware Development | Transforms mechanical reformers into data platforms generating recurring physiotherapist dashboard subscriptions. |
| Certification Program Expansion | Locks in recurring equipment purchases from affiliated studios through curriculum standardization and instructor loyalty. |
| Domestic Manufacturing Scale-Up | Compresses spare parts fulfillment timelines and reduces exposure to German and Japanese spring steel import volatility. |
| India Market Entry Partnership | Captures first-mover positioning in Mumbai and Bangalore studio markets with low reformer density relative to yoga saturation. |
| Bio-Based Foam Reformulation | Anticipates REACH and California DTSC chemical restrictions while maintaining 100,000-cycle durability benchmarks. |
Research Methodology
Desk research of trade customs records, EU Machinery Directive technical guidance, and CPSC enforcement databases preceded structured interviews with studio procurement directors, OEM aftermarket service heads, and physiotherapy center purchasing managers. Primary fieldwork with equipment manufacturers in Germany and the United States was cross-validated against secondary sources including ECHA substance restriction updates and lumber futures market data. Bottom-up equipment shipment analysis was triangulated with top-down market sizing across reformer, resistance band, and accessory categories.
Assumptions regarding regulatory compliance timelines, hardwood supply recovery, and franchise network expansion velocity were held fixed across baseline scenarios while sensor adoption rates and India market penetration were stress-tested. The analytical framework modeled equipment type, end-user segment, material composition, and regional regulatory cluster throughout the projection horizon. CAGRs were derived from installed base growth and replacement cycle velocity analysis. Forecast inputs included spring steel import dependency ratios and REACH substance restriction implementation pacing.
Practitioners should monitor EU Machinery Directive amendment proposals, California DTSC foam chemical escalation schedules, and India studio licensing policy developments for early signals of forecast revision triggers. Forecasts reflect assumptions about trade policy continuity and hardwood kiln-drying capacity expansion. Quarterly review of spring steel import volumes, REACH substance restriction enforcement patterns, and franchise network equipment procurement committee formation rates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fitness Equipment
Military Fitness Training Equipment Market
Fitness Equipment
Treadmill Ergometer Market
Fitness Equipment
Asia-Pacific Fitness Equipment Market
Fitness Equipment
Ergometer Market
Fitness Equipment
Fitness Equipment Market
Fitness Equipment
Lung Exercise Machine Market
Fitness Equipment
Elliptical Market
Fitness Equipment
Recumbent Stationary Bikes Market
Fitness Equipment
China Outdoor Fitness Equipment Market
Fitness Equipment
Weight Training Market
Fitness Equipment
China Fitness Rings Market
Fitness Equipment
North America Home Fitness Equipment Market
Fitness Equipment
Exercise Band Market
Fitness Equipment
North America Fitness Rings Market
Fitness Equipment
Belt Trainers Market
Fitness Equipment
GCC Fitness Ring Market