
 Yoga and Pilates Mats Market | 2026-2036
Yoga and Pilates Mats Market Size, Share, and Industry Trends Forecast 2026-2036
Yoga and Pilates Mats Market Analytics
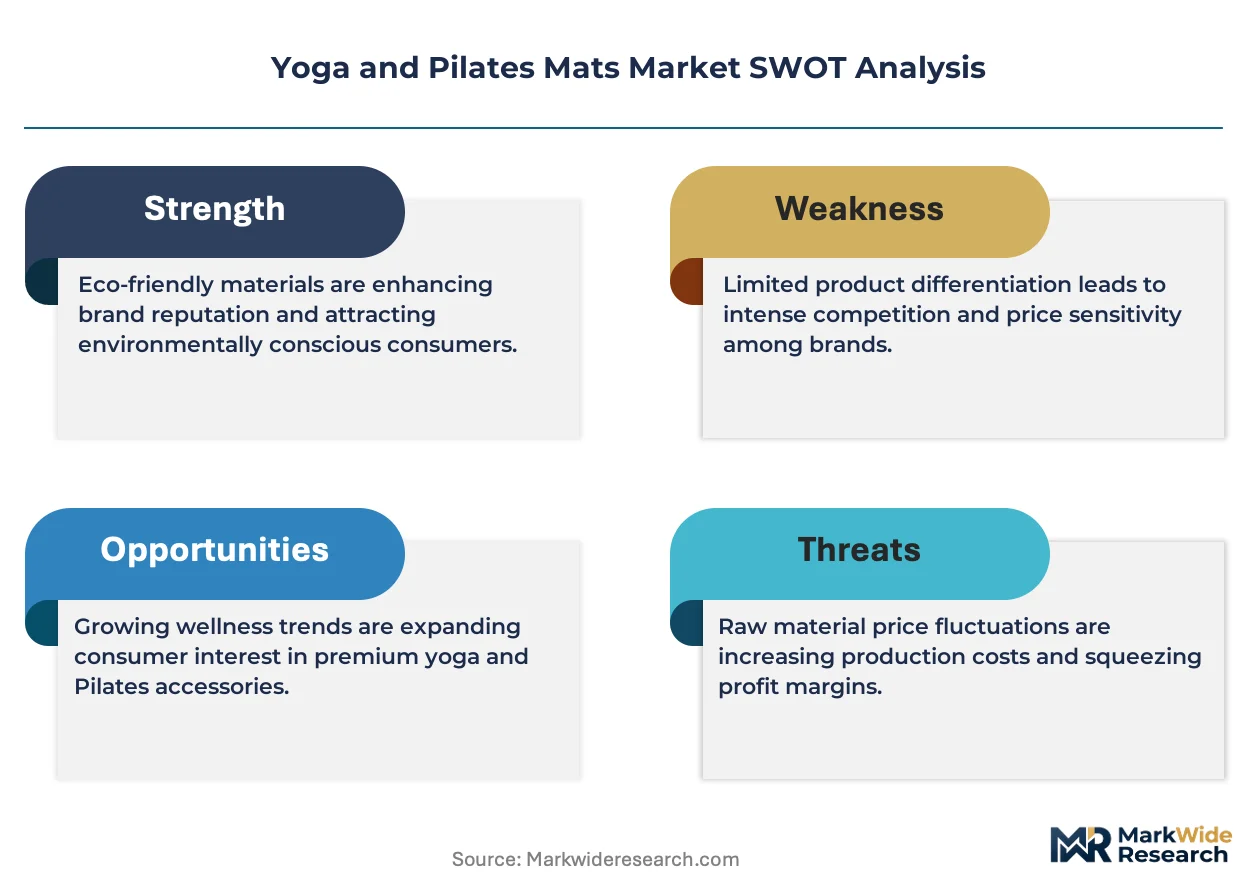
Modular bundling of mats with blocks, straps, and digital class subscriptions is decoupling hardware from standalone retail. Manduka LLC leverages its closed-cell manufacturing to sustain premium positioning in studio channels. Jade Yoga anchors its competitive stance through domestic U.S. production and tree-planting commitments. Liforme Ltd. differentiates via patented alignment systems that command higher price points in instructor-led settings.
Yoga and Pilates mats are engineered exercise surfaces, typically 4–6 mm thick, constructed from natural rubber, thermoplastic elastomer (TPE), or polyvinyl chloride (PVC) with textured or smooth finishes designed to prevent slippage during bodyweight movement sequences. Their primary commercial purpose is to provide cushioning, grip, and hygienic barriers between practitioners and floor surfaces in home, studio, and clinical rehabilitation environments. Natural rubber and TPE material categories capture expanding margin pools as studios phase out PVC under sustainability mandates. Studio use and rehabilitation use cases outpace personal use in replacement frequency, while travel-oriented thin profiles occupy a niche premium tier.
REACH in Europe restricts phthalate content in PVC-based mats, compelling suppliers to reformulate or shift substrate portfolios toward TPE and natural rubber alternatives. California's Proposition 65 disclosure requirements and the U.S. Consumer Product Safety Commission's lead-content standards shape import compliance costs for Asian manufacturers serving North American distributors. Stakeholders must monitor evolving chemical bans and certification schemes to align procurement specifications with jurisdiction-specific entry barriers.
Market Dynamics
Boutique fitness chains now consolidate mat procurement through direct sourcing agreements, compressing distributor margins while elevating material specifications for closed-cell construction and antimicrobial treatments.
Growth Catalysts
- REACH phthalate restrictions:ECHA mandates in Europe accelerate substrate migration from PVC toward TPE and natural rubber, opening margin pools for compliant suppliers.
- Rehabilitation clinics:Physical therapy practices in Germany and Australia standardize mat-based movement protocols, driving institutional replacement cycles above home-use frequencies.
- Closed-cell manufacturing:Advanced thermal bonding processes eliminate moisture absorption in studio environments, extending product lifespans and justifying premium positioning.
Market Restraints
- Natural rubber price volatility:Hevea brasiliensis supply concentrates in Southeast Asian plantations, exposing converters to latex cost swings and currency fluctuation.
- California Proposition 65:State-level chemical disclosure rules impose labeling burdens on PVC-based imports, elevating compliance costs for Asian manufacturers serving U.S. distributors.
- TPE formulation limits:Thermoplastic elastomer blends struggle to match natural rubber's compression set recovery in high-temperature studio storage conditions.
Strategic Opportunities
- Subscription bundling models:Digital fitness platforms in the United States now package hardware with content access, creating captive demand for co-branded mat lines.
- Alignment system patents:Proprietary grip patterns and visual positioning guides command instructor loyalty in premium studio channels.
- Domestic U.S. production:Tree-planting commitments and localized manufacturing resonate with sustainability-focused consumer segments and reduce tariff exposure.
Industry Challenges
- Biodegradability certification timelines:ASTM and ISO standards for end-of-life testing remain inconsistent across jurisdictions, delaying marketing claims and export approvals.
- Closed-cell bonding expertise:Thermal lamination technicians capable of maintaining porosity specifications command wage premiums in tight labor markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Yoga and Pilates Mats Market |
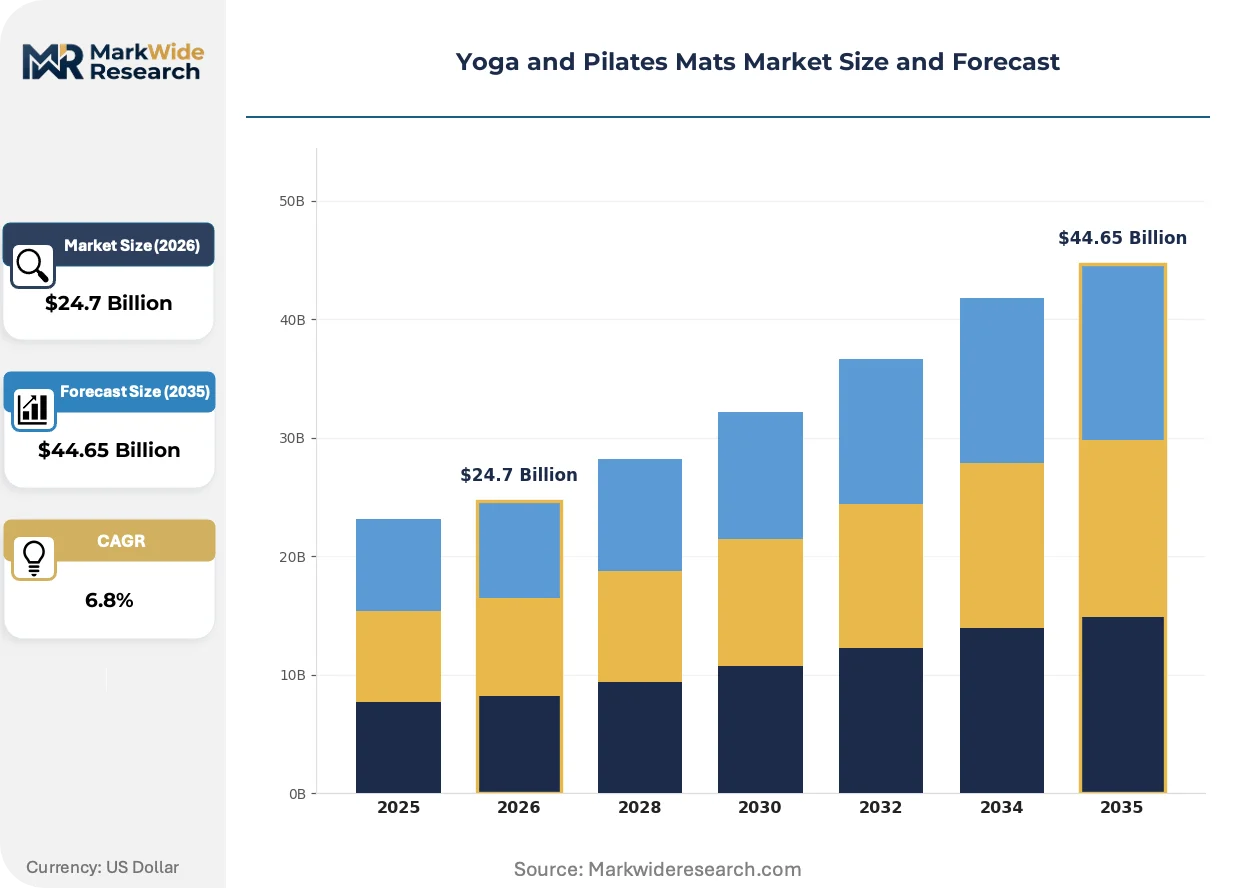
| Market Size in 2026 | $24.7 Billion |
| Market Size in 2035 | $44.65 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material: Natural Rubber, PVC, TPE, Cotton Thickness: 6 mm, 8 mm, 10 mm, 12 mm Use Case: Personal Use, Studio Use, Travel, Rehabilitation Surface Texture: Smooth, Textured, Eco-friendly, Standard |
| Companies Covered | Lululemon Athletica Inc., Manduka LLC, Gaiam, Jade Yoga, Adidas AG, Hugger Mugger Yoga Products, Liforme Ltd., Barefoot Yoga Co., Alo Yoga, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Yoga and Pilates Mats Market Evolving Landscape
Material science breakthroughs and regulatory chemistry bans are compressing legacy substrate dominance while digital-physical bundling rewires distribution economics.
Closed-cell thermal bonding technology is electrifying competitive positioning in studio-grade mat manufacturing. This process fuses polymer layers without adhesive residues, creating moisture-impermeable barriers that survive commercial laundering protocols. Premium boutique chains in the United States and Germany now specify bonded construction in procurement tenders, compressing demand for open-cell alternatives that degrade under sanitization heat cycles.
REACH Annex XVII phthalate restrictions are forcing substrate portfolio reconfiguration across European supply chains. ECHA enforcement actions against DEHP and DBP content in soft PVC articles have triggered converter migration toward TPE and FSC-certified natural rubber alternatives. German distributors now require full material disclosure documentation, shifting competitive advantage toward suppliers with vertically integrated polymer compounding capabilities.
Studio procurement departments now consolidate vendor relationships around integrated equipment bundles. Boutique fitness operators in Australia and California negotiate single-source agreements covering mats, blocks, straps, and sanitation protocols, displacing fragmented purchasing through sporting goods retailers. This concentration elevates supplier qualification barriers while compressing price transparency for smaller independent studios lacking volume leverage.
Yoga and Pilates Mats Market Segmentation
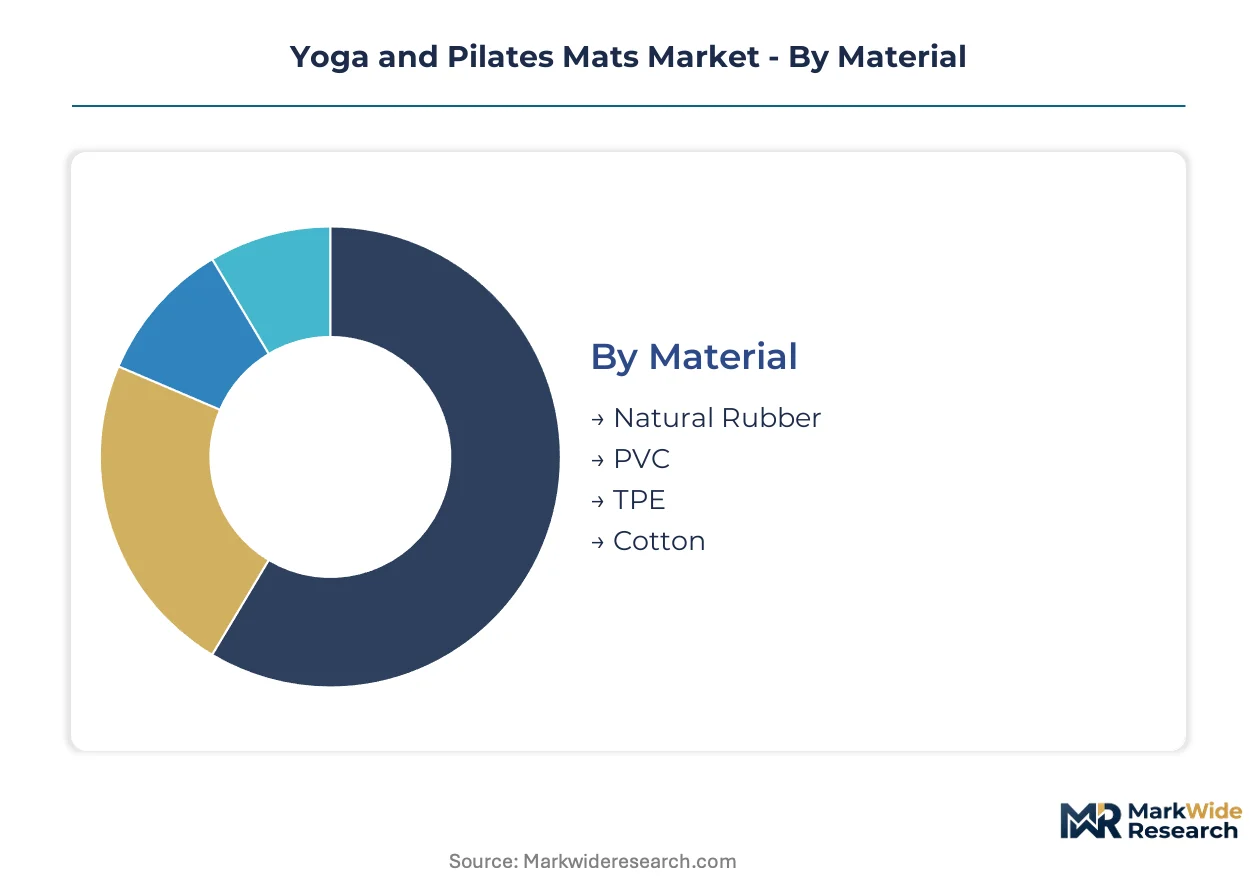
Material chemistry and thickness specifications dictate procurement economics across studio, home, and clinical channels. Understanding how substrate portfolios and dimensional profiles map to end-use durability requirements enables suppliers to align production capacity with replacement frequency patterns.
Material:
Natural rubber compounding demands the heaviest capital outlay for plantation sourcing partnerships and latex processing infrastructure, while TPE extrusion lines require moderate tooling investment with faster changeover flexibility.
- Natural Rubber:Harvested from Hevea brasiliensis plantations concentrated in Thailand and Indonesia, this substrate delivers superior compression set recovery and biodegradability credentials that command premium positioning in German rehabilitation clinics and California boutique studios. ECHA REACH compliance documentation and FSC chain-of-custody certification add fixed compliance costs that filter out smaller compounders.
- PVC:Polyvinyl chloride remains the lowest-cost production pathway through calendering and extrusion processes, though California Proposition 65 disclosure burdens and European phthalate restrictions are compressing addressable market share in regulated jurisdictions. Asian converters retain cost advantage in price-sensitive personal use segments.
- TPE:Thermoplastic elastomer blends offer mid-range capital requirements with recyclable processing advantages, though high-temperature studio storage conditions expose compression set limitations that shorten replacement cycles versus natural rubber alternatives.
- Cotton:Woven organic cotton mats require textile finishing equipment and dyeing compliance infrastructure, appealing to sustainability-focused personal use buyers in Australia and the United States with shorter durability horizons than polymer substrates.
Most installed capacity flows through PVC. Expansion is steepest in natural rubber.
Thickness:
Dimensional profiles correlate directly with cushioning performance specifications and transportation logistics costs, with thicker variants demanding expanded foam molding capital and elevated shipping cube economics.
- 6 mm:The standard studio specification balances ground feedback with joint protection, dominating procurement volumes for high-frequency commercial use in United States boutique chains where closed-cell thermal bonding extends sanitization durability.
- 8 mm:Rehabilitation clinics in Germany and physical therapy practices in Australia specify this profile for patient populations requiring enhanced cushioning during balance-challenged movement protocols, driving institutional replacement cycles above personal use frequencies.
- 10 mm:Extra-thick construction targets senior practitioners and restorative yoga modalities with elevated foam expansion equipment requirements and compressed roll-pack efficiency for retail distribution.
- 12 mm:Maximum cushioning profiles occupy niche positioning for therapeutic applications and specialty demographics, with limited volume scale due to storage footprint constraints in urban studio environments.
Studio procurement concentrates in 6 mm. Rehabilitation demand is climbing fastest in 8 mm.
Use Case:
End-use segmentation separates replacement frequency economics, with commercial environments demanding higher material specifications and accelerated refresh cycles versus occasional personal use patterns.
- Personal Use:Home practitioners prioritize price accessibility and storage convenience over commercial-grade durability, with purchase decisions increasingly bundled through digital fitness subscription platforms in the United States.
- Studio Use:Boutique fitness operators in California and Germany negotiate direct sourcing agreements specifying closed-cell construction and antimicrobial treatments, consolidating vendor relationships around integrated equipment bundles.
- Travel:Thin-profile foldable mats command premium positioning for mobile practitioners, with material efficiency requirements favoring TPE and natural rubber substrates over PVC in sustainability-aligned consumer segments.
- Rehabilitation:Physical therapy practices standardize mat-based movement protocols, with institutional procurement in Australia and Germany driving above-average replacement frequency and material certification documentation requirements.
Studio use commands the highest per-unit specification. Rehabilitation is expanding most quickly as clinical movement protocols proliferate.
Surface Texture:
Finish engineering determines grip performance across humidity conditions and movement modalities, with specialized texture patents creating differentiation moats in instructor-led premium channels.
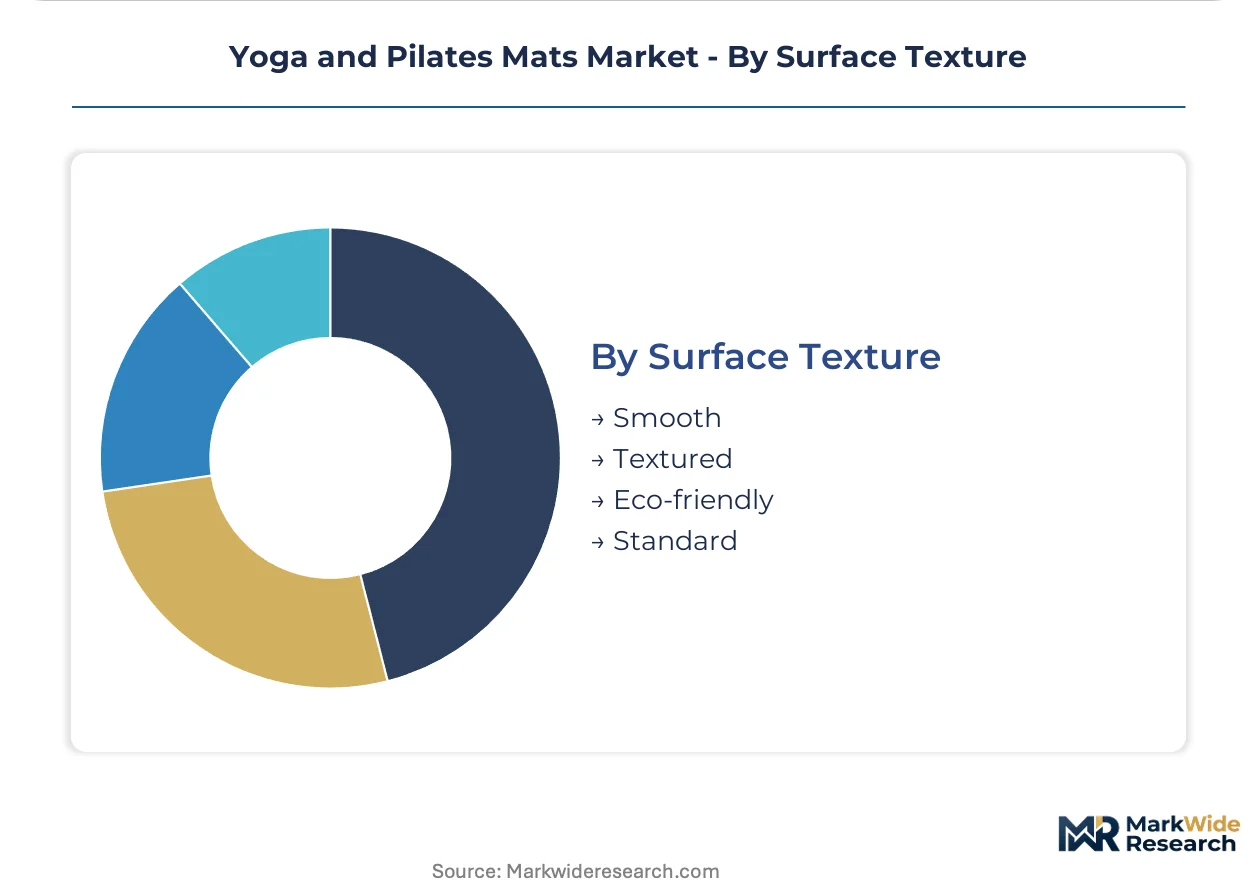
- Textured:Raised surface patterns deliver enhanced traction for dynamic vinyasa sequences and heated studio environments, with proprietary grip geometries commanding instructor loyalty and price premiums in competitive United States markets.
- Eco-friendly:Unbleached natural finishes and plant-based surface treatments target sustainability-certified studios in Germany and Australia, with biodegradability marketing claims pending inconsistent ASTM and ISO end-of-life testing standardization.
- Smooth:Uniform surface finishes suit restorative and yin yoga modalities with lower grip demands, offering manufacturing simplicity that supports economy pricing tiers for entry-level personal use segments.
- Standard:Baseline texture specifications balance cost efficiency with functional adequacy, dominating mass-market retail distribution through sporting goods channels with limited differentiation leverage.
Textured surfaces dominate studio specification. Eco-friendly finishes are gaining share fastest as sustainability mandates tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Yoga and Pilates mat manufacturing traces its commercial origins to California's 1970s wellness culture, where natural rubber processing for exercise surfaces first achieved industrial scale before expanding to Germany's rehabilitation equipment sector and Australia's boutique fitness market.
United States
Boutique fitness chains in California and New York drive procurement volumes through direct sourcing agreements specifying closed-cell construction. California's Proposition 65 imposes chemical disclosure burdens on PVC-based imports, elevating compliance costs for Asian manufacturers. Los Angeles anchors domestic production capabilities for premium studio-grade mats with thermal bonding expertise.
Germany
Physical therapy practices standardize mat-based movement protocols, driving institutional replacement cycles above home-use frequencies. ECHA REACH Annex XVII phthalate restrictions accelerate substrate migration from PVC toward TPE and natural rubber alternatives. Bavaria hosts vertically integrated compounders with FSC chain-of-custody certification infrastructure.
Australia
Premium studio chains and home fitness subscription services expand equipment refresh cycles across Sydney and Melbourne. The country's national chemical regulator maintains strict import standards for synthetic substrates used in clinical rehabilitation settings. Queensland's natural rubber processing facilities supply domestic converters with plantation-sourced latex.
United Kingdom
Sustainability-certified studios in London prioritize eco-friendly surface finishes and biodegradability marketing claims. The UK's product safety standards align with EU REACH frameworks post-Brexit, maintaining phthalate restrictions on soft PVC articles. Manchester's textile finishing infrastructure supports woven organic cotton mat production for personal use segments.
Japan
Tokyo's aging demographic drives demand for extra-thick therapeutic profiles in senior-focused movement modalities. METI oversees industrial standards for polymer substrates in consumer goods, influencing import specifications for TPE and natural rubber alternatives. Osaka's precision manufacturing cluster specializes in alignment system components for instructor-led premium channels.
Yoga and Pilates Mats Market Competitive Landscape
Premium-margin players sit above commodity-margin players across material certification and closed-cell manufacturing dimensions. The vendor base spans vertically integrated natural rubber processors, TPE compounders with recyclable processing advantages, and PVC converters serving price-sensitive personal use segments. Three archetypes dominate: plantation-integrated suppliers with FSC credentials, thermal bonding specialists serving studio procurement, and digital-physical bundlers packaging hardware with subscription content. Consolidation pressures concentrate around direct sourcing agreements with boutique chains, while capacity expansion focuses on REACH-compliant substrate portfolios.
Within the premium-tier vector, Manduka LLC exemplifies closed-cell manufacturing specialists, Liforme Ltd. anchors proprietary alignment system positioning, and Jade Yoga represents domestic U.S. production archetypes with sustainability commitments. These entities occupy positions across material chemistry differentiation, geographic manufacturing strategy, and instructor-channel loyalty building. Alo Yoga and Lululemon Athletica Inc. sit within apparel-origin diversifiers extending brand equity into equipment categories. Adidas AG exemplifies sportswear conglomerates leveraging distribution scale across mass-market retail channels. Gaiam, Hugger Mugger Yoga Products, and Barefoot Yoga Co. represent established category participants with heritage positioning in specialty yoga retail.
| Leading Market Players |
|---|
| Lululemon Athletica Inc. |
| Manduka LLC |
| Gaiam |
| Jade Yoga |
| Adidas AG |
| Hugger Mugger Yoga Products |
| Liforme Ltd. |
| Barefoot Yoga Co. |
| Alo Yoga |
| Others |
Value Network & Pricing Analysis
Boutique fitness chains in California and Germany now consolidate procurement through direct sourcing agreements, compressing distributor margins while elevating closed-cell construction specifications that stratify pricing across certification tiers.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates FSC-certified natural rubber mats from TPE alternatives and commodity PVC imports. Price differentiation hinges on REACH compliance documentation and closed-cell thermal bonding certification. Cost compression in the PVC tier is intensifying because California Proposition 65 disclosure burdens elevate compliance costs for Asian manufacturers. Home practitioners in the personal use segment exhibit highest price sensitivity, while German rehabilitation clinics accept premium positioning for institutional-grade durability specifications.
Supply Chain Analysis
Natural rubber latex supply rests on Hevea brasiliensis plantations concentrated in Thailand, Indonesia, and Vietnam, with Queensland processing facilities serving Australian domestic converters. TPE compounding draws from petrochemical feedstocks anchored in South Korean and Chinese specialty polymer operations. Single-source vulnerability concentrates in Southeast Asian latex harvesting, exposing converters to currency fluctuation and climate disruption. Distribution runs through sporting goods retailers for personal use, direct sourcing agreements for studio chains, and medical equipment distributors for rehabilitation channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where ECHA REACH Annex XVII phthalate restrictions accelerate substrate migration and open margin pools for compliant suppliers.
For Market Incumbents: Anchor studio channel loyalty through proprietary alignment system patents and closed-cell thermal bonding expertise that creates instructor switching costs. Deepen backward integration into FSC-certified plantation partnerships to secure latex supply against Hevea brasiliensis price volatility. Defend against TPE formulation advances by investing in biodegradable certification documentation that satisfies German distributor material disclosure requirements. For New Entrants and Emerging Players: Capture rehabilitation clinic procurement in Australia and Germany where institutional replacement cycles exceed home-use frequencies and certification barriers filter out commodity competitors. Target travel-oriented thin-profile segments where sustainability-aligned consumers favor natural rubber and TPE over PVC. Enter through digital fitness subscription bundling partnerships that package co-branded hardware with content access. For Investors and Strategic Acquirers: Boutique fitness conglomerates are the most active acquirer in this space, seeking captive equipment supply for franchise expansion. Long-term viability centers on regulatory compliance capabilities rather than commodity scale, favoring targets with vertically integrated polymer compounding and REACH documentation infrastructure. Watch ECHA enforcement action intensity as the inflection indicator for substrate portfolio reconfiguration velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Closed-Cell Manufacturing Scale-Up | Thermal bonding capacity expansion captures studio procurement consolidation in California and Germany. |
| Backward Integration into Plantation Supply | FSC-certified Hevea brasiliensis partnerships reduce latex cost volatility exposure for natural rubber compounders. |
| REACH-Compliant TPE Formulation Investment | European phthalate restrictions displace PVC and open margin pools for compliant substrate suppliers. |
| Digital-Physical Subscription Bundling | Hardware-content packaging creates captive demand through United States fitness platform partnerships. |
| Rehabilitation Channel Certification | Clinical movement protocol standardization in Germany and Australia drives above-average replacement frequency. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with studio procurement directors, rehabilitation clinic equipment managers, TPE compounding engineers, and natural rubber plantation sourcing leads with secondary validation through ECHA enforcement databases, customs trade records, and boutique fitness chain procurement disclosures. Bottom-up mat shipment estimates triangulated against top-down fitness equipment market sizing.
Historical reference periods anchored volume and value projections across the analysis window, with segmentation modeling across material chemistry, thickness specification, use case intensity, and surface texture finish. CAGRs derived from replacement frequency differentials between studio, rehabilitation, and personal use channels, incorporating natural rubber price elasticity and REACH compliance cost pass-through assumptions.
Regulatory enforcement intensity, latex supply disruption events, and TPE formulation breakthroughs are the dominant revision risks to modeled outcomes. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fitness Equipment
Gymnastics Equipment Market
Fitness Equipment
Gymnastic Springboard Market
Fitness Equipment
Fitness Rings Market
Fitness Equipment
Latin America Fitness Ring Market
Fitness Equipment
Belt Trainers Market
Fitness Equipment
Global Jumping Rope Market
Fitness Equipment
Elliptical Trainers Market
Fitness Equipment
China Fitness Rings Market
Fitness Equipment
Asia-Pacific Fitness Equipment Market
Fitness Equipment
North America Exercise Bike Market
Fitness Equipment
Weight Training Market
Fitness Equipment
Europe Home Fitness Equipment Market
Fitness Equipment
South Africa Gym Accessories Market
Fitness Equipment
China Outdoor Fitness Equipment Market
Fitness Equipment
Yoga Accessories Market
Fitness Equipment
Pilates Equipment and Gears Market