
 Recumbent Stationary Bikes Market | 2026-2036
Recumbent Stationary Bikes Market Size, Share, and Industry Trends Forecast 2026-2036
Recumbent Stationary Bikes Market Analytics
Asset-light leasing models for commercial fitness equipment is narrowing the capital barrier for mid-sized gym chains entering the recumbent bike category. NordicTrack leverages its direct-to-consumer platform and streaming content ecosystem to sustain recurring revenue beyond hardware sales. Schwinn anchors its position through deep retail partnerships with mass-market sporting goods channels. Sole Fitness differentiates through extended warranty programs and domestic assembly operations that compete on service reliability rather than price alone.
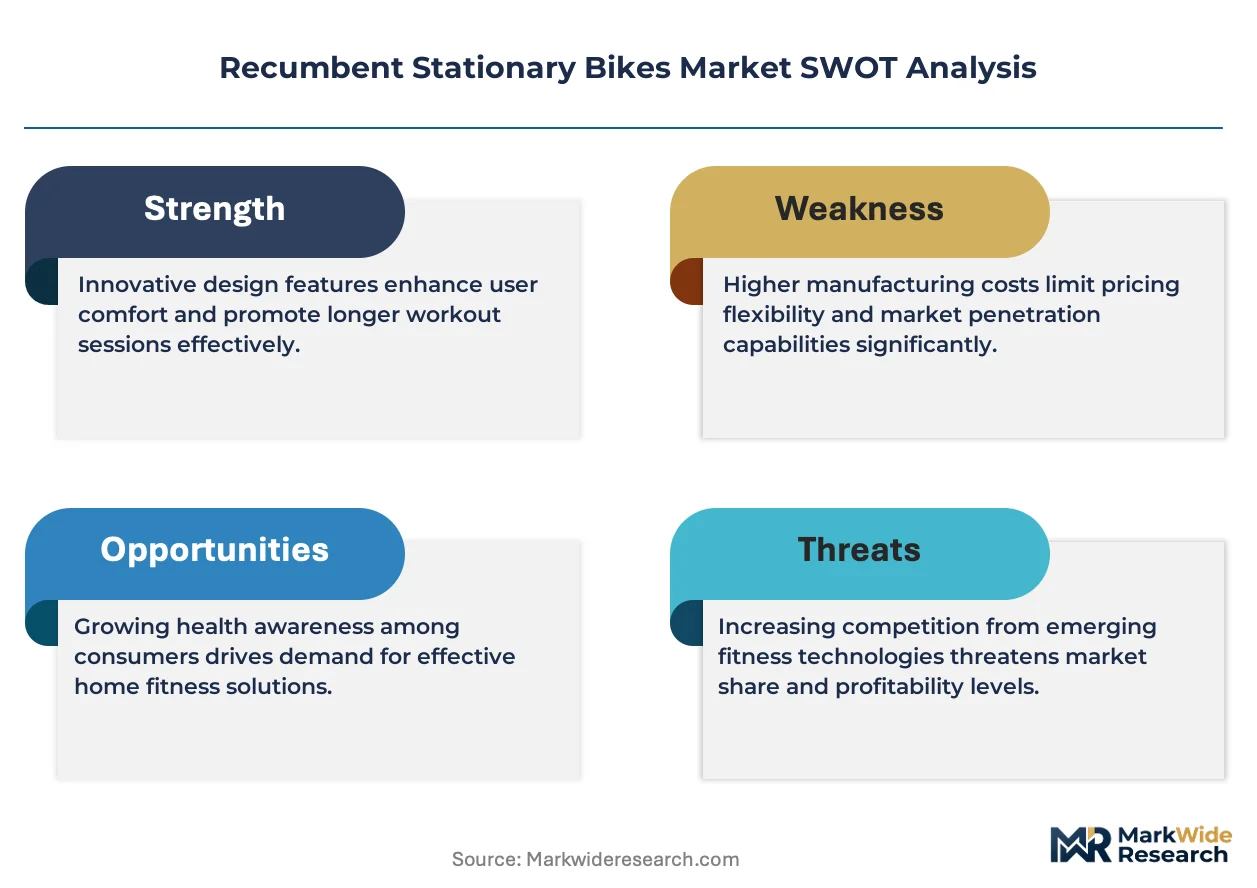
A recumbent stationary bike positions the rider in a reclined seated posture with a backrest support, distributing body weight across a larger surface area and reducing lumbar strain during extended exercise sessions. The design typically incorporates a step-through frame, weighted flywheel between 15 and 40 pounds, and adjustable magnetic resistance systems calibrated for low-impact cardiovascular conditioning. Motorized and smart bike configurations within the technology segment command the strongest margin pools as Bluetooth-enabled units with biometric tracking integration capture premium pricing from health clubs and rehabilitation centers. Foldable and compact variants represent the fastest-growing product type as residential users with space constraints prioritize storage efficiency over commercial-grade durability.
The FDA regulates medical fitness devices marketed for therapeutic rehabilitation claims, while the Consumer Product Safety Commission sets mechanical safety standards for stationary exercise equipment sold in the United States. ASTM International publishes voluntary consensus standards for stationary bicycle stability and structural integrity that manufacturers reference for liability risk management. Stakeholders must monitor how evolving digital health regulations from the FCC and emerging state-level biometric data privacy laws reshape software feature requirements and data governance obligations for connected fitness platforms.
Market Dynamics
Rehabilitation centers and cardiac care facilities are consolidating procurement around connected recumbent bikes with biometric tracking, compressing vendor margins while elevating software integration requirements above hardware durability as the primary selection criterion.
Growth Catalysts
- Medicare reimbursement expansion:The Centers for Medicare and Medicaid Services now covers cardiac rehabilitation equipment for qualifying outpatient programs, institutionalizing recumbent bikes as standard post-surgical recovery infrastructure.
- Magnetic resistance calibration:Precision-engineered electromagnetic resistance systems enable smoother power curves and quieter operation, expanding residential adoption among noise-sensitive apartment dwellers.
- Japan's super-aging society:Municipal fitness subsidies for seniors in prefectures like Aichi and Fukuoka prioritize low-impact cardiovascular equipment, creating concentrated public procurement demand.
Market Restraints
- Steel and rare-earth magnet volatility:Flywheel assembly costs fluctuate with neodymium pricing and cold-rolled steel tariffs, squeezing margins on mid-tier magnetic resistance units.
- Taiwanese electronics concentration:Bluetooth module and sensor PCB sourcing clusters heavily in Hsinchu Science Park, exposing supply chains to single-geography disruption risk.
- Stationary bike ceiling effect:Recumbent designs face inherent biomechanical limits on maximum resistance output, constraining appeal to advanced athletes seeking high-intensity interval training.
Strategic Opportunities
- Brazil's private health club expansion:Mid-tier gym chains in São Paulo and Rio de Janeiro are leasing equipment rather than purchasing, opening subscription-based revenue models for connected bike vendors.
- Remote patient monitoring convergence:Integration of recumbent bike telemetry with telehealth platforms enables real-time cardiac rehabilitation oversight, reimbursable under evolving CPT codes.
- Direct-to-consumer streaming bundles:Hardware-plus-content subscriptions bypass traditional sporting goods retail, capturing lifetime value through recurring membership fees rather than one-time equipment sales.
Industry Challenges
- Firmware validation timelines:FDA 510(k) clearance for devices marketed with therapeutic claims requires extensive clinical documentation, extending product launch cycles by 12-18 months.
- Biometric data governance:State-level privacy laws in California and emerging regulations in the European Union impose complex consent and deletion requirements on heart rate and performance data storage.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Recumbent Stationary Bikes Market |
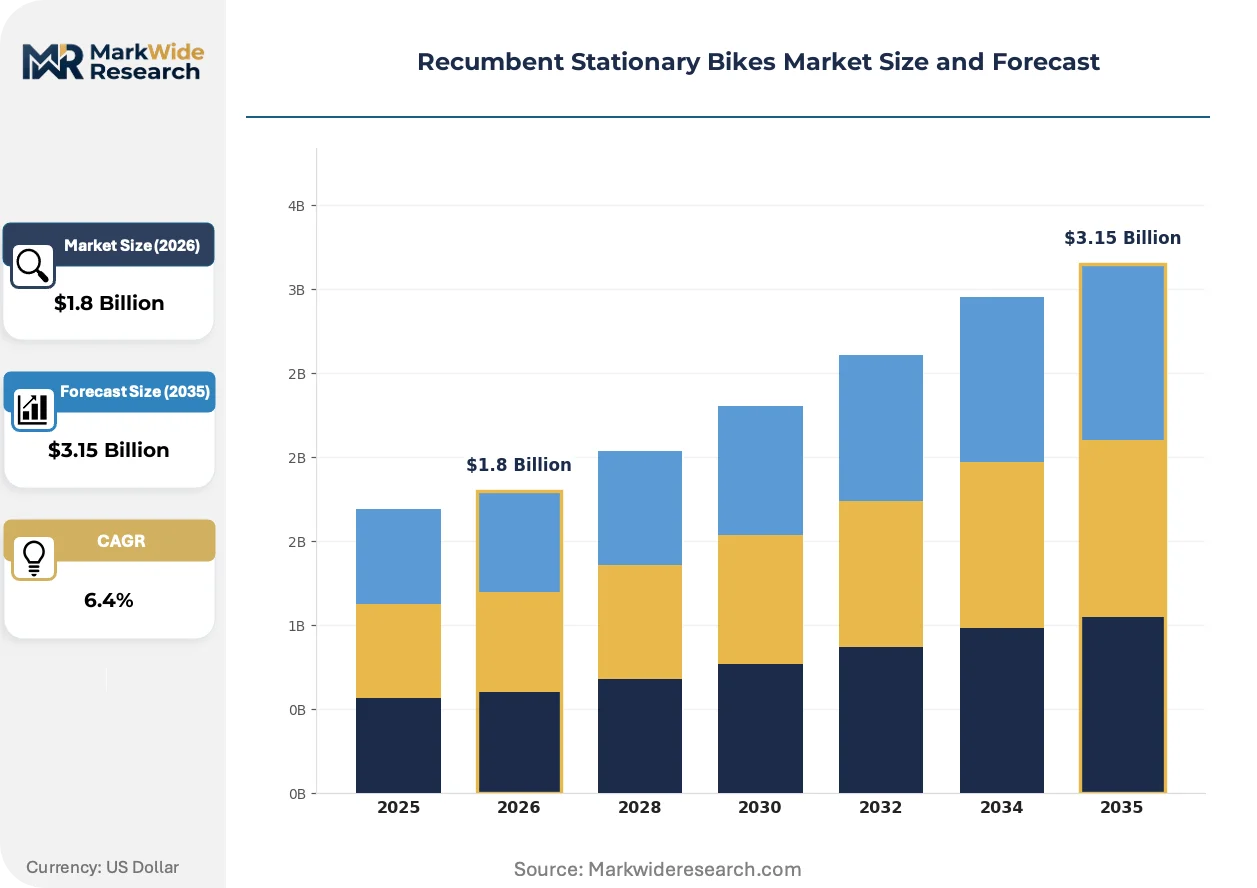
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Motorized, Manual, Foldable, Compact End User: Residential Users, Gyms, Rehabilitation Centers, Health Clubs Price Tier: Economy, Mid-Range, Premium, Luxury Technology: Smart Bikes, Biometric Tracking, Manual Adjustments, Bluetooth Enabled |
| Companies Covered | Schwinn, NordicTrack, Diamondback Fitness, Sunny Health & Fitness, Sole Fitness, Matrix Fitness, Technogym, Marcy, Star Trac, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Recumbent Stationary Bikes Market Evolving Landscape
Product development priorities are pivoting from mechanical durability to software-enabled personalization, with biometric feedback loops and adaptive resistance algorithms now commanding premium positioning over traditional build quality metrics.
Electromagnetic resistance systems with real-time power measurement are digitizing workout data streams for remote coaching and clinical oversight. Rehabilitation centers in Germany and the United States are adopting these configurations fastest, replacing friction-based flywheels within three-year capital refresh cycles. The technology is digitizing patient-provider relationships by enabling asynchronous monitoring and automated protocol adjustments without on-site supervision.
The European Union's Medical Device Regulation now classifies stationary bikes marketed for cardiac rehabilitation as Class IIa devices, mandating notified body involvement and post-market surveillance. Manufacturers targeting European healthcare procurement must maintain technical documentation and vigilance systems comparable to implantable device standards. German rehabilitation clinic chains are responding by consolidating vendor lists to partners with established MDR compliance infrastructure.
Asset-light leasing is displacing capital purchase for commercial fitness equipment, compressing upfront commitments while extending vendor cash conversion cycles. Health clubs in Texas and Florida are piloting usage-based rental models where monthly fees scale with member check-in frequency. This behavioral shift is most visible in the United States, where private equity-backed gym rollups prioritize balance sheet flexibility over long-term equipment ownership.
Recumbent Stationary Bikes Market Segmentation
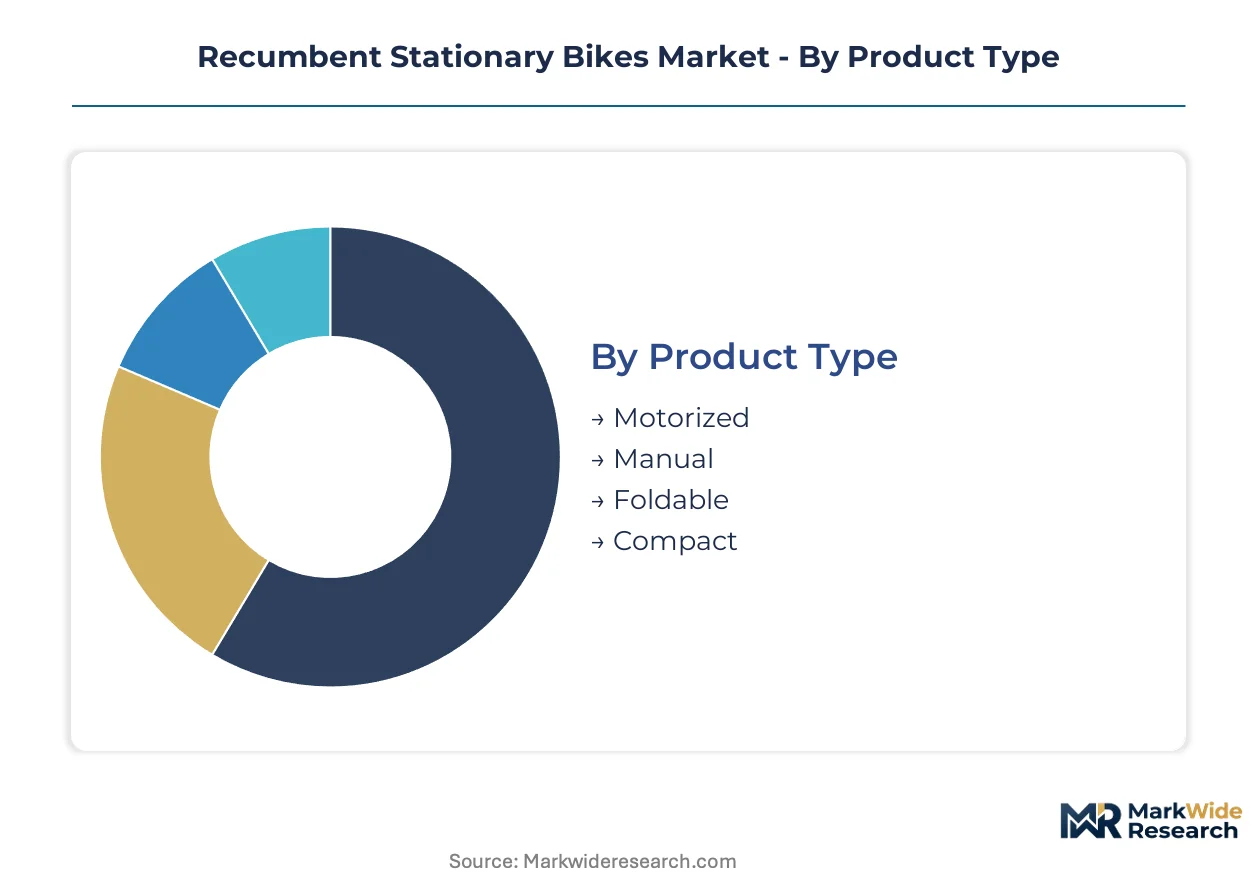
Recumbent stationary bikes serve divergent user needs ranging from clinical rehabilitation protocols to apartment-dwelling fitness enthusiasts. Segmentation reveals where margin pools concentrate versus where volume scales, guiding resource allocation across hardware configurations and software integration levels.
Product Type:
Replacement cycles vary dramatically across this category, with commercial-grade units in institutional settings turning over every 36-48 months while residential models face discretionary upgrade timelines stretching 7-10 years.
- Motorized:Electromagnetic resistance systems with programmable workout profiles and automated incline simulation dominate cardiac rehabilitation procurement. Rehabilitation centers in the United States prioritize these configurations for Medicare-reimbursable outpatient programs, where precise workload documentation satisfies clinical protocol requirements.
- Foldable:Collapsible frame designs with quick-release mechanisms and transport wheels address space-constrained urban residential environments. Municipal fitness subsidies in Japan's Aichi prefecture specifically prioritize compact storage-capable equipment for senior community centers, accelerating public procurement velocity for this configuration.
- Manual:Friction-based resistance systems with mechanical tension knobs serve price-sensitive residential segments and budget-conscious hotel fitness installations. These units bypass electronic component supply chain vulnerabilities concentrated in Taiwanese manufacturing clusters.
- Compact:Reduced-footprint frames with shortened wheelbases and lower seat heights target apartment dwellers and senior living facilities with spatial constraints. German rehabilitation clinic chains specify these dimensions for in-room patient conditioning protocols.
Motorized configurations anchor the volume base while foldable variants gain share at the steepest rate.
End User:
Procurement sophistication and software integration requirements escalate sharply across this spectrum, from individual consumers prioritizing streaming content compatibility to institutional buyers demanding EMR interoperability and usage telemetry.
- Residential Users:Individual consumers purchasing through direct-to-consumer platforms or mass-market retail channels, prioritizing subscription content bundles and Bluetooth-enabled biometric tracking for personal fitness app integration.
- Gyms:Mid-tier health club chains in São Paulo and Rio de Janeiro are shifting toward usage-based leasing models rather than capital purchases, compressing upfront equipment commitments while extending vendor cash conversion cycles.
- Rehabilitation Centers:Post-surgical recovery facilities consolidating procurement around connected bikes with real-time telemetry, where software integration requirements now outweigh hardware durability as the primary vendor selection criterion.
- Health Clubs:Private equity-backed fitness rollups in Texas and Florida piloting check-in-frequency-scaled rental agreements, prioritizing balance sheet flexibility over long-term equipment ownership.
Residential users anchor the volume base while rehabilitation centers command the steepest expansion trajectory.
Price Tier:
Margin structures compress at the economy extreme while luxury positioning requires sustained software ecosystem investment to justify sustained premium pricing against mid-range feature convergence.
- Premium:Electromagnetic resistance systems with integrated touchscreen displays and adaptive workout algorithms, capturing strongest margin pools from health clubs and rehabilitation centers where biometric tracking integration commands pricing power.
- Mid-Range:Magnetic resistance units with basic Bluetooth connectivity and manual programmability, serving the largest addressable residential segment where extended warranty programs and domestic assembly operations differentiate competing offerings.
- Economy:Entry-level friction-resistance models distributed through mass-market sporting goods channels, with NordicTrack and Schwinn anchoring retail shelf presence through deep partnership networks.
- Luxury:Commercial-grade configurations with medical-device-class build standards and telehealth platform integration, reimbursable under evolving CPT codes for remote patient monitoring applications.
Mid-range configurations anchor the volume base while premium tiers climb the fastest.
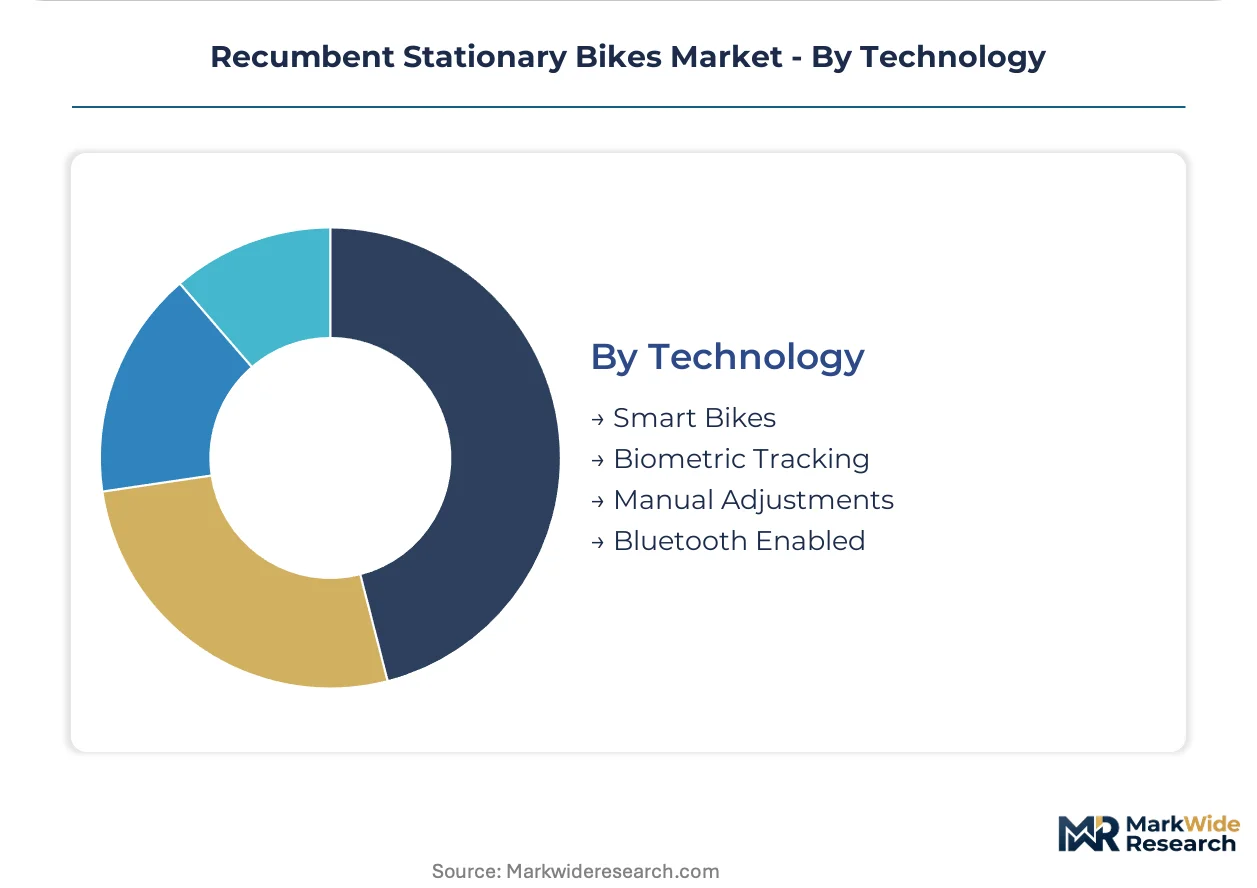
Technology:
Development priorities have pivoted from mechanical durability specifications to software-enabled personalization, with data governance obligations now shaping feature roadmaps as heavily as engineering constraints.
- Smart Bikes:Fully integrated platforms with proprietary operating systems, streaming content ecosystems, and automated resistance modulation based on biometric feedback loops, commanding recurring revenue streams beyond hardware margins.
- Biometric Tracking:Heart rate monitoring, power output measurement, and metabolic estimation sensors enabling asynchronous clinical oversight and automated protocol adjustments without on-site supervision.
- Manual Adjustments:Mechanical resistance controls and analog workout programming, serving institutional buyers with cybersecurity constraints and residential users with privacy concerns about connected fitness data collection.
- Bluetooth Enabled:Open-standard wireless connectivity allowing third-party app integration and BYOD screen mirroring, preferred by tech-savvy residential users seeking platform flexibility over walled-garden ecosystems.
Bluetooth-enabled configurations anchor the volume base while smart bikes expand most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Institutional buyers in the United States drive premium-tier procurement, while aging demographics in Japan and Germany reshape public fitness infrastructure priorities. Residential demand clusters in urban China and Brazil concentrate on compact, connected configurations.
United States
Medicare reimbursement policies for cardiac rehabilitation equipment institutionalize recumbent bikes as standard post-surgical recovery infrastructure. The FDA regulates medical fitness devices marketed with therapeutic claims, requiring 510(k) clearance for connected configurations. Rehabilitation centers in Texas and Florida pilot usage-based leasing models that scale monthly fees with member check-in frequency.
Germany
Rehabilitation clinic chains consolidate vendor lists around partners with established EU Medical Device Regulation compliance infrastructure. The MDR classifies stationary bikes marketed for cardiac rehabilitation as Class IIa devices, mandating notified body involvement and post-market surveillance. Bavaria-based clinic networks specify compact-frame dimensions for in-room patient conditioning protocols.
Japan
Municipal fitness subsidies for seniors in Aichi and Fukuoka prefectures prioritize low-impact cardiovascular equipment, creating concentrated public procurement demand. METI administers standards for consumer product safety and electromagnetic compatibility. Tokyo-area senior community centers accelerate replacement cycles for foldable, storage-capable configurations.
China
Apartment-dwelling fitness enthusiasts in Shanghai and Beijing prioritize space-efficient residential equipment with Bluetooth-enabled biometric tracking. SAMR enforces national standards for stationary exercise equipment mechanical safety and electromagnetic compatibility. Pearl River Delta manufacturing clusters supply electromagnetic resistance systems to domestic and export markets.
Brazil
Mid-tier gym chains in São Paulo and Rio de Janeiro shift toward equipment leasing rather than capital purchases, opening subscription-based revenue models. ANVISA regulates medical device classifications for therapeutic fitness claims. Private health club expansion in southeastern metropolitan areas concentrates demand for connected bike configurations with streaming content compatibility.
Recumbent Stationary Bikes Market Competitive Landscape
Channel-controlling players compete with product-specialist players across fragmented tiering. The vendor base organizes around three strategic archetypes: direct-to-consumer streaming platforms, mass-market retail anchors, and institutional-grade specialists. Consolidation pressure concentrates among rehabilitation-focused configurations where software integration requirements now outweigh hardware durability as selection criteria. Dominant competitive moves include strategic partnerships with telehealth platforms and geographic expansion through asset-light leasing models.
Among North American direct-to-consumer platforms, NordicTrack exemplifies the hardware-plus-content subscription archetype with streaming ecosystem integration. Schwinn anchors mass-market retail positioning through deep sporting goods channel partnerships. Sole Fitness occupies the service-reliability tier with extended warranty programs and domestic assembly operations. These three players represent divergent strategic bets on recurring revenue versus one-time equipment sales.
| Leading Market Players |
|---|
| Schwinn |
| NordicTrack |
| Diamondback Fitness |
| Sunny Health & Fitness |
| Sole Fitness |
| Matrix Fitness |
| Technogym |
| Marcy |
| Star Trac |
| Others |
Value Network & Pricing Analysis
Taiwanese electronics clusters in Hsinchu Science Park concentrate Bluetooth module and sensor PCB production, anchoring cost structures for connected recumbent bike configurations and compressing margins on mid-tier magnetic resistance units when neodymium pricing fluctuates. Certification-grade differentiation creates downstream pricing power for vendors serving Medicare-reimbursable rehabilitation programs.
Pricing Analysis
Certification level creates the primary spread between economy friction-resistance models and premium electromagnetic systems with FDA 510(k) clearance. Three-tier pricing structure across premium, standard, and economy levels stratifies by software integration depth, with biometric tracking capability commanding strongest margin pools from institutional buyers. Pricing pressure stems from steel and rare-earth magnet volatility squeezing mid-tier units. Rehabilitation centers exhibit lowest price sensitivity due to reimbursement coverage, while residential consumers in compact urban environments drive hardest bargain hunting.
Supply Chain Analysis
Extended payment terms from Hsinchu-based electronics suppliers to downstream assemblers compress working capital cycles for vendors offering usage-based leasing models. Manufacturing draws from Taiwanese semiconductor clusters, Chinese cold-rolled steel mills, and German electromagnetic resistance engineering. Single-geography concentration in Hsinchu exposes supply chains to disruption risk from regional logistics chokepoints. Distribution runs through direct-to-consumer platforms, mass-market sporting goods retail, and institutional procurement channels serving rehabilitation centers and health club chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among rehabilitation center chains and private equity-backed gym rollups, consolidating vendor lists around partners with established software integration capabilities and regulatory compliance infrastructure.
For Market Incumbents: Build switching-cost moats through EMR interoperability and telehealth platform integration to defend against hardware commoditization. Deepen captive supply of electromagnetic resistance systems to offset Taiwanese electronics concentration risk. Invest in FDA 510(k) clearance infrastructure to maintain access to Medicare-reimbursable procurement channels.
For New Entrants and Emerging Players: Establish a beachhead in Brazil's equipment-leasing segment where mid-tier gym chains prioritize balance sheet flexibility over vendor loyalty. Target Japan's municipal senior fitness subsidy programs with foldable configurations meeting METI storage-efficiency specifications. Lead with streaming content bundles to capture recurring revenue before hardware margins compress.
For Investors and Strategic Acquirers: Capital is best deployed toward software-enabled specialists with established MDR compliance infrastructure and telehealth integration capabilities. Long-term viability hinges on recurring revenue attachment rates rather than one-time equipment sales. Watch for CPT code expansion signals indicating reimbursement tailwinds for remote patient monitoring configurations.
| Strategic Initiative | Industry Significance |
|---|---|
| Telehealth Platform Integration | Enables reimbursable remote cardiac rehabilitation oversight through real-time biometric telemetry transmission. |
| EU MDR Compliance Infrastructure | Mandates notified body involvement for Class IIa device classification in German rehabilitation clinic procurement. |
| Asset-Light Leasing Model Expansion | Captures subscription revenue from São Paulo and Rio de Janeiro gym chains prioritizing balance sheet flexibility. |
| Direct-to-Consumer Streaming Launch | Bypasses sporting goods retail intermediaries to capture lifetime value through recurring membership fees. |
| Domestic Assembly Operations | Differentiates on service reliability through extended warranty programs competing beyond price alone. |
Research Methodology
Operator-level perspectives from rehabilitation center procurement directors, health club fleet managers, biomedical engineers, and GPO contracts managers anchored the qualitative base. Primary insights combined with secondary validation from FDA 510(k) filings, CMS Medicare reimbursement databases, hospital procurement records, and EU MDR technical documentation. Bottom-up equipment shipment analysis and top-down healthcare infrastructure spending triangulation established market sizing boundaries.
Scenario-bracketing around Medicare reimbursement policy continuity, neodymium price volatility bands, and Taiwanese supply disruption probability framed the analytical envelope across the projection horizon. Segmentation modeling incorporated product type, end-user procurement sophistication, price tier positioning, and technology integration level dimensions. CAGRs derived from replacement cycle analysis, institutional capital refresh patterns, and residential upgrade propensity curves specific to connected fitness equipment adoption.
Stress conditions across steel tariff regimes, FCC digital health regulatory evolution, and state-level biometric privacy law proliferation were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about reimbursement policy stability and supply chain geographic concentration. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fitness Equipment
Gym Fitness Accessories Market
Fitness Equipment
Japan Fitness Ring Market
Fitness Equipment
Belt Trainers Market
Fitness Equipment
US Fitness Rings Market
Fitness Equipment
Yoga Mat Market
Fitness Equipment
Military Fitness Training Equipment Market
Fitness Equipment
Yoga Equipment Market
Fitness Equipment
Middle East and Africa Fitness Equipment Market
Fitness Equipment
North America Fitness Rings Market
Fitness Equipment
China Outdoor Fitness Equipment Market
Fitness Equipment
Exercise Band Market
Fitness Equipment
Gymnastics Equipment Market
Fitness Equipment
Weight Training Benches Market
Fitness Equipment
Asia-Pacific Fitness Rings Market
Fitness Equipment
Fitness Rings Market
Fitness Equipment
BMI Machine Market