
 Lateral Fitness Equipment Market | 2026-2036
Lateral Fitness Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Lateral Fitness Equipment Market Intelligence
China is fragmenting its lateral fitness equipment manufacturing base as domestic brands scale capacity for export markets. Technogym S.p.A. leverages Italian design heritage to dominate premium commercial installations across Europe. Johnson Health Tech Co. Ltd. anchors volume production through vertically integrated facilities in Taiwan and mainland China. Cybex International Inc. competes on biomechanical engineering credibility within rehabilitation and performance segments.
Lateral fitness equipment encompasses devices engineered for frontal-plane movement training, typically featuring low-friction sliding surfaces with adjustable resistance mechanisms spanning 48 to 72 inches in track length, designed to develop hip abductor and adductor strength while reducing sagittal-plane joint loading. The equipment serves commercial gyms, sports performance centers, and physical therapy clinics seeking to correct muscular imbalances and enhance multi-directional athletic capacity. Lateral trainers within the product type category command the strongest margin pools due to electromechanical complexity and institutional procurement cycles, while slide boards sustain steady replacement demand from hockey and figure skating training facilities. Composite materials are displacing wood in professional-grade equipment as manufacturers pursue durability standards demanded by high-frequency health club usage.
The U.S. Consumer Product Safety Commission and ASTM International govern structural integrity and pinch-point safety for motorized lateral trainers sold in North American commercial settings. The EU's REACH regulation and CE marking requirements constrain polymer and adhesive formulations used in European-market equipment, elevating compliance costs for imported products. China's GB standards and SAMR oversight enforce labeling and quality certification for domestically manufactured fitness devices. Stakeholders must monitor evolving biomechanical research validating lateral training efficacy, as peer-reviewed outcomes will determine whether insurers and corporate wellness programs expand reimbursement eligibility for this modality.
Market Dynamics
Composite material substitution is forcing equipment manufacturers to requalify supply chains under stricter durability protocols, while boutique fitness studios compress replacement cycles through specialized programming demands.
Growth Catalysts
- EU Green Deal material mandates:REACH-compliant polymer formulations are unlocking institutional procurement channels previously closed to imported equipment.
- Functional training zone expansion:Commercial health clubs in the United States are dedicating floor space to multi-planar movement stations.
- Biomechanical validation research:Peer-reviewed studies on hip abductor strength outcomes are expanding reimbursement consideration by corporate wellness programs.
Market Restraints
- Carbon fiber cost volatility:Composite input prices fluctuate with aerospace sector demand, squeezing margin pools on professional-grade slide boards.
- Taiwan-mainland China supply concentration:Vertically integrated production clusters create geopolitical exposure for volume manufacturers.
- Motorized trainer technical limitations:Electromechanical complexity elevates service contract costs beyond budget gym operator thresholds.
Strategic Opportunities
- Germany boutique studio penetration:Specialized agility programming in Berlin and Munich drives premium equipment replacement at 18-24 month cycles.
- Rehabilitation-clinic application expansion:Physical therapy protocols for ACL recovery are incorporating lateral trainers into standardized care pathways.
- CE marking acceleration:Streamlined conformity assessment procedures are reducing time-to-market for composite-based product lines.
Industry Challenges
- Biomechanical engineering talent scarcity:Equipment manufacturers compete with automotive and aerospace sectors for composite structural analysts.
- ASTM certification timeline compression:U.S. Consumer Product Safety Commission structural integrity testing creates 8-14 month approval bottlenecks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lateral Fitness Equipment Market |
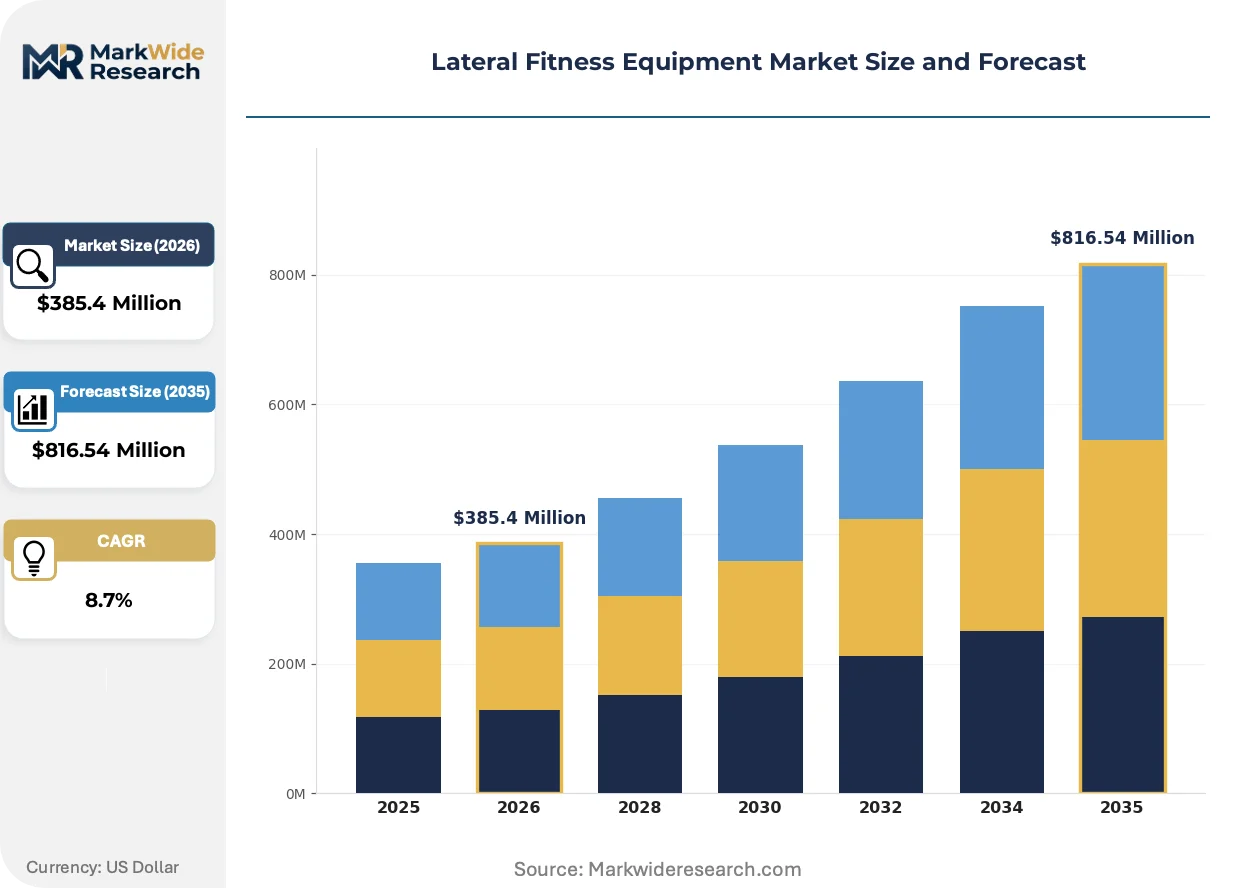
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $816.54 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Balance Boards, Agility Ladders, Lateral Trainers, Slide Boards End User: Fitness Enthusiasts, Professional Athletes, Health Clubs, Rehabilitation Centers Material: Plastic, Wood, Composite, Metal Distribution Channel: Online Retail, Specialty Stores, Fitness Equipment Resellers, Wholesale |
| Companies Covered | Technogym S.p.A., Johnson Health Tech Co. Ltd., Core Health & Fitness LLC., Nautilus Inc., ICON Health & Fitness Inc., Amer Sports Corporation, True Fitness Technology Inc., Impulse (Qingdao) Health Tech Ltd. Co., Cybex International Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lateral Fitness Equipment Market Strategic Shifts & Innovations
Equipment architecture is pivoting toward modularity and sensor integration, while regulatory chemistry constraints and buyer consolidation reshape competitive requirements across installation types.
Low-friction polymer track surfaces are migrating from wood-composite hybrids to full synthetic construction. High-frequency health clubs in the United States are adopting these surfaces at replacement-cycle intervals of 36-48 months. The shift is compressing traditional woodworking supply chains while elevating chemical compliance burdens under REACH and state-level disclosure rules.
REACH substance restrictions are tightening adhesive and polymer formulations for European-market equipment. Manufacturers reformulating bonding agents face 12-18 month requalification timelines. German and French procurement officers now require full material disclosure documentation, shifting supplier selection criteria toward in-house chemistry capabilities.
Leasing structures are displacing outright purchase for commercial installations. Boutique studios and municipal recreation centers are adopting 36-month equipment-as-service contracts with bundled maintenance. This pattern concentrates most visibly in Germany's studio segment, where cash-flow optimization overrides capital expenditure preference.
Lateral Fitness Equipment Market Segmentation
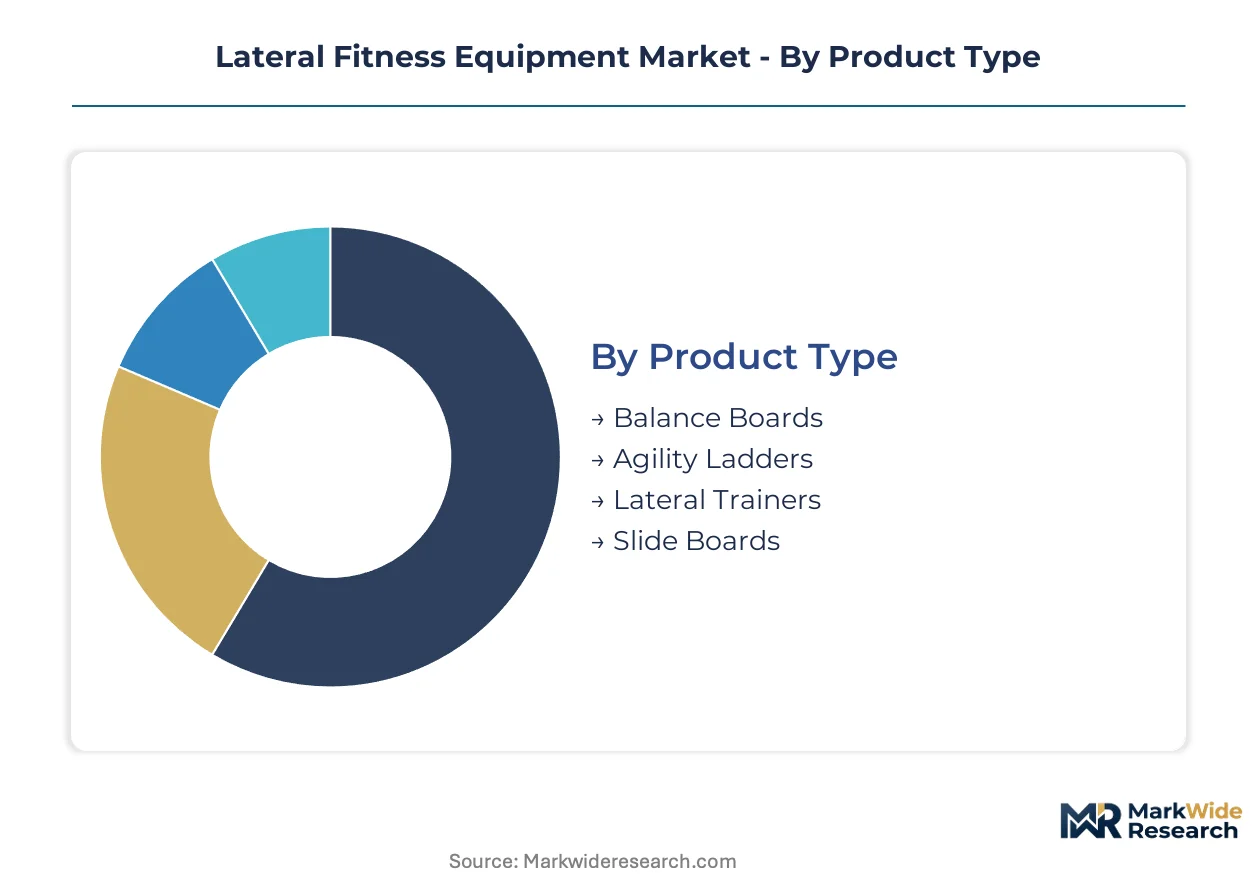
Segmentation in lateral fitness equipment reveals how procurement patterns, durability requirements, and channel economics fragment the addressable market. Equipment specifications vary sharply across installation types, from high-frequency health club usage demanding composite construction to home fitness enthusiasts prioritizing portability and price accessibility.
Product Type:
After-sales service intensity varies dramatically across product types, with electromechanical systems requiring preventive maintenance contracts while passive devices need only periodic surface replacement.
- Lateral Trainers:Motorized or magnetic-resistance platforms with 48-72 inch track lengths enable adjustable frontal-plane loading for hip abductor strengthening. Health clubs in the United States specify these for functional training zones, though electromechanical complexity elevates service contract costs beyond budget operator thresholds.
- Slide Boards:Low-friction synthetic or composite surfaces, typically 6-8 feet in length, support lateral sliding movements for hockey and figure skating training facilities. Germany's boutique studios compress replacement cycles to 18-24 months through specialized agility programming.
- Balance Boards:Rocker or wobble platforms with wooden or composite bases challenge proprioception and ankle stability. Home fitness enthusiasts drive volume through online retail channels.
- Agility Ladders:Flat or raised rung systems for footwork patterning, constructed from plastic webbing or fabric. Professional athletes and sports performance centers standardize these for multi-directional speed development.
Lateral Trainers holds the largest share; momentum sits with Slide Boards as composite material substitution accelerates replacement demand.
End User:
Cost tier stratification separates capital-intensive institutional procurement from discretionary consumer spending, with reimbursement eligibility emerging as a critical purchase enabler.
- Health Clubs:Commercial fitness facilities with 500+ member bases require ASTM-certified equipment with 36-48 month replacement cycles. Functional training zone expansion in the United States concentrates demand for multi-planar movement stations.
- Rehabilitation Centers:Physical therapy clinics incorporate lateral trainers into ACL recovery protocols, with peer-reviewed outcomes determining insurer reimbursement expansion. Equipment must satisfy clinical durability standards under repetitive patient use.
- Professional Athletes:Individual competitors and team facilities prioritize biomechanical precision and sport-specific movement patterns. Hockey and figure skating training facilities sustain steady slide board demand.
- Fitness Enthusiasts:Home-based consumers purchase entry-level balance boards and agility ladders through e-commerce channels, with price sensitivity limiting composite material adoption.
Health Clubs commands the dominant revenue position; Rehabilitation Centers are expanding most quickly as clinical protocols formalize lateral training integration.
Material:
Volume concentration in high-frequency commercial installations is driving material substitution away from traditional wood toward engineered composites with extended service intervals.
- Composite:Glass- and carbon-fiber reinforced polymers deliver durability for professional-grade equipment under intensive health club usage. REACH-compliant formulations unlock European institutional procurement previously closed to imported products.
- Plastic:Injection-molded polymers serve entry-level agility ladders and balance boards for consumer markets. Cost volatility in petrochemical feedstocks squeezes margin pools at the economy tier.
- Wood:Traditional hardwood construction persists in premium slide boards and balance platforms. Woodworking supply chains face compression as synthetic surfaces capture replacement demand.
- Metal:Steel and aluminum framing reinforce lateral trainer structural integrity under motorized resistance loads. ASTM structural testing requirements govern pinch-point safety and frame stability.
Composite captures the premium institutional segment; Plastic maintains volume leadership in consumer-accessible price tiers.
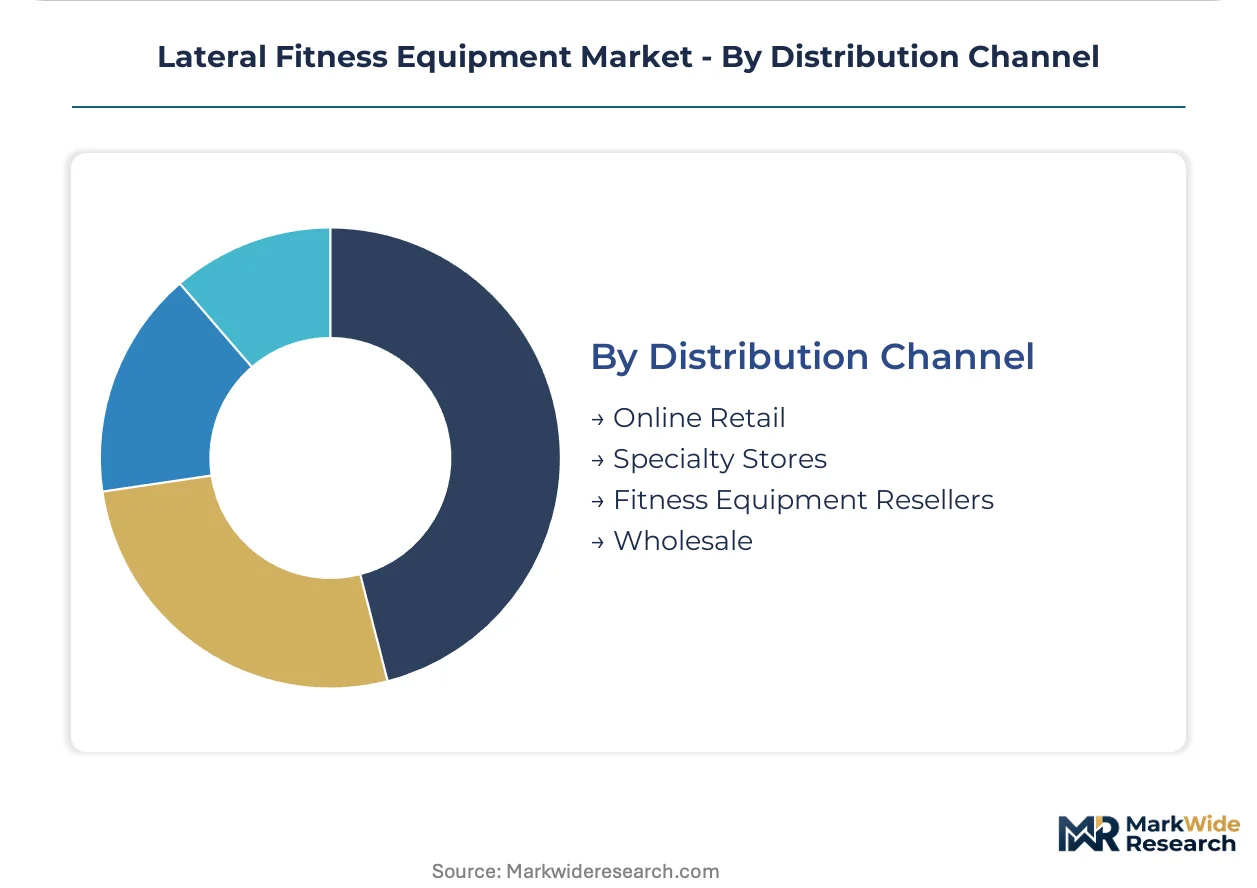
Distribution Channel:
Customer type and purchase scale determine channel selection, with leasing structures displacing outright purchase among cash-flow-conscious boutique operators.
- Fitness Equipment Resellers:Specialized distributors bundle installation, maintenance, and financing for commercial health club and rehabilitation center procurement. Germany's studio segment concentrates equipment-as-service contract adoption.
- Online Retail:Direct-to-consumer platforms serve fitness enthusiasts with standardized balance boards and agility ladders. Return logistics complexity constrains large-format lateral trainer sales.
- Specialty Stores:Physical showrooms enable tactile evaluation for premium composite slide boards and lateral trainers. Urban clusters in Berlin and Munich support boutique studio sourcing.
- Wholesale:Volume purchasing agreements supply municipal recreation centers and franchise health club chains. Procurement officers require full material disclosure documentation under EU Green Deal mandates.
Fitness Equipment Resellers dominates commercial value capture; Online Retail is gaining share fastest as home fitness investment persists post-pandemic.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's container throughput underwrites European fitness equipment import flows, while the Yangtze River Delta manufacturing corridor anchors Asian production capacity for lateral trainers.
United States
Commercial health clubs in Los Angeles and Miami are expanding functional training zones with multi-planar movement stations. ASTM International and the Consumer Product Safety Commission govern structural integrity testing for motorized lateral trainers, creating 8-14 month approval bottlenecks. The Pacific Northwest cluster around Seattle concentrates slide board demand from hockey training facilities.
Germany
Boutique studios in Berlin and Munich compress equipment replacement cycles to 18-24 months through specialized agility programming. The EU Green Deal and REACH substance restrictions tighten adhesive and polymer formulations, elevating compliance costs for imported products. The Rhine-Ruhr industrial corridor hosts procurement officers demanding full material disclosure documentation.
China
Domestic brands are scaling manufacturing capacity in the Pearl River Delta for export markets. GB standards and SAMR oversight enforce labeling and quality certification for domestically produced fitness devices. Shanghai's commercial gym operators drive demand for composite-based lateral trainers with extended service intervals.
Japan
Rehabilitation clinics in Tokyo and Osaka incorporate lateral trainers into ACL recovery protocols. METI and JIS standards govern equipment safety and performance specifications for commercial installations. The Kansai region concentrates sports performance centers serving professional athletes with biomechanical precision requirements.
United Kingdom
Corporate wellness programs in London are expanding reimbursement consideration for lateral training modalities based on peer-reviewed hip abductor strength outcomes. The Health and Safety Executive oversees workplace fitness equipment safety standards. The Southeast England cluster around London supports premium equipment resellers bundling installation and maintenance contracts.
Lateral Fitness Equipment Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream supplying track surfaces and resistance mechanisms. The vendor base fragments across vertically integrated volume manufacturers, design-driven premium specialists, and regional fabricators serving niche rehabilitation segments. Three strategic archetypes dominate: Italian heritage brands leveraging aesthetic differentiation, Taiwanese-Chinese conglomerates anchoring scale production, and biomechanical engineering specialists competing on clinical credibility. Competitive moves concentrate on M&A for technology access and capacity expansion in REACH-compliant polymer formulation.
Among the named players, Technogym S.p.A. and Cybex International Inc. occupy positions within the premium system tier, while Johnson Health Tech Co. Ltd. anchors volume production capabilities. These three exemplify the geographic and strategic segmentation visible across the competitive set: European design heritage, North American biomechanical engineering credibility, and Asia-Pacific manufacturing scale.
| Leading Market Players |
|---|
| Technogym S.p.A. |
| Johnson Health Tech Co. Ltd. |
| Core Health & Fitness LLC. |
| Nautilus Inc. |
| ICON Health & Fitness Inc. |
| Amer Sports Corporation |
| True Fitness Technology Inc. |
| Impulse (Qingdao) Health Tech Ltd. Co. |
| Cybex International Inc. |
| Others |
Cost & Logistics Intelligence
Undercapacity in Taiwan's vertically integrated manufacturing corridor is elevating supplier leverage over volume buyers while compressing margin pools for budget-tier lateral trainer producers. This utilization squeeze propagates through composite input pricing and electromechanical component sourcing, forcing procurement officers to accept extended lead times or absorb cost pass-throughs.
Pricing Analysis
REACH-compliant polymer formulations dictate the pricing tier structure across European institutional procurement channels. Three-tier pricing structure across premium, standard, and economy levels separates Italian-designed lateral trainers with full CE marking from Asian-manufactured alternatives with partial compliance documentation. Cost compression in the standard tier is intensifying because carbon fiber feedstock prices fluctuate with aerospace sector demand. Boutique studios in Germany exhibit the lowest price sensitivity due to 18-24 month replacement cycles, while municipal recreation centers face the highest budget constraints.
Supply Chain Analysis
Extended payment terms from 60 to 90 days are becoming standard for composite material suppliers serving volume manufacturers in Taiwan and mainland China. Manufacturing gravity draws from the Yangtze River Delta and Pearl River Delta corridors, with secondary sourcing from Italian design houses for premium track surface engineering. Critical dependencies include carbon fiber tow, low-friction polymer resins, and magnetic resistance mechanisms. Single-source vulnerability concentrates in electromechanical actuator supply. Distribution runs through specialized fitness equipment resellers bundling installation and preventive maintenance contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbent equipment manufacturers face substitution pressure from connected fitness platforms offering digital lateral training content without dedicated hardware. Defending installed base requires proactive moves across three stakeholder categories.
For Market Incumbents: Harden supply chain resilience by securing captive polymer formulation capacity under REACH compliance, insulating margin pools from carbon fiber cost volatility. Deepen backward integration into track surface manufacturing to compress 36-48 month replacement cycle economics for health club accounts. Prioritize ASTM certification pipeline acceleration to close 8-14 month approval bottlenecks before emerging competitors achieve parity.
For New Entrants and Emerging Players: Build out white-space presence in rehabilitation clinic applications where ACL recovery protocols are formalizing lateral trainer integration. Germany's boutique studio segment offers the most penetrable geography given compressed replacement cycles and premium equipment preference. Pursue equipment-as-service contract structures to bypass capital expenditure barriers among cash-flow-conscious municipal recreation centers.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across composite material formulation capabilities as REACH compliance timelines extend to 12-18 months. Five-to-ten year viability favors targets with in-house chemistry documentation and established European procurement relationships. Monitor CE marking acceleration timelines as the inflection signal for time-to-market competitiveness.
| Strategic Initiative | Industry Significance |
|---|---|
| REACH-Compliant Polymer Formulation | Unlocks institutional procurement channels in Germany and France previously closed to imported equipment. |
| Equipment-as-Service Contract Launch | Captures boutique studio demand in Berlin and Munich through cash-flow-optimized leasing structures. |
| ASTM Certification Pipeline Investment | Reduces 8-14 month approval bottlenecks for motorized lateral trainers in United States commercial installations. |
| Rehabilitation Clinic Partnership Program | Secures placement in ACL recovery protocols driving fastest-growing end-user segment expansion. |
| Composite Material Backward Integration | Insulates margin pools from carbon fiber cost volatility tied to aerospace sector demand swings. |
Research Approach
Cross-validation between primary interviews with fitness equipment procurement officers and secondary validation through customs trade data anchors the qualitative findings. The research program engaged plant managers at composite material suppliers, health club operations directors, rehabilitation clinic biomedical engineers, and aftermarket service heads. Bottom-up and top-down triangulation incorporated ASTM International certification databases, EU ECHA substance restriction filings, SEC 10-K disclosures from listed equipment manufacturers, and health club operator capex surveys.
Calibration against historical replacement cycle data and procurement contract structures shaped the analytical framework. The model spans product type, material composition, end-user facility tier, and regional regulatory cluster dimensions across the projection horizon. CAGRs were derived from segment-level demand elasticity analysis and supply-side capacity utilization assessments. Forecast inputs included REACH compliance timeline trajectories and biomechanical validation research publication rates influencing reimbursement eligibility.
Practitioners should monitor carbon fiber aerospace demand correlation and EU Green Deal material mandate expansion for early signals. Forecasts reflect assumptions regarding institutional procurement channel stability and composite material substitution rates. Macroeconomic deviation, regulatory chemistry restriction tightening, or peer-reviewed efficacy study outcomes would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fitness Equipment
South Africa Gym Accessories Market
Fitness Equipment
GCC Fitness Ring Market
Fitness Equipment
Cardio Fitness Trampolines Market
Fitness Equipment
Asia-Pacific Fitness Rings Market
Fitness Equipment
Pilates Equipment and Gears Market
Fitness Equipment
Gymnastics Equipment Market
Fitness Equipment
Yoga Accessories Market
Fitness Equipment
Japan Fitness Ring Market
Fitness Equipment
Mexico Outdoor Fitness Equipment Market
Fitness Equipment
Functional Fitness Equipment Market
Fitness Equipment
Yoga Equipment Market
Fitness Equipment
North America Exercise Bike Market
Fitness Equipment
Elliptical Trainers Market
Fitness Equipment
Yoga Mat Market
Fitness Equipment
Europe Fitness Rings Market
Fitness Equipment
North America Home Fitness Equipment Market