
 BMI Machine Market | 2026-2036
BMI Machine Market Size, Share, and Industry Trends Forecast 2026-2036
BMI Machine Market Analysis
China's manufacturing corridor for precision health electronics is narrowing the cost-performance gap between entry-level and clinical-grade BMI machines. Tanita Corporation leverages its Japanese sensor heritage to sustain premium positioning across hospital procurement channels. InBody Co., Ltd. anchors the professional segment with multi-frequency bioelectrical impedance systems. Seca GmbH & Co. KG competes through modular platform designs that span fitness and medical certifications.
A BMI machine quantifies body mass index through weight-to-height ratio calculation, with clinical variants integrating bioelectrical impedance analysis to estimate fat mass, lean tissue, and hydration status at frequencies between 5 and 1000 kHz. Portable units dominate volume sales in fitness centers where space constraints and member throughput prioritize compact footprints. Smart BMI devices represent the fastest-expanding category as Bluetooth-enabled data logging and EMR integration reshape clinical workflows. Floor models retain margin concentration in bariatric and research settings where load cell precision and stability standards exceed handheld specifications.
The FDA's 510(k) clearance pathway for body composition analyzers shapes product development timelines and clinical claims in the United States, while the EU Medical Device Regulation (MDR) reclassifies certain multi-parameter BMI systems and intensifies post-market surveillance obligations across European markets. India's CDSCO is aligning with IEC 60601-1 electrical safety standards for imported diagnostic scales, raising compliance barriers for uncertified suppliers. Stakeholders must weigh regulatory capital requirements against the pricing elasticity of emerging clinic networks in underserviced urban districts.
Market Dynamics
The BMI machine market is undergoing structural compression as multi-frequency bioelectrical impedance technology migrates from clinical-grade systems into mid-tier devices, eroding the historical performance gap between hospital and fitness-center equipment categories.
Growth Catalysts
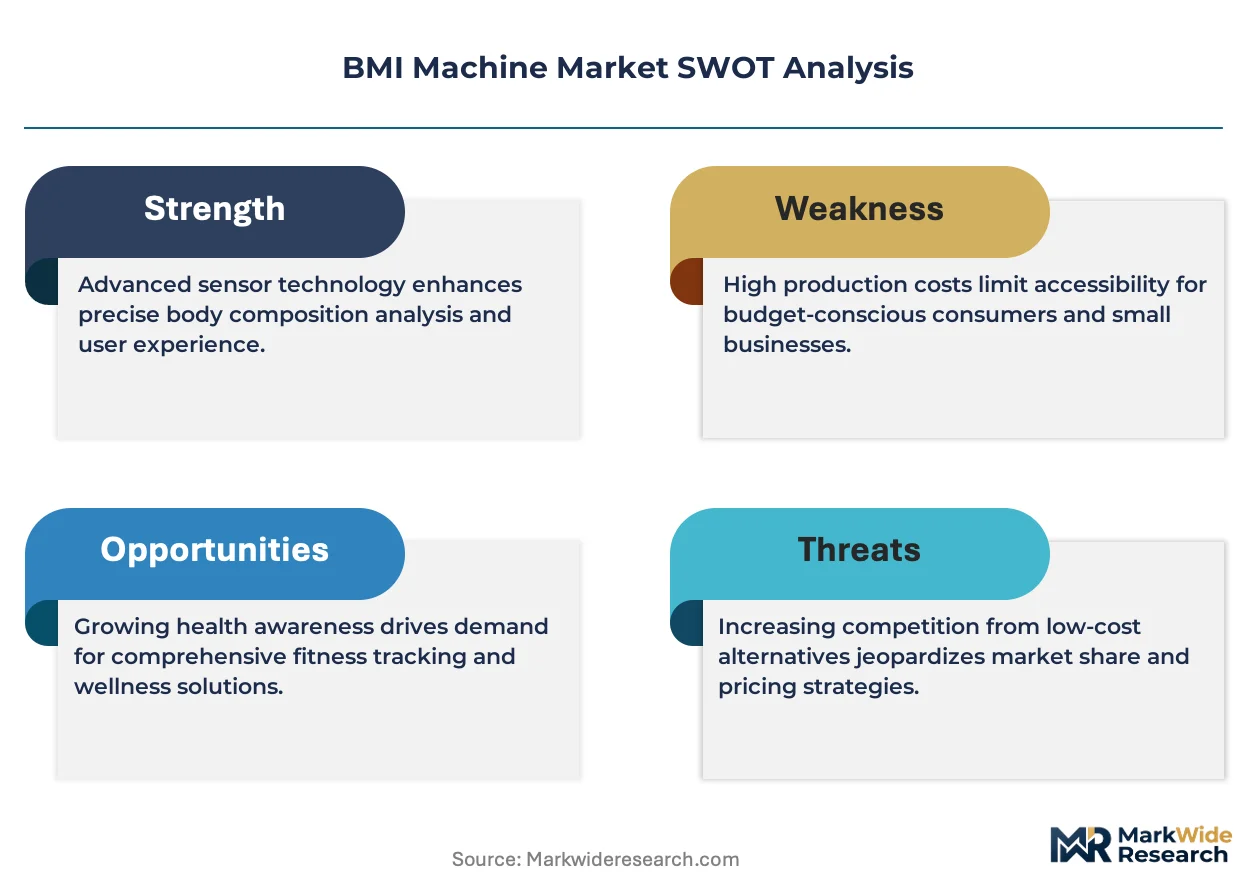
- CDSCO alignment with IEC 60601-1:India's electrical safety standardization for imported diagnostic scales is accelerating procurement by tier-2 clinic networks seeking certified equipment.
- Preventive healthcare infrastructure scaling:Municipal health initiatives across Southeast Asian urban districts are expanding connected diagnostic equipment procurement budgets.
- Bluetooth-enabled EMR integration:Smart BMI devices with wireless data logging are reshaping clinical workflows in outpatient settings.
Market Restraints
- Load cell precision costs:Bariatric-grade stability standards require specialized sensor arrays that inflate manufacturing input costs for floor-model producers.
- FDA 510(k) pathway duration:The clearance timeline for body composition analyzers extends product development cycles and delays clinical claim substantiation.
- Handheld unit substitution:Compact portable devices are capturing fitness-center volume demand that previously flowed to full-platform systems.
Strategic Opportunities
- EU MDR reclassification tailwind:Intensified post-market surveillance obligations for multi-parameter systems create compliance-service revenue streams for certified manufacturers.
- Tier-2 city clinic networks:Underserviced urban districts in India present white-space demand for connected diagnostic infrastructure.
- Sensor-software convergence:Integration of Japanese heritage sensor technology with cloud analytics platforms is opening premium positioning in research settings.
Industry Challenges
- Bioelectrical impedance calibration expertise:Shortage of technicians capable of maintaining multi-frequency system accuracy across 5-1000 kHz ranges is constraining service network expansion.
- Legacy EMR integration complexity:Hospital IT departments face technical friction when connecting smart BMI devices to established patient data architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | BMI Machine Market |
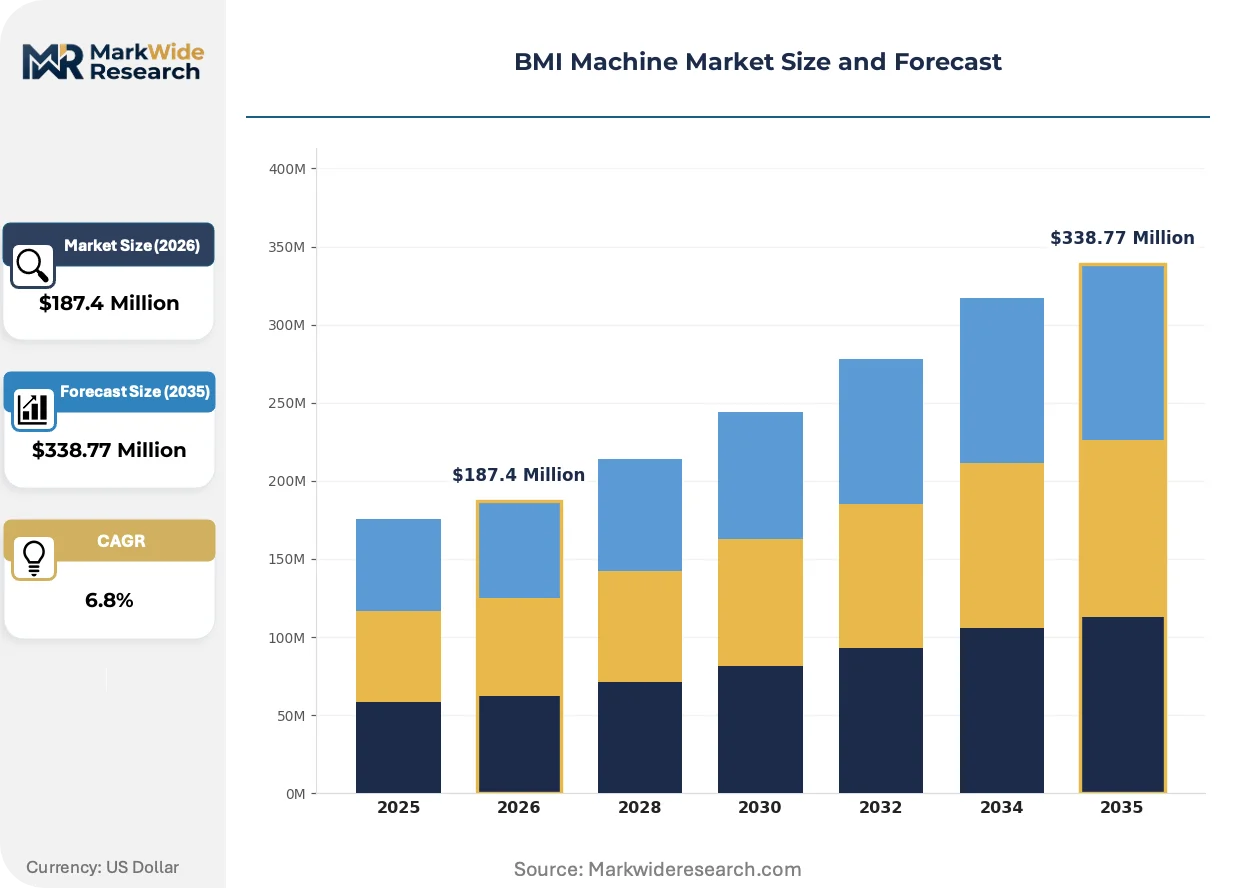
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Units, Wall-Mounted Scanners, Floor Models, Smart BMI Devices End User: Hospitals, Clinics, Fitness Centers, Home Users Technology: Bioelectrical Impedance, Dual-Energy X-Ray, Infrared Sensors, Mechanical Weighing Application: Health Monitoring, Fitness Assessment, Clinical Diagnosis, Research Studies |
| Companies Covered | InBody Co., Ltd., Tanita Corporation, seca GmbH & Co. KG, Omron Healthcare Co., Ltd., Beurer GmbH, A&D Company, Limited, Bodystat Ltd., Marsden Weighing Group Limited, GE Healthcare, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
BMI Machine Market Emerging Trajectories
Technology convergence and regulatory recalibration are compressing traditional equipment hierarchies while reshaping how clinical and fitness segments source body composition analysis capabilities.
Multi-frequency bioelectrical impedance analysis is collapsing the performance boundary between clinical and fitness-grade BMI machines. Hospital procurement departments are now evaluating mid-tier devices for non-bariatric applications. This compression is forcing premium manufacturers to defend positioning through software differentiation rather than hardware specifications alone.
The FDA's evolving accuracy requirements for body composition devices are tightening 510(k) clearance standards. Manufacturers must now submit expanded clinical validation data for fat-mass estimation claims. Professional-segment suppliers are responding by front-loading regulatory capital into pre-submission meetings.
Equipment-as-a-service models are displacing capital purchase cycles in corporate wellness programs. Subscription pricing with bundled calibration and software updates is capturing mid-size fitness chains. This shift is most visible in Southeast Asian markets where clinic networks prioritize operational expenditure flexibility over asset ownership.
BMI Machine Market Segmentation
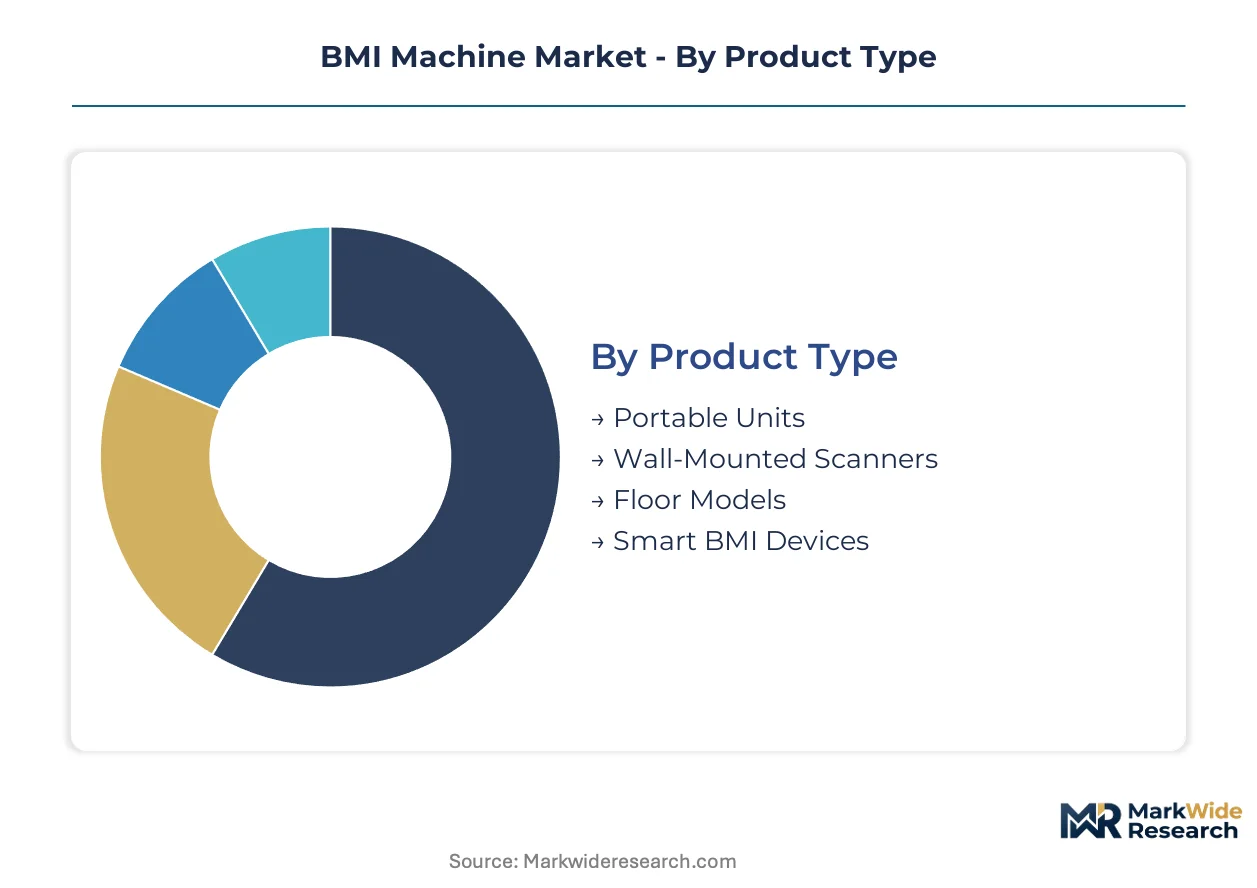
BMI machine segmentation reveals divergent replacement cycles across product architectures, with portable and smart-connected devices turning over every 3-4 years versus 7-10 year lifecycles for clinical floor systems. Procurement patterns in India's tier-2 cities and Southeast Asian clinic networks are compressing these cycles further as connected diagnostics reshape equipment refresh priorities.
Product Type:
Replacement velocity varies dramatically across form factors, with compact units cycling fastest due to member throughput demands and technology obsolescence pressures.
- Smart BMI Devices:Bluetooth-enabled platforms integrate bioelectrical impedance analysis with cloud data logging at 5-1000 kHz frequencies. Demand concentrates in Southeast Asian clinic networks seeking EMR-compatible workflows under municipal preventive health initiatives. CDSCO alignment with IEC 60601-1 standards is accelerating certified procurement in India's tier-2 urban districts.
- Portable Units:Compact footprints prioritize space efficiency and rapid member throughput in fitness centers where floor space commands premium pricing. Handheld substitution is capturing volume demand that previously flowed to full-platform systems, compressing margins for traditional manufacturers.
- Floor Models:Bariatric-grade load cell arrays deliver precision stability for research and hospital settings. Specialized sensor requirements inflate manufacturing input costs.
- Wall-Mounted Scanners:Fixed installations serve high-throughput clinical environments with permanent calibration infrastructure. Space-constrained facilities in dense Asian urban cores favor this architecture.
Portable units anchor the volume base while smart BMI devices gain share at the steepest rate.
End User:
Procurement sophistication tiers sharply across customer types, from research-grade specifications in academic medical centers to price-elastic purchasing in consumer wellness.
- Clinics:Outpatient networks across Southeast Asia are expanding connected diagnostic equipment budgets under municipal health initiatives. CDSCO electrical safety standardization is filtering uncertified suppliers from India's tier-2 procurement channels.
- Fitness Centers:Corporate wellness programs and mid-size chains are shifting toward equipment-as-a-service models with bundled calibration. Subscription pricing captures operational expenditure flexibility over asset ownership.
- Hospitals:Bariatric and research departments require load cell precision exceeding handheld specifications. FDA 510(k) clearance timelines extend product validation cycles for clinical claim substantiation.
- Home Users:Consumer-grade devices prioritize cost compression over multi-frequency accuracy. Bluetooth connectivity is penetrating this segment through smartphone ecosystem integration.
Clinics drive the steepest procurement expansion while fitness centers are displacing capital purchase cycles fastest.
Technology:
Performance convergence between clinical and fitness-grade systems is collapsing traditional technology hierarchies as multi-frequency bioelectrical impedance migrates downward.
- Bioelectrical Impedance:Multi-frequency analysis at 5-1000 kHz estimates fat mass, lean tissue, and hydration status. Technician shortages capable of maintaining calibration accuracy across this range are constraining service network expansion.
- Mechanical Weighing:Load cell-based height-to-weight calculation remains the cost floor for basic BMI quantification. Entry-level manufacturing in China's precision health electronics corridor is narrowing cost-performance gaps.
- Infrared Sensors:Non-contact measurement architectures serve specific wellness applications where user hygiene concerns predominate.
- Dual-Energy X-Ray:DXA systems anchor research and bariatric surgical planning with gold-standard body composition accuracy. Capital intensity limits deployment to academic medical centers.
Mechanical weighing retains the broadest installed base while bioelectrical impedance climbs the fastest.
Application:
Use-case specificity determines regulatory pathway complexity and pricing architecture, from wellness screening to diagnostic claim substantiation.
- Clinical Diagnosis:FDA 510(k) clearance requires expanded validation data for fat-mass estimation claims. Manufacturers are front-loading regulatory capital into pre-submission meetings to defend premium positioning.
- Health Monitoring:Preventive screening applications in municipal health initiatives across Southeast Asian urban districts are scaling procurement volumes. Connected data infrastructure is reshaping outpatient workflows.
- Fitness Assessment:Member throughput optimization drives compact device selection in commercial wellness settings. Space constraints prioritize portable architectures.
- Research Studies:Multi-parameter accuracy requirements sustain demand for Japanese heritage sensor technology integrated with cloud analytics platforms. Bariatric-grade stability standards command margin concentration.
Health monitoring anchors volume demand while clinical diagnosis commands the steepest pricing tier expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across geographies. Southeast Asian clinics prioritize connected diagnostic workflows under municipal health initiatives, while Indian procurement concentrates in tier-2 urban districts seeking certified equipment. US hospital networks demand FDA-cleared clinical validation, compressing development timelines.
United States
Hospital procurement departments evaluate mid-tier bioelectrical impedance devices for non-bariatric applications. FDA 510(k) clearance timelines extend validation cycles as accuracy requirements tighten for fat-mass estimation claims. Research institutions in the Boston-Cambridge corridor anchor demand for multi-frequency systems with cloud analytics integration.
China
Manufacturing corridors in the Yangtze River Delta narrow cost-performance gaps between entry-level and clinical-grade equipment. NMPA medical device registration accelerates for connected diagnostic platforms. Shenzhen-based electronics clusters supply precision sensor arrays to domestic and export markets.
India
Tier-2 city clinic networks in Gujarat and Karnataka scale preventive healthcare infrastructure procurement. CDSCO alignment with IEC 60601-1 electrical safety standards filters uncertified suppliers from import channels. Municipal health budgets in Pune and Ahmedabad prioritize EMR-integrated diagnostic equipment.
Japan
Hospital networks sustain premium positioning for heritage sensor technology in research and bariatric applications. PMDA medical device approval pathways shape product development for domestic and export markets. Nagoya-area precision electronics manufacturers supply multi-frequency impedance components.
Germany
EU MDR reclassification intensifies post-market surveillance obligations for multi-parameter body composition systems. Bavarian medical technology clusters develop modular platform designs spanning fitness and medical certifications. Hospital procurement in North Rhine-Westphalia demands compliance-service bundling.
BMI Machine Market Vendor Landscape
Capability concentration sits with heritage sensor manufacturers; scale advantage sits with diversified health electronics conglomerates. The market structures around three tiers: premium clinical-grade specialists, mid-tier connected device platforms, and volume-oriented fitness equipment suppliers. Consolidation pressures intensify as multi-frequency technology migrates downward. Dominant competitive moves include regulatory capital front-loading into pre-submission pathways and equipment-as-a-service subscription models displacing capital purchase cycles.
Within the heritage sensor tier, Tanita Corporation and InBody Co., Ltd. exemplify positioning anchored in Japanese precision electronics traditions. Tanita occupies a position representing multi-generational sensor development expertise, while InBody sits within the professional-segment archetype focused on multi-frequency bioelectrical impedance systems. Among European modular platform specialists, seca GmbH & Co. KG represents the certification-spanning design approach that bridges fitness and medical market boundaries.
| Leading Market Players |
|---|
| InBody Co., Ltd. |
| Tanita Corporation |
| seca GmbH & Co. KG |
| Omron Healthcare Co., Ltd. |
| Beurer GmbH |
| A&D Company, Limited |
| Bodystat Ltd. |
| Marsden Weighing Group Limited |
| GE Healthcare |
| Others |
Supply Flow & Price Mechanics
FDA 510(k) clearance chokepoints determine both tier spreads and supply chain configuration by forcing manufacturers to front-load regulatory capital, compressing margins for uncertified entrants while concentrating procurement power among pre-cleared suppliers.
Pricing Analysis
Chinese-manufactured precision health electronics compress entry-level pricing by 30-40% against Japanese heritage sensor platforms. Three-tier pricing structure across premium, standard, and economy levels separates FDA-cleared clinical systems from CDSCO-certified tier-2 clinic equipment and uncertified fitness-center imports. Pricing pressure stems from handheld unit substitution capturing volume demand previously flowing to full-platform systems. Fitness centers exhibit highest price sensitivity; bariatric research departments show lowest elasticity due to load cell precision requirements.
Supply Chain Analysis
Precision sensor arrays feed from Nagoya-area electronics clusters, Yangtze River Delta manufacturing corridors, and Shenzhen-based component hubs. Load cell assemblies, multi-frequency impedance modules, and Bluetooth connectivity chipsets constitute critical input dependencies. Single-source vulnerability concentrates in Japanese heritage sensor suppliers for research-grade accuracy standards. Distribution runs through hospital GPO contracts, fitness equipment distributors, and direct municipal procurement channels in Southeast Asian urban districts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Bluetooth-enabled EMR interoperability is transforming BMI machines from standalone hardware into connected diagnostic platform nodes, with subscription-based equipment-as-a-service models displacing capital purchase cycles across corporate wellness programs.
For Market Incumbents: Build regulatory certification moats by front-loading 510(k) pre-submission capital and securing CDSCO IEC 60601-1 alignment ahead of tier-2 clinic network procurement waves. Anchor sensor-software convergence through cloud analytics partnerships to defend against Chinese cost-performance compression. Prioritize calibration service network density to offset technician shortage constraints.
For New Entrants and Emerging Players: Pursue white-space penetration in India's tier-2 urban districts where preventive healthcare infrastructure scaling outpaces certified supplier availability. Target equipment-as-a-service subscription models for Southeast Asian municipal health initiatives seeking operational expenditure flexibility. Leverage Shenzhen electronics cluster cost advantages for mid-tier bioelectrical impedance platforms.
For Investors and Strategic Acquirers: EU MDR reclassification reshapes the acquisition landscape by intensifying post-market surveillance obligations and creating compliance-service revenue streams for certified manufacturers. Long-term viability favors modular platform specialists spanning fitness and medical certifications. Watch FDA accuracy requirement tightening as inflection signal for clinical claim substantiation cost escalation.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Pre-Submission Investment | Front-loaded regulatory capital compresses development timelines for fat-mass estimation claims. |
| CDSCO Certification Pathway | IEC 60601-1 alignment filters uncertified suppliers from India's tier-2 procurement channels. |
| Equipment-as-a-Service Launch | Subscription pricing captures Southeast Asian clinic networks prioritizing OPEX flexibility. |
| Cloud Analytics Integration | Japanese heritage sensor technology paired with EMR workflows defends premium positioning. |
| Calibration Service Network Expansion | Technician density constraints create defensive moats around multi-frequency system maintenance. |
Methodological Framework
The analysis maps smart-connected devices, portable units, floor models, and wall-mounted scanners, each validated through hospital procurement committees, biomedical engineers, fitness center operators, and GPO contracts managers. Primary interviews combined with secondary validation against FDA 510(k) filings, CDSCO import registration databases, EU MDR reclassification notices, and municipal health budget disclosures. Bottom-up equipment shipment tracking triangulates against top-down preventive healthcare infrastructure spending estimates.
Assumptions held fixed include regulatory pathway timelines and electrical safety standardization trajectories, while variables included tier-2 clinic network expansion rates and equipment-as-a-service adoption curves. Segmentation dimensions modeled encompass product architecture, end-user procurement sophistication, technology performance tier, and application regulatory complexity. CAGRs derived from installed base replacement velocity analysis and connected diagnostic budget allocation trends across the analysis window. Forecast inputs incorporated multi-frequency bioelectrical impedance migration patterns and Bluetooth EMR integration penetration rates.
Sensitivities concentrate around FDA accuracy requirement tightening, CDSCO enforcement intensity, and technician calibration expertise availability. Forecasts reflect assumptions about municipal health initiative continuity and corporate wellness program spending stability. Cross-checking against hospital procurement database benchmarks and fitness equipment distributor shipment records is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fitness Equipment
Gym Ball Market
Fitness Equipment
Yoga Mat Market
Fitness Equipment
Elliptical Trainers Market
Fitness Equipment
Yoga Accessories Market
Fitness Equipment
Elliptical Market
Fitness Equipment
Functional Fitness Equipment Market
Fitness Equipment
Yoga and Pilates Mats Market
Fitness Equipment
Lateral Fitness Equipment Market
Fitness Equipment
Indoor Bike Trainers Market
Fitness Equipment
Gym Fitness Accessories Market
Fitness Equipment
Home Fitness Market
Fitness Equipment
Japan Fitness Ring Market
Fitness Equipment
Push-Up Board Market
Fitness Equipment
Recumbent Stationary Bikes Market
Fitness Equipment
Global Jumping Rope Market
Fitness Equipment
US Fitness Rings Market