
 Lung Exercise Machine Market | 2026-2036
Lung Exercise Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Lung Exercise Machine Market Foresight
Asset-light leasing models for pulmonary rehabilitation equipment is narrowing the capital barrier for clinic chains and home-care distributors. Ambitech Healthcare leverages its manufacturing scale to serve bulk institutional contracts across South Asian markets. Wonder Healthcare competes through specialized airway resistance trainers designed for post-operative protocols. Equinox anchors its position in sports training channels with electronic feedback devices.
A lung exercise machine is a respiratory therapy device that generates calibrated airflow resistance or volume targets, typically measured in milliliters per second or cubic centimeters, to strengthen diaphragmatic and intercostal muscles. Its primary purpose is to improve inspiratory capacity, reduce atelectasis risk, and accelerate recovery from thoracic surgery or chronic obstructive conditions. Incentive spirometers occupy the largest installed base among product types due to low unit cost and standardized hospital procurement protocols. Smart devices represent the fastest-expanding technology segment as Bluetooth-enabled spirometry data integrates with remote patient monitoring platforms. Home users command growing attention from manufacturers seeking recurring revenue through consumable mouthpiece attachments.
The US FDA classifies incentive spirometers and positive pressure devices under 510(k) premarket notification requirements, while the EU Medical Device Regulation mandates clinical evidence for electronic lung trainers sold in European markets. ISO 13485 certification governs quality management systems for manufacturers distributing across multiple jurisdictions. Stakeholders must weigh reimbursement code alignment against the cost of connected-device compliance before committing to regional expansion strategies.
Market Dynamics
Remote patient monitoring reimbursement codes are accelerating hospital procurement of connected lung exercise devices, compressing the traditional three-year equipment replacement cycle toward annual software-enabled upgrades.
Growth Catalysts
- Post-operative pulmonary complication protocols:Thoracic surgery departments in US academic medical centers now mandate incentive spirometry for all lobectomy patients, creating institutional purchasing velocity.
- EU Medical Device Regulation clinical evidence requirements:MDR Article 61 is elevating entry barriers for low-quality competitors, concentrating demand among ISO 13485-certified manufacturers with established clinical data packages.
- Bluetooth Low Energy integration:Wireless spirometry data transmission is enabling automated documentation in electronic health records, reducing nursing documentation burden by eliminating manual peak flow transcription.
Market Restraints
- Medical-grade silicone mouthpiece cost volatility:Supply constraints in Malaysian rubber processing facilities are inflating consumable input costs for disposable airway components.
- Single-source dependency for precision pressure sensors:German MEMS foundries control critical airflow measurement chip supply, creating geographic concentration risk for electronic device assemblers.
- Reimbursement code fragmentation:Inconsistent CPT coding across US Medicare Administrative Contractors forces manufacturers to maintain multiple product SKUs for identical clinical functions.
Strategic Opportunities
- Pediatric cystic fibrosis home monitoring:Underpenetrated patient populations in France and the Netherlands present whitespace for gamified breathing exercise platforms with parental dashboards.
- US Center for Medicare and Medicaid Innovation bundled payment pilots:Episode-based reimbursement for chronic obstructive pulmonary disease is incentivizing health systems to invest in pre-hospitalization respiratory muscle training.
- Convergence of respiratory therapy and sleep medicine:Integration of positive airway pressure algorithms into lung exercise hardware is opening crossover sales to obstructive sleep apnea clinics.
Industry Challenges
- Firmware validation for FDA 510(k) submissions:Software-as-a-medical-device classification is extending quality assurance timelines and requiring specialized regulatory affairs talent.
- Legacy hospital IT system interoperability:HL7 FHIR integration with proprietary electronic health record architectures demands custom engineering resources at each major health system deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lung Exercise Machine Market |
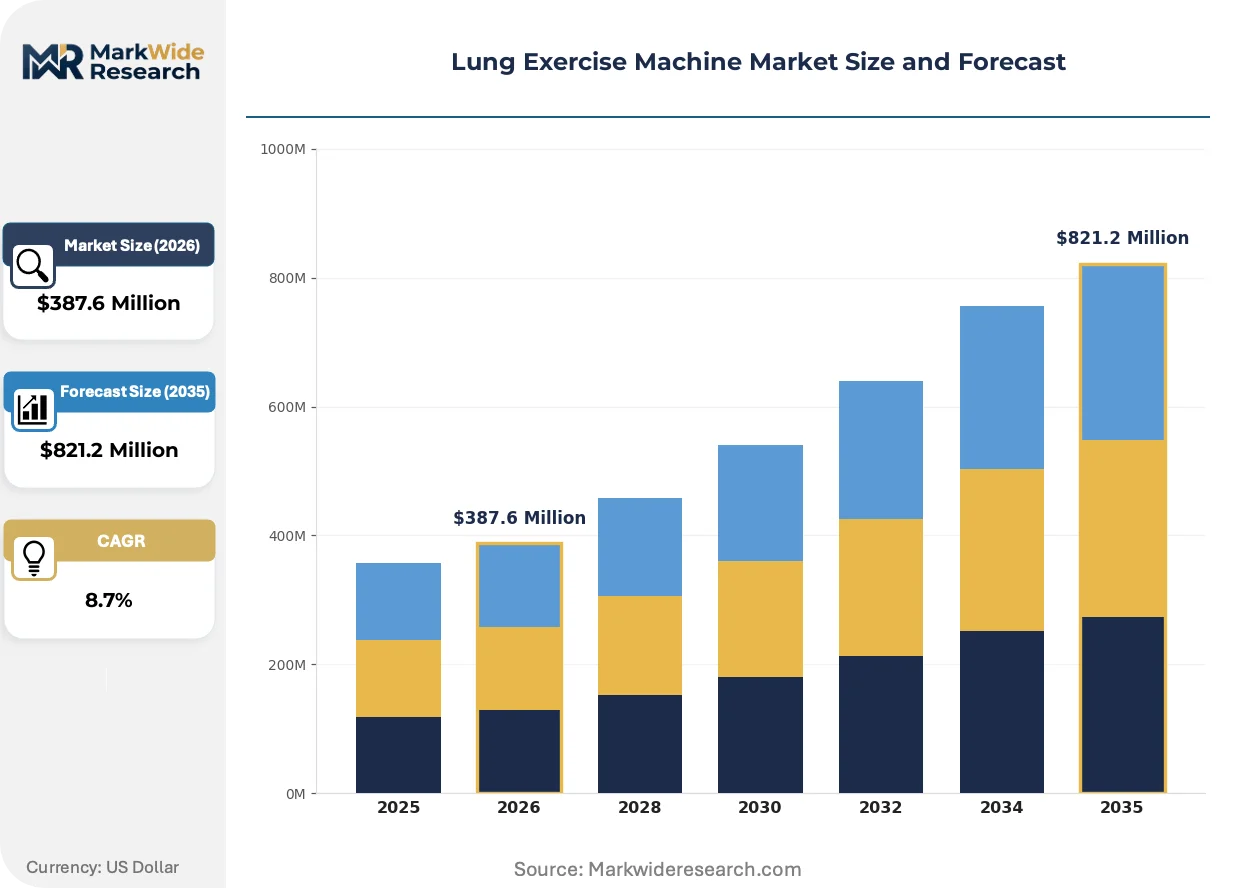
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $821.2 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Incentive Spirometers, Positive Pressure Devices, Breathing Trainers, Airway Resistance Trainers Application: Rehabilitation, Sports Training, Home Care, Post-operative Recovery End User: Hospitals, Physiotherapy Clinics, Sports Centers, Home Users Technology: Manual Devices, Electronic Devices, Smart Devices, Portable Devices |
| Companies Covered | Ambitech Healthcare, Angiplast, AuFlex, Sahyog Wellness, Wonder Healthcare, Equinox, Control D, Blue Echo Care, Life Health Wellness, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lung Exercise Machine Market Shifts & Advancements
Sensor miniaturization and cloud analytics are redefining how respiratory muscle training is prescribed, monitored, and reimbursed across ambulatory and acute care settings.
Microelectromechanical systems (MEMS) flow sensors are replacing mechanical ball-in-tube spirometers in next-generation devices. Pulmonary rehabilitation clinics in Germany and Japan are adopting these solid-state platforms for their calibration stability and Bluetooth connectivity. The technology is collapsing the price-performance gap between hospital-grade and home-use respiratory trainers.
The EU Medical Device Regulation's post-market surveillance requirements are mandating systematic clinical follow-up for electronic lung exercise devices sold in European markets. Manufacturers must now maintain vigilance databases tracking device performance across real-world use conditions. This regulatory architecture is favoring established players with dedicated pharmacovigilance infrastructure over new market entrants.
Direct-to-patient subscription models are disrupting traditional durable medical equipment distribution channels. Home-care distributors in the US are unbundling device provision from clinical training, instead offering telehealth-guided onboarding as a recurring service. This consumption-pattern shift is most visible in Medicare Advantage plans with supplemental respiratory therapy benefits.
Lung Exercise Machine Market Segmentation
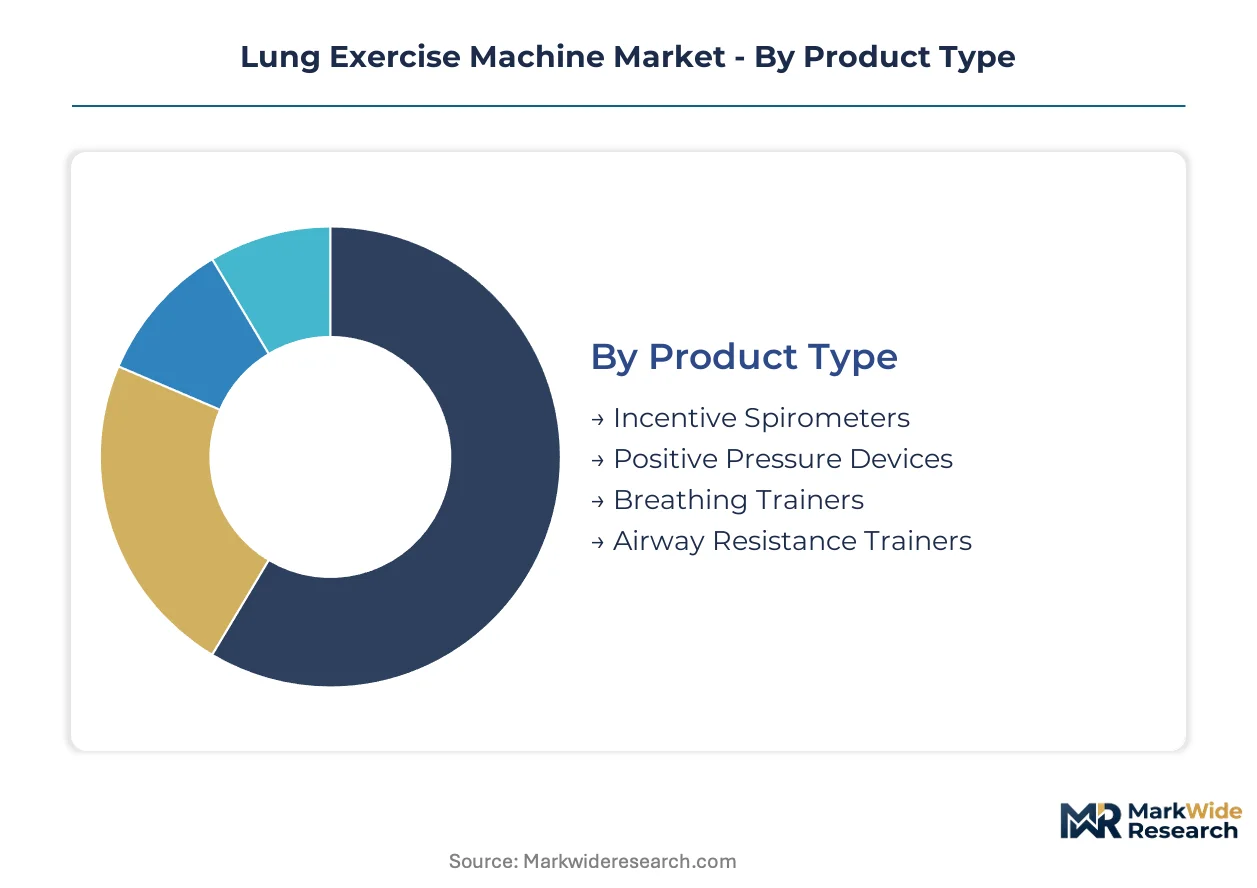
Segmentation in the lung exercise machine market reveals distinct procurement patterns across clinical and consumer channels. Product type and technology maturity determine reimbursement eligibility, while end-user concentration shapes distribution infrastructure requirements.
Product Type:
Mature mechanical formats coexist with emerging electronic platforms, creating a bifurcated supply base serving divergent price-performance requirements.
- Incentive Spirometers:Ball-in-tube or piston-based devices generating visual feedback through volume displacement, typically calibrated to 4000 mL capacity. US academic medical centers mandate these for all lobectomy patients, creating institutional purchasing velocity through standardized protocols.
- Positive Pressure Devices:Threshold resistor systems generating calibrated expiratory resistance through spring-loaded valves. German rehabilitation clinic networks concentrate demand for these units in pulmonary rehabilitation programs, driven by statutory reimbursement for COPD maintenance therapy.
- Breathing Trainers:Volume-oriented devices targeting respiratory muscle endurance through sustained inspiratory loading.
- Airway Resistance Trainers:Adjustable orifice systems modulating airflow turbulence for targeted muscle group isolation.
Incentive spirometers retain volume leadership; smart-enabled positive pressure devices hold the steepest expansion curve.
Application:
Cost tier stratification separates reimbursed clinical indications from discretionary consumer purchases, with distinct margin structures governing each tier.
- Rehabilitation:Structured protocols in outpatient pulmonary programs utilizing calibrated resistance progression. Germany's statutory health insurance system reimburses these interventions, concentrating demand in accredited clinic networks.
- Post-operative Recovery:Prophylactic protocols preventing atelectasis following thoracic or abdominal surgery. US hospital systems bundle these devices into surgical episode payments, driving bulk procurement through materials management departments.
- Sports Training:Discretionary purchase by elite athletes and fitness enthusiasts seeking respiratory performance optimization.
- Home Care:Unsupervised use by chronic respiratory patients managing conditions outside clinical settings.
Post-operative recovery commands the largest reimbursed volume; home care applications are climbing the fastest as remote monitoring infrastructure matures.
End User:
Customer type determines regulatory pathway complexity, with institutional buyers demanding ISO 13485 certification and home users prioritizing connectivity features.
- Hospitals:Acute care facilities procuring through group purchasing organizations with standardized technical specifications. US FDA 510(k) clearance remains mandatory for institutional adoption.
- Home Users:Individual consumers purchasing through durable medical equipment suppliers or direct-to-patient channels. Medicare Advantage plans with supplemental respiratory benefits are accelerating subscription-based distribution models.
- Physiotherapy Clinics:Outpatient rehabilitation facilities maintaining device inventories for supervised patient sessions.
- Sports Centers:Training facilities incorporating respiratory devices into athlete conditioning programs.
Hospitals dominate institutional procurement value; home users represent the fastest-expanding addressable base.
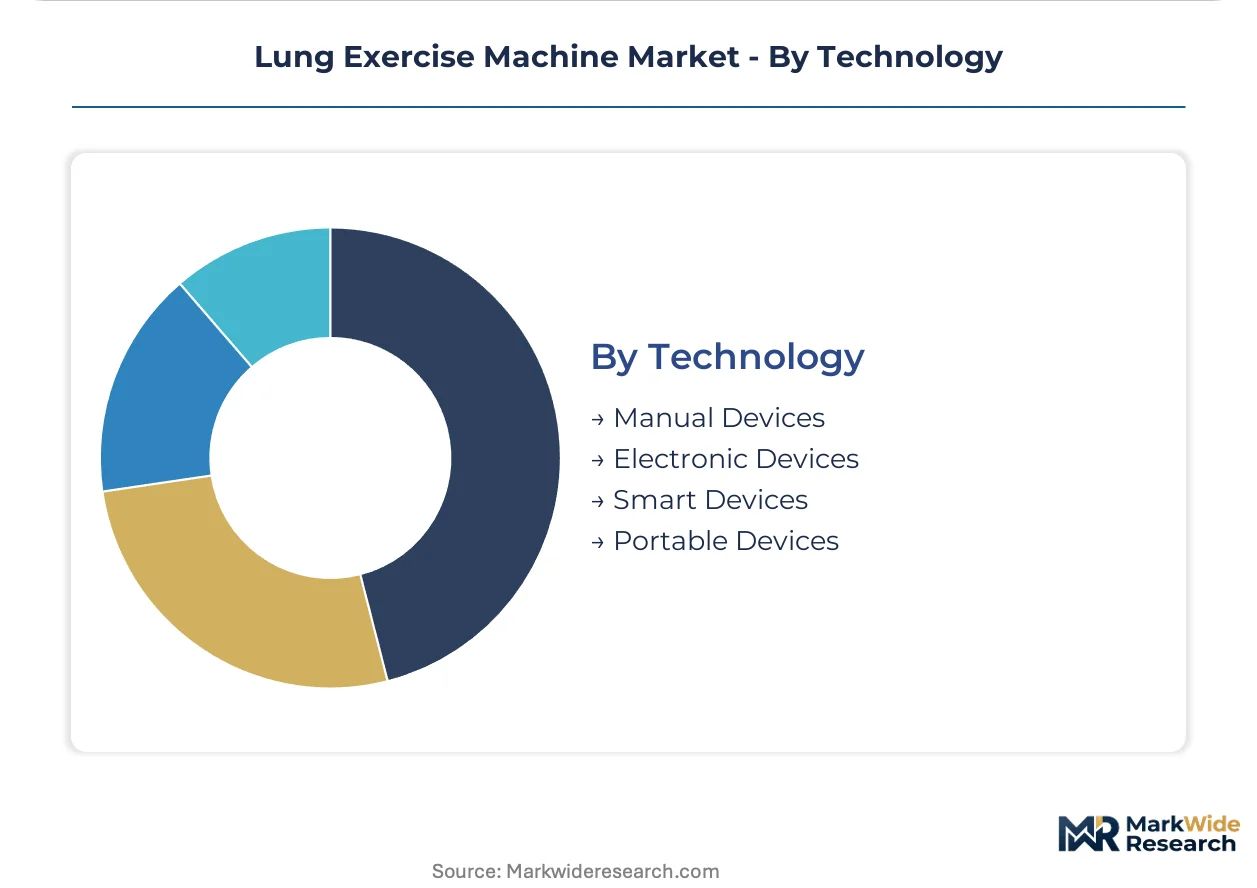
Technology:
Supply concentration in MEMS sensor fabrication and Bluetooth module sourcing favors assemblers with established electronics manufacturing partnerships.
- Manual Devices:Mechanical platforms without electronic components, offering calibration stability and zero firmware validation burden. These systems bypass FDA software-as-a-medical-device classification requirements.
- Smart Devices:Bluetooth-enabled platforms transmitting spirometry data to remote patient monitoring dashboards. HL7 FHIR integration capabilities are becoming mandatory for US hospital procurement committees.
- Electronic Devices:Microprocessor-controlled units with digital displays and programmable resistance profiles.
- Portable Devices:Compact formats optimized for travel and ambulatory use cases.
Manual devices retain installed base dominance; smart devices are gaining share fastest as reimbursement codes align with connected-care documentation requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's statutory health insurance reimbursement for COPD maintenance therapy anchors European procurement volumes for positive pressure devices. The US FDA's 510(k) clearance pathway shapes product entry timelines for institutional buyers. Japan's aging demographic accelerates home-care adoption of Bluetooth-enabled spirometry platforms.
United States
Academic medical centers mandate incentive spirometry for all lobectomy patients, creating institutional purchasing velocity through standardized protocols. The FDA classifies these devices under 510(k) premarket notification requirements. Hospital systems in the Northeast Corridor bundle respiratory trainers into surgical episode payments, compressing replacement cycles toward annual upgrades.
Germany
Rehabilitation clinic networks concentrate demand for positive pressure devices driven by statutory reimbursement frameworks. The EU Medical Device Regulation's Article 61 elevates entry barriers through clinical evidence requirements. Manufacturing clusters in Baden-Württemberg host ISO 13485-certified assemblers serving bulk institutional contracts across European markets.
Japan
Pulmonary rehabilitation clinics adopt MEMS-based solid-state platforms for calibration stability and wireless connectivity. METI guidelines on digital health device integration influence procurement specifications for connected-care infrastructure. Tokyo's metropolitan hospital networks pilot automated documentation systems reducing nursing transcription burden.
India
Home-care distributors expand asset-light leasing models narrowing capital barriers for chronic respiratory patients. CDSCO medical device registration requirements govern product entry timelines for electronic lung trainers. Manufacturing scale in South Asian markets serves bulk institutional contracts through regional production hubs.
France
Pediatric cystic fibrosis home monitoring presents whitespace for gamified breathing exercise platforms with parental dashboards. ANSM vigilance requirements mandate systematic clinical follow-up for electronic devices sold in French markets. Parisian rehabilitation centers integrate respiratory muscle training into bundled chronic disease management protocols.
Lung Exercise Machine Market Competitive Landscape
On the supply side, the industry is bifurcated between mechanical device specialists and electronics-integrated platform developers. Tiered competitive positioning separates ISO 13485-certified manufacturers with established clinical data packages from unvalidated entrants. Three strategic archetypes dominate: manufacturing-scale contract suppliers, specialized airway resistance trainers, and sports-channel electronic feedback providers. Competitive moves concentrate on M&A for regulatory compliance capabilities and strategic partnerships for MEMS sensor sourcing.
Within the manufacturing-scale tier, Ambitech Healthcare exemplifies bulk institutional contract suppliers serving South Asian markets. Wonder Healthcare occupies a position among specialized airway resistance trainer developers focused on post-operative protocols. Equinox anchors the sports-training channel with electronic feedback device representation. These three companies illustrate the geographic and application-based segmentation governing competitive positioning across clinical and consumer market vectors.
| Leading Market Players |
|---|
| Ambitech Healthcare |
| Angiplast |
| AuFlex |
| Sahyog Wellness |
| Wonder Healthcare |
| Equinox |
| Control D |
| Blue Echo Care |
| Life Health Wellness |
| Others |
Supply & Pricing Matrix
Shanghai-to-Rotterdam container freight volatility is compressing margins for European distributors of electronic lung exercise devices while amplifying price spreads between ISO 13485-certified manufacturers and uncertified competitors. This corridor's cost swings concentrate procurement power among hospital group purchasing organizations with multi-year contract leverage.
Pricing Analysis
Certification level creates the primary spread across the lung exercise machine market, with FDA 510(k)-cleared and MDR Article 61-compliant devices commanding substantial premiums over uncertified alternatives. Three-tier pricing structure across premium, standard, and economy levels reflects this stratification, with premium tiers bundling Bluetooth connectivity and HL7 FHIR integration. Cost compression in the economy tier is intensifying because Malaysian rubber processing constraints are inflating medical-grade silicone mouthpiece input costs. Home users through direct-to-patient subscription channels exhibit the highest price sensitivity, while US academic medical centers with bundled surgical episode payments demonstrate the lowest.
Supply Chain Analysis
German MEMS foundry export controls on precision pressure sensor technology are restricting component flows to electronic device assemblers outside established trade partnerships. Manufacturing concentrates in Germany, Malaysia, and China, with German facilities supplying critical airflow measurement chips, Malaysian processors dominating medical-grade silicone production, and Chinese assemblers serving volume production for South Asian markets. Supply chain risk centers on single-source dependency for MEMS sensors from Baden-Württemberg facilities. Distribution runs through hospital group purchasing organizations in North America, statutory reimbursement-accredited clinic networks in Germany, and direct-to-patient subscription platforms for home care segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The lung exercise machine market is entering a cyclical recovery phase as post-operative pulmonary complication protocols expand across US academic medical centers and EU MDR compliance costs force competitor consolidation.
For Market Incumbents: Pre-empt firmware validation bottlenecks by building dedicated regulatory affairs capabilities ahead of FDA software-as-a-medical-device classification expansion. Secure captive supply of precision pressure sensors through backward integration into German MEMS foundry partnerships or long-term offtake agreements. Consolidate position in pediatric cystic fibrosis home monitoring before gamified platform entrants establish parental dashboard loyalty. For New Entrants and Emerging Players: Mid-market physiotherapy clinics in France and the Netherlands represent the most penetrable entry point for MDR-compliant electronic trainers with simplified clinical evidence packages. Pediatric home monitoring applications with gamified breathing exercise platforms offer whitespace with lower incumbent saturation than hospital procurement channels. A telehealth-guided onboarding service model bypasses capital-intensive durable medical equipment distribution infrastructure. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified medical device conglomerates with underinvested respiratory therapy divisions lacking dedicated pharmacovigilance infrastructure. Long-term viability over the next decade hinges on regulatory compliance capability depth rather than manufacturing scale alone. Watch for bundled payment pilot expansion signals from the US Center for Medicare and Medicaid Innovation as inflection indicators for health system respiratory muscle training investment velocity.| Strategic Initiative | Industry Significance |
|---|---|
| MDR Article 61 Compliance Investment | Clinical evidence packages from ISO 13485-certified manufacturers now gate European market access. |
| Bluetooth Low Energy Platform Development | Wireless spirometry data transmission enables automated EHR documentation in US hospital systems. |
| Hospital System Partnership | Academic medical center procurement committees mandate HL7 FHIR integration for connected device adoption. |
| Software Companion Development | Gamified breathing exercise platforms with parental dashboards target underpenetrated pediatric cystic fibrosis populations. |
| Reimbursement Strategy Alignment | CPT code harmonization across Medicare Administrative Contractors reduces SKU proliferation for identical clinical functions. |
Research Methodology
A standing panel of hospital purchasing committee members, biomedical engineers, GPO contracts managers, and pulmonary rehabilitation clinicians provided ongoing calibration for demand assumptions. This primary fieldwork combined with secondary validation against FDA 510(k) filings, EU MDR vigilance databases, hospital procurement records, and CMS Medicare reimbursement code directories. Bottom-up unit economics triangulated against top-down market sizing across product type, application, end user, and technology segmentation dimensions.
Scenario-bracketing anchored projections across the analysis window, with growth rates derived from procedure volume trends in thoracic surgery, COPD prevalence modeling, and remote patient monitoring reimbursement expansion trajectories. Segmentation dimensions modeled include product format, clinical indication, care setting, connectivity tier, and regional regulatory cluster. Forecast inputs incorporated MEMS sensor supply constraints, Malaysian rubber processing capacity, and EU MDR post-market surveillance cost structures.
Practitioners should monitor FDA software-as-a-medical-device classification scope expansion and German MEMS foundry export control adjustments for early signals of forecast revision triggers. Material shifts in bundled payment pilot adoption rates or Malaysian medical-grade silicone supply disruption severity would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fitness Equipment
Fitness Ball Market
Fitness Equipment
Gym Ball Market
Fitness Equipment
North America Exercise Bike Market
Fitness Equipment
Saudi Arabia Outdoor Fitness Equipment Market
Fitness Equipment
India Fitness Ring Market
Fitness Equipment
Exercise Resistance Bands Market
Fitness Equipment
Yoga and Exercise Mats Market
Fitness Equipment
China Outdoor Fitness Equipment Market
Fitness Equipment
Smart Scales Market
Fitness Equipment
Resistance Bands Market
Fitness Equipment
Exercise Band Market
Fitness Equipment
Push-Up Board Market
Fitness Equipment
Strength Training Equipment Market
Fitness Equipment
North America Home Fitness Equipment Market
Fitness Equipment
Ergometer Market
Fitness Equipment
Home Fitness Equipment Market