
 Gym Fitness Accessories Market | 2026-2036
Gym Fitness Accessories Market Size, Share, and Industry Trends Forecast 2026-2036
Gym Fitness Accessories Market Insights
Market Context
Premium commercial-grade specifications are rotating into mainstream consumer channels as home gym setups mature and durability expectations rise. Eleiko Group AB leverages its Olympic-certification heritage to anchor pricing power in the high-performance barbell segment. Rogue Fitness sustains manufacturing scale through in-house steel forging operations in Columbus, Ohio. Life Fitness competes across integrated cardio-strength ecosystems in commercial club chains.
Technical Definition and Segment Structure
Gym fitness accessories encompass resistance-training implements, recovery tools, and mobility aids fabricated from vulcanized rubber, cold-rolled steel, open-cell foam, or woven cotton, typically engineered to withstand cyclic loading between 500 and 50,000 repetitions depending on product class. Their primary commercial purpose centers on enabling progressive overload, movement preparation, and tissue recovery across individual and institutional training environments. Weights and resistance bands command the largest revenue pools due to universal applicability across strength protocols, while yoga mats and foam rollers extract premium margins in the direct-to-consumer channel where material certifications and sustainability claims differentiate positioning. Online retail is displacing specialty stores as the dominant distribution vector, though wholesalers retain volume leverage with gym chains.
Regulatory Frame and Outlook
REACH in Europe restricts phthalates and heavy metals in rubber compounds, compelling reformulation of resistance bands and bumper plates. The EU Green Deal and emerging state-level extended producer responsibility frameworks in California and Germany are shifting cost structures toward recyclable material sourcing. China's GB standards for sports equipment safety and the FDA's oversight of antimicrobial claims in foam products create multi-jurisdictional compliance complexity. Stakeholders must monitor evolving chemical disclosure requirements and carbon-border adjustment mechanisms to preserve market access across premium and economy tiers.
Market Dynamics
REACH and RoHS compliance in Europe is elevating material standards for rubber and foam products, forcing reformulation across the supply chain and compressing margins for manufacturers dependent on legacy phthalate-based compounds.
Growth Catalysts
- REACH chemical restrictions:European ECHA mandates on phthalate elimination in rubber compounds are accelerating premium material adoption as manufacturers invest in bio-based alternatives to preserve EU market access.
- Boutique studio expansion:Hybrid training facilities in the United States are procuring commercial-grade equipment for home delivery, extending institutional durability standards into residential channels.
- Antimicrobial foam integration:FDA-registered antimicrobial claims in recovery rollers are commanding shelf-space priority in pharmacy and medical retail channels.
Market Restraints
- Natural rubber price volatility:Southeast Asian latex supply disruptions and climate-induced harvest variability are compressing margins for resistance band and bumper plate manufacturers.
- Steel forging concentration:Cold-rolled steel barbell production clusters heavily in Ohio and Shandong Province, creating geographic single-point-of-failure exposure.
- Extended producer responsibility:California's emerging mattress and foam take-back regulations are imposing end-of-life cost liabilities on yoga mat producers before infrastructure exists.
Strategic Opportunities
- German sustainability premiums:EU Green Deal carbon-border adjustments are creating first-mover advantage for recyclable TPE mat producers serving environmentally segmented consumers.
- Connected resistance systems:Force-sensor integration with mobile coaching platforms is opening subscription revenue models for smart band manufacturers.
- Medical rehabilitation channel:Physical therapy clinic chains are standardizing procurement around CE-marked mobility aids, creating institutional certification pathways.
Industry Challenges
- Vulcanization chemistry expertise:Reformulating rubber compounds for REACH compliance without sacrificing cyclic durability requires polymer scientists in short supply across mid-tier manufacturers.
- Multi-jurisdictional certification timelines:Simultaneous FDA antimicrobial, CE marking, and China GB compliance for foam products extends product launch cycles by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gym Fitness Accessories Market |
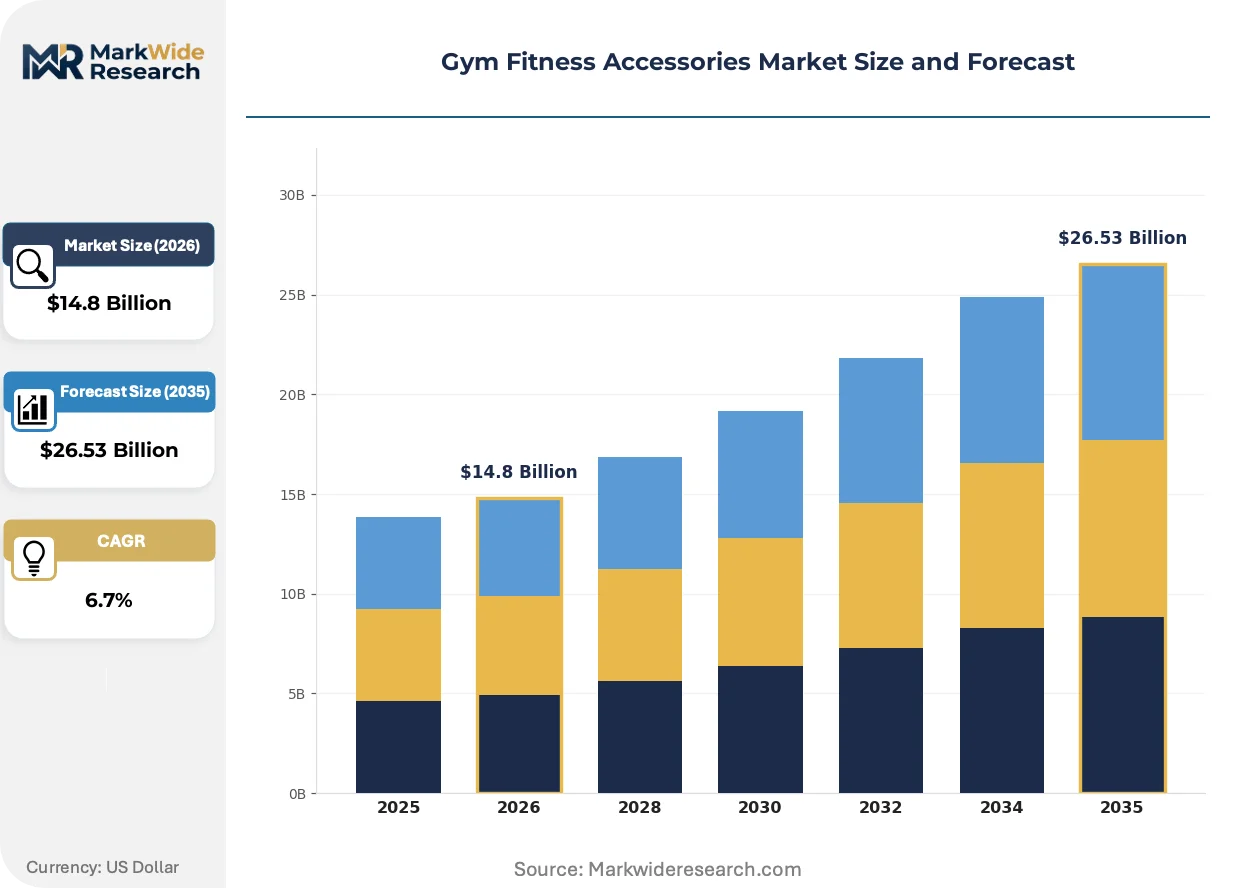
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $26.53 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Weights, Resistance Bands, Foam Rollers, Yoga Mats Material: Rubber, Steel, Foam, Cotton End User: Individuals, Fitness Enthusiasts, Trainers, Gyms Distribution Channel: Online Retail, Specialty Stores, Supermarkets, Wholesalers |
| Companies Covered | Core Health & Fitness, LLC, Life Fitness, Coulter Ventures, LLC (Rogue Fitness), Eleiko Group AB, Concept2, Inc., Body Solid Incorporated, JERAI Fitness Pvt Ltd., Hammer Sport AG, ANTA Sports Products Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gym Fitness Accessories Market Trends and Innovations
Material science advances and regulatory chemistry mandates are converging to reshape product architecture, with sustainability credentials and connected functionality emerging as the primary vectors of differentiation.
Thermoplastic elastomer (TPE) formulations with closed-cell density below 0.15 g/cm³ are supplanting PVC and natural rubber in yoga mat production due to recyclability and odor-free performance. Premium studio chains in Germany and California are specifying TPE exclusively for new procurement. This material transition is compressing margins for incumbent PVC processors while rewarding compounders with bio-based TPE pilot lines.
EU Green Deal extended producer responsibility frameworks are mandating recyclable content minimums and carbon footprint disclosure for fitness accessories sold in member states. Manufacturers are reconfiguring supply chains toward European TPE compounding and regional molding to reduce transport emissions. Yoga mat and foam roller segments face the steepest compliance cost escalation due to polymer intensity and short product lifecycles.
Boutique fitness chains are consolidating equipment procurement through direct manufacturer relationships, bypassing traditional wholesale distributors. Life Fitness and Rogue Fitness have established dedicated commercial sales divisions serving Equinox and Barry's Bootcamp directly. This channel compression is most advanced in the United States and United Kingdom, where studio concentration and private equity ownership enable centralized purchasing authority.
Gym Fitness Accessories Market Segmentation
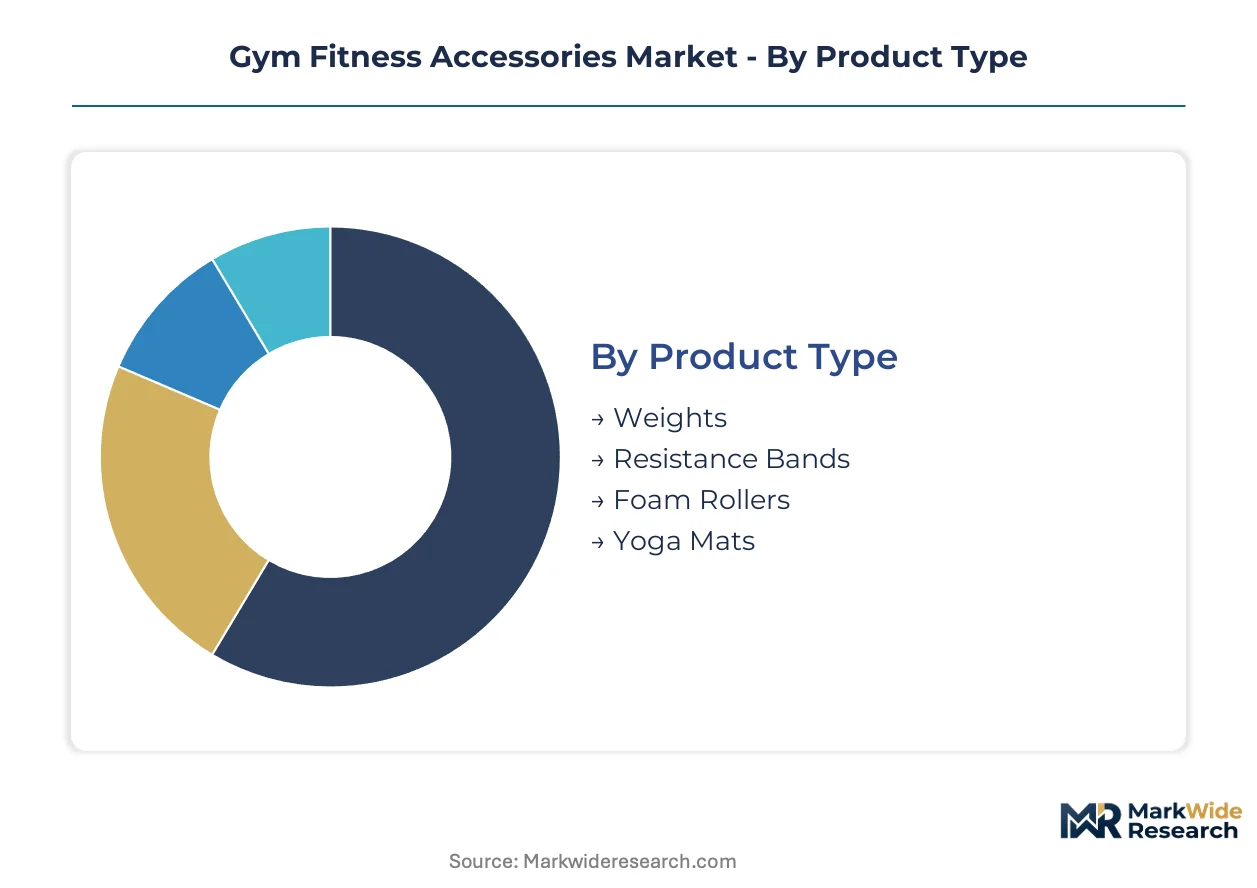
Segmentation in gym fitness accessories reveals how durability standards, material chemistry, and channel economics concentrate profit pools differently across product classes. Understanding these fault lines exposes where procurement power sits and which specifications command sustainable pricing premiums.
Product Type:
Margin pools concentrate in categories where commercial-grade specifications translate into residential willingness-to-pay, and where material intensity creates defensible sourcing advantages.
- Weights:Cold-rolled steel and cast iron implements, including barbells, dumbbells, and plate systems, engineered for cyclic loading exceeding 50,000 repetitions. Demand clusters in the United States and Germany where home gym maturation has elevated durability expectations toward institutional standards. Eleiko and Rogue Fitness anchor pricing power through Olympic-certification heritage and in-house forging operations.
- Resistance Bands:Vulcanized rubber or latex elastic implements providing variable resistance across tensile strength ratings from 5 to 150 pounds. Boutique studio expansion in California and New York is extending commercial procurement volumes into hybrid home delivery models, compressing wholesale distributor leverage.
- Foam Rollers:EVA or EPP foam cylinders for myofascial release, with antimicrobial FDA-registered variants commanding pharmacy channel priority. Physical therapy clinic chains in Germany are standardizing CE-marked procurement.
- Yoga Mats:TPE, PVC, or natural rubber surfaced mats with closed-cell density specifications, where EU Green Deal recyclability mandates are restructuring compounder relationships toward bio-based alternatives.
The dominant share belongs to Weights, while Resistance Bands is closing the gap fastest through studio-to-home channel extension.
Material:
Cost tier stratification follows raw material volatility and regulatory compliance burden, with premium positioning accruing to compounds that satisfy REACH phthalate restrictions without sacrificing performance.
- Rubber:Vulcanized natural and synthetic latex compounds for bands, bumper plates, and flooring, facing Southeast Asian supply disruption and ECHA-mandated reformulation timelines. Compounders with bio-based pilot lines capture German sustainability premiums.
- Steel:Cold-rolled and forged carbon steel for load-bearing implements, with production gravity in Ohio and Shandong Province creating geographic concentration risk. In-house forging capabilities at Rogue Fitness and Eleiko insulate margin compression.
- Foam:Open-cell and closed-cell polyurethane, EVA, and EPP formulations for rollers and mats, where FDA antimicrobial registration extends launch cycles but unlocks medical retail placement.
- Cotton:Woven and braided natural fiber for straps, belts, and suspension trainers, extracting artisan positioning in direct-to-consumer channels but facing volume constraints against synthetic alternatives.
Rubber commands the volume base, though Steel retains the steepest pricing power through forging capability scarcity.
End User:
Application intensity varies dramatically across user types, with institutional procurement consolidating around durability specifications that residential buyers increasingly mimic.
- Individuals:Residential consumers purchasing through online retail, where review velocity and material certification claims drive conversion. California and Texas postcodes show highest per-capita expenditure on premium TPE mat configurations.
- Fitness Enthusiasts:Serious amateur athletes with hybrid gym-home routines, demanding commercial-grade specifications in residential quantities. This segment pays steepest premiums for Olympic-certification heritage and connected sensor integration.
- Trainers:Independent and studio-affiliated professionals procuring portable equipment kits, where brand association and warranty terms influence selection. Direct manufacturer relationships are displacing wholesale intermediaries.
- Gyms:Commercial clubs and boutique studios with centralized procurement authority, standardizing around lifecycle cost rather than upfront price. Equinox and Barry's Bootcamp in the United States negotiate direct with Rogue Fitness and Life Fitness.
Gyms anchor institutional volume, while Fitness Enthusiasts is expanding most quickly as home gym investment persists post-pandemic.
Distribution Channel:
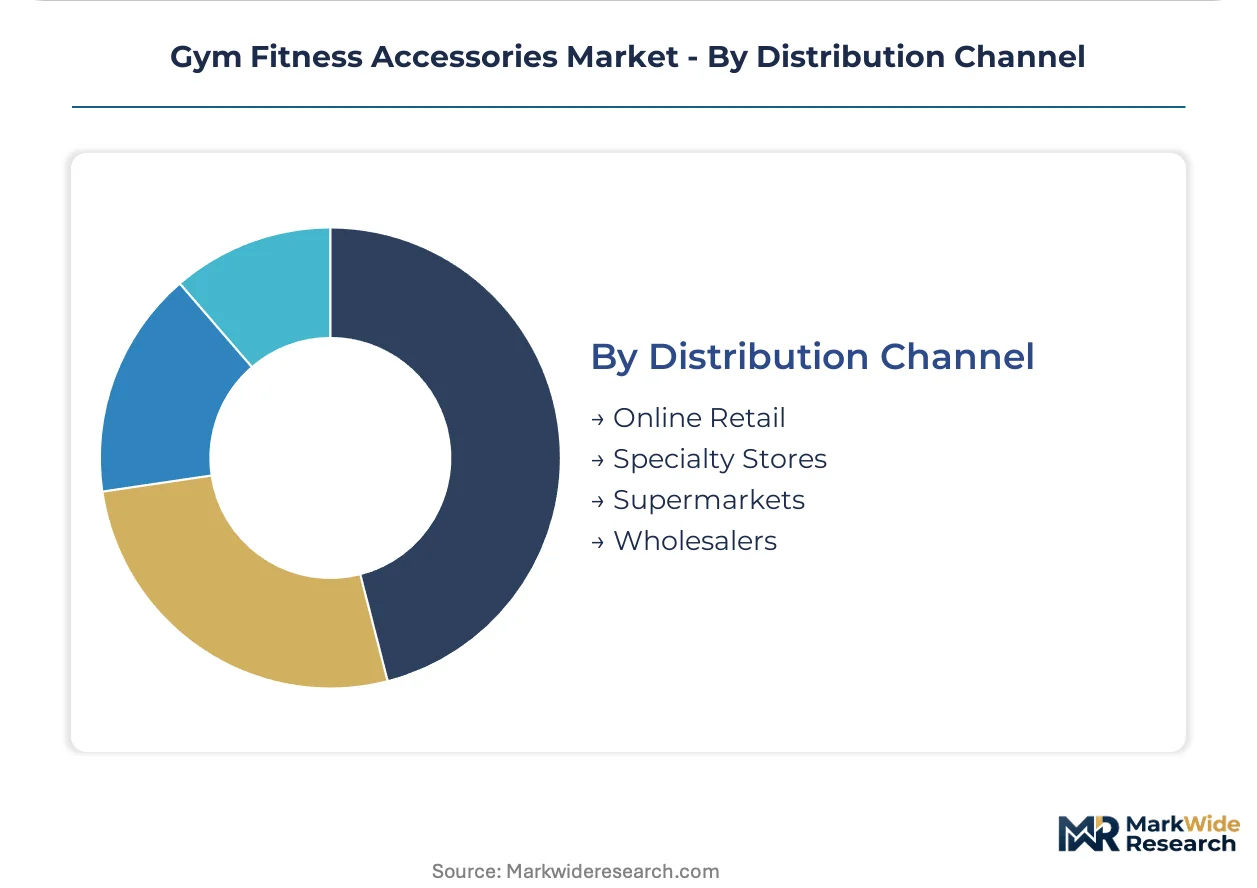
Channel economics are compressing as manufacturer-direct relationships with studio chains and platform algorithms displace traditional wholesale and specialty retail.
- Online Retail:E-commerce platforms and direct-to-consumer brand sites, now dominant vector for residential procurement. Amazon and brand-owned storefronts in the United States and Germany capture search-driven purchase intent.
- Specialty Stores:Dedicated fitness equipment retailers with consultative sales staff, retaining relevance for high-consideration barbell and rack systems but losing share in accessories.
- Supermarkets:Mass-market retail with impulse-accessory placement, moving volume in resistance bands and entry-level mats at compressed margins.
- Wholesalers:Traditional distributors serving independent gyms and municipal facilities, facing disintermediation as boutique chains consolidate procurement authority.
Online Retail holds the volume lead, though Wholesalers retain leverage with municipal and independent club segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cold-rolled steel forging for load-bearing implements clusters in Columbus, Ohio and Shandong Province, while TPE compounding for yoga mats migrates toward German and Californian facilities to satisfy EU Green Deal carbon-border requirements.
United States
Boutique fitness chains in New York and California are consolidating procurement authority through direct manufacturer relationships, bypassing wholesale distributors. The FDA regulates antimicrobial claims in foam recovery products, extending registration timelines for rollers targeting pharmacy channels. Rogue Fitness maintains in-house steel forging operations in Columbus, Ohio, insulating barbell production from supply disruption.
Germany
Physical therapy clinic chains are standardizing procurement around CE-marked mobility aids, creating institutional certification pathways for foam roller manufacturers. ECHA REACH restrictions on phthalates in rubber compounds are accelerating bio-based alternative adoption among resistance band producers. Premium studio chains in Bavaria and North Rhine-Westphalia specify TPE yoga mats exclusively to satisfy EU Green Deal recyclability mandates.
China
GB standards for sports equipment safety are creating multi-jurisdictional compliance complexity for exporters serving European and North American markets. Shandong Province hosts concentrated cold-rolled steel barbell production, creating geographic single-point-of-failure exposure. ANTA Sports Products leverages domestic scale to supply mid-tier resistance bands and accessories across Asia-Pacific distribution channels.
India
JERAI Fitness anchors domestic manufacturing of institutional-grade strength equipment for South Asian gym chains and municipal facilities. BIS certification requirements for sports equipment safety are elevating quality standards for rubber and foam products entering organized retail. Maharashtra and Gujarat host emerging compounder operations serving TPE mat exporters targeting European sustainability premiums.
Gym Fitness Accessories Market Competitive Landscape
Concentration sits with heritage-certified specialists and vertically integrated fabricators, while mid-tier compounders face margin compression from regulatory reformulation costs. Olympic-certification heritage and in-house forging capabilities define pricing power in barbell segments. Three archetypes dominate: Olympic-certification heritage brands, in-house forging operators, and multi-category fitness ecosystem providers. Capacity expansion in TPE compounding and strategic partnerships with boutique studio chains represent the dominant competitive moves.
Within the heritage-certification tier, Eleiko Group AB exemplifies pricing power anchored in Olympic-standard barbell heritage, while Rogue Fitness occupies a position as an in-house forging operator with captive steel production. Among multi-category ecosystem providers, Life Fitness represents integrated cardio-strength positioning across commercial club chains. These three anchors illustrate how capability scarcity in forging and certification translates into sustainable margin structures.
| Leading Market Players |
|---|
| Core Health & Fitness, LLC |
| Life Fitness |
| Coulter Ventures, LLC (Rogue Fitness) |
| Eleiko Group AB |
| Concept2, Inc. |
| Body Solid Incorporated |
| JERAI Fitness Pvt Ltd. |
| Hammer Sport AG |
| ANTA Sports Products Limited |
| Others |
Pricing and Supply Chain Analysis
TPE mat formulations displacing PVC and natural rubber in yoga mat production are simultaneously relocating compounding operations toward German and Californian facilities to satisfy EU Green Deal carbon-border requirements while compressing margins for incumbent PVC processors unable to pivot material chemistry. This substitution dynamic concentrates pricing power with compounders possessing bio-based pilot lines and regional molding capabilities, while forcing legacy manufacturers to absorb reformulation costs or exit premium tier positioning.
Pricing Analysis
REACH chemical restrictions dictate the pricing tier structure across rubber and foam accessories, with ECHA-mandated phthalate elimination creating a three-tier pricing structure across premium, standard, and economy levels. Price differentiation rests on certification grade—specifically ECHA compliance documentation and FDA antimicrobial registration—and volume scale for institutional procurement. Cost compression in economy-tier resistance bands is intensifying because Southeast Asian latex supply disruptions compound reformulation timelines. Boutique studio chains exhibit lowest price sensitivity due to lifecycle cost modeling, while residential online buyers show highest elasticity to material certification claims.
Supply Chain Analysis
China and the United States anchor cold-rolled steel forging for load-bearing implements, with Shandong Province and Columbus, Ohio hosting concentrated barbell production clusters. Raw material dependencies draw from Malaysian and Thai natural rubber latex, Ukrainian and Russian steel billet feedstocks, and Saudi petrochemical derivatives for TPE compounding. Single-source vulnerability runs through Shandong Province's forging concentration, where climate-induced logistics disruption or regulatory enforcement actions create supply interruption risk. Distribution runs through manufacturer-direct relationships with boutique studio chains, bypassing traditional wholesale intermediaries in the United States and United Kingdom.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Gym fitness accessories incumbents face substitution pressure from connected resistance systems integrating force sensors with mobile coaching platforms, threatening to commoditize traditional hardware through subscription revenue models that capture ongoing customer value.
For Market Incumbents: Fortify material science capabilities through captive TPE compounding investments in Germany or California to secure EU Green Deal compliance and carbon-border positioning. Deepen direct procurement relationships with Equinox and Barry's Bootcamp archetypes to lock institutional volume before connected-system entrants scale subscription alternatives. For New Entrants and Emerging Players: Connected-system service layers where incumbents under-serve present white-space entry points, specifically force-sensor integration with physical therapy clinic chains standardizing around CE-marked procurement. Target German and California residential markets where sustainability premiums support TPE mat pricing power. Pursue medical rehabilitation channel partnerships as the most penetrable institutional pathway, leveraging FDA antimicrobial registration to unlock pharmacy retail placement. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed boutique studio chains consolidating procurement authority through direct manufacturer relationships. Five-to-ten year viability hinges on material chemistry adaptation speed rather than brand heritage alone. Watch for ECHA enforcement action acceleration against non-compliant rubber compounders as the inflection signal indicating margin compression severity for legacy manufacturers unable to reformulate.| Strategic Initiative | Industry Significance |
|---|---|
| Bio-Based TPE Compounding Capacity Expansion | Secures EU Green Deal compliance and carbon-border positioning for German market access. |
| Force-Sensor Integration with Mobile Platforms | Opens subscription revenue models threatening traditional hardware commoditization. |
| Direct Manufacturer-Studio Procurement Relationships | Bypasses wholesale intermediaries and locks institutional volume with Equinox archetypes. |
| FDA Antimicrobial Registration Pathway | Unlocks pharmacy channel priority for foam rollers targeting medical rehabilitation. |
| In-House Steel Forging Capability Investment | Insulates barbell production from Shandong Province geographic concentration risk. |
Research Methodology
A standing panel of commercial gym procurement directors, boutique studio operations managers, TPE compounder technical leads, and physical therapy clinic chain purchasing officers provided ongoing calibration across primary interview cycles, validated against customs trade records for rubber and steel imports, ECHA REACH compliance databases, FDA antimicrobial registration filings, and SEC 10-K disclosures from listed fitness equipment manufacturers. Bottom-up volume modeling triangulated against top-down market sizing from production capacity assessments.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. Segmentation dimensions modeled include product type, material chemistry tier, end-user application intensity, and distribution channel structure. CAGRs derived from regression analysis of historical procurement patterns and forward-looking studio expansion pipelines, incorporating natural rubber price volatility indices and carbon-border adjustment mechanism implementation timelines as industry-specific forecast inputs.
Underlying assumptions cover ECHA enforcement continuity, boutique studio expansion persistence, and connected-system adoption curves, with deviation risk concentrated in Southeast Asian latex supply disruption severity and EU Green Deal implementation acceleration. Recalibration cycles align with material shifts in regulatory enforcement patterns and substitute technology penetration rates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fitness Equipment
Europe Fitness Rings Market
Fitness Equipment
India Fitness Ring Market
Fitness Equipment
Weight Training Benches Market
Fitness Equipment
Muscle Oxygen Monitors Market
Fitness Equipment
Mexico Outdoor Fitness Equipment Market
Fitness Equipment
Exercise Bike Market
Fitness Equipment
Weight Training Market
Fitness Equipment
Latin America Fitness Ring Market
Fitness Equipment
Japan Fitness Ring Market
Fitness Equipment
Functional Fitness Equipment Market
Fitness Equipment
Yoga and Pilates Mats Market
Fitness Equipment
Global Jumping Rope Market
Fitness Equipment
Personal Exercise Mats Market
Fitness Equipment
Lung Exercise Machine Market
Fitness Equipment
Pilates Equipment Market
Fitness Equipment
PVC Stretch Yoga Mats Market