
 Gymnastics Equipment Market | 2026-2036
Gymnastics Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Gymnastics Equipment Market Outlook
Buyer concentration among elite coaching institutions and national federation programs is hardening as Olympic qualification standards tighten equipment specifications. Taishan Sports Industry Group leverages its FIG certification breadth to anchor supply contracts across Asian national teams. American Athletic Inc competes through domestic manufacturing scale and NCAA program relationships. Norberts Athletic Products Inc specializes in youth-focused apparatus with adjustable specifications for developmental academies.
Gymnastics equipment encompasses apparatus designed for artistic, rhythmic, and trampoline disciplines, typically constructed with steel frames, fiberglass or wood cores, and multi-density foam padding covered in synthetic leather or carpet for impact absorption and rotational grip. Floor mats incorporate cross-linked polyethylene foam layers ranging from 20-40 cm thickness to meet federation rebound standards. Balance beams and uneven bars represent mature segments with stable replacement cycles, while vaulting tables with adjustable height mechanisms capture margin pools from elite training facilities. The recreational user segment within end users shows structural expansion as parkour and ninja-style fitness trends broaden addressable demand beyond traditional gymnastics enrollment.
FIG apparatus norms govern international competition equipment, while national regulators like the Consumer Product Safety Commission in the United States enforce youth product safety standards for home and school use. The European Committee for Standardization maintains EN 913 for gymnastic equipment, shaping import requirements and domestic manufacturer compliance obligations across EU member states. Stakeholders must monitor evolving federation specifications and regional safety mandates to align R&D roadmaps with certification timelines.
Market Dynamics
Foam-cored beam construction is displacing traditional wood cores under updated FIG equipment norms, forcing apparatus manufacturers to retool production lines and recertify product lines ahead of Olympic qualification cycles.
Growth Catalysts
- FIG Certification Mandates:Federation Internationale de Gymnastique apparatus norms now require third-party safety validation for competitive equipment, creating replacement demand across national federation programs.
- NCAA Program Expansion:Collegiate athletic departments in the United States are upgrading training facilities to attract scholarship athletes, driving apparatus procurement cycles.
- Parkour Facility Buildout:Ninja-style fitness centers are installing modified gymnastics apparatus, broadening addressable demand beyond traditional enrollment channels.
Market Restraints
- Steel and Fiberglass Input Volatility:Raw material price swings compress margin pools for manufacturers dependent on imported composite cores and alloy frames.
- Supplier Concentration in Shandong Province:FIG-certified apparatus production clusters heavily in eastern China, exposing procurement timelines to regional logistics disruptions.
- Substitution by Modular Fitness Systems:Functional training rigs with adjustable attachments compete for facility floor space and capital budgets.
Strategic Opportunities
- India School Infrastructure Buildout:Government physical education mandates are creating first-time apparatus demand in tier-two and tier-three cities lacking legacy equipment.
- Sensor-Enabled Performance Tracking:Force plates and motion-capture integration with vaulting tables and floor systems create data-service revenue streams.
- Direct-to-Academy Distribution:Manufacturers are bypassing traditional sporting goods wholesalers to sell configurable apparatus packages through digital configuration tools.
Industry Challenges
- FIG Recertification Timeline Compression:Apparatus makers face 18-month validation windows for updated equipment norms, squeezing R&D-to-market cycles.
- Specialized Welding and Composite Layup Skills:Shortage of certified technicians for steel frame fabrication and fiberglass core production limits output scaling.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gymnastics Equipment Market |
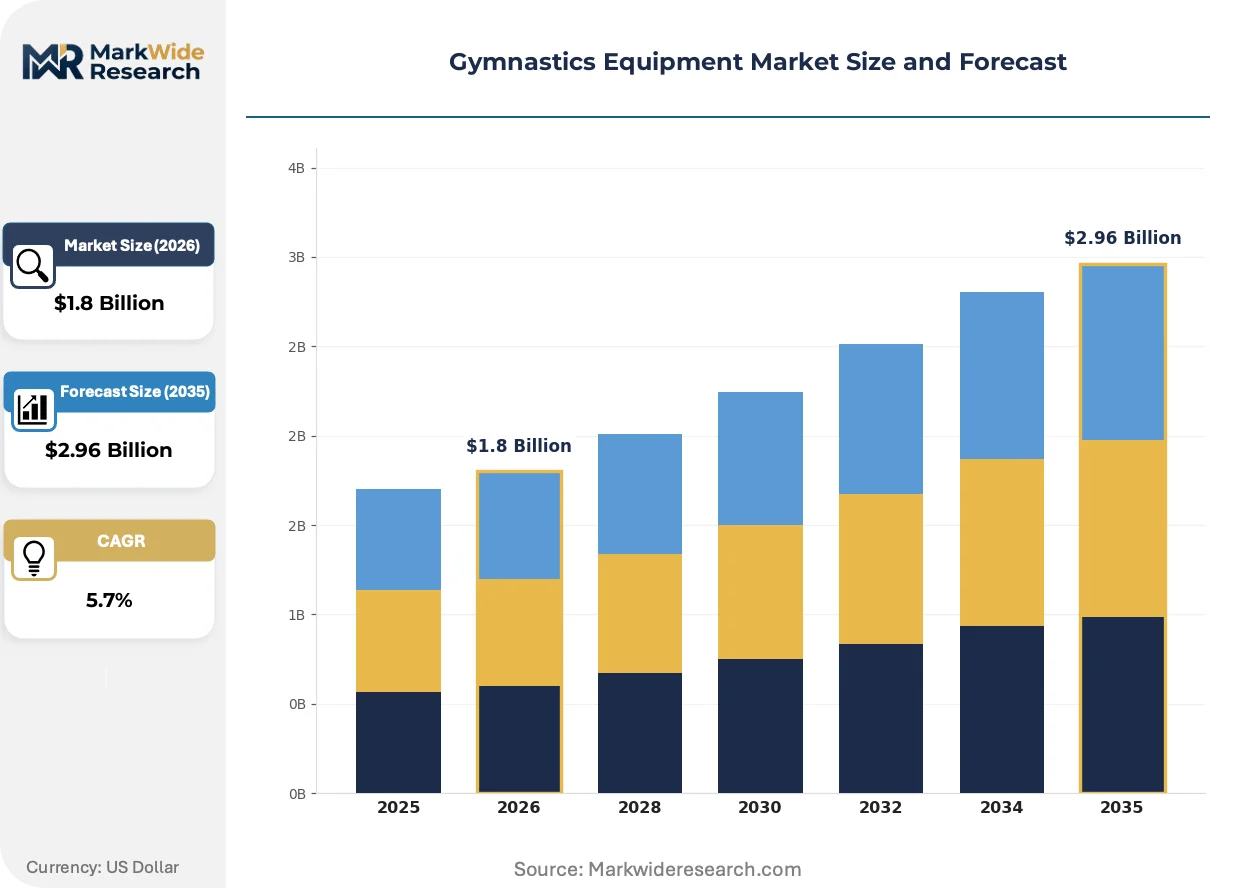
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Balance Beams, Uneven Bars, Vaulting Horses, Floor Mats End User: Professional Athletes, Recreational Users, Coaching Institutions, Fitness Centers Material: Wood, Fiberglass, Foam, Steel Age Group: Children, Teens, Adults, Seniors |
| Companies Covered | Taishan Sports Industry Group, Norberts Athletic Products Inc, American Athletic Inc, Abeo SA, Continental Sports Ltd, Spieth America, Gymnova, Kubler Sport GmbH, Mizuno Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gymnastics Equipment Market Strategic Shifts
Material science advances and federation specification updates are converging to reshape apparatus design priorities, with durability standards and athlete safety metrics now driving engineering roadmaps ahead of cost minimization.
Cross-linked polyethylene foam cores with variable density layering are expanding into competitive balance beam and vaulting table construction. Elite training facilities in the United States and China are specifying these materials for apparatus replacement cycles. This shift is expanding into margin pools previously captured by traditional wood-core suppliers as FIG norms prioritize impact absorption metrics.
REACH substance restrictions in the European Union are limiting phthalate content in synthetic leather coverings and foam padding formulations. Manufacturers serving EU member states must reformulate material specifications to maintain CE marking compliance. Rhythmic gymnastics apparatus suppliers face the tightest reformulation deadlines given the extensive foam and fabric components in balls, hoops, and ribbons.
Buyer concentration among national federation programs is compressing sales cycles and elevating specification complexity. Private academy chains now emulate federation procurement standards, displacing price-driven purchasing from traditional sporting goods retailers. This pattern is most visible in Australia and Germany, where club accreditation programs mandate FIG-equivalent apparatus for competitive stream enrollment.
Gymnastics Equipment Market Segmentation
Segmentation in gymnastics equipment reveals how apparatus specifications diverge across competitive intensity levels and user physiology. Material choices and dimensional standards cascade differently through Olympic training centers versus recreational facilities, shaping procurement priorities and replacement cycles.
Product Type:
Standalone apparatus dominates competitive environments where FIG certification mandates discrete equipment procurement, while modular systems embed into multi-purpose training facilities seeking floor-space flexibility.
- Balance Beams:Constructed with foam-cored substrates replacing traditional wood under updated FIG norms, these apparatus now emphasize variable-density layering for impact absorption. Demand concentrates in NCAA programs and Chinese national team facilities where beam replacement cycles accelerate ahead of Olympic qualification windows.
- Uneven Bars:Steel-framed apparatus with fiberglass composite rails require precision welding and tension calibration for competitive use. Elite coaching institutions in the United States specify these for scholarship athlete development, driving premium procurement despite longer replacement intervals than beam apparatus.
- Vaulting Horses:Adjustable-height mechanisms with polyethylene foam landing surfaces serve developmental and elite training tiers.
- Floor Mats:Cross-linked foam systems with 20-40 cm thickness profiles meet federation rebound standards for competition and training.
Floor mats lead volumes today; vaulting horses with integrated sensor platforms are gaining share fastest.
End User:
Cost-tier stratification separates federation-grade procurement with multi-year certification cycles from price-sensitive recreational purchasing.
- Professional Athletes:National team programs and Olympic training centers specify FIG-certified apparatus with third-party safety validation. These buyers concentrate procurement in Shandong Province manufacturing clusters, accepting 18-month recertification timelines for norm-compliant equipment.
- Coaching Institutions:Private academy chains and collegiate programs emulate federation standards to attract competitive enrollment. NCAA athletic departments in the United States drive apparatus upgrades as scholarship competition intensifies, creating replacement demand independent of Olympic cycles.
- Recreational Users:Home and school purchasers prioritize adjustable specifications and storage efficiency over competitive-grade performance.
- Fitness Centers:Parkour and ninja-style facilities repurpose gymnastics apparatus for functional fitness programming.
Coaching institutions lead volumes today; fitness centers are expanding most quickly as parkour participation broadens addressable demand.
Material:
Volume concentration favors steel and foam composites where manufacturing scale and certification breadth anchor supplier positioning.
- Foam:Cross-linked polyethylene cores with variable-density layering now dominate beam and vault construction under FIG impact-absorption priorities. Taishan Sports Industry Group and domestic U.S. manufacturers are retooling production lines to capture margin pools previously held by wood-core suppliers.
- Steel:Alloy frames for bars and vaulting apparatus require certified welding technicians, creating supply bottlenecks as demand scales. Chinese manufacturing clusters maintain concentration in frame fabrication, exposing procurement timelines to regional logistics constraints.
- Wood:Traditional beam cores face displacement as FIG norms prioritize foam substrates.
- Fiberglass:Composite rails and core components balance durability with weight specifications for competitive apparatus.
Steel leads volumes today; foam substrates are climbing the fastest as federation norms drive material substitution.
Age Group:
Application intensity varies dramatically—competitive stream enrollment peaks in teen categories while recreational participation broadens across adult demographics.
- Children:Developmental programs specify adjustable-height apparatus with enhanced padding for safety compliance. Norberts Athletic Products Inc targets this segment with modular specifications that accommodate growth progression.
- Teens:Competitive stream concentration drives FIG-certified apparatus demand with full performance specifications. This cohort anchors replacement cycles for beams, bars, and vaulting equipment in federation and academy channels.
- Adults:Recreational and fitness-oriented participation expands through parkour and ninja-style programming.
- Seniors:Low-impact rhythmic and flexibility apparatus serve rehabilitation and wellness applications.
Teens lead volumes today; adults are gaining share fastest as fitness trends broaden gymnastics-derived participation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China commands FIG-certified apparatus production while the United States drives replacement demand through NCAA expansion. Germany enforces REACH substance restrictions on foam padding formulations. India generates first-time procurement through school infrastructure mandates. Australia and Japan anchor Pacific Rim demand through federation accreditation programs.
United States
NCAA athletic departments and private academy chains accelerate beam and bar replacement cycles ahead of scholarship competition windows. The Consumer Product Safety Commission enforces youth product safety standards for home and school apparatus. Manufacturing clusters in the Midwest and Southeast supply domestic institutional demand with shortened lead times versus Asian imports.
China
National team programs and provincial sports bureaus expand procurement of Olympic-grade equipment ahead of qualification cycles. SAMR oversees product quality certification under GB standards for domestic distribution. Shandong Province manufacturing clusters concentrate FIG-certified apparatus production, exposing global supply timelines to regional logistics constraints.
Germany
Club accreditation programs mandate FIG-equivalent apparatus for competitive stream enrollment across federal states. ECHA REACH restrictions limit phthalate content in synthetic leather coverings and foam padding. Industrial concentration in Baden-Württemberg and Bavaria supports precision fabrication of steel-framed bars and vaulting mechanisms.
India
Government physical education mandates create first-time apparatus demand in tier-two and tier-three cities lacking legacy equipment. BIS certification requirements shape import specifications for school procurement programs. Manufacturing activity in Maharashtra and Gujarat supplies adjustable developmental apparatus for emerging coaching academies.
Australia
Gymnastics federation club accreditation drives FIG-standard procurement across state-level competitive programs. The country's national consumer protection regulator enforces product safety standards for youth equipment. Sydney and Melbourne metropolitan areas concentrate elite coaching institutions with accelerated replacement cycles.
Gymnastics Equipment Market Competitive Environment
Shandong Province producers anchor the certification-intensive tier; American and European specialists hold relationship-driven positions with institutional buyers. The vendor base separates into three strata: FIG-certified apparatus manufacturers with federation validation breadth, domestic-scale fabricators serving NCAA and academy channels, and youth-focused specialists with adjustable specifications. Competitive moves concentrate on direct-to-academy digital distribution buildout and sensor-enabled performance tracking integration.
Within the certification-led tier, Taishan Sports Industry Group and American Athletic Inc exemplify geographic anchoring strategies—Chinese manufacturing scale versus domestic NCAA relationships. Norberts Athletic Products Inc occupies the developmental-academy specialist position with modular apparatus configurations. These three entities represent distinct competitive archetypes: federation-validated export scale, institutional relationship density, and youth-segment product adaptability.
| Leading Market Players |
|---|
| Taishan Sports Industry Group |
| Norberts Athletic Products Inc |
| American Athletic Inc |
| Abeo SA |
| Continental Sports Ltd |
| Spieth America |
| Gymnova |
| Kubler Sport GmbH |
| Mizuno Corporation |
| Others |
Value Chain & Pricing Dynamics
FIG recertification timelines compressing to eighteen-month windows are forcing apparatus manufacturers to accelerate R&D cycles and absorb compliance costs, which in turn hardens price floors for federation-grade equipment as smaller fabricators exit certification-intensive tiers.
Pricing Analysis
Capacity additions in Shandong Province are reshaping price floors for FIG-certified apparatus, though certified welding technician shortages limit output scaling. Three-tier pricing structure across federation-certified, collegiate-grade, and developmental tiers separates buyers by validation breadth and performance specifications. Cost compression in recreational-tier foam-cored beams intensifies because wood-core displacement expands addressable supply. Private academy chains exhibit highest price sensitivity; Olympic training centers prioritize certification compliance over unit economics.
Supply Chain Analysis
Refurbishment flows for steel-framed bars and vaulting mechanisms remain underdeveloped, creating stranded asset risk for coaching institutions with legacy apparatus. Manufacturing concentrates in China, the United States, and Germany. Production draws from fiberglass composite cores, cross-linked polyethylene foam, and certified alloy steel tubing. Single-source vulnerability in Shandong Province apparatus fabrication exposes procurement timelines to regional logistics disruptions. Distribution runs through direct-to-academy digital configuration tools and traditional sporting goods wholesalers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The gymnastics equipment market compounds steadily as federation specification updates mandate recurring replacement cycles across national team programs and emulative collegiate facilities.
For Market Incumbents: Cement FIG certification breadth as a defensive moat by accelerating third-party validation investments ahead of Olympic qualification windows. Deepen upstream control over certified welding technician pipelines to relieve production bottlenecks. Sensor-enabled performance tracking integration represents a margin expansion lever against modular fitness system substitutes. For New Entrants and Emerging Players: Launch via direct-to-academy digital distribution to bypass wholesale margin capture by established sporting goods channels. White-space opportunity concentrates in India's tier-two and tier-three school infrastructure buildout, where first-time apparatus demand lacks legacy supplier relationships. Adjustable developmental specifications for youth programs offer the most penetrable entry segment. For Investors and Strategic Acquirers: Asymmetric upside sits with domestic-scale fabricators holding NCAA program relationships and sensor-integrated product roadmaps. Long-term viability hinges on federation validation durability rather than recreational volume exposure. Monitor FIG norm revision frequency and national team procurement acceleration as inflection indicators for replacement cycle intensity.| Strategic Initiative | Industry Significance |
|---|---|
| FIG Certification Investment | Third-party validation breadth anchors supply contracts with Chinese national team programs. |
| Sensor Platform Integration | Force plate and motion-capture data services expand recurring revenue beyond apparatus sales. |
| Direct-to-Academy Distribution | Digital configuration tools bypass wholesale margin capture and compress sales cycles. |
| Certified Technician Pipeline Development | In-house welding and composite layup training relieves output scaling constraints. |
| India Market Entry | Government physical education mandates in tier-two cities create first-mover positioning. |
Study Parameters
Bottom-up coaching institution and federation procurement modeling reconciled against top-down manufacturing capacity and certification tracking forms the analytical core. Primary interviews with apparatus R&D directors, NCAA athletic department procurement officers, national federation equipment managers, and certified welding technicians were validated against secondary sources including FIG apparatus norm filings, Consumer Product Safety Commission youth product safety databases, SAMR GB standard certifications, and customs trade records for gymnastics equipment imports.
Input-output matrices map raw material flows—fiberglass composite cores, cross-linked polyethylene foam, alloy steel tubing—through Shandong Province fabrication clusters to end-use segments across the projection horizon. Segmentation dimensions include product type, end-user tier, material substrate, and age-group participation intensity. CAGRs derive from replacement cycle analysis tied to Olympic qualification windows and NCAA scholarship competition dynamics.
Forecast precision tightens around the base case; tail outcomes carry wider variance under FIG norm revision acceleration or regional logistics disruptions in eastern China. Practitioners should monitor federation recertification timeline compression and parkour facility buildout rates for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fitness Equipment
Recumbent Stationary Bikes Market
Fitness Equipment
Belt Trainers Market
Fitness Equipment
Resistance Bands Market
Fitness Equipment
Pilates Equipment and Gears Market
Fitness Equipment
Europe Fitness Rings Market
Fitness Equipment
Pilates Equipment Market
Fitness Equipment
Smart Scales Market
Fitness Equipment
North America Home Fitness Equipment Market
Fitness Equipment
Asia-Pacific Fitness Equipment Market
Fitness Equipment
Global Jumping Rope Market
Fitness Equipment
Latin America Fitness Ring Market
Fitness Equipment
Gymnastic Springboard Market
Fitness Equipment
Muscle Oxygen Monitors Market
Fitness Equipment
North America Fitness Rings Market
Fitness Equipment
Lung Exercise Machine Market
Fitness Equipment
Yoga Accessories Market