
 Global Inline Metal Detector Market | 2026-2036
Global Inline Metal Detector Market Size, Share, and Industry Trends Forecast 2026-2036
Global Inline Metal Detector Market Outlook
Aftermarket service revenue is tilting toward predictive maintenance contracts as original equipment margins compress. Mettler-Toledo International Inc. leverages its global service footprint to lock in multi-year calibration agreements. Thermo Fisher Scientific Inc. anchors its position through deep integration with laboratory information management systems. Fortress Technology Inc. specializes in washdown-resistant designs that dominate dairy and ready-to-eat lines.
Inline metal detectors are electromechanical inspection devices that use balanced coil electromagnetic fields to identify ferrous, non-ferrous, and stainless-steel contaminants in moving product streams, typically achieving detection thresholds of 0.3 to 1.0 millimeters depending on aperture size and product effect. These systems serve primarily to prevent contaminated goods from reaching consumers and to protect downstream processing equipment from damage. Conveyor Systems occupy the largest installed base due to their ubiquity in high-volume food and pharmaceutical packaging lines, while Pipeline Detectors represent the fastest-expanding category as liquid and slurry processors retrofit existing transfer systems. Electromagnetic technology leads in absolute unit shipments, though Inductive systems are gaining ground in applications demanding detection of non-magnetic alloys at elevated throughput speeds.
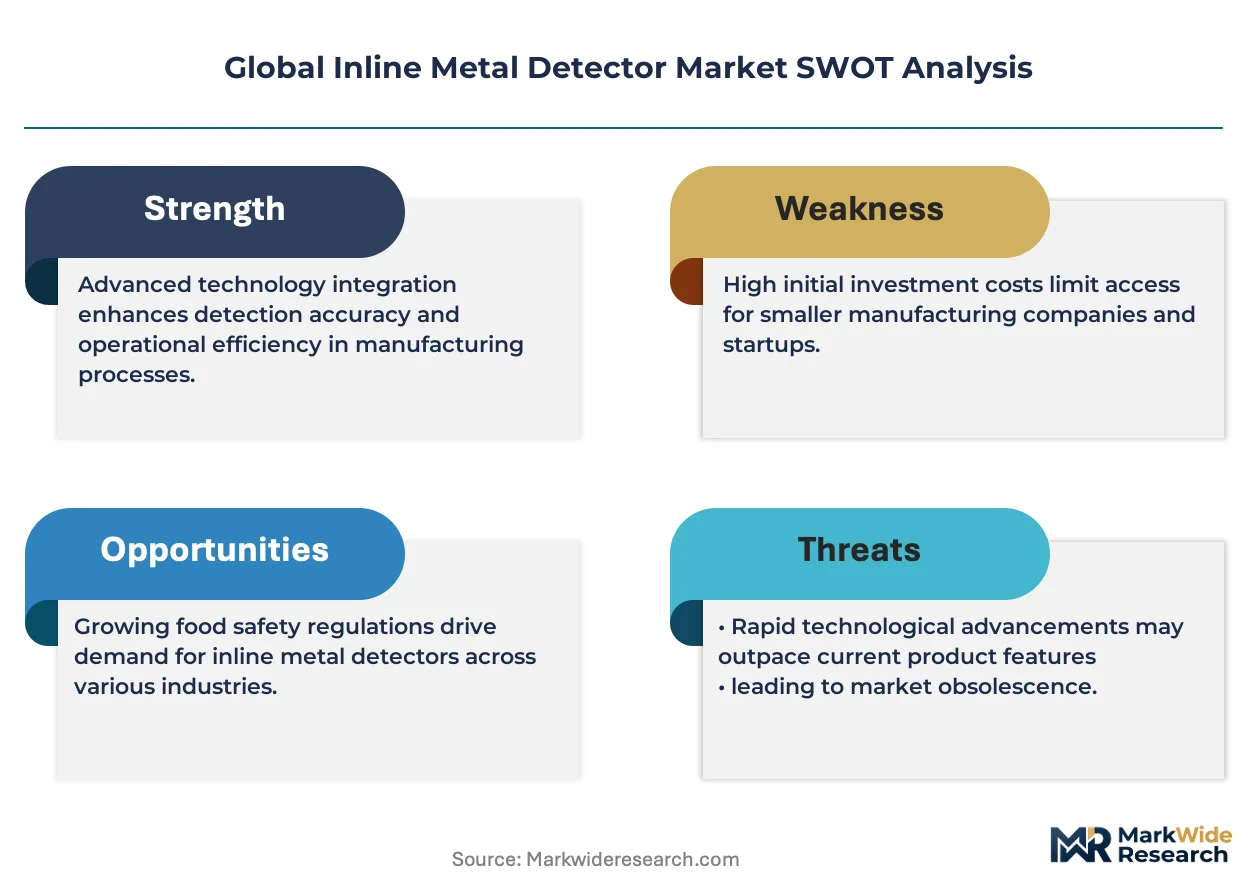
The FDA enforces Hazard Analysis and Critical Control Point mandates that require documented metal detection at specified control points in food manufacturing, directly driving replacement cycles and sensitivity upgrades across U.S. processing facilities. EMA and national regulators across Europe enforce similar contamination prevention standards under the EU Hygiene Package, while China's SAMR has tightened GB standards for food contact equipment inspection protocols. Stakeholders must weigh the capital cost of multi-frequency digital signal processing architectures against the operational risk of failing audits triggered by evolving detection thresholds.
Market Dynamics
Multi-frequency digital signal processing architectures are compressing detection thresholds below 0.3 millimeters, forcing incumbent hardware into accelerated replacement cycles across USDA-inspected meat facilities and pharmaceutical packaging lines.
Growth Catalysts
- EU Hygiene Package enforcement:EMA and national regulators across Europe mandate documented contamination prevention at specified control points, compelling sensitivity upgrades in dairy and ready-to-eat processing plants.
- Pipeline retrofit wave:Liquid and slurry processors in Japan's seafood export zones are retrofitting existing transfer systems with inductive detection arrays for non-magnetic alloy identification.
- GB standards tightening:China's SAMR has strengthened food contact equipment inspection protocols, accelerating inline inspection line expansions ahead of compliance deadlines.
Market Restraints
- Copper coil input volatility:Electromagnetic coil arrays depend on copper pricing that fluctuates with energy-intensive smelter output, compressing original equipment margins.
- Technical detection ceiling:Product effect interference from high-moisture or high-salt content limits reliable identification of stainless-steel particles below 0.3 millimeters in washdown environments.
- Service footprint concentration:Predictive maintenance contract penetration clusters with vendors possessing established calibration infrastructure, raising switching costs for processor facilities.
Strategic Opportunities
- India food processing expansion:FSSAI-mandated hazard analysis protocols in emerging cold chain hubs create first-mover positioning for inductive system deployments.
- Laboratory information management convergence:Deep integration between inline detection data and LIMS platforms enables real-time batch release automation in pharmaceutical packaging.
- Brazil export corridor penetration:ANVISA-aligned inspection requirements for protein exporters open retrofit demand in underpenetrated beef and poultry processing corridors.
Industry Challenges
- Electromagnetic field calibration expertise:Balanced coil optimization requires specialized technicians scarce in secondary processing regions, delaying commissioning timelines.
- Legacy conveyor integration friction:Retrofitting digital signal processing architectures into existing high-volume packaging lines demands custom aperture engineering and extended downtime windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Inline Metal Detector Market |
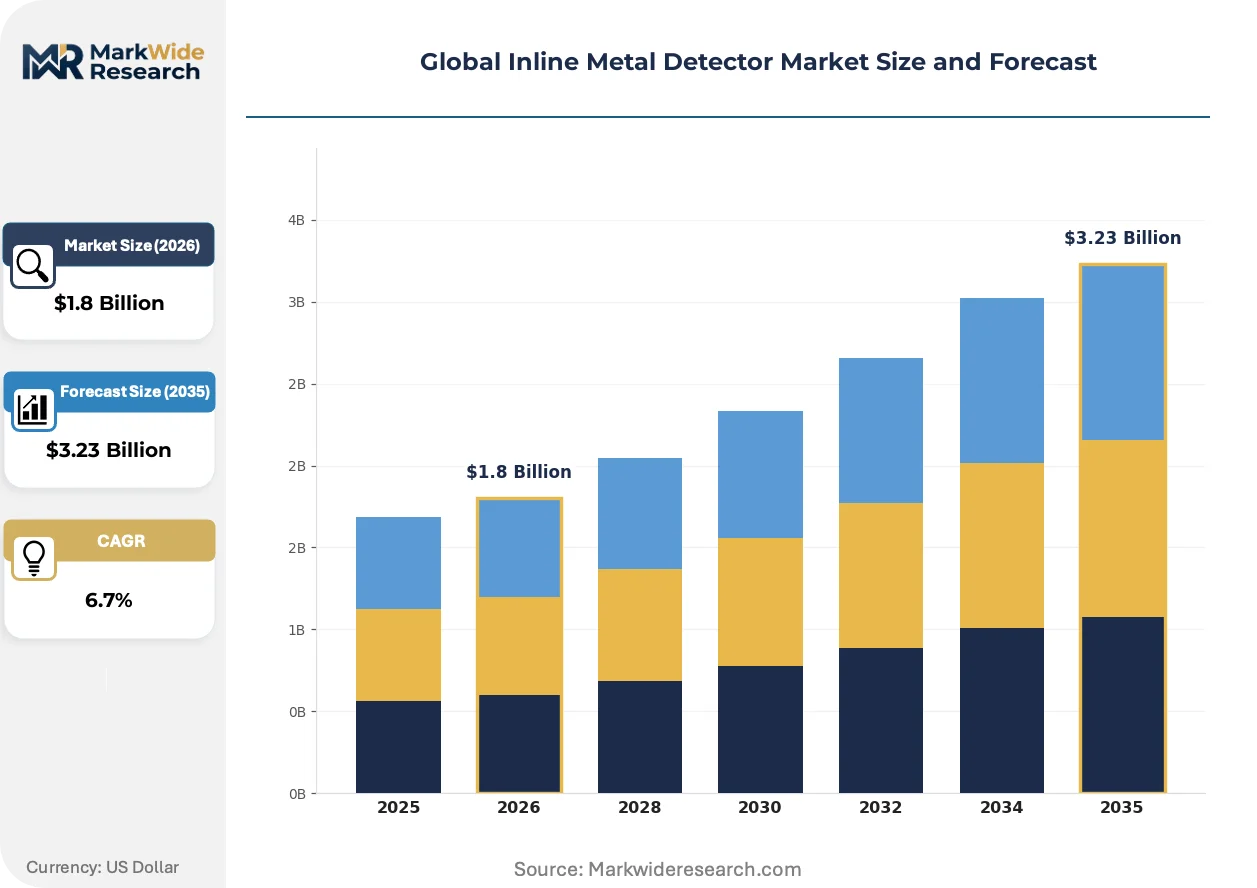
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Conveyor Systems, Handheld Detectors, Pipeline Detectors, Portable Units Technology: Electromagnetic, Inductive, Capacitive, Magnetic End User: Food Processing, Pharmaceuticals, Packaging, Textile Application: Quality Control, Safety Inspection, Product Detection, Contamination Prevention |
| Companies Covered | Mettler-Toledo International Inc., Thermo Fisher Scientific Inc., Fortress Technology Inc., Loma Systems, Ishida Co., Ltd., CEIA S.p.A., Anritsu Corporation, Eriez Manufacturing Co., Sesotec GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Inline Metal Detector Market Strategic Shifts
Detection technology is bifurcating between electromagnetic dominance in absolute unit shipments and inductive system gains in high-throughput alloy identification, while regulatory documentation requirements reshape service contract structures.
Multi-frequency digital signal processing is rendering obsolete single-frequency electromagnetic architectures that struggle with product effect cancellation in high-salt seafood and marinated meat applications. Japanese seafood export processors and German dairy cooperatives are adopting these arrays at replacement-cycle pace. The technology is compressing hardware replacement windows from seven-year cycles toward four-year sensitivity upgrade mandates.
REACH-aligned material traceability requirements are extending contamination documentation obligations upstream to equipment component suppliers. ECHA substance of very high concern screening now encompasses detector housing polymers and coil insulation materials. Pharmaceutical packaging lines in Switzerland and the Netherlands are prioritizing vendors with full material disclosure certification to preempt audit failures.
Service unbundling is fragmenting traditional bundled maintenance agreements into discrete calibration, spare parts, and remote diagnostics subscriptions. Meat processors in the United States are disaggregating multi-year vendor lock-in in favor of third-party metrology laboratory verification. This shift concentrates in USDA-inspected facilities where independent calibration documentation strengthens audit defensibility against FDA enforcement actions.
Global Inline Metal Detector Market Segmentation
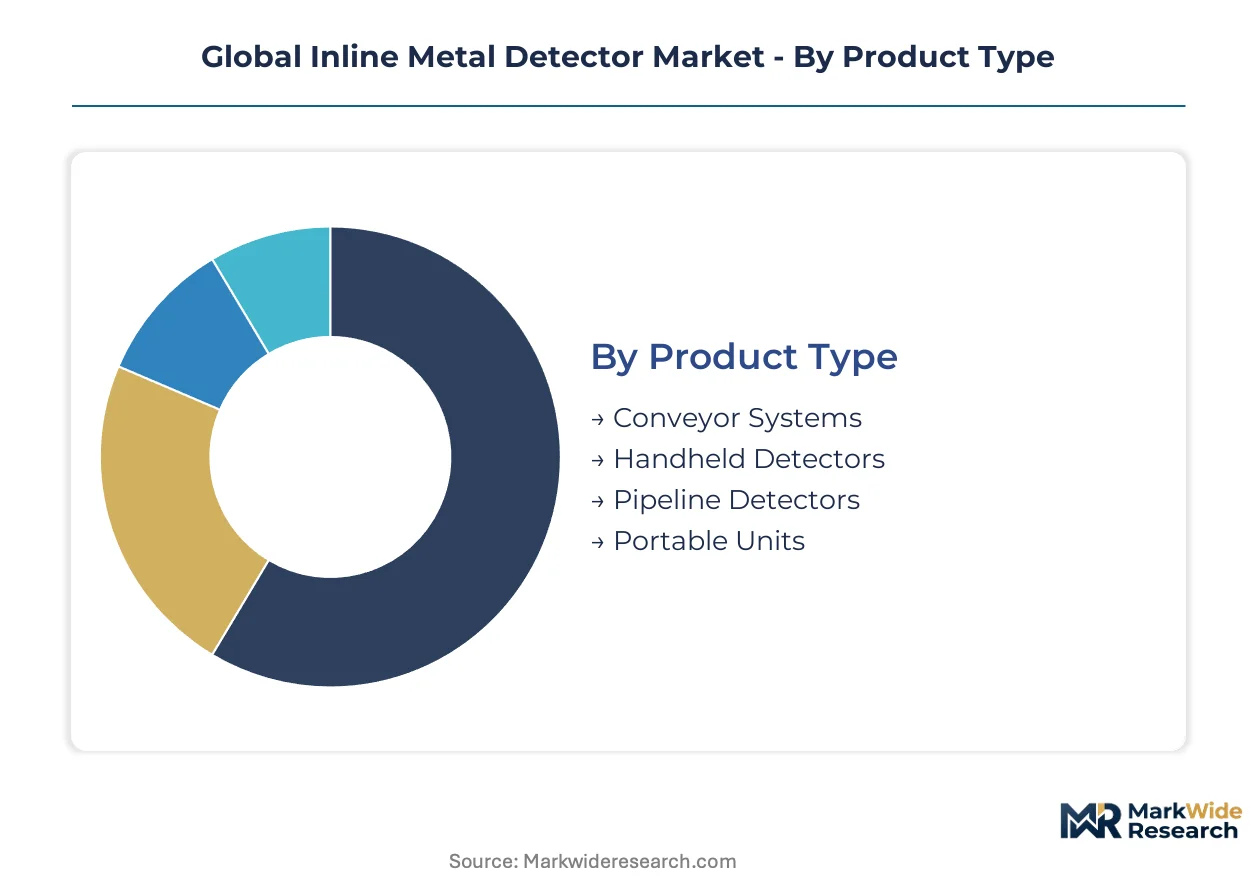
Inline metal detector segmentation reflects divergent technical requirements across product form factors, detection physics, and regulatory exposure. Procurement patterns cluster where inspection mandates intersect with material handling constraints.
Product Type:
Mature conveyor architectures dominate installed base economics while emerging pipeline configurations reshape retrofit demand.
- Conveyor Systems:Fixed-aperture electromagnetic arrays process bulk solids through high-volume packaging lines. USDA-inspected meat facilities in the United States concentrate replacement demand where seven-year hardware cycles compress toward four-year sensitivity mandates.
- Pipeline Detectors:Inductive coil configurations wrap existing liquid and slurry transfer infrastructure without flow interruption. Japanese seafood export processors drive retrofit adoption to isolate non-magnetic alloy contaminants in high-salt marinades.
- Handheld Detectors:Portable electromagnetic wands supplement fixed installations for spot-check verification in secondary processing zones.
- Portable Units:Battery-powered systems enable mobile contamination screening across multi-line dairy cooperatives in Germany.
Conveyor Systems handle the majority of throughput; Pipeline Detectors are expanding most quickly on share.
Technology:
Cost tier stratification separates established electromagnetic dominance from premium inductive positioning in alloy-sensitive applications.
- Electromagnetic:Balanced coil architectures generate oscillating fields for ferrous and non-ferrous particle identification. Absolute unit shipments concentrate in standard-threshold food packaging where copper coil input costs pressure original equipment margins.
- Inductive:Multi-frequency digital signal processing arrays cancel product effect interference in high-moisture environments. Pharmaceutical packaging lines in Switzerland prioritize these systems for stainless-steel detection below 0.3 millimeters.
- Capacitive:Dielectric measurement variants address non-metallic contaminant screening in specialized textile fiber inspection.
- Magnetic:Permanent magnet configurations serve low-sensitivity bulk material pre-screening ahead of precision detection stages.
Electromagnetic technology captures the volume base; Inductive systems command the steepest expansion trajectory.
End User:
Application risk profiles segment procurement between consumer safety-critical food processing and documentation-intensive pharmaceutical packaging.
- Food Processing:Inline inspection lines in Germany and China expand ahead of stricter GB standards and EU Hygiene Package enforcement. Dairy and ready-to-eat plants prioritize washdown-resistant coil housings.
- Pharmaceuticals:Batch release automation demands deep LIMS integration. Swiss and Dutch packaging lines require full material disclosure certification under REACH-aligned traceability mandates.
- Packaging:Final-line verification stations in high-volume export corridors combine metal detection with checkweighing modules.
- Textile:Needle and broken machinery fragment detection in garment finishing operations, particularly in South Asian export manufacturing.
Food Processing anchors the installed base; Pharmaceuticals is climbing the fastest on compliance-driven replacement.
Application:
Customer type segmentation separates preventive capital deployment from reactive safety inspection procurement.
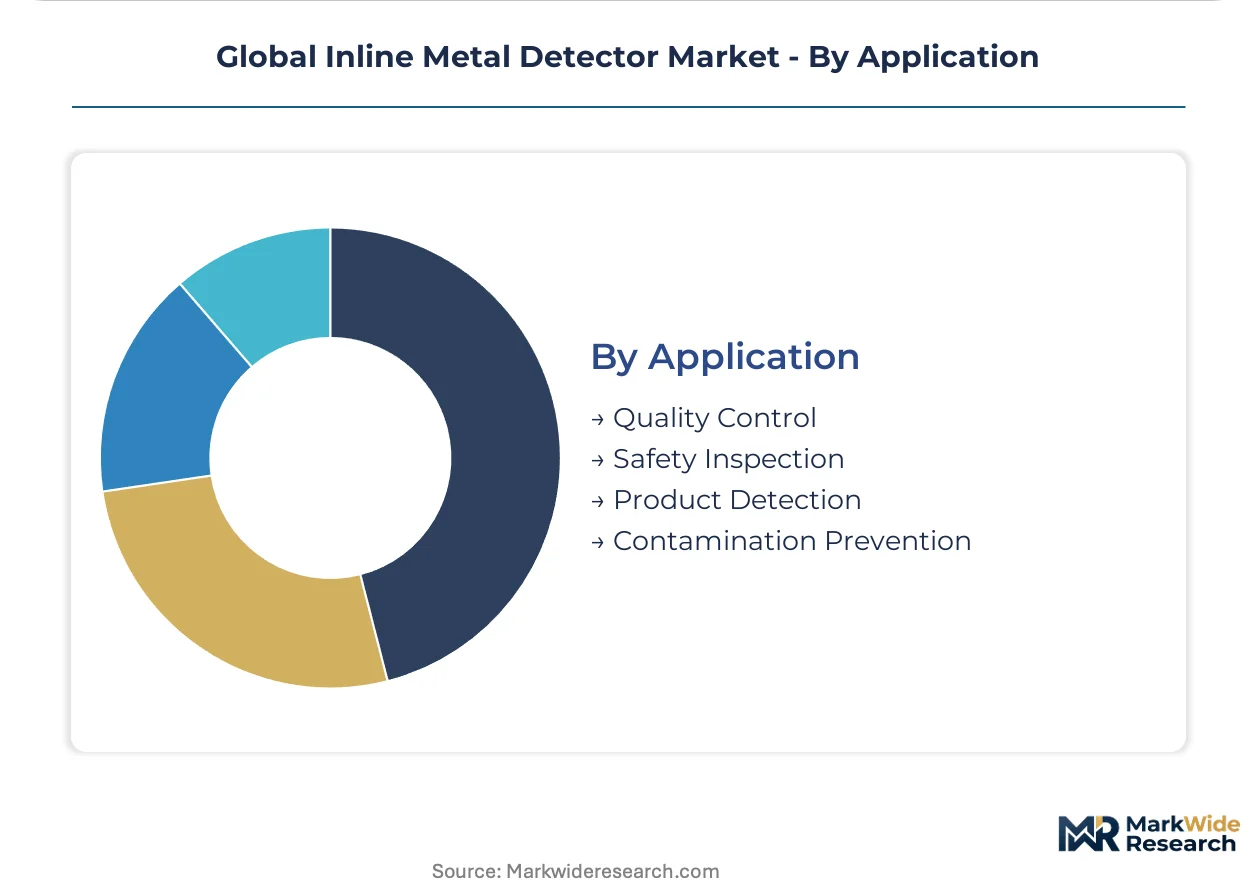
- Quality Control:Statistical process control integration enables real-time rejection threshold adjustment. High-throughput meat facilities deploy these architectures to minimize false-positive product waste.
- Safety Inspection:Mandated control point documentation under FDA HACCP and EMA protocols drives sensitivity upgrade cycles. Independent calibration verification strengthens audit defensibility.
- Product Detection:Missing component verification in pharmaceutical blister packaging lines prevents incomplete dosing units from reaching distribution.
- Contamination Prevention:Upstream detection placement protects downstream extrusion and cutting equipment from damage in polymer processing.
Quality Control manages the largest equipment footprint; Safety Inspection is gaining share fastest on regulatory documentation requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity diverges sharply across procurement contexts. German dairy cooperatives and Swiss pharmaceutical packers absorb premium pricing for sub-0.3mm detection thresholds, while Brazilian beef processors prioritize cost-efficient retrofit compatibility over sensitivity specifications.
United States
USDA-inspected meat facilities concentrate replacement demand in the Midwest and Southeast processing corridors. FDA HACCP mandates compress hardware replacement cycles from seven years toward four-year sensitivity upgrades. Chicago and Omaha clusters drive multi-frequency digital signal processing adoption to minimize false-positive waste in high-throughput lines.
Germany
Dairy cooperatives and ready-to-eat manufacturers anchor European washdown-resistant coil procurement. EU Hygiene Package enforcement compels documented contamination prevention at specified control points. Bavarian processing hubs retrofit existing conveyor lines with predictive maintenance contracts to lock in calibration infrastructure.
China
Food processing plants expand inline inspection capacity ahead of SAMR-tightened GB standards for food contact equipment. Domestic cold chain hub development accelerates inductive system deployment in emerging processing zones. Yangtze River Delta facilities prioritize electromagnetic arrays for bulk solids handling at compressed capital cost points.
Japan
Seafood export processors in Kyushu and Chubu drive pipeline detector retrofit demand for high-salt marinade inspection. METI-aligned quality protocols elevate non-magnetic alloy detection requirements in export corridors. Osaka-area packaging lines adopt multi-frequency architectures to cancel product effect interference in moisture-intensive applications.
Switzerland
Pharmaceutical packaging lines prioritize full material disclosure certification under REACH-aligned traceability mandates. Swissmedic documentation requirements extend contamination obligations upstream to equipment component suppliers. Basel and Zurich clusters anchor LIMS-integrated batch release automation demand for stainless-steel detection below 0.3 millimeters.
Global Inline Metal Detector Market Competitive Environment
Precision instrumentation conglomerates and specialized detection fabricators split the market along integration depth lines. Tiering concentrates around service footprint scale, with global calibration infrastructure commanding multi-year lock-in premiums against regional price competition. Three archetypes dominate: diversified laboratory equipment houses with LIMS convergence capability; washdown-specialized engineering boutiques with dairy sector entrenchment; and electromagnetic component suppliers with copper coil cost exposure. Consolidation pressure intensifies through predictive maintenance contract aggregation and aperture engineering acquisition.
Among precision instrumentation houses, Mettler-Toledo International Inc. and Thermo Fisher Scientific Inc. exemplify the diversified archetype with global service footprint leverage. Fortress Technology Inc. occupies a position within the specialized engineering tier. These three anchors illustrate the competitive divergence between scale-driven calibration lock-in and application-specific washdown resistance design.
| Leading Market Players |
|---|
| Mettler-Toledo International Inc. |
| Thermo Fisher Scientific Inc. |
| Fortress Technology Inc. |
| Loma Systems |
| Ishida Co., Ltd. |
| CEIA S.p.A. |
| Anritsu Corporation |
| Eriez Manufacturing Co. |
| Sesotec GmbH |
| Others |
Value Chain & Pricing Dynamics
Guangdong Province's electromagnetic coil manufacturing clusters anchor global detector production capacity, with smelter-adjacent wire drawing operations feeding downstream aperture fabrication. This geographic concentration grants incumbent suppliers leverage over pricing negotiations with European and North American OEMs seeking washdown-resistant configurations.
Pricing Analysis
Multi-year calibration service contracts generate the dominant share of lifetime customer value, displacing transactional hardware margins as the primary profit pool. Three-tier pricing structure across premium, standard, and economy levels separates pharmaceutical-grade LIMS-integrated systems from dairy-sector washdown models and basic conveyor arrays. Cost compression in the economy tier is intensifying because copper coil input volatility pressures original equipment manufacturers without captive smelter relationships. Brazilian beef processors exhibit the highest price sensitivity, prioritizing retrofit compatibility over sub-0.3mm detection thresholds, while Swiss pharmaceutical packers absorb premium positioning for REACH-aligned material certification.
Supply Chain Analysis
Electronics manufacturing services in China, Germany, and Japan hold concentrated capacity for multi-frequency digital signal processing board assembly. Detector fabrication draws from copper wire rod, ferrite core materials, and food-grade polymer housings. Single-source vulnerability in high-purity copper cathode supply from Chilean mining operations exposes margin structures to commodity swings. Distribution runs through authorized service networks that bundle installation commissioning with predictive maintenance subscriptions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized electromagnetic field calibration expertise represents the critical capability gap constraining market expansion, with technician scarcity in secondary processing regions delaying commissioning timelines and inflating service premiums.
For Market Incumbents: Insulate market position by acquiring aperture engineering boutiques with dairy-sector entrenchment, neutralizing the threat from washdown-specialized regional competitors. Deepen backward integration into copper coil winding operations to buffer margin compression from smelter output volatility.
For New Entrants and Emerging Players: Mid-market food processing facilities in India's emerging cold chain hubs represent the most penetrable entry point, where FSSAI-mandated hazard analysis protocols outpace established vendor service footprint expansion. Brazil's underpenetrated beef and poultry export corridors offer secondary white-space targeting ANVISA-aligned inspection retrofits. Lead with inductive system deployments pitched against electromagnetic legacy architectures struggling with product effect cancellation.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors diversified precision instrumentation houses with LIMS convergence capability over pure-play electromagnetic component suppliers exposed to copper cost cycles. Long-term viability hinges on predictive maintenance contract aggregation and calibration infrastructure lock-in. Watch FDA enforcement action intensity against USDA-inspected facilities as the signal indicating replacement cycle compression toward four-year mandates.
| Strategic Initiative | Industry Significance |
|---|---|
| Acquisition of Aperture Engineering Specialist | Fortress Technology's dairy-sector entrenchment demonstrates washdown-resistant design premiums. |
| Predictive Maintenance Contract Aggregation | Mettler-Toledo's global service footprint locks in multi-year calibration agreements against regional price competition. |
| LIMS Platform Integration Partnership | Thermo Fisher Scientific's laboratory information management convergence enables real-time pharmaceutical batch release. |
| Copper Coil Backward Integration | Captive wire drawing capacity insulates margin structures from smelter output volatility. |
| Inductive System Product Launch | Multi-frequency arrays displace single-frequency architectures in high-moisture Japanese seafood processing. |
Study Parameters
The analysis maps conveyor system deployments, pipeline detector retrofits, electromagnetic coil architectures, and inductive multi-frequency arrays, each validated through maintenance directors, plant engineers, OEM procurement teams, and aftermarket service heads. Primary interview intelligence triangulates against customs/trade data, SEC 10-K filings, food safety regulator enforcement databases, and industry association equipment shipment surveys. Bottom-up installation base counts and top-down market sizing converge through cross-referencing vendor service contract disclosures with end-user facility audit documentation.
Forecast assumptions hold regulatory detection threshold mandates fixed at current FDA HACCP and EU Hygiene Package specifications while varying copper price scenarios and replacement cycle compression rates across the projection horizon. Segmentation dimensions include product type, detection physics, end-use industry, and regional regulatory cluster. CAGRs derive from sensitivity upgrade cycle velocity and retrofit penetration curves in liquid processing applications. Industry-specific inputs incorporate SAMR GB standards implementation timelines and METI-aligned Japanese export quality protocols.
Practitioners should monitor copper cathode price movements, FDA enforcement action frequency, and REACH-aligned material disclosure mandate expansion for early signals of forecast revision. Quarterly review of service contract renewal rates and third-party metrology laboratory verification adoption is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Safety Testing
UAE Product Testing Lab Services Market
Food Safety Testing
Global Food Diagnostics Market
Food Safety Testing
Food and Beverages Disinfection Market
Food Safety Testing
Edible Oil Adulteration Testing Chemicals Market
Food Safety Testing
Adulteration Tester Market
Food Safety Testing
South Africa Food Safety Testing Market
Food Safety Testing
Fruit & Vegetable Wash Market
Food Safety Testing
Inline Beverage Gas and Microbial Load Monitoring Test Systems Market
Food Safety Testing
Food Safety Testing Services Market
Food Safety Testing
Food Traceability Solutions Market
Food Safety Testing
Ireland Food Testing Market
Food Safety Testing
Middle East and Africa Food Safety Testing Market
Food Safety Testing
Water Activity Instrumentation Market
Food Safety Testing
Salmonella Testing Market
Food Safety Testing
Residual Lactose Analyzer Market
Food Safety Testing
North America Consumer Product Safety Testing Market