
 Food Tester Market | 2026-2036
Food Tester Market Size, Share, and Industry Trends Forecast 2026-2036
Food Tester Market Foresight
Equipment leasing and asset-light service models is rewriting competitive dynamics for smaller laboratories seeking access to advanced spectrometry without capital outlay. Eurofins Scientific leverages its distributed laboratory network to offer testing-as-a-service bundles that reduce client equipment purchases. SGS SA anchors its position through long-term facility management contracts with multinational food manufacturers. Thermo Fisher Scientific Inc. differentiates by sustaining deep R&D investment in handheld contaminant detection platforms.
Food testers comprise analytical instruments that measure chemical composition, physical properties, and biological contaminants in food matrices using techniques such as near-infrared spectroscopy, electrochemical sensing, and chromatographic separation, typically achieving detection thresholds in parts per million or billion depending on analyte class. Their primary commercial purpose is to verify compliance with safety limits and quality specifications before products reach distribution channels. Portable testers command expanding share among on-site quality control teams requiring rapid turnaround without laboratory infrastructure. Benchtop analyzers retain margin concentration in nutritional analysis applications where precision demands justify higher capital expenditure. Spectrometers represent the fastest-expanding product category as Raman and mass spectrometry techniques penetrate routine safety inspection workflows previously dominated by immunoassay methods.
The FDA enforces Hazard Analysis and Critical Control Point verification through mandatory pathogen testing protocols that directly determine equipment specifications for domestic food manufacturers. EFSA and EU member state regulators under the Official Control Regulation mandate standardized analytical methods that shape instrument validation requirements across European laboratories. China's SAMR implements GB standards for heavy metal and additive limits that compel domestic and imported testing equipment to achieve specific metrological certifications. Stakeholders must monitor divergence between regional certification regimes when configuring product portfolios for cross-border deployment.
Market Dynamics
Equipment replacement cycles across food manufacturing facilities are compressing as regulatory verification protocols tighten under the FDA Food Safety Modernization Act and parallel EU frameworks, forcing capital redeployment toward portable spectrometry platforms.
Growth Catalysts
- Pathogen testing mandates:FDA enforcement of Hazard Analysis and Critical Control Point verification protocols compels domestic food manufacturers to install automated detection systems across critical control points.
- Heavy metal limits in China:SAMR implementation of GB standards for additive and contaminant thresholds drives domestic laboratory equipment upgrades and imported instrument certification.
- Portable Raman adoption:On-site quality control teams in large-scale processing facilities are replacing immunoassay workflows with handheld spectrometry for rapid contaminant screening.
Market Restraints
- Metrological certification costs:Divergence between FDA validation requirements, EFSA standardized methods, and SAMR GB compliance creates redundant testing expenditure for cross-border equipment deployment.
- Optical component supply concentration:German and Japanese precision optics manufacturers control critical laser and detector supply for high-resolution spectrometers, exposing buyers to extended lead times.
- Electrochemical sensor drift:Calibration degradation in field-deployed units limits detection reliability below laboratory-grade thresholds for trace analyte quantification.
Strategic Opportunities
- Testing-as-a-service expansion:Distributed laboratory networks in Germany and the United States are bundling spectrometry access with facility management contracts, reducing capital barriers for mid-tier processors.
- Near-infrared integration with chromatography:Convergence of rapid screening and confirmatory methods enables single-platform compliance verification, compressing laboratory footprint requirements.
- EU Official Control Regulation alignment:Standardized analytical method mandates across member states create bulk replacement demand for validated benchtop analyzers in centralized testing facilities.
Industry Challenges
- Spectroscopy technician scarcity:Interpretation of complex spectral data requires specialized analytical chemistry training that outpaces vocational pipeline output in major manufacturing regions.
- Legacy LIMS integration:Handheld and benchtop platforms must interface with established laboratory information management systems, extending deployment timelines and validation costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Food Tester Market |
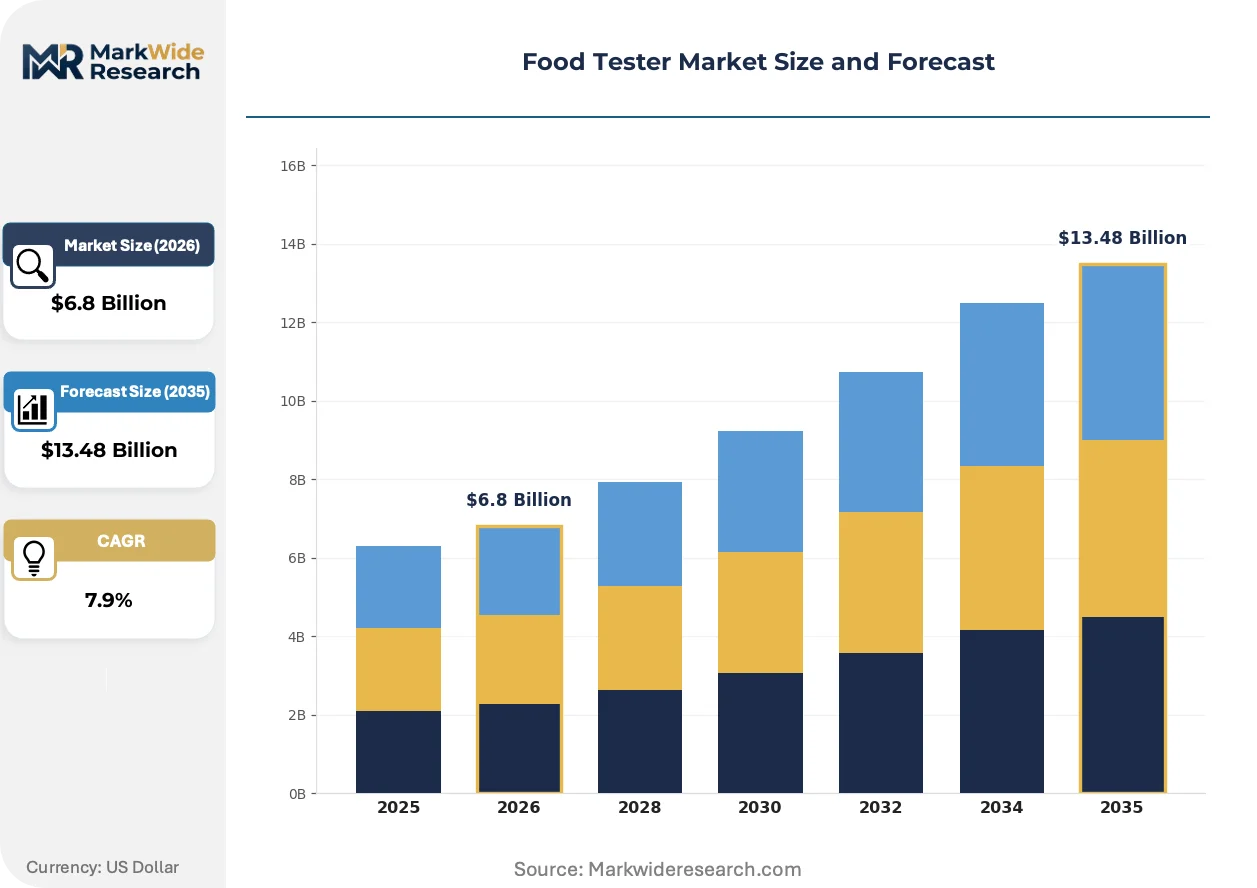
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $13.48 Billion |
| CAGR (2026 – 2036) | 7.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Testers, Benchtop Analyzers, Spectrometers, pH Meters, Moisture Meters Application: Quality Control, Safety Inspection, Nutritional Analysis, Contaminant Detection, Sensory Evaluation End User: Food Manufacturers, Packaging Firms, Research Laboratories, Regulatory Bodies, Ingredient Suppliers Distribution Channel: Direct Sales, Distributors, E-commerce Platforms, Dealers, Authorized Resellers |
| Companies Covered | Eurofins Scientific, SGS SA, Bureau Veritas, Intertek Group plc, Thermo Fisher Scientific Inc., ALS, NSF International, TÜV SÜD, Mérieux NutriSciences, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Food Tester Market Shifts & Advancements
Spectrometry platforms are virtualizing traditional laboratory functions while regulatory verification protocols harden across major jurisdictions, compressing the boundary between field and centralized testing infrastructure.
Cloud-connected Raman spectrometers are virtualizing reference library management and spectral interpretation workflows previously requiring dedicated laboratory workstations. Quality assurance managers at distributed processing sites now access centralized algorithm updates and regulatory method libraries without hardware modification. This architecture is virtualizing capital allocation patterns, converting fixed instrument expenditure into subscription-accessible analytical capacity.
EFSA harmonization under the Official Control Regulation is mandating standardized analytical methods across European national reference laboratories, eliminating instrument validation fragmentation that previously complicated cross-border equipment procurement. Food manufacturers operating multi-facility networks must now configure unified testing protocols or maintain parallel validation documentation. Benchtop mass spectrometry suppliers face compressed certification timelines as member state regulators synchronize inspection criteria.
Service contract unbundling is separating hardware ownership from analytical method access across North American and European markets. Mid-tier processors increasingly lease portable contamination screening units with embedded regulatory method packages rather than purchasing capital equipment outright. This preference shift concentrates in Germany and the United States where distributed laboratory networks compete directly with instrument manufacturers for recurring revenue relationships.
Food Tester Market Segmentation
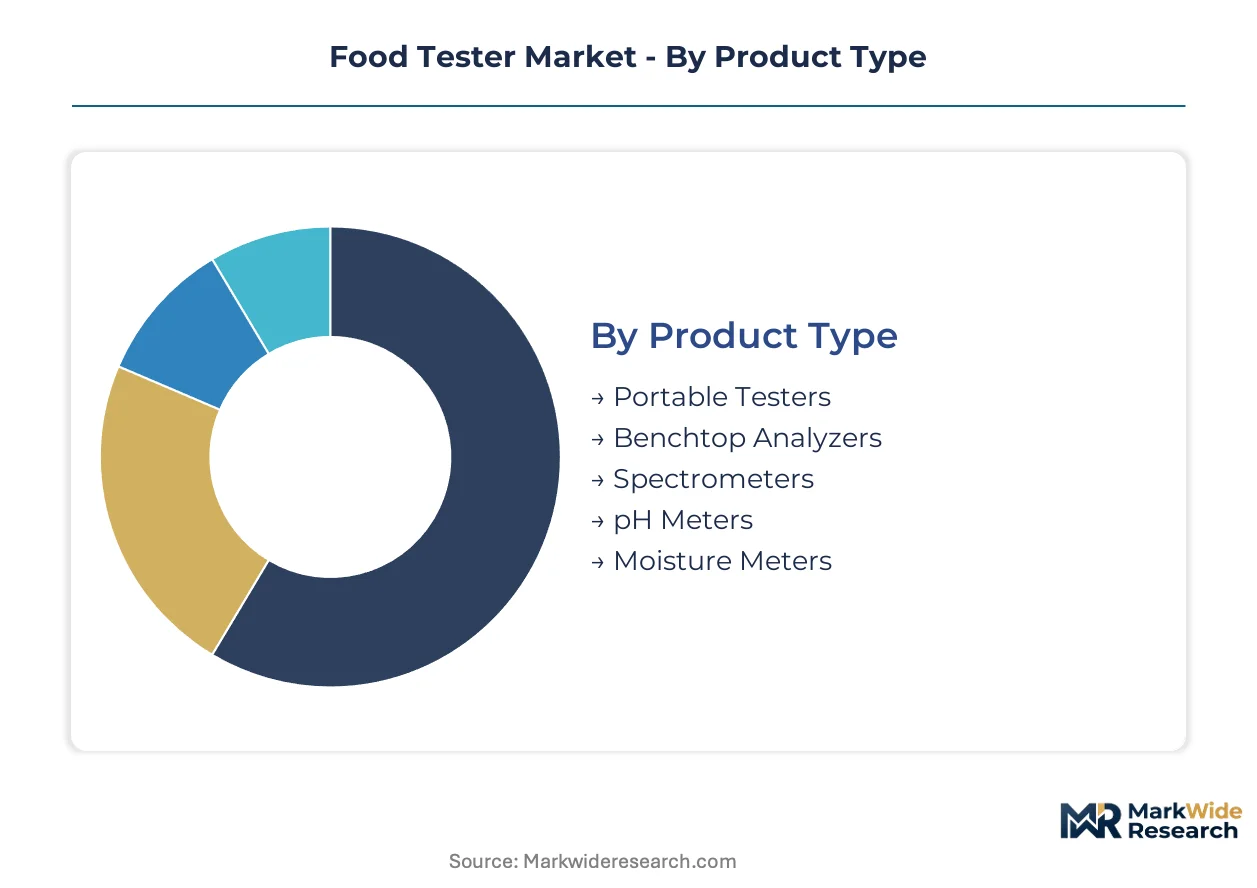
Equipment specifications vary sharply across deployment contexts in food testing. Manufacturers configure product portfolios around four intersecting dimensions that determine detection thresholds, throughput capacity, and regulatory compliance pathways.
Product Type:
Portable units serve field verification while benchtop systems anchor laboratory precision workflows.
- Portable Testers:Handheld units employing electrochemical sensing and near-infrared spectroscopy achieve rapid contaminant screening at processing lines without infrastructure investment. Demand concentrates in large-scale meat and dairy facilities across Germany and the United States where on-site quality control teams require immediate turnaround for pathogen alerts.
- Spectrometers:Raman and mass spectrometry platforms penetrate routine safety inspection workflows previously dominated by immunoassay methods, offering molecular fingerprinting for adulterant identification. Adoption accelerates in China where SAMR-mandated GB standards for heavy metal detection drive laboratory equipment upgrades.
- Benchtop Analyzers:Higher capital expenditure instruments retain margin concentration in nutritional analysis applications requiring precision measurement of macronutrient composition.
- pH Meters:Electrochemical probes verify acidity thresholds in fermentation processes and canned goods sterilization protocols.
- Moisture Meters:Near-infrared and capacitive sensors quantify water activity in grain storage and dehydrated product manufacturing.
The dominant share belongs to Benchtop Analyzers, while Spectrometers are closing the gap fastest.
Application:
Regulatory mandates determine which analytical methods processors must deploy at each production stage.
- Quality Control:In-line monitoring of physical properties and chemical composition ensures batch consistency before packaging release. Food manufacturers in the United States deploy these protocols to satisfy FDA Food Safety Modernization Act verification requirements.
- Contaminant Detection:Pathogen, heavy metal, and pesticide residue screening represents the most stringent analytical challenge, driving spectrometry adoption. Chinese processors face SAMR enforcement of GB standards that compel upgraded detection capabilities for both domestic and imported equipment.
- Safety Inspection:Hazard Analysis and Critical Control Point verification protocols mandate automated detection systems at critical control points.
- Nutritional Analysis:Macronutrient and micronutrient quantification supports label claim verification and reformulation initiatives.
- Sensory Evaluation:Electronic nose and tongue systems supplement human panels for flavor and aroma consistency testing.
Safety Inspection commands the largest equipment allocation, though Contaminant Detection is expanding most quickly as regulatory thresholds tighten.
End User:
Procurement authority and technical capability diverge substantially across buyer categories.
- Food Manufacturers:Integrated processors operating multi-facility networks drive bulk orders for standardized testing protocols. These buyers in Germany and the United States favor service contracts that bundle equipment access with regulatory method updates.
- Research Laboratories:Academic and government facilities require highest-precision instrumentation for method development and reference standard creation. EFSA-mandated standardized analytical methods under the Official Control Regulation shape validation requirements across European national reference laboratories.
- Packaging Firms:Migration testing and seal integrity verification dominate analytical priorities for material suppliers.
- Regulatory Bodies:Government inspection agencies deploy portable units for field enforcement and compliance verification.
- Ingredient Suppliers:Certificate of analysis generation and supplier qualification testing support downstream customer requirements.
Food Manufacturers account for the predominant revenue share, while Research Laboratories are gaining procurement momentum through centralized facility funding.
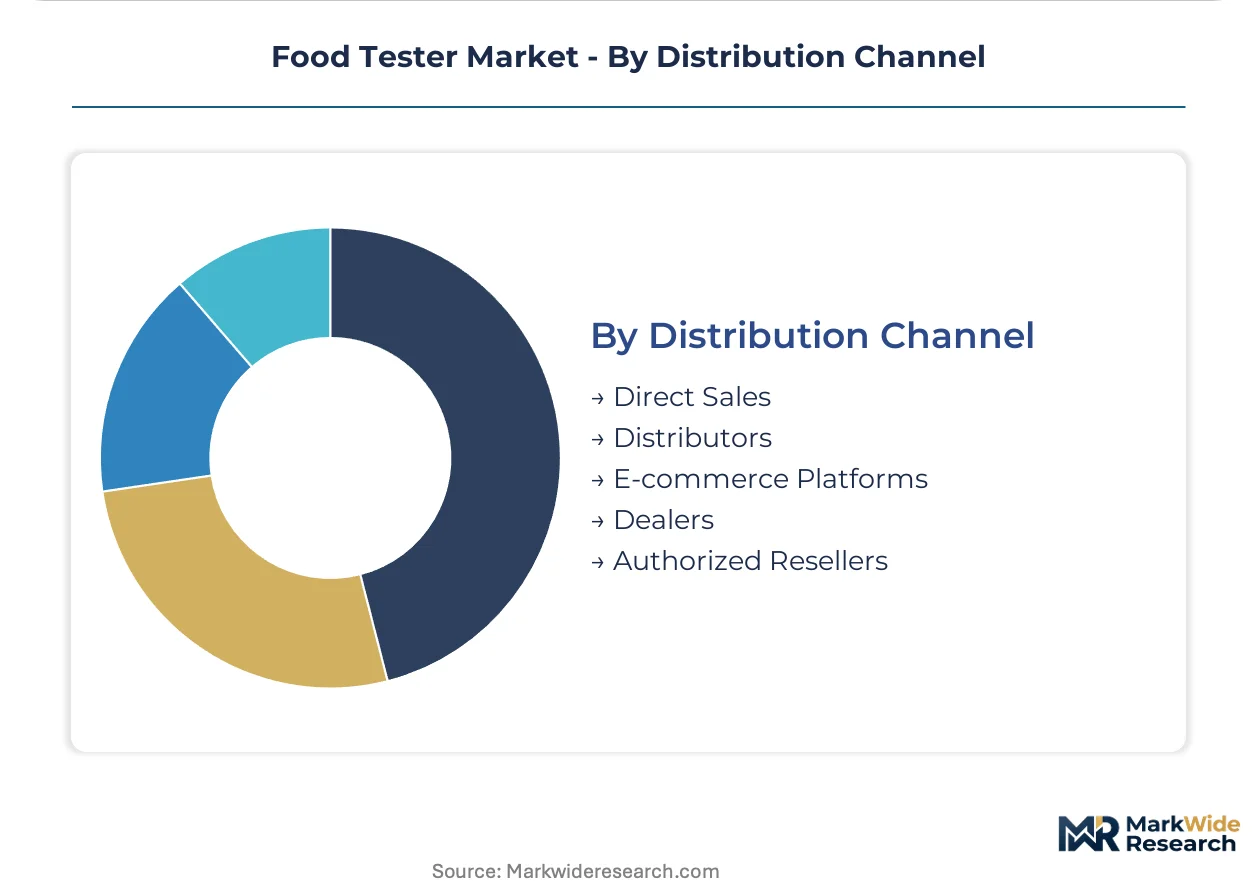
Distribution Channel:
Channel selection reflects capital intensity and technical support requirements.
- Direct Sales:Manufacturers maintain field engineering teams for complex spectrometry installations and validation support. Thermo Fisher Scientific and similar suppliers leverage direct relationships with multinational food manufacturers for multi-site deployments.
- Distributors:Regional inventory and service networks reduce lead times for replacement parts and consumables. Eurofins Scientific and SGS SA compete through bundled facility management contracts that include equipment provision.
- E-commerce Platforms:Standardized pH and moisture meters move through digital channels for small processor and restaurant laboratory procurement.
- Dealers:Local representation supports emerging market penetration where manufacturer direct presence remains limited.
- Authorized Resellers:Certified partners deliver installation and training services for mid-tier analytical platforms.
Direct Sales retains the largest transaction value, though Distributors are capturing share fastest through service-integrated offerings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Food tester equipment flows disproportionately toward export-oriented processing economies with stringent import verification regimes. Trade-dependent markets in Germany, China, and the United States absorb the highest equipment volumes as domestic safety mandates tighten and cross-border shipment protocols demand documented analytical compliance.
United States
Large-scale meat and dairy processors drive bulk orders for portable contamination screening units across Midwest and Southeast production corridors. FDA enforcement of Hazard Analysis and Critical Control Point verification protocols compels automated detection system installation at critical control points. Chicago and Omaha processing clusters favor service-integrated procurement models that bundle equipment access with regulatory method updates.
Germany
Multinational food manufacturers headquartered in Bavaria and North Rhine-Westphalia anchor European demand for benchtop analyzers with nutritional analysis precision. EFSA harmonization under the Official Control Regulation mandates standardized analytical methods across national reference laboratories. Munich and Hamburg laboratory networks compete directly with instrument manufacturers through testing-as-a-service bundles that reduce client capital expenditure.
China
Domestic laboratory equipment upgrades accelerate under SAMR enforcement of GB standards for heavy metal and additive limits. Processors in Yangtze River Delta and Pearl River Delta manufacturing zones face compulsion to achieve specific metrological certifications for both domestic and imported testing equipment. Shanghai and Shenzhen facilities drive replacement demand as regulatory thresholds tighten for contaminant detection workflows.
Japan
Precise optical component manufacturing in Chubu and Kansai regions supplies critical laser and detector inputs for high-resolution spectrometers. METI industrial standards shape validation requirements for food safety testing equipment deployed across domestic processing facilities. Osaka and Nagoya precision optics clusters expose international buyers to extended lead times for spectroscopy platform assembly.
India
Emerging laboratory infrastructure in Maharashtra and Gujarat drives demand for electrochemical sensing and near-infrared spectroscopy platforms. FSSAI implementation of standardized food safety protocols compels mid-tier processors to upgrade from manual testing methods. Mumbai and Ahmedabad quality control teams increasingly deploy portable units for rapid contaminant screening without laboratory infrastructure investment.
Food Tester Market Competitive Landscape
On the supply side, the industry is consolidating around three distinct capability tiers that separate capital-intensive instrument manufacturers from distributed service networks and specialized component suppliers. Full-spectrum analytical platform builders occupy the premium tier with direct multinational relationships. Testing-as-a-service aggregators capture mid-market share through facility management contracts that bundle equipment access with regulatory compliance documentation. Precision optics and sensor component specialists anchor the upstream tier with concentrated supply control over critical subsystems. Competitive dynamics center on vertical integration into consumables streams and geographic expansion through certified distributor networks.
Within the integrated laboratory services tier, Eurofins Scientific and SGS SA exemplify asset-light models that reduce client equipment purchases through distributed testing networks. Thermo Fisher Scientific Inc. occupies a position among capital equipment specialists sustaining deep research and development investment in detection platform miniaturization. These three entities represent contrasting strategic archetypes: service bundling versus hardware innovation versus facility management contracting.
| Leading Market Players |
|---|
| Eurofins Scientific |
| SGS SA |
| Bureau Veritas |
| Intertek Group plc |
| Thermo Fisher Scientific Inc. |
| ALS |
| NSF International |
| TÜV SÜD |
| Mérieux NutriSciences |
| Others |
Supply & Pricing Matrix
German and Japanese precision optics manufacturers control critical laser and detector supply for high-resolution spectrometers, concentrating margin capture upstream while downstream equipment vendors compete on service bundling and certification speed.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels, with differentiation driven by FDA validation tier and after-sales service bundling. Pricing pressure stems from mid-tier processors shifting toward testing-as-a-service models that eliminate capital expenditure. Food manufacturers in Germany and the United States show lowest price sensitivity due to regulatory compliance mandates, while emerging market laboratories exhibit highest sensitivity to upfront instrument costs.
Supply Chain Analysis
Extended payment terms and supply-chain finance facilities from precision optics suppliers in Germany, Japan, and the United States ease working capital constraints for spectrometer assemblers. Critical inputs include laser diodes, photodetector arrays, and specialized optical gratings. Single-source vulnerability concentrates in Chubu region precision manufacturing clusters. Distribution runs through authorized resellers with certified installation capabilities for complex benchtop platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The food tester market operates as a defensive-moat industry where regulatory entrenchment creates substantial switching costs for validated equipment platforms.
For Market Incumbents: Insulate installed base relationships by deepening captive supply of consumables and calibration standards, particularly for FDA-validated methods. Accelerate certification investment in China's SAMR GB standards to preempt domestic competitor displacement. Secure long-term facility management contracts with multinational food manufacturers before testing-as-a-service aggregators expand geographic coverage.
For New Entrants and Emerging Players: Build out portable Raman spectrometry offerings targeting mid-tier meat and dairy processors in India's Maharashtra and Gujarat regions where laboratory infrastructure remains underdeveloped. Penetrate through equipment-leasing partnerships with regional distributors who already maintain service relationships. Focus initial deployment on FSSAI-mandated safety protocols that compel upgrade from manual testing methods.
For Investors and Strategic Acquirers: Capital is best deployed toward precision optics component specialists with established relationships to German and Japanese manufacturing clusters, as these upstream positions capture durable margin pools. Long-term viability rests on regulatory method entrenchment rather than hardware innovation cycles. Watch for SAMR acceleration of GB standard enforcement as the signal indicating replacement demand inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Certification Acceleration | FDA and SAMR validation speed determines competitive access to replacement cycles in the United States and China. |
| Testing-as-a-Service Expansion | Eurofins and SGS service bundles reduce capital barriers and capture recurring revenue from mid-tier processors. |
| Precision Optics Backward Integration | In-house laser and detector production insulates margins from Japanese and German supplier lead time volatility. |
| Cloud-Connected Platform Development | Virtualized spectral libraries convert fixed instrument sales into subscription revenue streams. |
| Emerging Market Distributor Partnerships | Local service networks in India and Southeast Asia reduce deployment timelines for portable units. |
Research Methodology
The analysis maps portable testers, benchtop analyzers, spectrometers, and electrochemical sensors, each validated through quality control managers at food manufacturers, laboratory directors at contract testing facilities, and procurement leads at multinational processors. Primary interviews combined with secondary validation from FDA guidance documents, EFSA standardized method registers, SAMR GB standard publications, and customs trade data for analytical instrument imports. Bottom-up equipment shipment estimates triangulated against top-down processing facility counts across major manufacturing corridors.
Assumption sets held regulatory enforcement timelines and certification pathway durations within observed historical patterns while varying replacement cycle compression rates and service model adoption curves. Segmentation dimensions modeled include product type, application workflow, end-user procurement authority, and regional regulatory cluster. CAGRs derived from equipment shipment trajectories cross-referenced with processing capacity expansion in Germany, China, and the United States. Industry-specific inputs incorporated pathogen testing mandate expansion under FDA FSMA and heavy metal limit enforcement by SAMR.
The forecast holds incumbent behavior within observed patterns; aggressive moves by domestic Chinese instrument manufacturers or rapid cloud-platform disruption would shift outcomes. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Safety Testing
Allergen Testing Market
Food Safety Testing
US Food Allergen Testing Market
Food Safety Testing
Carbohydrates Testing Services Market
Food Safety Testing
Water Quality Testing Market
Food Safety Testing
Middle East and Africa Food Safety Testing Market
Food Safety Testing
Global Food Diagnostics Market
Food Safety Testing
Animal Feed Safety Testing Equipment Market
Food Safety Testing
US Legionella Testing Market
Food Safety Testing
Genetically Modified Food Safety Testing Market
Food Safety Testing
Global Lipid Testing Market
Food Safety Testing
Italy Food Safety Testing Market
Food Safety Testing
Food Traceability Solutions Market
Food Safety Testing
Central & South America Food Safety Testing Market
Food Safety Testing
Salt Meter Market
Food Safety Testing
Beverage Tester Market
Food Safety Testing
Meat Speciation Testing Service Market