
 Salmonella Testing Market | 2026-2036
Salmonella Testing Market Size, Share, and Industry Trends Forecast 2026-2036
Salmonella Testing Market Outlook
The EU Green Deal's farm-to-fork contamination targets is repositioning procurement priorities across European food safety networks. Thermo Fisher Scientific leverages its real-time PCR platform dominance to anchor molecular diagnostics contracts with multinational processors. bioMérieux SA specializes in automated culture confirmation systems that sustain long-term service relationships with reference laboratories. Neogen Corporation competes through rapid lateral flow devices that occupy on-site testing niches in meat and poultry plants.
Salmonella testing encompasses laboratory and point-of-use methods for detecting serovars of Salmonella enterica in food, clinical, and environmental matrices, typically employing selective enrichment followed by biochemical or genetic confirmation with sensitivity thresholds reaching single CFU per gram after enrichment. The primary purpose is preventing foodborne illness outbreaks and ensuring regulatory compliance across supply chains. PCR Kits capture premium pricing in high-complexity laboratories where turnaround time drives operational decisions, while Rapid Testing Devices expand fastest among processors seeking same-shift release authority. Conventional Culture methods retain stubborn utility in regulatory reference work despite molecular alternatives displacing them in routine screening.
The FDA enforces zero-tolerance standards for Salmonella in ready-to-eat products through its Food Safety Modernization Act framework, compelling manufacturers to validate preventive controls with documented testing protocols. EFSA coordinates baseline surveys across member states that harmonize detection methodologies and outbreak traceability requirements. China's SAMR implements GB standards that mandate pathogen testing for imported and domestic food products alike. Stakeholders must monitor how next-generation sequencing adoption reshapes regulatory acceptance criteria and laboratory capital allocation priorities.
Market Dynamics
Molecular diagnostics platforms are compressing detection timelines from days to hours, forcing laboratories to retire legacy culture workflows and reallocate capital toward automated PCR infrastructure.
Growth Catalysts
- FSMA preventive controls mandate:FDA enforcement compels food manufacturers to validate hazard analysis protocols with documented testing, sustaining instrument procurement cycles.
- Centralized meat processing clusters:High-throughput slaughter facilities in the United States and Germany generate concentrated demand for same-shift pathogen screening.
- Real-time PCR sensitivity thresholds:Single-CFU detection capability after enrichment eliminates false-negative risks that plagued biochemical confirmation methods.
Market Restraints
- Enzyme and reagent cost volatility:Polymerase supply concentrates among specialized biochemical manufacturers, exposing laboratories to input price swings.
- Reference method lock-in:Regulatory agencies still require culture-based confirmation for enforcement actions, forcing dual-method maintenance.
- Capital intensity of platform migration:Thermocycler and liquid handling automation demands seven-figure laboratory investments with five-year depreciation cycles.
Strategic Opportunities
- On-site lateral flow penetration:Meat and poultry processors seek same-shift release authority without external laboratory dependency.
- Next-generation sequencing convergence:Whole-genome serotyping integrated with epidemiological surveillance creates outbreak traceability value.
- EU Green Deal farm-to-fork targets:Contamination reduction mandates reposition procurement priorities across European food safety networks.
Industry Challenges
- Molecular biology technician scarcity:PCR protocol optimization and troubleshooting require specialized expertise absent in routine food microbiology laboratories.
- Multi-platform data integration:LIMS connectivity between legacy culture systems and new molecular instruments demands custom middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Salmonella Testing Market |
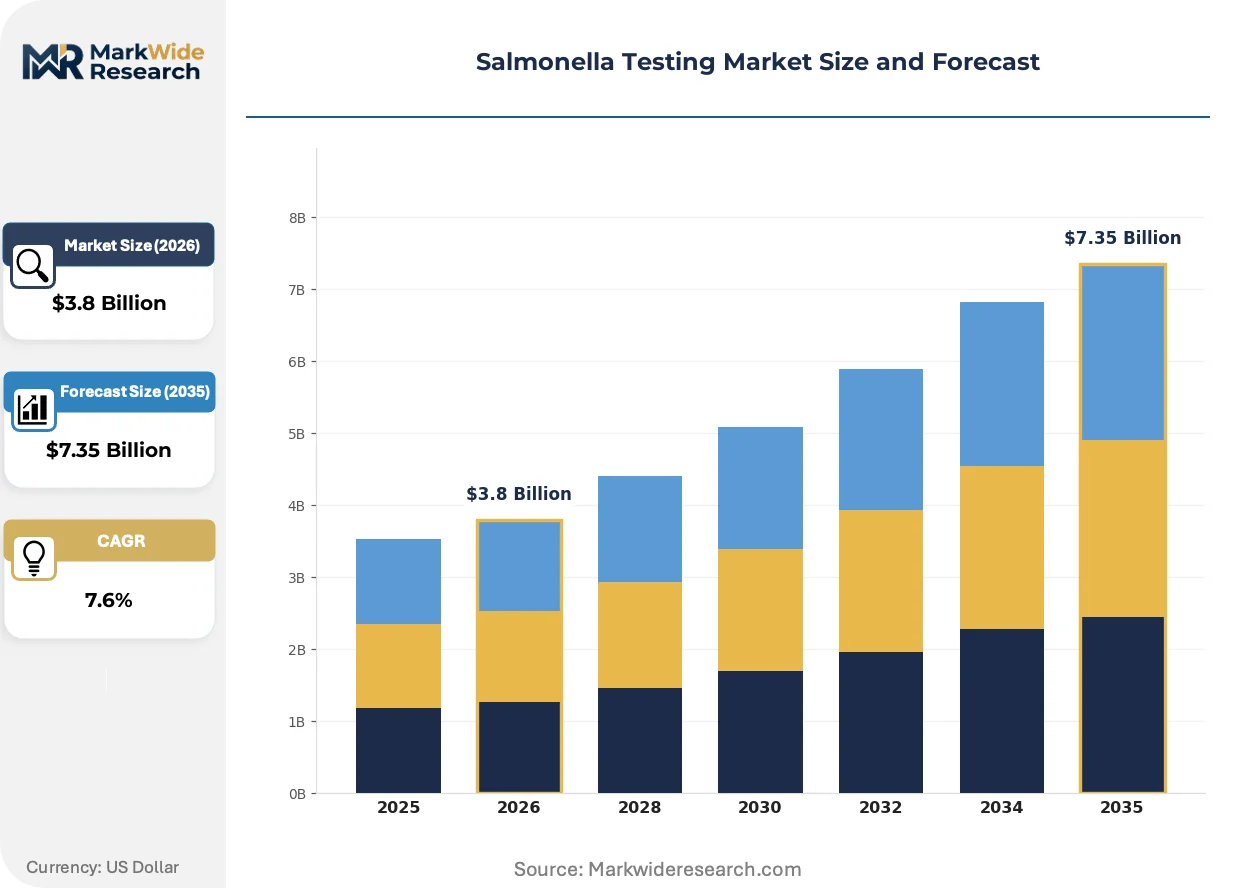
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $7.35 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: PCR Kits, Culture Media, Rapid Testing Devices, Immunoassay Kits End User: Hospitals, Food Safety Labs, Pharmaceuticals, Environmental Testing Facilities Technology: Conventional Culture, Molecular Diagnostics, Immunological Testing, Next-Generation Sequencing Application: Food Testing, Clinical Diagnostics, Water Quality Testing, Surface Testing |
| Companies Covered | Thermo Fisher Scientific, Merck KGaA, bioMérieux SA, QIAGEN N.V., Neogen Corporation, Eurofins Scientific, PerkinElmer Inc., 3M, Intertek Group plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Salmonella Testing Market Strategic Shifts
Detection methodology is fragmenting across the speed-versus-certainty spectrum, with laboratories adopting tiered architectures that deploy rapid screening for routine release while reserving reference methods for regulatory disputes.
Loop-mediated isothermal amplification (LAMP) is decentralizing Salmonella screening to processing plant floor stations. Mid-sized poultry processors in the United States adopt cartridge-based LAMP systems to bypass centralized laboratory queues. This diffusion is compressing the addressable market for reference laboratory services while expanding consumable pull-through at plant locations.
EFSA baseline survey harmonization mandates standardized detection methodologies across member states. Food business operators must align protocols with EU-wide outbreak traceability requirements. Ready-to-eat manufacturers in Germany and France face the steepest compliance adjustments as national reference laboratories consolidate method validation authority.
Service unbundling now separates instrument placement from reagent supply and data analytics. Multinational processors negotiate direct reagent contracts with diagnostics manufacturers while retaining third-party maintenance providers. This pattern is most pronounced in the United States, where vertically integrated meatpackers seek procurement leverage across multiple plant locations.
Salmonella Testing Market Segmentation
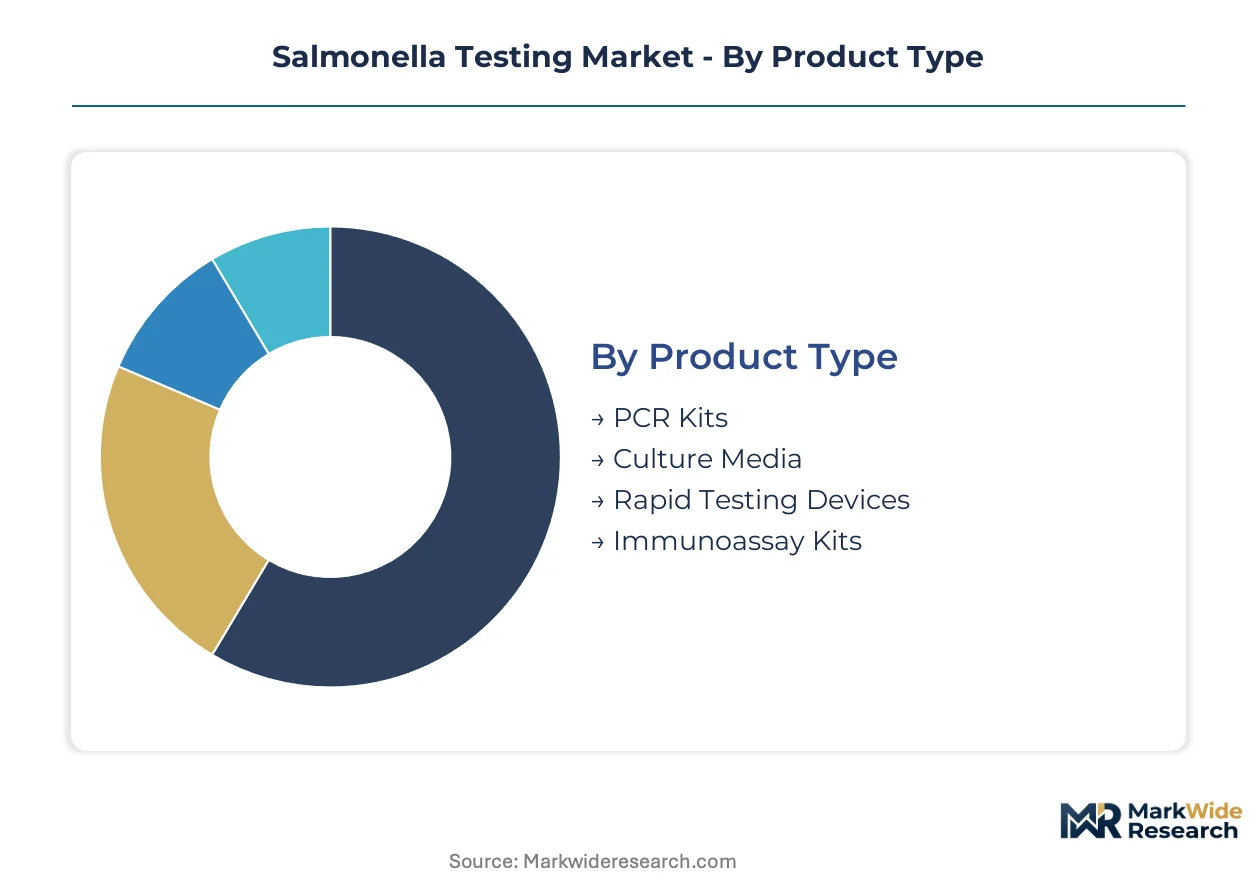
Salmonella testing procurement splits across four distinct decision frameworks: instrument capital allocation, end-use workflow requirements, detection technology performance thresholds, and regulatory compliance scope. Each dimension commands separate budget lines and vendor relationships within food safety organizations.
Product Type:
Laboratory directors prioritize detection sensitivity against per-test operating cost when selecting consumable platforms.
- PCR Kits:Real-time amplification chemistries achieve single-CFU sensitivity after selective enrichment. High-complexity laboratories in the United States and Germany anchor demand as FSMA and EU reference protocols validate molecular confirmation for enforcement documentation.
- Culture Media:Selective agar formulations and enrichment broths constitute the regulatory reference standard despite slower turnaround. Reference laboratories across Europe maintain dual-method workflows where culture confirmation remains mandatory for official control samples.
- Rapid Testing Devices:Lateral flow and immunochromatographic cartridges compress detection to same-shift timelines. Meat and poultry processors deploy these at receiving docks to bypass external laboratory queues.
- Immunoassay Kits:Enzyme-linked formats serve mid-throughput laboratories balancing cost against automation capability. Regional dairy processors in France and the Netherlands favor these for routine environmental monitoring programs.
Volume sits with Culture Media; growth tilts toward PCR Kits.
End User:
Budget authority and sample volume determine procurement sophistication across institutional categories.
- Food Safety Labs:Centralized reference facilities process regulatory enforcement samples and industry contract testing. EFSA-coordinated baseline surveys in Germany, France, and Italy sustain instrument refresh cycles as harmonized methods displace national variations.
- Hospitals:Clinical microbiology departments detect enteric salmonellosis in stool and blood specimens. Diagnostic stewardship programs in the United States are consolidating send-out testing to health system reference laboratories.
- Pharmaceuticals:Sterility testing and raw material release protocols demand validated pathogen absence. Vaccine manufacturers maintain dedicated microbiology suites with redundant detection platforms.
- Environmental Testing Facilities:Surface and water matrices require modified enrichment protocols for inhibitor tolerance. Agricultural runoff monitoring in the Netherlands and Denmark drives seasonal demand spikes.
Food Safety Labs command the largest installed base; Hospitals are expanding molecular platform adoption fastest.
Technology:
Capital depreciation horizons and technician skill availability shape platform migration decisions.
- Molecular Diagnostics:PCR and isothermal amplification platforms compress detection from days to hours. Thermocycler automation with integrated sample preparation is displacing manual protocols in high-throughput United States meatpacking laboratories.
- Conventional Culture:Enrichment, selective plating, and biochemical confirmation retain regulatory supremacy despite throughput limitations. China's SAMR reference laboratories mandate culture-based methods for import certification and domestic surveillance.
- Immunological Testing:Antibody-based formats trade sensitivity for speed in screening applications. Poultry processors across the southeastern United States deploy lateral flow devices at slaughter facility receiving bays.
- Next-Generation Sequencing:Whole-genome serotyping integrates outbreak surveillance with epidemiological traceability. Public health agencies in England and Denmark are piloting sequencing-based confirmation for cluster investigation.
Conventional Culture retains the broadest installed base; Next-Generation Sequencing is climbing the fastest as reference networks consolidate validation authority.
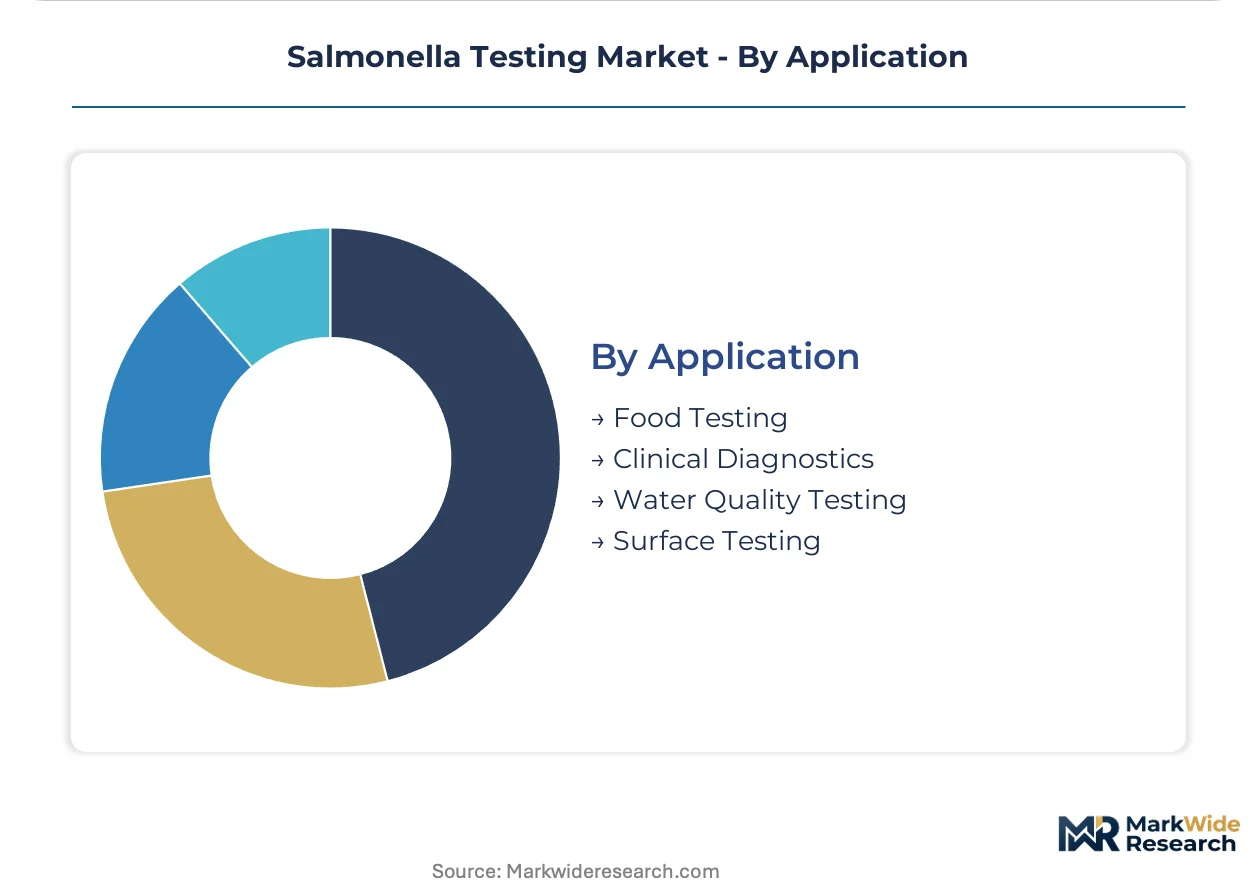
Application:
Matrix complexity and regulatory scrutiny intensity define testing protocol selection.
- Food Testing:Ready-to-eat products, raw meat, and poultry matrices dominate sample volume. Zero-tolerance enforcement by FDA and EFSA compels documented preventive controls with validated detection protocols.
- Clinical Diagnostics:Stool culture and blood stream infection identification guide therapeutic intervention. Hospital laboratories are adopting multiplex gastrointestinal panels that include Salmonella among enteric pathogens.
- Water Quality Testing:Recreational and potable water surveillance detects environmental contamination. Agricultural districts in California's Central Valley face seasonal monitoring mandates under regional water quality control board orders.
- Surface Testing:Environmental monitoring verifies sanitation efficacy in processing facilities. Swab-based sampling of equipment contact surfaces supports hazard analysis validation under FSMA preventive controls rules.
Food Testing absorbs the greatest consumable throughput; Clinical Diagnostics is gaining share fastest as hospital-acquired infection surveillance expands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chicago's meatpacking corridor concentrates North American pathogen testing demand as centralized slaughter facilities drive same-shift screening volume.
United States
High-throughput poultry processors in Georgia and Arkansas deploy LAMP-based floor stations to bypass external laboratory queues. FDA's FSMA preventive controls mandate compels documented testing protocols across ready-to-eat manufacturers. Nebraska's beef processing clusters anchor instrument procurement cycles for molecular diagnostics platforms.
Germany
EFSA baseline survey harmonization forces national reference laboratories to consolidate method validation authority. The EU Green Deal's farm-to-fork contamination targets reposition procurement priorities across food safety networks. Bavaria's dairy cooperatives face steepest compliance adjustments as standardized protocols displace regional variations.
China
SAMR's GB standards mandate pathogen testing for imported and domestic food products alike. Shanghai's centralized food processing districts generate sustained testing volume for molecular confirmation workflows. Guangdong's poultry export facilities maintain dual-method capabilities for trade certification requirements.
United Kingdom
Public Health England pilots whole-genome serotyping for outbreak traceability in cluster investigations. Post-Brexit regulatory divergence creates uncertainty around reference method acceptance criteria. Yorkshire's ready-to-eat manufacturing belt sustains consumable demand for rapid screening devices.
Netherlands
Agricultural runoff monitoring drives seasonal demand spikes for environmental testing protocols. Wageningen's food safety research cluster influences method adoption patterns across European processors. The country's centralized laboratory infrastructure accelerates platform migration toward automated PCR systems.
Salmonella Testing Market Competitive Environment
Premium-margin players sit above commodity-margin players across the speed-versus-certainty spectrum, with molecular diagnostics specialists commanding pricing power against culture-media suppliers. The vendor base organizes into three tiers: multinational platform manufacturers anchoring high-complexity laboratories, regional reagent suppliers serving mid-throughput processors, and point-of-use device specialists penetrating plant-floor applications. Consolidation pressures intensify as service unbundling separates instrument placement from consumable supply. Strategic partnerships between diagnostics manufacturers and third-party maintenance providers reshape procurement leverage for vertically integrated meatpackers.
Among platform-anchoring multinationals, Thermo Fisher Scientific and bioMérieux SA exemplify divergent specialization archetypes. Thermo Fisher's real-time PCR platform dominance anchors molecular diagnostics contracts with multinational processors seeking sensitivity thresholds. bioMérieux occupies a position within automated culture confirmation systems that sustain long-term service relationships with European reference laboratories. Neogen Corporation represents the point-of-use penetration strategy, with rapid lateral flow devices occupying on-site testing niches in meat and poultry plants seeking same-shift release authority.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| Merck KGaA |
| bioMérieux SA |
| QIAGEN N.V. |
| Neogen Corporation |
| Eurofins Scientific |
| PerkinElmer Inc. |
| 3M |
| Intertek Group plc |
| Others |
Value Chain & Pricing Dynamics
Captive reagent supply agreements anchor pricing power for molecular diagnostics manufacturers serving high-throughput food safety laboratories, locking processors into multi-year consumable contracts that resist spot-market volatility. Thermo Fisher Scientific and bioMérieux SA leverage backward integration into polymerase and selective media formulations to defend margin structures against commodity reagent suppliers.
Pricing Analysis
Outcome-based pricing tied to detection sensitivity thresholds and same-shift release authority commands premium positioning for PCR platforms against conventional culture workflows. Three-tier pricing structure across premium, standard, and economy levels separates real-time PCR kits from automated culture confirmation systems and rapid lateral flow devices. Cost compression in the rapid testing tier is intensifying because meat processors negotiate direct reagent contracts bypassing distributor markups. Small regional laboratories exhibit highest price sensitivity; multinational meatpackers with volume concentration leverage exhibit lowest.
Supply Chain Analysis
Domestic-content mandates under China's SAMR GB standards and EU Green Deal procurement rules are reshaping sourcing patterns for enrichment media and diagnostic reagents. Polymerase production concentrates in the United States, Germany, and China; selective agar formulations draw from specialized biochemical manufacturers in France and Japan. Taq polymerase, enrichment broths, and lateral flow membranes constitute critical input dependencies. Single-source vulnerability in thermostable enzyme supply creates exposure to fermentation capacity constraints. Distribution runs through authorized distributor networks for reference laboratories and direct sales forces for plant-floor device deployment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Salmonella testing market sits in a technology-transition phase where real-time PCR platforms displace culture-based workflows in routine screening, forcing stakeholders to reposition around speed-versus-certainty value propositions.
For Market Incumbents: Anchor platform dominance through reagent contract bundling that locks high-throughput processors into multi-year consumable commitments. Defend against LAMP-based decentralization by accelerating cartridge-based system development for plant-floor deployment. Invest in automated sample preparation modules that reduce technician skill requirements and sustain laboratory capital refresh cycles. For New Entrants and Emerging Players: Enter via underserved mid-sized poultry processors in the southeastern United States seeking same-shift release authority without seven-figure capital investments. Target environmental testing facilities in the Netherlands and Denmark facing seasonal agricultural runoff monitoring mandates. Pursue service-unbundling partnerships that separate instrument maintenance from reagent supply, capturing procurement leverage from vertically integrated meatpackers. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisitions by multinational diagnostics platforms seeking molecular biology capability fill-ins. Long-term viability favors automated workflow specialists with regulatory reference method validation across multiple jurisdictions. Watch next-generation sequencing adoption rates in public health reference networks as the inflection signal for serotyping market displacement.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Thermocycler automation with sample preparation modules reduces technician labor costs for FSMA-compliant laboratories. |
| Regulatory Approval Pathway | EFSA harmonized method validation opens procurement access across Germany, France, and Italy reference networks. |
| Backward Integration | In-house polymerase fermentation capacity buffers input cost volatility from specialized biochemical suppliers. |
| Geographic Expansion | Guangdong and Shanghai facility presence satisfies SAMR GB standards for domestic and import certification testing. |
| Strategic Partnership | Third-party maintenance alliances separate service revenue from instrument placement for meatpacker procurement leverage. |
Study Parameters
SEC filings, FDA enforcement documentation, and EFSA baseline survey publications formed the secondary backbone, cross-referenced with customs records for diagnostic reagent trade flows. Primary interviews with food safety laboratory directors, regulatory affairs managers at multinational processors, and diagnostics manufacturer product managers validated instrument procurement cycle assumptions. Bottom-up and top-down triangulation reconciled consumable volume estimates against capital equipment installed base calculations.
Bottom-up modeling built from segment-level detection technology adoption curves, while top-down verification checked aggregate market evolution against regulatory mandate implementation timelines. Segmentation dimensions included product type, end-user category, technology platform, and application matrix across food, clinical, environmental, and surface testing workflows. CAGRs derived from instrument replacement cycles and consumable pull-through rates per installed platform. FSMA preventive controls enforcement intensity and EU Green Deal farm-to-fork targets served as demand-side forecast anchors.
Forecast precision tightens around the base case; tail outcomes carry wider variance under sequencing-based regulatory acceptance acceleration or polymerase supply disruption scenarios. Forecasts reflect documented assumptions regarding reference method validation timelines and laboratory capital allocation priorities. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Safety Testing
Rapid Microbiology Testing Market
Food Safety Testing
Food Tester Market
Food Safety Testing
Food Safety Testing Services Market
Food Safety Testing
Edible Oil Adulteration Testing Chemicals Market
Food Safety Testing
Beverage Tester Market
Food Safety Testing
Chromatography Food Testing Market
Food Safety Testing
Ireland Food Testing Market
Food Safety Testing
Genetically Modified Food Safety Testing Market
Food Safety Testing
Shelf-Life Testing Market
Food Safety Testing
Global Food Diagnostics Market
Food Safety Testing
Europe Food Safety Testing Market
Food Safety Testing
Allergen Testing Market
Food Safety Testing
Water Quality Testing Market
Food Safety Testing
Vitamin Test Market
Food Safety Testing
Global Inline Metal Detector Market
Food Safety Testing
Meat Speciation Testing Service Market