
 North America IT Asset Disposition Market | 2026-2036
North America IT Asset Disposition Market Size, Share, and Industry Trends Forecast 2026-2036
North America IT Asset Disposition Market Insights
The capital-intensity divergence between integrated ITAD providers and regional dismantlers is unwinding competitive stability across North America. Dell Technologies leverages its reverse logistics network to capture enterprise refresh cycles directly from original equipment placements. Iron Mountain sustains dominance in secure chain-of-custody services through its physical infrastructure footprint. Sims Limited anchors volume processing capabilities through metals recovery specialization at industrial scale.
IT asset disposition encompasses the secure decommissioning, data sanitization, remarketing, and environmentally responsible recycling of retired enterprise technology equipment, requiring NIST 800-88 compliant overwrite verification or physical destruction for storage media containing sensitive information. The practice serves organizations managing cybersecurity risk exposure, regulatory compliance documentation, and recovery of residual value from depreciated hardware. Data destruction services command premium margins relative to commodity recycling due to liability concentration and certification requirements. Resale channels for servers and networking equipment retain value recovery advantages over mobile devices given longer enterprise depreciation cycles and secondary market depth.
The EPA oversees baseline hazardous waste handling under RCRA while NIST publishes media sanitization standards that contractually bind federal suppliers and their subcontractors. State-level extended producer responsibility frameworks in California and New York impose additional registration and collection targets on manufacturers and their designated recyclers. Stakeholders must monitor emerging SEC climate disclosure rules that will require documented e-waste diversion metrics from covered enterprises.
Market Dynamics
Enterprise data center consolidation cycles are compressing hardware refresh timelines across the United States and Canada, forcing ITAD providers to scale secure chain-of-custody infrastructure faster than organic capacity expansion permits.
Growth Catalysts
- Financial services compliance mandates:Banks and insurance carriers require NIST 800-88 certified destruction documentation for audit trails, creating recurring contracted demand for verified data sanitization services.
- California's SB-20 framework:Extended producer responsibility rules mandate manufacturer-funded collection targets, directing enterprise volumes toward certified R2 and e-Stewards processors.
- Silicon Valley cluster concentration:Hyperscale cloud operators and semiconductor fabs generate concentrated retirement volumes of servers and networking equipment with recoverable residual value.
Market Restraints
- Capital intensity for secure logistics:GPS-tracked transport fleets and tamper-evident packaging requirements demand sustained fleet investment that regional dismantlers cannot finance.
- Smelter concentration in Asia:Precious metals recovery depends on export flows to specialized copper and gold refiners, exposing processors to shipping cost volatility and trade policy friction.
- Labor scarcity for certified technicians:R2 and e-Stewards auditing requirements limit the pool of qualified personnel capable of executing witnessed destruction protocols.
Strategic Opportunities
- Canadian provincial EPR expansion:Ontario and British Columbia are implementing manufacturer-funded electronics recycling frameworks that will formalize ITAD service procurement across federal and provincial agencies.
- SEC climate disclosure rules:Documented e-waste diversion metrics will become mandatory disclosure items for covered enterprises, creating audit-grade service tier demand.
- AI inference hardware retirement:GPU-intensive machine learning clusters are reaching end-of-life with specialized memory sanitization requirements and premium resale channels for accelerators.
Industry Challenges
- Certification timeline compression:R2v3 and e-Stewards 4.0 standard updates require facility re-auditing and documentation system overhauls that strain mid-scale operators.
- Chain-of-custody system integration:Enterprise clients demand real-time tracking APIs that connect ITAD workflows to their existing IT service management platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America IT Asset Disposition Market |
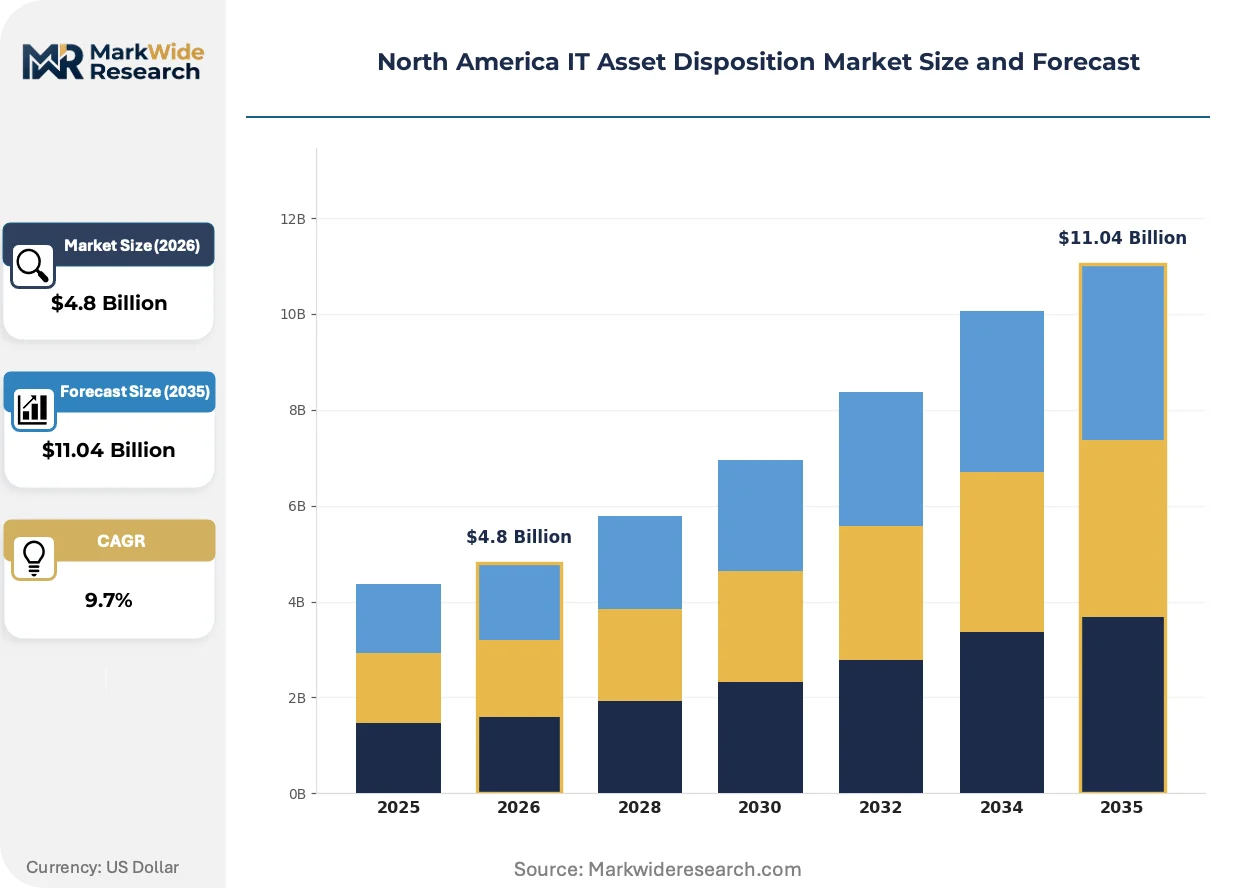
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $11.04 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Recycling, Resale, Data Destruction, Donation End User: Corporations, Educational Institutions, Government Agencies, Small Businesses Product Type: Computers, Servers, Mobile Devices, Networking Equipment Technology: Cloud Solutions, IT Asset Management Software, E-Waste Treatment, Mobility Solutions |
| Companies Covered | Dell Technologies, Iron Mountain, IBM, Hewlett Packard Enterprise, Arrow Electronics, Apto Solutions, Sims Limited, ITRenew, LifeSpan International, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America IT Asset Disposition Market Trends and Innovations
Automation is penetrating data destruction verification workflows, replacing manual witness protocols with cryptographic attestation systems that reduce labor dependency while tightening audit reliability.
Cryptographic verification modules are embedding tamper-evident signatures directly onto storage device controllers during overwrite sequences. Financial services and healthcare providers are piloting these systems for high-volume laptop and mobile device retirement. This approach is displacing human witness requirements for Category 1 sanitization, compressing per-unit processing costs and enabling overnight batch destruction cycles.
EPA enforcement of RCRA hazardous waste classifications for lithium-ion battery handling is tightening across the United States. The agency's revised interpretation classifies damaged or end-of-life battery packs as universal waste requiring manifest documentation. Enterprise data centers with uninterruptible power supply systems are most affected, accelerating partnerships with processors holding EPA ID numbers and DOT hazmat certifications.
Subscription-based ITAD contracting is replacing transactional per-pound pricing for enterprise accounts. Fortune 500 technology departments are consolidating vendor relationships into multi-year agreements with guaranteed service level agreements for pickup windows and certificate turnaround times. This pattern is most visible in Texas and Illinois manufacturing corridors where industrial IoT device retirement volumes are scaling faster than procurement teams can manage spot vendor relationships.
North America IT Asset Disposition Market Segmentation
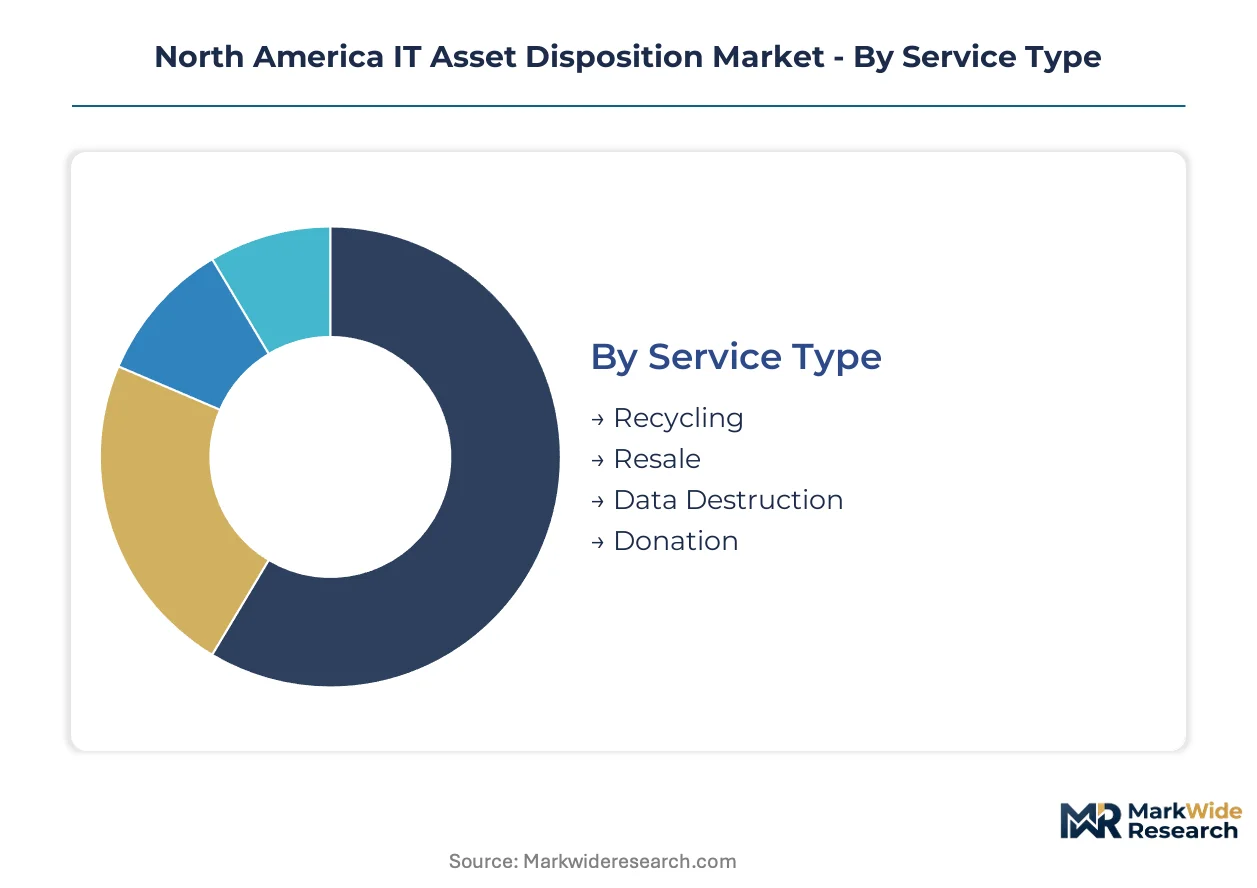
IT asset disposition service providers structure their offerings around liability concentration, regulatory certification tiers, and residual value recovery potential. Segmentation reflects how enterprise procurement teams evaluate vendor capabilities against NIST 800-88 compliance requirements and chain-of-custody documentation standards.
Service Type:
EPA RCRA hazardous waste classifications and NIST media sanitization mandates create distinct compliance obligations that segment service pricing and vendor qualification requirements across the United States and Canada.
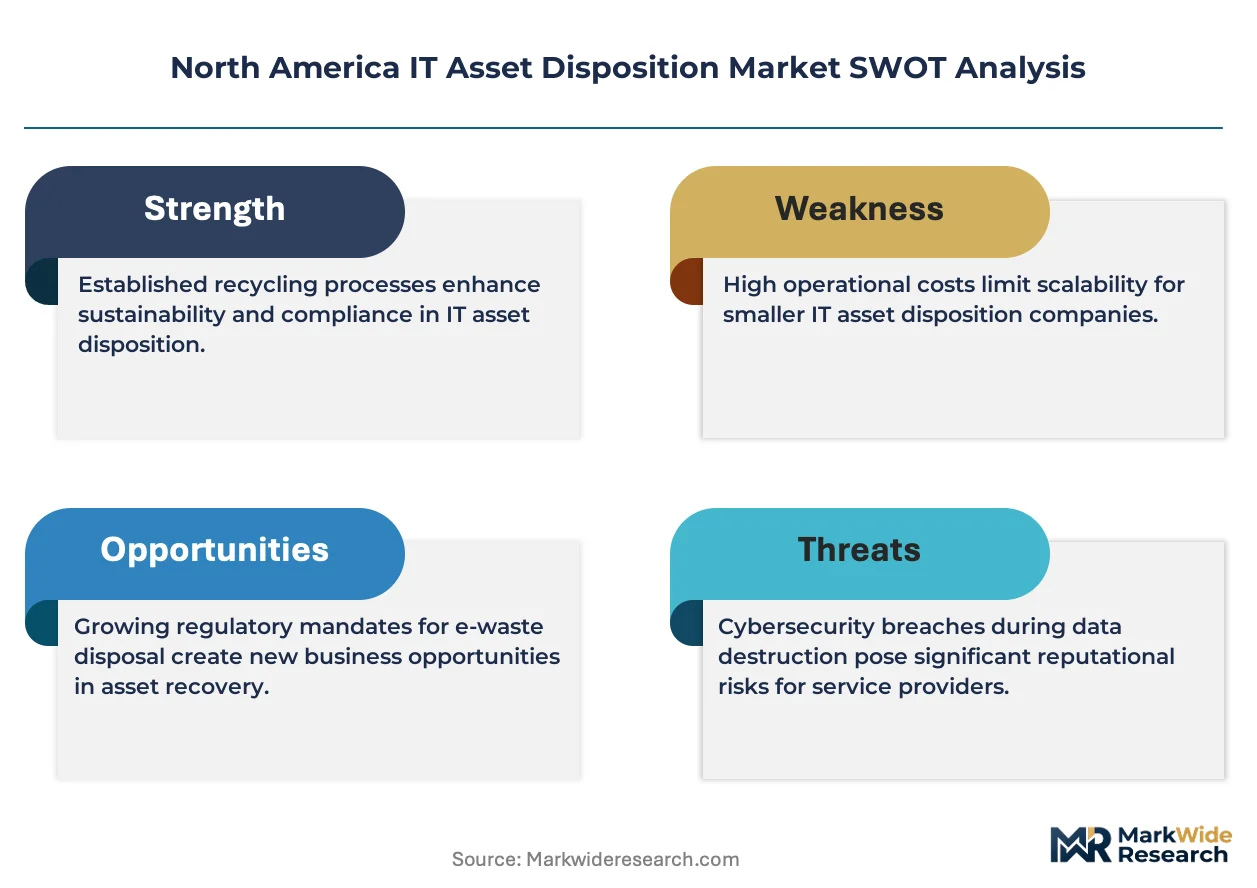
- Recycling:Industrial-scale processing of end-of-life electronics through R2 or e-Stewards certified facilities. Demand concentrates in California's Silicon Valley corridor where enterprise data center refresh cycles generate concentrated volumes of server boards and power supply units requiring precious metals recovery.
- Resale:Remarketing of depreciated enterprise hardware through secondary channels with verified data sanitization documentation. Financial services firms in New York and Chicago drive premium pricing for certified refurbishment with full audit trails.
- Data Destruction:NIST 800-88 compliant overwrite verification or physical destruction protocols for storage media containing sensitive information.
- Donation:Charitable redistribution of functional equipment with tax documentation and liability transfer mechanisms.
Recycling handles the majority of throughput; data destruction is the fastest mover on share as financial services compliance mandates tighten.
End User:
Procurement scale and audit complexity separate enterprise accounts from transactional service relationships across North American markets.
- Corporations:Fortune 500 technology departments managing multi-site hardware retirement with real-time tracking API requirements. Hyperscale cloud operators in Washington State and Texas generate the largest contracted volumes with guaranteed service level agreements for pickup windows.
- Government Agencies:Federal and provincial entities bound by NIST 800-88 contractual requirements and documented chain-of-custody protocols. Canadian federal procurement under Ontario and British Columbia EPR frameworks is formalizing ITAD service tiers.
- Educational Institutions:Universities and K-12 districts with seasonal refresh cycles and grant-funded technology replacement programs.
- Small Businesses:Spot-market relationships with per-pound pricing and minimal documentation requirements.
Corporations command the highest contract values; government agencies are expanding most quickly as Canadian provincial EPR frameworks mature.
Product Type:
Depreciation cycles and secondary market depth determine residual value recovery rates across hardware categories.
- Servers:Enterprise rack and blade systems with three-to-five-year depreciation schedules and active secondary markets for memory and processor components. Silicon Valley semiconductor fabs and hyperscale operators in Northern California generate concentrated retirement volumes with premium resale channels.
- Networking Equipment:Switches, routers, and firewalls with longer enterprise depreciation cycles and specialized memory sanitization requirements for configuration data.
- Computers:Desktop and laptop fleets with standardized NIST 800-88 overwrite protocols and high-volume processing economics.
- Mobile Devices:Smartphones and tablets with shorter replacement cycles and compressed residual value recovery windows.
Servers retain the highest per-unit recovery values; mobile devices are climbing the fastest on processing volume as enterprise mobility programs scale.
Technology:
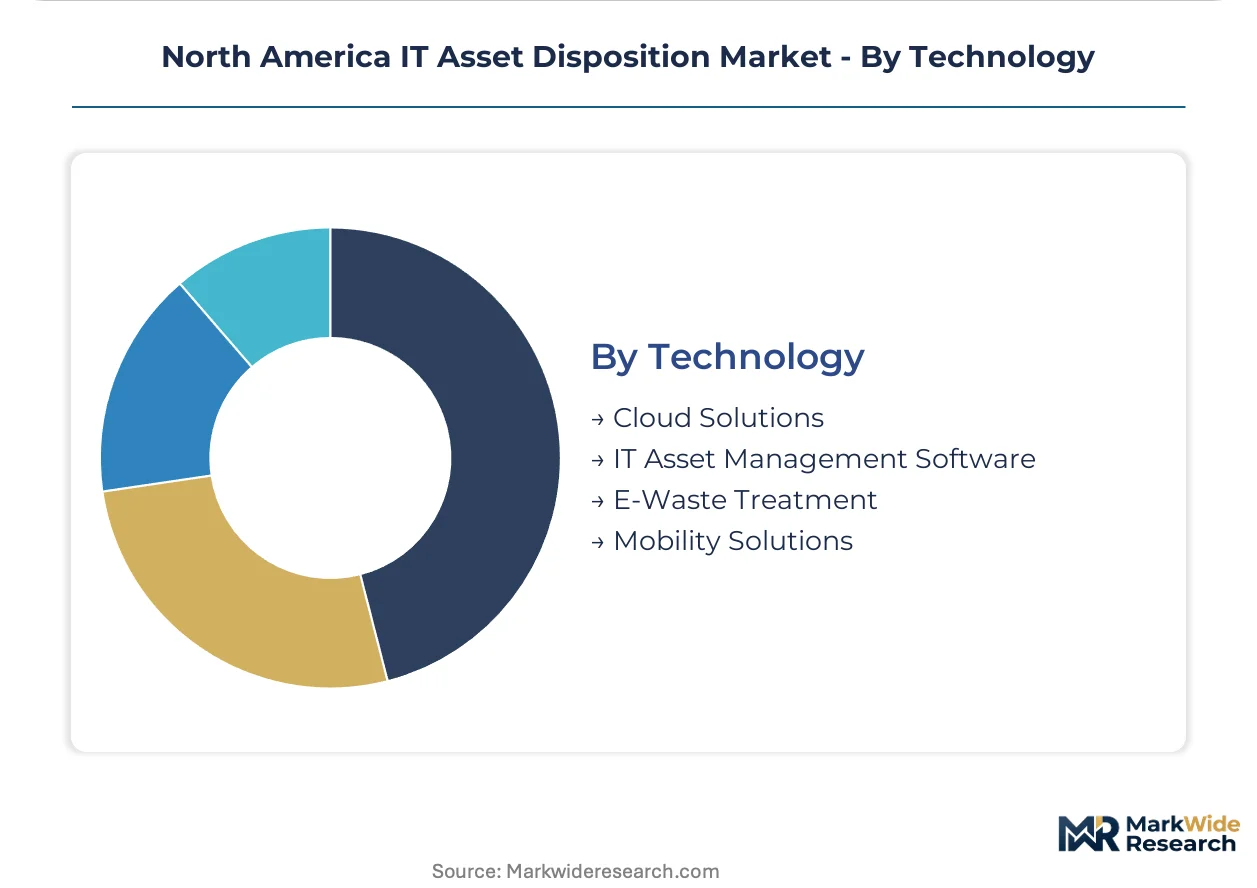
Automation penetration and system integration capabilities separate premium service tiers from commodity processing across North American provider networks.
- IT Asset Management Software:Real-time inventory tracking and certificate-of-destruction documentation systems integrated with enterprise IT service management platforms. Financial services and healthcare providers in Boston and Minneapolis are piloting cryptographic attestation modules for high-volume device retirement.
- Cloud Solutions:Subscription-based contracting with guaranteed service level agreements replacing transactional per-pound pricing for enterprise accounts.
- E-Waste Treatment:Industrial-scale dismantling, shredding, and metals separation processes with EPA hazardous waste manifest documentation.
- Mobility Solutions:GPS-tracked transport fleets and tamper-evident packaging for secure chain-of-custody enforcement.
IT asset management software commands the highest implementation margins; cloud solutions are gaining share fastest as Fortune 500 procurement teams consolidate vendor relationships.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Mexico's informal sector exhibit the highest price sensitivity, while Fortune 500 procurement teams in the United States absorb premium pricing for certified chain-of-custody documentation. Canadian federal agencies occupy a mid-tier elasticity position, balancing compliance mandates against budget constraints.
United States
Financial services firms in New York and Chicago drive contracted demand for NIST 800-88 certified destruction with full audit trails. The EPA enforces RCRA hazardous waste classifications for lithium-ion battery handling from enterprise UPS systems. Silicon Valley's hyperscale cloud operators generate concentrated server retirement volumes with active secondary markets for memory components.
Canada
Ontario and British Columbia are implementing manufacturer-funded electronics recycling frameworks that formalize ITAD procurement across federal agencies. Health Canada coordinates with provincial regulators on hazardous waste manifest documentation for cross-border equipment flows. Toronto's financial district generates premium-tier demand for secure data destruction with real-time tracking integration.
Mexico
Maquiladora operations along the northern border states generate growing volumes of retired industrial IoT and automation equipment. The country's federal environmental prosecutor enforces hazardous waste regulations that increasingly align with R2 certification standards. Guadalajara's electronics manufacturing cluster is emerging as a secondary processing hub for North American e-waste diversion.
California
SB-20 extended producer responsibility rules mandate manufacturer-funded collection targets directing enterprise volumes toward certified processors. The state's Department of Toxic Substances Control audits R2 and e-Stewards facilities with heightened enforcement frequency. San Jose and Santa Clara County host the densest concentration of semiconductor fabs and cloud data centers undergoing accelerated refresh cycles.
Texas
Energy sector data centers in Dallas-Fort Worth and Houston drive demand for UPS battery retirement with EPA hazardous waste documentation. The Texas Commission on Environmental Quality oversees industrial e-waste permitting with evolving standards for precious metals recovery facilities. Austin's technology corridor generates mixed enterprise and mid-market volumes with growing subscription-based ITAD contracting adoption.
North America IT Asset Disposition Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, creating a two-speed competitive structure where scale and certification depth determine contract access. Dell Technologies leverages its reverse logistics network to capture enterprise refresh cycles directly from original equipment placements. Iron Mountain sustains dominance in secure chain-of-custody services through its physical infrastructure footprint. Three archetypes dominate: integrated technology vendors with captive logistics, specialized secure storage operators with ITAD extensions, and industrial-scale metals recovery processors. Competitive moves concentrate on multi-year subscription contracting with guaranteed SLAs and cryptographic attestation system deployment for automated verification.
Among integrated technology vendors, Dell Technologies and Hewlett Packard Enterprise exemplify the equipment-origin archetype, leveraging manufacturing relationships to secure downstream disposition volumes. Iron Mountain occupies a distinctive position bridging physical records management with secure ITAD services, representing the infrastructure-heavy specialist tier. Sims Limited anchors the industrial processing segment, exemplifying scale-driven metals recovery specialization. These three patterns illustrate how competitive positioning depends on upstream control over equipment flows, captive secure logistics networks, or downstream precious metals refining relationships.
| Leading Market Players |
|---|
| Dell Technologies |
| Iron Mountain |
| IBM |
| Hewlett Packard Enterprise |
| Arrow Electronics |
| Apto Solutions |
| Sims Limited |
| ITRenew |
| LifeSpan International |
| Others |
Pricing and Supply Chain Analysis
R2 and e-Stewards certification requirements simultaneously gate supplier qualification tiers and stratify price premiums across North American ITAD markets. Financial services procurement teams absorb 40-60% premiums for witnessed destruction protocols while regional dismantlers compete on per-pound commodity rates without audit-grade documentation.
Pricing Analysis
Multi-year subscription contracts with guaranteed SLAs now drive lifetime customer value beyond transactional per-pound revenue. Three-tier pricing structure across certified audit-grade, standard commercial, and spot-market commodity levels reflects NIST 800-88 compliance depth and chain-of-custody rigor. Cost compression in standard commercial tiers is intensifying because GPS-tracked fleet operators are consolidating regional dismantler relationships. Small businesses and K-12 districts exhibit highest price sensitivity; Fortune 500 technology departments and federal agencies absorb premium tiers without elasticity.
Supply Chain Analysis
China, South Korea, and Japan anchor precious metals refining capacity for copper, gold, and rare earth recovery from shredded circuit boards. North American ITAD processors draw from domestic collection networks but remain tethered to Asian smelter relationships for final materials extraction. Single-source vulnerability concentrates in specialized lithium-ion battery refining where EPA hazardous waste manifest requirements intersect with limited DOT-certified transport capacity. Distribution runs through enterprise direct contracts, OEM reverse logistics partnerships, and regional dismantler spot markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory-moat defense where certification entrenchment creates switching costs that lock enterprise accounts into multi-year relationships. NIST 800-88 compliance documentation requirements embed providers into audit workflows that resist vendor substitution.
For Market Incumbents: Secure cryptographic attestation system deployment to displace labor-intensive witness protocols and compress per-unit processing costs. Expand R2v3 and e-Stewards 4.0 re-audit capacity before mid-scale competitors complete facility upgrades. Certification timeline compression threatens margin stability for operators with single-facility footprints. For New Entrants and Emerging Players: Differentiate on Canadian provincial EPR framework compliance as Ontario and British Columbia formalize government procurement tiers. Target AI inference hardware retirement verticals where GPU memory sanitization requirements exceed standard overwrite protocols. Lead with API-first IT service management platform integration to bypass incumbent documentation system lock-in. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across secure logistics fleet and facility certification categories. Five-to-ten year viability favors integrated providers with captive reverse logistics networks over pure-play dismantlers exposed to metals price volatility. Acquisition target archetype: mid-scale regional operators with EPA ID numbers and pending R2v3 certification in underserved Texas or Illinois corridors. Signal to monitor: SEC climate disclosure rule implementation pace driving audit-grade service tier demand inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Year Subscription Contracting | Fortune 500 procurement teams consolidate vendor relationships into guaranteed SLA frameworks. |
| Cryptographic Attestation Deployment | Financial services pilots displace manual witness requirements with tamper-evident verification modules. |
| Canadian EPR Framework Compliance | Ontario and British Columbia procurement formalization creates government-tier service demand. |
| AI Hardware Retirement Specialization | GPU-intensive cluster end-of-life requires specialized memory sanitization and accelerator resale channels. |
| Secure Logistics Fleet Expansion | GPS-tracked transport and tamper-evident packaging investments separate premium from commodity tiers. |
Research Methodology
Initial hypotheses were tested against primary input from ITAD operations directors, enterprise procurement officers, compliance auditors, and EPA regional enforcement staff and refined through secondary validation. Primary fieldwork combined facility site assessments with structured interviews across R2-certified processors, e-Stewards facilities, and financial services asset management teams. Secondary sources encompassed EPA RCRA enforcement records, NIST 800-88 revision documentation, SEC climate disclosure proposals, and provincial EPR framework filings. Bottom-up volume modeling triangulated against top-down market sizing from hardware shipment depreciation curves.
Variance decomposition across the projection horizon isolates volume drivers from price-mix effects within service type, end user, and product type segmentations. The analytical framework models IT asset management software penetration, cloud solution adoption curves, and mobility solution deployment intensity as technology-tier inputs. CAGRs derive from hardware refresh cycle compression rates intersecting with compliance mandate expansion timelines. Forecast inputs include enterprise data center consolidation velocity, lithium-ion battery retirement volumes from UPS systems, and AI inference hardware replacement cycles.
Material uncertainties — trade policy friction affecting precious metals export flows, R2v3 audit backlog delays, and SEC disclosure rule implementation timing — sit outside the modeled envelope. Forecasts reflect assumptions about certification standard stability and enterprise procurement centralization trends. Recalibration cycles align with material shifts in EPA enforcement posture and provincial EPR framework maturity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Contact Tracing Application Market
Digital Solutions
France Digital Twin Market
Digital Solutions
Consent Management Market
Digital Solutions
Business As a Service Market
Digital Solutions
Correspondence Management Solution Market
Digital Solutions
Lecture Capture Systems Market
Digital Solutions
Europe Digital Shipyard Market
Digital Solutions
Business Document Work Process Management Market
Digital Solutions
Game Engines Market
Digital Solutions
Business Transcription Market
Digital Solutions
Global Freight Software Market
Digital Solutions
Asia-Pacific Multichannel Order Management Market
Digital Solutions
Self-Service Kiosk Market
Digital Solutions
Employee Recognition and Reward System Market
Digital Solutions
Asia-Pacific Digital Twin Market
Digital Solutions
Product Engineering Services Market