
 China Home Textiles Market | 2026-2036
China Home Textiles Market Size, Share, and Industry Trends Forecast 2026-2036
China Home Textiles Market Outlook
Subscription-based refresh programs for bed linen and curtain sets is realigning how Chinese households consume home textiles, shifting purchase patterns from episodic replacement to scheduled replenishment. Hengli Petrochemical leverages its upstream polyester capacity to secure feedstock cost advantages across the value chain. Zhejiang Hangmin anchors its position through integrated spinning-weaving-finishing operations in Zhejiang province. Shanghai Shuixing Home Textile differentiates via direct-to-consumer digital channels that bypass traditional wholesale layers.
China home textiles encompass woven, knitted, and non-woven fabric articles designed for residential interior applications, with specifications typically spanning thread counts from 200 to 800 for bed linen and flame-retardant treatments for curtain fabrics meeting GB 8624 combustion standards. Cotton bed linen retains the largest volume share due to breathability preferences in humid southern climates, while silk cushion covers command the highest margin pools among material categories. Online retail channels are capturing the fastest growth trajectory as live-streaming commerce platforms reshape discovery and purchase behavior for mid-range and premium price tiers.
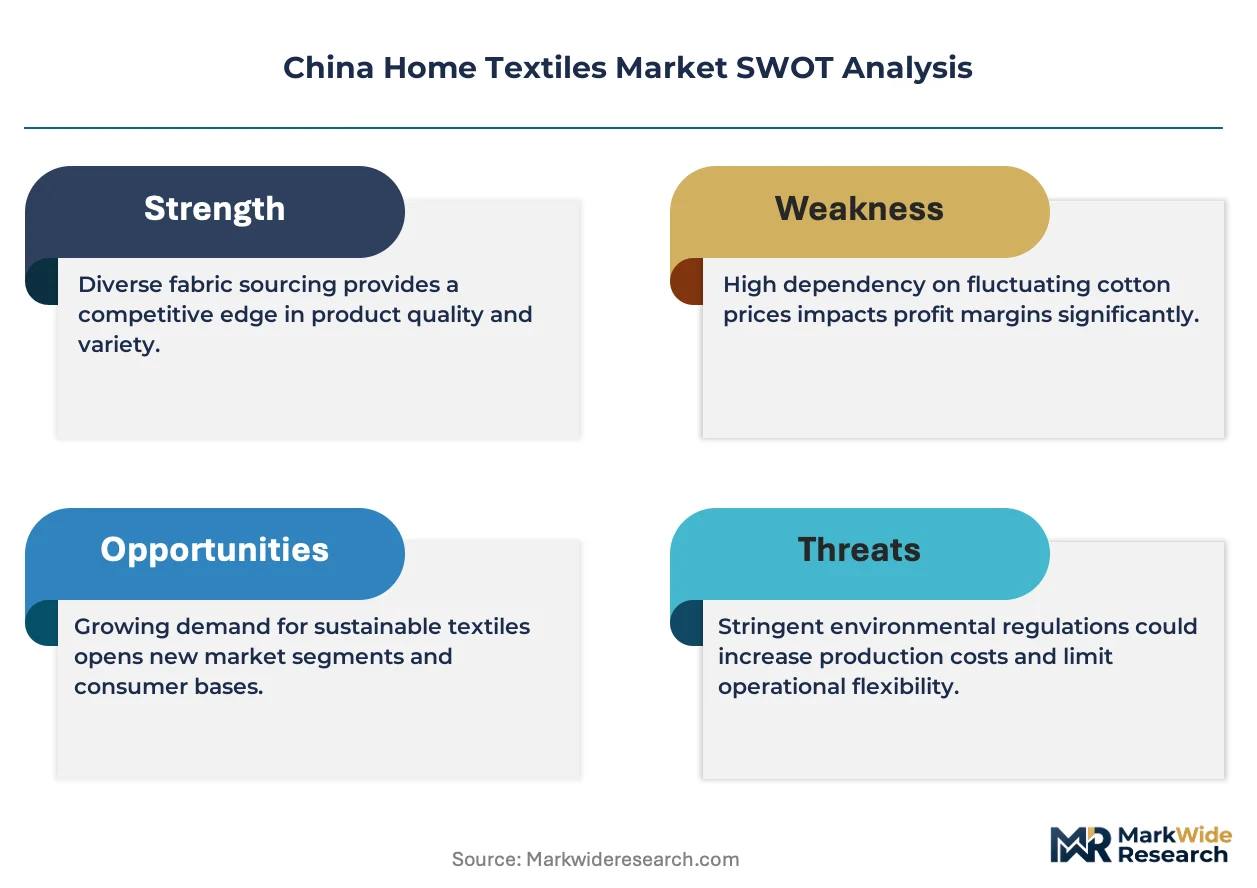
SAMR enforces GB 18401 national general safety technical code for textile products, setting mandatory limits on formaldehyde content and color fastness that manufacturers must certify before market placement. MIIT's industrial policy directives promote digital weaving and dyeing upgrades under the smart manufacturing framework, pressuring smaller mills to modernize or exit. The dual carbon goals articulated by MEE are tightening energy intensity benchmarks for textile finishing operations, particularly in water-heavy dyeing processes. Stakeholders must monitor how evolving eco-labeling requirements and carbon accounting rules reshape supplier qualification criteria and procurement priorities.
Market Dynamics
Urban renovation cycles in China are compressing replacement intervals for bed linen and curtain sets, pulling consumption forward from traditional episodic purchase patterns toward scheduled refresh models that favor subscription-ready suppliers.
Growth Catalysts
- GB 18401 compliance upgrading:Mandatory formaldehyde limits and color fastness standards under SAMR enforcement are filtering out subscale dye houses, concentrating orders among certified mills capable of rapid certification turnaround.
- Live-streaming commerce penetration:Digital discovery platforms are collapsing wholesale layers for mid-range and premium tiers, enabling direct manufacturer-to-household relationships that capture margin previously distributed through provincial distributors.
- Yangtze River Delta clustering:Proximity of spinning, weaving, and finishing operations around Shanghai and Hangzhou is shortening lead times for design-to-shelf cycles, attracting brand headquarters and sample development centers.
Market Restraints
- Polyester feedstock volatility:Crude-linked PTA and MEG pricing swings transmit directly into synthetic fabric cost structures, compressing margin predictability for mills without captive petrochemical supply.
- Water-intensive finishing concentration:Dyeing and printing operations cluster in water-stressed basins where MEE discharge permits are tightening, forcing capacity relocation or wastewater treatment capex that smaller operators cannot fund.
- Cotton substitution pressure:Lyocell and regenerated cellulose fibers are capturing share in humid southern climates where breathability commands premium positioning, threatening volume retention for conventional cotton spinners.
Strategic Opportunities
- Smart manufacturing subsidies:MIIT directives funding digital weaving and dyeing upgrades create qualification advantages for early adopters seeking preferred supplier status under state procurement frameworks.
- Carbon accounting integration:Dual carbon goals are embedding energy intensity benchmarks into buyer qualification criteria, opening audit and certification service revenue streams for mills with verified low-carbon production.
- Cross-border e-commerce channels:Direct export via digital marketplaces bypasses traditional trading company intermediaries, enabling Hangzhou and Ningbo-based manufacturers to capture overseas retail margin in Southeast Asian markets.
Industry Challenges
- Digital weaving technician scarcity:Smart manufacturing upgrades require operators capable of interfacing with IoT-enabled looms and dye controllers, a skill set concentrated in coastal provinces with limited migration into inland mill towns.
- Legacy finishing equipment stranded cost:Water-heavy beam dyeing and rotary printing lines face accelerated obsolescence under tightening MEE discharge standards, forcing write-down decisions before depreciation cycles complete.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Home Textiles Market |
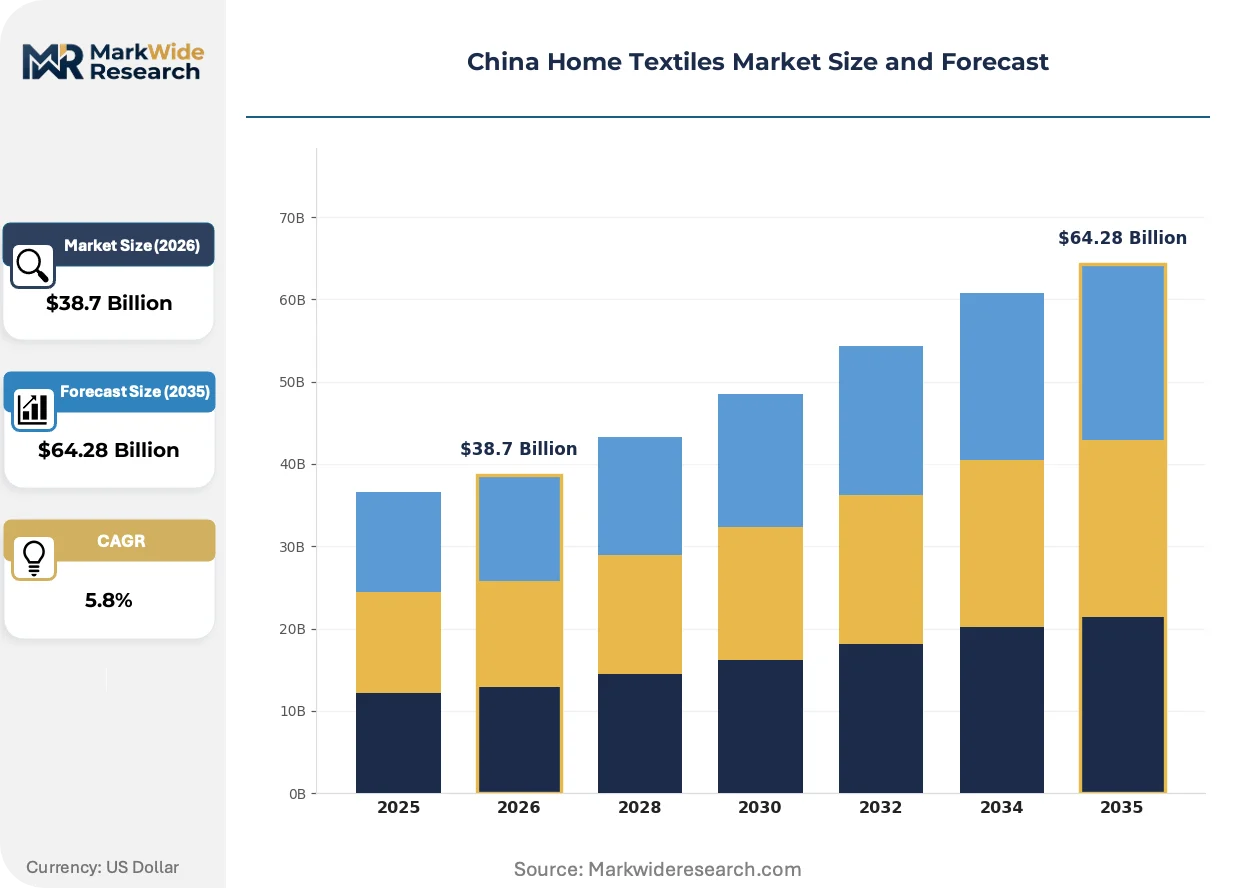
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $64.28 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bed Linen, Curtains, Cushion Covers, Table Cloths Material: Cotton, Polyester, Silk, Linen Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Wholesale Price Tier: Premium, Mid-range, Budget, Luxury |
| Companies Covered | Shandong Nanshan Zhishang Sci-Tech, Zhejiang Hangmin, Hengli Petrochemical, Jiangsu Jujie Microfiber Technology Group, Shanghai Shuixing Home Textile, Tongkun Group, Zhejiang Taihua New Material, QL Textiles, Inner Mongolia Erdos Resources, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Home Textiles Market Strategic Shifts
Digital integration across design, production, and distribution is collapsing traditional cycle times and enabling mass customization at scale previously reserved for artisan production.
Recycled PET filament yarn is absorbing post-consumer plastic waste streams into home textile supply chains, converting discarded bottles into polyester fiber feedstock for curtain and upholstery applications. Zhejiang-based weavers are adopting this material at accelerating rates to meet downstream brand sustainability requirements. The technology is absorbing compliance cost pressures from tightening eco-labeling standards by converting waste liability into certified input.
MIIT's smart manufacturing framework is mandating digital loom connectivity and real-time production monitoring across subsidized upgrade programs, forcing equipment replacement decisions at mills with depreciated mechanical assets. Dye houses in Shaoxing and Jiaxing are responding fastest, installing IoT-enabled color kitchens that reduce re-dye rates and water consumption simultaneously. Medium-scale integrated operations capture the largest efficiency gains from these deployments.
Subscription-based linen refresh programs are displacing traditional retail replacement cycles among affluent urban households in Shanghai, Shenzhen, and Hangzhou. Direct-to-consumer platforms bundle scheduled delivery with take-back logistics, compressing the effective product lifecycle while securing predictable revenue streams. This model concentrates in tier-one cities where apartment renovation rates and digital payment penetration intersect most densely.
China Home Textiles Market Segmentation
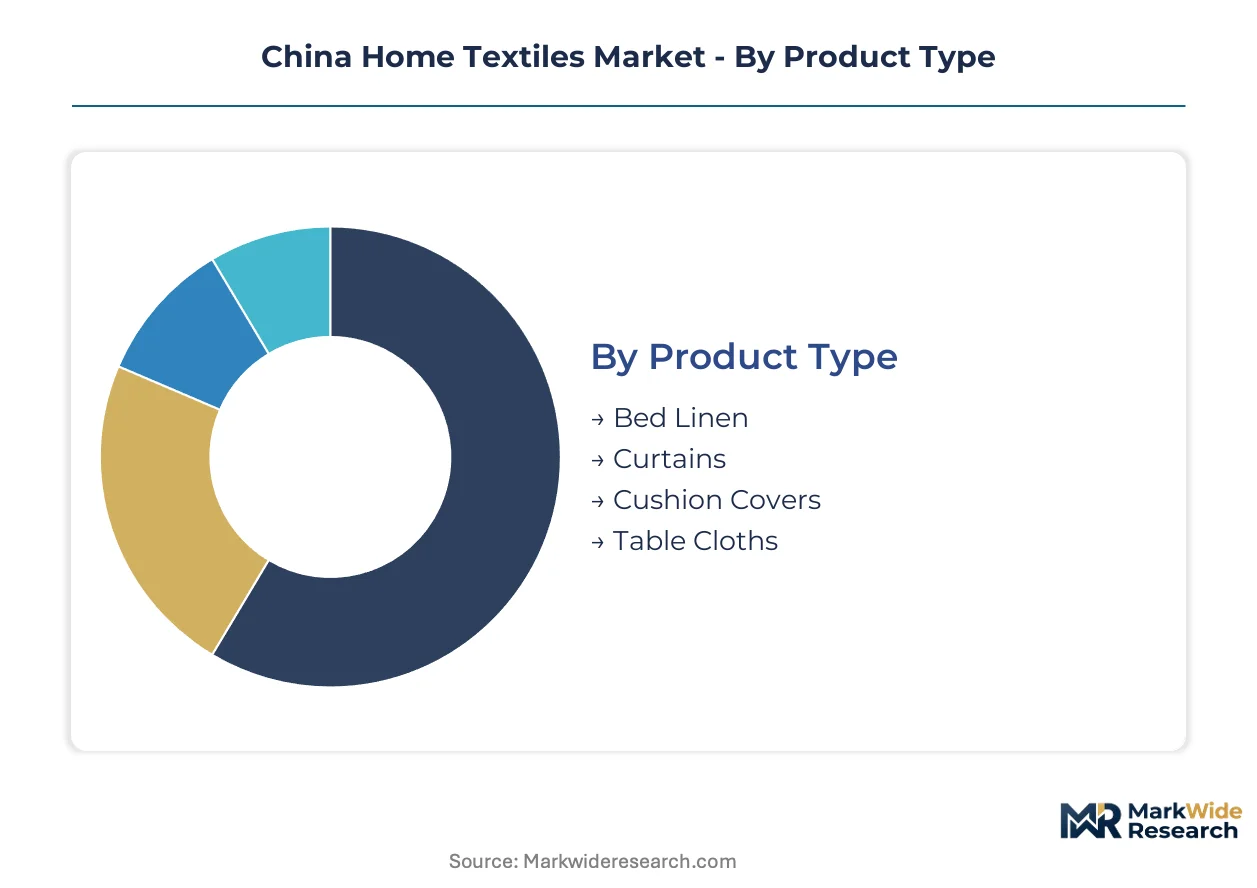
Segmentation in the China home textiles market reveals how technical specifications, material sourcing, and channel economics create distinct competitive arenas. Manufacturers must align production capabilities with the precise requirements of each segment to capture margin and volume simultaneously.
Product Type:
Thread count specifications and functional performance requirements define the technical axis across residential textile categories.
- Bed Linen:Thread counts ranging from 200 to 800 determine breathability and durability profiles, with higher specifications commanding positioning in humid southern climates where moisture management is critical. Urban renovation cycles in Shanghai and Hangzhou are compressing replacement intervals for premium sets.
- Curtains:Flame-retardant treatments meeting GB 8624 combustion standards are mandatory for commercial applications, while residential demand concentrates on blackout and thermal insulation properties in high-rise apartment clusters. MEE discharge permit tightening is raising finishing costs for dyed curtain fabrics.
- Cushion Covers:Decorative accent pieces with lower functional requirements than bed linen, typically manufactured in smaller batch sizes with faster design turnover.
- Table Cloths:Stain-resistant coatings and easy-care finishes dominate functional specifications, with cotton-polyester blends capturing volume share in household applications.
Mature deployment sits with bed linen. Newer deployment is concentrated in curtain sets with integrated smart home compatibility.
Material:
Raw material selection directly determines cost structure, processing requirements, and end-market positioning across the value chain.
- Cotton:Retains the largest volume share due to breathability preferences in humid southern climates, though Xinjiang sourcing compliance is raising traceability audit costs for export-oriented manufacturers.
- Polyester:Captures share fastest in mass-market curtain and upholstery applications where Hengli Petrochemical's upstream PTA-MEG integration delivers feedstock cost advantages unavailable to cotton spinners.
- Silk:Commands the highest margin pools among material categories, with Suzhou and Hangzhou maintaining heritage processing capabilities for luxury positioning.
- Linen:Growing substitution threat to cotton in breathable summer bedding, sourced increasingly from European flax suppliers to bypass domestic quality inconsistencies.
Volume leadership belongs to cotton. Margin expansion is concentrating in silk and certified sustainable polyester.
Distribution Channel:
Channel selection determines margin capture, customer relationship depth, and inventory risk allocation for manufacturers.
- Online Retail:Live-streaming commerce platforms on Douyin and Taobao are collapsing wholesale layers for mid-range and premium tiers, enabling direct manufacturer-to-household relationships that bypass provincial distributor networks.
- Supermarkets:High-volume, low-margin positioning for standardized bed linen SKUs with limited design differentiation and rapid inventory turns.
- Specialty Stores:Tactile evaluation remains critical for silk and high-thread-count cotton purchases, sustaining physical retail relevance in tier-one cities.
- Wholesale:Traditional channel for hotel and institutional procurement, though digital B2B platforms are fragmenting buyer-seller relationships.
Established volume flows through wholesale and supermarkets. Channel investment is pivoting toward online retail infrastructure.
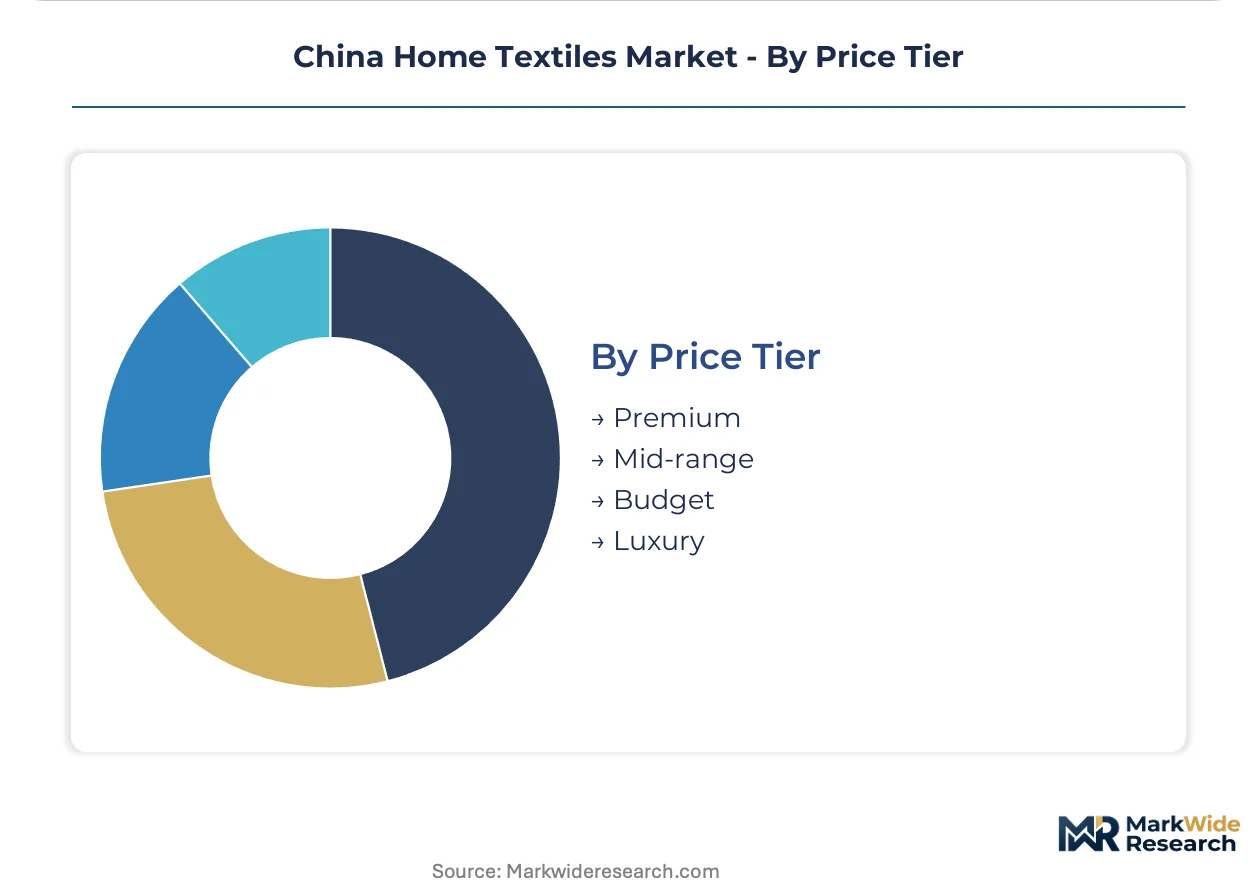
Price Tier:
Pricing stratification reflects certification grade, material provenance, and brand equity accumulation rather than manufacturing cost alone.
- Premium:GB 18401 Class A certification, organic cotton or traceable silk sourcing, and design collaboration credentials define positioning in Shanghai and Shenzhen household segments.
- Mid-range:Largest volume pool where polyester-cotton blends and standard thread counts meet functional requirements without provenance premiums.
- Budget:Price-driven positioning in third-tier cities and rural markets, with minimal compliance documentation and maximum supply chain cost compression.
- Luxury:Artisan production, limited editions, and heritage brand narratives command positioning in high-net-worth household segments with subscription-based refresh program compatibility.
Mid-range tier anchors current revenue. Premium and luxury tiers are capturing disproportionate investment in direct-to-consumer platform development.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's home textiles production concentrates in coastal provinces while consumption spreads across urbanizing interior markets. This geographic split shapes logistics costs, regional brand strategies, and regulatory enforcement intensity across the value chain.
Yangtze River Delta
Shanghai and Hangzhou anchor the nation's largest integrated manufacturing cluster, combining spinning, weaving, and finishing operations within 200-kilometer radius. SAMR's GB 18401 enforcement tightens fastest here, filtering subscale dye houses from supplier pools. Ningbo and Shaoxing mills are absorbing smart manufacturing subsidies under MIIT directives to install IoT-enabled production lines.
Pearl River Delta
Shenzhen and Guangzhou drive premium consumption for subscription-based linen refresh programs among affluent households. MEE discharge permits are constraining water-intensive finishing capacity in the Dongjiang basin, forcing relocation to peripheral zones. Foshan maintains specialized upholstery fabric production for export-oriented furniture manufacturers.
Shandong Peninsula
Qingdao and Weihai host large-scale polyester filament operations feeding curtain and bedding applications. The province's industrial policy promotes digital weaving upgrades through provincial technology funds. Local mills face cotton substitution pressure as lyocell fibers capture share in breathable summer bedding segments.
Sichuan-Chongqing
Chengdu and Chongqing represent the fastest-growing consumption base for mid-range home textiles as interior incomes rise. SAMR's market surveillance networks are less dense here, creating compliance arbitrage opportunities for budget-tier suppliers. Dye houses are migrating from coastal provinces to exploit lower wastewater treatment costs.
Beijing-Tianjin-Hebei
Beijing's renovation-driven demand for premium bed linen and flame-retardant curtain sets outstrips local production capacity. MEE's dual carbon goals are accelerating energy intensity benchmarks for textile finishing in Hebei province. Tianjin port infrastructure supports import of European flax for linen substitution strategies.
China Home Textiles Market Competitive Environment
Capital-heavy producers compete with asset-light designers across China's home textiles sector, creating a tiered structure where integrated mills battle specialized trading companies for margin capture. The market fragments across three strategic archetypes: upstream petrochemical integrators controlling polyester feedstock costs, mid-scale weavers with captive spinning-weaving-finishing operations, and digital-native brands bypassing wholesale layers through direct-to-consumer channels. Competitive moves center on smart manufacturing subsidies qualification and cross-border e-commerce platform development rather than traditional capacity expansion.
Among Zhejiang-based integrated operators, Zhejiang Hangmin exemplifies the spinning-weaving-finishing archetype with provincial production concentration. Hengli Petrochemical occupies a position reflecting upstream petrochemical integration into synthetic fiber supply chains. Shanghai Shuixing Home Textile represents the digital-native vector with direct-to-consumer channel development. These three anchors illustrate how geographic clustering around Shanghai and Hangzhou intersects with divergent strategic postures across the value chain.
| Leading Market Players |
|---|
| Shandong Nanshan Zhishang Sci-Tech |
| Zhejiang Hangmin |
| Hengli Petrochemical |
| Jiangsu Jujie Microfiber Technology Group |
| Shanghai Shuixing Home Textile |
| Tongkun Group |
| Zhejiang Taihua New Material |
| QL Textiles |
| Inner Mongolia Erdos Resources |
| Others |
Value Chain & Pricing Dynamics
Affluent urban households in Shanghai, Shenzhen, and Hangzhou anchor premium pricing power through subscription-based linen refresh programs that compress replacement cycles and secure predictable revenue streams for direct-to-consumer platforms.
Pricing Analysis
Margin tightening in mid-range tiers traces to live-streaming commerce penetration collapsing wholesale markups previously captured by provincial distributors. Three-tier pricing structure across premium, standard, and economy levels stratifies by GB 18401 certification grade and thread count specifications. Cost-down pressure on polyester-based curtain fabrics accelerates because Hengli Petrochemical's upstream PTA-MEG integration feeds synthetic fiber cost advantages unavailable to cotton spinners. Budget-tier buyers in third-tier cities exhibit highest price sensitivity, while luxury subscribers demonstrate lowest elasticity.
Supply Chain Analysis
Polyester filament supply rests on petrochemical integration along China's eastern seaboard, with PTA and MEG feedstock drawing from Hengli Petrochemical's Dalian complex and Tongkun Group's Zhejiang operations. Cotton sourcing hinges on Xinjiang production subject to escalating traceability audit costs for export-oriented manufacturers. Water-intensive dyeing and finishing clusters concentrate in Shaoxing and Jiaxing, where MEE discharge permit tightening forces capacity relocation or treatment capex. Single-source vulnerability sits with European flax suppliers for linen substitution strategies. Distribution runs through direct-to-consumer digital channels that bypass traditional wholesale layers for mid-range and premium tiers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
China's home textiles sector is becoming a vertical-integration race where control over polyester feedstock or direct consumer relationships determines margin capture. Players are pursuing upstream petrochemical integration and downstream digital channel ownership as dual levers.
For Market Incumbents: Deepen spinning-weaving-finishing integration in Zhejiang province to defend against lyocell fiber substitution threatening cotton volume retention. Invest in IoT-enabled dye house upgrades to qualify for MIIT smart manufacturing subsidies before smaller competitors secure preferred supplier status. Consolidate position around GB 18401 Class A certification as SAMR enforcement filters subscale dye houses from supplier pools. For New Entrants and Emerging Players: Recycled PET filament technology offers a white-space entry point for curtain and upholstery applications as Zhejiang-based weavers accelerate adoption to meet brand sustainability requirements. Target Sichuan-Chongqing consumption growth for mid-range bed linen where SAMR surveillance density creates compliance arbitrage for digital-native entrants. Pursue cross-border e-commerce channels via Hangzhou and Ningbo infrastructure to capture Southeast Asian retail margin without trading company intermediaries. For Investors and Strategic Acquirers: The window for entry favors integrated operators with captive polyester feedstock or direct-to-consumer platform infrastructure. Long-term viability centers on mills with verified low-carbon production credentials as dual carbon goals embed energy intensity benchmarks into buyer qualification criteria. Watch MEE discharge permit tightening in water-stressed basins as the inflection signal forcing accelerated consolidation among finishing-dependent operators.| Strategic Initiative | Industry Significance |
|---|---|
| Smart Manufacturing Upgrade | MIIT subsidies for IoT-enabled looms create qualification advantages under state procurement frameworks. |
| Recycled PET Filament Adoption | Post-consumer plastic conversion meets tightening eco-labeling standards while converting waste liability into certified input. |
| Direct-to-Consumer Platform Buildout | Live-streaming commerce on Douyin and Taobao collapses wholesale layers for mid-range and premium tiers. |
| Carbon Accounting Certification | Verified low-carbon production opens audit service revenue streams as dual carbon goals reshape procurement priorities. |
| Cross-Border E-Commerce Expansion | Hangzhou and Ningbo digital marketplaces bypass trading intermediaries to capture Southeast Asian retail margin. |
Study Parameters
Multi-period observation of urban renovation cycles, live-streaming commerce penetration rates, and GB 18401 certification timelines anchored the trend analysis, supplemented by interviews with Zhejiang-based mill operations directors, SAMR compliance officers, MIIT technology fund administrators, and Shanghai-based direct-to-consumer platform managers. Secondary validation drew from MIIT industrial policy directives, MEE discharge permit databases, customs textile trade records, and provincial smart manufacturing subsidy disclosures. Bottom-up mill capacity assessments triangulated against top-down household consumption surveys.
Input-output matrices modeled demand across product type, material composition, distribution channel, and price tier segmentation dimensions. CAGRs were derived from trend extrapolation of renovation-driven replacement intervals and digital channel share capture. Industry-specific forecast inputs included polyester feedstock cost trajectories linked to crude-linked PTA-MEG pricing and MEE energy intensity benchmark tightening schedules across the analysis window.
Several conditions sit outside the modeled scope, including abrupt shifts in Xinjiang cotton sourcing compliance requirements, sudden MEE wastewater discharge standard revisions, and live-streaming platform regulatory interventions. Forecasts reflect documented assumptions about continued urban household income growth and smart manufacturing subsidy continuity. Abrupt feedstock price volatility, accelerated lyocell substitution rates, or cross-border e-commerce tariff impositions warrant ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Home Textiles
Latin America Home Textiles Market
Home Textiles
Australia Home Textiles Market
Home Textiles
Wool Dryer Ball Market
Home Textiles
Turkey Home Textile Market
Home Textiles
Towel Market
Home Textiles
North America Home Textile Market
Home Textiles
Global Theater Linen Market
Home Textiles
Japan Home Textile Market
Home Textiles
Blanket Market
Home Textiles
Asia-Pacific Home Textile Market
Home Textiles
Home Textile Products Market
Home Textiles
Cotton Towel Market
Home Textiles
Fabric Wash and Care Market
Home Textiles
Canada Home Textile Market
Home Textiles
GCC Home Textile Market
Home Textiles
Bangladesh Home Textile Market