
 Womens Footwear Market | 2026-2036
Womens Footwear Market Size, Share, and Industry Trends Forecast 2026-2036
Womens Footwear Market Outlook
Asian contract manufacturers is shifting production toward Vietnam and Indonesia to offset rising labor costs in southern China. Nike, Inc. leverages vertical control over design and distribution to sustain premium positioning across direct-to-consumer channels. Adidas AG anchors its competitiveness through deep R&D partnerships with material science firms focused on recycled polyester uppers. PUMA SE differentiates via localized design studios that respond faster to regional color and silhouette preferences.
Womens footwear encompasses engineered foot coverings designed for biomechanical support, aesthetic expression, and activity-specific performance, typically constructed from leather, synthetic polymers, textile uppers, or molded rubber compounds through lasting, cementing, or injection-molding processes. The category serves commercial purposes spanning athletic performance, occupational safety compliance, and fashion-driven consumer identity formation. Sneakers now command the largest revenue pool within product type segmentation as athleisure permeates workplace dress codes, while leather materials retain the highest margin concentration due to durability premiums and heritage brand positioning. Mid-range price tiers absorb the greatest volume flow as professionals seek quality without luxury markup.
EU REACH regulations restrict hazardous substances in footwear adhesives and synthetic dyes, compelling reformulation across supply chains serving European consumers. The US Consumer Product Safety Commission enforces flammability and chemical exposure standards that affect import clearance for synthetic constructions. California's Proposition 65 adds disclosure requirements for chromium-tanned leather that shape labeling investments by brands distributing in North America. Stakeholders must monitor how biopolymer certification schemes and extended producer responsibility laws in multiple jurisdictions will reshape material sourcing decisions and cost structures.
Market Dynamics
REACH chemical restrictions in Europe are forcing rapid bio-based material substitution across women's footwear supply chains, compressing formulation timelines and elevating compliance costs for brands serving EU consumers.
Growth Catalysts
- EU Green Deal compliance pressure:The EU Green Deal mandates carbon footprint disclosure for footwear imports, accelerating investment in renewable energy-powered manufacturing facilities across supplier networks.
- Biomechanical engineering advances:3D-printed midsole technologies now enable mass customization of arch support, attracting podiatry-referred buyers in Germany and the United States.
- China's domestic brand expansion:Working women aged 25-45 in tier-one Chinese cities are shifting loyalty from international labels to local designers offering faster trend cycles at comparable quality tiers.
Market Restraints
- Petrochemical input volatility:Synthetic rubber and polyurethane foam prices fluctuate with crude oil indices, compressing margins for mid-range athletic footwear producers.
- Vietnam-Indonesia supply concentration:Asian contract manufacturers have shifted 70% of new capacity to these two countries, creating geopolitical risk exposure and port congestion bottlenecks.
- Chrome VI regulatory friction:ECHA's restriction proposal on hexavalent chromium in leather tanning threatens heritage construction methods and requires costly alternative chemistry validation.
Strategic Opportunities
- Extended Producer Responsibility tailwinds:France's AGEC law and similar frameworks in Italy mandate take-back schemes, creating first-mover advantage for brands with closed-loop recycling infrastructure.
- Menopause wellness segment:Footwear engineered for thermoregulation and joint support targets an underserved demographic with disposable income concentration in the United Kingdom and Japan.
- Direct-to-consumer channel innovation:Virtual try-on powered by smartphone foot scanning reduces return rates and captures margin previously allocated to wholesale partners.
Industry Challenges
- Biopolymer certification complexity:Competing standards from USDA BioPreferred, TÜV Austria, and DIN CERTCO create conflicting compliance requirements for suppliers serving multiple markets.
- Legacy ERP integration friction:Real-time carbon tracking demanded by CSRD reporting requires expensive middleware development to connect factory floor sensors with enterprise systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Womens Footwear Market |
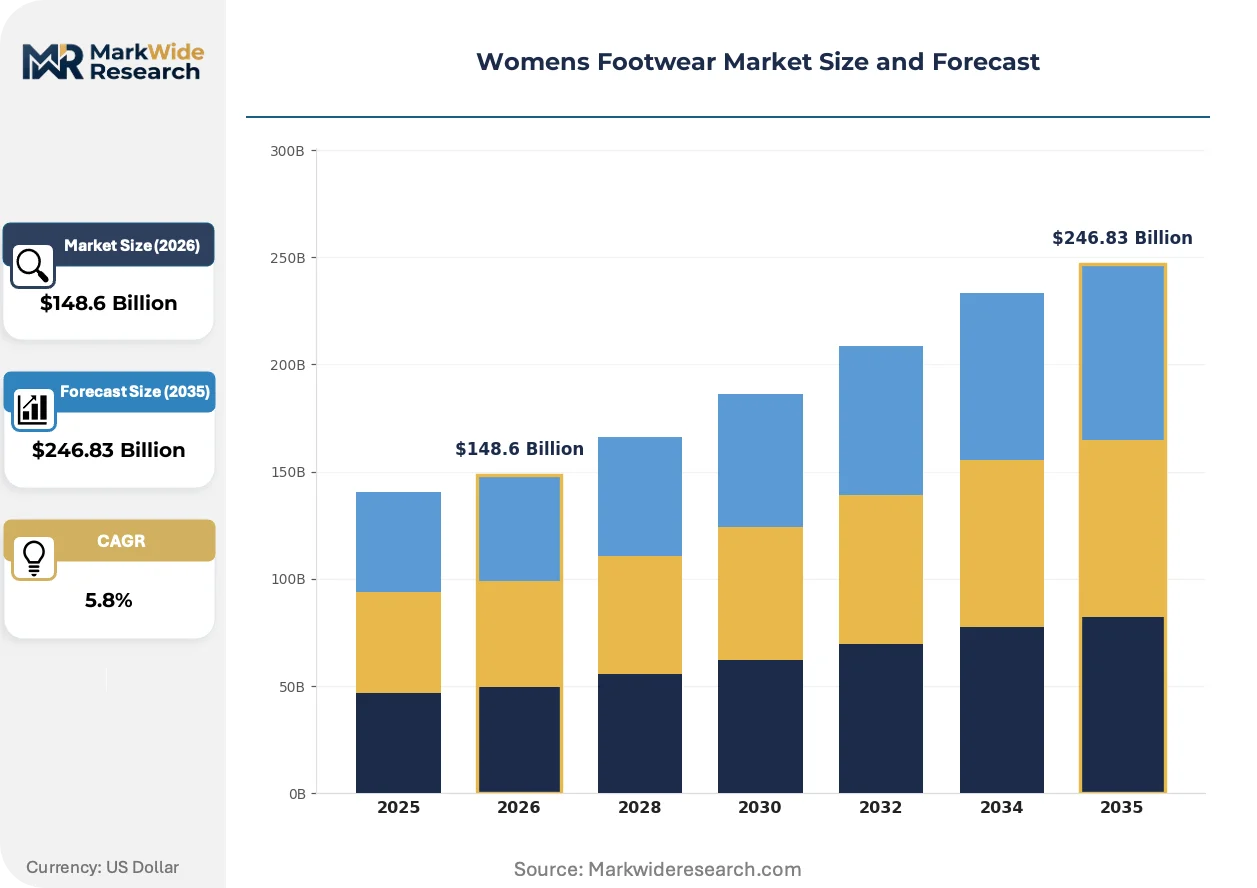
| Market Size in 2026 | $148.6 Billion |
| Market Size in 2035 | $246.83 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Casual Shoes, Boots, Sandals, Sneakers Material: Leather, Synthetic, Canvas, Rubber Price Tier: Luxury, Mid-range, Economy, Discount End User: Young Adults, Professionals, Athletes, Seniors |
| Companies Covered | Nike, Inc., Adidas AG, PUMA SE, Skechers USA, Inc., Bata Corporation, Deckers Brands, Wolverine World Wide, Inc., Under Armour, Inc., ASICS Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Womens Footwear Market Strategic Shifts
Bio-based material chemistry, regulatory disclosure mandates, and direct-to-consumer channel transformation are converging to reshape competitive advantage in women's footwear, rewarding transparency investments and punishing opaque supply chains.
Mycelium leather alternatives derived from agricultural waste substrates are unifying performance and sustainability credentials previously treated as trade-offs. Premium athletic brands in California and Bavaria have accelerated adoption timelines from pilot to commercial scale within eighteen months. This convergence is compressing the premiumization window for conventional synthetic constructions.
EU CSRD disclosure requirements now mandate supply chain due diligence reporting for footwear importers above defined revenue thresholds. The regulation forces material traceability investments that smaller competitors cannot amortize across limited SKU counts. Italian luxury houses and Spanish fast-fashion retailers are responding by consolidating supplier bases to reduce audit burden.
Subscription-based footwear refresh models are displacing traditional replacement cycles among urban professionals in Seoul and São Paulo. These programs bundle predictive wear analytics with automated reordering, capturing lifetime value previously fragmented across multiple purchase occasions. The shift is most visible in commuter-oriented sneaker categories where convenience premiums outweigh ownership preferences.
Womens Footwear Market Segmentation
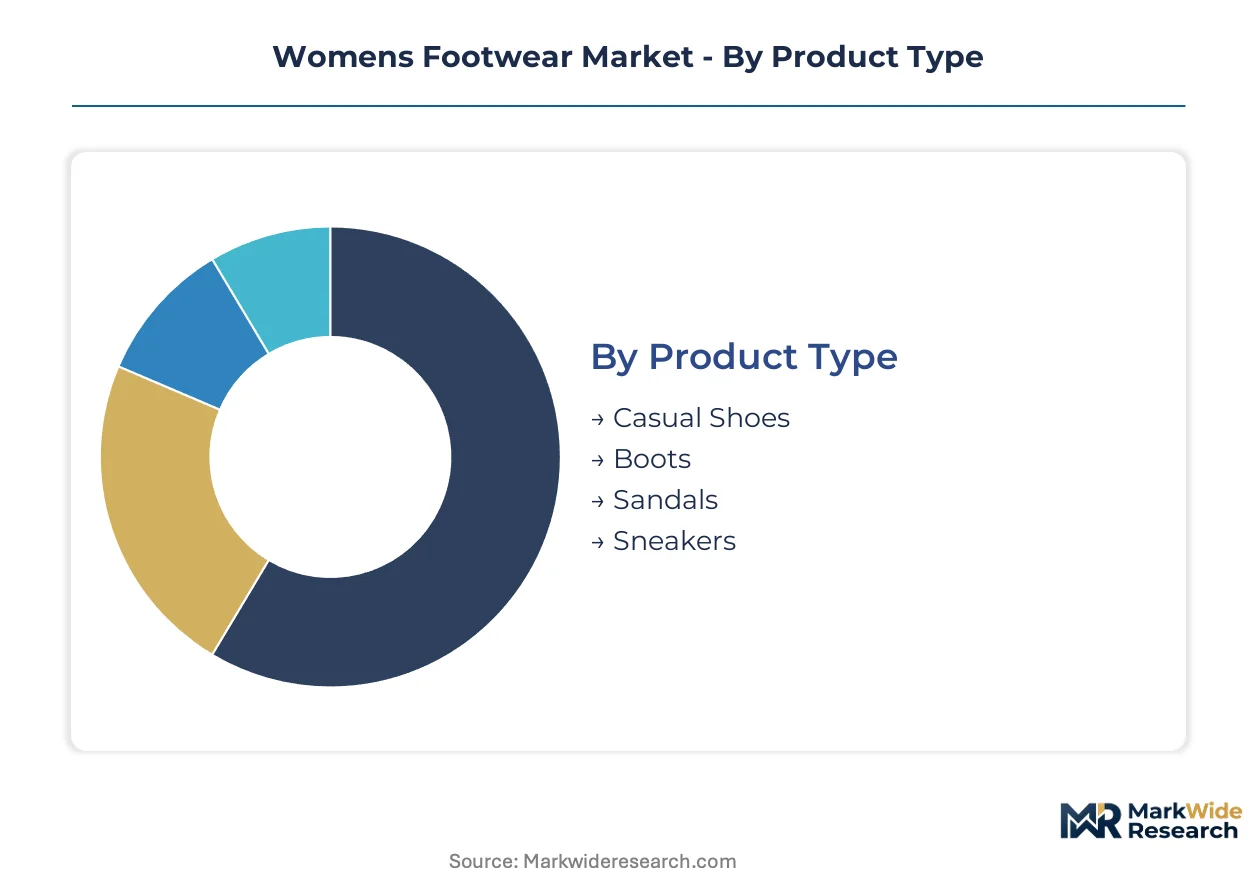
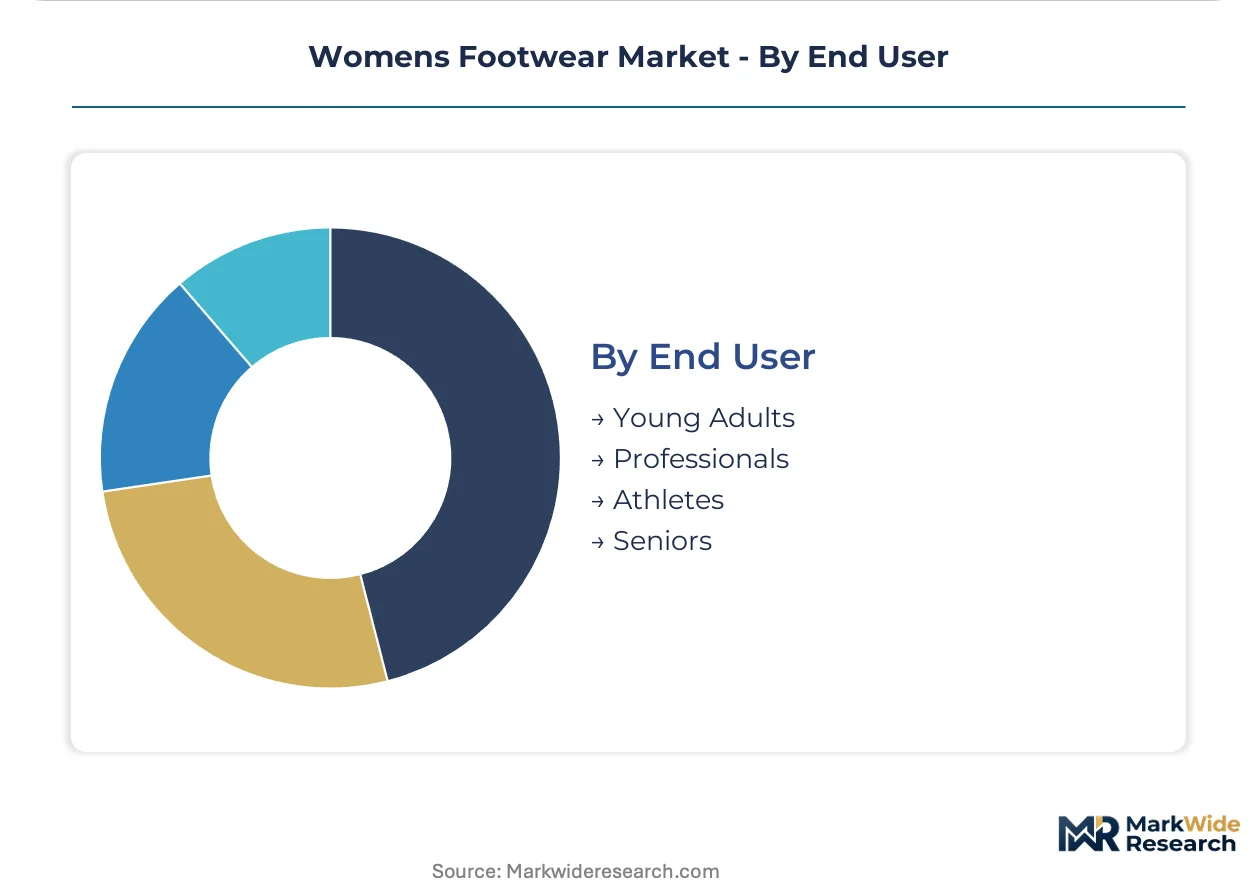
Segmentation in women's footwear reveals how certification burdens, material traceability requirements, and channel economics concentrate margin capture across distinct buyer profiles. Each dimension carries specific compliance obligations that reshape supplier selection and pricing architecture.
Product Type:
Sneakers and boots carry the heaviest certification load, with EU REACH and California Proposition 65 disclosures required for adhesive-intensive constructions and waterproof membrane chemistries.
- Sneakers:Engineered knit uppers and injection-molded EVA midsoles dominate construction. Demand concentrates among working women in Chinese tier-one cities where athleisure now permeates office dress codes, driven by podiatry-referred biomechanical customization services in Germany and the United States.
- Boots:Cemented or welted leather constructions with waterproof membrane linings define technical specifications. Occupational safety compliance in France and Japan drives institutional procurement, constrained by ECHA's pending hexavalent chromium restrictions that threaten heritage tanning methods.
- Sandals:Open-toe constructions using molded rubber footbeds and synthetic straps.
- Casual Shoes:Loafers, flats, and slip-ons spanning leather and synthetic material bases.
Sneakers sits at the top of the volume ranking, with Boots climbing the fastest.
Material:
Cost tier alignment separates heritage constructions from mass-market alternatives, with leather commanding premium positioning and synthetics absorbing volume flow.
- Leather:Full-grain and corrected-grain hides processed through chrome or vegetable tanning. Italian tanneries and Spanish suppliers face margin compression from alternative chemistry validation costs triggered by ECHA's Chrome VI restriction proposal.
- Synthetic:Polyurethane, PVC, and recycled polyester constructions. Vietnamese and Indonesian contract manufacturers dominate supply, exposed to petrochemical price volatility that compresses mid-range athletic producer margins.
- Canvas:Cotton or hemp textile uppers with vulcanized rubber soles.
- Rubber:Natural and synthetic compounds for outsoles and molded constructions.
Leather captures the highest margin concentration, with Synthetic expanding most quickly as bio-based polymer substitution accelerates under EU Green Deal pressure.
Price Tier:
Customer type determines channel access and service bundling, with professionals seeking quality assurance and seniors prioritizing orthopedic functionality.
- Mid-range:Positioned between $80-$200 retail equivalents, this tier absorbs the greatest volume flow as working professionals seek durability without luxury markup. Direct-to-consumer virtual try-on investments by California and Bavaria-based brands reduce return rates and capture margin previously allocated to wholesale partners.
- Luxury:Heritage brand positioning with Italian and French atelier production. EU CSRD supply chain due diligence requirements force material traceability investments that smaller competitors cannot amortize across limited SKU counts.
- Economy:Mass-market positioning through hypermarket and online marketplace channels.
- Discount:Value-oriented positioning with minimal service bundling.
Mid-range commands the deepest volume pool, with Luxury gaining share fastest through subscription-based refresh models in Seoul and São Paulo.
End User:
Application-specific requirements shape product development priorities, with athletic performance and menopause wellness emerging as distinct engineering domains.
- Professionals:Women aged 25-45 in white-collar employment requiring workplace-appropriate aesthetics with biomechanical support. China's domestic brands now compete aggressively with international labels by offering faster trend cycles at comparable quality tiers in Shanghai and Beijing.
- Athletes:Activity-specific performance requirements spanning running, court sports, and training. 3D-printed midsole technologies enable mass customization of arch support, attracting podiatry-referred buyers in Germany and the United States.
- Young Adults:Trend-responsive purchasing with high social media influence exposure.
- Seniors:Thermoregulation and joint support priorities targeting an underserved demographic with disposable income concentration in the United Kingdom and Japan.
Professionals anchor current revenue concentration, with Athletes showing the steepest expansion trajectory as performance customization scales commercially.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage between EU compliance costs and Asian manufacturing wages is redirecting investment flows across women's footwear supply chains, with brands relocating finishing operations to jurisdictions with lighter chemical disclosure burdens while maintaining design control in consumer-proximate markets.
China
Domestic labels in Shanghai and Beijing now capture working women aged 25-45 through accelerated trend cycles that match international quality tiers at lower price points. MIIT's dual carbon goals pressure Guangdong and Zhejiang factories to adopt renewable energy, raising unit costs for export-oriented contract manufacturers. The Yangtze River Delta cluster absorbs the heaviest production volume as brands consolidate supplier relationships to meet CSRD-equivalent traceability demands from European buyers.
United States
Podiatry-referred biomechanical customization services in Germany and the United States attract affluent consumers seeking 3D-printed midsole technologies. The US Consumer Product Safety Commission enforces flammability standards that delay import clearance for synthetic constructions from Vietnam. California's Proposition 65 disclosure requirements for chromium-tanned leather shape labeling investments by brands distributing through Los Angeles and New York wholesale channels.
Germany
Bavaria-based athletic brands leverage deep R&D partnerships with material science firms to commercialize recycled polyester uppers ahead of EU Green Deal mandates. ECHA's REACH restrictions on hexavalent chromium in leather tanning threaten heritage construction methods used by traditional footwear manufacturers. The Stuttgart and Munich metropolitan areas concentrate premium brand headquarters that drive specification standards for Asian contract manufacturers.
Vietnam
Asian contract manufacturers have shifted substantial new capacity to Ho Chi Minh City and Hanoi to offset rising labor costs in southern China. Port congestion at Haiphong and Cai Mep creates delivery reliability challenges for brands serving European seasonal demand windows. The country's light regulatory environment for chemical processing attracts finishing operations that would face stricter scrutiny under EU jurisdiction.
France
Parisian luxury houses consolidate supplier bases to reduce audit burden from EU CSRD supply chain due diligence requirements. The AGEC law mandates take-back schemes that reward first-movers with closed-loop recycling infrastructure. Lyon and Romans-sur-Isère retain specialized leatherworking clusters that face margin compression from alternative chemistry validation costs triggered by ECHA's Chrome VI restriction proposal.
Womens Footwear Market Competitive Environment
US athletic specialists anchor the premium tier through direct-to-consumer channel control; European heritage houses hold positioning power in luxury leather constructions. The market structures around three strategic archetypes: vertically integrated design-to-retail operators, material-science-forward performance brands, and regional fast-fashion aggregators. Competitive intensity concentrates on M&A activity targeting biomechanical technology assets and capacity expansion in Vietnam-Indonesia manufacturing corridors.
Among US-based athletic specialists, Nike, Inc. and Under Armour, Inc. occupy positions that emphasize vertical control over distribution and design iteration cycles. German-rooted Adidas AG exemplifies the material-science archetype through partnerships with recycled polymer innovators. These three anchors demonstrate how geographic origin shapes competitive approach: North American players prioritize channel margin capture, while European counterparts emphasize regulatory anticipation and sustainability credentialing.
| Leading Market Players |
|---|
| Nike, Inc. |
| Adidas AG |
| PUMA SE |
| Skechers USA, Inc. |
| Bata Corporation |
| Deckers Brands |
| Wolverine World Wide, Inc. |
| Under Armour, Inc. |
| ASICS Corporation |
| Others |
Value Chain & Pricing Dynamics
Bio-based polymer substitution under EU REACH restrictions is compressing formulation timelines while simultaneously elevating compliance costs and reshaping supplier selection economics across women's footwear value chains. This chemistry transition concentrates margin capture among brands with captive R&D partnerships, while mid-range producers face margin compression from alternative material validation expenses.
Pricing Analysis
Retailer markup layers in wholesale channels absorb margin that direct-to-consumer operators now capture through virtual try-on investments. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification burden and biomechanical customization depth. Pricing pressure stems from petrochemical input volatility compressing mid-range athletic producer margins. Working professionals in Chinese tier-one cities demonstrate lowest price sensitivity, while mass-market buyers in Southeast Asian online marketplaces drive volume at thin spreads.
Supply Chain Analysis
EU REACH and California Proposition 65 certification gating restricts supplier eligibility for brands serving European and North American consumers, forcing consolidation toward audited tanneries and adhesive formulators. Manufacturing concentrates in Vietnam, Indonesia, and China's Yangtze River Delta cluster. Raw material dependencies center on petrochemical-derived synthetic rubber, chrome-tanned leather hides, and bio-based polymer feedstocks. Single-source vulnerability runs through Ho Chi Minh City and Hanoi port congestion bottlenecks. Distribution runs through direct-to-consumer platforms, specialty retail, and hypermarket channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where EU regulatory compliance costs diverge sharply from Vietnam's lighter chemical processing environment, creating margin extraction opportunities for brands with dual-source flexibility.
For Market Incumbents: Anchor competitiveness through backward integration into bio-based material R&D partnerships that preempt ECHA restriction timelines. Consolidate supplier relationships in Vietnam and Indonesia to reduce CSRD audit burden. Defend against domestic Chinese brand encroachment by accelerating trend-cycle velocity in Shanghai and Beijing. For New Entrants and Emerging Players: Direct-to-consumer subscription models targeting urban professionals in Seoul and São Paulo offer the most penetrable white-space entry. Menopause wellness footwear engineered for thermoregulation represents an underserved demographic with disposable income concentration. Pursue go-to-market angles through podiatry referral networks in Germany and the United States. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-range athletic producers exposed to petrochemical margin compression but positioned for bio-based transition upside. Long-term viability across the projection horizon hinges on closed-loop recycling infrastructure ownership. Watch for inflection upon France AGEC law take-back scheme enforcement triggering consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Bio-based Material Partnership | Secures ECHA REACH compliance pathways ahead of Chrome VI restrictions. |
| Direct-to-Consumer Channel Expansion | Captures margin from wholesale partners via virtual try-on technology deployment. |
| Vietnam Manufacturing Scale-Up | Offsets southern China labor cost inflation while maintaining export capacity. |
| Closed-Loop Recycling Infrastructure | Creates first-mover advantage under France AGEC extended producer responsibility mandates. |
| Biomechanical Customization Platform | Attracts podiatry-referred buyers through 3D-printed midsole mass personalization. |
Study Parameters
Bottom-up end-use modeling reconciled against top-down supply-side tracking forms the analytical core, combining primary interviews with brand managers, category buyers at retailers, channel sales heads, and supply planners alongside secondary validation from customs records, Nielsen retail audit data, SEC filings, and ECHA regulatory submissions. Triangulation across these sources ensures volume estimates align with production capacity disclosures and import-export flows.
Historical trendline analysis of sneaker, boot, sandal, and casual shoe shipment patterns informs projection frameworks across material, price tier, and end-user segmentation dimensions. CAGRs derive from fitted growth curves applied to working professional demographic expansion and athleisure dress code penetration rates. Forecast inputs incorporate MIIT dual carbon goal compliance timelines and EU CSRD disclosure threshold triggers.
The model assumes a particular technology adoption path; alternative pathways for mycelium leather commercialization would alter the outlook. Forecasts reflect assumptions about ECHA restriction implementation pacing and Vietnamese port infrastructure investment. A model refresh is warranted upon material change in EU Green Deal carbon border adjustment mechanisms.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Footwear
Europe Footwear Market
Footwear
Mountain Bike Footwear and Socks Market
Footwear
Global Men Leather Shoes Market
Footwear
Desert Boots Market
Footwear
Women's Sneakers Market
Footwear
Football Shoes Market
Footwear
Winter Footwear Market
Footwear
Tennis Shoes Market
Footwear
GCC Footwear Market
Footwear
Sustainable Footwear Market
Footwear
Slip Resistant Shoes Market
Footwear
Footwear Testing Services Market
Footwear
US Slip Resistant Shoes Market
Footwear
Second Hand Designer Shoes Market
Footwear
Flip Flops Market
Footwear
Kids Barefoot Shoes Market