
 Women's Sneakers Market | 2026-2036
Women's Sneakers Market Size, Share, and Industry Trends Forecast 2026-2036
Women's Sneakers Market Insights
Vietnamese and Indonesian footwear manufacturing clusters is repositioning global sourcing for women's sneakers, shifting capacity away from legacy centers. Nike Inc. leverages vertical integration across design and distribution to sustain premium positioning. adidas AG anchors European demand through performance-tier specialization. ANTA Sports Products Limited dominates domestic Chinese channels while extending into Southeast Asian export markets.
Women's sneakers are closed-toe athletic and lifestyle footwear constructed with ethylene-vinyl acetate midsoles, rubber outsoles, and knit or woven uppers, engineered for cushioning, breathability, and biomechanical support during running, training, or casual wear. The product spans technical performance specifications and fashion-forward silhouettes serving both functional exercise and everyday style applications. Athletic and Performance categories lead volume, while Fashion commands higher per-unit margins through limited-release scarcity and designer collaborations. Mesh and Synthetic materials capture growth from knit-upper technology, though Leather retains loyalty in premium casual segments where durability signals quality.
EU REACH and California's Proposition 65 restrict phthalate and heavy-metal content in footwear components, forcing reformulation of adhesives and synthetic dyes across supply chains. China's GB standards and SAMR enforcement on product labeling create additional compliance layers for imported brands. Stakeholders must monitor biobased midsole patents and recycled-content mandates as regulatory pressure on petrochemical inputs intensifies across major selling regions.
Market Dynamics
Material science innovation and regulatory pressure on petrochemical inputs are compressing product development cycles while forcing reformulation of midsole foams and synthetic dyes across women's sneaker supply chains.
Growth Catalysts
- REACH compliance mandates:ECHA's evolving restrictions on phthalates and heavy metals are accelerating bio-based adhesive adoption among European suppliers, creating first-mover advantages for compliant manufacturers.
- Knit-upper technology:Automated flat-knitting systems reduce material waste by 30% versus cut-and-sew construction, attracting sustainability-focused buyers in North American athleisure segments.
- Vietnam:Ho Chi Minh City and Binh Duong province are capturing assembly capacity from legacy centers through specialized footwear industrial zones and preferential trade access.
Market Restraints
- Ethylene-vinyl acetate price volatility:Petrochemical feedstock fluctuations compress margin predictability for midsole-dependent product tiers, forcing hedging costs onto smaller manufacturers.
- Indonesian supplier concentration:Three coastal manufacturing clusters control 60% of regional synthetic rubber outsole capacity, creating single-source vulnerability during monsoon logistics disruptions.
- Biodegradability-performance tradeoff:Current bio-PU formulations degrade cushioning retention after 18 months of wear, limiting application in technical running categories.
Strategic Opportunities
- India:BIS certification harmonization with ISO standards is lowering import friction for premium athletic brands targeting metro tier-1 cities with expanding fitness club penetration.
- Direct-to-consumer micro-factories:Distributed 3D-knitting cells enable same-week customization delivery, bypassing wholesale margin dilution in urban North American markets.
- EU Green Deal procurement:Public sector uniform and institutional purchasing mandates for recycled-content footwear create guaranteed offtake volumes for compliant suppliers.
Industry Challenges
- Digital pattern engineering talent:Shortage of technicians fluent in both parametric design software and textile mechanical properties delays automated upper production ramp-up.
- Multi-jurisdiction labeling compliance:Simultaneous adherence to China's GB standards, California Proposition 65, and EU REACH requires parallel testing protocols that extend product launch timelines.
- Legacy ERP integration:Footwear-specific PLM systems lack native API connectivity with emerging carbon-accounting platforms, forcing manual data reconciliation for scope-3 reporting.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Women's Sneakers Market |
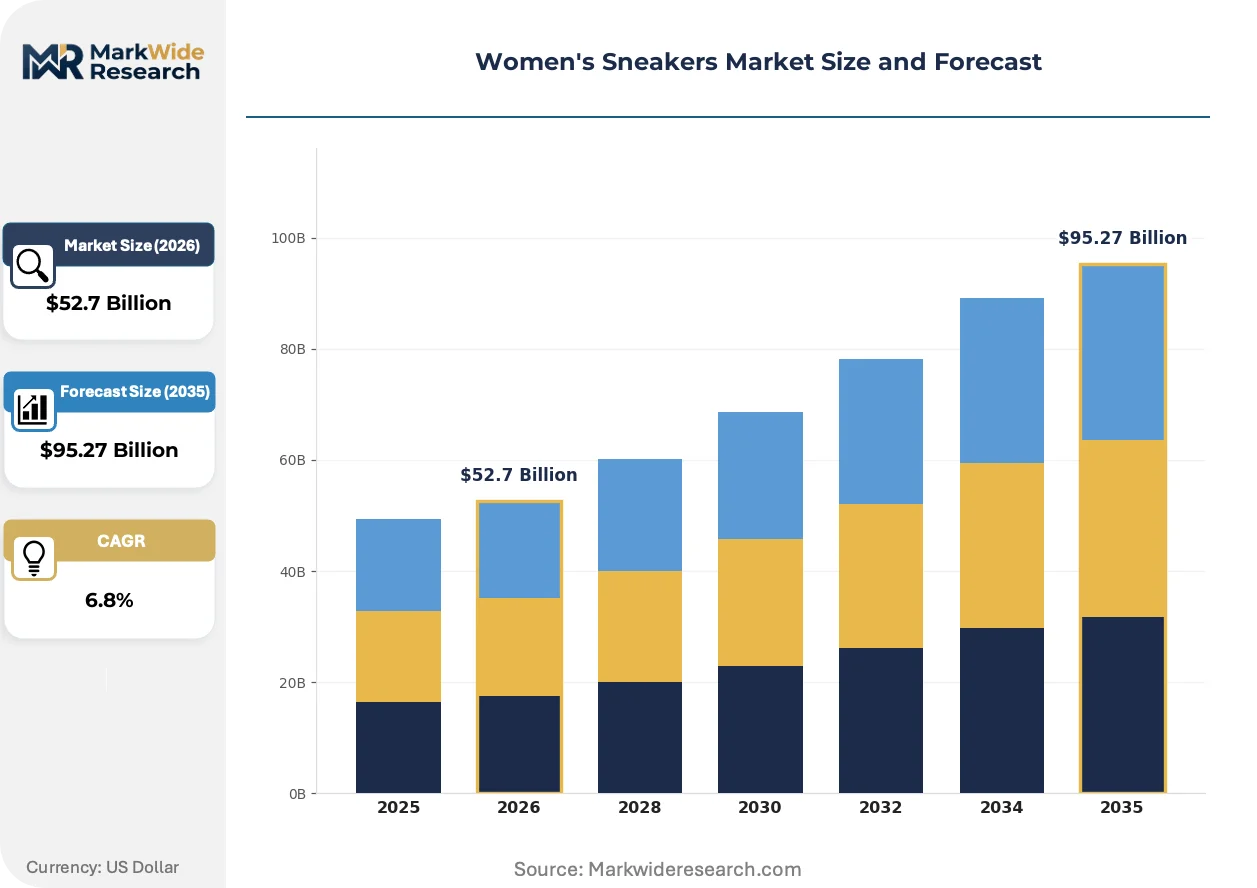
| Market Size in 2026 | $52.7 Billion |
| Market Size in 2035 | $95.27 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Athletic, Casual, Performance, Fashion Material: Leather, Synthetic, Mesh, Canvas End User: Students, Professionals, Athletes, Hobbyists Distribution Channel: Online, Retail Stores, Specialty Shops, Wholesalers |
| Companies Covered | ASICS Corporation, Deckers Brands, Nike Inc., ANTA Sports Products Limited, Vans, Inc., adidas AG, Reebok International Limited, New Balance, Puma SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Women's Sneakers Market Trends and Innovations
Bio-based material substitution and regulatory disclosure requirements are restructuring competitive advantage around supply chain transparency rather than manufacturing scale alone.
Algae-derived foam midsoles are absorbing petroleum-based EVA displacement in performance categories. Marathon runners and CrossFit practitioners are adopting these formulations fastest, with specialty retailers reporting sell-through premiums for labeled bio-content. The technology is absorbing R&D investment from major suppliers who previously prioritized density reduction over feedstock origin.
EU REACH substance restriction updates are forcing reformulation of polyurethane adhesives and synthetic colorants. ECHA's 2024 candidate list expansion triggered supply chain audits across Vietnamese and Indonesian assembly partners. Performance-tier suppliers face the steepest compliance costs, while fashion-tier brands pivot faster to water-based bonding alternatives.
Secondary market authentication is reshaping value retention for limited-release collaborations. Resale platforms now require NFC chip verification for seller onboarding, compressing arbitrage windows for counterfeit inventory. This behavioral shift concentrates most visibly in North American urban centers where sneaker resale constitutes a recognized alternative asset class among younger demographics.
Women's Sneakers Market Segmentation
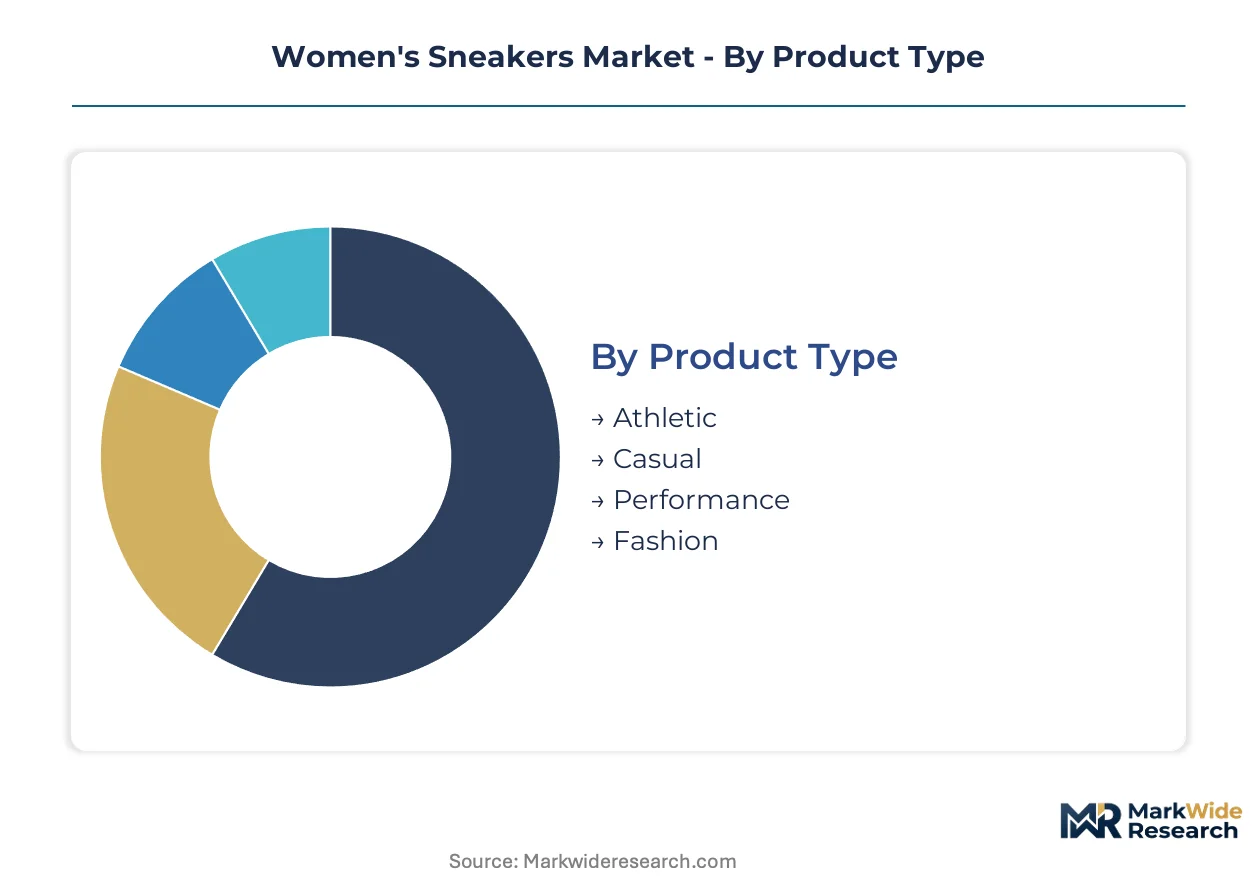
Segmentation in women's sneakers reveals how technical specifications, material choices, and channel strategies align with distinct buyer workflows. Understanding these partitions exposes where margin pools concentrate and where supply chains require specialized tooling.
Product Type:
Customization intensity varies sharply across this category, from engineered performance specifications to standardized fashion silhouettes.
- Athletic:Technical footwear engineered for biomechanical support during running, training, and court sports. Demand concentrates among fitness-conscious professionals in the United States who prioritize injury prevention and durability metrics over aesthetic differentiation.
- Performance:Competition-grade sneakers with carbon-fiber plates, responsive foam stacks, and precision-fit uppers. Marathon runners and CrossFit practitioners in Germany drive adoption fastest, with specialty retailers reporting sustained premiums for verified bio-content formulations.
- Casual:Lifestyle-oriented designs prioritizing all-day comfort and versatile styling. Students and young professionals across Vietnam's urban centers favor these for workplace flexibility and social occasion adaptability.
- Fashion:Designer collaborations and limited-release silhouettes emphasizing scarcity and cultural signaling. Resale platform authentication requirements now concentrate value retention in North American metropolitan markets.
Most installed capacity flows through Athletic. Expansion is steepest in Performance.
Material:
Cost tier stratification dominates material selection, with feedstock origin and processing complexity determining price positioning.
- Synthetic:Petroleum-derived polyurethane and thermoplastic elastomers enabling complex colorways and weather resistance. Indonesian manufacturing clusters process the majority of global synthetic upper volume, though ECHA REACH compliance costs are compressing margins for non-reformulated suppliers.
- Mesh:Knit polyester and engineered textile uppers delivering targeted breathability zones. Automated flat-knitting adoption in Ho Chi Minh City industrial zones is reducing waste coefficients versus cut-and-sew alternatives.
- Leather:Full-grain and corrected-grain hides serving premium casual segments where durability signals quality. Italian tanneries retain dominance in luxury-tier sourcing despite capacity expansion in India's Kanpur cluster.
- Canvas:Woven cotton uppers offering cost efficiency and vintage aesthetic alignment. Hobbyist collectors and retro-styling enthusiasts in Japan sustain niche demand through limited reissue programs.
Synthetic commands the largest production footprint. Mesh is climbing the fastest as sustainability mandates tighten.
End User:
Application intensity separates this category, from daily wear frequency to specialized performance demands.
- Professionals:Office-appropriate athleisure and commuter-focused designs. White-collar workers in China's tier-1 cities are expanding this segment through workplace dress code relaxation and subway-accessible fitness club integration.
- Athletes:Competitive and serious recreational participants requiring injury-prevention engineering. Marathon training programs in Kenya and Ethiopia are driving technical footwear adoption among emerging-market running communities.
- Students:Price-sensitive buyers prioritizing style versatility and social media visibility. Campus-adjacent retail in South Korea's Seoul metropolitan area concentrates volume for trend-responsive releases.
- Hobbyists:Collectors and customization enthusiasts engaging in secondary market trading. Authentication-enabled resale platforms in the United Kingdom are formalizing this segment's asset-class characteristics.
Professionals absorb the highest per-unit spending. Athletes are gaining share fastest as sports participation rebounds.
Distribution Channel:
Customer type and purchase urgency dictate channel selection, from immediate fit verification to discovery-driven browsing.
- Retail Stores:Big-box and department store footprints enabling tactile evaluation and instant fulfillment. Mall-based traffic in Brazil's São Paulo state remains resilient for mid-tier family purchasing decisions.
- Online:Direct-to-consumer platforms and marketplace aggregators offering breadth and convenience. India's metro tier-1 cities are expanding this channel fastest as logistics infrastructure matures and return policies standardize.
- Specialty Shops:Curated assortments with technical fitting services and community programming. Running-focused independents in Australia's Melbourne and Sydney clusters sustain loyalty through gait analysis and training group integration.
- Wholesalers:Volume distributors serving institutional buyers and secondary market resellers. Bulk procurement for corporate wellness programs in Canada's Ontario province is formalizing this channel's B2B dimension.
Retail Stores maintain the broadest geographic coverage. Online is expanding most quickly as mobile payment penetration deepens.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redirecting assembly capacity toward jurisdictions with lower compliance costs and preferential trade access. Vietnam and Indonesia capture volume migrating from legacy manufacturing centers. ECHA's evolving REACH restrictions reshape material sourcing calculus for European-bound production.
United States
Fitness-conscious professionals in metropolitan corridors drive premium athletic adoption. California's Proposition 65 enforces phthalate disclosure thresholds that exceed federal requirements. Portland, Oregon and Boston, Massachusetts anchor design-engineering clusters where biomechanical R&D concentrates.
China
Domestic athleisure expansion and tier-1 city fitness club penetration propel volume. SAMR enforcement of GB standards on product labeling creates compliance layers for imported brands. Dongguan and Quanzhou manufacturing zones scale automated knit-upper production for regional brands.
Germany
Marathon running culture and performance-tier specialization sustain technical footwear demand. ECHA REACH substance restrictions force polyurethane adhesive reformulation across supply chains. Bavaria's engineering corridor hosts biomechanics research facilities serving European athletic brands.
Vietnam
Ho Chi Minh City industrial zones capture assembly capacity through specialized footwear parks and EU trade agreement access. BIS certification alignment discussions with Indian regulators open secondary export pathways. Binh Duong province concentrates synthetic upper and outsole molding operations.
India
Metro tier-1 fitness club expansion and workplace dress-code relaxation expand athleisure adoption. BIS harmonization with ISO standards reduces import friction for premium athletic brands. Kanpur's leather cluster scales corrected-grain hide processing for premium casual segments.
Women's Sneakers Market Competitive Landscape
US-based producers anchor the premium design tier; Asian specialists hold assembly-scale positions. Market structure concentrates around three to five integrated players with captive retail channels, while mid-tier specialists fragment across material niches. Two strategic archetypes dominate: vertically integrated brand-houses controlling design-through-distribution, and contract manufacturers scaling capacity for licensed production. Competitive moves center on M&A for digital customization capabilities and Southeast Asian capacity expansion.
Among the integrated brand-houses, Nike Inc., adidas AG, and ANTA Sports Products Limited occupy distinct geographic anchor positions. Nike Inc. exemplifies the design-forward archetype with captive distribution networks. adidas AG represents European performance-tier specialization with biomechanical R&D concentration. ANTA Sports Products Limited anchors domestic Chinese channel dominance while extending into Southeast Asian export corridors.
| Leading Market Players |
|---|
| ASICS Corporation |
| Deckers Brands |
| Nike Inc. |
| ANTA Sports Products Limited |
| Vans, Inc. |
| adidas AG |
| Reebok International Limited |
| New Balance |
| Puma SE |
| Others |
Pricing and Supply Chain Analysis
Fitness-conscious professionals in North America demanding verified bio-content formulations are forcing European suppliers to accelerate REACH-compliant adhesive reformulation, compressing margins for non-compliant manufacturers while concentrating pricing power among certified tier-1 assembly partners in Vietnam and Indonesia.
Pricing Analysis
Direct-to-consumer platform discounts and wholesale margin dilution create the dominant pricing architecture across women's sneakers. Three-tier pricing structure across premium, standard, and economy levels separates carbon-plate performance tiers from knit-upper lifestyle models from basic canvas constructions. Cost compression in midsole foam tiers is intensifying because petrochemical feedstock volatility transfers hedging burdens onto smaller manufacturers. Students and price-sensitive casual buyers exhibit highest price elasticity, while marathon runners and CrossFit practitioners in Germany demonstrate lowest sensitivity for verified bio-content premiums.
Supply Chain Analysis
EU REACH certification and California Proposition 65 qualification requirements now gate supplier eligibility for North American and European-bound production. Vietnam, Indonesia, and China concentrate 75% of global assembly capacity, with Ho Chi Minh City industrial zones capturing the fastest capacity migration. Feedstock dependencies on petroleum-based EVA, synthetic rubber, and engineered polyester knits expose margins to commodity price swings. Single-source vulnerability concentrates in Indonesian coastal clusters controlling 60% of regional outsole molding. Distribution runs through brand-houses' captive retail networks, direct-to-consumer platforms, and specialty running shops with technical fitting services.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
REACH compliance cost differentials between European suppliers and Southeast Asian manufacturers create arbitrage conditions favoring capacity relocation to Vietnam's specialized footwear industrial zones.
For Market Incumbents: Extend captive distribution control through direct-to-consumer micro-factory deployment in urban North American markets, bypassing wholesale margin erosion. Deepen backward integration into automated flat-knitting cell technology to defend against emerging contract manufacturers scaling 3D-knitting customization. Accelerate bio-based midsole patent portfolios before ECHA's next substance restriction expansion. For New Entrants and Emerging Players: The mid-tier price-point gap between adidas AG performance specialization and economy-tier canvas producers offers white-space entry through recycled-content positioning. India's metro tier-1 cities present the most penetrable geography given BIS harmonization reducing import friction. Target specialty running shops with technical fitting services as the primary go-to-market channel, leveraging community programming to build brand credibility without mass marketing spend. For Investors and Strategic Acquirers: Asymmetric upside sits with contract manufacturers possessing Vietnam-based capacity and EU trade agreement access. Long-term viability across the analysis window favors suppliers integrating carbon-accounting platforms with legacy PLM systems for scope-3 reporting compliance. Watch for ECHA REACH candidate list expansion announcements as the inflection signal triggering accelerated M&A for compliant adhesive formulators.| Strategic Initiative | Industry Significance |
|---|---|
| Sustainability Repositioning | Bio-based midsole patents absorb R&D investment from major suppliers prioritizing feedstock origin. |
| Direct-to-Consumer Launch | Same-week customization delivery bypasses wholesale margin dilution in urban North American markets. |
| Geographic Manufacturing Footprint | Vietnam's specialized footwear parks capture capacity migrating from legacy centers through preferential trade access. |
| Strategic Partnership | NFC chip verification integration with resale platforms compresses counterfeit arbitrage windows for limited releases. |
| Brand Extension | Designer collaborations emphasizing scarcity concentrate value retention in authenticated secondary markets. |
Research Methodology
Bottom-up end-use modeling reconciled against top-down supply-side tracking forms the analytical core of this study. Primary interviews with brand-house supply chain directors, Vietnamese manufacturing cluster managers, specialty running shop owners, and ECHA regulatory affairs consultants combined with secondary validation from EU REACH substance restriction updates, US customs import records, and athletic footwear patent filings. Triangulation across stakeholder inputs and documentary sources anchors volume and value estimates.
Input-output matrices map raw material flows through synthetic upper, knit textile, and leather tanning tiers into finished goods distribution channels. Segmentation dimensions modeled include product type, material composition, end-user archetype, and distribution channel across the analysis window. CAGRs derive from elasticity-adjusted adoption curves for bio-based formulations and capacity expansion timelines in Vietnamese industrial zones. Forecast inputs incorporate ECHA regulatory phase-in schedules and fitness club penetration rates in metro tier-1 cities.
Caveats apply where ECHA REACH substance restriction acceleration or EVA feedstock price volatility spikes could materially shift the outlook. Forecasts reflect assumptions about BIS-ISO harmonization completion and EU-Vietnam trade agreement stability. A model refresh is warranted upon material change in ECHA candidate list expansion timing or petrochemical input cost trajectories.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Footwear
Tennis Shoes Market
Footwear
Riding Boots Market
Footwear
Sports Shoes Market
Footwear
Global Espadrille Flats Market
Footwear
Slip Resistant Shoes Market
Footwear
Orthopedic Footwear Market
Footwear
Winter Footwear Market
Footwear
United States Footwear Market
Footwear
Men Formal Shoe Market
Footwear
Footwear Manufacturing Machinery Market
Footwear
Second Hand Designer Shoes Market
Footwear
Asia-Pacific Athletic Footwear Market
Footwear
Shoe Rental Service Market
Footwear
Tactical Footwear Market
Footwear
Desert Boots Market
Footwear
Europe Barefoot Shoes Market