
 Mountain Bike Footwear and Socks Market | 2026-2036
Mountain Bike Footwear and Socks Market Size, Share, and Industry Trends Forecast 2026-2036
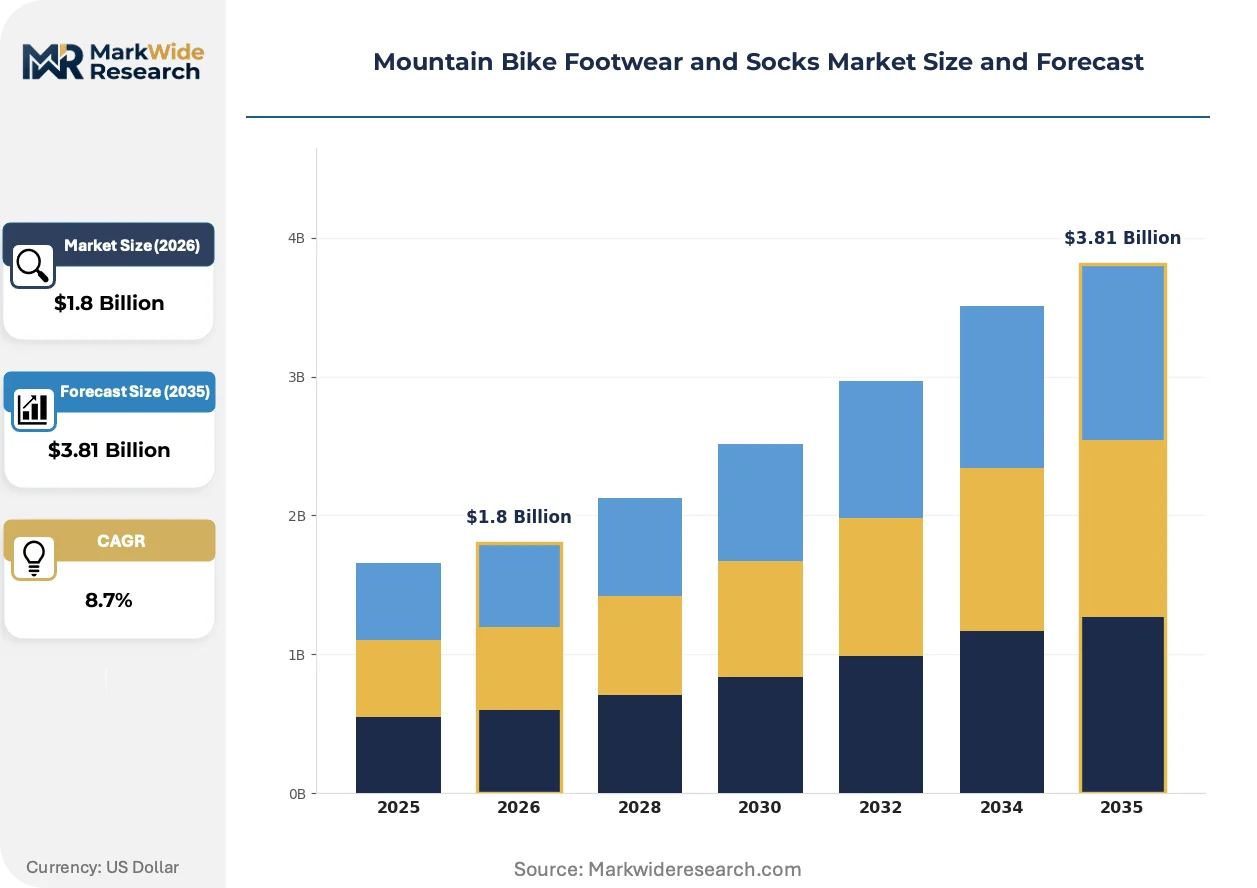
Mountain Bike Footwear and Socks Market Outlook
CE marking under the EU Personal Protective Equipment Regulation is rotating the competitive landscape for mountain bike footwear sold in Europe, forcing smaller brands to absorb third-party testing costs or exit. Shimano leverages its drivetrain ecosystem to anchor clipless shoe demand across OEM partnerships with bike manufacturers. Five Ten specializes in Stealth rubber compound R&D to dominate the flat pedal segment among gravity riders. Pearl Izumi sustains brand loyalty through domestic manufacturing flexibility and rapid seasonal colorway turnover.
Mountain bike footwear and socks comprise purpose-built pedal interface systems and moisture-management textiles engineered with thermoplastic polyurethane shanks, EVA midsole stacks, and merino-nylon sock blends for impact absorption and thermoregulation during off-road cycling. Clipless shoes with two-bolt cleat compatibility capture the largest revenue pool as cross-country and marathon disciplines retain dedicated rider bases, while flat pedal shoes with proprietary rubber outsoles represent the fastest-expanding category driven by downhill and freeride participation growth. Technical socks with graduated compression zones and reinforced heel-toe boxes command premium positioning as riders treat them as performance equipment rather than commodity accessories.
REACH restrictions on per- and polyfluoroalkyl substances constrain waterproof membrane chemistries across European supply chains, compelling reformulation of breathable bootie constructions. The US Consumer Product Safety Commission monitors children's footwear flammability standards, though adult mountain bike products fall outside mandatory testing scopes. California's Proposition 65 labeling requirements create compliance friction for direct-to-consumer brands shipping into the state. Stakeholders must track evolving chemical disclosure mandates and cleat interface standardization debates between SPD and competing pedal systems to anticipate inventory and design commitments.
Market Dynamics
Thermoplastic polyurethane midsole construction is compressing product development cycles while REACH chemical compliance in Europe forces rapid reformulation of waterproof membrane chemistries across supply chains.
Growth Catalysts
- Enduro racing participation:Gravity discipline expansion across Colorado's Front Range and British Columbia's Sea-to-Sky corridor is pulling flat pedal shoe demand upward through dedicated trail network investment.
- REACH chemical disclosure mandates:European reformulation requirements are accelerating R&D collaboration between material suppliers and footwear brands seeking compliant waterproof bootie constructions.
- Merino-nylon textile blends:Sock manufacturers deploying graduated compression zones are capturing premium positioning as riders reclassify technical socks from accessories to performance equipment.
Market Restraints
- TPU resin price volatility:Thermoplastic polyurethane feedstock fluctuations compress margin predictability for midsole stack producers dependent on petrochemical supply chains.
- CE marking compliance costs:EU Personal Protective Equipment Regulation third-party testing burdens force smaller brands to absorb fixed costs or exit European distribution entirely.
- Clipless-to-flat switching friction:Rider investment in two-bolt cleat systems creates stickiness that slows category migration even as gravity participation expands.
Strategic Opportunities
- German specialty retail consolidation:Independent bike shop networks in Bavaria and Baden-Württemberg present white space for direct brand partnership models bypassing traditional distribution markups.
- California Proposition 65 compliance services:Direct-to-consumer brands face labeling friction entering the state, creating advisory and logistics service revenue pools for compliance specialists.
- SPD-HT interface convergence:Cleat standardization debates between competing pedal systems open technology licensing windows for interface-agnostic footwear architectures.
Industry Challenges
- Rapid seasonal colorway turnover:Domestic manufacturing flexibility demands compress design-to-shelf timelines, straining inventory planning systems and forecast accuracy.
- Children's footwear flammability monitoring:US Consumer Product Safety Commission surveillance creates testing overhead even where adult products fall outside mandatory scopes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mountain Bike Footwear and Socks Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Clipless Shoes, Flat Pedal Shoes, Mountain Bike Socks, Technical Socks Material: Mesh, Leather, Synthetic, Wool Feature: Waterproof, Breathable, Insulated, Lightweight Size: Small, Medium, Large, Extra Large |
| Companies Covered | Specialized, Shimano, Five Ten, Pearl Izumi, Giro, Northwave, Fox Racing, Sidi, Mavic, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mountain Bike Footwear and Socks Market Strategic Shifts
Material science breakthroughs and regulatory chemistry constraints are simultaneously enabling performance gains and forcing supply chain reconstruction across mountain bike footwear manufacturing.
Thermoplastic polyurethane shank integration is fragmenting traditional EVA-dominant midsole construction. Downhill and freeride riders are adopting stiffer platform shoes at accelerating rates. This stiffness gradient is fragmenting the historical cross-country monopoly on technical footwear premiumization.
REACH restrictions on per- and polyfluoroalkyl substances are eliminating legacy waterproof membrane chemistries from European supply chains. Breathable bootie constructions require complete reformulation without performance degradation. German and Austrian alpine-oriented brands face the steepest retooling timelines given their waterproofing heritage.
After-sales service unbundling is disrupting traditional warranty bundling across direct-to-consumer channels. Riders now purchase crash replacement and resoling as separate SKUs rather than embedded value. British Columbia's dense trail network shows the highest attach rates for these unbundled service contracts.
Mountain Bike Footwear and Socks Market Segmentation
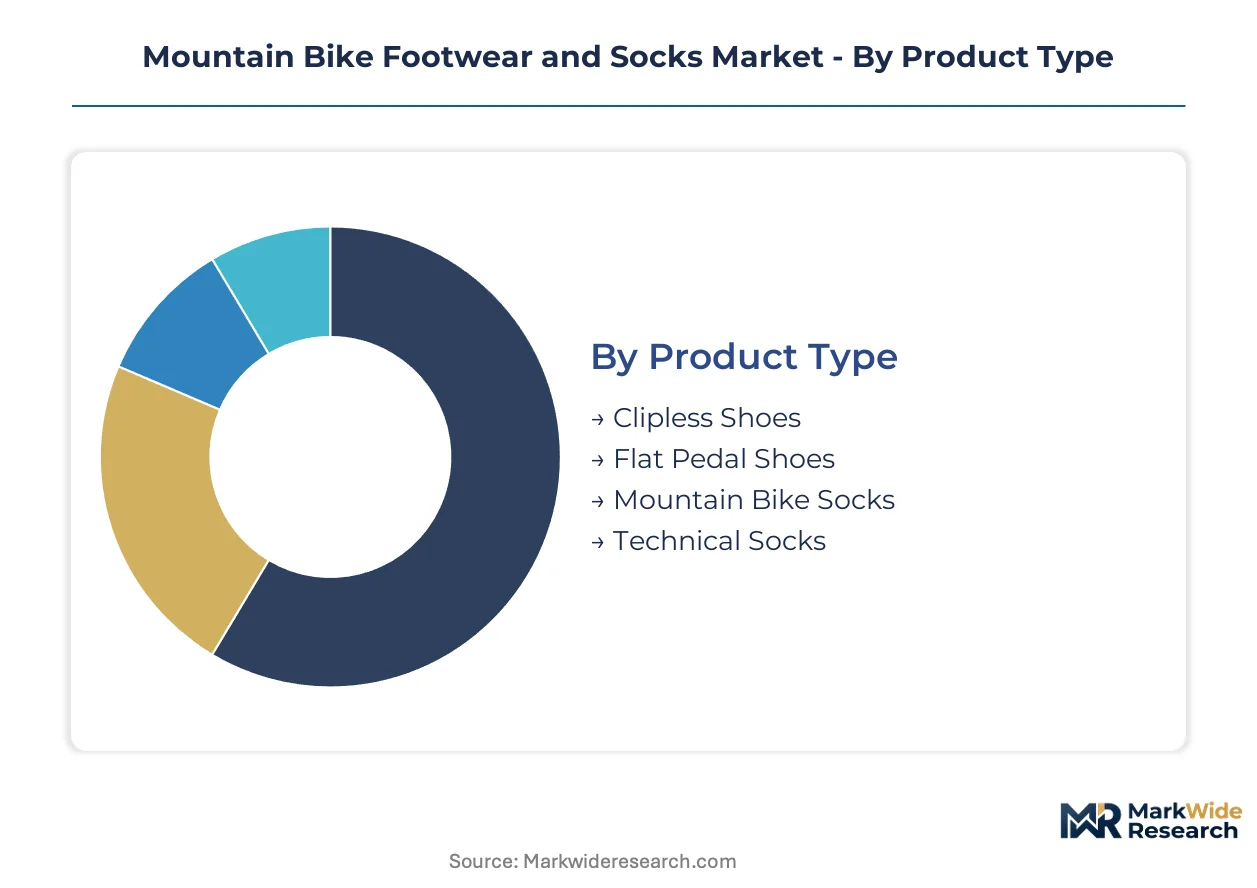
Mountain bike footwear and socks fragment across pedal interface systems, textile engineering, and climate-adaptive features. Manufacturers configure supply chains differently for each segment, with clipless production concentrating near drivetrain OEMs while flat pedal and sock manufacturing disperses across textile hubs.
Product Type:
Clipless shoes dominate domestic manufacturing footprints in Germany and Colorado, while flat pedal and sock production spreads across Asian textile corridors for cost-competitive export positioning.
- Clipless Shoes:Two-bolt cleat-compatible uppers integrate thermoplastic polyurethane shanks and EVA midsole stacks for power transfer efficiency. Demand clusters around Bavaria's marathon racing circuits and Colorado's cross-country trail networks, constrained by rider investment stickiness in existing pedal systems.
- Flat Pedal Shoes:Proprietary rubber outsoles—Stealth compounds and competing formulations—deliver friction coefficients optimized for gravity riding. British Columbia's Sea-to-Sky corridor and Colorado's Front Range pull volume fastest as enduro trail networks expand.
- Mountain Bike Socks:Basic moisture-wicking constructions serve entry-level riders through mass retail channels.
- Technical Socks:Graduated compression zones and merino-nylon blends command premium positioning in specialty retail.
Clipless shoes command the established base. The steepest expansion runs through flat pedal shoes.
Material:
Cost tiers separate premium natural fibers from mass-market synthetics, with leather and wool commanding 3-4x raw material premiums over mesh and petroleum-based alternatives.
- Mesh:Synthetic woven uppers prioritize breathability and weight reduction for cross-country racing applications.
- Leather:Full-grain and nubuck constructions deliver durability and weather resistance for alpine touring segments in Austria and Switzerland.
- Synthetic:PU-coated textiles and welded overlays dominate volume manufacturing through thermoforming compatibility and REACH-compliant chemistry pathways.
- Wool:Merino blends regulate temperature across variable elevation zones, concentrating demand in Pacific Northwest and New Zealand riding climates.
Leather retains the premium positioning anchor. Synthetic materials scale fastest through manufacturing flexibility.
Feature:
Application context—racing versus recreational, summer versus winter—determines feature bundling, with waterproofing facing the steepest regulatory reformulation costs under REACH.
- Waterproof:Breathable bootie constructions with membrane laminates face forced chemistry transitions as ECHA restrictions eliminate legacy PFAS formulations. German and Austrian alpine brands absorb the steepest retooling timelines.
- Breathable:Ventilated uppers and moisture-wicking linings target high-output aerobic riding in temperate climates, dominating Colorado and California retail mixes.
- Insulated:Thinsulate and synthetic loft constructions extend riding seasons into sub-zero conditions, concentrating in Scandinavian and Rocky Mountain markets.
- Lightweight:Minimal stack heights and drilled carbon soles serve competitive cross-country weight weenies.
Breathable features capture volume leadership. Waterproof segments face the most volatile supply reconstruction.
Size:
Volume concentration in medium and large brackets shapes inventory planning, while small and extra-large SKUs strain forecast accuracy through irregular demand patterns.
- Small:Junior and women-specific lasts require dedicated mold investments with lower utilization rates.
- Medium:Core adult male sizing drives production line configuration and bulk material procurement.
- Large:Secondary volume anchor with strong correlation to North American body mass distributions.
- Extra Large:Niche sizing with elevated stockout risk and limited style availability.
Medium sizing anchors production planning. Large sizing scales fastest through demographic shifts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
REACH chemical disclosure mandates in Europe and trail network investments across North American recreational corridors are redistributing manufacturing footprints and retail channel priorities for mountain bike footwear and socks.
United States
Colorado's Front Range and Pacific Northwest trail systems are accelerating flat pedal shoe demand through enduro network expansion. The US Consumer Product Safety Commission monitors children's footwear flammability standards, creating compliance overhead for brands with junior product lines. California's Proposition 65 labeling requirements generate friction for direct-to-consumer brands shipping into the state.
Germany
Bavaria's marathon racing circuits and Baden-Württemberg's specialty retail networks anchor clipless shoe demand across Alpine touring segments. ECHA restrictions on per- and polyfluoroalkyl substances force reformulation of waterproof membrane chemistries, compelling R&D collaboration between material suppliers and footwear brands. The Black Forest region concentrates alpine-oriented brands facing steep retooling timelines.
Canada
British Columbia's Sea-to-Sky corridor pulls volume fastest as gravity trail networks expand across Whistler and Squamish. Health Canada oversees product safety standards for recreational equipment entering provincial distribution. Vancouver's dense trail network shows the highest attach rates for unbundled after-sales service contracts including crash replacement and resoling.
Austria
Alpine touring segments in Tyrol and Salzburg drive demand for leather-constructed, weather-resistant footwear. REACH compliance deadlines accelerate supply chain reconstruction for waterproof bootie constructions. The Inn Valley region hosts material suppliers partnering with footwear brands on compliant membrane laminates.
United Kingdom
Scottish Highlands trail development and Welsh gravity centers are diversifying rider discipline participation beyond traditional cross-country bases. The UK's departure from EU regulatory frameworks creates dual compliance obligations for brands serving both markets. The Peak District concentrates independent bike shop networks experimenting with direct brand partnership models.
Mountain Bike Footwear and Socks Market Competitive Environment
Player mix skews toward diversified outdoor conglomerates and drivetrain-integrated specialists, with footwear-pure players occupying niche premium positions. Three structural tiers have crystallized: ecosystem-anchored manufacturers leveraging OEM bike partnerships, rubber compound specialists dominating gravity segments, and textile-centric brands capturing sock premiumization. Competitive moves concentrate on strategic partnerships with bike manufacturers and rapid seasonal colorway turnover to defend shelf position.
Within the ecosystem-anchored tier, Shimano Inc. and Specialized Bicycle Components occupy positions that exemplify drivetrain-to-footwear integration strategies. Five Ten represents the rubber compound specialization archetype, while Pearl Izumi sits within the domestic manufacturing flexibility tier that enables rapid design-to-shelf timelines.
| Leading Market Players |
|---|
| Specialized |
| Shimano |
| Five Ten |
| Pearl Izumi |
| Giro |
| Northwave |
| Fox Racing |
| Sidi |
| Mavic |
| Others |
Value Chain & Pricing Dynamics
Ninety-day inventory cycles for TPU midsole components compress margin buffers while amplifying pricing power for German and Austrian alpine brands with captive membrane R&D capabilities. This lead-time band concentrates cost pressure on flat pedal shoe manufacturers dependent on Asian rubber compound sourcing, forcing tiered pricing responses across clipless and gravity segments.
Pricing Analysis
CE certification grade creates the primary spread between premium alpine footwear and mass-market trail shoes. Three-tier pricing structure across premium, standard, and economy levels segments riders by pedal system investment and climate exposure. Pricing pressure stems from REACH reformulation costs absorbing waterproof membrane R&D budgets. Entry-level cross-country riders show highest price sensitivity, while enduro participants accept premium positioning for Stealth rubber and crash replacement bundles.
Supply Chain Analysis
Strait of Malacca transit routes underpin thermoplastic polyurethane resin flows from South Korean petrochemical complexes to Vietnamese midsole molding facilities. Manufacturing gravity centers on China for flat pedal rubber outsoles, Vietnam for TPU shank integration, and Germany for clipless cleat interface precision. Raw material dependencies include petroleum-derived TPU feedstocks, merino wool from New Zealand, and synthetic rubber from Thailand. Single-source vulnerability concentrates in Stealth rubber compound formulations. Distribution runs through Colorado and British Columbia specialty retail clusters for gravity segments, Bavarian independent bike shops for alpine touring.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Mountain bike footwear demand tracks trail network investment cycles, with British Columbia and Colorado infrastructure spending signaling recovery-phase entry. Enduro racing participation growth provides the cyclical justification for capacity commitment.
For Market Incumbents: Shield proprietary rubber compound IP through exclusive supplier agreements with Thai synthetic rubber processors. Consolidate position in Bavarian specialty retail through direct partnership models that bypass distributor markups. Counter Five Ten's gravity dominance by acquiring merino-nylon textile specialists in New Zealand. For New Entrants and Emerging Players: Differentiate on REACH-compliant waterproof membrane formulations targeting German and Austrian alpine brands facing retooling deadlines. Target the flat pedal sock premiumization white space where graduated compression technology remains underdeveloped. Pursue direct-to-consumer launch with California Proposition 65 compliance bundled as a service feature. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across TPU midsole construction as European brands reshore membrane lamination capabilities. Five-to-ten year viability favors footwear-pure players with domestic manufacturing flexibility over diversified outdoor conglomerates. Watch SPD-HT cleat standardization debates as the inflection signal for interface-agnostic acquisition targets.| Strategic Initiative | Industry Significance |
|---|---|
| REACH-Compliant Membrane Reformulation | ECHA deadlines force R&D collaboration between Austrian material suppliers and Bavarian footwear brands. |
| Direct-to-Consumer Channel Launch | California Proposition 65 compliance services create advisory revenue pools for specialty entrants. |
| Domestic Manufacturing Flexibility Investment | Pearl Izumi's rapid colorway turnover model defends shelf position against Asian cost competitors. |
| After-Sales Service Unbundling | British Columbia riders purchase crash replacement and resoling as separate SKUs at highest attach rates. |
| Cleat Interface Technology Licensing | SPD-HT standardization debates open windows for pedal-agnostic footwear architectures. |
Study Parameters
Desk research of customs trade data, ECHA chemical restriction filings, and specialty retail point-of-sale audits preceded structured interviews with footwear R&D directors, independent bike shop owners in Bavaria and Colorado, TPU material suppliers in Germany, and enduro race organizers in British Columbia. Primary fieldwork with cleat interface engineers and sock textile manufacturers validated secondary findings. Bottom-up segment sizing triangulated against top-down outdoor industry expenditure estimates.
Variance decomposition across pedal interface systems, textile engineering tiers, and climate-adaptive features shaped the analytical framework over the projection horizon. Modeled dimensions include clipless versus flat pedal architecture, waterproof versus breathable construction, and regional regulatory clusters. CAGRs derived from trail network investment pipelines and participation rate elasticities. Industry-specific inputs incorporated REACH compliance cost absorption rates and seasonal inventory turnover benchmarks from Pacific Northwest retailers.
The analysis sits within stated boundaries; outcomes outside sustained enduro racing participation growth or ECHA enforcement intensity would require recalibration. Forecasts reflect documented assumptions regarding TPU resin price stability and cleat standardization timelines. Practitioners should keep alternative scenarios live as REACH chemical disclosure mandates and trail infrastructure funding cycles evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Footwear
Desert Boots Market
Footwear
Orthopedic Footwear Market
Footwear
Luxury Footwear Market
Footwear
Athletic Footwear Market
Footwear
Slip Resistant Shoes Market
Footwear
Equestrian Footwear Market
Footwear
Western Boots Market
Footwear
White Sneakers Market
Footwear
Tactical Footwear Market
Footwear
Self-Lacing Shoes Market
Footwear
Training Shoes Market
Footwear
Duck Boots Market
Footwear
Platform Boots Market
Footwear
Global Men Leather Shoes Market
Footwear
Women's Sneakers Market
Footwear
Dance Shoes Market