
 Footwear Testing Services Market | 2026-2036
Footwear Testing Services Market Size, Share, and Industry Trends Forecast 2026-2036
Footwear Testing Services Market Insights
Vietnam's footwear export corridor is reconfiguring how testing providers allocate laboratory capacity across Southeast Asia. Intertek Group Plc leverages its Ho Chi Minh City facility network to anchor chemical testing workflows for brands shifting production from China. Bureau Veritas competes through specialized safety footwear certification programs aligned with ASTM and EN standards. SATRA differentiates by sustaining deep technical partnerships with UK-based retail chains requiring pre-shipment durability validation.
Footwear testing services encompass mechanical, chemical, performance, and durability assessments applied to finished shoes, components, and raw materials to verify compliance with safety, quality, and environmental specifications. Mechanical testing evaluates sole adhesion, upper tensile strength, and heel impact resistance using calibrated equipment under controlled temperature and humidity conditions. Chemical testing dominates service revenue as manufacturers face escalating restrictions on restricted substances like chromium VI and phthalates across multiple jurisdictions. Performance testing grows fastest among segments, driven by athletic brands requiring biomechanical validation of cushioning, traction, and energy return claims before market introduction.
FDA guidelines for medical-grade therapeutic footwear, EPA regulations on volatile organic compound emissions from adhesives, and ISO 17025 accreditation requirements collectively shape laboratory investment priorities and client eligibility criteria. REACH enforcement by ECHA and California's Proposition 65 litigation risk compel brands to expand testing scope beyond baseline compliance to full material transparency. Stakeholders must monitor evolving PFAS restrictions in multiple jurisdictions and assess whether existing chemical testing protocols capture next-generation fluorinated compounds before regulatory deadlines crystallize.
Market Dynamics
Factory consolidation across Vietnam's export manufacturing zones is compressing testing batch sizes while elevating frequency requirements, forcing laboratories to reconfigure workflow automation and shift scheduling to maintain margin.
Growth Catalysts
- REACH Substance Restrictions:ECHA's expanding candidate list of restricted chemicals compels EU-bound manufacturers to validate every material tier, multiplying testing touchpoints per footwear shipment.
- Athletic Biomechanics Validation:Performance claims for energy return and traction now require pre-market laboratory certification, creating dedicated testing programs for running and basketball shoe lines.
- Vietnam Export Corridor Concentration:Factory clustering in Ho Chi Minh City and Binh Duong provinces generates economies of scale for regional laboratory networks serving US and EU destinations.
Market Restraints
- Specialized Equipment Capital Intensity:Mass spectrometry and climate-controlled aging chambers require seven-figure investments with depreciation cycles exceeding contract renewal horizons.
- Phthalate Reference Material Volatility:Certified chemical standards for restricted substance calibration face supply bottlenecks from limited European specialty chemical producers.
- ISO 17025 Accreditation Friction:Multi-year certification timelines and audit backlogs constrain laboratory expansion velocity in high-demand manufacturing regions.
Strategic Opportunities
- India Domestic Manufacturing Incentives:PLI scheme subsidies for footwear production are attracting testing providers to establish presence in Tamil Nadu and Uttar Pradesh industrial corridors.
- PFAS Next-Generation Protocol Development:Regulatory deadlines for fluorinated compound restrictions create first-mover advantage for laboratories validating alternative water-repellent chemistries.
- Digital Twin Integration:Convergence of finite element modeling with physical testing protocols enables predictive durability simulation before prototype fabrication.
Industry Challenges
- Chromatography Specialist Scarcity:Chemical testing workflows face recruitment friction for technicians proficient in GC-MS and LC-MS/MS operation and interpretation.
- Multi-Jurisdiction Certification Parallel Processing:Simultaneous ASTM, EN, and GB standard validation creates scheduling complexity and equipment conflict in shared laboratory facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Footwear Testing Services Market |
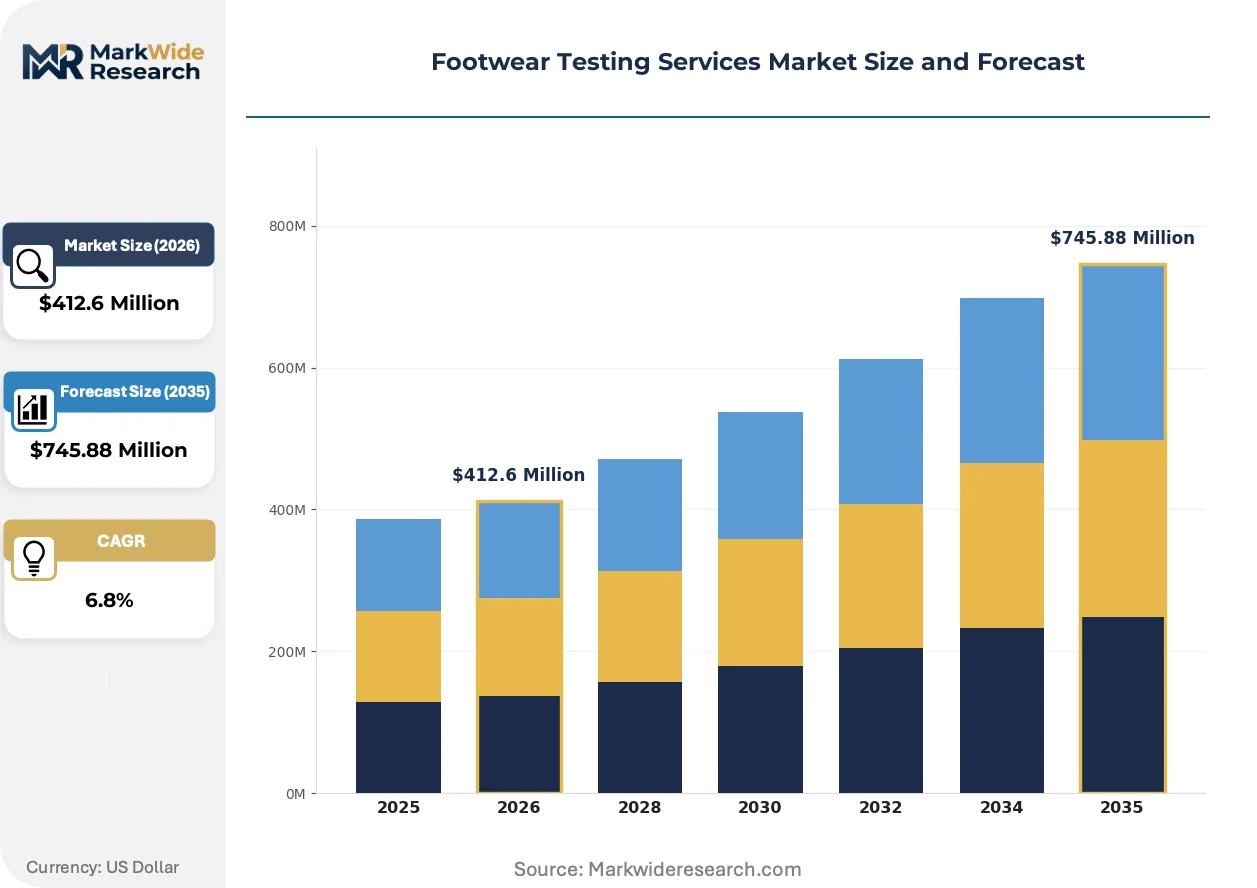
| Market Size in 2026 | $412.6 Million |
| Market Size in 2035 | $745.88 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Mechanical Testing, Chemical Testing, Performance Testing, Durability Testing End User: Manufacturers, Retailers, Distributors, Quality Assurance Labs Testing Standard: ISO, ASTM, EN, BS Footwear Type: Sports Shoes, Casual Footwear, Safety Shoes, Fashion Footwear |
| Companies Covered | Intertek Group Plc, SGS SA, Bureau Veritas, SATRA, Highlight, Exos, TÜV SÜD, UL Solutions, ALS Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Footwear Testing Services Market Trends and Innovations
Digital instrumentation and automated sample handling are compressing turnaround times while expanding the scope of detectable chemical species, reshaping how laboratories compete on throughput and analytical depth.
Automated liquid handling systems are migrating from high-volume pharmaceutical quality control into footwear chemical testing workflows. Mid-sized athletic brands now specify robotic sample preparation in laboratory RFPs to reduce human error in restricted substance screening. This migration from manual pipetting is enabling 24-hour batch processing and compressing pre-shipment validation timelines from weeks to days.
REACH enforcement by ECHA is tightening documentation requirements for articles imported into the European single market. Manufacturers must now disclose full material composition down to 0.1% weight concentration for SVHCs, expanding testing scope from finished shoes to every component and adhesive layer. Athletic footwear with complex multi-material construction faces the steepest compliance cost escalation.
Retailer consolidation is consolidating testing procurement through approved vendor lists rather than factory-direct arrangements. Mass-market chains now mandate pre-shipment validation through designated laboratories, displacing manufacturer-selected testing relationships. This concentration is most visible in UK and German retail supply chains, where durability and chemical compliance certificates must carry specific laboratory accreditation marks.
Footwear Testing Services Market Segmentation
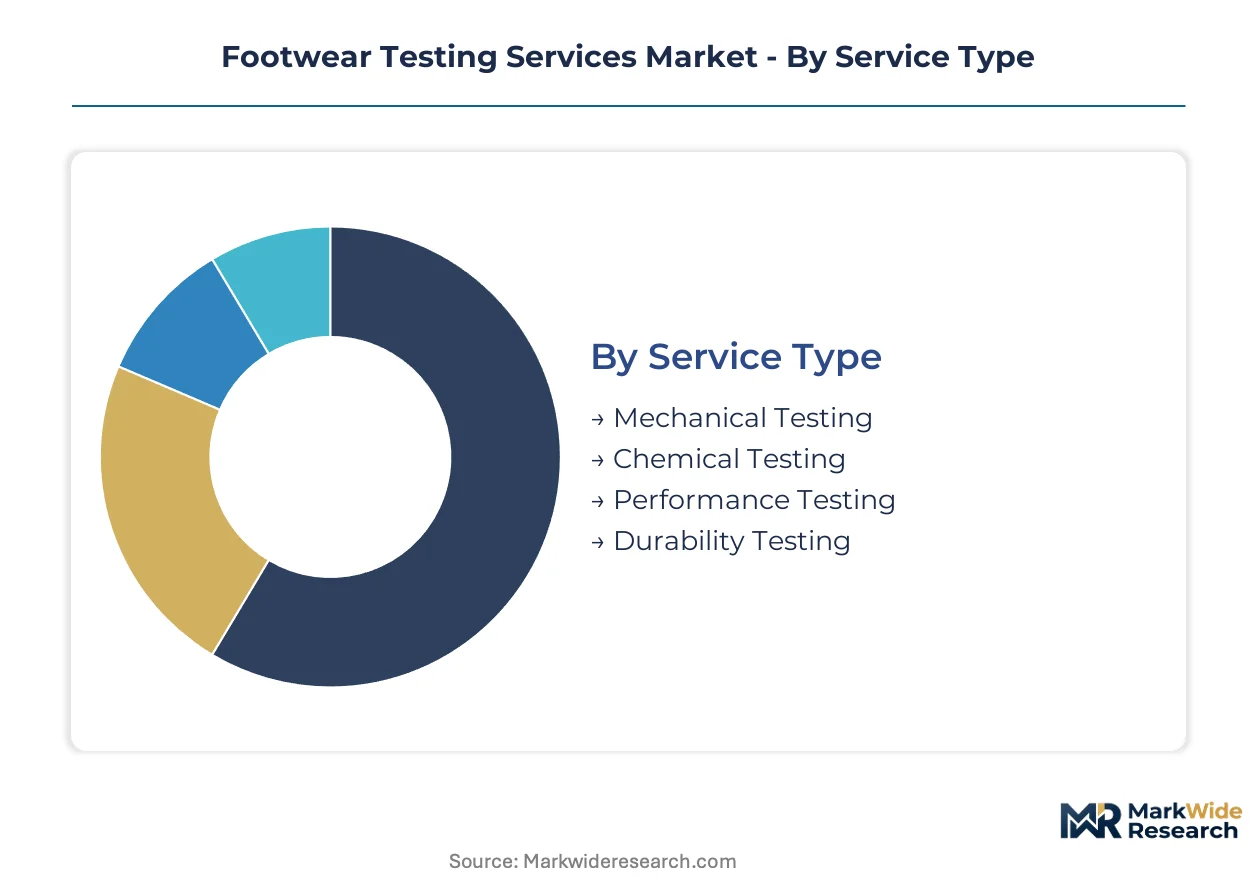
Testing service providers configure laboratory capacity and pricing structures around segment-specific turnaround demands. Chemical validation cycles differ sharply from mechanical stress protocols, creating distinct operational profiles within the same facility network.
Service Type:
Cycle times vary from same-day mechanical screening to multi-week chromatography workflows, compressing margin structures for high-frequency, low-margin segments while enabling premium pricing for complex analytical protocols.
- Chemical Testing:Mass spectrometry and chromatography protocols detect restricted substances including chromium VI, phthalates, and PFAS compounds across adhesives, textiles, and synthetic leathers. REACH enforcement by ECHA and Proposition 65 litigation in California compel athletic brands to validate every material tier, multiplying testing touchpoints per shipment.
- Performance Testing:Biomechanical validation of cushioning, traction, and energy return claims requires specialized equipment including force plates and motion capture systems. Running and basketball shoe lines now mandate pre-market certification, creating dedicated testing programs with extended validation timelines.
- Mechanical Testing:Evaluates sole adhesion, upper tensile strength, and heel impact resistance using calibrated equipment under controlled temperature and humidity conditions.
- Durability Testing:Climate-controlled aging chambers simulate wear cycles and environmental exposure for pre-shipment validation of finished footwear.
Chemical testing dominates installed base. Performance testing is where expansion concentrates.
End User:
Procurement authority is shifting from factory-direct arrangements toward retailer-mandated laboratory networks, restructuring how testing providers build account relationships and accreditation portfolios.
- Manufacturers:Factory consolidation across Vietnam's export zones is compressing batch sizes while elevating testing frequency, forcing producers to renegotiate annual testing contracts around throughput guarantees rather than per-sample pricing.
- Retailers:UK and German mass-market chains now mandate pre-shipment validation through approved vendor lists, displacing manufacturer-selected testing relationships and concentrating procurement through designated laboratories carrying specific accreditation marks.
- Distributors:Regional logistics providers require batch compliance documentation for customs clearance and warehouse acceptance across multiple destination markets.
- Quality Assurance Labs:Third-party facilities serving smaller brands seek ISO 17025 accreditation to qualify for retailer-approved vendor lists.
Manufacturers retain the largest testing volume. Retailer-mandated programs are gaining share fastest.
Testing Standard:
Multi-jurisdiction certification requirements create scheduling complexity and equipment conflict in shared laboratory facilities, particularly for athletic footwear destined for simultaneous EU and US market entry.
- ISO:ISO 17025 accreditation serves as baseline eligibility for laboratory participation in retailer-approved vendor programs and government procurement frameworks.
- ASTM:US-market safety footwear certification requires compliance with ASTM F2413 impact and compression standards, driving specialized equipment investment for industrial protective footwear.
- EN:European Norm standards govern safety footwear certification for EU single market access, with EN ISO 20345 representing the dominant technical specification.
- BS:British Standards remain relevant for UK-specific certification requirements post-Brexit, particularly for safety footwear procurement by UK-based industrial end-users.
ISO accreditation dominates laboratory certification portfolios. EN standard validation commands the steepest expansion trajectory.
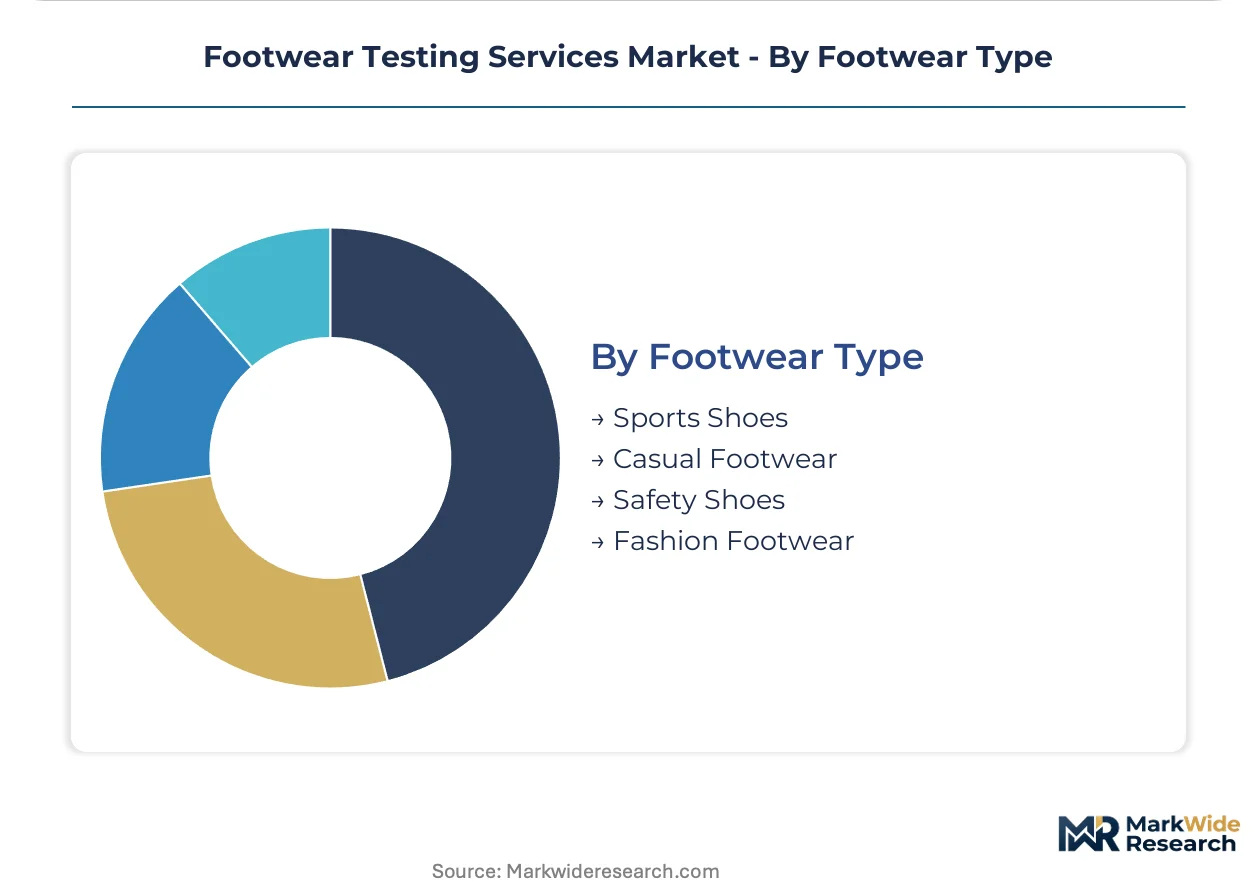
Footwear Type:
Material complexity and regulatory exposure vary sharply across footwear categories, with multi-material athletic construction facing the steepest compliance cost escalation.
- Sports Shoes:Complex multi-material construction combining synthetic textiles, foamed midsoles, and rubber outsoles faces the most extensive chemical screening requirements. Athletic brands now require biomechanical validation of performance claims before market introduction, layering performance testing atop baseline compliance.
- Safety Shoes:Protective footwear for industrial environments requires mechanical certification against impact, compression, and puncture hazards. ASTM and EN standard validation creates dedicated testing programs with specialized equipment configurations.
- Casual Footwear:Leather and canvas construction faces baseline REACH and Proposition 65 screening with moderate material complexity.
- Fashion Footwear:Seasonal product cycles and rapid style turnover compress testing timelines, prioritizing laboratory relationships with expedited turnaround capabilities.
Safety shoes anchor mechanical testing capacity. Sports shoes are driving the steepest expansion in chemical and performance validation demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Factory consolidation across Vietnam's export manufacturing zones is compressing testing batch sizes while elevating frequency requirements, reshaping how laboratories allocate capacity across Southeast Asia. Intertek Group Plc leverages its Ho Chi Minh City facility network to anchor chemical testing workflows for brands shifting production from China. This supply-side concentration is forcing testing providers to reconfigure workflow automation and shift scheduling to maintain margin.
Vietnam
Athletic footwear manufacturers are expanding third-party testing commitments as factory consolidation elevates batch-testing volumes for EU and US-bound shipments. REACH compliance requirements and dual carbon goals in China tighten material disclosure requirements for exporters. Ho Chi Minh City and Binh Duong provinces generate economies of scale for regional laboratory networks serving international destinations.
China
Dual carbon goals and tightening environmental regulations are displacing some footwear production to Vietnam while elevating domestic testing standards for remaining manufacturers. SAMR enforcement of GB standards and MEE oversight of chemical emissions compel brands to validate material composition. The Pearl River Delta and Yangtze River Delta industrial corridors maintain significant testing capacity for domestic and export markets.
United States
California's Proposition 65 litigation risk compels brands to expand testing scope beyond baseline compliance to full material transparency. FDA guidelines for medical-grade therapeutic footwear and EPA regulations on volatile organic compound emissions shape laboratory investment priorities. Testing demand concentrates in ports of entry and manufacturing clusters serving athletic and safety footwear segments.
Germany
ECHA's expanding candidate list of restricted chemicals compels EU-bound manufacturers to validate every material tier, multiplying testing touchpoints per footwear shipment. REACH enforcement tightens documentation requirements for articles imported into the European single market. Industrial clusters in Bavaria and North Rhine-Westphalia anchor safety footwear certification programs aligned with EN standards.
India
PLI scheme subsidies for footwear production are attracting testing providers to establish presence in Tamil Nadu and Uttar Pradesh industrial corridors. BIS standards and DGFT export requirements create domestic certification demand alongside international compliance needs. Factory expansion in these states is generating new laboratory capacity requirements for chemical and mechanical validation.
Footwear Testing Services Market Competitive Landscape
Full-service multinationals and specialized footwear technologists split the market between scale-driven compliance factories and boutique validation studios. Laboratory networks with ISO 17025 accreditation dominate retailer-approved vendor programs, while niche providers sustain deep technical partnerships with specific brand segments. Two strategic archetypes prevail: global testing conglomerates with diversified industrial portfolios, and footwear-dedicated specialists with embedded industry relationships. Competitive intensity centers on geographic expansion into Vietnam's export corridor and accreditation portfolio diversification to capture multi-jurisdiction certification demand.
Within the global conglomerate tier, Intertek Group Plc and SGS SA exemplify scale-driven positioning through facility networks spanning manufacturing origins and destination markets. Bureau Veritas occupies a position emphasizing specialized safety footwear certification programs. Among footwear-dedicated specialists, SATRA represents the boutique archetype through sustained technical partnerships with retail chains requiring pre-shipment durability validation. TÜV SÜD and UL Solutions sit within the diversified industrial testing segment, leveraging cross-sector accreditation portfolios to participate in footwear compliance workflows.
| Leading Market Players |
|---|
| Intertek Group Plc |
| SGS SA |
| Bureau Veritas |
| SATRA |
| Highlight |
| Exos |
| TÜV SÜD |
| UL Solutions |
| ALS Limited |
| Others |
Pricing and Supply Chain Analysis
REACH substance restriction enforcement from ECHA compresses both pricing tier spreads and supply chain configuration, compelling laboratories to absorb calibration material volatility while manufacturers face escalating validation costs per shipment tier.
Pricing Analysis
REACH compliance dictates the pricing tier structure across footwear testing services, separating ISO 17025-accredited premium laboratories from standard-tier facilities and economy providers lacking multi-jurisdiction certification. Price differentiation rests on accreditation portfolio breadth and robotic sample preparation capabilities, with athletic brands commanding expedited turnaround premiums. Cost compression in the economy tier is intensifying because factory consolidation in Vietnam elevates batch frequency without proportional volume scaling. Small and mid-sized manufacturers exhibit the highest price sensitivity, while multinational athletic brands prioritize accreditation marks over per-sample economics.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk calculus for footwear testing services, accelerating production relocation to Vietnam and compressing laboratory capacity planning horizons. Testing infrastructure concentrates in Vietnam, China, and Germany, with Ho Chi Minh City corridor expansion outpacing legacy Pearl River Delta capacity. Chromatography workflows draw from certified reference material suppliers in Europe, mass spectrometry equipment from Germany and Japan, and climate-controlled aging chambers from specialized industrial manufacturers. Single-source vulnerability pervades phthalate standard procurement from limited European specialty chemical producers. Distribution runs through retailer-approved vendor lists rather than factory-direct relationships, concentrating procurement authority with UK and German mass-market chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Footwear testing services are recovering from pandemic-induced laboratory capacity constraints, with factory consolidation in Vietnam driving cyclical demand expansion for pre-shipment validation workflows.
For Market Incumbents: Insulate margin structures by embedding automated liquid handling systems in Ho Chi Minh City facilities to offset technician recruitment friction for GC-MS and LC-MS/MS operation. Expand ISO 17025 accreditation portfolios to capture EN standard validation demand from EU-bound athletic footwear shipments, defending against specialized safety footwear certification programs from Bureau Veritas. For New Entrants and Emerging Players: Build out PFAS next-generation protocol development capabilities to capture first-mover advantage before regulatory deadlines crystallize across multiple jurisdictions. Target India's Tamil Nadu and Uttar Pradesh industrial corridors under PLI scheme subsidies, leveraging lower accreditation backlog friction than saturated Southeast Asian markets. Position through digital twin integration partnerships with athletic brands seeking predictive durability simulation before prototype fabrication. For Investors and Strategic Acquirers: The market sits at a capacity-constrained recovery phase that favors accredited laboratory networks with embedded retailer relationships over undifferentiated testing commodity providers. Long-term viability across the next decade hinges on capturing multi-jurisdiction certification demand from factory consolidation trends. Monitor ECHA candidate list expansion velocity as the primary inflection signal for chemical testing scope escalation and laboratory equipment investment cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Robotic Sample Preparation Deployment | Automated liquid handling from pharmaceutical QC migrates into footwear chemical testing, compressing turnaround from weeks to days. |
| Multi-Jurisdiction Accreditation Expansion | Simultaneous ASTM, EN, and GB certification captures athletic footwear destined for simultaneous EU and US market entry. |
| PFAS Protocol Development Investment | First-mover validation of alternative water-repellent chemistries captures regulatory deadline-driven demand from athletic brands. |
| India Laboratory Network Establishment | PLI scheme subsidies in Tamil Nadu and Uttar Pradesh generate new capacity requirements for chemical and mechanical validation. |
| Digital Twin Integration Partnership | Finite element modeling convergence with physical testing enables predictive durability simulation before prototype fabrication costs. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of regulatory filings, trade databases, and industry technical standards to construct segment-level demand estimates. Primary interviews engaged laboratory operations directors, athletic brand compliance managers, retailer procurement leads, and chromatography equipment specialists across Vietnam, China, Germany, and the United States. Secondary validation drew from ECHA restriction candidate list updates, ISO 17025 accreditation registries, SAMR GB standard enforcement records, and customs documentation from Vietnam's export manufacturing zones. Bottom-up facility capacity analysis triangulates against top-down market sizing from testing service procurement patterns.
Forecast inputs span service type segmentation across chemical, performance, mechanical, and durability testing workflows, end-user archetypes from manufacturers through retailer-mandated programs, and footwear category complexity tiers from safety shoes through multi-material athletic construction. CAGRs derive from laboratory capacity expansion trajectories, accreditation timeline modeling, and regulatory enforcement intensity assumptions across the projection horizon. Industry-specific inputs include REACH candidate list expansion velocity, factory consolidation rates in Vietnam's export corridor, and PFAS restriction deadline clustering effects.
Practitioners should monitor ECHA enforcement intensity, phthalate reference material supply bottlenecks, and ISO 17025 audit backlog durations for early signals requiring forecast revision. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Footwear
UK Lifestyle Sneakers Market
Footwear
Platform Boots Market
Footwear
Breathable Mesh Running Shoes Market
Footwear
GCC Footwear Market
Footwear
Sandals Market
Footwear
Water Shoes Market
Footwear
Driving Footwear Market
Footwear
Protective Footwear Market
Footwear
Footwear Manufacturing Machinery Market
Footwear
Womens Footwear Market
Footwear
Europe Barefoot Shoes Market
Footwear
Slip Resistant Shoes Market
Footwear
Luxury Footwear Market
Footwear
Refurbished Sneaker Market
Footwear
UGG Boots Market
Footwear
Flip Flops Market