
 Japan Telecom Towers Market | 2026-2036
Japan Telecom Towers Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Telecom Towers Market Insights
Market Context
The tower-to-operator distribution channel is narrowing as Japanese carriers consolidate vendor relationships around shared infrastructure models. NTT DOCOMO sustains its position through captive site ownership across rural Hokkaido and Tohoku corridors. SoftBank Corp. competes by leveraging JTower's neutral-host platforms in dense metropolitan zones. KDDI differentiates through submarine cable-tower convergence investments along coastal prefectures.
Technical Definition and Segments
Japan telecom towers are steel or composite structures engineered to support antenna arrays at heights of 30 to 100 meters, with wind-load ratings calibrated to the country's seismic and typhoon exposure. These structures enable radio frequency propagation for commercial and public-safety communications across mountainous terrain and dense urban canyons. Lattice towers dominate rural and mountainous deployments where structural resilience against seismic stress commands premium engineering specifications. 5G NR infrastructure represents the fastest-expanding technology segment, with micro-cell and small-cell attachments outpacing macro-tower additions in Tokyo and Osaka prefectures. Independent tower companies capture margin pools through long-term lease escalation clauses tied to carrier spectrum utilization rates.
Regulatory Framework
METI spectrum auctions and MIC infrastructure-sharing mandates compel carriers to pool passive infrastructure, reshaping ownership economics across the tower ecosystem. JIS standards for structural steel and earthquake-resistant foundation design govern construction specifications, with local municipal ordinances imposing additional setback and zoning requirements. Stakeholders must monitor MIC deliberations on 6G spectrum roadmaps and METI carbon-neutrality benchmarks for telecom infrastructure energy consumption.
Market Dynamics
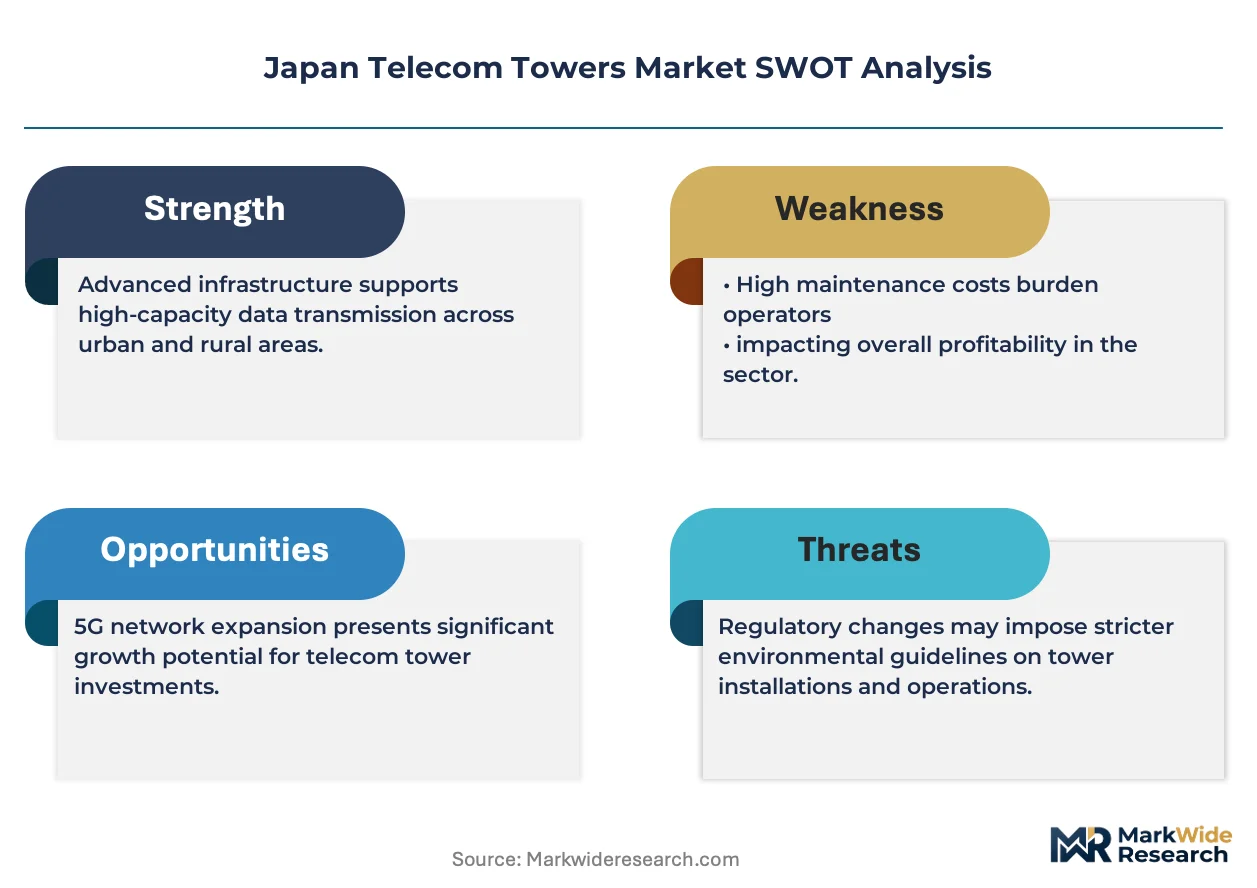
Japan's telecom tower sector is compressing around infrastructure-sharing mandates that force carriers to pool passive assets, eroding traditional site ownership economics and accelerating neutral-host penetration across metropolitan corridors.
Growth Catalysts
- METI spectrum allocation policies:Compressed carrier capex timelines are accelerating 5G densification deployments across Tokyo, Osaka, and Fukuoka prefectures. Operators must utilize allocated bands within mandated windows or face forfeiture.
- Urban micro-cell architectures:Dense metropolitan zones in Japan are driving demand for small-cell attachments that supplement macro-tower coverage in urban canyons where line-of-sight propagation fails.
- Seismic engineering standards:JIS-certified lattice towers command premium lease rates in rural Hokkaido and Tohoku corridors where earthquake-resistant foundations are non-negotiable for carrier insurance compliance.
Market Restraints
- Domestic steel price volatility:Structural steel input costs for lattice tower fabrication fluctuate with global commodity markets, compressing margins for tower constructors locked into long-term lease escalation clauses.
- Municipal zoning friction:Local ordinances in Tokyo and Osaka impose setback requirements and aesthetic restrictions that extend site acquisition timelines by twelve to eighteen months.
- Submarine cable substitution:KDDI's coastal convergence investments are displacing some tower-dependent backhaul requirements along Japan's Pacific seaboard prefectures.
Strategic Opportunities
- Rural Tohoku expansion:Underpenetrated mountainous terrain in northern Japan presents white space for shared infrastructure models where single-carrier economics previously failed.
- Open RAN convergence:Rakuten Mobile's virtualized architecture is hybridizing with neutral-host platforms to enable multi-tenant spectrum sharing without hardware duplication.
- MIC 6G roadmap positioning:Early engagement with Ministry deliberations on sub-terahertz spectrum allocation is securing preferred site access for next-generation infrastructure deployment.
Industry Challenges
- Seismic certification bottlenecks:JIS structural testing protocols for earthquake-resistant foundations create twelve-month approval queues that delay revenue recognition on completed tower construction.
- Legacy macro-tower integration:Retrofitting existing steel structures for 5G massive MIMO arrays requires structural reinforcement engineering that complicates lease renegotiations with incumbent carriers.
- Site acquisition talent scarcity:Municipal negotiation specialists with relationships across Tokyo's ward offices command compensation premiums that inflate SG&A for independent tower companies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Telecom Towers Market |
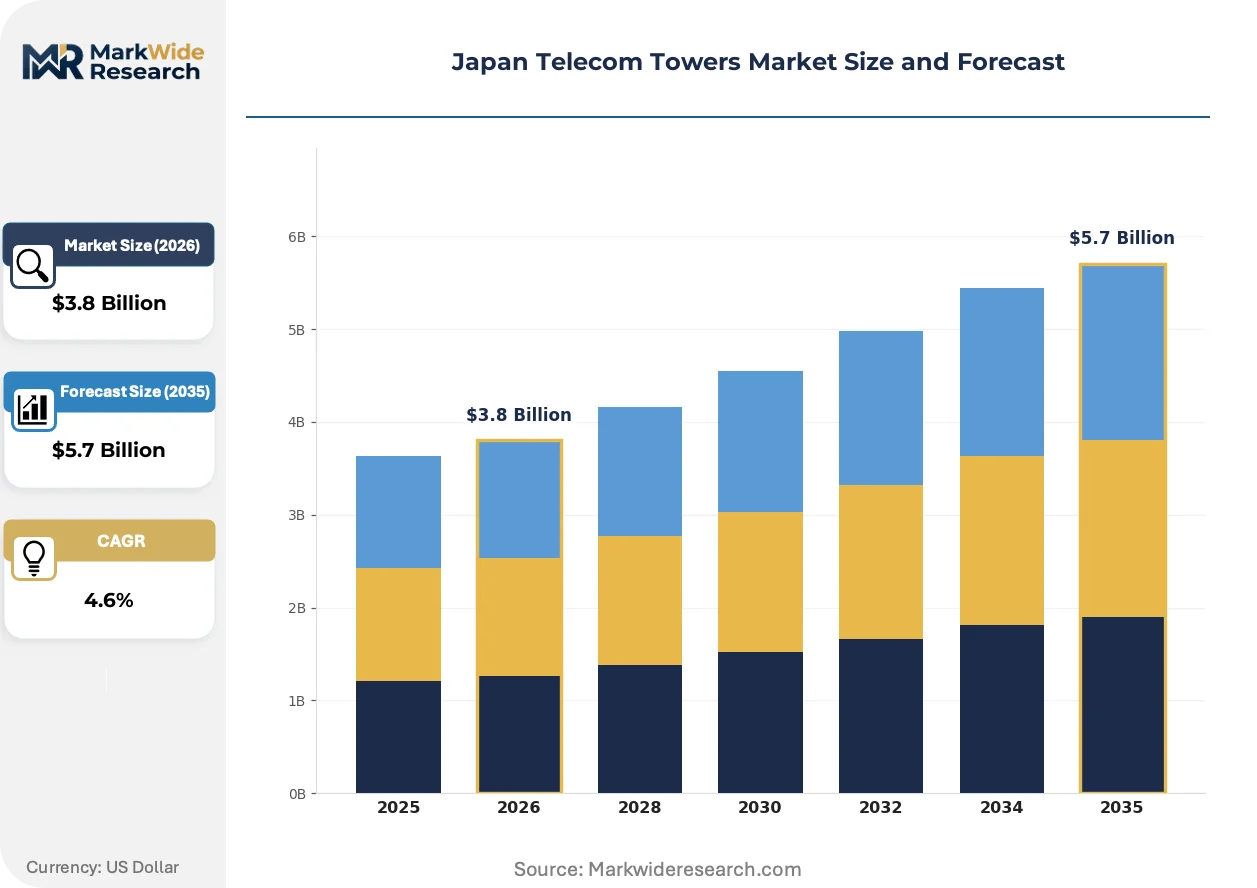
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Tower Type: Monopole, Lattice, Stealth, Guyed Technology: 4G LTE, 5G NR, Microwave, Wi-Fi Ownership Model: Independent, Carrier-Owned, Tower Company, Government Deployment Mode: Urban, Suburban, Rural, Indoor |
| Companies Covered | Rakuten Mobile, DigitalBridge, NTT DOCOMO, NTT, Macquarie, KDDI, JTower, Obayashi Corporation, SoftBank Corp., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Telecom Towers Market Trends and Innovations
Japan's tower ecosystem is pivoting from asset-heavy ownership models toward shared infrastructure architectures, with regulatory pressure and virtualization technology converging to reshape competitive positioning across urban and rural deployment zones.
Hybrid steel-composite tower materials are hybridizing traditional lattice construction with carbon-fiber reinforcement to reduce seismic mass while maintaining wind-load ratings. Japanese carriers are piloting these structures in typhoon-exposed coastal prefectures where foundation costs dominate project economics. The technology is hybridizing capex allocation between tower constructors and their carrier tenants, shifting structural risk onto neutral-host balance sheets.
METI carbon-neutrality benchmarks for telecom infrastructure energy consumption are compelling tower operators to integrate solar microgrids and battery storage into remote site designs. These mandates are accelerating diesel generator retirement across Hokkaido's rural corridors where grid connectivity remains unreliable. Mountainous deployments are most affected, with operators retrofitting existing lattice towers with photovoltaic arrays to avoid regulatory penalties.
Carrier procurement of tower access is consolidating around long-term lease escalation clauses tied to spectrum utilization rates rather than flat per-site fees. This model is displacing traditional per-tenant pricing in Tokyo and Osaka metropolitan zones where Rakuten Mobile's open RAN architecture enables rapid capacity scaling. The shift is most visible in dense urban prefectures where neutral-host platforms aggregate multiple carriers onto single structures.
Japan Telecom Towers Market Segmentation
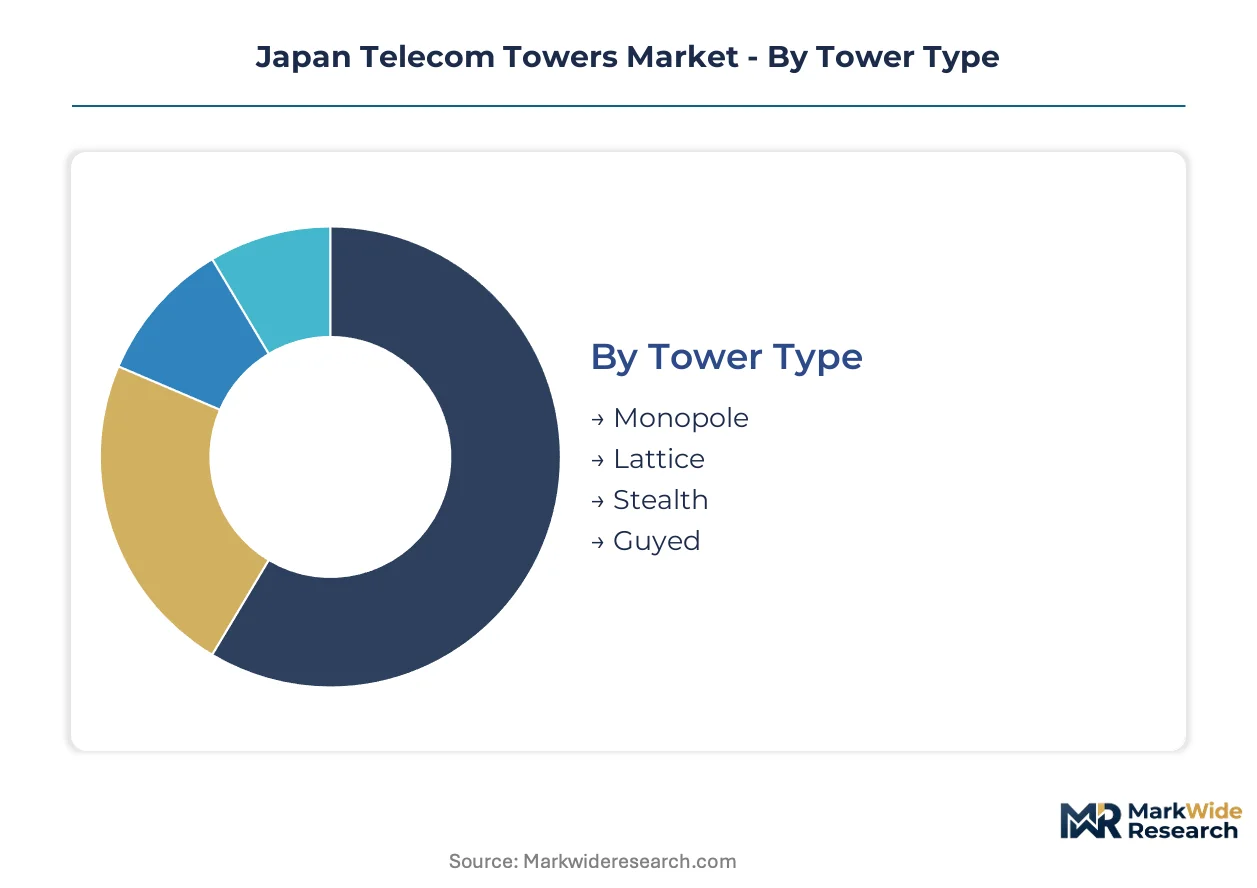
Japan's telecom tower segmentation reveals how regulatory mandates and seismic engineering requirements fragment procurement patterns across structural types and ownership models. Carrier consolidation around shared infrastructure compresses traditional category boundaries.
Tower Type:
Mature lattice designs dominate rural corridors where earthquake resilience commands premium specifications, while emerging stealth configurations penetrate dense urban wards with strict aesthetic codes.
- Monopole:Single-shaft steel structures engineered for minimal footprint in Tokyo and Osaka metropolitan zones where municipal setback restrictions limit lattice deployment. Demand concentrates in Shibuya and Minato wards where visual impact regulations from local ordinances extend site acquisition timelines.
- Lattice:Triangular or square-section steel frameworks with redundant bracing calibrated to JIS seismic load standards for Hokkaido and Tohoku earthquake zones. Rural carriers in Aomori and Iwate prefectures prioritize these structures for insurance compliance against foundation failure during seismic events.
- Stealth:Architecturally disguised structures mimicking building elements or vegetation to satisfy Tokyo's landscape ordinances in historic districts.
- Guyed:Tension-supported masts deployed in remote mountainous terrain where transport costs prohibit lattice assembly.
Lattice handles the majority of throughput across northern prefectures; stealth configurations are gaining share fastest in Tokyo's 23 special wards.
Technology:
Cost tier stratification separates legacy 4G infrastructure from premium 5G deployments, with microwave backhaul occupying a mid-tier position for coastal convergence strategies.
- 4G LTE:Macro-cell radio equipment on existing steel structures across rural Shikoku and Kyushu islands where carrier capex prioritizes coverage maintenance over capacity expansion. Prefectural governments in Ehime and Kagoshima extend 4G lease terms to avoid stranded asset write-downs.
- 5G NR:Massive MIMO antenna arrays and millimeter-wave small cells driving micro-cell densification in Tokyo, Osaka, and Fukuoka prefectures. Rakuten Mobile's open RAN architecture enables rapid spectrum refarming in dense urban corridors where METI utilization mandates compress deployment windows.
- Microwave:Point-to-point transmission links for submarine cable-tower convergence along Pacific coastal prefectures.
- Wi-Fi:Neutral-host offload infrastructure in indoor commercial venues and transportation hubs.
5G NR infrastructure captures the steepest expansion trajectory; 4G LTE retains volume leadership in western prefectures.
Ownership Model:
Volume concentration favors carrier-captive assets, while margin pools shift toward independent platforms as MIC sharing mandates erode traditional site economics.
- Independent:Neutral-host tower companies aggregating multi-tenant access through long-term lease escalation clauses tied to spectrum utilization rates. JTower's metropolitan platforms in Tokyo and Osaka enable SoftBank and KDDI to share passive infrastructure without hardware duplication.
- Carrier-Owned:Captive site portfolios maintained by NTT DOCOMO across rural Hokkaido and Tohoku corridors where single-carrier economics previously justified proprietary construction. These assets face stranded value risk as MIC pooling mandates expand.
- Tower Company:Dedicated infrastructure specialists with balance-sheet capacity for seismic-certified new builds.
- Government:Public-safety and disaster-reserve structures maintained by prefectural authorities.
Carrier-owned sites still dominate rural prefecture counts; independent platforms are climbing the fastest in metropolitan lease revenue.
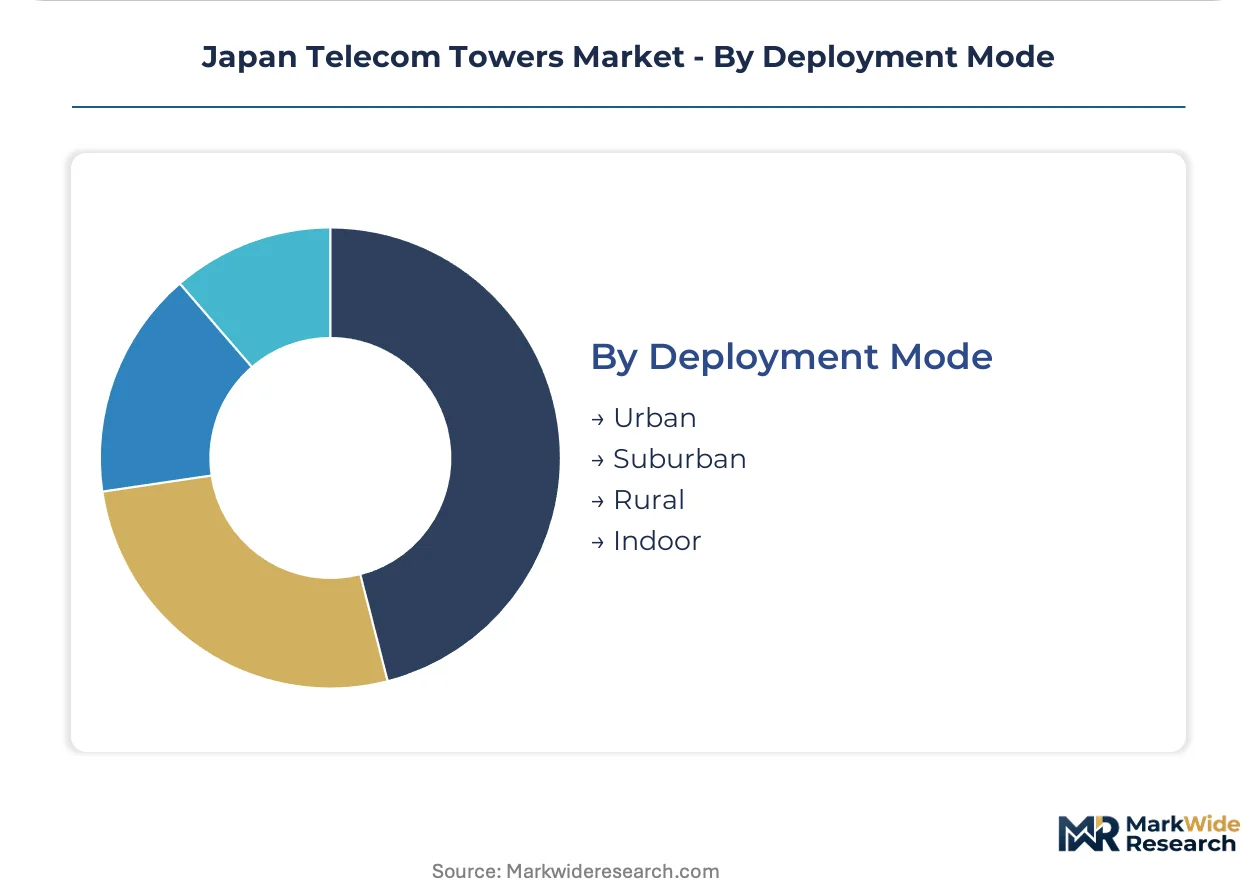
Deployment Mode:
Geography-driven segmentation separates high-capex urban micro-cells from low-density rural macro-towers, with indoor venues emerging as a distinct procurement category.
- Urban:Dense small-cell grids and rooftop macro installations across Tokyo's 23 wards and Osaka's Kita and Chuo wards where line-of-sight propagation fails in concrete canyons. Municipal zoning friction from setback requirements extends site acquisition timelines by twelve to eighteen months.
- Rural:Macro-tower coverage extensions across underpenetrated mountainous terrain in northern Tohoku where shared infrastructure models displace single-carrier economics. Akita and Yamagata prefectures present white space for neutral-host penetration.
- Suburban:Transition-zone deployments balancing coverage radius with capacity density in Saitama and Chiba prefectures.
- Indoor:Distributed antenna systems for commercial venues, stadiums, and subway infrastructure.
Urban deployments generate the majority of lease revenue; rural configurations are expanding most quickly as MIC mandates unlock shared economics in previously marginal territories.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Pacific fiber-optic cable landings at Shima and Chikura anchor Kanto's dominance in Japan's telecom tower ecosystem, underwriting Tokyo's position as the primary aggregation point for 5G infrastructure investment.
Kanto/Tokyo
Shibuya and Minato wards drive micro-cell densification for Rakuten Mobile's open RAN deployment. METI spectrum utilization mandates compress carrier deployment windows to avoid forfeiture. The Tokyo Bay corridor concentrates neutral-host platforms where JTower aggregates SoftBank and KDDI tenancy.
Kansai/Osaka
Osaka's Kita and Chuo wards face acute line-of-sight propagation failures in concrete canyons, accelerating small-cell attachment demand. MIC infrastructure-sharing mandates erode single-carrier site economics in these dense urban zones. The Osaka Station district hosts converged fiber-tower backhaul nodes for submarine cable convergence.
Hokkaido
Rural coverage extensions across Aomori and Iwate prefectures prioritize JIS-certified lattice towers for seismic insurance compliance. METI carbon-neutrality benchmarks compel diesel generator retirement through solar microgrid integration. The Doo coastal plain presents white space for shared infrastructure models displacing legacy NTT DOCOMO captive ownership.
Kyushu
Fukuoka prefecture anchors 5G densification alongside Tokyo and Osaka under compressed METI capex timelines. Municipal zoning friction in Fukuoka City extends site acquisition timelines through setback requirements. The Kitakyushu industrial corridor hosts steel-composite tower pilots for typhoon-resistant coastal deployment.
Tohoku
Mountainous terrain in Akita and Yamagata prefectures presents underpenetrated white space for neutral-host penetration. JIS structural testing protocols create twelve-month seismic certification queues delaying revenue recognition. The Sendai metropolitan zone balances suburban transition deployments between coverage radius and capacity density requirements.
Japan Telecom Towers Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in structural fabrication and foundation engineering. The vendor base compresses around infrastructure-sharing mandates that privilege neutral-host balance sheets over carrier-captive ownership. Three archetypes dominate: telecommunications carriers with captive site portfolios, independent tower companies aggregating multi-tenant access, and construction conglomerates with seismic engineering certification. Competitive moves concentrate on strategic partnerships for shared infrastructure deployment and portfolio diversification into carbon-neutral site energy systems.
Among Japan-based carriers, NTT DOCOMO, KDDI, and SoftBank Corp. exemplify the captive-to-shared transition archetype, each repositioning rural Hokkaido and Tohoku assets against MIC pooling mandates while leasing metropolitan capacity from independent platforms. JTower occupies the neutral-host specialist tier, aggregating tenancy across Tokyo and Osaka metropolitan zones through long-term lease escalation structures. Rakuten Mobile represents the virtualized challenger archetype, hybridizing open RAN architecture with neutral-host site access to bypass legacy hardware duplication.
| Leading Market Players |
|---|
| Rakuten Mobile |
| DigitalBridge |
| NTT DOCOMO |
| NTT |
| Macquarie |
| KDDI |
| JTower |
| Obayashi Corporation |
| SoftBank Corp. |
| Others |
Pricing and Supply Chain Analysis
Domestic steel price volatility determines both pricing tier spreads and supply chain shape across Japan's telecom tower sector, compressing margins for lattice tower fabricators locked into long-term lease escalation clauses while forcing carrier procurement toward neutral-host platforms that aggregate seismic certification costs across multiple tenants.
Pricing Analysis
Volume-discount tiering structures dominate carrier procurement, with JIS-certified seismic foundations commanding premium lease rates against standard-grade monopole deployments in metropolitan zones. Price differentiation rests on earthquake-resistance certification grade and multi-tenant aggregation scale. Cost compression in rural lattice segments is intensifying because domestic steel input fluctuations erode constructor margins. Municipal tower companies exhibit highest price sensitivity; NTT DOCOMO's captive rural portfolios show lowest sensitivity due to insurance compliance non-negotiability.
Supply Chain Analysis
Export-control regime angles from allied semiconductor restrictions limit 5G massive MIMO component flows into Japanese carrier supply chains. Geographic supply concentration centers on domestic steel mills for lattice fabrication, South Korean foundries for RF componentry, and Chinese manufacturers for photovoltaic microgrid equipment. Raw material dependencies include structural steel, carbon-fiber composite reinforcement, and battery storage systems. Single-source vulnerability sits with JIS-certified foundation engineering capacity. Distribution runs through neutral-host platforms that consolidate multi-tenant access.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity emerges across Japan's telecom tower landscape as MIC infrastructure-sharing mandates carve niches for specialized seismic engineering providers and rural neutral-host platforms that displace single-carrier economics in previously marginal territories.
For Market Incumbents: Build regulatory compliance moats through preemptive JIS certification expansion across Tohoku's underpenetrated mountainous corridors. Threat from Rakuten Mobile's virtualized open RAN architecture demands captive site portfolio rationalization. Lever vertical integration into solar microgrid installation capacity to capture METI carbon-neutrality mandate premiums. For New Entrants and Emerging Players: Establish a beachhead in Akita and Yamagata prefectures where shared infrastructure models unlock economics that previously failed single-carrier deployment. Rural Tohoku presents the most penetrable geography. Go-to-market angle centers on municipal relationship networks that compress twelve-month site acquisition timelines. For Investors and Strategic Acquirers: The market sits at a regulatory inflection phase that favors neutral-host balance sheets over carrier-captive ownership. Long-term viability favors platforms with multi-tenant aggregation capacity and seismic engineering certification depth. Target acquisition archetype: independent tower companies with JIS-approved foundation testing protocols. Signal to watch: MIC deliberation outcomes on 6G spectrum roadmaps that reset site access priorities.| Strategic Initiative | Industry Significance |
|---|---|
| JIS Certification Expansion | Seismic foundation approval queues create twelve-month bottlenecks that certified providers exploit for lease premiums. |
| Solar Microgrid Integration | METI carbon-neutrality benchmarks compel diesel generator retirement across Hokkaido's unreliable grid corridors. |
| Neutral-Host Platform Scaling | JTower's metropolitan aggregation model enables SoftBank and KDDI tenancy without hardware duplication costs. |
| Open RAN Architecture Convergence | Rakuten Mobile's virtualized deployment hybridizes with neutral-host access to bypass legacy infrastructure. |
| Rural Tohoku Site Acquisition | MIC pooling mandates unlock shared economics in Akita and Yamagata where single-carrier models previously failed. |
Research Methodology
Operator-level perspectives from NTT DOCOMO network planning executives, JTower infrastructure leasing managers, SoftBank procurement leads, and KDDI submarine convergence specialists anchored the qualitative base. Primary interview findings triangulated against secondary validation from MIC spectrum allocation records, METI infrastructure energy consumption benchmarks, JIS structural steel certification databases, and municipal zoning ordinance filings across Tokyo's 23 wards. Bottom-up tower deployment counts and top-down carrier capex disclosures were reconciled to establish market sizing boundaries.
Scenario-bracketing framed the analytical approach across the analysis window, with segmentation dimensions spanning tower type, ownership model, deployment mode, and technology generation. CAGRs were derived from carrier spectrum utilization mandate timelines and neutral-host lease escalation trajectories. Industry-specific forecast inputs incorporated seismic certification approval queue durations and domestic steel price volatility indices.
Macroeconomic conditions sit as an overlay; deviation in yen-denominated steel input costs and METI enforcement intensity on carbon-neutrality benchmarks would shift the trajectory. Forecasts reflect documented assumptions regarding MIC infrastructure-sharing mandate expansion pace and JIS testing protocol efficiency. Cross-checking against carrier-reported tower lease expense disclosures is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telecommunications Infrastructure
Colombia Telecom Tower Market
Telecommunications Infrastructure
5G Infrastructure Equipment Market
Telecommunications Infrastructure
NLD and ILD Telecom Service Market
Telecommunications Infrastructure
Telecom Network Infrastructure Market
Telecommunications Infrastructure
Saudi Arabia Telecom Towers Market
Telecommunications Infrastructure
Global Telecom Cable Market
Telecommunications Infrastructure
Europe 5G Infrastructure Market
Telecommunications Infrastructure
Broadcast Infrastructure Market
Telecommunications Infrastructure
Germany Telecom Towers Market
Telecommunications Infrastructure
Brazil Telecom Tower Market
Telecommunications Infrastructure
5G Network Infrastructure Market
Telecommunications Infrastructure
Fiber to the X (FTTX) Market
Telecommunications Infrastructure
5G Infrastructure Market
Telecommunications Infrastructure
Global Telecom Towers Market
Telecommunications Infrastructure
Panama Telecom Market
Telecommunications Infrastructure
Canada Telecom Towers Market