
 Canada Telecom Towers Market | 2026-2036
Canada Telecom Towers Market Size, Share, and Industry Trends Forecast 2026-2036
Canada Telecom Towers Market Insights
Canada is fragmenting its telecom tower build-out across provincial jurisdictions with uneven terrain and regulatory timelines. Bell Canada leverages its incumbent wireline footprint to co-locate wireless infrastructure and reduce greenfield deployment costs. Rogers Communications anchors its strategy in Ontario and British Columbia through dense urban macro sites and strategic rural infill. TELUS Corporation differentiates via aggressive western Canada expansion and shared tower economics with regional carriers.
Canada telecom towers are steel or concrete structures engineered to support multiple antenna arrays, transmission lines, and auxiliary equipment at elevations typically ranging from 15 to 120 metres, designed to ensure line-of-sight propagation for wireless signals across varied topography. These structures serve as the physical backbone for mobile voice, data, and emergency communication services across Canada's vast geography. Lattice towers dominate the tall-structure segment for rural and remote coverage where wind load and ice accretion demand structural redundancy. Monopole installations lead urban and suburban deployments where aesthetic constraints and limited footprint favour slim profiles. Rooftop mounting concentrates in downtown Toronto, Vancouver, and Montreal where ground space scarcity pushes carriers to leverage existing commercial real estate.
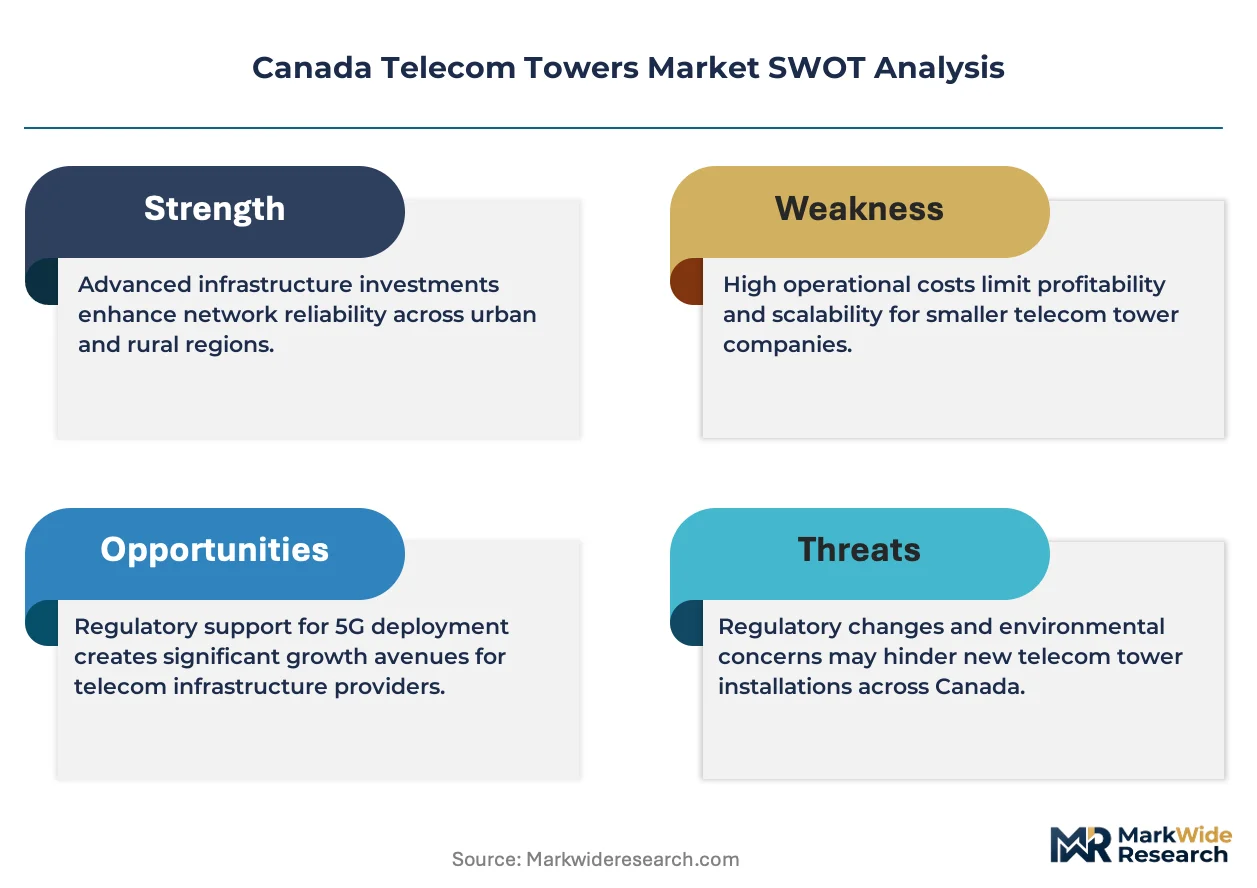
Health Canada sets radiofrequency electromagnetic field exposure limits under Safety Code 6, directly influencing tower siting distances and public consultation requirements that extend deployment timelines. Industry Canada (ISED) manages spectrum allocation and antenna structure registration, creating compliance layers that shape capital planning for carriers and tower companies. Provincial environmental assessment processes add jurisdiction-specific permitting hurdles, particularly in ecologically sensitive northern regions. Stakeholders must monitor how municipal zoning reforms and First Nations consultation protocols evolve to determine build-out feasibility and partnership structures.
Market Dynamics
5G mid-band densification is compressing tower spacing requirements across Canadian provinces, forcing carriers to triple site counts while halving per-site coverage radius compared to legacy LTE macro planning.
Growth Catalysts
- ISED Spectrum Auctions:Industry Canada releases 3.5 GHz and 26 GHz bands with rural deployment mandates attached, compelling carriers to build in underserved northern corridors.
- Fixed Wireless Access:Internet Service Providers deploy 5G CPE to bypass fiber trenching costs in remote Alberta and Saskatchewan communities.
- Ice Loading Standards:CSA S37 structural codes for extreme wind and ice accretion enable taller lattice towers in Atlantic provinces where coastal storms exceed continental load assumptions.
Market Restraints
- Steel Price Volatility:Hot-rolled structural sections fluctuate with scrap metal and energy input costs, squeezing fabrication margins for tower manufacturers.
- First Nations Consultation:Duty-to-consult protocols in British Columbia and northern territories extend permitting timelines by 18-36 months for greenfield sites.
- Monopole Height Limits:Municipal aesthetic bylaws in Vancouver and Toronto cap structures at 30 metres, forcing expensive stealth designs or rooftop alternatives.
Strategic Opportunities
- Northern Infrastructure Gap:Nunavut and Northwest Territories lack terrestrial backhaul, creating demand for satellite-tower hybrid sites with diesel-solar hybrid power.
- Shared Tower Economics:Multi-tenant arrangements reduce per-carrier capex by 40-60% in low-density rural markets where single-tenant economics fail.
- Green Bond Financing:Sustainability-linked debt instruments reward tower companies for renewable energy integration at off-grid remote sites.
Industry Challenges
- RF Engineer Shortage:Specialized talent for microwave path analysis and Safety Code 6 compliance planning is concentrated in Toronto and Calgary, creating recruitment bottlenecks for prairie and maritime deployments.
- Legacy Co-location:3G and LTE antenna arrays occupy prime mounting positions, forcing costly structural reinforcement or full tower replacement to accommodate 5G massive MIMO panels.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canada Telecom Towers Market |
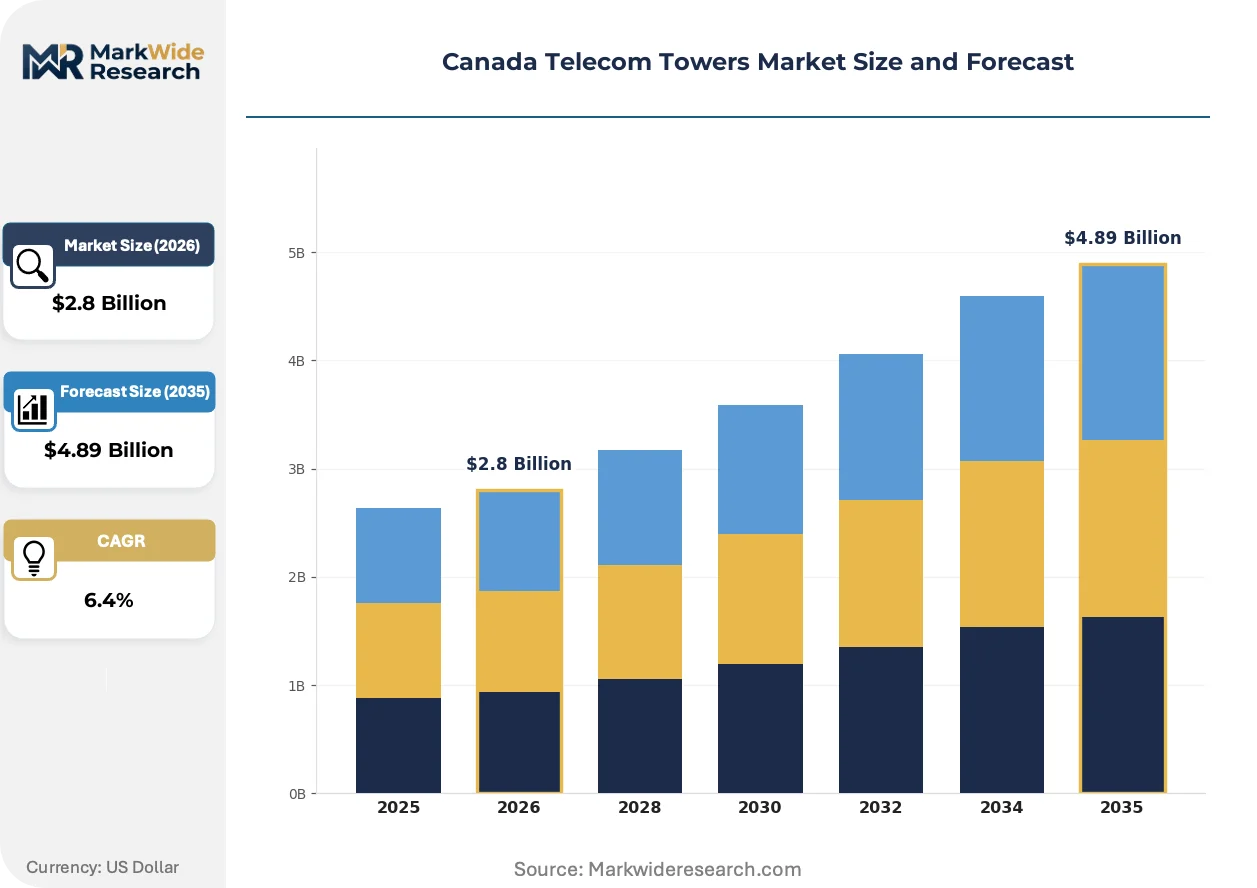
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.89 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Structure Type: Monopole, Lattice, Stealth, Rooftop Height Category: Low, Medium, Tall, Extra Tall End User: Mobile Network Operators, Internet Service Providers, Broadcasting Companies, Government Agencies Installation Type: Ground Mounted, Roof Mounted, Pole Mounted, Others |
| Companies Covered | Bell Canada, Rogers Communications, TELUS Corporation, Quebecor, Videotron, Freedom Mobile, SaskTel, American Tower Corporation, Cellcom Communications, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canada Telecom Towers Market Trends and Innovations
Open RAN architectures are decoupling hardware from software at the baseband layer, enabling tower operators to host multiple vendor radio heads on shared infrastructure without proprietary lock-in.
Virtualized RAN (vRAN) software is virtualizing baseband processing functions onto commercial servers, allowing carriers to centralize compute pools and reduce equipment shelter footprints at tower bases. Rural deployments in Manitoba and eastern Ontario adopt this first to minimize on-site power and cooling loads. The shift is compressing traditional vendor equipment margins while opening tower real estate to edge computing colocation.
Health Canada's Safety Code 6 revision process is tightening radiofrequency exposure limits in residential zones, forcing carriers to extend setback distances or deploy lower-power small cells. Municipal councils in Ottawa and Halifax cite these guidelines to reject macro tower proposals near schools and hospitals. Tower companies respond with distributed antenna systems and concealed pole designs that blend into streetscape infrastructure.
Carrier procurement teams now bundle tower access with fiber backhaul and power in single master service agreements, displacing the historic model of separate tower, transport, and energy contracts. This consolidation favors vertically integrated infrastructure providers with owned fiber and electrical utility relationships. The pattern is most pronounced in Quebec where Hydro-Québec's grid access creates bundled power-communications offerings.
Canada Telecom Towers Market Segmentation
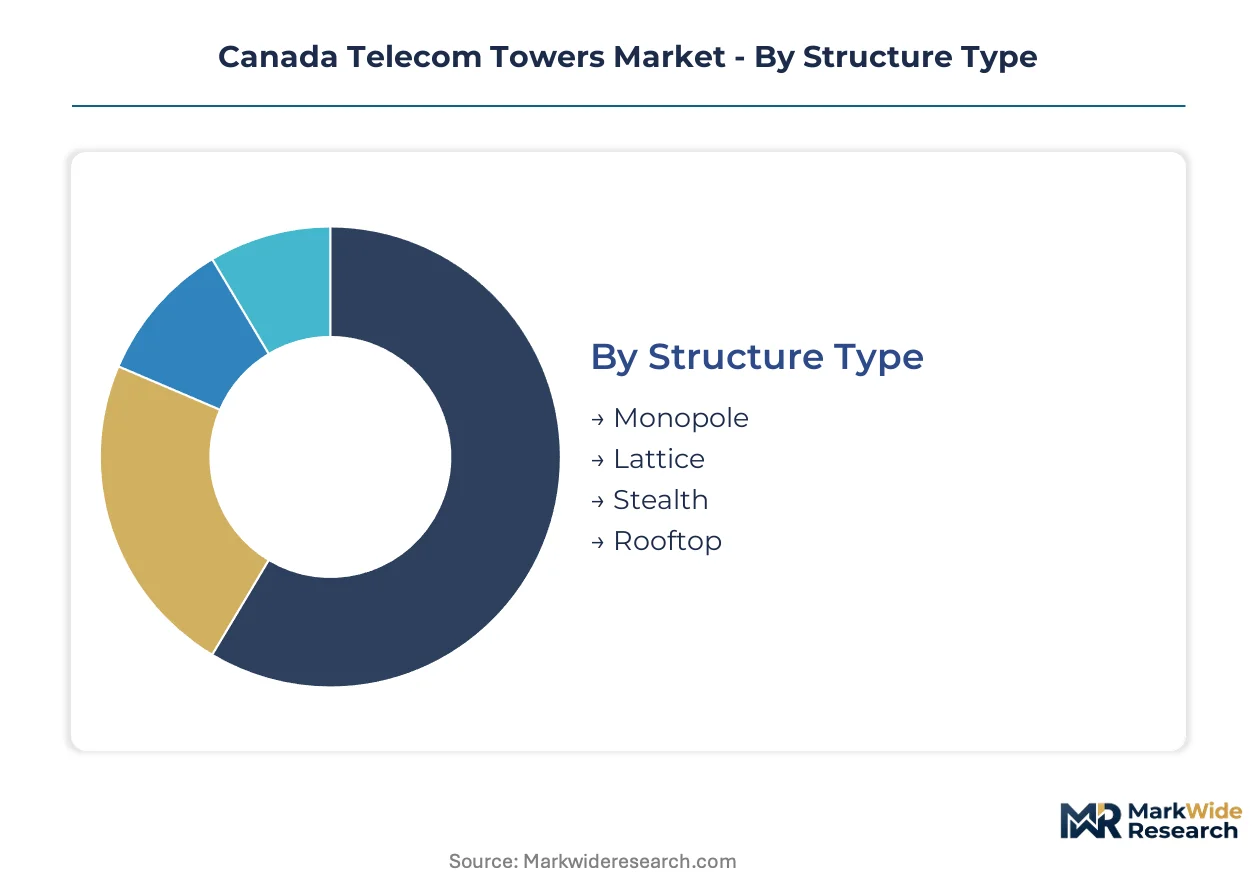
Canada's telecom tower segmentation reflects the tension between aesthetic constraints in dense urban cores and structural resilience demands across remote northern terrain. Structure type and height category decisions cascade through permitting timelines, capital intensity, and carrier co-location economics.
Structure Type:
Lattice towers turn over slowest due to 25-30 year structural lifespans and rural deployment cycles, while stealth designs refresh fastest as municipal bylaws tighten.
- Monopole:Single-pole steel or concrete structures with diameters tapering from 2-3 metres at the base. Demand concentrates in Vancouver and Toronto suburbs where municipal height caps at 30 metres force slim profiles. Health Canada Safety Code 6 setback calculations favour monopoles for residential adjacency.
- Lattice:Triangular or square truss configurations built from angled steel members. Ontario and Quebec rural corridors anchor demand where wind and ice loading exceed monopole engineering limits. CSA S37 codes mandate lattice for structures exceeding 60 metres.
- Stealth:Concealed designs mimicking flagpoles, church steeples, or architectural features. Ottawa and Halifax councils drive uptake near schools and hospitals.
- Rooftop:Antenna arrays mounted on commercial and residential buildings. Downtown Toronto and Montreal density pushes carrier preference for existing real estate over greenfield towers.
Lattice anchors the volume base while stealth gains share at the steepest rate.
Height Category:
Cost tier stratification separates capital-heavy tall structures from rapid-deploy low-height alternatives.
- Low:Structures under 15 metres including small cells and distributed antenna systems. Urban infill in Calgary and Edmonton drives replacement cycles as 5G densification compresses site spacing.
- Medium:15-45 metre configurations serving suburban macro coverage. Bell Canada and TELUS standardize here for Ontario-Quebec corridor overlap.
- Tall:45-90 metre towers spanning rural coverage gaps. Prairie provinces and Atlantic Canada anchor demand where terrain undulation demands elevation.
- Extra Tall:Structures exceeding 90 metres for remote northern coverage. Nunavut and Northwest Territories deployment requires diesel-solar hybrid power and satellite backhaul integration.
Medium-height structures dominate capital deployment while extra tall climbs fastest on northern infrastructure mandates.
End User:
Customer type determines contract duration and co-location intensity.
- Mobile Network Operators:Bell, Rogers, and TELUS drive 10-15 year master lease agreements with 3-4 carriers per tower average. 5G massive MIMO upgrades are forcing structural reinforcements at legacy sites.
- Internet Service Providers:Rural broadband specialists including Xplore and Videotron deploy fixed wireless access to bypass fiber trenching. Federal connectivity subsidies accelerate prairie and maritime build-outs.
- Broadcasting Companies:CBC and private radio operators maintain legacy AM/FM transmission with minimal new tower demand.
- Government Agencies:Public Safety Canada and provincial emergency management units require hardened structures for first responder networks.
Mobile operators anchor tenancy revenue while Internet Service Providers expand most quickly on rural connectivity programs.
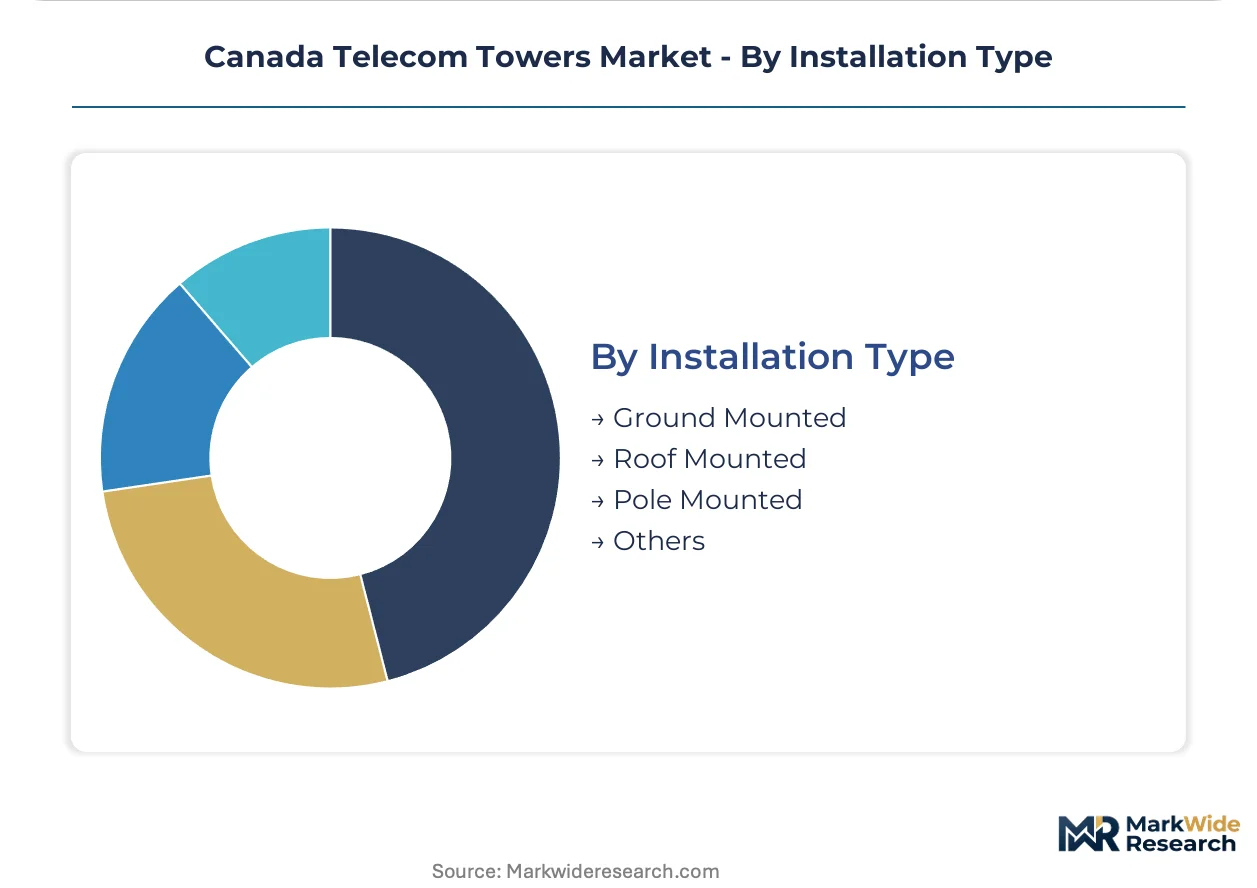
Installation Type:
Volume concentration tracks geography and real estate availability.
- Ground Mounted:Standard tower foundations with concrete caissons or grillage bases. Rural Ontario and Quebec agricultural land offers lowest site acquisition costs.
- Roof Mounted:Equipment platforms on commercial buildings and high-rise residential. Vancouver and Toronto zoning scarcity pushes carriers upward.
- Pole Mounted:Streetlight and utility pole attachments for small cell densification. Municipal street furniture agreements in Montreal and Calgary standardize deployments.
- Others:Includes wall-mounted and temporary trailer-based installations for emergency coverage and construction sites.
Ground mounted retains the largest installed base while pole mounted expands fastest on 5G mid-band densification timelines.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Tower deployment concentrates in southern provinces where population density and backhaul infrastructure overlap. Northern territories require satellite-dependent hybrid architectures with diesel-solar power systems.
Ontario
Toronto and Ottawa anchor 5G mid-band densification with pole-mounted small cells proliferating along municipal street furniture. Health Canada Safety Code 6 compliance drives setback negotiations in residential zones. The Greater Toronto Area hosts the densest rooftop mounting concentration as ground space scarcity pushes carriers upward.
Quebec
Bell Canada and Videotron expand fixed wireless access across rural corridors to bypass fiber trenching costs. Hydro-Québec grid access enables bundled power-communications offerings that reduce operational complexity. Montreal's aesthetic bylaws cap structures at 30 metres, forcing stealth designs near schools and hospitals.
British Columbia
First Nations consultation protocols extend permitting timelines by 18-36 months for greenfield sites in coastal and northern regions. Rogers Communications anchors its western strategy through dense urban macro sites in Vancouver and strategic rural infill. The province's mountainous terrain demands taller lattice configurations for line-of-sight propagation.
Alberta
Fixed wireless access deployment accelerates across prairie communities as ISPs leverage federal connectivity subsidies. TELUS Corporation differentiates via aggressive western expansion and shared tower economics with regional carriers. Calgary and Edmonton drive urban infill with low-height small cell replacements as 5G densification compresses site spacing.
Atlantic Canada
CSA S37 structural codes for extreme wind and ice accretion enable taller lattice towers in coastal provinces where storms exceed continental load assumptions. Xplore and rural broadband specialists deploy towers across agricultural land with lowest site acquisition costs. Nova Scotia and New Brunswick anchor maritime deployment as federal programs close connectivity gaps.
Canada Telecom Towers Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream with structural fabrication and power systems. The Canadian market structures around three archetypes: incumbent mobile network operators with captive tower portfolios, independent tower companies leasing multi-tenant space, and regional carriers pooling infrastructure via shared economics. Dominant competitive moves include vertical integration of fiber backhaul with tower access and strategic partnerships with provincial utilities for bundled power offerings.
Among incumbent operators with integrated infrastructure, Bell Canada exemplifies the platform-integrator archetype through wireline-wireless convergence. Rogers Communications and TELUS Corporation represent competing national-scale strategies, with the former concentrating in Ontario and British Columbia while the latter anchors western expansion. American Tower Corporation sits within the independent tower company tier, offering multi-tenant economics that reduce per-carrier capex in low-density rural markets where single-tenant deployments fail.
| Leading Market Players |
|---|
| Bell Canada |
| Rogers Communications |
| TELUS Corporation |
| Quebecor |
| Videotron |
| Freedom Mobile |
| SaskTel |
| American Tower Corporation |
| Cellcom Communications |
| Others |
Pricing and Supply Chain Analysis
Ontario's Hamilton-Niagara steel fabrication cluster anchors structural tower manufacturing capacity, with hot-rolled section availability directly influencing downstream pricing power for lattice and monopole configurations. Health Canada Safety Code 6 compliance costs and CSA S37 certification requirements cascade through contract negotiations, compressing margins for non-integrated fabricators while rewarding captive steel sourcing.
Pricing Analysis
Health Canada Safety Code 6 dictates the pricing tier structure across installation categories, separating certified high-elevation rural towers from standard suburban monopoles. Three-tier pricing structure across premium, standard, and economy levels reflects structural load ratings, ice accretion engineering, and after-sales maintenance bundling. Price erosion runs through economy-tier rooftop mounting as municipal bylaws restrict new ground builds. Internet Service Providers exhibit highest price sensitivity due to federal subsidy dependency, while Mobile Network Operators absorb premium tier costs for 5G massive MIMO compatibility.
Supply Chain Analysis
Valmont Industries and Sabre Industries hold contract-manufacturing concentration for lattice tower sections, with regional Canadian fabricators supplying monopole and stealth structures. Steel sourcing draws from Ontario domestic mills and U.S. Midwest producers, while aluminum extrusions and galvanized coatings feed from Quebec and Michigan suppliers. Single-source vulnerability concentrates in specialized RF antenna arrays from Nordic and U.S. vendors. Distribution runs through carrier procurement consortiums and tower company master service agreements, with direct-to-site logistics for remote northern deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Open RAN interoperability is reshaping tower economics from proprietary single-vendor lock-in toward multi-tenant infrastructure platforms, creating ecosystem-level value capture opportunities.
For Market Incumbents: Insulate tenancy revenue through fiber backhaul vertical integration and long-term power purchase agreements with provincial utilities. Bell Canada and Rogers Communications should reinforce structural load capacity at legacy sites ahead of 5G massive MIMO retrofits, as antenna weight increases threaten co-location density. Locking municipal street furniture agreements in Toronto and Vancouver creates defensive moats against pole-mounted small cell entrants. For New Entrants and Emerging Players: Northern territories underpenetration offers white-space expansion for satellite-tower hybrid architectures with diesel-solar power systems. Nunavut and Northwest Territories lack terrestrial backhaul infrastructure, creating demand for turnkey remote site deployment. Target First Nations partnership structures in British Columbia to bypass extended consultation timelines that burden incumbent greenfield permitting. For Investors and Strategic Acquirers: Long-term, this sits as a regulated utility play because tower cash flows exhibit infrastructure-like stability under multi-tenant lease structures. Acquisition focus should center on independent tower companies with established carrier relationships and owned fiber assets. Watch ISED spectrum auction rural deployment mandates as the signal for accelerated northern capital deployment.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Tenant Tower Sharing Agreements | Reduces per-carrier capex by 40-60% in low-density rural markets where single-tenant economics fail. |
| Fiber Backhaul Integration | Bell Canada bundles transport and tower access, displacing separate contracts and locking carrier relationships. |
| Stealth Design Certification | Ottawa and Halifax municipal councils mandate concealed structures near schools, creating premium service tier. |
| Renewable Energy Microgrids | Green bond financing rewards diesel-solar hybrid power at off-grid Nunavut and Northwest Territories sites. |
| First Nations Partnership Protocols | British Columbia consultation requirements extend timelines 18-36 months, favoring early relationship investment. |
Research Methodology
The analysis maps lattice, monopole, stealth, and rooftop structure segments, each validated through RF engineering directors, carrier procurement executives, tower company lease administrators, and municipal zoning officers. Primary interviews with ISED spectrum planners and Health Canada Safety Code 6 compliance specialists cross-reference against Industry Canada antenna structure registrations, CSA S37 technical standards, provincial environmental assessment filings, and carrier capex disclosure reports. Bottom-up site deployment modeling triangulates with top-down infrastructure investment tracking.
Assumptions hold ISED spectrum auction rural mandates, Health Canada radiofrequency exposure limits, and provincial permitting timelines constant across the projection horizon. Segmentation models structure type, height category, end user, and installation type dimensions with regional deployment intensity variations. CAGRs derive from carrier-reported site counts, tower company tenancy ratios, and federal connectivity subsidy allocation trajectories. Forecast inputs incorporate steel price volatility bands and First Nations consultation duration distributions.
The forecast holds incumbent behavior within observed patterns; aggressive moves by satellite broadband providers or municipal fiber overbuilders would shift outcomes. Quarterly review of ISED auction announcements, CSA code revision proposals, and provincial zoning reform legislation is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telecommunications Infrastructure
United Kingdom Telecom Towers Market
Telecommunications Infrastructure
Carrier Infrastructure in Telecom Applications Market
Telecommunications Infrastructure
UAE Telecom Towers Market
Telecommunications Infrastructure
South Korea Telecom Tower Market
Telecommunications Infrastructure
Vietnam Telecom Towers Market
Telecommunications Infrastructure
Mexico Telecom Tower Market
Telecommunications Infrastructure
Europe 5G Infrastructure Market
Telecommunications Infrastructure
Asia Pacific Voice Over LTE Market
Telecommunications Infrastructure
Israel Telecom Market
Telecommunications Infrastructure
Global Mobile and Wireless Backhaul Equipment Market
Telecommunications Infrastructure
Iraq Telecom Market
Telecommunications Infrastructure
Fixed Telephony Service Market
Telecommunications Infrastructure
China Telecom Equipment Market
Telecommunications Infrastructure
Nepal Telecom Market
Telecommunications Infrastructure
Microwave Backhaul System Market
Telecommunications Infrastructure
Terrestrial Trunked Radio (TETRA) System Market