
 Cattle Farm Equipment Market | 2026-2036
Cattle Farm Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Cattle Farm Equipment Market Outlook
Dealer and co-op distribution networks across the North American Midwest is reshaping how cattle farm equipment reaches end users. John Deere leverages its integrated precision agriculture platform to extend influence from crop systems into livestock operations. AGCO Corporation anchors its position through specialized hay and forage equipment lines that serve mixed crop-livestock producers. DeLaval competes aggressively in automated milking systems, controlling premium technology segments in dairy-heavy regions.
Cattle farm equipment encompasses machinery and infrastructure designed for bovine husbandry, including feeding systems rated for tons-per-hour throughput, milking parlor equipment with pulsation rates of 50-60 cycles per minute, and climate-controlled housing structures maintaining 10-24°C optimal ranges for herd health. Its primary commercial purpose centers on labor reduction, animal welfare compliance, and operational throughput maximization across dairy and beef production systems. Automated systems within the technology dimension lead capital expenditure allocation as labor costs escalate in developed markets, while precision farming tools represent the fastest-growing category through sensor-based feed optimization and reproductive monitoring. Traditional equipment maintains volume dominance in emerging markets where capital constraints limit technology uptake.
The EPA enforces Clean Water Act provisions that mandate waste management infrastructure upgrades for large confined animal feeding operations, directly stimulating equipment replacement cycles. FDA food safety regulations under the Animal Food Safety Modernization Act shape feed handling equipment design standards, particularly for medicated feed mixing and storage systems. USDA conservation programs provide cost-share incentives for fencing and watering system improvements on grazing lands. Stakeholders must monitor evolving animal welfare certification standards and their equipment specification implications as retail supply chains tighten sourcing requirements.
Market Dynamics
Automated milking systems and precision feeding technologies are compressing labor dependency across dairy operations, while EPA enforcement of nutrient management rules accelerates capital replacement cycles for waste handling infrastructure.
Growth Catalysts
- Labor Cost Escalation:Dairy operations in developed markets face wage pressures that accelerate returns on robotic milking parlor investments. Capital allocation tilts toward systems reducing headcount dependency.
- Clean Water Act Enforcement:EPA mandates for confined animal feeding operations require lagoon covers, separators, and composting infrastructure. Equipment replacement cycles compress where violations trigger consent decrees.
- Sensor-Based Feed Optimization:Rumen monitoring boluses and automated ration delivery systems cut feed waste. Adoption concentrates in herds exceeding 500 head where marginal gains scale across tonnage.
Market Restraints
- Steel and Aluminum Input Volatility:Feeding equipment and housing structures carry raw material exposure. Price swings compress fabricator margins and delay farmer purchase decisions.
- Precision Component Supply Concentration:Automated milking system controllers, sensors, and software modules source from specialized German and Dutch suppliers. Geographic concentration creates lead time vulnerability.
- Substitution by Precision Grazing:Intensive rotational grazing systems reduce dependence on mechanical feeding and housing infrastructure. Beef operations in pasture-rich regions defer capital deployment.
Strategic Opportunities
- Brazil's Mato Grosso Expansion:Large-scale feedlot and confinement operations in Brazil's central-west region lack automated infrastructure. Equipment providers face open competitive terrain outside established dairy strongholds.
- USDA Conservation Cost-Share Programs:Environmental Quality Incentives Program funding for fencing, watering systems, and prescribed grazing infrastructure subsidizes equipment purchases on marginal grazing lands.
- Integration of Genomic Data with Reproductive Equipment:Heat detection systems and timed artificial insemination protocols converge with genomic selection databases. Value capture shifts toward data-integrated hardware bundles.
Industry Challenges
- Veterinary Technician Shortage:Automated health monitoring systems require skilled interpretation of lameness alerts, mastitis indicators, and reproductive status flags. Talent scarcity limits realized value from sensor investments.
- Legacy Parlor Retrofit Complexity:Existing herringbone and parallel parlor infrastructure constrains robotic milking system installation. Concrete work, electrical upgrades, and cow flow reconfiguration extend project timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cattle Farm Equipment Market |
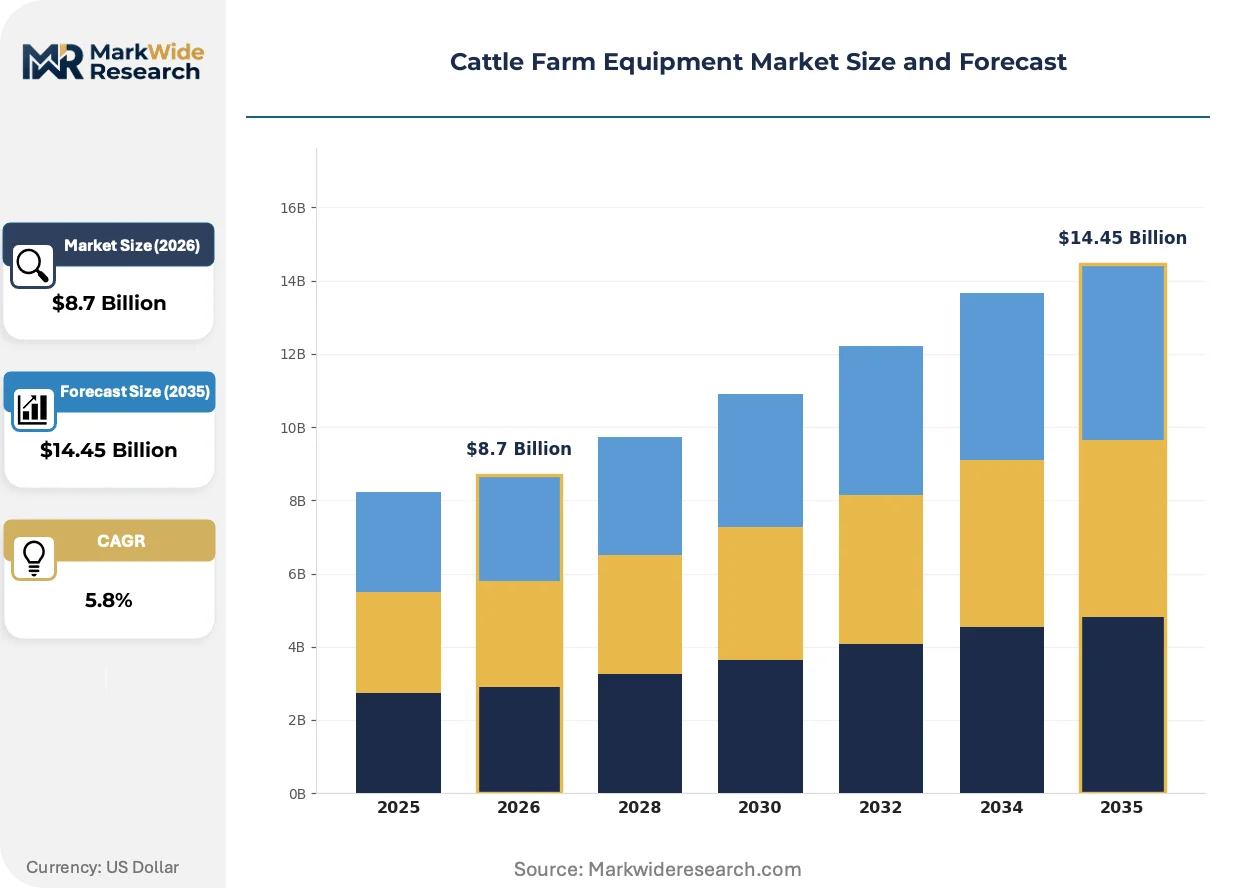
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.45 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Feeders, Waterers, Fencing Systems, Housing Structures End User: Dairy Farms, Beef Farms, Family Farms, Large Enterprises Technology: Automated Systems, Precision Farming Tools, IoT Solutions, Traditional Equipment Application: Cattle Feeding, Milking Operations, Herd Management, Breeding Programs |
| Companies Covered | John Deere, AGCO Corporation, CNH Industrial, Kubota Corporation, DeLaval, GEA Group, Afimilk Ltd, Nedap N.V., Fullwood, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cattle Farm Equipment Market Strategic Shifts
Robotic systems and data-driven management tools are displacing manual workflows across cattle operations, while regulatory pressure on emissions and waste reshapes equipment specifications.
Computer vision systems for body condition scoring and lameness detection are rendering obsolete manual herd inspection protocols. Large dairy cooperatives in the Netherlands and Denmark deploy camera networks at feeding alleys and exit lanes. Labor reallocation toward higher-skill veterinary and reproductive functions follows automation deployment.
EU F-Gas Regulation phase-down schedules constrain refrigerant options for milk cooling equipment and climate-controlled housing. Manufacturers accelerate adoption of natural refrigerant systems and heat recovery modules. Dairy-dense regions in northern Germany and Denmark face compressed equipment replacement timelines where existing systems use restricted synthetic refrigerants.
Cooperative and dealer financing programs now bundle equipment, installation, and service contracts into single obligations. Traditional bank lending for capital purchases loses share to captive finance arms of major suppliers. This restructuring concentrates in North American Midwest markets where cooperative membership dominates farm capital access.
Cattle Farm Equipment Market Segmentation
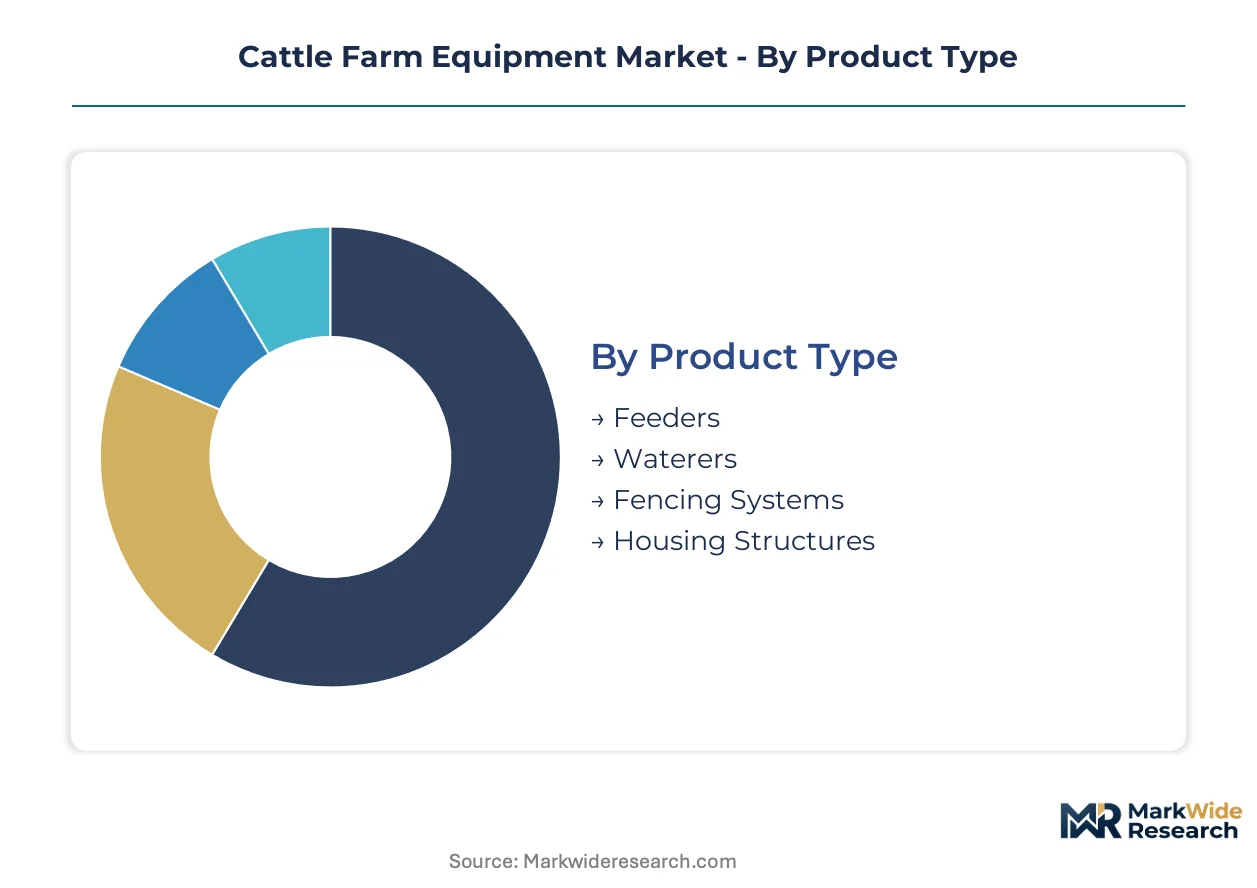
Cattle farm equipment segmentation reveals divergent technology maturity across product lines and user bases. Equipment categories span from centuries-old fencing methods to sensor-integrated robotic milking systems. Understanding these splits clarifies where capital flows concentrate and where substitution risks emerge.
Product Type:
Mature metal fabrication categories dominate volume, while emerging composite and automated systems reshape premium tiers.
- Feeders:Trough and bunk configurations handle dry matter delivery at 2-5 tons per hour throughput rates. Demand concentrates in Texas Panhandle and Brazilian Mato Grosso feedlot corridors where thousand-head operations require continuous ration distribution. Labor cost escalation accelerates interest in automated feed pushers and self-propelled mixing wagons.
- Waterers:Frost-free hydrants, energy-free livestock fountains, and heated automatic waterers maintain hydration across climate zones. USDA Natural Resources Conservation Service cost-share programs subsidize installation on marginal grazing lands in Montana and Wyoming, tightening specification requirements for flow rates and freeze protection.
- Fencing Systems:High-tensile wire, electric polywire, and portable paddock systems enable rotational grazing protocols.
- Housing Structures:Freestall barns, hoop buildings, and open-front sheds provide climate buffering and manure collection infrastructure.
Feeders handle the majority of throughput; automated waterers are expanding most quickly on share as frost-protection technology improves.
End User:
Customer scale determines capital access and technology sophistication, with family operations and large enterprises occupying opposite ends of the automation spectrum.
- Dairy Farms:Parlors, milking robots, and cooling systems serve lactating herds with strict sanitation protocols. Wisconsin and California operations above 500 head drive automated milking system deployment, with DeLaval and Lely installations compressing labor dependency in regions facing agricultural wage pressure.
- Beef Farms:Backgrounding and finishing operations prioritize feed handling, processing facilities, and waste management infrastructure. Nebraska and Kansas feedlots confront EPA Clean Water Act enforcement that mandates lagoon covers and solid separators, accelerating capital replacement cycles.
- Family Farms:Operations under 200 head rely on used equipment markets and cooperative financing for essential infrastructure.
- Large Enterprises:Vertically integrated protein companies deploy enterprise-scale herd management software and centralized maintenance programs.
Dairy farms absorb the highest equipment expenditure per animal unit; large enterprises are climbing the fastest on technology adoption curves.
Technology:
Cost tier stratification separates precision-enabled premium offerings from conventional mechanical systems.
- Automated Systems:Robotic milking parlors, automated calf feeders, and self-propelled feed delivery units operate with minimal human intervention. Dutch and Danish dairy cooperatives deploy camera networks for lameness detection, reallocating labor toward veterinary functions.
- Precision Farming Tools:Rumen monitoring boluses, body condition scoring cameras, and reproductive heat detection systems optimize biological efficiency. Adoption clusters in herds exceeding 500 head where marginal gains scale across tonnage and animal numbers.
- IoT Solutions:Cloud-connected sensors for environmental monitoring and equipment diagnostics enable predictive maintenance.
- Traditional Equipment:Mechanical feeders, gravity waterers, and fixed fencing systems maintain dominance in emerging markets with capital constraints.
Traditional equipment maintains volume leadership; automated systems demonstrate the steepest expansion trajectory as labor economics shift.
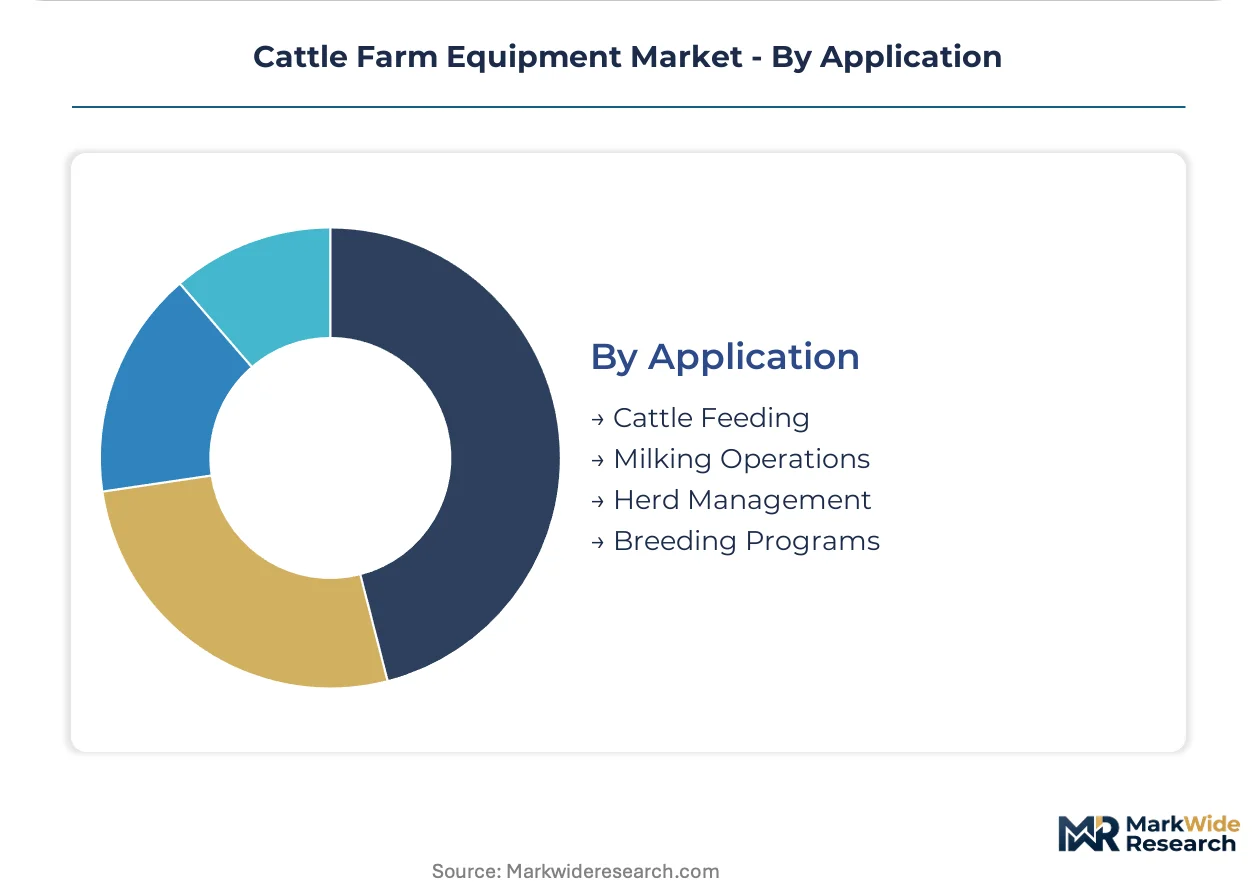
Application:
Functional purpose divides equipment between biological production stages, with milking and feeding commanding distinct supply chains.
- Cattle Feeding:TMR mixers, feed delivery wagons, and bunk management tools control dry matter intake and ration consistency. Brazilian central-west expansion creates open competitive terrain for large-scale feeding infrastructure outside established dairy strongholds.
- Milking Operations:Parlor equipment, pipeline systems, and bulk tank cooling infrastructure handle sanitary fluid collection. EU F-Gas Regulation phase-down schedules force refrigerant transitions in northern Germany and Denmark, compressing replacement timelines for existing synthetic systems.
- Herd Management:Identification systems, weighing platforms, and sorting gates track individual animal performance.
- Breeding Programs:Heat detection aids, semen handling equipment, and calving detection systems support reproductive protocols.
Cattle feeding generates the broadest equipment demand; milking operations capture the highest value per installed unit.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The EPA anchors equipment demand in the United States through Clean Water Act enforcement that mandates waste management infrastructure upgrades for confined animal feeding operations. Dairy and beef producers across multiple geographies face divergent regulatory pressures and capital access conditions that reshape equipment procurement patterns.
United States
Wisconsin and California dairy operations above 500 head drive automated milking system deployment as agricultural wage pressures compress returns on robotic investments. USDA Environmental Quality Incentives Program cost-share funding subsidizes fencing and watering system improvements on marginal grazing lands in Montana and Wyoming. Nebraska and Kansas feedlots confront EPA consent decrees that accelerate capital replacement cycles for lagoon covers and solid separators.
Brazil
Large-scale feedlot and confinement operations in Mato Grosso lack automated infrastructure, creating open competitive terrain for feeding equipment providers. ANVISA veterinary product regulations shape medicated feed handling specifications for integrated protein companies. São Paulo state dairy cooperatives import precision farming tools from European suppliers to modernize aging parlor infrastructure.
Germany
Dairy-dense regions in northern Germany face compressed equipment replacement timelines under EU F-Gas Regulation phase-down schedules for synthetic refrigerants. KBA machinery safety standards influence automated system design specifications for export markets. Bavarian family farms rely on cooperative financing for essential infrastructure while large enterprises deploy enterprise-scale herd management software.
Netherlands
Dutch dairy cooperatives deploy camera networks for lameness detection and body condition scoring, reallocating labor toward veterinary functions. EU Green Deal agricultural transition funding supports climate-controlled housing upgrades that meet tightening emissions standards. Friesland and Gelderland provinces concentrate demand for robotic milking systems as labor costs escalate beyond manual parlor economics.
China
Large-scale dairy enterprises in Heilongjiang and Inner Mongolia import automated milking systems to offset rural labor shortages. MEE environmental regulations tighten manure management requirements for concentrated animal feeding operations near urban centers. Shandong Province beef feedlots expand mechanical feeding infrastructure as corn-soy supply chains mature.
Cattle Farm Equipment Market Competitive Environment
Diversified agricultural machinery conglomerates and specialized dairy technology providers split the market along automation sophistication lines. The vendor base stratifies into three tiers: full-line equipment manufacturers with integrated precision platforms, dedicated livestock technology specialists with premium automation offerings, and regional fabricators serving price-sensitive replacement demand. Consolidation pressure intensifies as cooperative financing programs bundle equipment, installation, and service contracts that favor captive finance arms over traditional bank lending.
Within the diversified machinery tier, John Deere and AGCO Corporation occupy positions that leverage crop system relationships into livestock equipment channels. DeLaval exemplifies the specialized dairy technology archetype with concentrated presence in automated milking systems. Among precision farming specialists, Nedap N.V. and Afimilk Ltd represent sensor-integrated hardware bundles that capture value from genomic data convergence with reproductive equipment. These companies sit within competitive terrain where data-integrated offerings reshape premium-tier procurement decisions.
| Leading Market Players |
|---|
| John Deere |
| AGCO Corporation |
| CNH Industrial |
| Kubota Corporation |
| DeLaval |
| GEA Group |
| Afimilk Ltd |
| Nedap N.V. |
| Fullwood |
| Others |
Value Chain & Pricing Dynamics
Steel and aluminum input volatility determines both pricing tier spreads and supply chain shape across cattle farm equipment manufacturing. Fabricators in the North American Midwest and German industrial clusters face compressed margins when commodity swings hit, forcing tiered pricing separation between configured-to-order automated systems and standard mechanical equipment while extending supplier financing terms to preserve order flow.
Pricing Analysis
The customization-premium spread separates robotic milking parlors priced on configured-to-order engineering from standard feeding and housing equipment sold through catalog channels. Three-tier pricing structure across premium, standard, and economy levels reflects automation sophistication, with DeLaval and GEA Group commanding brand premiums for integrated sensor platforms. Cost compression in the standard tier is intensifying because Brazilian and Chinese fabricators are expanding export capacity. Family farms under 200 head exhibit highest price sensitivity, deferring replacement cycles when steel futures spike, while large enterprises absorb premium pricing for labor-reducing automation.
Supply Chain Analysis
Supplier-financing facilities from cooperative banks and captive finance arms now extend 180-day payment terms for qualifying dealers, reshaping working capital dynamics across distribution networks. Automated system controllers and precision sensors draw from concentrated German and Dutch supplier bases, while structural steel and aluminum extrusions feed from Chinese and Turkish mills. Single-source vulnerability concentrates in specialized pulsation controllers and herd management software modules. Distribution runs through John Deere's precision agriculture platform and regional co-op networks that bundle installation and service contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cattle farm equipment constitutes a defensive-moat market anchored in regulatory entrenchment. EPA consent decrees and EU F-Gas phase-down schedules lock in replacement demand cycles that insulate incumbent positions from demand volatility.
For Market Incumbents: Insulate installed base positions by deepening backward integration into precision sensor manufacturing and expanding captive financing capacity. The threat of emerging Chinese automation providers in Brazilian feedlot markets demands defensive certification investment in EU CE marking and US UL safety standards. Channel control through exclusive dealer territories remains the priority lever against price-aggressive entrants.
For New Entrants and Emerging Players: Establish a beachhead in Brazil's Mato Grosso feedlot corridor where automated infrastructure penetration lags dairy strongholds. White-space concentrates in large-scale feeding equipment for thousand-head operations and precision grazing tools for USDA-subsidized marginal lands. A go-to-market angle bundling equipment with genomic data integration captures value from reproductive equipment convergence.
For Investors and Strategic Acquirers: The market sits at a replacement-cycle acceleration phase that favors precision automation specialists over commodity fabricators. Long-term viability over the coming decade rests on data-integrated hardware bundles that capture recurring service revenue. Acquisition targets should display software-enabled predictive maintenance capabilities and established cooperative financing relationships. The signal to watch is EPA enforcement intensity against concentrated animal feeding operations as a demand inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Sensor Manufacturing | Reduces dependency on Dutch and German controller suppliers while capturing margin from precision automation tiers. |
| Cooperative Financing Program Expansion | Captures capital-constrained family farm demand through bundled equipment-installation-service contracts against bank lending. |
| EU F-Gas Compliant Refrigerant Transition | Accelerates replacement timelines for milk cooling equipment in northern Germany and Denmark under regulatory mandate. |
| Genomic Data Platform Integration | Converges heat detection hardware with reproductive databases to shift value capture toward data-integrated bundles. |
| Brazilian Feedlot Infrastructure Deployment | Addresses open competitive terrain in Mato Grosso where large-scale confinement operations lack automated systems. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of USDA conservation program databases, EPA enforcement records, EU F-Gas regulatory filings, and customs trade data for steel and aluminum inputs. Primary interviews captured perspectives from dairy operations managers, cooperative financing officers, precision agriculture platform engineers, aftermarket service directors, and veterinary technology specialists. Secondary validation drew from SEC 10-K disclosures of diversified machinery manufacturers, ANVISA veterinary product regulations, and herd management software deployment statistics. Bottom-up equipment unit economics triangulate against top-down market sizing across the analysis window.
Forecast inputs span product type segmentation across feeders, milking equipment, and housing structures; technology tiers from traditional mechanical to automated robotic systems; end-user scale from family farms to large enterprises; and application categories spanning feeding, milking, herd management, and breeding programs. CAGRs derive from equipment replacement cycle analysis, regulatory mandate timelines, and labor cost elasticity modeling. Industry-specific inputs include EPA Clean Water Act enforcement trajectory projections and Brazilian central-west feedlot expansion plans.
Sensitivities concentrate around steel and aluminum commodity volatility, precision component supply disruptions, and regulatory enforcement intensity variations. Forecasts reflect documented assumptions regarding labor cost escalation rates and cooperative financing penetration. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Livestock Equipment
Animal Workstations Market
Livestock Equipment
Automated Feeding System Market
Livestock Equipment
Canada Horse Riding Equipment Market
Livestock Equipment
Poultry Feeder Market
Livestock Equipment
Bird Feeding and Watering Suppliers Market
Livestock Equipment
Horse Bell Boots Market
Livestock Equipment
Livestock Identification Market
Livestock Equipment
Cattle Feeder Panels Market
Livestock Equipment
Russia Horse Riding Equipment Market
Livestock Equipment
Nigeria Horse Riding Equipment Market
Livestock Equipment
Cow Lifting Harness Market
Livestock Equipment
Automatic Hog Feeder Market
Livestock Equipment
Sheep Tilt Table Market
Livestock Equipment
Livestock Panel Gates Market
Livestock Equipment
Livestock Farm Equipment Market
Livestock Equipment
Sheep Creep Feeder Market