
 Automatic Hog Feeder Market | 2026-2036
Automatic Hog Feeder Market Size, Share, and Industry Trends Forecast 2026-2036
Automatic Hog Feeder Market Outlook
Modular feeder-to-waterer bundling is repositioning procurement decisions across US swine operations. Hog Slat leverages its integrated building systems to anchor barn construction contracts that include captive feeder placement. Big Dutchman competes through European-engineered electronic feeding lines adapted for North American voltage standards. Sioux Steel Company sustains regional dominance across the upper Midwest through welded-steel fabrication and direct distribution.
An automatic hog feeder is a mechanically or electronically controlled dispensing device that delivers measured rations of dry or wet feed to swine on scheduled intervals or demand-based triggers, typically incorporating auger systems, load cells, or RFID sensors to regulate portion accuracy and reduce waste. The equipment serves commercial pork producers seeking labor reduction, feed conversion optimization, and individual animal tracking. Electronic feeders capture the dominant installed base among operations exceeding five thousand head, while smart feeders integrating IoT-based solutions represent the fastest-expanding category as cloud-connected weight data enables real-time diet adjustment. Mechanical feeders retain cost advantages for family farms and temporary setups where capital recovery periods stretch operational budgets.
USDA grading standards for pork quality indirectly shape feeder specification requirements by incentivizing uniform growth rates that precision feeding supports. FDA veterinary feed directive rules restrict antibiotic inclusion in medicated rations, forcing feeder calibration systems to accommodate phased diet transitions without cross-contamination. EPA concentrated animal feeding operation permits govern manure management interfaces where feeder placement affects nutrient loading calculations. Stakeholders must monitor how pending FDA traceability mandates for livestock movement could integrate with RFID-enabled feeding records to create compliance-adjacent value.
Market Dynamics
IoT-enabled weight monitoring is electrifying feeder specification decisions across US commercial pork operations, forcing mechanical timer-based units into obsolescence as precision feeding becomes a baseline procurement requirement rather than a premium upgrade.
Growth Catalysts
- FDA Veterinary Feed Directive:Restrictions on antibiotic inclusion in medicated rations compel feeder calibration systems that execute phased diet transitions without cross-contamination risk.
- USDA Grading Standards:Pork quality incentives reward uniform growth rates that precision feeding systems deliver through portion-controlled ration dispensing.
- Corn Belt Farm Consolidation:Large integrated pork producers exceeding five thousand head generate concentrated demand for electronic feeders with cloud-connected weight data capabilities.
Market Restraints
- Steel Input Volatility:Welded-steel fabrication costs for feeder housings fluctuate with Midwest scrap metal pricing, compressing margins for regional manufacturers.
- European Component Dependency:Electronic feeding lines rely on voltage-adapted European-engineered control systems, creating lead time exposure to transatlantic supply disruptions.
- Family Farm Capital Constraints:Mechanical feeders retain cost advantages where capital recovery periods exceed operational budget horizons for sub-thousand-head operations.
Strategic Opportunities
- Pending FDA Traceability Mandates:RFID-enabled feeding records could integrate with livestock movement tracking to create compliance-adjacent value for integrated producers.
- Modular Feeder-to-Waterer Bundling:Integrated building systems contracts capture captive feeder placement during new barn construction cycles.
- EPA CAFO Permit Interfaces:Feeder placement optimization affects nutrient loading calculations, positioning precision equipment vendors as manure management compliance partners.
Industry Challenges
- IoT Integration Complexity:Cloud-connected weight data systems require retrofitting legacy barn infrastructure with reliable cellular or WiFi coverage in rural Iowa and North Carolina facilities.
- Calibration Technician Scarcity:Load cell maintenance and RFID sensor troubleshooting demand specialized skills that rural service networks struggle to supply.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automatic Hog Feeder Market |
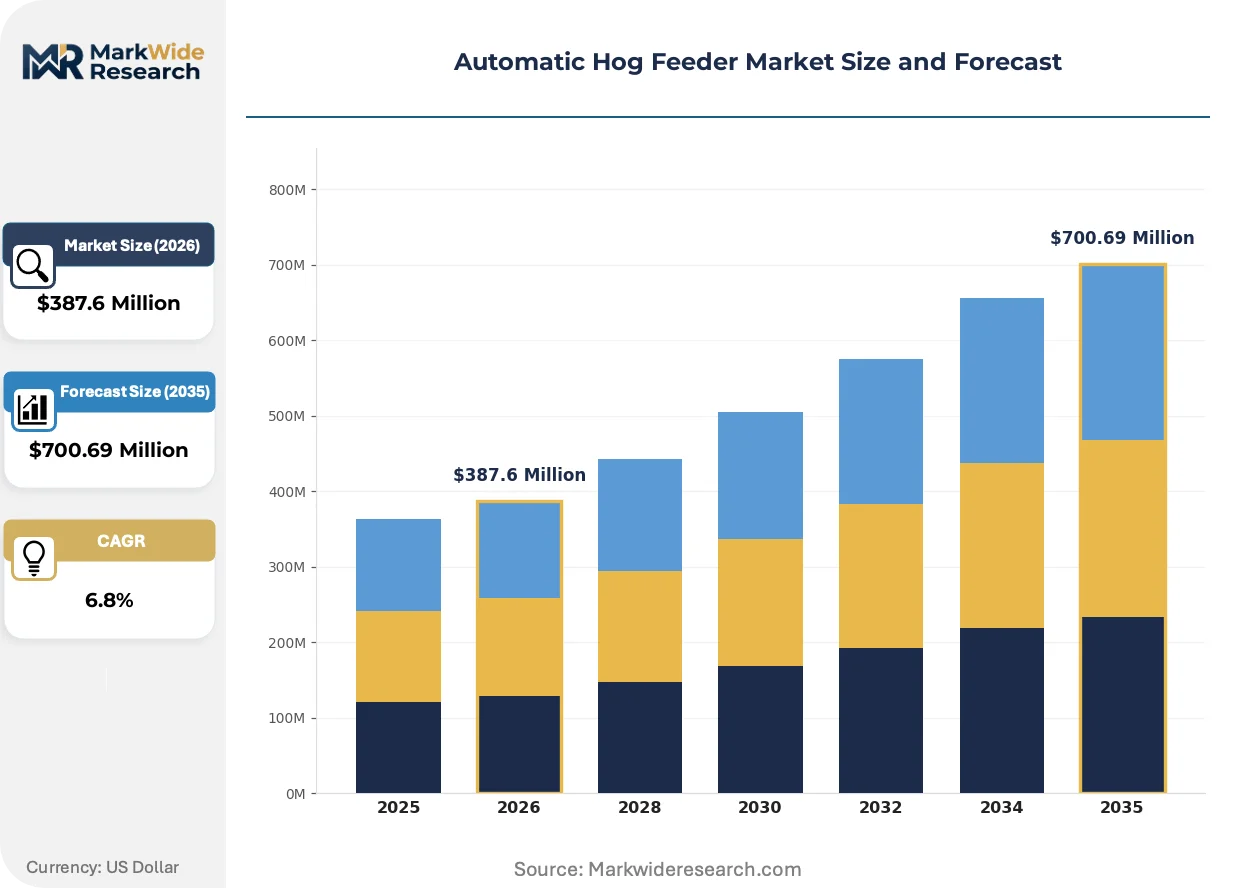
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $700.69 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electronic Feeders, Mechanical Feeders, Smart Feeders, Traditional Feeders End User: Commercial Farms, Family Farms, Agricultural Cooperatives, Research Institutions Technology: IoT-Based Solutions, Automated Systems, RFID Enabled, Mechanical Systems Installation: On-Premise, Mobile Units, Fixed Installations, Temporary Setups |
| Companies Covered | Hog Slat, Sioux Steel Company, Osborne Livestock Equipment, Big Dutchman, Roxell, Schauer Agrotronic GmbH, GEA Group Aktiengesellschaft, Fancom BV, Brehmer Mfg., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automatic Hog Feeder Market Strategic Shifts
Feeder technology is converging with building systems and data infrastructure, transforming standalone equipment purchases into integrated barn construction decisions where connectivity and compliance capabilities determine vendor selection.
Load cell arrays paired with auger dispensing mechanisms are electrifying portion accuracy standards across the commercial segment. Operations exceeding five thousand head deploy these systems to capture real-time weight data that triggers automatic diet adjustments. Cloud connectivity compresses the feedback loop between animal performance and nutritional formulation, displacing mechanical timer-based units that cannot respond to individual consumption patterns.
EPA concentrated animal feeding operation permits are tightening nutrient loading calculations that feeder placement directly influences. Pork producers in Iowa and North Carolina redesign barn layouts to optimize manure management interfaces, specifying precision equipment that reduces feed waste and stabilizes excretion predictability. Equipment vendors respond by embedding placement consulting into sales engineering functions.
Buying committees at large integrated producers now bundle feeder procurement with waterer systems and building construction contracts. Hog Slat anchors these decisions through integrated building systems that specify captive feeder placement during initial barn design. This procurement compression disadvantages standalone equipment vendors who cannot offer construction-phase integration, concentrating specification authority with firms controlling concrete and ventilation contracts.
Automatic Hog Feeder Market Segmentation
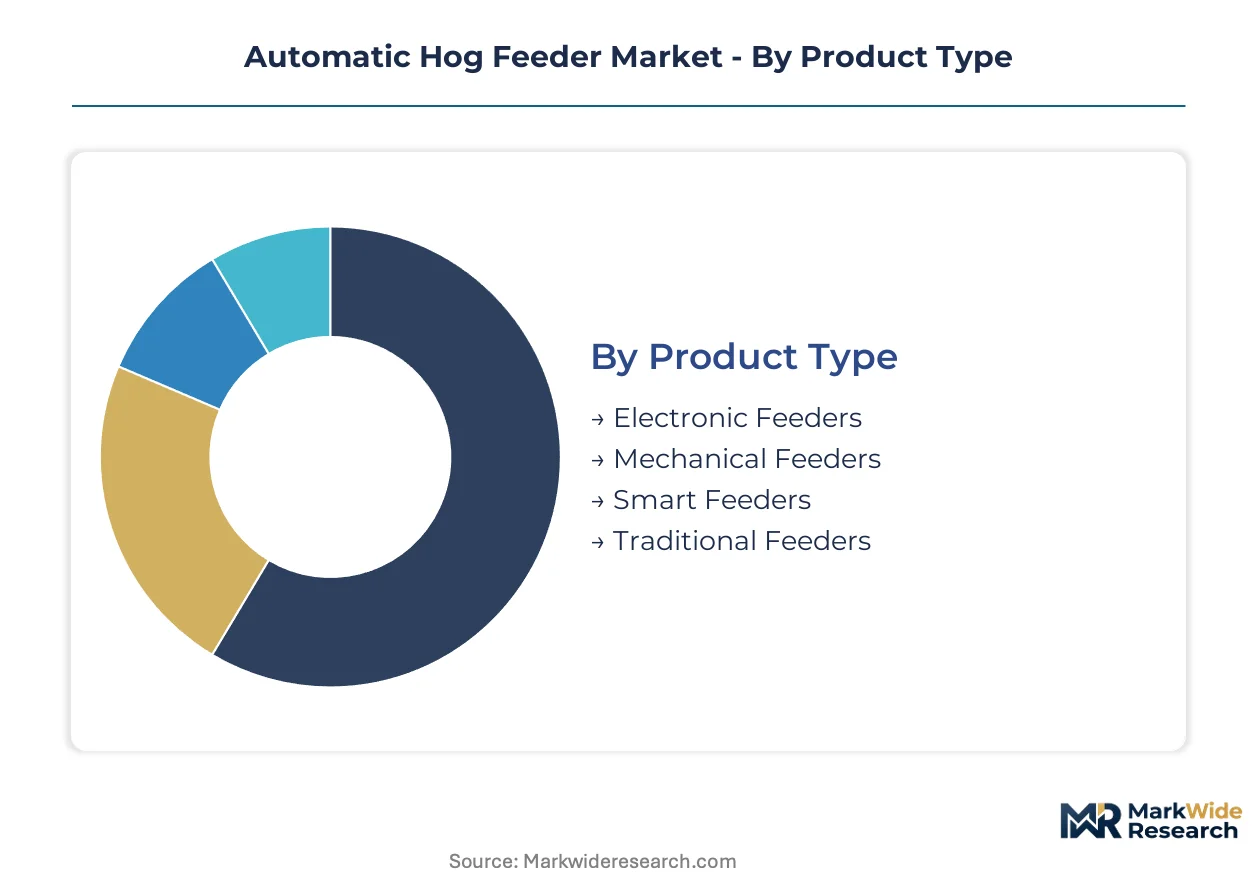
Feeder specification decisions across US pork operations fragment sharply across capital intensity thresholds and regulatory compliance burdens. USDA antibiotic-reduction mandates and FDA traceability requirements are concentrating procurement authority among segments capable of integrating cloud-connected data infrastructure.
Product Type:
FDA Veterinary Feed Directive compliance requirements and USDA grading standards impose distinct certification burdens across product tiers, with electronic and smart systems bearing the heaviest calibration documentation obligations while mechanical units face lighter regulatory scrutiny.
- Electronic Feeders:Load cell arrays paired with auger dispensing mechanisms deliver portion-controlled rations triggered by real-time weight data. Demand concentrates among Iowa and North Carolina operations exceeding five thousand head where cloud connectivity enables automatic diet adjustments and compliance documentation.
- Smart Feeders:IoT-enabled units integrate RFID sensors with cellular data transmission to capture individual animal consumption patterns and feed conversion metrics. North Carolina integrated producers deploy these systems to satisfy pending FDA traceability mandates for livestock movement tracking.
- Mechanical Feeders:Timer-based dispensing systems without electronic control modules serve family farms and temporary setups across the upper Midwest where capital recovery periods constrain technology adoption.
- Traditional Feeders:Gravity-fed trough designs without automated dispensing mechanisms retain niche placement in research institutions and small-scale breeding operations requiring minimal capital outlay.
Electronic feeders sit at the top of the volume ranking, with smart feeders climbing the fastest as integrated producers prioritize compliance-adjacent data capabilities.
End User:
Procurement scale and technical service access separate end-user tiers, with commercial operations commanding dedicated calibration technician networks unavailable to smaller installations.
- Commercial Farms:Operations exceeding five thousand head generate concentrated demand for electronic and smart feeder systems with cloud-connected weight monitoring. Iowa and North Carolina facilities drive specification decisions that prioritize EPA CAFO permit compliance through nutrient loading optimization.
- Family Farms:Sub-thousand-head operations across the Corn Belt favor mechanical feeders where lower capital requirements align with constrained operational budgets and limited technical service access.
- Agricultural Cooperatives:Member-owned purchasing consortia aggregate demand across multiple small and mid-sized operations, creating volume leverage for electronic system adoption that individual farms cannot achieve independently.
- Research Institutions:University and government agricultural research stations specify precision feeding equipment for controlled nutrition studies, prioritizing data granularity over capital efficiency.
Commercial farms command the dominant procurement volume, with agricultural cooperatives expanding their share fastest through consolidated purchasing power.
Technology:
Connectivity infrastructure requirements and sensor calibration complexity stratify technology tiers, with rural cellular coverage gaps constraining IoT deployment in certain geographies.
- IoT-Based Solutions:Cloud-connected systems transmit real-time consumption and weight data to centralized management platforms, enabling remote diet adjustment across dispersed barn locations. Corn Belt operations with reliable cellular infrastructure deploy these systems to compress feedback loops between animal performance and nutritional formulation.
- RFID Enabled:Individual animal identification systems pair ear tag readers with feeder access controls to track consumption per head, supporting antibiotic-free production verification required by certain USDA quality programs.
- Automated Systems:Programmable logic controllers manage feed dispensing without cloud connectivity, serving operations seeking precision portion control without data transmission infrastructure requirements.
- Mechanical Systems:Gravity and timer-based dispensing without electronic components retains cost advantages in temporary setups and facilities lacking reliable power or network access.
IoT-based solutions capture the steepest expansion trajectory, while automated systems without cloud dependency hold steady volume in connectivity-constrained geographies.
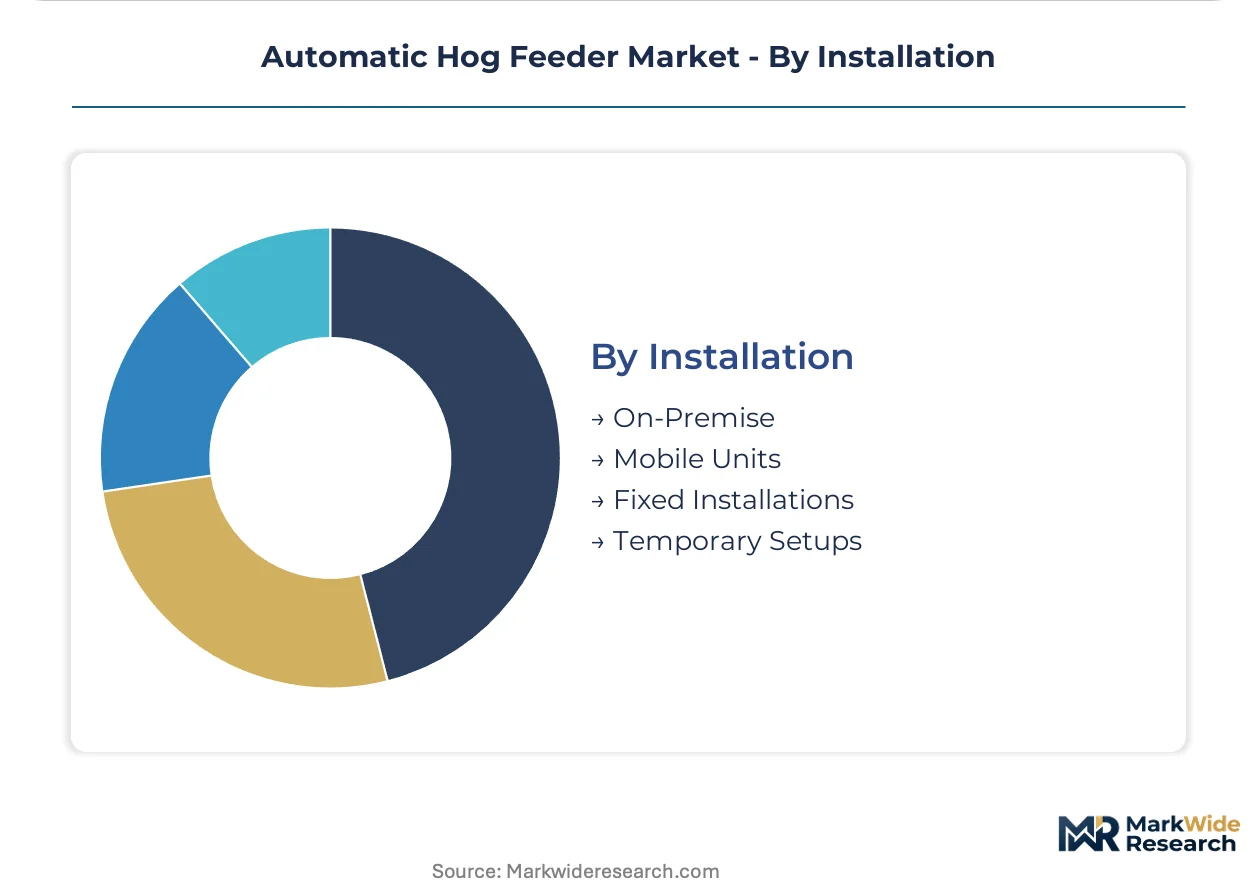
Installation:
Barn construction cycles and manure management permit timelines dictate installation type selection, with permanent fixtures dominating new construction and mobile units serving facility expansion phases.
- Fixed Installations:Permanent mounting integrated with concrete slats and ventilation systems during initial barn construction, specified through Hog Slat and similar integrated building system contracts that capture captive feeder placement.
- Mobile Units:Skid-mounted or wheeled feeders relocate between barn sections or temporary facilities, serving producers expanding capacity ahead of permanent construction permits.
- On-Premise:Hardwired electrical connections with dedicated load cell calibration infrastructure, standard for commercial operations with in-house maintenance capabilities.
- Temporary Setups:Portable mechanical feeders deployed in emergency capacity expansion or disease quarantine scenarios where permanent infrastructure investment is premature.
Fixed installations dominate current deployment volume, with mobile units gaining share fastest among producers navigating EPA CAFO permit delays.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The automatic hog feeder industry traces its commercial roots to the US Corn Belt, where post-war mechanization of pork production first standardized timed feeding systems. Iowa and North Carolina remain the twin anchors of North American demand, though manufacturing and specification influence now extends across multiple continents.
United States
Iowa and North Carolina hog operations drive specification standards through USDA antibiotic-reduction mandates and EPA CAFO permit requirements. FDA Veterinary Feed Directive rules force feeder calibration systems that eliminate cross-contamination risks during phased diet transitions. Sioux Steel Company anchors welded-steel fabrication across the upper Midwest through direct distribution networks serving family and commercial farms alike.
Germany
Precision engineering traditions from agricultural machinery manufacturing inform European electronic feeding line development. EFSA feed safety regulations and EU Green Deal sustainability targets shape equipment certification requirements for cross-border pork producers. Big Dutchman exemplifies the engineering-intensive archetype, adapting voltage standards for North American market entry while maintaining continental R&D concentration.
China
Vertical integration of pork production into national food security planning accelerates mechanization mandates across provincial breeding facilities. MIIT industrial upgrading programs subsidize IoT sensor deployment in livestock operations exceeding ten thousand head. Yangtze River Delta equipment fabricators supply cost-optimized mechanical units for interior provinces where capital constraints persist.
Brazil
Export-oriented pork production in Santa Catarina and Rio Grande do Sul drives adoption of precision feeding systems meeting EU import standards. ANVISA veterinary product regulations align feeder sanitation protocols with international biosecurity requirements. Southern Brazilian cooperatives aggregate member demand for electronic systems that individual mid-scale operations cannot finance independently.
Netherlands
Intensive livestock density in Brabant and Gelderland provinces concentrates demand for manure management-integrated feeding systems. EU Nitrates Directive compliance forces feeder placement optimization that reduces nutrient loading variability. Fancom BV occupies the data-centric archetype, positioning cloud-connected systems as environmental compliance tools rather than pure production equipment.
Automatic Hog Feeder Market Competitive Environment
The competitive structure tilts toward integrated building systems specialists who capture feeder placement during barn construction contracts. Regional welded-steel fabricators defend position through direct distribution and service proximity. Three archetypes dominate: construction-integrated suppliers, precision-engineering European exporters, and regional metalworking specialists. Consolidation pressure concentrates among standalone equipment vendors unable to bundle with concrete and ventilation contracts. Technology licensing agreements between European control system engineers and North American housing fabricators represent the dominant alliance pattern.
Among construction-integrated suppliers, Hog Slat anchors the captive placement model through barn design-phase specification authority. Sioux Steel Company exemplifies the regional fabricator archetype with welded-steel production concentrated in the upper Midwest. Big Dutchman represents the European engineering export pattern, adapting continental electronic feeding lines for North American voltage and regulatory environments. These three occupy distinct competitive vectors rather than direct confrontation, with procurement scale and integration depth determining vendor selection.
| Leading Market Players |
|---|
| Hog Slat |
| Sioux Steel Company |
| Osborne Livestock Equipment |
| Big Dutchman |
| Roxell |
| Schauer Agrotronic GmbH |
| GEA Group Aktiengesellschaft |
| Fancom BV |
| Brehmer Mfg. |
| Others |
Value Chain & Pricing Dynamics
IoT-enabled weight monitoring technology is simultaneously elevating precision-feeding equipment costs and concentrating procurement power among integrated building systems vendors who bundle feeders into construction contracts. This dual shift compresses margins for standalone mechanical feeder producers while rewarding firms controlling concrete, ventilation, and data infrastructure deployment across Iowa and North Carolina barn construction cycles.
Pricing Analysis
Three-tier pricing structure across premium smart feeders, standard electronic systems, and economy mechanical units stratifies the market by connectivity depth and calibration documentation. Price differentiation hinges on FDA Veterinary Feed Directive certification tier and cloud-connected weight data capability, with premium tiers commanding substantial uplifts for compliance-adjacent traceability features. Pricing pressure stems from Midwest scrap metal volatility compressing welded-steel housing margins. Family farms below one thousand head exhibit acute price sensitivity, while commercial operations exceeding five thousand head prioritize total cost of ownership over capital outlay.
Supply Chain Analysis
Transatlantic freight costs for voltage-adapted European control systems impose working capital burdens on North American distributors of precision feeding lines. Manufacturing concentrates in Germany for electronic control engineering, China for cost-optimized sensor fabrication, and the US upper Midwest for welded-steel housing production. Raw material dependencies span load cell arrays, programmable logic controllers, and corrosion-resistant auger metals. Supply chain risk centers on single-source vulnerability for European-engineered voltage conversion modules. Distribution runs through direct manufacturer relationships with large integrated producers and agricultural cooperative purchasing consortia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
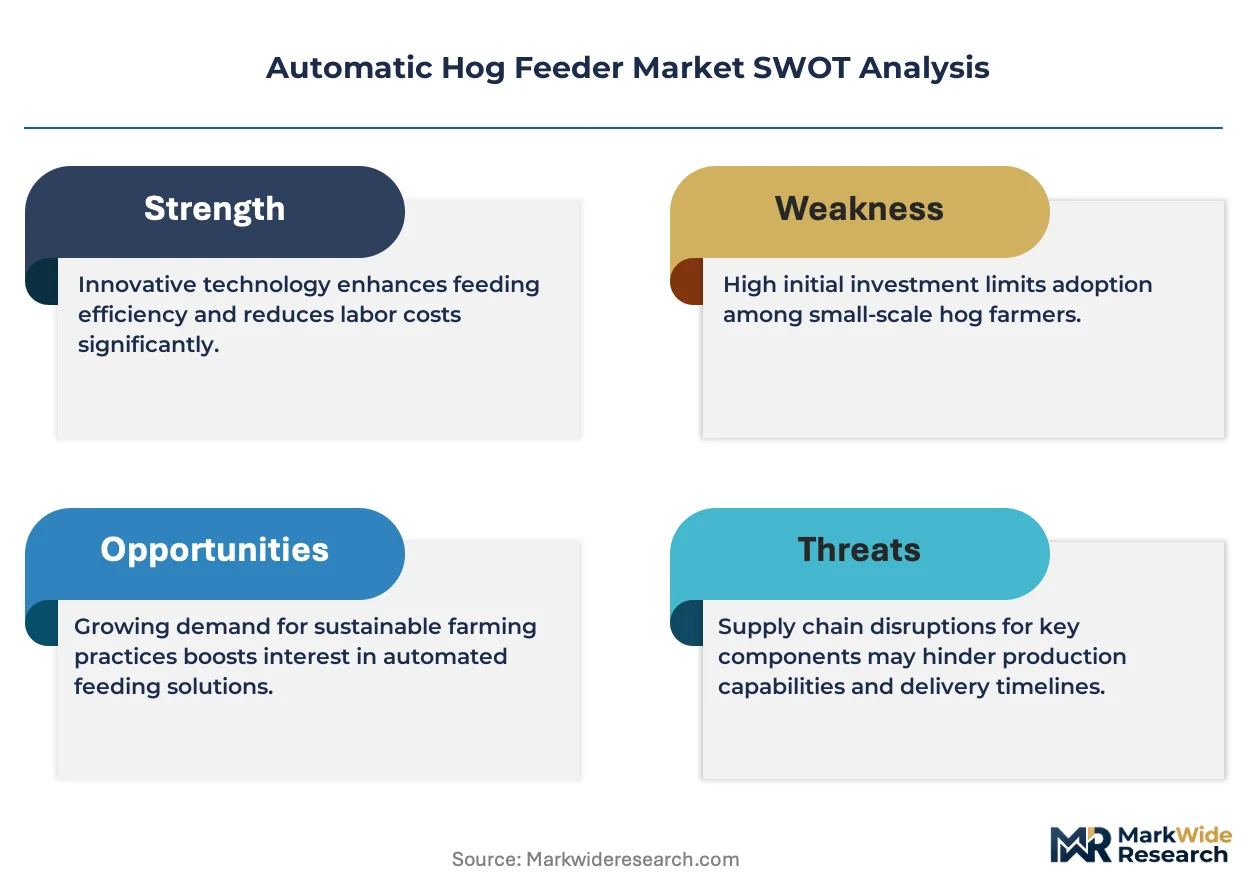
The automatic hog feeder market functions as a stable compounder anchored by irreversible regulatory mandates for antibiotic reduction and livestock traceability that embed precision feeding as baseline infrastructure.
For Market Incumbents: To counter standalone equipment margin compression from integrated building systems bundling, anchor specification authority through backward integration into barn design-phase consulting and captive concrete slat placement. Deepen regional service technician networks across Iowa and North Carolina to defend calibration maintenance relationships against European engineering exporters. For New Entrants and Emerging Players: FDA traceability mandates in the United States open a window for RFID-enabled feeding record systems that integrate with livestock movement tracking. Target agricultural cooperatives as aggregation channels for sub-thousand-head operations seeking electronic system access through pooled purchasing power. Pursue white-label partnerships with regional welded-steel fabricators lacking cloud connectivity engineering capabilities. For Investors and Strategic Acquirers: Valuations sit cheapest among regional metalworking specialists with established distribution networks but underdeveloped IoT engineering functions. The five-to-ten-year viability window favors acquisition targets possessing EPA CAFO permit consulting relationships that position feeders as manure management compliance tools. Monitor FDA livestock traceability rulemaking progress as the critical inflection signal for smart feeder demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Barn Design Consulting | Captures feeder specification authority during concrete and ventilation contract phases. |
| IoT Sensor Calibration Service Networks | Defends recurring revenue relationships against European equipment exporters lacking rural US presence. |
| RFID-Enabled Traceability Platform Development | Positions feeding records for integration with pending FDA livestock movement mandates. |
| Agricultural Cooperative Distribution Partnerships | Aggregates fragmented family farm demand into electronic system volume purchasing. |
| EPA CAFO Permit Compliance Integration | Transforms feeder placement optimization into manure management consulting revenue. |
Study Parameters
Direct dialogue with barn construction contractors, livestock nutrition consultants, agricultural cooperative procurement managers, and EPA CAFO permit compliance officers grounded qualitative findings. Secondary validation drew from USDA livestock reports, FDA veterinary feed directive guidance documents, Iowa State University extension publications, and SEC filings of publicly traded pork processors. Bottom-up demand modeling triangulated against top-down agricultural equipment spending patterns.
Bottom-up volume projections aggregated individual farm capacity expansion plans across the Corn Belt and Southeast production clusters. Segmentation dimensions spanned product type, end-user scale tier, technology connectivity depth, and installation permanence. CAGRs derived from regression analysis of historical equipment replacement cycles and regulatory compliance deadline proximity. Feed conversion ratio improvements and labor cost inflation served as industry-specific forecast inputs.
Revisions become necessary when FDA traceability mandate timelines shift, EPA CAFO permit approval velocities change, or cellular infrastructure deployment in rural Iowa and North Carolina stalls. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Livestock Equipment
Cattle Blower Market
Livestock Equipment
Horse Bell Boots Market
Livestock Equipment
Wire Livestock Panels Market
Livestock Equipment
Canada Horse Riding Equipment Market
Livestock Equipment
Cattle Handling Systems Market
Livestock Equipment
Sheep Handling Equipment Market
Livestock Equipment
Goat Handling Equipment Market
Livestock Equipment
Sheep Tilt Table Market
Livestock Equipment
Animal Feed Mixer Market
Livestock Equipment
Cattle Grooming Chute Market
Livestock Equipment
Livestock Carrier Market
Livestock Equipment
Russia Horse Riding Equipment Market
Livestock Equipment
Slaughtering Equipment Market
Livestock Equipment
Poultry Feeder Market
Livestock Equipment
Rabbit Hutches Market
Livestock Equipment
Milking Equipment Market