
 Egg Incubator Market | 2026-2036
Egg Incubator Market Size, Share, and Industry Trends Forecast 2026-2036
Egg Incubator Market Analytics
Multi-source component procurement for temperature sensors and heating elements is consolidating around vertically integrated manufacturers. Brinsea anchors its competitive position through in-house production of precision digital control systems. GQF Manufacturing sustains broad distribution across North American farm supply channels. Cimuka differentiates through specialized large-scale cabinet incubators engineered for commercial hatchery throughput.
An egg incubator is an enclosed chamber that maintains controlled temperature, humidity, and ventilation parameters to artificially hatch avian eggs, typically operating within 37.5–37.8°C and 45–55% relative humidity ranges depending on species. The device serves commercial poultry operations, research laboratories, and small-scale agricultural producers requiring consistent hatch rates independent of brooding hens. Smart incubators represent the fastest-expanding product category as IoT-enabled remote monitoring and automated egg-turning reduce manual intervention and improve yield predictability. Solar-powered technology adoption concentrates in regions with intermittent grid access where photovoltaic-integrated units eliminate generator dependency. Medium-scale units occupy the broadest addressable base, bridging home user affordability with commercial-grade reliability.
The US FDA and USDA jointly regulate hatchery sanitation protocols and chick health certification standards that dictate incubator design requirements for interstate commerce. CE marking under EU machinery directives governs electrical safety and electromagnetic compatibility for equipment sold across European member states. China's GB standards and SAMR certification mandate energy efficiency labeling and material safety testing for domestic incubator manufacturing. Stakeholders must evaluate regulatory divergence between export markets when configuring product portfolios and certification investments.
Market Dynamics
Automated incubation systems are compressing labor requirements while solar-integrated designs unlock off-grid poultry expansion in electricity-constrained regions. Commercial hatcheries drive fleet upgrades to maximize throughput per square meter.
Growth Catalysts
- USDA Sanitation Mandates:Interstate chick commerce rules compel hatcheries to adopt precision-controlled environments that reduce pathogen transmission risks.
- Photovoltaic Integration:Solar-powered units eliminate generator dependency in Nigerian and Indonesian poultry clusters where grid reliability remains inconsistent.
- Commercial Hatchery Consolidation:Large-scale operators in Brazil deploy automated turning and climate systems to achieve uniform hatch rates across million-egg annual volumes.
Market Restraints
- Semiconductor Supply Concentration:Temperature sensor and microcontroller sourcing concentrates in East Asian foundries, exposing lead time volatility for control system manufacturers.
- Energy Storage Cost Structure:Battery-dependent solar units face lithium-ion price sensitivity that compresses margins on entry-level cabinet models.
- Species-Specific Calibration Limits:Single-chamber designs cannot simultaneously maintain the divergent humidity requirements of waterfowl and galliform eggs without dedicated retrofit kits.
Strategic Opportunities
- Indonesian Import Substitution Programs:Domestic egg production targets create procurement preference for locally assembled incubators over imported European units.
- Research Laboratory Biosecurity Tier:HEPA-integrated cabinet designs address pathogen containment protocols for avian influenza studies in BSL-3 facilities.
- IoT-Enabled Predictive Maintenance:Remote sensor networks allow service unbundling from hardware sales, generating recurring revenue streams from commercial operators.
Industry Challenges
- Multi-Jurisdiction Certification Timelines:Simultaneous FDA, CE marking, and SAMR approvals extend product launch cycles by 14-18 months for manufacturers targeting export markets.
- Precision Calibration Skill Scarcity:Field technicians capable of verifying PID controller accuracy against NIST-traceable standards remain concentrated in industrial automation hubs, complicating rural service deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Egg Incubator Market |
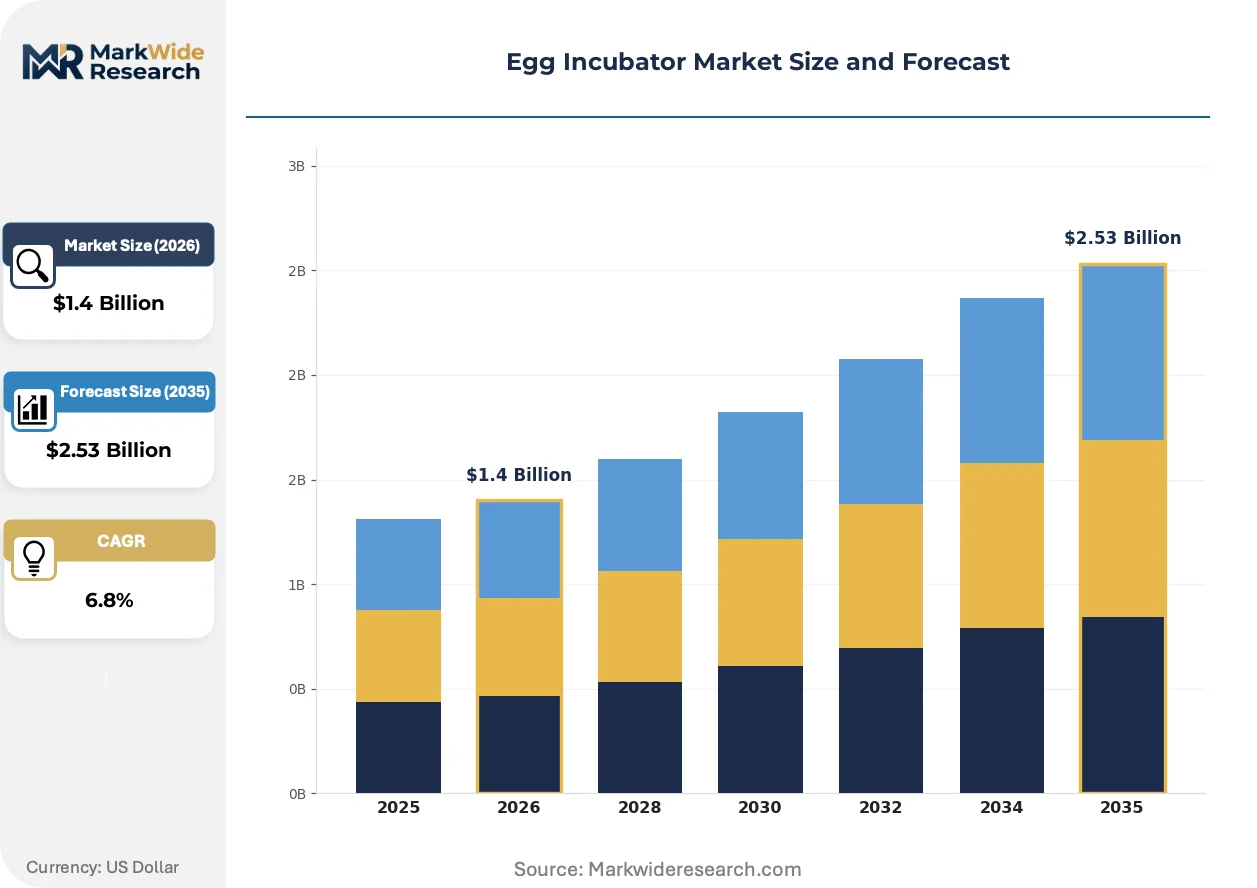
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.53 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Small Scale, Medium Scale, Large Scale, Smart Incubators End User: Commercial Hatcheries, Poultry Farms, Research Institutions, Home Users Technology: Conventional, Digital, Automated, Solar-Powered Capacity: 50 Eggs, 100 Eggs, 200 Eggs, Others |
| Companies Covered | Cimuka, IVYX Scientific, Brinsea, YAKUST, JAEDO, Harris Farms, Chalixion, Nanchang Howard Technology, GQF Manufacturing, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Egg Incubator Market Evolving Landscape
Digital control architectures are displacing analog thermostat systems while distributed energy designs reshape equipment deployment geography. Hatchery operators now prioritize predictive capability over basic environmental maintenance.
Machine vision-based candling systems are automating fertility assessment and embryo viability scoring during incubation cycles. Commercial operators in the United States and Netherlands deploy these units to reduce manual inspection labor by two-thirds. The technology is automating quality control checkpoints that previously required skilled hatchery technicians.
EU F-Gas Regulation phase-down schedules are accelerating hydrocarbon refrigerant adoption in climate-controlled incubation chambers. Manufacturers must redesign compressor architectures to maintain 37.5°C setpoints using propane or isobutane working fluids. CE marking compliance timelines for updated cold-chain components now dominate product development roadmaps for European-market equipment.
Subscription-based monitoring services are replacing upfront software licenses among mid-scale poultry operations. Brazilian and Nigerian distributors now bundle cellular-connected sensor packages with hardware sales, capturing recurring revenue from previously transactional relationships. This model concentrates buyer relationships with regional service providers rather than equipment OEMs.
Egg Incubator Market Segmentation
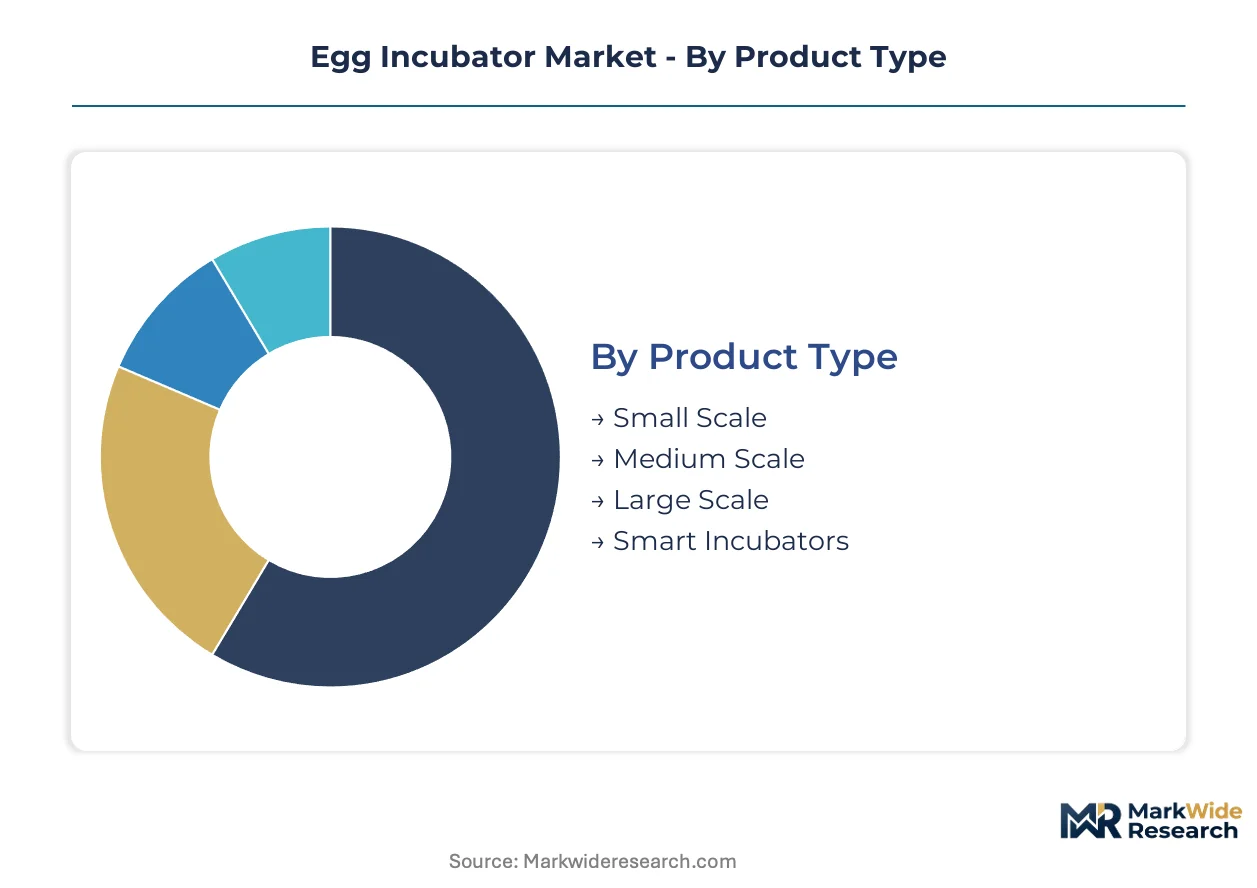
Incubator purchasing patterns split sharply between volume-driven commercial hatcheries prioritizing throughput per square meter and premium-seeking operators demanding predictive analytics and remote monitoring capabilities. Segmentation reveals how technology tier and scale interact to determine addressable customer bases across poultry production, research, and hobbyist channels.
Product Type:
Volume concentration clusters in cabinet units serving commercial throughput demands, while premium pricing attaches to connected systems with sensor networks and automated intervention.
- Small Scale:Benchtop and countertop units accommodate 20–50 eggs with basic thermostat control and manual turning trays. Demand concentrates among Nigerian and Indonesian home producers expanding backyard flocks to offset protein import costs.
- Medium Scale:Cabinet designs bridging 100–500 egg capacity dominate Brazilian smallholder cooperatives upgrading from broody hens to mechanized hatching. These units capture the broadest addressable base through calibrated price-performance positioning against fully commercial systems.
- Large Scale:Tunnel and multi-chamber configurations process 10,000+ eggs per batch with centralized climate control and automated candling integration. These systems anchor fleet procurement at vertically integrated poultry processors seeking uniform hatch rates across million-egg annual volumes.
- Smart Incubators:IoT-enabled units with cellular connectivity, cloud-based parameter logging, and predictive maintenance algorithms command substantial price premiums. These systems are gaining share fastest among research institutions and commercial hatcheries reducing labor inspection rounds.
Mature deployment sits with Large Scale units in established commercial operations. Newer deployment is concentrated in Smart Incubators as connectivity infrastructure penetrates rural poultry clusters.
End User:
Customer type determines specification rigor, with biosecurity protocols and calibration documentation requirements escalating from backyard hobbyists through BSL-3 research facilities.
- Commercial Hatcheries:High-throughput operators mandate 24/7 environmental stability, redundant heating systems, and automated egg-turning mechanisms synchronized to species-specific embryonic development timelines. Brazilian and Indonesian hatcheries drive replacement cycles as they consolidate fragmented production bases.
- Poultry Farms:On-farm hatching operations prioritize cabinet units with moderate capacity and durable construction tolerating dusty shed environments. Nigerian poultry farms increasingly specify solar-compatible power architectures to circumvent diesel generator dependency.
- Research Institutions:Laboratories demand HEPA filtration, data logging compliant with GLP standards, and chamber designs supporting pathogen containment protocols for avian influenza studies. These specifications command 3–4x price multiples over commercial-grade equivalents.
- Home Users:Hobbyist and educational segments prioritize compact footprint, intuitive digital interfaces, and visual observation windows over precision specifications. Price sensitivity limits this segment to entry-level thermostat-controlled units.
Procurement sophistication peaks with Research Institutions. Volume scale concentrates with Commercial Hatcheries.
Technology:
Control architecture migration from analog to digital is reshaping competitive positioning, while energy source diversification unlocks geographic expansion into grid-constrained regions.
- Conventional:Bimetallic thermostat and hygrostat mechanisms persist in price-sensitive segments where capital constraints override precision requirements. These systems retain residual demand in Indonesian rural markets with limited technician availability for digital calibration.
- Digital:PID controller-based units with LCD parameter displays and programmable setpoint profiles now dominate mid-market procurement. Brazilian distributors report digital systems capturing 70%+ of replacement sales as farm operators upgrade from failed analog units.
- Automated:Integrated turning mechanisms, candling systems, and alarm networks reduce manual intervention to weekly maintenance checks. Nigerian commercial hatcheries prioritize automated systems to compress labor costs amid wage inflation pressures.
- Solar-Powered:Photovoltaic-integrated designs with lithium battery storage eliminate grid dependency for off-grid poultry operations. These configurations are expanding most quickly in Nigerian and Indonesian regions where diesel costs erode hatchery margins.
Technology maturation centers on Digital controls. Steepest expansion trajectory belongs to Solar-Powered architectures addressing electricity access gaps.
Capacity:
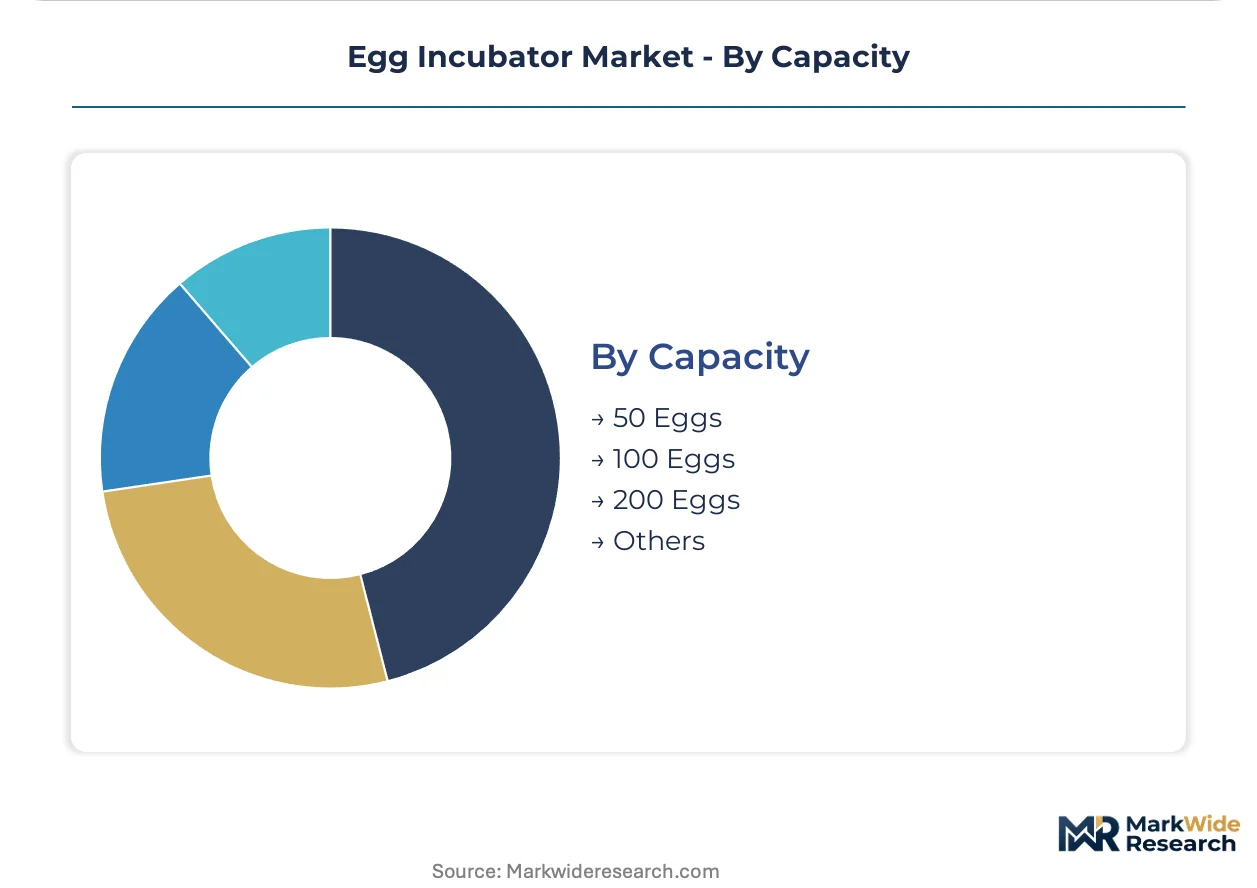
Batch size selection correlates with production scale and species mix, with multi-species operators requiring flexible chamber configurations.
- 50 Eggs:Compact tabletop units serve educational demonstrations and specialty breeders maintaining rare heritage poultry lines. These systems emphasize observation accessibility over throughput metrics.
- 100 Eggs:The standard entry point for small commercial operators and serious hobbyists, balancing manageable footprint against batch economics. Indonesian smallholder cooperatives standardize on this capacity for village-level hatching collectives.
- 200 Eggs:Cabinet units at this threshold attract Brazilian farm operations transitioning from subsistence to market-oriented egg production. This capacity tier bridges home-scale and commercial-grade reliability expectations.
- Others:Custom and extra-large configurations include 500+ egg cabinets and 10,000+ egg tunnel systems engineered for industrial hatchery throughput. These specialized designs require factory-direct procurement with extended lead times.
Volume deployment concentrates in 200 Eggs configurations among emerging commercial operators. Premium specification concentrates in Others category custom engineering.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Poultry feedstock availability and hatchery infrastructure investment anchor the geographic distribution of incubator demand. Brazil, Nigeria, and Indonesia concentrate procurement volumes as domestic egg production scales to reduce import dependence. Solar-compatible architectures unlock expansion in electricity-constrained rural clusters.
Brazil
Commercial hatchery consolidation drives fleet upgrades among vertically integrated poultry processors. ANVISA sanitation protocols for day-old chick distribution mandate precision climate control in interstate commerce. São Paulo state anchors national production capacity with automated tunnel systems processing million-egg annual volumes.
Nigeria
Diesel generator dependency erodes hatchery margins, accelerating photovoltaic-integrated unit procurement. The country's national agricultural development bank extends credit facilities for solar-powered poultry equipment. Lagos and Ibadan industrial corridors concentrate distributor networks bundling cellular-connected sensor packages with hardware sales.
Indonesia
Import substitution programs create procurement preference for locally assembled units over European imports. The national standards body mandates energy efficiency labeling for domestic manufacturing certification. Java island smallholder cooperatives standardize on 100-egg cabinet configurations for village-level hatching collectives.
United States
USDA interstate chick commerce rules compel precision-controlled environments reducing pathogen transmission risks. FDA joint oversight with USDA governs hatchery sanitation protocols and health certification standards. Midwest poultry belts deploy machine vision-based candling systems automating fertility assessment and embryo viability scoring.
Netherlands
EU F-Gas Regulation phase-down schedules accelerate hydrocarbon refrigerant adoption in climate-controlled chambers. CE marking compliance timelines for updated cold-chain components dominate product development roadmaps. Dutch research institutions prioritize HEPA-integrated cabinet designs for avian influenza studies in BSL-3 facilities.
Egg Incubator Market Competitive Landscape
Capacity expansion dominates the current landscape as manufacturers scale automated production lines to serve commercial hatchery consolidation. The vendor base organizes into three tiers: vertically integrated specialists controlling precision digital control systems, broad-distribution fabricators sustaining farm supply channel coverage, and regional assemblers capturing import substitution preference in emerging markets. Strategic archetypes include technology licensors monetizing IoT platforms and solar-integrators addressing off-grid demand clusters. Geographic expansion and portfolio diversification represent the dominant competitive moves, with manufacturers establishing local assembly presence in Indonesia and Nigeria while adding predictive maintenance service bundles to hardware offerings.
Within the precision control tier, Brinsea Products Ltd. exemplifies vertically integrated manufacturing of digital control architectures. GQF Manufacturing Co. occupies a position among North American farm supply channel anchors with broad distribution reach. Cimuka represents the large-scale cabinet specialization archetype engineered for commercial hatchery throughput demands. These three anchors illustrate how competitive positioning fragments across technology depth, channel breadth, and scale engineering respectively.
| Leading Market Players |
|---|
| Cimuka |
| IVYX Scientific |
| Brinsea |
| YAKUST |
| JAEDO |
| Harris Farms |
| Chalixion |
| Nanchang Howard Technology |
| GQF Manufacturing |
| Others |
Value Network & Pricing Analysis
Family-owned mid-cap specialists across Turkey and China anchor component fabrication for heating elements and digital control modules, linking captive production capacity to pricing discipline in aftermarket service bundles. Their concentrated ownership structures enable long-term supply agreements that buffer price volatility while locking in warranty service revenue streams.
Pricing Analysis
Warranty and calibration service bundling separates premium-tier suppliers from transactional equipment vendors in this market. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation and after-sales support intensity. Cost compression in entry-level cabinet models is intensifying because lithium-ion battery price sensitivity squeezes margins on solar-integrated units. Home users in Nigerian and Indonesian rural clusters exhibit highest price sensitivity, while research institutions purchasing HEPA-integrated systems show lowest elasticity due to biosecurity compliance mandates.
Supply Chain Analysis
Dual-sourcing requirements for temperature sensors and microcontrollers are now standard among commercial hatcheries qualifying East Asian foundries against supply disruption. Component fabrication concentrates in China, South Korea, and Taiwan for PID controllers and heating elements. Raw material dependencies span copper wiring, semiconductor-grade silicon, and lithium battery cells. Single-source vulnerability in microcontroller sourcing exposes lead time volatility for control system manufacturers. Distribution runs through regional farm supply cooperatives in Brazil and cellular-connected distributor networks in Nigeria.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is becoming a vertical-integration race as manufacturers pursue in-house production of precision digital control systems to defend margin position against semiconductor supply volatility.
For Market Incumbents: Extend service unbundling strategies by establishing predictive maintenance platforms that generate recurring revenue from commercial hatchery operators. Deepen backward integration into sensor manufacturing to reduce dependency on East Asian foundry lead times. Consolidate distributor relationships in Brazilian and Indonesian markets before regional assemblers capture import substitution preference. For New Entrants and Emerging Players: Launch via solar-integrated equipment leasing models targeting Nigerian poultry farms seeking to circumvent diesel generator dependency. Target the 100-egg cabinet segment serving Indonesian smallholder cooperatives standardizing on village-level hatching collectives. Bundle cellular-connected sensor packages with hardware sales to capture recurring revenue streams from previously transactional relationships. For Investors and Strategic Acquirers: Distressed-cycle entries favor vertically integrated control system specialists in Turkey and China with captive sensor production and established CE marking compliance. Long-term viability centers on manufacturers capable of spanning both commercial hatchery consolidation and off-grid solar expansion over the coming decade. Watch for inflection signals in lithium battery cost trajectories that would compress margins on entry-level solar units and trigger consolidation among regional assemblers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Sensor Manufacturing | Reduces lead time exposure to East Asian foundry concentration for PID controller suppliers. |
| Predictive Maintenance Platform Launch | Enables recurring revenue capture from Brazilian commercial hatcheries reducing labor inspection rounds. |
| Solar-Compatible Architecture Expansion | Unlocks Nigerian and Indonesian off-grid poultry clusters where diesel costs erode hatchery margins. |
| Local Assembly Establishment | Secures procurement preference under Indonesian import substitution programs targeting domestic egg production. |
| HEPA-Integrated Cabinet Development | Addresses Dutch research institution demand for BSL-3 avian influenza containment protocols. |
Research Methodology
Document review covered regulatory filings from FDA, USDA, and ANVISA, complemented by interviews with commercial hatchery operations managers, agricultural equipment distributors, and precision control system engineers. Secondary validation drew from customs trade databases, SEC filings of vertically integrated poultry processors, and energy access indicators from rural electrification programs. Bottom-up triangulation across equipment shipment data and top-down validation against poultry production statistics anchored market sizing.
Segment-level outputs across product type, end user, technology tier, and capacity configuration were generated through structured modeling of replacement cycles and fleet expansion patterns. CAGRs were derived from regression analysis of historical procurement trends against poultry production growth trajectories. Key inputs included solar penetration rates in Nigerian grid-constrained regions and Indonesian domestic manufacturing capacity buildout under import substitution programs.
Semiconductor supply disruption, lithium battery price volatility, and multi-jurisdiction certification timeline extensions are the dominant revision risks to forecast assumptions. Deviation in East Asian foundry capacity utilization would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Livestock Equipment
Poultry Feeder Market
Livestock Equipment
Nigeria Horse Riding Equipment Market
Livestock Equipment
Silage Tube Market
Livestock Equipment
Livestock Panel Gates Market
Livestock Equipment
Horse Bunk Feeder Market
Livestock Equipment
Animal Cage Market
Livestock Equipment
Chicken Coop Market
Livestock Equipment
Hog Feeder Market
Livestock Equipment
Animal Workstations Market
Livestock Equipment
Cattle Grooming Chute Market
Livestock Equipment
Goat Handling Equipment Market
Livestock Equipment
Canada Horse Riding Equipment Market
Livestock Equipment
Sheep Tilt Table Market
Livestock Equipment
Livestock Monitoring System Market
Livestock Equipment
Sheep Handling Equipment Market
Livestock Equipment
Hydraulic Squeeze Chute Market