
 Robotics Milking Systems Market | 2026-2036
Robotics Milking Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Robotics Milking Systems Market Insights
The divergence between premium and commodity tiers in robotics milking systems is hardening around sensor accuracy, software integration depth, and post-installation service commitments. DeLaval leverages its vertically controlled supply chain to dominate high-throughput installations across Northern Europe. Lely sustains brand loyalty through proprietary herd management algorithms that extend beyond milking into feed optimization and health monitoring. GEA Group Aktiengesellschaft competes on manufacturing scale, anchoring its position in mid-size farm segments where price sensitivity constrains full automation.
Robotics milking systems integrate robotic arms, optical sensors, and AI-driven teat identification to execute automated milking without human intervention, typically processing 60-70 cows per unit daily with real-time somatic cell counting. Their primary commercial purpose centers on labor reduction, milk quality traceability, and individual cow health analytics for intensive dairy operations. Automated Milking Systems lead product type demand as farms replace tie-stall parlors with free-traffic box configurations, while the Artificial Intelligence technology segment captures expanding margin pools through predictive mastitis detection and estrus alerting. Dairy Farms anchor end-user demand, though Agricultural Cooperatives represent the fastest-growing buyer category as shared-equipment models lower capital barriers for smaller producers.
The EU Green Deal and F-Gas Regulation shape equipment energy efficiency and refrigerant requirements for on-farm milk cooling integrated with robotic systems, while CE marking mandates govern machine safety and electromagnetic compatibility for European market access. The USDA and FDA influence North American product standards through Grade A dairy facility requirements and veterinary drug residue testing protocols tied to automated milking data logs. Stakeholders must monitor how carbon accounting rules and animal welfare certification schemes reshape procurement criteria for robotics milking investments across divergent regulatory environments.
Market Dynamics
The EU Farm to Fork Strategy is compressing investment timelines for dairy automation as livestock operators race to meet binding animal welfare and emissions benchmarks ahead of enforcement deadlines.
Growth Catalysts
- CE marking mandates:Machine safety and electromagnetic compatibility requirements accelerate replacement cycles for aging tie-stall parlors across Germany, Denmark, and the Netherlands.
- Free-traffic box configurations:Automated Milking Systems eliminate labor-intensive pre-milking preparation, cutting staffing requirements by half on intensive operations converting from conventional herringbone setups.
- Dairy cooperatives in Lower Saxony:Shared-equipment models pool capital across multiple smallholder farms, collapsing upfront cost barriers that previously blocked robotic adoption.
Market Restraints
- Stainless steel and precision sensor supply:Input cost volatility for robotic arm components and optical teat-detection modules squeezes gross margins on mid-tier system configurations.
- F-Gas Regulation refrigerant phase-down:On-farm milk cooling equipment integrated with robotic systems faces retrofit costs or replacement mandates, extending payback periods for capital-constrained buyers.
- Technical limitation in pasture-based systems:Robotic units require fixed barn infrastructure incompatible with seasonal grazing management, excluding extensive dairy regions from addressable demand.
Strategic Opportunities
- Polish and Romanian dairy sectors:Underpenetrated markets with rising herd sizes and EU structural fund access present first-mover positioning for equipment vendors ahead of regulatory harmonization.
- Predictive mastitis detection:Artificial Intelligence convergence with real-time somatic cell counting creates subscription revenue streams beyond hardware sales through health-alerting services.
- USDA conservation programs:Environmental Quality Incentives Program cost-sharing for precision livestock equipment lowers net capital burden for Midwest dairy operations evaluating automation.
Industry Challenges
- Mechatronics and data analytics skill gaps:Farm-level technicians capable of diagnosing robotic arm calibration failures and interpreting AI-generated health alerts remain scarce, forcing reliance on manufacturer service contracts.
- Grade A dairy facility recertification:FDA-aligned state inspectors require extensive documentation of automated milking data logs for veterinary drug residue compliance, stretching implementation timelines.
- Legacy parlor integration complexity:Retrofit installations must reconcile existing herd management software with proprietary robotic protocols, triggering data migration bottlenecks and operational downtime.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Robotics Milking Systems Market |
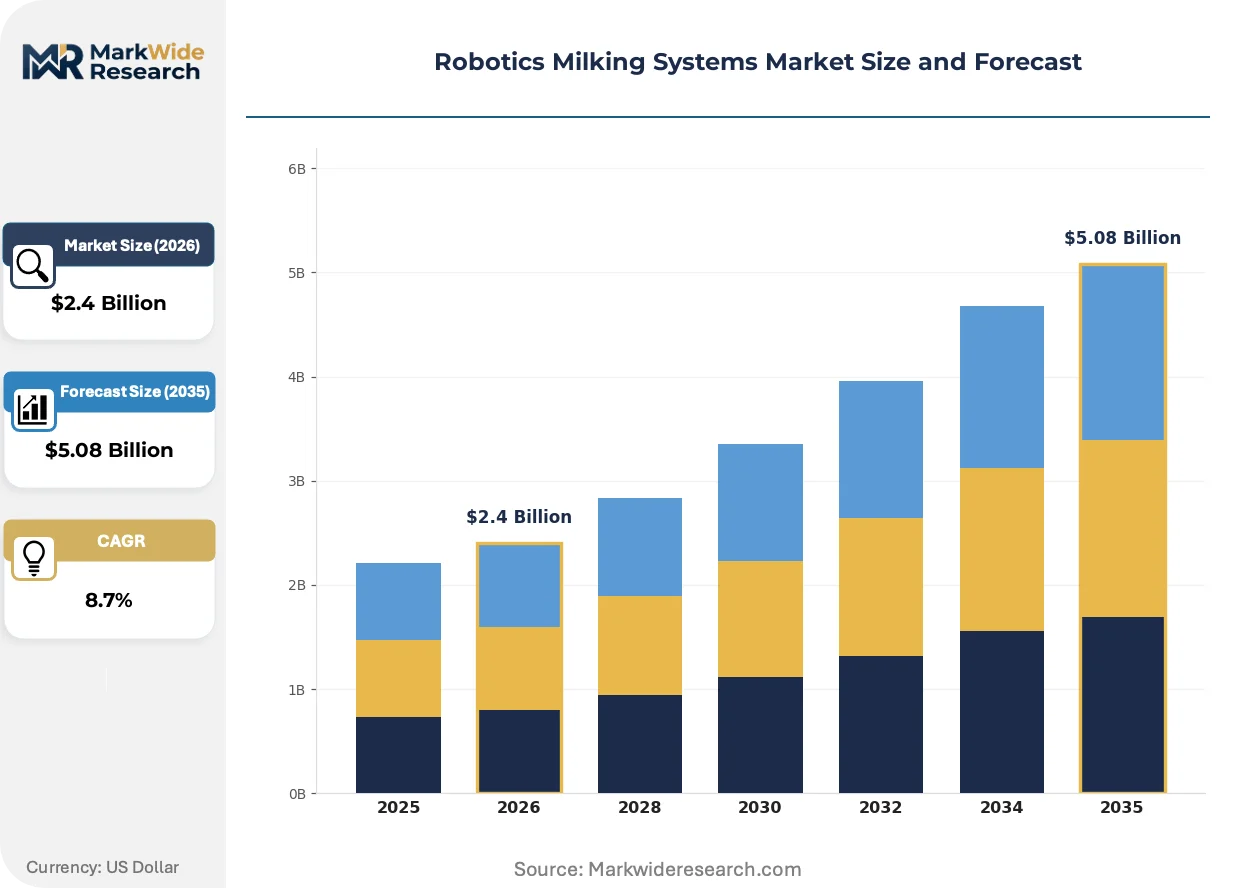
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $5.08 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
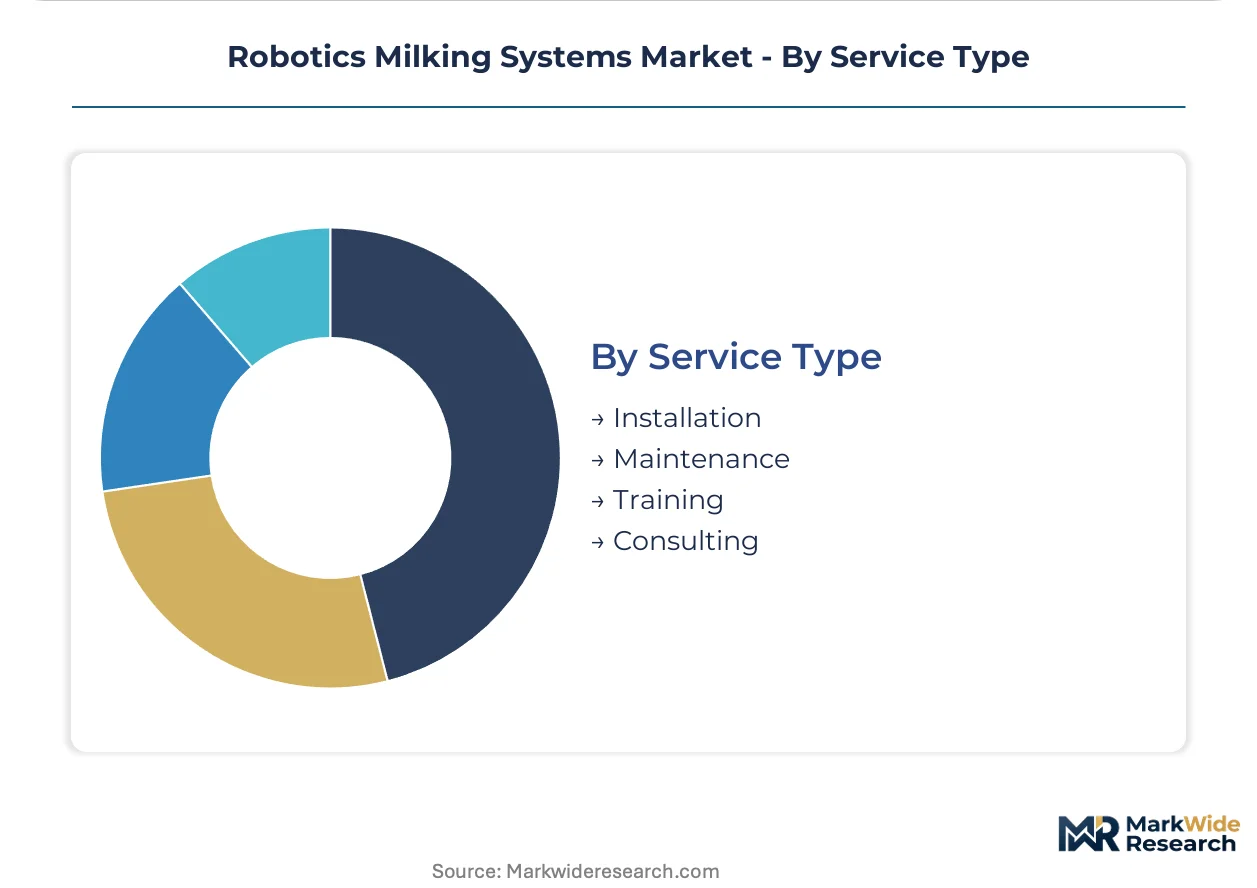
| Segmentation | Product Type: Robotic Milking Machines, Automated Milking Systems, Components, Sensors End User: Dairy Farms, Livestock Producers, Agricultural Cooperatives, Research Institutions Technology: Artificial Intelligence, Machine Learning, IoT, Data Analytics Service Type: Installation, Maintenance, Training, Consulting |
| Companies Covered | DeLaval, Lely, GEA Group Aktiengesellschaft, DAIRYMASTER, BouMatic, Fullwood JOZ, AMS Galaxy USA, Nedap N.V., System Happel GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Robotics Milking Systems Market Trends and Innovations
Edge computing architectures and machine-vision advances are redistributing analytical workloads from centralized servers to on-unit processors, collapsing latency for real-time teat identification and health monitoring decisions.
Computer vision is decentralizing milk quality assessment by embedding somatic cell counting and mastitis detection directly within robotic arm housings, eliminating laboratory sample transport delays. Large-scale operations in the Netherlands deploy these units to process individual cow data without batching delays. This compression of analytical workflow is decentralizing veterinary intervention timing from reactive treatment to pre-symptomatic isolation protocols.
The EU AI Act risk classification framework imposes conformity assessment obligations on automated milking systems employing machine learning for animal health predictions. Equipment manufacturers must document algorithmic transparency and bias mitigation measures to maintain CE marking validity. Dairy technology suppliers in Germany and Denmark accelerate in-house compliance teams to preempt notified body bottlenecks ahead of enforcement activation.
Cooperative procurement consortia displace direct manufacturer relationships as the dominant acquisition channel for mid-size farm segments. Agricultural cooperatives in Bavaria and Brittany aggregate demand across dozens of member operations to extract volume pricing and standardized service terms. This buyer-side consolidation concentrates negotiation leverage with regional supply cooperatives rather than individual farm enterprises.
Robotics Milking Systems Market Segmentation
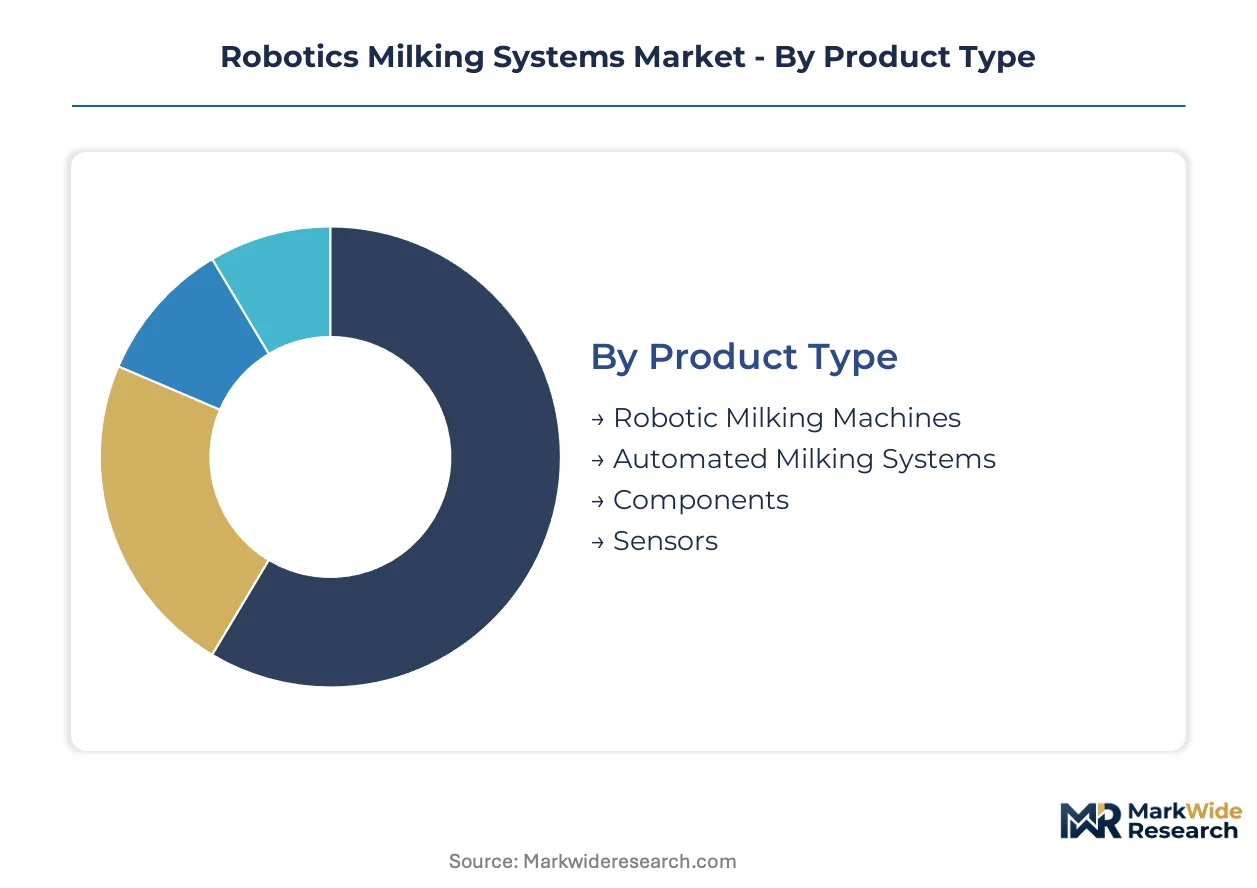
Segmentation in robotics milking systems reveals how capital intensity, technical complexity, and regulatory alignment fragment procurement patterns across dairy operations. Equipment vendors configure product portfolios around herd size thresholds, automation depth, and service bundling to match divergent buyer capabilities and compliance obligations.
Product Type:
Technical specification and integration depth separate premium installations from modular retrofits across European dairy operations.
- Robotic Milking Machines:Standalone units with articulated arms and optical teat detection process 60-70 cows per unit daily. Demand concentrates in the Netherlands where large-scale farms expand automated herd management capacity under tightening EU Farm to Fork emissions benchmarks.
- Automated Milking Systems:Free-traffic box configurations eliminate pre-milking labor, cutting staffing requirements by half on intensive operations converting from herringbone parlors. German dairy cooperatives in Lower Saxony drive retrofit demand as shared-equipment models collapse upfront cost barriers.
- Components:Modular robotic arms, vacuum pumps, and control units enable phased automation upgrades for capital-constrained mid-size farms.
- Sensors:Optical teat-detection modules and milk quality probes supply aftermarket replacement demand and legacy system upgrades.
Mature deployment sits with Robotic Milking Machines. Newer deployment is concentrated in Automated Milking Systems.
End User:
Buyer scale and capital access determine procurement channel selection and service bundling preferences.
- Dairy Farms:Private operations with 100+ cow herds anchor baseline demand for single-unit installations, prioritizing labor reduction and milk quality traceability.
- Livestock Producers:Integrated meat-dairy operations seek hybrid automation solutions spanning feeding, milking, and health monitoring functions.
- Agricultural Cooperatives:Bavaria and Brittany consortia aggregate demand across dozens of member operations to extract volume pricing and standardized service terms, gaining share fastest among mid-size farm segments.
- Research Institutions:Wageningen University and Danish agricultural universities pilot next-generation AI teat identification and predictive health algorithms.
Direct manufacturer relationships dominate Dairy Farm procurement. Cooperative procurement channels are displacing traditional sales models in Agricultural Cooperatives.
Technology:
Algorithmic capability and data processing location differentiate competitive positioning among equipment suppliers.
- Artificial Intelligence:Machine learning models for predictive mastitis detection and estrus alerting create subscription revenue streams beyond hardware sales. Edge computing architectures redistribute analytical workloads to on-unit processors, collapsing latency for real-time decisions in Dutch large-scale operations.
- Machine Learning:Supervised learning models trained on historical herd data optimize milking frequency and feed rations per individual cow.
- IoT:Sensor networks connect robotic units to centralized herd management platforms, enabling remote monitoring and predictive maintenance alerts.
- Data Analytics:Cloud-based dashboards aggregate multi-unit performance metrics for cooperative managers overseeing distributed farm networks.
Proprietary algorithm development concentrates in Artificial Intelligence. Open-standard integration is advancing fastest in IoT.
Service Type:
Post-installation revenue models shift from transactional break-fix contracts to outcome-based performance guarantees.
- Installation:Barn retrofitting, concrete work, and software integration require specialized mechatronics technicians scarce across rural Germany and Poland.
- Maintenance:Preventive service contracts covering robotic arm calibration, sensor replacement, and vacuum system optimization generate recurring revenue.
- Training:Operator certification programs and farm staff upskilling address skill gaps in AI-generated health alert interpretation.
- Consulting:Herd management optimization and carbon accounting compliance advisory expand margins for vendors with veterinary and regulatory expertise.
Break-fix maintenance dominates legacy contracts. Outcome-based performance guarantees are emerging in Installation and Maintenance bundling.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Wageningen anchors robotics milking deployment density, hosting research consortia that pilot next-generation teat identification algorithms for commercial translation across Northern European dairy corridors.
Netherlands
Friesland's large-scale farms expand automated herd management capacity under binding EU Farm to Fork emissions deadlines. CE marking mandates for machine safety accelerate replacement cycles for aging tie-stall parlors. Wageningen University clusters pilot AI-driven health monitoring systems for commercial scaling.
Germany
Lower Saxony dairy cooperatives retrofit conventional herringbone setups with free-traffic box configurations, pooling capital across member operations. The F-Gas Regulation refrigerant phase-down forces cooling equipment upgrades alongside robotic installations. Bavarian procurement consortia extract volume pricing through aggregated demand.
Denmark
Jutland's intensive operations prioritize labor reduction through automated milking systems processing 60-70 cows per unit. National veterinary drug residue protocols align with FDA-grade documentation requirements for automated data logs. Aarhus University agricultural departments validate predictive mastitis detection algorithms.
Poland
Masovian dairy sectors access EU structural funds to finance first robotic installations as herd sizes scale beyond manual milking viability. The country's national agricultural regulator harmonizes equipment certification with CE marking standards. Greater Warsaw clusters attract vendor service hubs for Central European expansion.
United States
Wisconsin and California dairy operations leverage USDA Environmental Quality Incentives Program cost-sharing for precision livestock equipment. Grade A dairy facility recertification demands extensive automated milking data logs for veterinary drug residue compliance. Midwest cooperative networks evaluate shared-equipment models tested in European markets.
Robotics Milking Systems Market Competitive Landscape
Premium-margin players sit above commodity-margin players across sensor accuracy and post-installation service depth. The vendor base concentrates around three strategic archetypes: vertically integrated system integrators controlling captive component supply, algorithm-focused specialists monetizing subscription health analytics, and manufacturing-scale producers anchoring mid-tier price points. Dominant competitive moves include cooperative procurement channel capture and edge computing capability integration for latency reduction.
Among European-based system integrators, DeLaval and Lely occupy positions at the premium tier, while GEA Group Aktiengesellschaft exemplifies manufacturing-scale competition for mid-size farm segments. DeLaval represents vertically controlled supply chain execution across Northern European installations. Lely anchors algorithm-centric positioning through proprietary herd management platforms extending beyond milking functions. GEA Group Aktiengesellschaft sits within the scale-driven archetype where price sensitivity constrains full automation deployment.
| Leading Market Players |
|---|
| DeLaval |
| Lely |
| GEA Group Aktiengesellschaft |
| DAIRYMASTER |
| BouMatic |
| Fullwood JOZ |
| AMS Galaxy USA |
| Nedap N.V. |
| System Happel GmbH |
| Others |
Pricing and Supply Chain Analysis
Stainless steel and precision sensor input costs flow through three distinct pricing tiers, with optical teat-detection modules and robotic arm actuators anchoring premium configurations while commodity-grade vacuum pumps and control units populate economy segments.
Pricing Analysis
Throughput-based pricing anchors vendor quotations, with DeLaval and Lely commanding per-cow-daily premiums tied to guaranteed uptime and milk quality yield commitments. Price differentiation separates CE-marked installations with full algorithmic health suites from basic robotic units lacking predictive mastitis detection. Pricing pressure stems from shared-equipment cooperative procurement in Lower Saxony and Brittany, where aggregated volume discounts compress vendor margins. Agricultural cooperatives exhibit highest price sensitivity due to pooled capital constraints, while Netherlands-based large-scale farms prioritize performance guarantees over upfront cost.
Supply Chain Analysis
Direct-to-farm channels handle premium installations for 100+ cow herds, while cooperative procurement consortia in Bavaria and Lower Saxony aggregate demand across dozens of member operations. Component manufacturing concentrates in Germany, the Netherlands, and Denmark, with precision optical sensors sourced from specialized suppliers in Jutland and robotic arm assemblies fabricated in North Rhine-Westphalia. Supply chain risk centers on single-source dependency for AI-enabled edge computing processors subject to CE marking and EU AI Act conformity bottlenecks. Distribution runs through manufacturer-direct sales teams for large farms and agricultural cooperative networks for mid-size segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Free-traffic box configurations are displacing conventional herringbone parlors across intensive dairy operations, compressing the transition window for equipment vendors and farm operators alike.
For Market Incumbents: Lock in cooperative procurement channel control through exclusive service bundling and predictive health algorithm subscriptions, countering emerging algorithm specialists threatening margin pools. Prioritize backward integration into optical sensor manufacturing to reduce exposure to stainless steel price volatility and precision component lead time uncertainty.
For New Entrants and Emerging Players: Begin with modular component supply to mid-size Polish and Romanian dairy sectors accessing EU structural funds, where first-mover positioning precedes regulatory harmonization completion. Target retrofit installation services for legacy parlor upgrades, exploiting mechatronics technician scarcity that forces reliance on external service providers.
For Investors and Strategic Acquirers: USDA Environmental Quality Incentives Program cost-sharing expansion is the leading indicator that Midwest cooperative networks will accelerate robotic adoption, signaling long-term demand viability across the 5-10 year horizon. Prioritize acquisition targets with proprietary edge computing architectures and FDA-aligned data logging capabilities for Grade A facility compliance.
| Strategic Initiative | Industry Significance |
|---|---|
| Algorithmic Health Suite Development | Predictive mastitis detection creates recurring subscription revenue beyond hardware sales for DeLaval and Lely. |
| Cooperative Procurement Channel Capture | Bavaria and Brittany consortia concentrate buyer leverage, displacing direct manufacturer relationships in mid-size segments. |
| Edge Computing Architecture Integration | On-unit processing collapses latency for real-time teat identification in Wageningen pilot deployments. |
| CE Marking and EU AI Act Compliance Investment | Conformity assessment obligations for machine learning health predictions preserve market access validity. |
| Service Technician Network Expansion | Mechatronics skill scarcity in rural Germany and Poland forces reliance on manufacturer service contracts. |
Research Methodology
Independent corroboration across equipment vendor technical specifications, EU regulatory filings, and USDA program documentation underwrites the qualitative findings. Primary interviews with dairy farm operators, agricultural cooperative procurement managers, and veterinary health technology specialists combined with secondary validation from CE marking databases, F-Gas Regulation implementation reports, and EU Farm to Fork Strategy progress assessments. Bottom-up installation data triangulates against top-down market sizing from trade association statistics and equipment shipment records.
Rate-of-change decomposition separates hardware unit growth from software and services expansion across the projection horizon. Segmentation dimensions modeled include product type, end-user category, technology tier, and service bundling configuration, with herd size thresholds and regulatory compliance intensity as industry-specific cross-cutting variables. CAGRs derive from installed base evolution, replacement cycle compression, and cooperative procurement penetration curves, incorporating EU structural fund disbursement timelines and F-Gas Regulation enforcement phasing as forecast inputs.
Underlying measurement precision varies by segment; Agricultural Cooperatives and AI-enabled technology tiers carry tighter precision than Components and Sensors aftermarket categories due to data availability disparities. Forecasts reflect assumptions about regulatory enforcement timing, input cost stabilization, and technician training pipeline expansion that warrant periodic stress-testing of base assumptions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Livestock Equipment
Cattle Feeder Panels Market
Livestock Equipment
Cattle Farm Equipment Market
Livestock Equipment
Cattle Handling Systems Market
Livestock Equipment
Silage Tube Market
Livestock Equipment
Electric Fencing Market
Livestock Equipment
Animal Cage Market
Livestock Equipment
Chicken Feeder and Drinkers Market
Livestock Equipment
Animal Workstations Market
Livestock Equipment
Horse Grain Feeders Market
Livestock Equipment
Cattle Grooming Chute Market
Livestock Equipment
Poultry Feeder Market
Livestock Equipment
Livestock Trailers Market
Livestock Equipment
Bird Feeding and Watering Suppliers Market
Livestock Equipment
Sheep Supplies Market
Livestock Equipment
Egg Incubator Market
Livestock Equipment
Hog Feeder Market