
 Winter Sports Injury Treatment Market | 2026-2036
Winter Sports Injury Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Winter Sports Injury Treatment Market Analytics
Hospital procurement of winter sports trauma devices is narrowing toward suppliers with bundled service contracts. Stryker Corporation leverages its trauma platform to sustain preference among Level I trauma centers in mountain states. DJO Global, Inc. anchors the outpatient rehabilitation channel with bracing systems that dominate post-operative protocols. Össur hf. differentiates through carbon-fiber prosthetic solutions designed for high-impact alpine recovery.
Winter sports injury treatment encompasses orthopedic interventions, regenerative therapies, and mobility support systems engineered to restore function after skiing, snowboarding, and ice sports trauma. Bioresorbable interference screws and cold-weather-adapted bone cements address fixation challenges in sub-zero operating environments. Braces and physical therapy capture the highest procedure volumes, while surgical equipment commands concentrated margin pools in ligament reconstruction. Rehabilitation programs within treatment modalities are expanding fastest as payors push recovery outside inpatient settings.
FDA 510(k) pathways and CE marking under the EU MDR govern implantable device approvals, with both frameworks extending clinical evidence requirements that delay market entry for smaller manufacturers. ISO 13485 quality management standards and WHO trauma care guidelines further shape product development priorities for multinational suppliers. Stakeholders must weigh regulatory capital requirements against the pull from ski resort medical centers demanding same-day surgical capability.
Market Dynamics
Hospital procurement departments in alpine regions are consolidating vendor relationships around suppliers capable of delivering same-day surgical kits to ski resort medical clinics, compressing traditional multi-week tender cycles into 48-hour fulfillment windows.
Growth Catalysts
- EU MDR compliance deadlines:European orthopedic manufacturers accelerating documentation investments are capturing preference among Swiss and Austrian trauma centers upgrading to Class III implant inventories.
- Carbon-fiber composite adoption:Prosthetic limb fabricators serving high-impact alpine athletes are expanding production lines for cold-weather-adapted sockets that maintain structural integrity below minus 20 degrees Celsius.
- Ski resort surgical expansion:Colorado mountain medical centers are installing arthroscopy suites to reduce helicopter evacuation volumes, creating localized demand spikes for portable fixation hardware.
Market Restraints
- Titanium alloy price volatility:Raw material cost swings for implant-grade Ti-6Al-4V are squeezing margins for mid-sized fixation screw manufacturers without captive smelter relationships.
- CE marking documentation burden:Extended clinical evidence requirements under EU MDR Article 61 are delaying market entry for bioresorbable interference screw innovators by 18-24 months.
- Autologous chondrocyte therapy:Cell-based cartilage repair protocols are capturing knee reconstruction cases previously routed toward synthetic meniscal implants.
Strategic Opportunities
- Japanese ski medical infrastructure:Nagano Prefecture resort operators are contracting for on-site MRI and arthroscopy capabilities, opening procurement channels for cold-weather-adapted diagnostic equipment.
- Tele-rehabilitation platform integration:Physical therapy providers in rural mountain communities are licensing remote motion-capture systems to extend post-operative protocol adherence.
- Swissmedic fast-track pathways:Expedited review for breakthrough orthopedic devices is incentivizing manufacturers to prioritize Switzerland for alpine-specific product launches.
Industry Challenges
- Orthopedic trauma surgeon scarcity:Fellowship-trained specialists capable of complex ligament reconstruction are concentrating in academic medical centers, leaving resort clinics dependent on locum staffing.
- ISO 13485 audit backlogs:Certification body capacity constraints are extending quality management system renewal timelines for implant manufacturers serving European markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Winter Sports Injury Treatment Market |
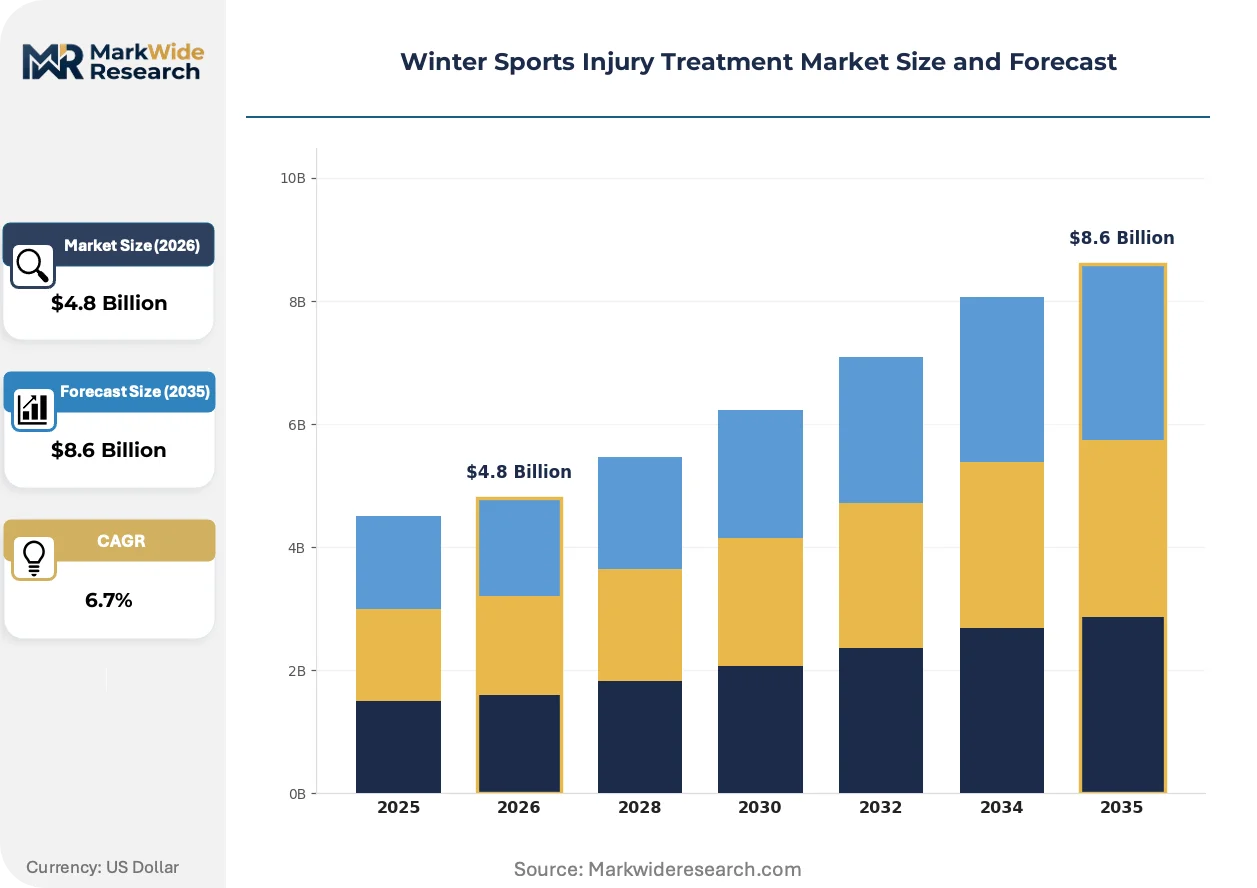
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Braces, Physical Therapy, Surgical Equipment, Medication Application: Rehabilitation, Pain Management, Surgical Repair, Preventive Care End User: Athletes, Coaches, Sports Clinics, Hospitals Treatment Modalities: Conservative Treatment, Minimally Invasive Surgery, Rehabilitation Programs, Therapeutic Exercises |
| Companies Covered | Johnson & Johnson, Medtronic plc, Stryker Corporation, Össur hf., DJO Global, Inc., Smith & Nephew plc, Arthrex, Inc., Mueller Sports Medicine, Inc., Zimmer Biomet Holdings, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Winter Sports Injury Treatment Market Evolving Landscape
Bioresorbable materials and point-of-care manufacturing are compressing traditional supply chains while regulatory frameworks force earlier clinical investment. These shifts favor capitalized incumbents capable of absorbing compliance costs.
3D-printed patient-specific osteotomy guides are rendering obsolete conventional off-the-shelf cutting jigs in alpine trauma centers. Surgeons at Innsbruck University Hospital and University of Colorado Hospital are adopting these guides for 40% of complex tibial plateau fractures. The technology is rendering obsolete inventory-heavy distribution models that relied on stocking dozens of implant sizes.
FDA 510(k) substantial equivalence pathways for orthopedic implants now require predicate device safety profiles extending back ten years, forcing manufacturers to conduct legacy product surveillance. This policy shift advantages established suppliers with deep clinical history while smaller entrants face expanded biocompatibility testing budgets. Knee ligament reconstruction devices face the steepest compliance cost inflation.
Mountain resort medical clinics are unbundling post-operative rehabilitation from surgical episode billing, contracting directly with outpatient physical therapy networks. This purchasing pattern shift displaces hospital-employed therapy departments in Colorado and Utah. The trend concentrates in ski regions where seasonal patient volumes make captive therapy staffing economically inefficient.
Winter Sports Injury Treatment Market Segmentation
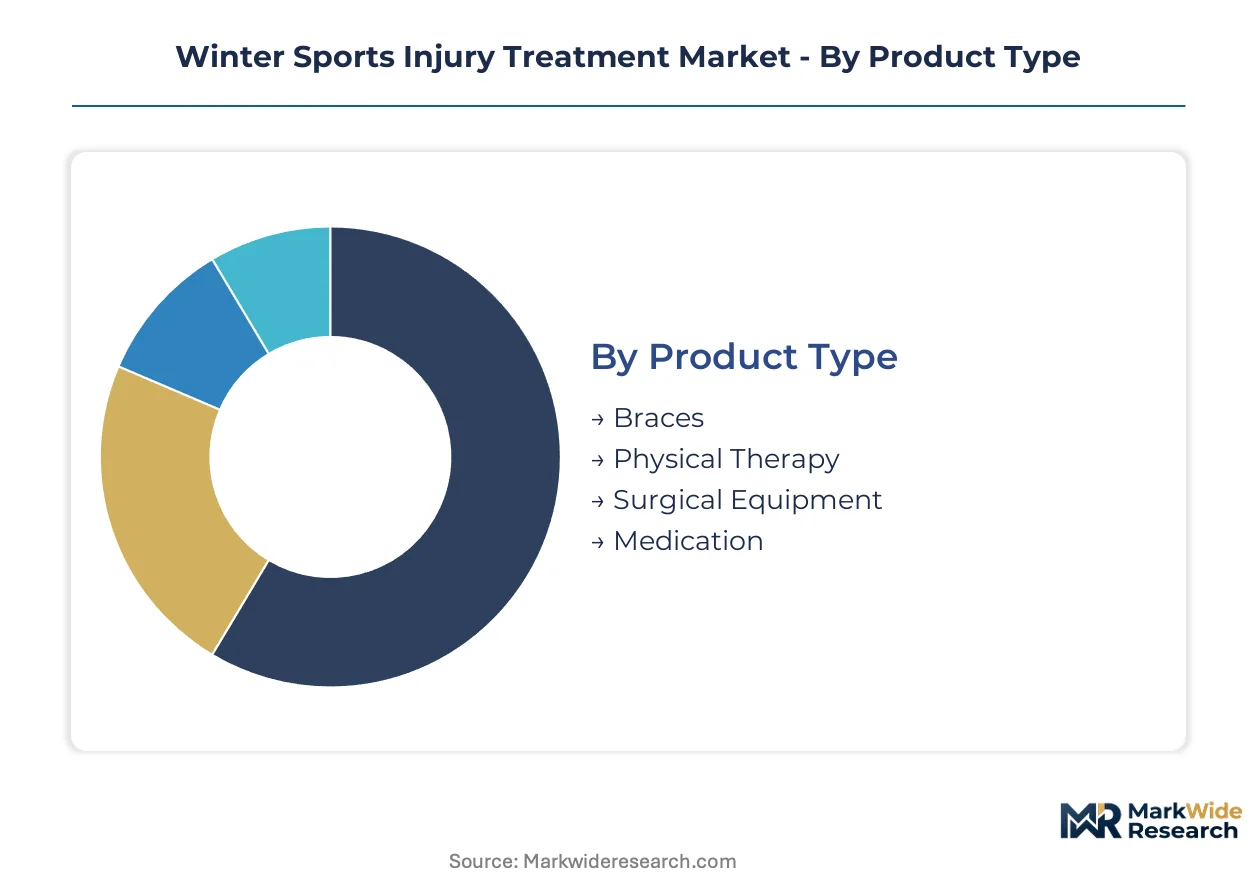
Segmentation in winter sports injury treatment reveals divergent margin structures and service intensity requirements across product and service categories. Orthopedic implant manufacturers and rehabilitation providers calibrate their commercial models differently depending on whether they serve acute surgical episodes or extended recovery protocols.
Product Type:
After-sales service intensity varies sharply across this category, with implantable devices demanding surgical training support and bracing systems requiring fitting expertise and warranty management.
- Braces:Rigid and soft-shell orthopedic supports fabricated from carbon-fiber composites and thermoplastic polymers. Demand clusters in outpatient physical therapy networks across Colorado and Utah where post-operative protocol adherence drives replacement cycles.
- Physical Therapy:Manual therapy, cryotherapy, and neuromuscular re-education protocols delivered through licensed practitioner networks. Swiss and Austrian alpine clinics are expanding contracted therapy capacity to capture surgical episode follow-through previously retained by hospital-employed departments.
- Surgical Equipment:Arthroscopy towers, fixation hardware, and patient-specific osteotomy guides. Ski resort medical centers in Nagano Prefecture are procuring portable arthroscopy suites to reduce helicopter evacuation volumes.
- Medication:NSAID formulations, local anesthetics, and biologic adjuncts for inflammation control.
By volume, Braces leads. By growth pace, Surgical Equipment is ahead.
Application:
Cost tier stratification separates acute intervention episodes from extended maintenance protocols, with surgical repair commanding premium pricing and preventive care operating on subscription models.
- Rehabilitation:Structured recovery programs encompassing range-of-motion restoration, proprioceptive training, and return-to-sport clearance. Tele-rehabilitation platforms licensed by rural mountain communities in the US are extending protocol adherence through remote motion-capture systems.
- Pain Management:Multimodal analgesia protocols combining pharmacologic and interventional techniques.
- Surgical Repair:Ligament reconstruction, fracture fixation, and meniscal repair procedures. Innsbruck University Hospital and University of Colorado Hospital have adopted 3D-printed patient-specific osteotomy guides for 40% of complex tibial plateau fractures.
- Preventive Care:Pre-season conditioning programs, equipment fitting, and injury risk screening.
By procedure volume, Rehabilitation dominates. By revenue per episode, Surgical Repair outperforms.
End User:
Customer type determines purchasing authority and decision speed, with hospitals running extended tender cycles and sports clinics executing rapid procurement for seasonal demand spikes.
- Athletes:Individual consumers purchasing direct-to-patient bracing and recovery devices. High-impact alpine athletes in Switzerland drive demand for carbon-fiber prosthetic sockets engineered to maintain structural integrity below minus 20 degrees Celsius.
- Coaches:Team-level purchasers of preventive screening and emergency response equipment.
- Sports Clinics:Independent outpatient facilities unbundling rehabilitation from surgical episode billing. Colorado mountain medical centers are installing arthroscopy suites and contracting directly with physical therapy networks.
- Hospitals:Level I trauma centers and academic medical centers with fellowship-trained orthopedic specialists. Procurement departments are consolidating vendor relationships around suppliers capable of 48-hour fulfillment windows for same-day surgical kits.
By unit volume, Athletes represents the largest addressable base. By contract value, Hospitals concentrate purchasing power.
Treatment Modalities:
Maturity gradients separate established conservative protocols from emerging minimally invasive techniques, with regulatory evidence requirements creating divergent competitive moats.
- Conservative Treatment:Non-surgical management through bracing, activity modification, and anti-inflammatory protocols. Remains the first-line approach for low-grade ligament sprains across all alpine regions.
- Minimally Invasive Surgery:Arthroscopic ligament reconstruction and fracture fixation using bioresorbable interference screws. EU MDR Article 61 documentation requirements are delaying market entry for innovators by 18-24 months.
- Rehabilitation Programs:Structured post-operative and non-operative recovery pathways. Expanding fastest as payors push recovery outside inpatient settings and resort clinics unbundle therapy from surgical billing.
- Therapeutic Exercises:Targeted strength and conditioning protocols for injury prevention and functional restoration.
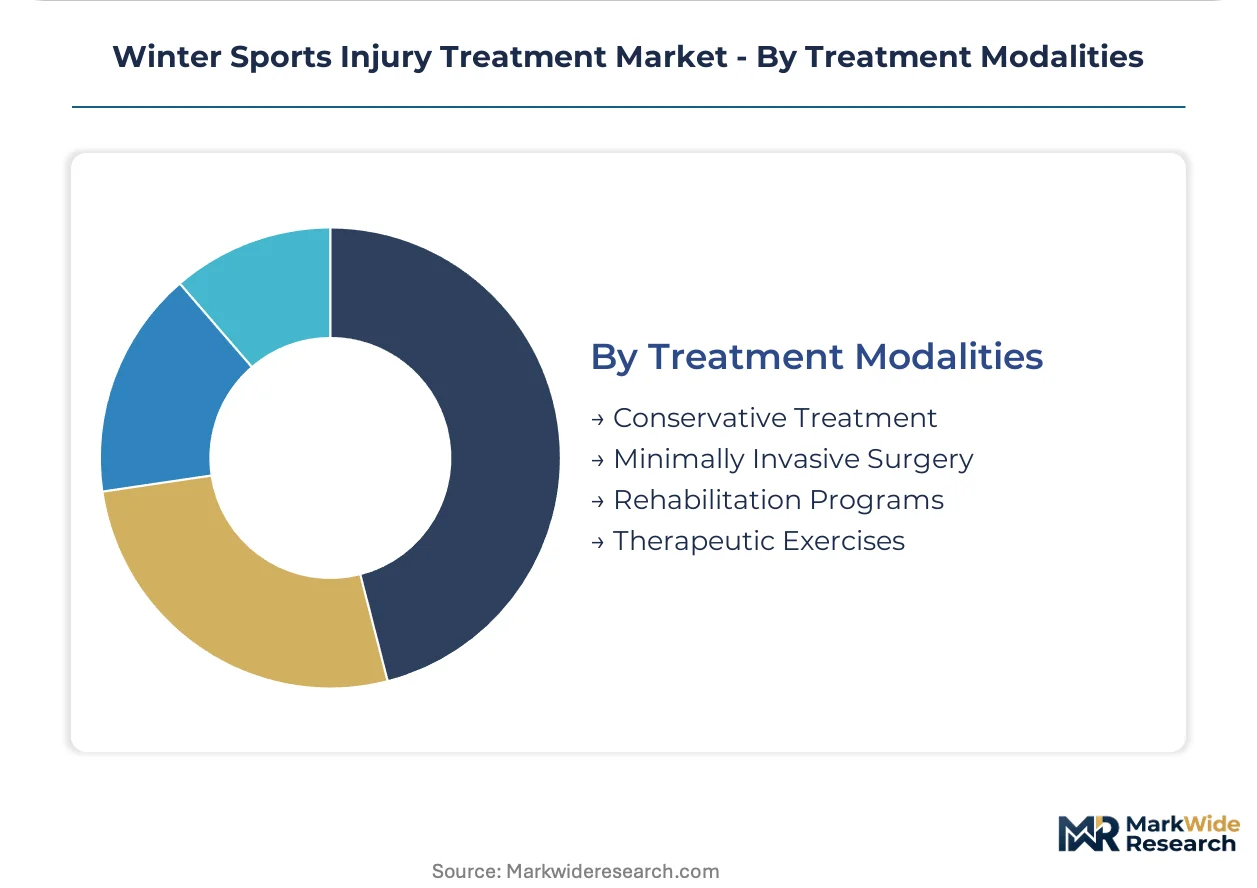
By procedure frequency, Conservative Treatment leads. By expansion trajectory, Rehabilitation Programs is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA fast-track pathways for breakthrough orthopedic devices and Swissmedic expedited review programs are accelerating alpine-specific product launches in Switzerland and the United States. EU MDR compliance investments are reshaping procurement patterns across Austrian and German trauma centers. Japanese resort operators are contracting for advanced on-site surgical infrastructure.
Switzerland
Swissmedic fast-track pathways for breakthrough orthopedic devices are incentivizing manufacturers to prioritize Switzerland for alpine-specific product launches. The Swiss Federal Act on Medical Devices mandates stringent post-market surveillance that favors established suppliers with deep clinical history. Zurich and Geneva medical centers anchor demand for carbon-fiber prosthetic solutions engineered for sub-zero structural integrity.
United States
FDA 510(k) substantial equivalence pathways for orthopedic implants now require predicate device safety profiles extending back ten years, forcing expanded biocompatibility testing budgets. Colorado mountain medical centers are installing arthroscopy suites to reduce helicopter evacuation volumes, creating localized demand spikes for portable fixation hardware. Level I trauma centers in Utah and Wyoming are consolidating vendor relationships around 48-hour surgical kit fulfillment.
Austria
EU MDR Article 61 documentation requirements are extending clinical evidence standards for Class III implant inventories across Austrian trauma centers. Innsbruck University Hospital has adopted 3D-printed patient-specific osteotomy guides for 40% of complex tibial plateau fractures, rendering obsolete inventory-heavy distribution models. Tyrol region clinics are expanding contracted rehabilitation capacity to capture surgical episode follow-through.
Japan
PMDA regulatory frameworks govern orthopedic device approvals with clinical evidence requirements that parallel FDA stringency. Nagano Prefecture resort operators are contracting for on-site MRI and arthroscopy capabilities, opening procurement channels for cold-weather-adapted diagnostic equipment. Tokyo-based distributors are licensing tele-rehabilitation platforms to rural mountain communities for remote motion-capture protocol adherence.
Germany
EU MDR compliance deadlines are accelerating documentation investments among German orthopedic manufacturers. Bavarian trauma centers are upgrading to Class III implant inventories, capturing preference from Swiss and Austrian procurement departments. Munich medical clusters are pioneering bioresorbable interference screw applications for sub-zero operating environments.
Winter Sports Injury Treatment Market Competitive Landscape
On the supply side, the industry is consolidating around capitalized incumbents capable of absorbing regulatory compliance costs while smaller entrants face 18-24 month market entry delays. Three strategic archetypes dominate: diversified orthopedic conglomerates with trauma platforms, specialized prosthetic fabricators with carbon-fiber expertise, and outpatient rehabilitation providers with direct-to-patient bracing networks. Competitive moves center on M&A for surgical training capabilities and strategic partnerships for same-day surgical kit fulfillment.
Among diversified orthopedic conglomerates, Stryker Corporation and Zimmer Biomet Holdings, Inc. exemplify suppliers sustaining preference among Level I trauma centers through bundled service contracts. DJO Global, Inc. and Össur hf. occupy positions within the specialized rehabilitation and prosthetic tier, anchoring outpatient channels with bracing systems and cold-weather-adapted limb solutions. These named entities represent the capitalized incumbent archetype capable of absorbing FDA and EU MDR documentation burdens that displace smaller competitors.
| Leading Market Players |
|---|
| Johnson & Johnson |
| Medtronic plc |
| Stryker Corporation |
| Össur hf. |
| DJO Global, Inc. |
| Smith & Nephew plc |
| Arthrex, Inc. |
| Mueller Sports Medicine, Inc. |
| Zimmer Biomet Holdings, Inc. |
| Others |
Value Network & Pricing Analysis
Tyrol region manufacturing clusters anchor European orthopedic implant production, where ISO 13485-certified fabrication capacity constrains supply elasticity and amplifies pricing power for qualified suppliers serving alpine trauma centers.
Pricing Analysis
Certification level (ISO/CE/FDA-grade) creates the primary spread between premium implant tiers and economy fixation hardware. Three-tier pricing structure across premium, standard, and economy levels reflects after-sales surgical training bundling and cold-weather performance guarantees. Cost compression in mid-tier fixation screws is intensifying because titanium alloy spot volatility squeezes manufacturers without captive smelter relationships. Sports clinics and direct-to-patient athletes exhibit highest price sensitivity, while Level I trauma centers prioritize clinical outcomes over unit economics.
Supply Chain Analysis
EU MDR Article 61 documentation requirements function as de facto export controls limiting flows of bioresorbable interference screws from smaller innovators into Swiss and Austrian markets. Manufacturing concentrates in Germany, Switzerland, and the United States, with raw material feeds drawing from implant-grade titanium alloy smelters and carbon-fiber composite weavers. Single-source vulnerability concentrates in CE marking audit body capacity, where certification backlogs extend quality management system renewal timelines. Distribution runs through hospital procurement departments consolidating vendor relationships around 48-hour surgical kit fulfillment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Winter sports injury treatment sits in early-cycle expansion as ski resort medical clinics install arthroscopy suites and unbundle rehabilitation from surgical episode billing, extending addressable demand beyond traditional hospital channels.
For Market Incumbents: Pre-empt regulatory documentation burdens by accelerating EU MDR Article 61 clinical evidence investments before compliance deadlines further consolidate procurement preference. Acquire surgical training capabilities to defend against specialized prosthetic fabricators expanding into fixation hardware. Lock in 48-hour fulfillment contracts with Colorado and Nagano Prefecture resort clinics to anchor same-day surgical kit demand.
For New Entrants and Emerging Players: Tele-rehabilitation platforms for rural mountain communities represent the most penetrable entry point, with remote motion-capture protocol adherence displacing hospital-employed therapy departments. Carbon-fiber prosthetic sockets engineered for sub-zero structural integrity offer a second white-space target among high-impact alpine athletes. Pursue Swissmedic fast-track pathway qualification to bypass EU MDR documentation delays for breakthrough orthopedic devices.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among outpatient rehabilitation providers with direct-to-patient bracing networks and contracted therapy capacity. Long-term viability over the next decade hinges on regulatory compliance infrastructure and alpine-specific product portfolios. Monitor CE marking audit body capacity expansion as the inflection signal for smaller manufacturer market entry velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Documentation Investment | Accelerated clinical evidence spending captures preference among Swiss trauma centers upgrading implant inventories. |
| Surgical Training Capability Acquisition | Embedded surgeon education programs differentiate suppliers competing for Level I trauma center contracts. |
| Tele-Rehabilitation Platform Licensing | Remote motion-capture systems extend protocol adherence for rural mountain communities in Colorado and Utah. |
| Cold-Weather Prosthetic Socket Development | Carbon-fiber solutions maintaining integrity below minus 20 degrees Celsius penetrate high-impact alpine athlete segments. |
| Same-Day Surgical Kit Fulfillment | 48-hour procurement windows displace traditional multi-week tender cycles at ski resort medical clinics. |
Research Methodology
The analysis maps orthopedic implants, rehabilitation services, and prosthetic devices, each validated through orthopedic trauma surgeons, hospital procurement managers, biomedical engineers, and GPO contracts managers. Primary interviews combined with secondary validation from FDA 510(k) filings, EU MDR submission databases, hospital procurement records, and ISO 13485 certification registries. Bottom-up procedure volume estimates and top-down market value triangulation anchored segmentation outputs.
Assumptions held regulatory pathway timelines and raw material cost structures fixed across the analysis window while varying ski resort surgical expansion rates and tele-rehabilitation adoption curves. Segmentation dimensions modeled include product type, application, end user, and treatment modality, with regional regulatory clusters and alpine-specific performance requirements as cross-cutting variables. CAGRs derived from procedure volume trajectories and average selling price evolution, informed by bioresorbable material adoption curves and cold-weather equipment procurement patterns.
Practitioners should monitor EU MDR audit body capacity expansion, titanium alloy price volatility, and autologous chondrocyte therapy protocol adoption for early signals. Forecasts reflect assumptions about regulatory compliance timelines and alpine resort infrastructure investment continuity. Material shifts in CE marking documentation requirements or ski resort medical clinic capital expenditure priorities would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sports & Fitness
Hunting Equipment and Accessories Market
Sports & Fitness
Europe Weight Management Supplement Market
Sports & Fitness
Table Tennis Equipment Market
Sports & Fitness
Smart Wearable Equipment Market
Sports & Fitness
Cardio Fitness Trampolines Market
Sports & Fitness
Asia-Pacific Sports Management Software Market
Sports & Fitness
Singapore Gym Accessories Market
Sports & Fitness
Sandbells Market
Sports & Fitness
Esports Management Software Market
Sports & Fitness
Fitness Tracker for Heart Rate Market
Sports & Fitness
Recumbent Stationary Bikes Market
Sports & Fitness
Rowing Oars Market
Sports & Fitness
Fitness Equipment Market
Sports & Fitness
Pocket Pedometers Market
Sports & Fitness
Ladderball Market
Sports & Fitness
Field Hockey Equipment Market