
 Rowing Oars Market | 2026-2036
Rowing Oars Market Size, Share, and Industry Trends Forecast 2026-2036
Rowing Oars Market Outlook
Carbon fiber specification-tier upgrades is reorganizing the rowing oars competitive landscape. Concept2 Inc. leverages its manufacturing scale to dominate North American institutional channels. Empacher GmbH anchors premium competitive segments through precision German engineering. Croker Oars Pty Ltd. competes across sculling and sweep disciplines with specialized Australian production.
Rowing oars are lever-based propulsion tools comprising a shaft, blade, and handle, typically manufactured from carbon fiber pre-preg layups or laminated wood to achieve specific flexural rigidity measured in stiffness ratings, designed to transfer athlete power into hull forward motion across racing shells and recreational boats. Carbon fiber oars command the fastest expansion within product type segments as national federations mandate equipment standardization for championship eligibility. Composite material formulations capture widening margin pools as manufacturers blend glass fiber with carbon to balance cost against performance in training-grade equipment. Standard length configurations between 8 ft and 10 ft remain the volume anchor across both sweep and sculling disciplines.
FISA equipment certification standards govern blade geometry and shaft dimensions for international competition eligibility, while ISO 12217 small craft stability requirements influence recreational oar design safety margins. Germany's KBA and France's ANSM do not directly regulate rowing equipment, though EU REACH compliance on resin systems affects carbon fiber manufacturing supply access. Stakeholders must monitor evolving national federation equipment lists and material substance restrictions to anticipate product line certification requirements.
Market Dynamics
Carbon fiber specification-tier upgrades is reorganizing the rowing oars competitive landscape as aerospace manufacturing techniques transfer into recreational and competitive equipment, compressing traditional wood-laminate production while elevating performance benchmarks across institutional procurement channels.
Growth Catalysts
- University program expansion:Competitive rowing programs at collegiate and club levels are expanding equipment procurement budgets as athletic departments prioritize crew program visibility and recruitment competitiveness.
- EU REACH compliance:Resin system standardization under REACH is streamlining carbon fiber supply access for European manufacturers, reducing material qualification barriers for new market entrants.
- FISA equipment certification:International federation standardization mandates for blade geometry and shaft dimensions are forcing equipment upgrades as national federations align championship eligibility requirements.
Market Restraints
- Carbon fiber input volatility:Pre-preg composite material costs fluctuate with aerospace sector demand cycles, compressing margin predictability for oar manufacturers dependent on specialized fiber grades.
- German supply concentration:Dense equipment replacement cycles concentrate demand in German coastal and inland rowing clubs, creating geographic dependency risk for manufacturers without diversified regional exposure.
- Wood-laminate substitution ceiling:Traditional laminated wood oars retain cost advantages in recreational segments, limiting carbon fiber penetration in price-sensitive training equipment categories.
Strategic Opportunities
- Glass-carbon hybrid formulations:Composite material blending technologies enable margin expansion in training-grade equipment by balancing performance against cost in club-level procurement segments.
- ISO 12217 safety alignment:Recreational boat stability standard adoption creates design specification openings for manufacturers developing safety-margin-compliant oar systems for non-competitive markets.
- Direct institutional channels:Bypassing traditional distributor networks through university athletic department direct relationships captures procurement budget visibility and reduces channel margin leakage.
Industry Challenges
- FISA certification timeline compression:International federation equipment list updates require rapid product line recertification, straining quality assurance and documentation capabilities at smaller manufacturers.
- Stiffness rating calibration expertise:Flexural rigidity measurement standardization demands specialized engineering talent scarce in traditional boatbuilding regions, constraining product development velocity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Rowing Oars Market |
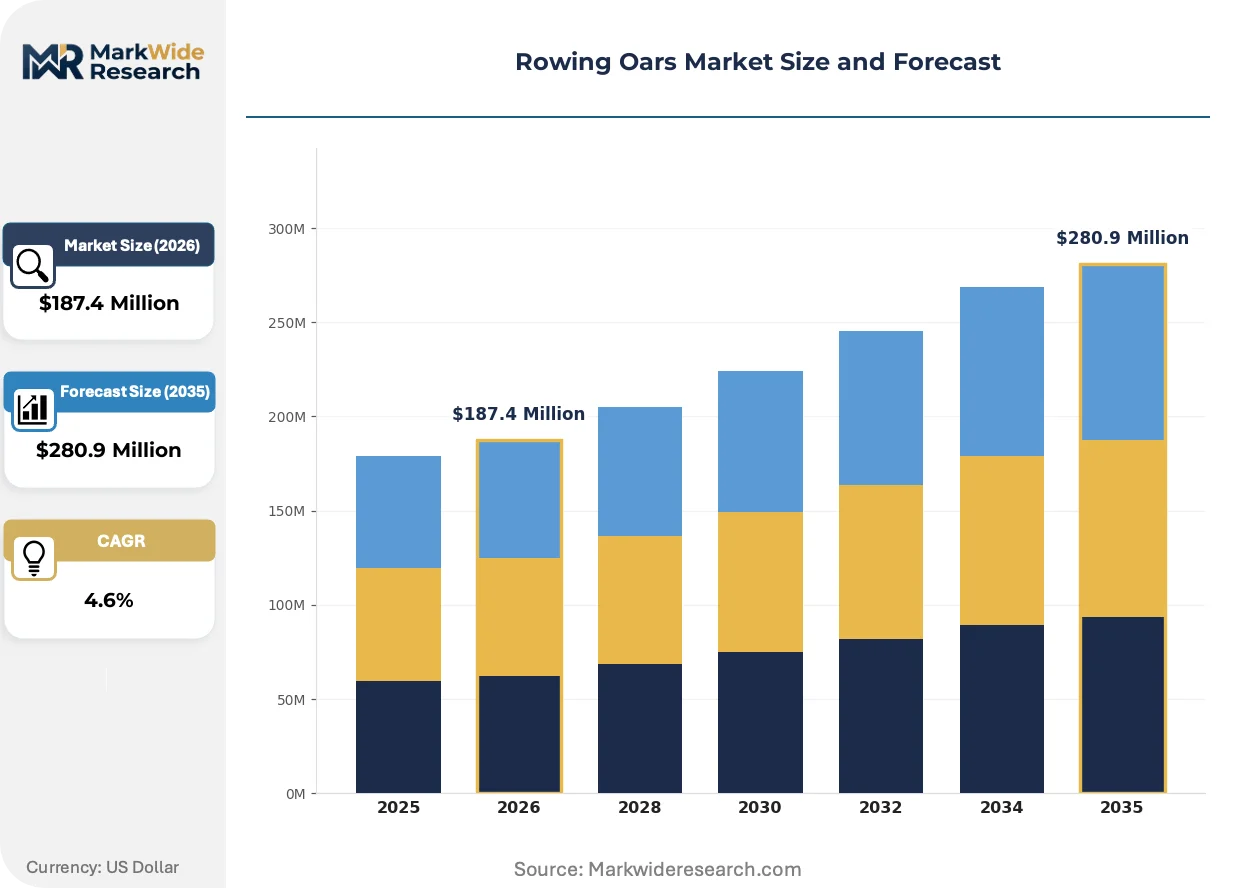
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $280.9 Million |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sculling Oars, Sweep Oars, Wooden Oars, Carbon Fiber Oars Use Case: Recreational Boating, Competitive Rowing, Training, Water Sports Material: Wood, Carbon Fiber, Aluminum, Composite Length: Short (Less than 8 ft), Standard (8 ft - 10 ft), Long (Above 10 ft), Custom |
| Companies Covered | Concept2 Inc., Croker Oars Pty Ltd., WinTech Racing, Braca-Sport, Empacher GmbH, Sykes Racing, Filippi Lido S.R.L., Vespoli USA, BBG Bootsbau Berlin GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Rowing Oars Market Strategic Shifts
Manufacturing technique migration from aerospace and automotive sectors is actively reshaping material science and production economics in rowing equipment, with implications for competitive positioning and procurement patterns across institutional and recreational segments.
Automated fiber placement is decomposing traditional hand-layup carbon fiber production methods in premium oar shaft manufacturing. National federation equipment programs and elite training centers are adopting these shafts at accelerating rates as stiffness-to-weight ratios improve measurably. This technology is decomposing the cost structure advantage previously held by established manual-layup specialists, forcing capability investments or margin compression across tier-one suppliers.
EU REACH substance restrictions on epoxy resin systems are tightening formulation requirements for carbon fiber pre-preg suppliers serving European oar manufacturers. Industrial consequence includes supply base consolidation as smaller chemical compounders exit compliant formulation development. German and French manufacturers face accelerated raw material qualification timelines, with competitive rowing equipment categories most affected as clubs demand documented substance compliance for championship eligibility.
Club-level procurement committees are consolidating purchasing authority previously dispersed across individual boat captains and volunteer equipment managers. This buyer concentration is disrupting traditional specialty retailer relationships as aggregated volume contracts migrate toward manufacturer-direct arrangements. The shift is most visible in German university and municipal rowing associations, where centralized tender processes now dominate equipment replacement cycles.
Rowing Oars Market Segmentation
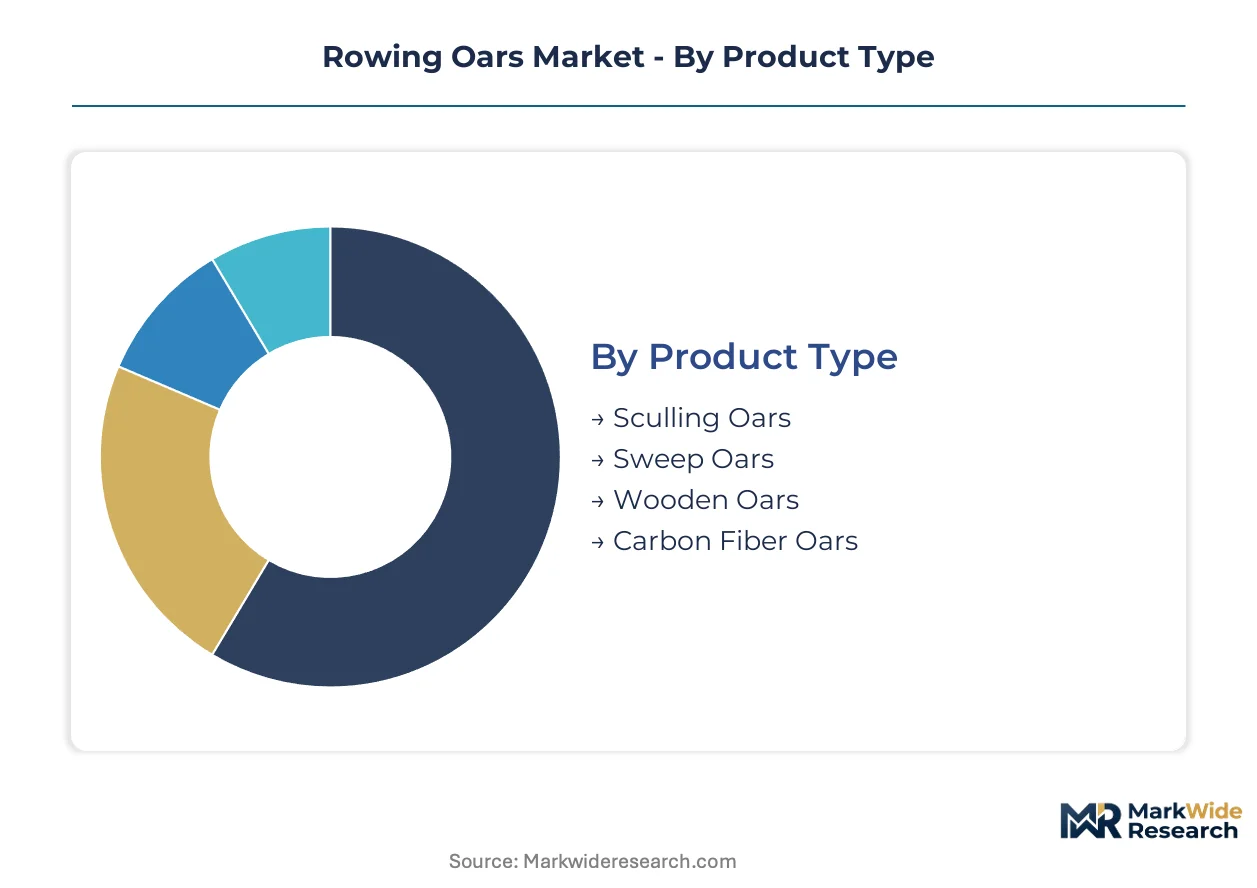
Segmentation in rowing oars reveals how procurement authority concentrates across institutional buyers and how material science investments map to performance tiering. Price elasticity varies dramatically between recreational and competitive channels.
Product Type:
Margin pools concentrate in carbon fiber specification tiers where aerospace manufacturing transfers command pricing power.
- Carbon Fiber Oars:Automated fiber placement from aerospace manufacturing improves stiffness-to-weight ratios measurably. National federations mandate equipment standardization for championship eligibility, concentrating procurement in German and Australian elite training centers.
- Sculling Oars:Paired oars operated by single athletes demand precise flexural rigidity calibration across shaft lengths. University programs in Germany and the United States drive replacement cycles as competitive recruitment intensifies.
- Sweep Oars:Single oars per rower in crew boats prioritize durability under high-load conditions.
- Wooden Oars:Laminated construction retains cost advantages in recreational and training segments.
The dominant share belongs to carbon fiber oars, while sculling oars are closing the gap fastest through university program expansion.
Use Case:
Application segmentation tracks how buyer authority consolidates from individual boat captains toward centralized procurement committees.
- Competitive Rowing:FISA certification requirements force equipment upgrades as national federations align championship eligibility. German coastal and inland clubs maintain dense replacement cycles.
- Training:Glass-carbon hybrid formulations balance performance against cost in club-level procurement. Aggregated volume contracts now dominate German university and municipal associations.
- Recreational Boating:ISO 12217 stability standards influence design safety margins for non-competitive markets.
- Water Sports:Casual use segments prioritize durability over stiffness optimization.
Competitive rowing captures the premium tier, with training applications expanding most quickly through institutional budget growth.
Material:
Supply base consolidation under EU REACH compliance is restructuring raw material access across European manufacturers.
- Carbon Fiber:Pre-preg composite formulations face qualification timeline compression as smaller chemical compounders exit compliant development. German manufacturers face accelerated documentation requirements.
- Composite:Glass-carbon blending technologies enable margin expansion in training-grade equipment. Club procurement segments adopt these formulations for cost-performance balance.
- Wood:Traditional laminated construction serves price-sensitive recreational demand.
- Aluminum:Metal shafts retain niche presence in rental and institutional durability applications.
Carbon fiber leads value contribution, while composite materials gain share fastest through training segment adoption.
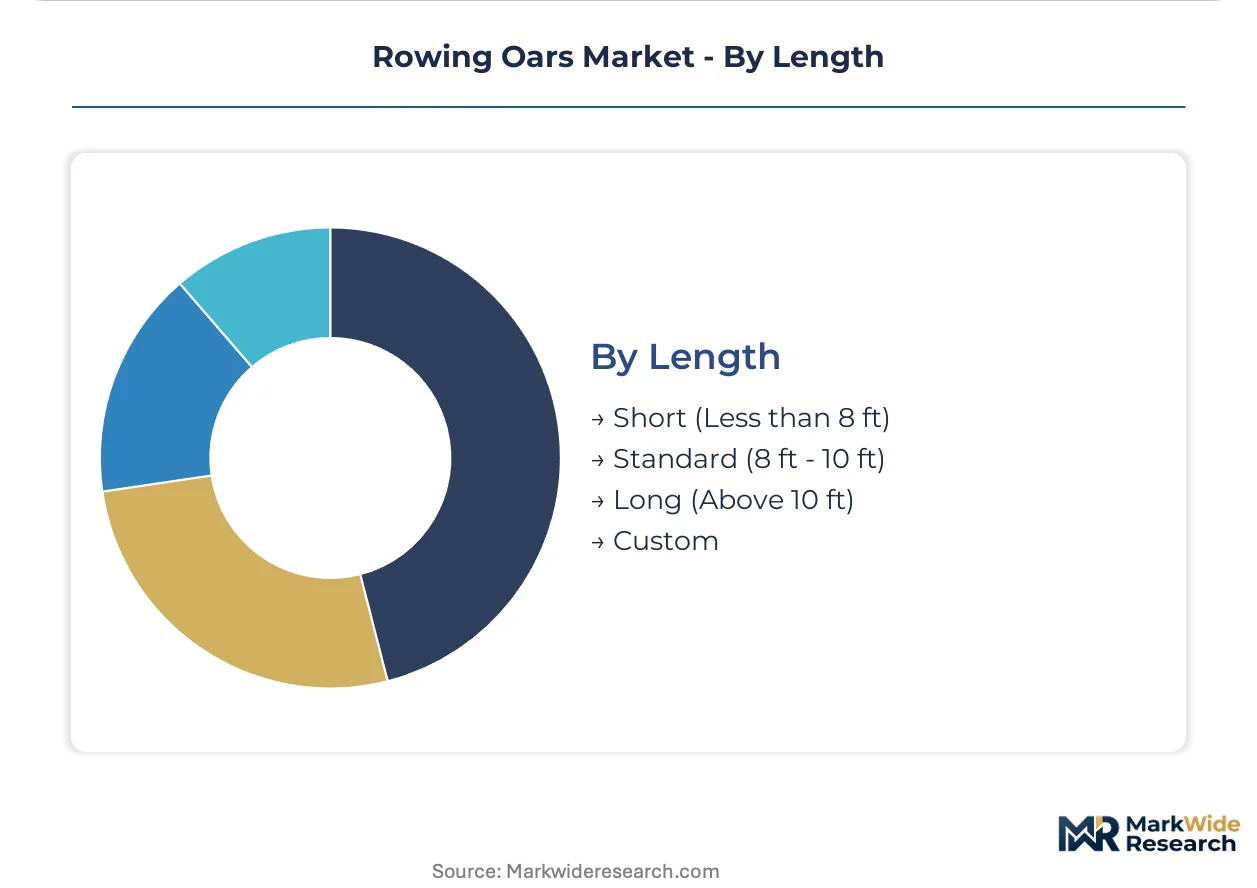
Length:
Configuration standardization reduces inventory complexity for manufacturers serving institutional channels.
- Standard (8 ft - 10 ft):Volume anchor across sweep and sculling disciplines. FISA dimensional mandates reinforce this specification as the procurement default.
- Custom:Athlete-specific flexural rigidity tuning serves elite competitive segments. National training centers commission shaft modifications for individual biomechanics.
- Short (Less than 8 ft):Specialized junior and adaptive rowing applications.
- Long (Above 10 ft):Extended leverage configurations for specific hull designs.
Standard lengths dominate procurement volume, with custom specifications climbing fastest through elite program specialization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German manufacturers export carbon fiber oars across European club networks while Australian and North American producers serve regional demand through localized production. Import dependency concentrates in specialized pre-preg composite formulations where aerospace-grade suppliers maintain limited qualified vendor lists. Trade flows follow competitive rowing federation procurement calendars with equipment certification timelines dicting seasonal shipment patterns.
Germany
Coastal and inland rowing clubs in Hamburg and Berlin maintain dense equipment replacement cycles driven by municipal sports budget allocations. KBA vehicle safety standards do not directly regulate rowing equipment, though EU REACH compliance on epoxy resin systems shapes carbon fiber manufacturing supply access. The Ruhr industrial corridor hosts precision engineering clusters transferring aerospace automation techniques into oar shaft production.
United States
University athletic departments in Boston and Philadelphia expand crew program procurement budgets as collegiate rowing visibility intensifies recruitment competition. NCAA governance structures influence equipment standardization timelines without direct regulatory mandate. The Pacific Northwest manufacturing corridor around Seattle concentrates automated fiber placement capability serving institutional channels.
Australia
Sculling and sweep discipline specialization drives demand from Melbourne and Sydney club networks with strong national federation equipment programs. The country's national chemical regulator enforces substance compliance documentation affecting carbon fiber pre-preg import qualification. Gold Coast composites clusters supply regional training-grade equipment through glass-carbon hybrid formulations.
United Kingdom
Oxford and Cambridge collegiate programs anchor premium equipment demand with documented replacement cycles tied to boat fleet modernization. British Rowing federation equipment lists mandate FISA-aligned certification for championship eligibility, compressing manufacturer recertification timelines. The Thames Valley corridor concentrates specialist boatbuilders integrating oar procurement with hull manufacturing.
Italy
Veneto and Lombardy lake rowing clubs sustain steady equipment turnover through regional sports association centralized purchasing. CE marking requirements on recreational small craft influence safety margin specifications for training-grade oar systems. The Como industrial district hosts precision metalworking clusters supporting custom shaft modification services for elite programs.
Rowing Oars Market Competitive Environment
Concentration sits with precision-engineering specialists and scaled composite manufacturers serving distinct procurement tiers. The vendor base separates into three strategic archetypes: German-engineered premium specialists, North American institutional-scale producers, and Australian discipline-focused fabricators. Competitive moves center on automated fiber placement capability investments and direct university athletic department relationship cultivation bypassing traditional distributor networks.
Among German-engineered specialists, Empacher GmbH exemplifies precision manufacturing archetypes through its GmbH structure, while Concept2 Inc. anchors the institutional-scale tier with North American production reach. Croker Oars Pty Ltd. occupies a position within Australian sculling and sweep specialization, representing discipline-focused competitive positioning. These three entities collectively illustrate how geographic origin and corporate structure map to distinct procurement channel access.
| Leading Market Players |
|---|
| Concept2 Inc. |
| Croker Oars Pty Ltd. |
| WinTech Racing |
| Braca-Sport |
| Empacher GmbH |
| Sykes Racing |
| Filippi Lido S.R.L. |
| Vespoli USA |
| BBG Bootsbau Berlin GmbH |
| Others |
Value Chain & Pricing Dynamics
Ninety-day pre-preg carbon fiber lead times from aerospace-qualified suppliers compress margin flexibility for European oar manufacturers, concentrating pricing power with German and Australian producers who maintain bonded inventory positions. This inventory discipline separates institutional-grade suppliers from training-equipment competitors dependent on spot resin markets.
Pricing Analysis
University athletic department buyers anchor three-tier pricing structure across premium, standard, and economy levels in North American and German procurement channels. Price differentiation rests on FISA certification tier and automated fiber placement manufacturing depth, with certified competition shafts commanding substantial premiums over training-grade hybrids. Cost compression in recreational wooden oars intensifies as laminated construction retains cost advantages against entry-level carbon fiber. Club-level procurement committees exhibit highest price sensitivity, while national training centers demonstrate lowest sensitivity due to biomechanical customization requirements.
Supply Chain Analysis
Container availability constraints on Asia-Europe trade lanes elevate inbound logistics costs for Australian and Southeast Asian carbon fiber pre-preg suppliers serving European manufacturers. Raw material sourcing draws from Japanese and German aerospace-grade fiber producers, with epoxy resin systems qualified under EU REACH compliance. Single-source vulnerability concentrates in automated fiber placement equipment, where German and Italian machinery builders maintain limited qualified vendor lists. Distribution runs through manufacturer-direct channels for institutional buyers, while specialty retailers serve individual recreational consumers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Automated fiber placement engineering talent scarcity constrains product development velocity across mid-tier manufacturers, privileging incumbents with captive aerospace manufacturing relationships. This capability gap widens as national federations compress equipment recertification timelines.
For Market Incumbents: Compound automated fiber placement capability investments in Ruhr and Pacific Northwest engineering clusters to defend against emerging Asian composite specialists. Deepen backward integration into carbon fiber pre-preg formulation to offset aerospace demand cycle volatility. Prioritize direct university athletic department relationship cultivation bypassing distributor margin leakage. For New Entrants and Emerging Players: FISA certification fast-track partnerships with German and Australian national federations open procurement access in competitive rowing segments. Target glass-carbon hybrid formulation development for training-grade equipment where incumbent focus on premium tiers leaves white space. Pursue aggregated volume contracts with German municipal rowing associations as beachhead channel strategy. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified marine equipment conglomerates with underoptimized rowing oar divisions lacking automated manufacturing capability. Long-term viability favors precision-engineering specialists with documented FISA certification pipelines and university direct-channel relationships. Monitor national federation equipment list update frequency as inflection indicator for recertification-driven replacement cycle intensity.| Strategic Initiative | Industry Significance |
|---|---|
| Automated Fiber Placement Investment | Ruhr engineering clusters transfer aerospace techniques to oar shaft production, elevating stiffness-to-weight benchmarks. |
| FISA Certification Fast-Track | National federation partnerships compress equipment list approval timelines for competitive eligibility. |
| Backward Integration into Pre-Preg | In-house resin formulation qualification reduces EU REACH compliance documentation burden. |
| Direct Institutional Channel Development | University athletic department relationships capture procurement budget visibility and reduce distributor margin leakage. |
| Glass-Carbon Hybrid Formulation | Gold Coast composites clusters balance cost-performance for training-grade club procurement segments. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted across German coastal clubs, Australian national training centers, and North American university athletic departments. Primary interviews with equipment managers, composite manufacturing engineers, and federation technical directors combined with secondary validation from FISA equipment certification records, EU REACH substance databases, and customs trade flows. Bottom-up club-level procurement surveys triangulated against top-down manufacturer shipment data.
Across the projection horizon, the analytical framework modeled segmentation dimensions including material specification tier, use case intensity, and regional federation equipment program alignment. CAGRs derived from equipment replacement cycle analysis and procurement budget elasticity assessments. Forecast inputs incorporated university program expansion rates and automated manufacturing adoption curves.
Underlying assumptions cover stable aerospace carbon fiber supply access and FISA certification timeline continuity, with deviation risk concentrated in EU REACH formulation restrictions and national federation equipment mandate changes. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sports Equipment
Gym Shoes Market
Sports Equipment
Sports Protection Equipment Market
Sports Equipment
Sports Flooring Market
Sports Equipment
Soccer Gear Market
Sports Equipment
Gear Bicycle Market
Sports Equipment
Surface Water Sports Equipment Market
Sports Equipment
Kiteboarding Equipment Market
Sports Equipment
Balance Bike Market
Sports Equipment
Pitching Machine Market
Sports Equipment
Kick Scooter Tire Market
Sports Equipment
Speed Hurdle Market
Sports Equipment
Sports Devices Market
Sports Equipment
US Sports Flooring Market
Sports Equipment
China Sports Optic Market
Sports Equipment
Rubber Fitness Flooring Market
Sports Equipment
Sports Fishing Equipment Market