
 Fitness Equipment Market | 2026-2036
Fitness Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Fitness Equipment Market Analysis
Chinese fitness equipment manufacturing is consolidating around Guangdong and Zhejiang province clusters, tightening component sourcing for global brands. Technogym S.p.A. leverages its vertical integration across design, production, and digital services to sustain premium positioning in European commercial gyms. Johnson Health Tech Co. Ltd. anchors its competitive stance through manufacturing scale across Taiwan and mainland China facilities. Peloton Interactive Inc. differentiates via proprietary content- hardware integration, though it navigates channel complexity between direct-to-consumer and third-party retail.
Fitness equipment encompasses mechanical and electromechanical apparatus designed for cardiovascular conditioning, resistance training, and physical rehabilitation, typically constructed from powder-coated steel frames, thermoplastic housings, and belt-drive or magnetic resistance systems rated for duty cycles exceeding 10,000 hours in commercial settings. Its primary purpose spans consumer health maintenance, athletic performance development, and clinical physical therapy applications. Treadmills and ellipticals retain the largest installed base among product types, reflecting their accessibility for entry-level users and established gym floor economics. Smart equipment with wearable integration commands the fastest expansion within technology segments, as real-time biometric feedback redefines user engagement and subscription monetization. Home users now represent the most contested end-user category, with post-pandemic habit persistence blurring historical boundaries between residential and commercial procurement patterns.
Product safety mandates from the Consumer Product Safety Commission in the United States and CE marking requirements under the EU Machinery Directive establish baseline compliance thresholds for electrical safety and structural integrity, directly influencing design costs and market access timelines. The EU Green Deal's evolving ecodesign criteria are beginning to press manufacturers toward recyclable material content and energy-efficient motor specifications. Stakeholders must monitor how emerging AI-enabled coaching features trigger additional scrutiny under the EU AI Act's risk classification framework, particularly for equipment marketed with health diagnostic claims.
Market Dynamics
Connected fitness ecosystems are compressing equipment replacement cycles while forcing legacy manufacturers to absorb software development costs previously outside their competency. The collision between hardware durability expectations and digital service refresh rates is restructuring vendor economics across every price tier.
Growth Catalysts
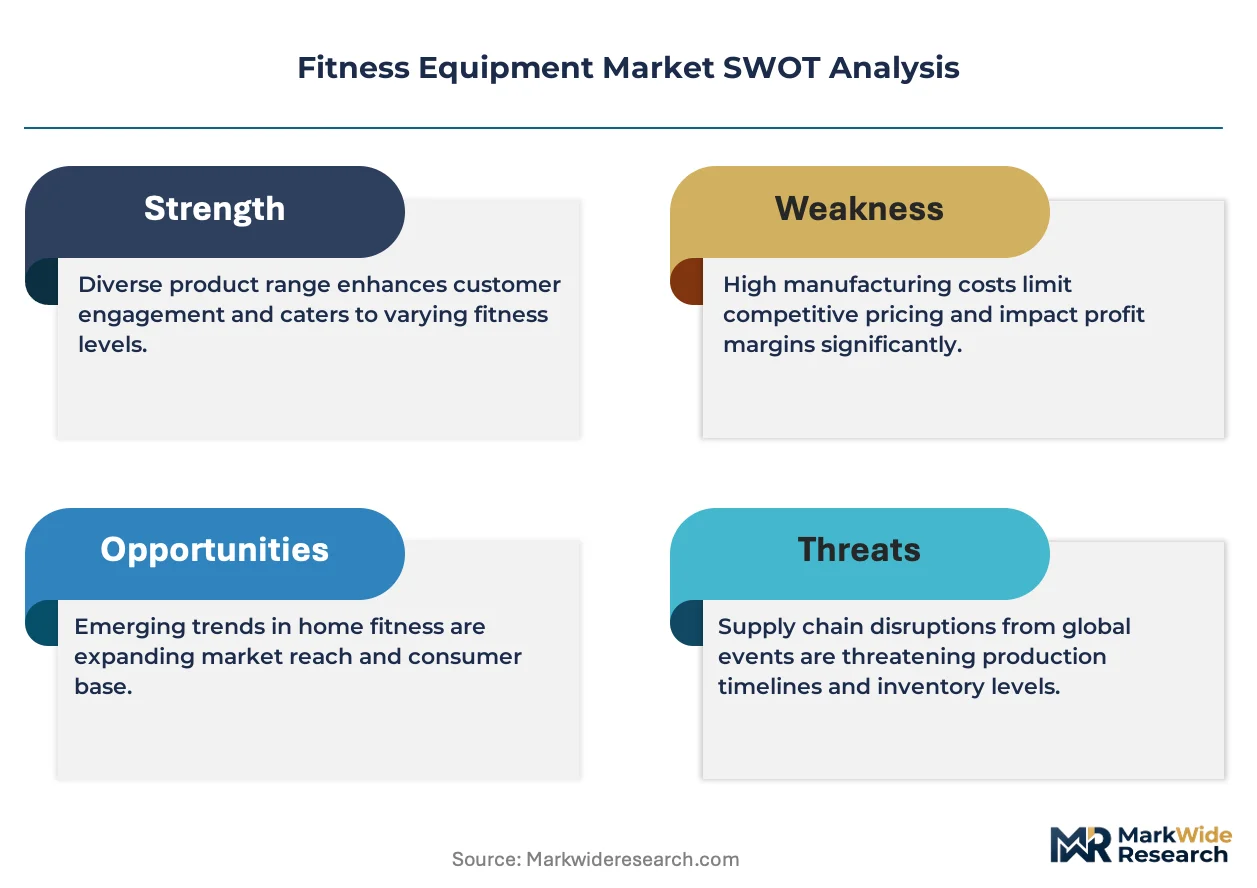
- EU AI Act compliance pathways:Equipment vendors incorporating biometric diagnostic features gain first-mover advantage in European commercial gym procurement as risk classification rules clarify liability frameworks.
- Home-based cardiac rehabilitation protocols:Hospital discharge programs in the United States now prescribe connected treadmills and ellipticals, creating institutional pull-through for residential smart equipment categories.
- Guangdong province component clustering:Concentrated motor controller and sensor manufacturing is shortening prototype-to-production timelines for brands with established supplier relationships in southern China.
Market Restraints
- Steel and rare-earth magnet cost volatility:Powder-coated frame materials and neodymium-based resistance systems face input price swings that compress gross margins on mid-tier equipment.
- Single-source dependency for Taiwan semiconductor fabrication:Motor control chip supply concentrates with foundries subject to geopolitical disruption risk, constraining production scaling.
- CE marking timeline friction:EU Machinery Directive conformity assessment for electromechanical equipment with wireless connectivity extends market entry lead times by four to eight months versus purely mechanical alternatives.
Strategic Opportunities
- India's PLI scheme for wearable devices:Domestic manufacturing incentives create cost-competitive assembly options for smart fitness equipment targeting price-sensitive Asian markets.
- Rehabilitation center digitization mandates:Physical therapy clinics in Germany and France face reimbursement pressure to demonstrate patient outcome metrics, opening demand for equipment with built-in progress tracking.
- Content-hardware bundling via streaming partnerships:Fitness platforms are expanding into equipment distribution through co-branded hardware, bypassing traditional retail markup structures.
Industry Challenges
- Embedded software engineering talent scarcity:Legacy equipment manufacturers lack in-house capability to maintain secure firmware update pipelines for cloud-connected devices.
- Biometric data governance complexity:HIPAA compliance for equipment capturing heart rate variability and metabolic estimates requires legal infrastructure most hardware vendors have not built.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fitness Equipment Market |
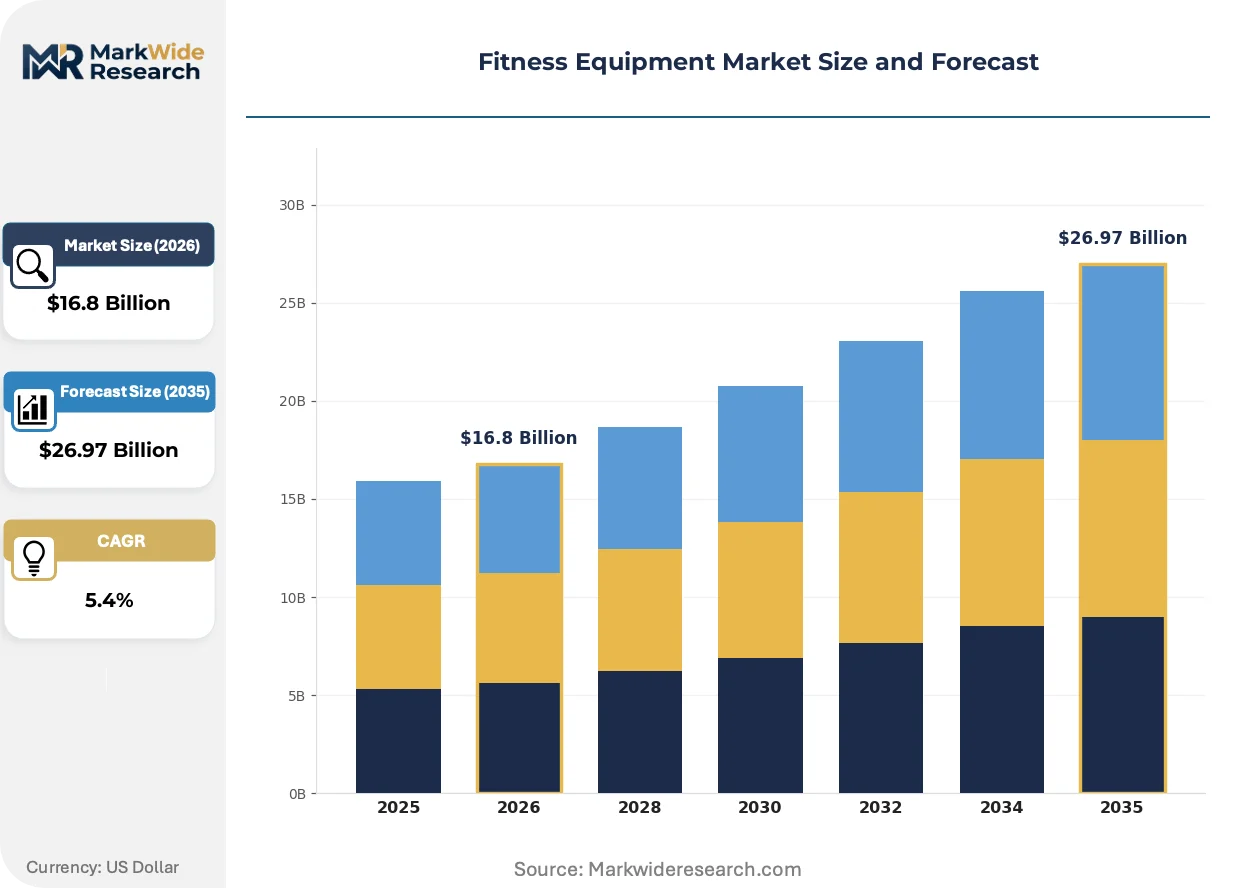
| Market Size in 2026 | $16.8 Billion |
| Market Size in 2035 | $26.97 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Treadmills, Ellipticals, Strength Machines, Free Weights End User: Home Users, Gyms, Health Clubs, Sports Teams Technology: Bluetooth-Enabled, Smart Equipment, Wearable Integration, Biometric Monitoring Distribution Channel: Online Retail, Specialty Stores, Direct Sales, Distributors |
| Companies Covered | Technogym S.p.A., Johnson Health Tech Co. Ltd., Life Fitness LLC, Icon Health & Fitness Inc., Core Health & Fitness LLC, Precor Incorporated, Nautilus Inc., Peloton Interactive Inc., Torque Fitness, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fitness Equipment Market Emerging Trajectories
Digital-native fitness platforms are rewriting equipment value propositions by unbundling hardware from content subscriptions. This structural separation is forcing incumbent manufacturers to choose between margin compression or capability acquisition.
Electromagnetic resistance systems are replacing mechanical flywheels in premium strength equipment. Commercial gyms in South Korea and Australia are adopting these systems for silent operation and precise load modulation. The technology is expanding into residential price tiers as Chinese motor manufacturers achieve cost parity with traditional friction-based alternatives.
REACH substance restrictions on persistent organic pollutants are pressuring manufacturers to reformulate powder coatings and cable sheathing. The EU Green Deal's evolving ecodesign criteria now cover standby power consumption for networked fitness equipment. Vendors targeting German and Nordic markets are redesigning power supplies to meet sub-one-watt idle requirements ahead of formal mandate deadlines.
Corporate wellness procurement departments are consolidating vendor relationships through multi-site equipment leasing arrangements. Fitness equipment distributors in the United States are responding by building service networks capable of same-day technician dispatch across metropolitan footprints. This behavior is most visible in Texas and California, where technology sector employers compete for talent through amenity differentiation.
Fitness Equipment Market Segmentation
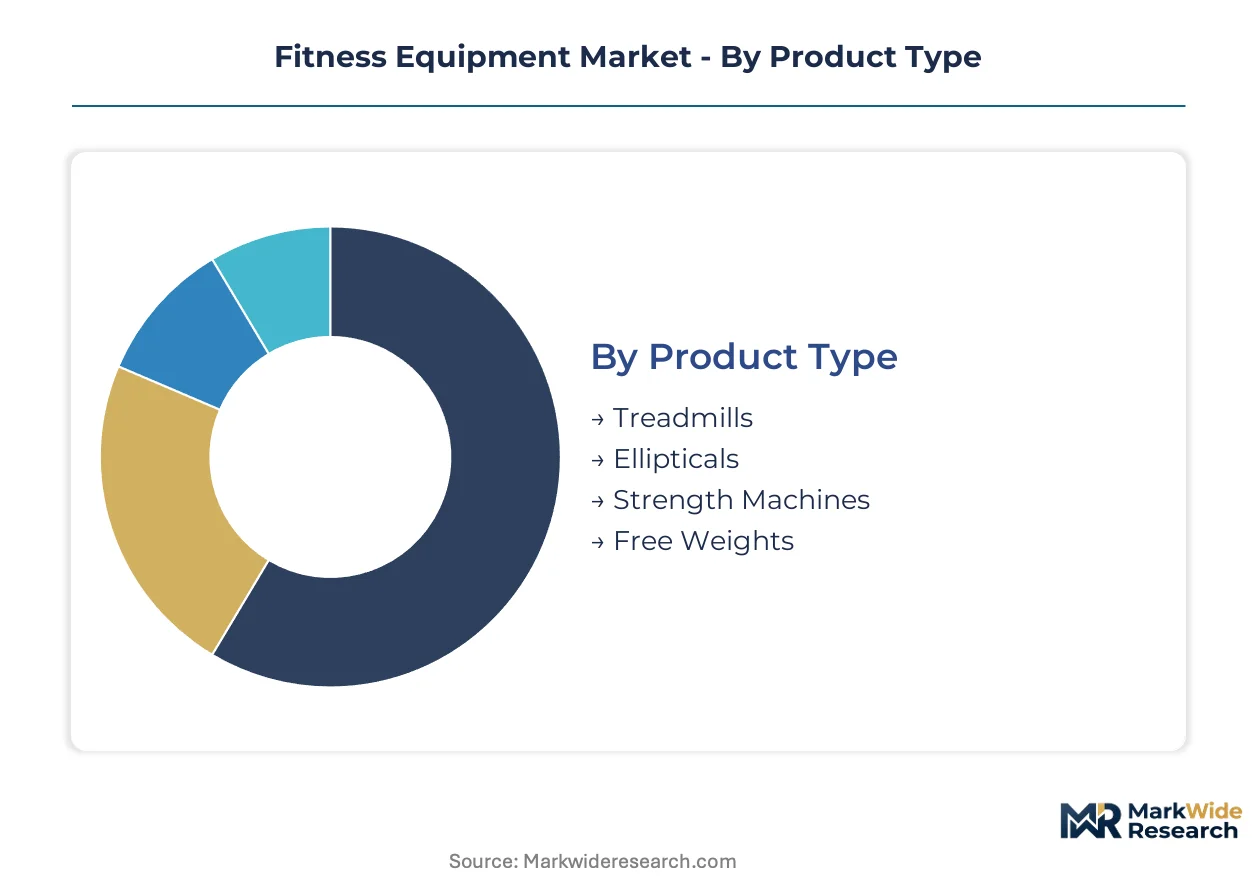
Segmentation reveals divergent equipment replacement dynamics across user environments. Home fitness ecosystems compress hardware refresh cycles through software dependency, while commercial installations prioritize durability metrics and service contract structures.
Product Type:
Upgrade cycles vary sharply by mechanical complexity and connected feature integration.
- Treadmills:Belt-drive motor systems with powder-coated steel frames dominate commercial gym floors. Demand clusters in United States hospital discharge programs prescribing home-based cardiac rehabilitation protocols.
- Ellipticals:Low-impact magnetic resistance configurations serve entry-level residential users and aging populations. German and French physical therapy clinics drive procurement for equipment with built-in progress tracking capabilities.
- Strength Machines:Selectorized weight stacks and cable systems anchor commercial facility layouts.
- Free Weights:Cast iron and rubber-coated dumbbells, barbells, and plate sets retain longest replacement cycles.
Volume placements concentrate in Treadmills; the faster expansion belongs to Smart Equipment-enabled Ellipticals.
End User:
Customer type determines margin structure and service intensity requirements.
- Home Users:Residential purchasers prioritize space efficiency and content subscription bundling. Texas and California technology sector employers compete for talent through amenity differentiation, pulling premium equipment into home office configurations.
- Gyms:Multi-site commercial operators consolidate vendor relationships through leasing arrangements with same-day technician dispatch requirements.
- Health Clubs:Premium wellness facilities demand electromagnetic resistance systems for silent operation.
- Sports Teams:Professional and collegiate athletic programs specify load modulation precision for periodized training protocols.
Procurement volume concentrates in Gyms; Health Clubs represent the steepest expansion trajectory for connected equipment categories.
Technology:
Feature integration is restructuring competitive economics across price tiers.
- Bluetooth-Enabled:Basic wireless connectivity for heart rate strap pairing and mobile app synchronization. China's Guangdong province component clustering shortens production timelines for brands with established supplier relationships.
- Smart Equipment:Embedded touchscreens with proprietary content ecosystems and automated resistance adjustment. EU AI Act risk classification rules are clarifying liability frameworks for vendors incorporating biometric diagnostic features.
- Wearable Integration:Real-time data exchange with third-party fitness trackers and smartwatches.
- Biometric Monitoring:Continuous heart rate variability and metabolic estimate capture requiring HIPAA compliance infrastructure.
Bluetooth-Enabled systems dominate unit shipments; Biometric Monitoring is gaining share fastest among premium residential installations.
Distribution Channel:
Channel selection reflects customer acquisition cost tradeoffs and service bundling requirements.
- Online Retail:Direct-to-consumer platforms with content-hardware bundling bypass traditional retail markup structures. India's PLI scheme for wearable devices creates cost-competitive assembly options for smart fitness equipment targeting price-sensitive Asian markets.
- Specialty Stores:Physical showrooms with demonstration floors and white-glove delivery capabilities. CE marking timeline friction under EU Machinery Directive extends market entry lead times by four to eight months for electromechanical inventory.
- Direct Sales:Manufacturer-owned channels with subscription integration and firmware update pipelines.
- Distributors:Third-party logistics networks with regional service technician coverage.
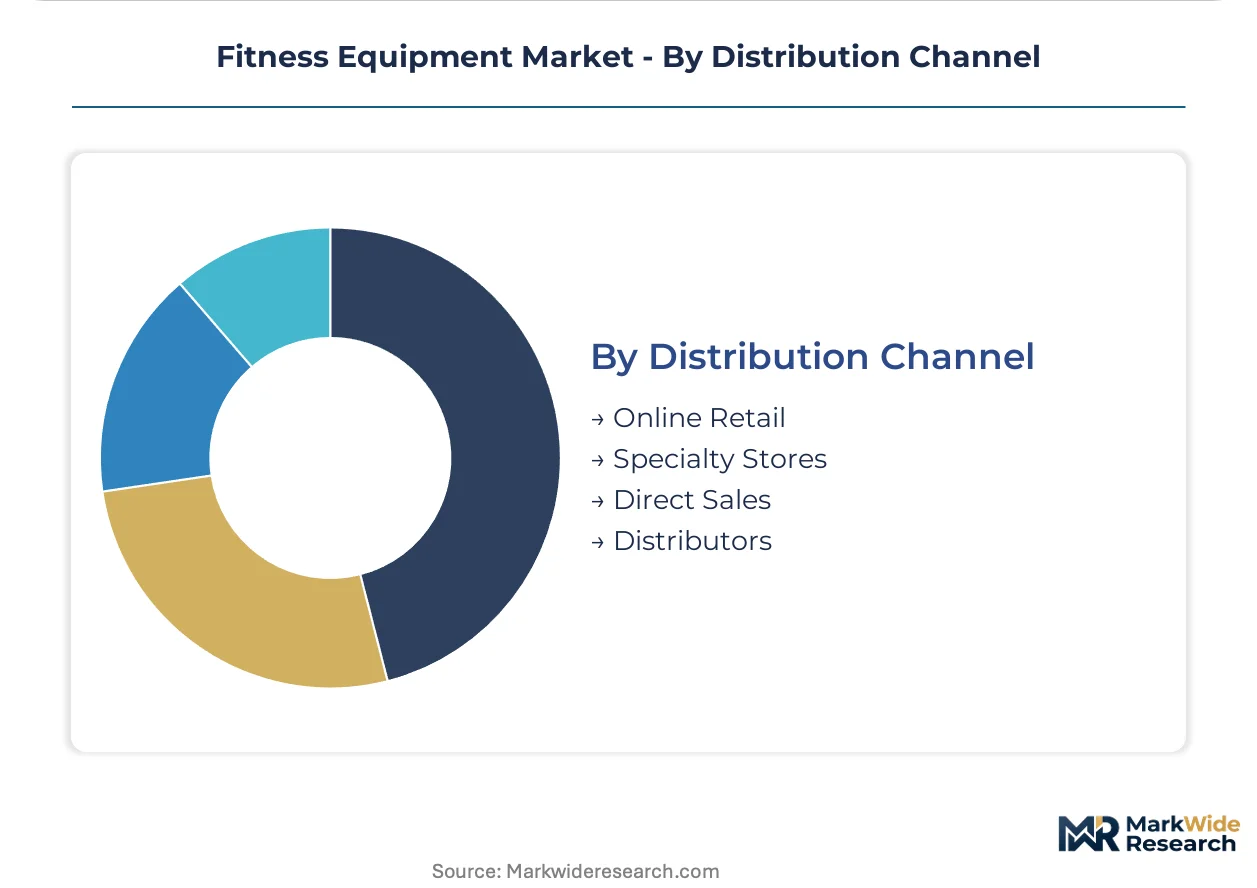
Shipment volume concentrates in Online Retail; Direct Sales channels are expanding most quickly for connected equipment with recurring revenue attachment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Guangdong province motor controller manufacturing anchors Asia-Pacific supply chains for smart fitness equipment, while North American and European demand concentrates around cardiac rehabilitation protocols and corporate wellness procurement.
United States
Hospital discharge programs in Texas and California prescribe connected treadmills for home-based cardiac rehabilitation, pulling institutional demand into residential channels. HIPAA compliance requirements govern equipment capturing heart rate variability and metabolic estimates. Austin and Dallas-Fort Worth technology sector employers compete for talent through premium home office fitness amenity packages.
Germany
Physical therapy clinics in Bavaria and North Rhine-Westphalia face reimbursement pressure to demonstrate patient outcome metrics, opening demand for progress-tracking ellipticals. The EU Machinery Directive's CE marking timelines extend market entry lead times for wireless-enabled electromechanical equipment. Baden-Württemberg industrial clusters supply precision motor controllers for electromagnetic resistance systems.
China
Domestic health consciousness and manufacturing scale in Guangdong and Zhejiang provinces reshape regional supply patterns for global brands. The country's dual carbon goals press manufacturers toward energy-efficient motor specifications. Shenzhen sensor and motor controller clusters shorten prototype-to-production timelines for established supplier relationships.
India
Price-sensitive consumer demand in Maharashtra and Karnataka creates procurement pull for cost-competitive smart equipment assembly. The PLI scheme for wearable devices incentivizes domestic manufacturing of connected fitness hardware. Tamil Nadu electronics manufacturing zones attract component sourcing for Bluetooth-enabled equipment categories.
South Korea
Commercial gyms in Seoul and Busan adopt electromagnetic resistance systems for silent operation and precise load modulation. The MFDS regulates equipment marketed with health diagnostic claims under evolving medical device frameworks. Gyeonggi-do manufacturing corridors supply motor systems for premium strength equipment expanding into residential tiers.
Fitness Equipment Market Vendor Landscape
Global majors compete with regional champions across content integration and manufacturing scale. The vendor base organizes into three tiers: premium ecosystem providers with proprietary software stacks, mid-scale fabricators with established Asian supply relationships, and specialty rehabilitation equipment makers. Strategic moves concentrate on M&A for digital capability acquisition and capacity expansion in southern Chinese component clusters.
Within the premium ecosystem tier, Technogym S.p.A. and Peloton Interactive Inc. exemplify divergent approaches to content-hardware bundling. Johnson Health Tech Co. Ltd. occupies a position among scale-driven manufacturers with Taiwan and mainland China production footprints. These three anchors illustrate how competitive positioning splits between software-dependent recurring revenue models and manufacturing efficiency across Pacific Rim supply chains.
| Leading Market Players |
|---|
| Technogym S.p.A. |
| Johnson Health Tech Co. Ltd. |
| Life Fitness LLC |
| Icon Health & Fitness Inc. |
| Core Health & Fitness LLC |
| Precor Incorporated |
| Nautilus Inc. |
| Peloton Interactive Inc. |
| Torque Fitness |
| Others |
Supply Flow & Price Mechanics
Hospital discharge programs prescribing connected treadmills for home-based cardiac rehabilitation are consolidating procurement volumes around equipment vendors capable of embedding HIPAA-compliant biometric monitoring, forcing supply chains to absorb firmware development costs previously external to hardware manufacturing and compressing margins on mid-tier configurations that lack subscription attach revenue.
Pricing Analysis
Warranty and service bundling separates premium vendors from commodity competitors, with three-tier pricing structure across premium, standard, and economy levels anchored by after-sales technician coverage and firmware update commitments. Price differentiation hinges on CE marking tier and geographic delivery cost, with German and Nordic markets commanding sub-one-watt idle power supply specifications that add design overhead. Pricing pressure stems from electromagnetic resistance system cost parity achieved by Chinese motor manufacturers, eroding mechanical flywheel margins. Home users in Texas and California technology corridors show lowest price sensitivity, while price-sensitive Asian markets resist premium content-hardware bundles.
Supply Chain Analysis
Reverse-logistics flows for refurbishment and remanufacturing concentrate in Guangdong and Zhejiang province clusters, where domestic health consciousness creates secondary market demand for certified-preowned equipment. Raw material dependencies center on powder-coated steel frames, neodymium-based magnetic resistance systems, and Taiwan-fabricated motor control chips. Single-source vulnerability for semiconductor fabrication constrains production scaling during demand spikes. Distribution runs through direct-to-consumer platforms with content subscription integration, bypassing traditional retail markup structures for connected equipment categories.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Electromagnetic resistance systems are displacing mechanical flywheels across premium and residential tiers simultaneously, compressing the window for legacy manufacturers to absorb software development competencies or cede share to digital-native entrants.
For Market Incumbents: Deploy M&A for digital capability acquisition to secure firmware engineering talent pipelines and cloud-connected device security infrastructure. Consolidate supplier relationships in Guangdong motor controller clusters to shorten prototype-to-production timelines against Chinese cost-competitive entrants. Address the threat of content-hardware unbundling by Peloton-style platform competitors through captive subscription revenue attachment.
For New Entrants and Emerging Players: Physical therapy clinics in Germany and France present the most penetrable white-space target, given reimbursement pressure for patient outcome metrics and incumbent manufacturers' lag in progress-tracking ellipticals. India's PLI scheme for wearable devices enables cost-competitive assembly for Bluetooth-enabled equipment targeting Maharashtra and Karnataka price-sensitive demand. Pursue co-branded hardware distribution through streaming platform partnerships to bypass specialty retail channel costs.
For Investors and Strategic Acquirers: The window for entry favors mid-scale fabricators with established Asian supply relationships and dormant brand equity ripe for connected equipment repositioning. Long-term viability over the coming decade rests on recurring revenue attachment rates rather than transactional hardware margins. Watch EU AI Act risk classification implementation as the inflection signal determining liability exposure for biometric diagnostic feature vendors.
| Strategic Initiative | Industry Significance |
|---|---|
| Digital Capability Acquisition | M&A targets with embedded software engineering teams address firmware talent scarcity constraining cloud-connected device security. |
| CE Marking Pathway Investment | Early compliance with EU Machinery Directive wireless connectivity timelines secures four-to-eight month market entry advantage. |
| Content-Hardware Bundling Partnership | Co-branded distribution through streaming platforms bypasses traditional retail markup structures for residential smart equipment. |
| Guangdong Supplier Consolidation | Deepened relationships with Shenzhen motor controller clusters shorten prototype-to-production timelines against cost-competitive entrants. |
| HIPAA Compliance Infrastructure Build | Legal and technical frameworks for biometric data governance unlock hospital discharge program procurement pull-through. |
Methodological Framework
SEC filings, EU Machinery Directive conformity assessment databases, and hospital procurement contract records formed the secondary backbone, cross-referenced with primary interviews involving equipment manufacturing executives, physical therapy clinic procurement directors, commercial gym chain operators, and connected fitness platform product managers. Bottom-up and top-down triangulation validated shipment estimates against motor controller and sensor import data from Guangdong customs records.
Bottom-up modeling anchored volume projections to installed base replacement cycles and technology segment penetration curves across the analysis window, while top-down cross-checks applied macroeconomic health expenditure trends. Segmentation dimensions spanned product type mechanical complexity, end-user environment, technology integration tier, and regional regulatory cluster. CAGRs derived from fitted growth curves incorporating smart equipment adoption elasticity and content subscription attach rates.
Caveats apply where EU AI Act risk classification implementation, Taiwan semiconductor supply disruption, or steel and rare-earth magnet cost volatility could materially shift the outlook. Material deviation in these named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fitness Equipment
Treadmill Desks Market
Fitness Equipment
Elliptical Trainers Market
Fitness Equipment
Push-Up Board Market
Fitness Equipment
Exercise Resistance Bands Market
Fitness Equipment
Asia-Pacific Fitness Equipment Market
Fitness Equipment
China Fitness Rings Market
Fitness Equipment
Pilates Equipment Market
Fitness Equipment
Europe Fitness Equipment Market
Fitness Equipment
Yoga Accessories Market
Fitness Equipment
Pilates Reformer Market
Fitness Equipment
Pilates Equipment and Gears Market
Fitness Equipment
Resistance Bands Market
Fitness Equipment
Europe Refurbished Fitness Equipment Market
Fitness Equipment
Ergometer Market
Fitness Equipment
India Fitness Ring Market
Fitness Equipment
GCC Fitness Ring Market