
 Sandbells Market | 2026-2036
Sandbells Market Size, Share, and Industry Trends Forecast 2026-2036
Sandbells Market Analytics
Neoprene is expanding its share in sandbell construction as manufacturers phase out PVC-dominant designs to meet chemical-content restrictions. Hyperwear leverages its patented fillable-shell architecture to sustain premium positioning across CrossFit-affiliated facilities. Rogue Fitness anchors North American distribution through direct-to-gym procurement portals that bypass traditional sporting-goods intermediaries. REP Fitness competes on manufacturing scale with domestically produced neoprene shells that reduce ocean-freight exposure.
A sandbell is a sand-filled, soft-sided resistance implement encased in neoprene, vinyl, or canvas, typically ranging from 3 lbs to 20 lbs, engineered for dynamic lifting, throwing, and gripping exercises where rigid dumbbells present injury risk. Neoprene-shell sandbells dominate commercial-gym procurement due to tear resistance and washability under high-rotation studio use. Weighted sandbells capture the fastest expansion as HIIT programming migrates from barbells to unstable-load protocols. Home-fitness demand for standard 10-lb and 20-lb units matures post-pandemic, concentrating margin pools in institutional contracts with rehabilitation centers requiring progressive-load gradations.
FDA oversight of latex-content labeling in fitness accessories shapes neoprene-sourcing decisions for US-bound inventory. EPA guidelines on vinyl chloride emissions constrain domestic manufacturing of PVC-alternative shells, pushing brands toward REACH-compliant European neoprene suppliers. California's Proposition 65 enforcement on phthalate disclosure adds compliance cost layers that smaller canvas-specialist entrants struggle to absorb. Stakeholders must monitor how state-level chemical regulations fragment sourcing strategies and whether neoprene price volatility forces material substitution back toward rubber compounds.
Market Dynamics
Functional fitness programming is accelerating equipment turnover cycles as boutique studio chains standardize sand-based resistance protocols, compressing replacement timelines from five-year to eighteen-month intervals.
Growth Catalysts
- REACH-compliant neoprene sourcing:European chemical-content frameworks are phasing out PVC-dominant shell designs, opening procurement lanes for tear-resistant alternatives that withstand high-rotation commercial use.
- Rehabilitation center procurement:Progressive-load gradations for physical therapy protocols are institutionalizing sandbell adoption across post-acute care facilities.
- HIIT programming migration:Unstable-load training protocols are displacing barbell-centric regimens in CrossFit-affiliated facilities, elevating dynamic throwing and gripping implements.
Market Restraints
- Neoprene price volatility:Asia-Pacific petrochemical feedstock fluctuations are compressing margin pools for shell manufacturers dependent on ocean-freight supply chains.
- California Proposition 65 enforcement:Phthalate disclosure mandates are adding compliance cost layers that canvas-specialist entrants struggle to absorb.
- Canvas durability limitations:Washability and tear-resistance gaps versus neoprene are constraining canvas-shell penetration in high-rotation studio environments.
Strategic Opportunities
- Home-fitness premium tier:Post-pandemic maturation of standard 10-lb and 20-lb unit demand is opening margin pools in connected-fitness bundled offerings.
- EPA vinyl chloride guidelines:Domestic manufacturing constraints on PVC-alternative shells are creating first-mover advantages for REACH-compliant European neoprene suppliers.
- Direct-to-gym procurement portals:Bypassing traditional sporting-goods intermediaries is enabling volume pricing capture and programming standardization contracts.
Industry Challenges
- FDA latex-content labeling timelines:Fitness accessory compliance documentation is extending product launch cycles for neoprene-sourcing decisions on US-bound inventory.
- Material substitution engineering:Rubber compound reformulation to offset neoprene cost spikes requires R&D capex that mid-scale manufacturers lack.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sandbells Market |
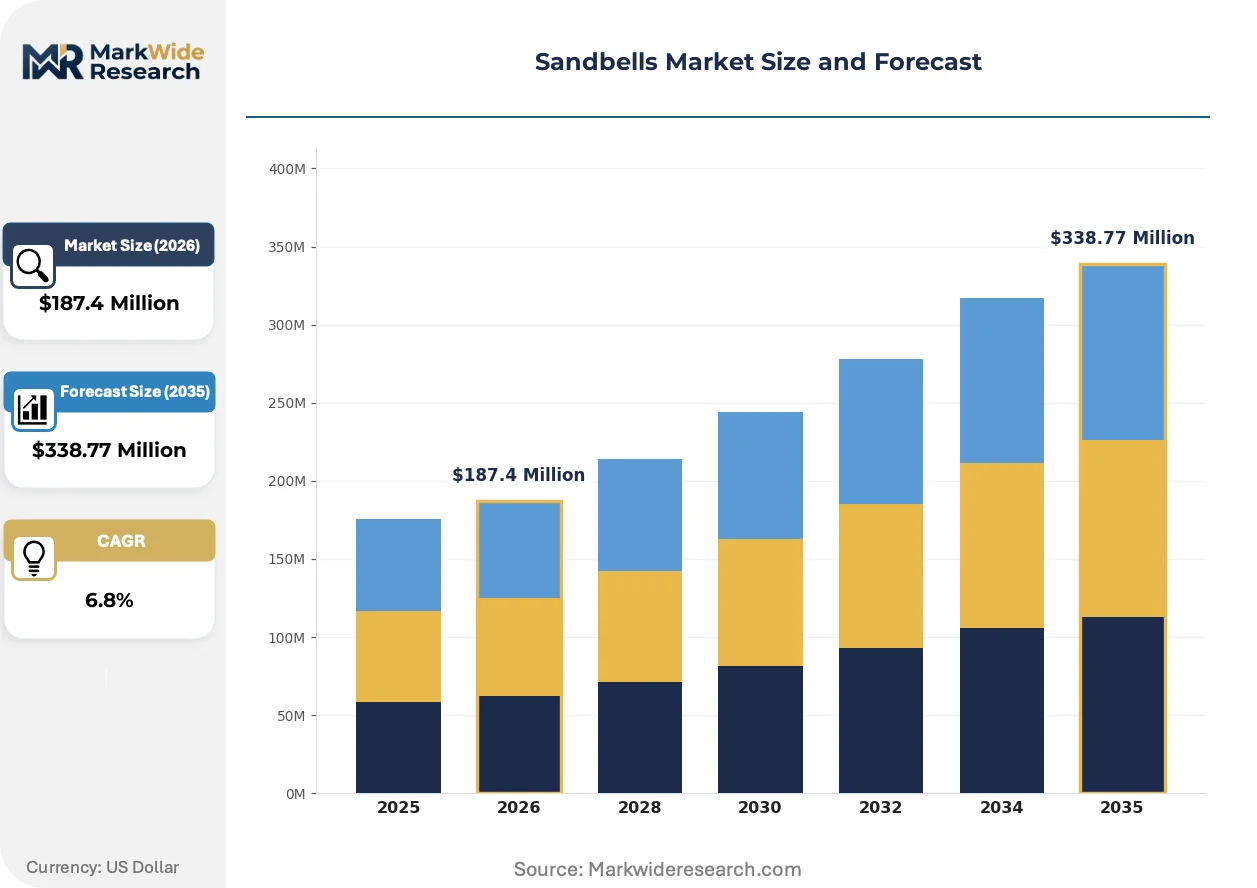
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Weighted Sandbells, Standard Sandbells, Heavyweight Sandbells, Fitness Sandbells End User: Gyms, Home Fitness, Personal Trainers, Rehabilitation Centers Material: Neoprene, Vinyl, Rubber, Canvas Size: 3 lbs, 5 lbs, 10 lbs, 20 lbs |
| Companies Covered | Hyperwear, REP Fitness, Rogue Fitness, GORUCK, Ultimate Sandbag, EMR-Tek, Garage Gym Lab, Stone Circle, Bühler AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sandbells Market Evolving Landscape
Material science advances and regulatory chemistry frameworks are converging to reshape shell construction, distribution architecture, and buyer procurement patterns across resistance-equipment supply chains.
Fillable-shell architecture is integrating patented neoprene-bladder systems that enable dynamic weight adjustment without shell replacement. Commercial gym operators are adopting these systems at accelerated pace to reduce SKU proliferation across functional training zones. This technology is integrating programming flexibility that compresses equipment procurement cycles from multi-year capital budgets to annual operating expenditures.
REACH chemical-content restrictions are mandating systematic PVC phase-outs across European-sourced fitness accessories. Shell manufacturers are reformulating polymer blends to maintain tear-resistance thresholds under washability protocols. Rehabilitation centers and boutique studios in Germany and France are absorbing premium pricing for compliant neoprene units to preempt liability exposure.
Boutique studio chains are consolidating vendor relationships around programming-standardization contracts that bundle equipment with instructor certification. Traditional sporting-goods distributors are losing shelf access as direct procurement portals capture institutional volume. This concentration is most visible in United States metropolitan markets where regional franchise operators negotiate enterprise pricing with fillable-shell specialists.
Sandbells Market Segmentation
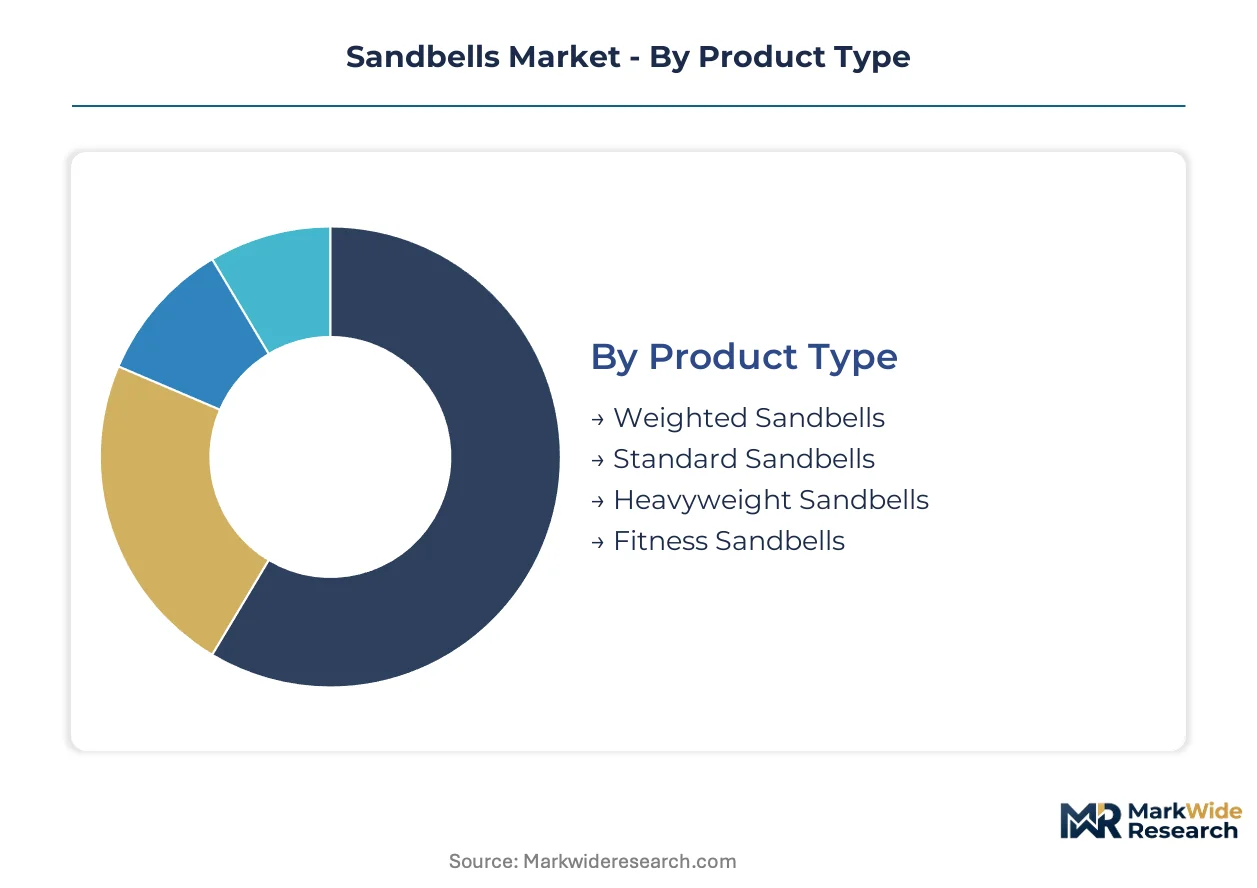
Material composition and weight specifications determine compliance pathways and procurement economics for sandbell manufacturers. Certification requirements fragment across shell chemistry, creating divergent margin structures for neoprene-dominant versus canvas-specialist suppliers.
Product Type:
FDA latex-content labeling applies to fillable-shell architectures, while REACH compliance dominates fixed-weight neoprene units bound for European institutional buyers.
- Weighted Sandbells:Patented fillable-bladder systems enable dynamic load adjustment from 5 lbs to 20 lbs without shell replacement. HIIT programming at CrossFit-affiliated facilities in the United States drives procurement concentration here, with unstable-load protocols displacing traditional dumbbell regimens.
- Standard Sandbells:Fixed-weight neoprene shells in 10-lb and 20-lb configurations dominate commercial-gym procurement due to washability under high-rotation studio use. Post-pandemic home-fitness demand for these units has matured, compressing margin pools toward institutional contracts.
- Heavyweight Sandbells:Specialized 25-lb+ units for advanced strength training protocols.
- Fitness Sandbells:Entry-level vinyl-shelled variants for recreational users prioritizing cost over durability.
Weighted Sandbells sits at the top of the volume ranking, with Heavyweight Sandbells climbing the fastest.
End User:
Procurement scale and replacement frequency vary dramatically across customer types, with institutional buyers compressing equipment cycles to eighteen-month intervals.
- Gyms:Boutique studio chains standardize programming around sand-based resistance tools, negotiating enterprise pricing through direct procurement portals. Commercial operators absorb premium neoprene pricing to preempt liability exposure under high-rotation use.
- Rehabilitation Centers:Progressive-load gradations for physical therapy protocols institutionalize adoption across post-acute care facilities. These buyers require REACH-compliant shells to satisfy procurement standards at German and French healthcare networks.
- Home Fitness:Post-pandemic maturation of 10-lb and 20-lb unit demand has shifted margin pools toward connected-fitness bundled offerings.
- Personal Trainers:Individual practitioners purchasing portable kits for client sessions prioritize fillable-shell flexibility over fixed-weight convenience.
Gyms command the largest procurement volumes, while Rehabilitation Centers gain share fastest as physical therapy protocols expand.
Material:
Shell chemistry determines regulatory exposure, with California Proposition 65 enforcement adding compliance cost layers that reshape competitive positioning.
- Neoprene:Tear-resistant polymer blends withstand washability protocols under high-rotation commercial use. Asia-Pacific petrochemical feedstock fluctuations compress margin pools for manufacturers dependent on ocean-freight supply chains.
- Vinyl:PVC-dominant designs face systematic phase-outs under REACH chemical-content restrictions, constraining penetration in European markets.
- Rubber:Compound reformulation to offset neoprene cost spikes requires R&D capex that mid-scale manufacturers lack.
- Canvas:Natural fiber shells struggle with washability and tear-resistance gaps versus neoprene, limiting penetration in studio environments.
Neoprene maintains volume leadership, with Rubber compounds expanding most quickly as manufacturers seek cost insulation from petrochemical volatility.
Size:
Weight gradations align with programming intensity tiers, with rehabilitation protocols demanding finer incremental steps than HIIT regimens.
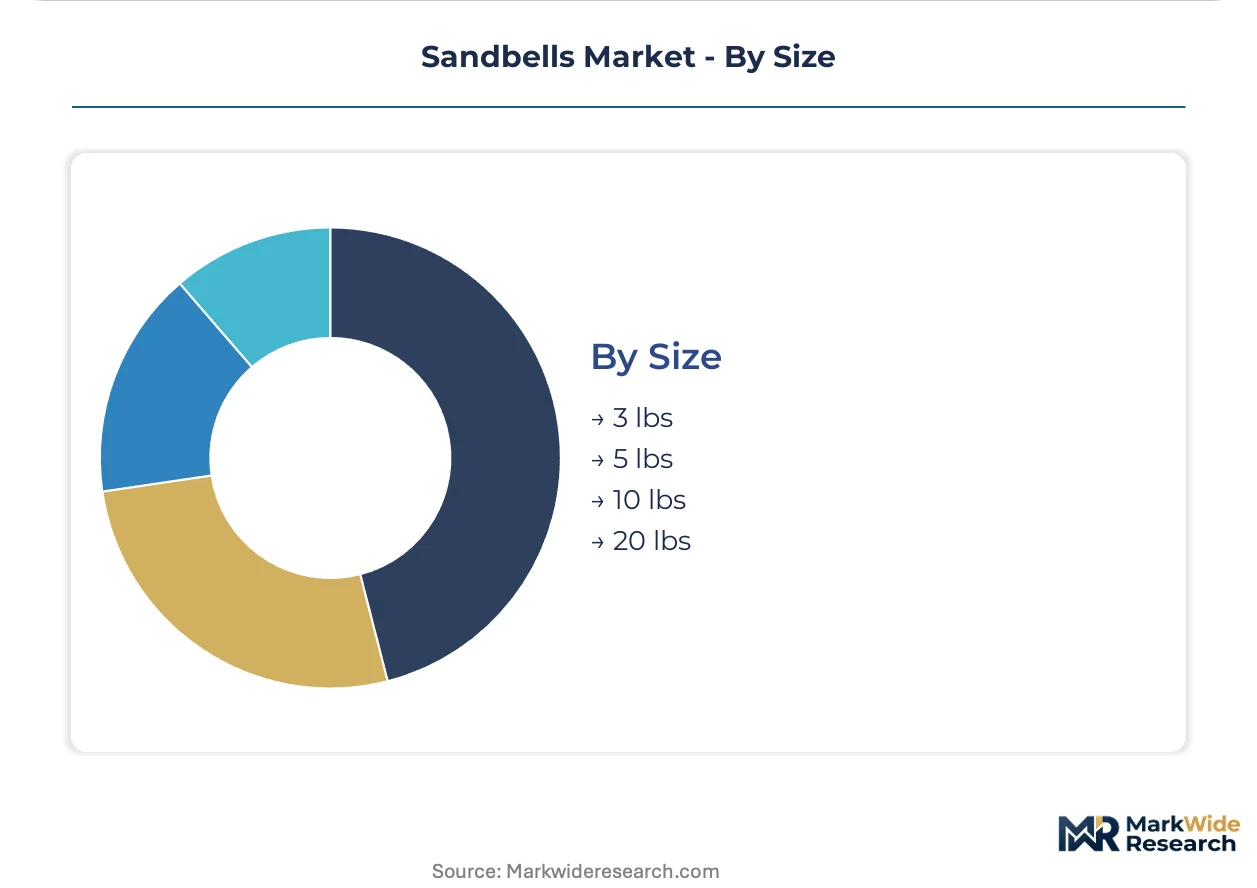
- 10 lbs:The standard unit for functional fitness programming dominates commercial-gym procurement. United States metropolitan markets show particular concentration as regional franchise operators standardize equipment specifications.
- 20 lbs:Advanced training protocols drive demand here, with unstable-load throwing exercises requiring sufficient mass for kinetic feedback.
- 3 lbs:Entry-level rehabilitation and senior fitness applications.
- 5 lbs:Progressive-load physical therapy protocols and beginner functional training.
10 lbs units anchor volume rankings, with 20 lbs configurations showing the steepest expansion trajectory as HIIT intensity escalates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Boutique fitness studio chains in the United States are compressing equipment replacement cycles to eighteen-month intervals. This concentration pattern extends across four additional national markets where functional fitness adoption drives procurement scale.
United States
CrossFit-affiliated facilities and regional franchise operators anchor procurement volume for fillable-shell architectures. FDA latex-content labeling requirements extend product launch timelines for neoprene-sourcing decisions on domestic-bound inventory. Metropolitan markets in Texas and California show particular concentration as direct-to-gym procurement portals bypass traditional sporting-goods intermediaries.
Germany
REACH chemical-content frameworks are phasing out PVC-dominant shell designs across rehabilitation centers and boutique studios. Healthcare networks in Bavaria and North Rhine-Westphalia absorb premium pricing for compliant neoprene units to preempt liability exposure. ECHA enforcement is mandating systematic polymer blend reformulation to maintain tear-resistance thresholds under washability protocols.
United Kingdom
Commercial gym operators in London and the Southeast are standardizing programming around sand-based resistance tools. The country's national chemical regulator enforces disclosure requirements on phthalate content in fitness accessories. Industrial clusters in the Midlands are developing REACH-compliant neoprene supply relationships to service institutional contracts.
Japan
Post-acute care facilities in Tokyo and Osaka are institutionalizing progressive-load gradations for physical therapy protocols. METI guidelines on chemical safety in consumer products shape shell material specifications for imported equipment. Regional franchise operators in the Kanto corridor are negotiating enterprise pricing for fillable-bladder systems.
Australia
Boutique studio chains in Sydney and Melbourne are migrating HIIT programming from barbells to unstable-load protocols. The Therapeutic Goods Administration oversees material safety claims for rehabilitation-center procurement. Domestic distributors are consolidating vendor relationships around programming-standardization contracts that bundle equipment with instructor certification.
Sandbells Market Competitive Landscape
Direct-to-gym procurement portal development dominates the current landscape as manufacturers bypass traditional sporting-goods intermediaries. The vendor base organizes around three strategic archetypes: premium fillable-shell specialists, scale-driven domestic fabricators, and canvas-specialist regional entrants. M&A activity concentrates on captive neoprene supply relationships, while capacity expansion targets REACH-compliant European manufacturing.
Among premium-tier specialists, Hyperwear exemplifies patented fillable-shell architecture positioning. Rogue Fitness occupies a position as a North American distribution anchor through direct procurement channels. REP Fitness represents scale-driven domestic manufacturing with neoprene shell production.
| Leading Market Players |
|---|
| Hyperwear |
| REP Fitness |
| Rogue Fitness |
| GORUCK |
| Ultimate Sandbag |
| EMR-Tek |
| Garage Gym Lab |
| Stone Circle |
| Bühler AG |
| Others |
Value Network & Pricing Analysis
Fillable-shell premium tier bifurcation from fixed-weight commodity units manifests in pricing power concentration at patented-bladder specialists and margin compression at canvas-dependent regional fabricators. REACH compliance costs and Asia-Pacific petrochemical volatility simultaneously reshape procurement economics across both tiers.
Pricing Analysis
Petrochemical feedstock pass-through from neoprene suppliers in Asia-Pacific compresses margin pools for shell manufacturers dependent on ocean-freight supply chains. Three-tier pricing structure across premium fillable-shell, standard neoprene fixed-weight, and economy canvas variants stratifies by certification grade and washability durability. Pricing pressure intensifies in the standard tier as post-pandemic home-fitness demand matures and institutional buyers consolidate volume through direct procurement portals. Rehabilitation centers exhibit lowest price sensitivity due to liability-driven procurement standards, while recreational home users anchor the economy tier.
Supply Chain Analysis
REACH and FDA qualification gating for neoprene shell chemistry fragments supplier bases between European REACH-compliant specialists and Asia-Pacific cost-optimized producers. Manufacturing concentrates in China, Vietnam, and domestic United States facilities for neoprene-bladder assembly. Raw material dependencies span chloroprene rubber feedstocks, polyester reinforcement textiles, and precision valve hardware for fillable architectures. Single-source vulnerability runs through Asia-Pacific petrochemical supply chains exposed to freight rate volatility. Distribution runs through direct-to-gym procurement portals that bypass traditional sporting-goods intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds regulatory value as REACH chemical-content phase-outs and FDA latex-labeling timelines institutionalize compliance premiums across institutional procurement channels.
For Market Incumbents: To counter margin compression from neoprene price volatility, deepen captive supply relationships with REACH-certified European polymer suppliers and anchor enterprise pricing through programming-standardization contracts with boutique studio chains. For New Entrants and Emerging Players: The price-point gap between premium fillable-shell systems and economy canvas units opens white-space at mid-tier neoprene fixed-weight offerings for rehabilitation center procurement. Target German and French healthcare networks with progressive-load gradations and bundled instructor certification programs. For Investors and Strategic Acquirers: Consolidation pressure builds where mid-scale manufacturers lack R&D capex for rubber compound reformulation and REACH compliance documentation. Long-term viability favors vertically integrated specialists with captive neoprene supply and direct procurement portal infrastructure. Monitor ECHA enforcement intensity as inflection signal for compliance-premium sustainability.| Strategic Initiative | Industry Significance |
|---|---|
| REACH-Compliant Neoprene Sourcing | Preempts liability exposure for institutional buyers under ECHA enforcement frameworks. |
| Fillable-Shell Patent Expansion | Secures programming-flexibility premiums at CrossFit-affiliated facilities and rehabilitation centers. |
| Direct-to-Gym Procurement Portal | Bypasses traditional sporting-goods intermediaries to capture enterprise pricing and volume. |
| Rubber Compound R&D Investment | Insulates margin pools from Asia-Pacific petrochemical feedstock volatility. |
| Programming-Standardization Contract | Bundles equipment procurement with instructor certification to lock replacement cycles. |
Research Methodology
Multiple input streams — primary interviews with equipment procurement directors at boutique studio chains, neoprene supplier technical leads, and rehabilitation center purchasing managers, alongside secondary validation through customs trade data, SEC filings of publicly listed fitness equipment distributors, and ECHA chemical restriction databases — were reconciled through bottom-up and top-down triangulation.
Historical volume trajectories were cross-referenced against panel inputs from commercial gym operators and physical therapy protocol specialists across the analysis window. Segmentation dimensions modeled include shell material chemistry, weight specification tiers, end-user procurement scale, and regional regulatory cluster. CAGRs were derived from fitted growth curves incorporating HIIT programming adoption rates and institutional replacement cycle compression.
Caveats apply where neoprene price volatility spikes or California Proposition 65 enforcement expansion could materially shift the outlook for canvas-specialist viability. Forecasts reflect assumptions around REACH phase-out timelines and boutique studio chain consolidation trajectories. A model refresh is warranted upon material change in ECHA chemical-content restriction schedules.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sports Equipment
Bicycle Pumps Market
Sports Equipment
Riding Gear Market
Sports Equipment
Clay Pigeon Thrower Market
Sports Equipment
Kids Sports Equipment and Accessories Market
Sports Equipment
Crampon Market
Sports Equipment
Pickleball Pitching Machine Market
Sports Equipment
Soccer Cleats Market
Sports Equipment
UK Horse Riding Equipment Market
Sports Equipment
Mountain Bicycle Cassette Market
Sports Equipment
Athletic Mask Market
Sports Equipment
Shuffleboard Equipment Market
Sports Equipment
Ice Cleat Market
Sports Equipment
United States Running Gear Market
Sports Equipment
Golf Bags Market
Sports Equipment
Shuttlecock Market
Sports Equipment
Gym Bag Market