
 Table Tennis Equipment Market | 2026-2036
Table Tennis Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Table Tennis Equipment Market Analytics
Certified table tennis coaching capacity is reorganizing how brands penetrate grassroots markets. Butterfly leverages its academy network in Japan to sustain premium positioning among competitive players. STIGA Sports AB anchors its Nordic manufacturing heritage to differentiate on blade craftsmanship and wood sourcing transparency.
Table tennis equipment encompasses rackets with laminated wood blades and regulated rubber surfaces, balls meeting ITTF diameter and weight specifications, competition-grade tables with standardized bounce characteristics, and tension-adjustable net assemblies. The primary purpose is to enable standardized play across recreational, educational, and professional competitive environments. Rackets command the dominant margin pool due to customization complexity and rubber replacement cycles, while online retail channels are capturing volume growth from direct-to-consumer blade configuration tools. Composite materials represent the fastest-growing material segment as manufacturers balance performance with supply chain resilience.
ISO standards govern equipment dimensional tolerances and performance consistency, while national Olympic committees and sports federations enforce procurement specifications for sanctioned events. China's SAMR monitors product safety labeling for domestic sales, and the EU's REACH framework restricts hazardous substances in rubber formulations and adhesives. Stakeholders must weigh certification investments against the fragmentation of regional approval pathways as amateur leagues formalize equipment compliance requirements.
Market Dynamics
Equipment certification requirements are fragmenting procurement pathways as amateur leagues formalize compliance standards, forcing manufacturers to maintain parallel approval processes across Japan's JIS framework, China's GB standards, and the EU's REACH restrictions on rubber compounds.
Growth Catalysts
- School athletic program expansion:Rising junior participation in China's provincial school leagues is creating sustained replacement demand for entry-level rackets and training balls.
- Sustainable material mandates:The EU Green Deal is accelerating reformulation of blade adhesives and rubber compounds toward bio-based alternatives.
- Composite material adoption:Carbon fiber reinforcement in blade construction is enabling thinner profiles without sacrificing stiffness, attracting competitive players seeking faster response.
Market Restraints
- Natural rubber price volatility:Plantation supply disruptions in Southeast Asia are compressing margins on high-tension rubber sheets.
- Manufacturing cluster concentration:Over 60% of blade production sits within Guangdong Province, creating single-point vulnerability.
- REACH compliance costs:European chemical registration requirements are extending product development timelines by 8-14 months for adhesive systems.
Strategic Opportunities
- Direct-to-consumer blade configuration:Online customization tools are bypassing traditional sporting goods distributors in North American markets.
- India's underpenetrated school sector:Table tennis remains secondary to cricket in physical education curricula, leaving white space for equipment suppliers.
- Recyclable rubber initiatives:Japan's METI circular economy incentives are funding closed-loop manufacturing pilots for rubber sheet recovery.
Industry Challenges
- Certified coaching scarcity:ITTF Level 1 instructor shortages in emerging markets are limiting grassroots program scalability.
- Multi-standard testing burden:Simultaneous ISO, JIS, and GB compliance testing is straining quality assurance budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Table Tennis Equipment Market |
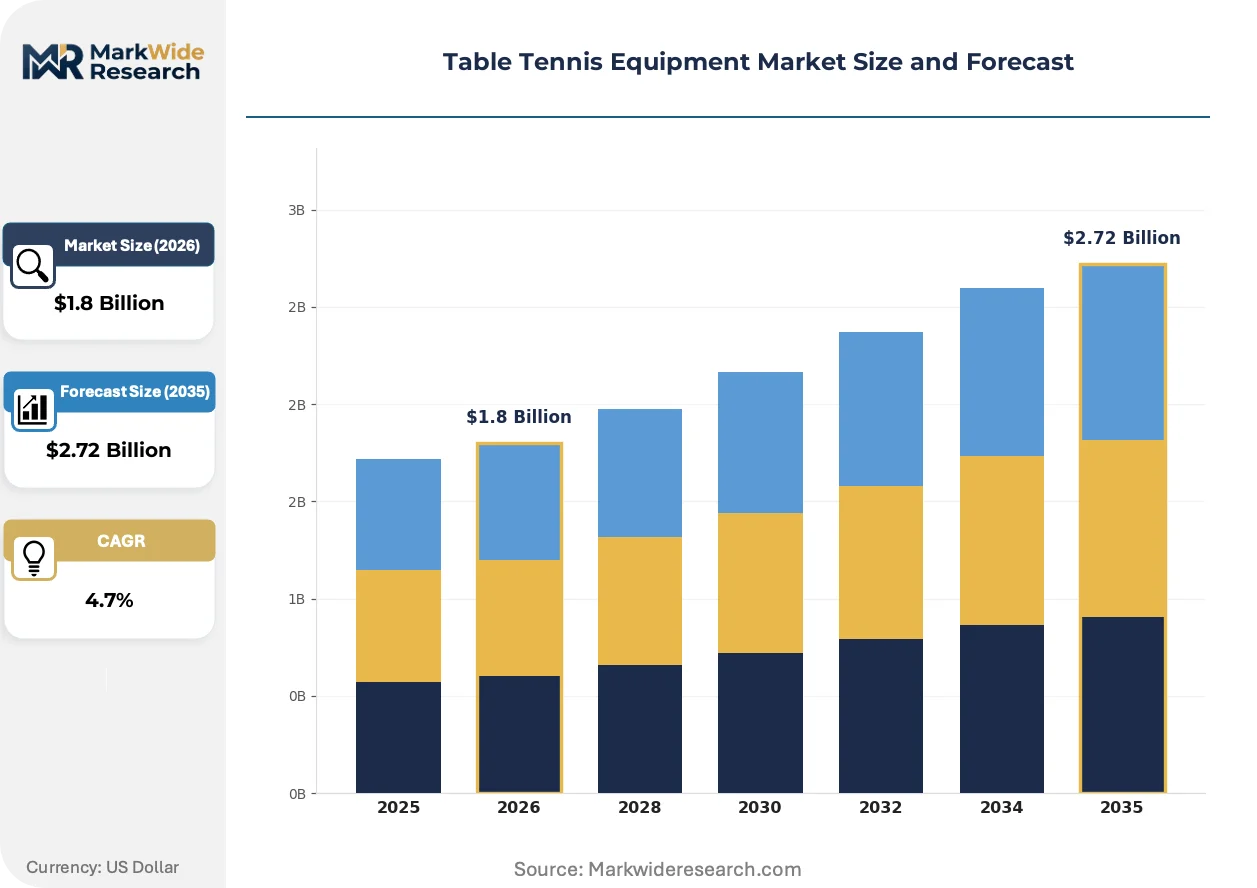
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rackets, Balls, Tables, Nets End User: Schools, Clubs, Professional Players, Recreational Players Material: Wood, Plastic, Rubber, Composite Distribution Channel: Online Retail, Specialty Stores, Sports Outlets, Others |
| Companies Covered | JOOLA, Yasaka, Butterfly, Nippon Takkyu, Tibhar, Double Happiness, STIGA Sports AB, XIOM Corporation, DONIC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Table Tennis Equipment Market Evolving Landscape
Material science advances and regulatory chemistry restrictions are jointly redefining performance benchmarks across blade construction and rubber formulation, while digital channels are compressing traditional distribution hierarchies.
Aramid-carbon hybrid fiber layups are supplanting traditional all-wood blades in competitive segments. National team procurement contracts in South Korea and Germany now specify composite-reinforced constructions exclusively. This shift is compressing demand for premium-grade limba and koto wood veneers, forcing traditional craftsmen to diversify material sourcing or exit the tournament-grade segment entirely.
REACH Annex XVII restrictions on isocyanate-based adhesives are compelling reformulation of blade lamination processes. Manufacturers serving European markets must now validate alternative bonding chemistries through ECHA notification procedures. The competitive rubber sheet segment bears the highest compliance burden, with smaller compounders exiting rather than absorbing registration costs.
Club-level buyers are consolidating purchases through cooperative procurement platforms, disintermediating regional distributors who previously held inventory risk. This pattern concentrates volume with manufacturers maintaining direct fulfillment infrastructure. The shift is most pronounced in Germany's Verein-based club system, where aggregated orders now exceed individual retail transactions for competition-grade tables.
Table Tennis Equipment Market Segmentation
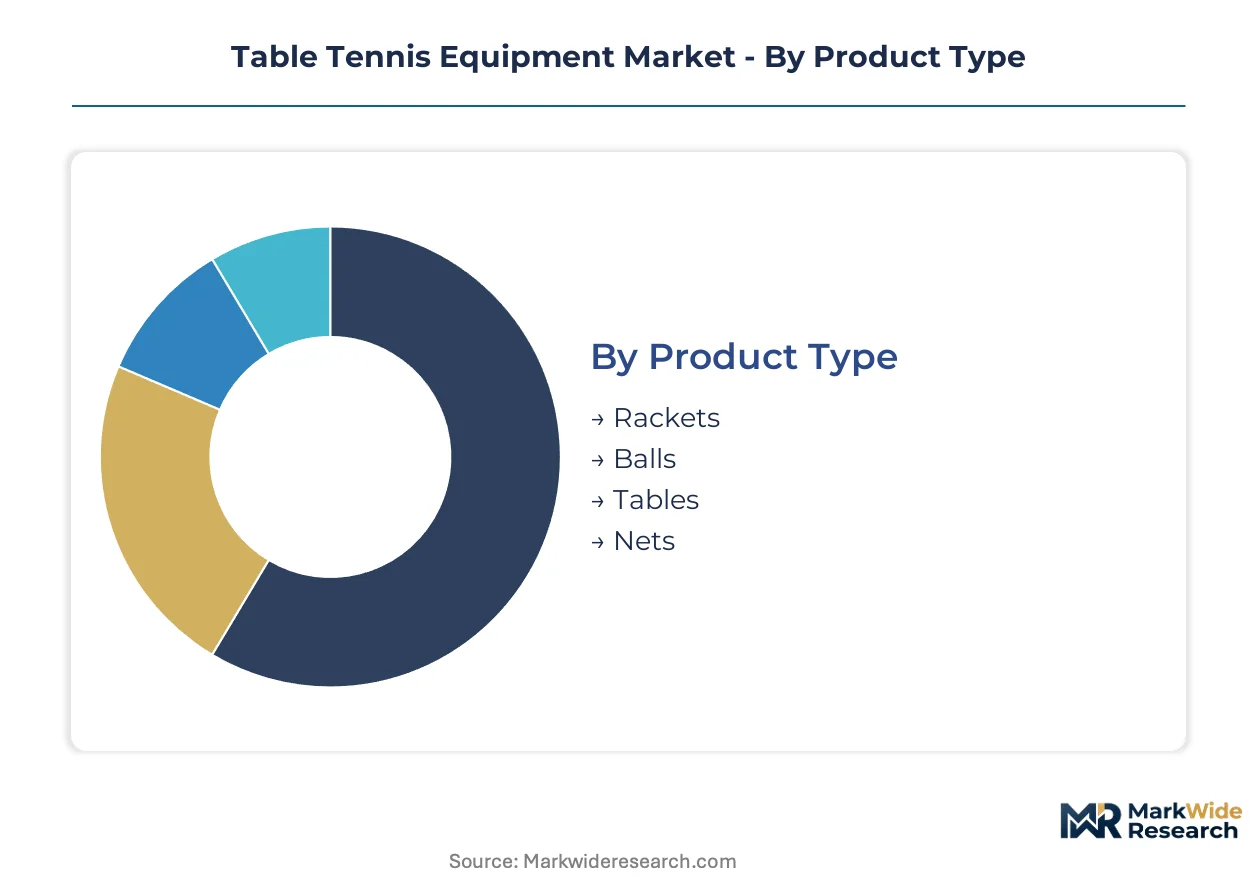
Segmentation in table tennis equipment reveals how procurement authority, material science, and channel economics split demand across radically different buyer behaviors. School districts negotiate volume contracts for standardized gear while professional players commission custom blade configurations through direct channels.
Product Type:
Domestic consumption in China and Japan absorbs the majority of racket and ball output, while tables and nets ship disproportionately to export markets building club infrastructure.
- Rackets:Laminated wood blades paired with ITTF-certified rubber surfaces command the dominant margin pool. Demand concentrates among competitive players in Japan and South Korea seeking customized tension specifications and replacement rubber cycles.
- Balls:Celluloid and ABS plastic spheres meeting strict diameter and weight tolerances. Schools across China's provincial athletic programs drive volume procurement for training inventory, though professional-grade seamless poly balls attract premium positioning in tournament circuits.
- Tables:Competition-grade surfaces with standardized bounce characteristics and wheel-locking systems. Export demand from Germany's Verein-based club system and North American recreational facilities sustains manufacturing.
- Nets:Tension-adjustable assemblies with height regulation mechanisms. Institutional buyers in India's emerging school sector and Southeast Asian municipal programs anchor volume.
Rackets command the established base. The steepest expansion runs through balls as school program formalization accelerates replacement rates.
End User:
Cost tier stratification separates institutional buyers operating on fixed budgets from discretionary spenders pursuing performance optimization.
- Schools:Provincial education bureaus in China and district athletic coordinators in Japan issue standardized procurement specifications. Volume discounts and durability requirements override brand preference in bid evaluations.
- Clubs:Germany's cooperative procurement platforms aggregate orders across multiple Verein, disintermediating traditional distributors. Maintenance contracts for table surfaces and net assemblies generate recurring revenue streams.
- Professional Players:National team contracts in South Korea and Germany specify composite-reinforced blade constructions exclusively. Custom rubber compound matching to individual playing styles sustains premium pricing.
- Recreational Players:Entry-level pre-assembled rackets and recreational-grade balls dominate. North American direct-to-consumer channels capture this segment through online blade configuration tools.
Schools anchor volume throughput. Professional players deliver the highest margin realization per unit.
Material:
Application requirements dictate material selection, with competitive performance specifications diverging sharply from institutional durability standards.
- Wood:Premium limba and koto veneers traditionally dominated tournament-grade blade construction. Demand is compressing as national team procurement shifts toward composite-reinforced alternatives.
- Plastic:ABS and celluloid formulations for ball production. China's SAMR monitors safety labeling for domestic sales while REACH restrictions govern European import compliance.
- Rubber:High-tension sheets with regulated thickness and pimple geometry. Southeast Asian plantation supply disruptions are compressing margins on natural rubber compounds.
- Composite:Aramid-carbon hybrid fiber layups enabling thinner blade profiles without stiffness loss. Carbon fiber reinforcement is gaining share fastest among competitive segments seeking faster response characteristics.
Wood retains heritage positioning. Composite materials are climbing the fastest as performance benchmarks shift.
Distribution Channel:
Customer type and geography jointly determine channel selection, with institutional buyers favoring relationship-based procurement while individual players migrate online.
- Online Retail:Direct-to-consumer blade configuration tools bypass traditional sporting goods distributors. North American markets show strongest channel shift as players customize handle shapes and rubber combinations digitally.
- Specialty Stores:Certified coaches and equipment technicians provide fitting services. Japan's academy network and Butterfly's retail presence sustain this channel for premium racket sales.
- Sports Outlets:Mass-market retailers stock entry-level pre-assembled rackets and recreational balls. China's provincial school districts leverage these channels for emergency inventory replenishment.
- Others:Cooperative procurement platforms and direct manufacturer relationships serve Germany's club system and institutional buyers with aggregated volume requirements.
Specialty stores hold premium positioning. Online retail is expanding most quickly as configuration technology matures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
SAMR's product safety labeling mandates anchor procurement patterns in China, the dominant geography. Japan's METI circular economy incentives and Germany's REACH enforcement create divergent compliance pathways. Equipment demand clusters around manufacturing corridors in Guangdong Province, Tokyo's sporting goods corridor, and Germany's Verein-based club networks.
China
Provincial school athletic programs in Jiangsu and Shandong provinces drive volume demand for entry-level rackets and training balls. SAMR monitors safety labeling for domestic sales while GB standards govern equipment specifications. Guangdong Province hosts over sixty percent of global blade production, with Shenzhen and Dongguan serving as export manufacturing hubs.
Japan
National team procurement contracts and academy network expansion sustain premium racket demand in Tokyo and Osaka metropolitan areas. METI circular economy incentives fund closed-loop rubber sheet recovery pilots. Tokyo's sporting goods corridor concentrates certified coaching capacity and specialty retail infrastructure.
Germany
Verein-based club systems aggregate equipment purchases through cooperative procurement platforms, bypassing traditional distributors. REACH Annex XVII restrictions on isocyanate-based adhesives compel reformulation of blade lamination processes. North Rhine-Westphalia hosts the densest concentration of table tennis clubs, driving competition-grade table demand.
South Korea
National team contracts specify composite-reinforced blade constructions exclusively, accelerating aramid-carbon hybrid adoption. The country's national sports federation enforces procurement specifications for sanctioned events. Seoul's metropolitan area anchors professional player equipment customization services.
United States
Direct-to-consumer blade configuration tools capture recreational player demand through digital channels. Entry-level pre-assembled rackets dominate mass-market retail in California and Texas. The absence of federal equipment standards leaves procurement to school district athletic coordinators and municipal recreation departments.
Table Tennis Equipment Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the equipment value chain. The vendor base separates into heritage craftsmen, composite material specialists, and mass-market fabricators. Premium positioning depends on certified academy networks and national team endorsements. Capacity expansion and portfolio diversification represent the dominant competitive moves as manufacturers balance performance innovation with REACH compliance timelines.
Among heritage manufacturers, Butterfly and STIGA Sports AB occupy positions defined by geographic origin and craftsmanship positioning. Butterfly exemplifies the academy-network archetype through its Japan-based coaching infrastructure. STIGA Sports AB represents Nordic manufacturing heritage and wood sourcing transparency. XIOM Corporation sits within the composite material specialist tier, reflecting South Korean national team procurement relationships. These three anchors illustrate how certification depth and material science capabilities stratify competitive positioning without requiring identical strategic moves.
| Leading Market Players |
|---|
| JOOLA |
| Yasaka |
| Butterfly |
| Nippon Takkyu |
| Tibhar |
| Double Happiness |
| STIGA Sports AB |
| XIOM Corporation |
| DONIC |
| Others |
Value Network & Pricing Analysis
Long-term offtake agreements between Guangdong blade manufacturers and Japanese academy networks lock in supply access while anchoring price visibility for premium racket tiers. This contract structure insulates established players from spot-market volatility in koto and limba veneers, though REACH compliance costs are compressing margins on European-bound shipments.
Pricing Analysis
Geographic price spreads separate Tokyo's specialty retail corridor from North American direct-to-consumer channels by certification depth rather than material cost alone. Three-tier pricing structure across premium, standard, and economy levels stratifies by ITTF certification grade and rubber tension customization, with professional players absorbing the widest premiums. Pricing pressure stems from Southeast Asian natural rubber supply disruptions forcing compounders to reformulate. School districts in China's provincial leagues exhibit highest price sensitivity, while national team procurement contracts in South Korea demonstrate lowest elasticity.
Supply Chain Analysis
Inbound logistics costs through Shenzhen and Dongguan port clusters fluctuate with container availability on Asia-Europe trade lanes, compressing landed costs for German Verein buyers. Blade production concentrates in China, Japan, and South Korea, drawing from koto and limba veneer feedstocks plus aramid-carbon fiber imports. Single-source vulnerability runs through Guangdong Province's sixty-percent share of global blade output. Distribution runs through cooperative procurement platforms in Germany, specialty academy networks in Japan, and mass sporting goods retailers in North America.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution pressure from composite-reinforced blade technologies that displace traditional all-wood craftsmanship in competitive segments. Defense requires securing supply chain position while accelerating material science differentiation.
For Market Incumbents: Secure backward integration into koto and limba veneer sourcing to defend against Southeast Asian plantation supply disruptions. Anchor certification depth through ITTF academy network expansion, creating switching costs that emerging composite specialists cannot replicate overnight. For New Entrants and Emerging Players: Certified coaching capacity gaps in India's underpenetrated school sector offer white-space entry with lower competitive density than East Asian markets. Target municipal procurement in emerging geographies through standardized equipment bundles that bypass customization complexity. For Investors and Strategic Acquirers: Capital is best deployed toward composite material specialists with South Korean national team relationships and proven REACH-compliant adhesive formulations. Watch aramid-carbon hybrid adoption rates in club-level segments as the inflection signal for technology transition velocity.| Strategic Initiative | Industry Significance |
|---|---|
| REACH-Compliant Adhesive Reformulation | ECHA notification procedures validate alternative bonding chemistries for European market access. |
| Direct-to-Consumer Blade Configuration | Online customization tools bypass traditional sporting goods distributors in North American recreational segments. |
| Academy Network Expansion | ITTF-certified coaching infrastructure locks in premium racket demand through player development pipelines. |
| Composite Material R&D Investment | Aramid-carbon hybrid layups enable thinner blade profiles that attract competitive player migration. |
| Closed-Loop Rubber Recovery Pilot | METI circular economy incentives fund sustainable manufacturing positioning for Japanese market leadership. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with equipment manufacturing executives, ITTF-certified coaching directors, and school district procurement officers in China and Germany; and secondary validation through customs trade records, SAMR safety labeling filings, and ECHA REACH registration databases. Bottom-up segment sizing triangulated against top-down macroeconomic indicators across the analysis window.
Across the projection horizon, the analytical framework modeled demand by product type, end-user archetype, material composition, and distribution channel, with regional regulatory clusters as a cross-cutting dimension. CAGRs derived from historical shipment trajectories adjusted for school program formalization rates and composite material substitution elasticities. Forecast inputs incorporated natural rubber plantation yield projections and METI circular economy incentive disbursement patterns.
Forecasts assume regulatory continuity in REACH, SAMR, and GB standards regimes; material policy shifts would require re-modeling. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sports Equipment
Recreational Rowing Boats Market
Sports Equipment
United States Running Gear Market
Sports Equipment
UAE Horse Riding Equipment Market
Sports Equipment
Golf Equipment Market
Sports Equipment
Running Gear Market
Sports Equipment
Sandbells Market
Sports Equipment
Global Badminton Equipment and Facilities Market
Sports Equipment
Surfing Equipment Market
Sports Equipment
Global Weighted Hula Hoop Market
Sports Equipment
Windsurfing Equipment Market
Sports Equipment
Riding Gear Market
Sports Equipment
Europe Running Gear Market
Sports Equipment
Global Spikeball Equipment Market
Sports Equipment
Boxing Gear Market
Sports Equipment
UK Horse Riding Equipment Market
Sports Equipment
Baseball Shoes Market