
 Portable Basketball Hoops Market | 2026-2036
Portable Basketball Hoops Market Size, Share, and Industry Trends Forecast 2026-2036
Portable Basketball Hoops Market Analytics
Big-box retail and direct-to-consumer channels is fragmenting as specialty sporting goods stores lose ground to Amazon, Walmart, and manufacturer-owned websites. Lifetime Products controls the mass-market segment through polyethylene backboard lines sold at major home improvement retailers. Goalrilla dominates premium adjustable systems through welded steel construction and dealer networks. Spalding leverages institutional relationships to sustain school and municipal contract volume despite price compression in consumer tiers.
Portable basketball hoops are wheeled, freestanding systems with weighted bases—typically water- or sand-filled—and adjustable poles allowing rim height variation from 7.5 to 10 feet, designed for residential, recreational, and light institutional use without permanent installation. Steel-framed adjustable height systems anchor the value pool due to durability premiums and replacement part economics, while mini hoops for indoor door mounting represent the fastest-expanding volume tier among apartment dwellers and younger children. Acrylic backboards command margin concentration in mid-premium segments where rebound performance justifies price steps over polycarbonate alternatives.
ASTM F1882 and F2220 standards govern tip-over stability and backboard impact resistance in the United States, with CPSC recall protocols pressuring manufacturers toward heavier base designs and anti-tip engineering. The EU's REACH regulation and General Product Safety Directive constrain polypropylene and aluminum sourcing for units sold in European markets, elevating compliance costs for imported systems. Stakeholders must monitor how municipal park budgets and school infrastructure bonds reshape institutional procurement cycles independent of consumer demand fluctuations.
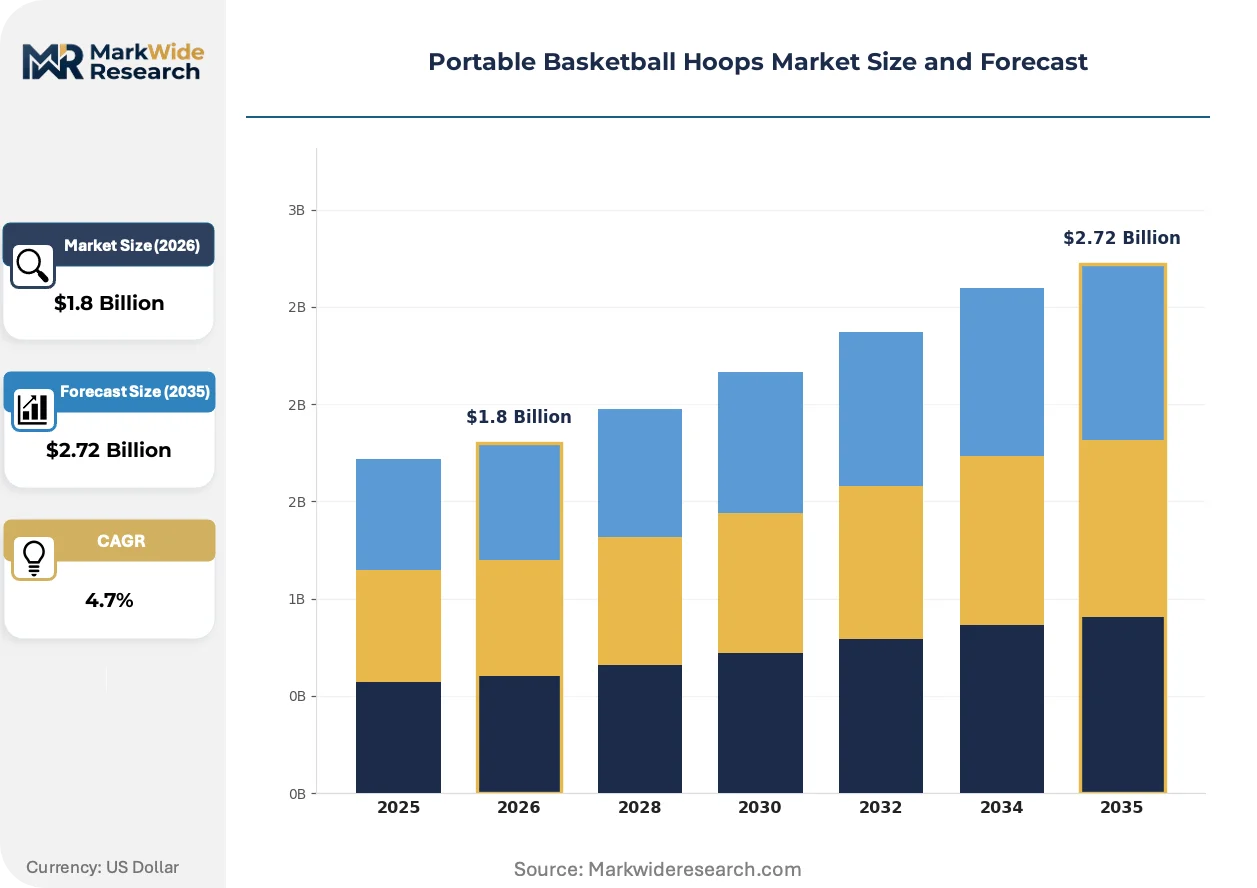
Market Dynamics
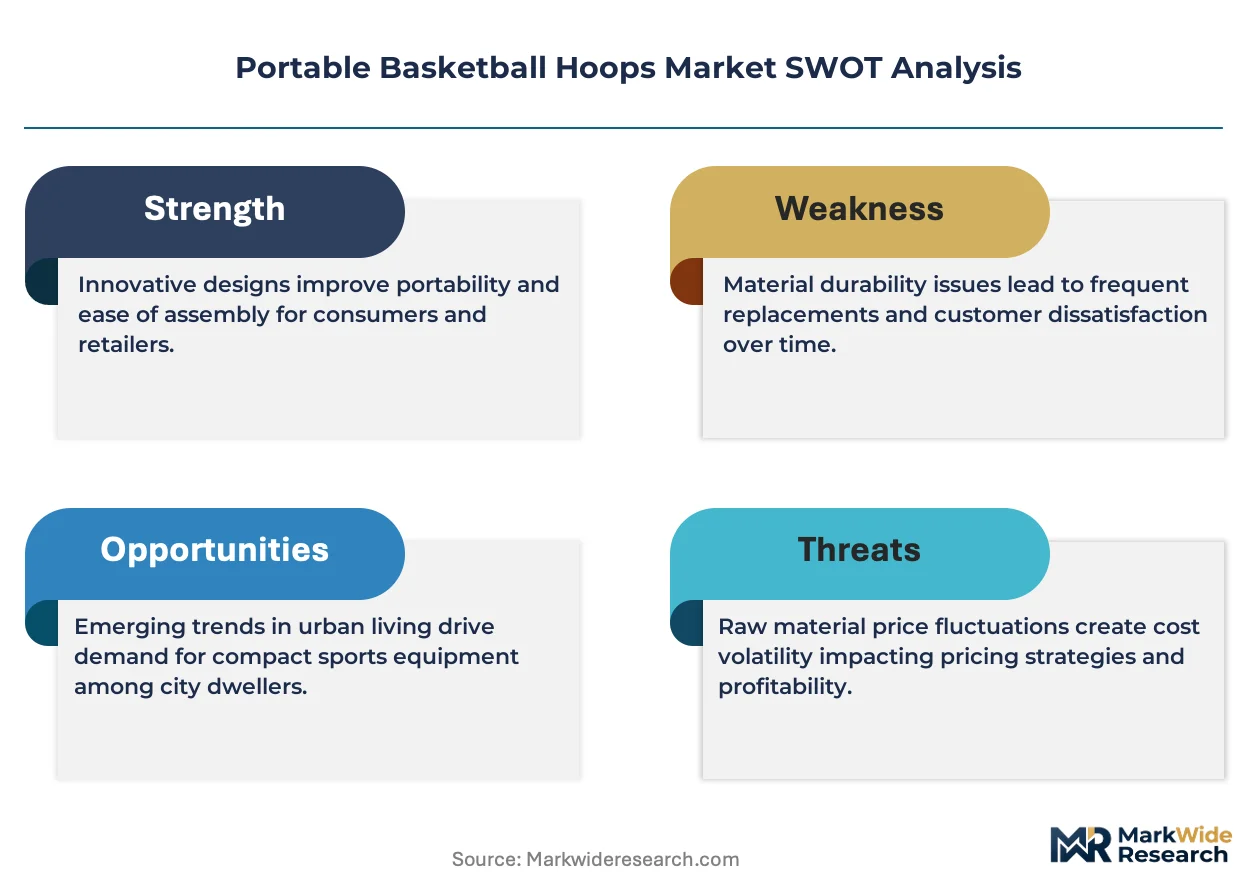
ASTM International's tightened tip-over stability standards are compressing product development cycles and forcing base-weight engineering revisions across North American manufacturers, reshaping competitive positioning toward safety-certified systems.
Growth Catalysts
- ASTM F1882 compliance mandates:School districts and municipal parks now require certified stability documentation, pulling procurement toward engineered systems with documented testing protocols.
- Suburban driveway installation density:Residential development patterns in the United States embed basketball court infrastructure as standard amenity, sustaining replacement and upgrade cycles.
- Polyethylene rotational molding:This manufacturing process enables complex base geometries with integrated ballast compartments, reducing unit weight while maintaining tip-over resistance.
Market Restraints
- Steel price volatility:Pole and frame fabrication depends on cold-rolled steel input costs, which fluctuate with scrap metal availability and energy pricing.
- REACH chemical restrictions:EU regulations on polypropylene additives constrain material sourcing for European-bound inventory, elevating compliance overhead.
- Fixed-base system substitution:In-ground permanent installations capture premium residential segments where property owners prioritize stability over portability.
Strategic Opportunities
- Apartment-dwelling mini-hoop demand:Door-mounted systems for indoor use represent underpenetrated volume among urban renters with no outdoor space.
- Amazon Marketplace channel expansion:Direct-to-consumer logistics bypass traditional sporting goods retail, capturing margin and customer data.
- Acrylic backboard performance tiering:Rebound quality differentiation justifies price steps in mid-premium segments above polycarbonate alternatives.
Industry Challenges
- Anti-tip engineering talent scarcity:Mechanical design expertise for stability simulation and testing remains concentrated among legacy manufacturers.
- ASTM certification timeline compression:Third-party laboratory testing queues extend product launch windows, delaying seasonal inventory positioning.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Portable Basketball Hoops Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: In-Ground, Adjustable Height, Fixed Height, Mini Hoops Material: Steel, Aluminum, Polypropylene, Acrylic Target Audience: Schools, Recreational, Professional, Home Use Features: Portability, Stability, Weather Resistance, Easy Assembly |
| Companies Covered | Spalding, Lifetime Products, Goalsetter, Bison, First Team Inc., Goaliath, Barbarian Basketball Systems, Goalrilla, Huffy, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Portable Basketball Hoops Market Evolving Landscape
Material science advances and regulatory pressure are converging to redefine product architecture, with manufacturers racing to integrate lighter base technologies while satisfying stricter safety protocols.
Glass-reinforced polymer composite poles are hybridizing with traditional steel construction, enabling height-adjustable systems with reduced shipping weight and corrosion resistance. Recreational buyers in coastal United States markets are adopting these hybrid structures at accelerating rates. This material convergence is hybridizing supply chain requirements, forcing manufacturers to dual-source metal and polymer fabrication capabilities.
ASTM International's updated F2220 backboard impact standards are mandating thicker polycarbonate gauges and reinforced mounting brackets. Manufacturers serving school and municipal contracts must redesign product lines to meet documented impact resistance thresholds. The institutional segment is responding by consolidating procurement around pre-certified suppliers with established testing relationships.
Seasonal rental and subscription models are disrupting traditional ownership patterns among transient suburban families and youth league organizers. Specialty sporting goods retailers are piloting summer-long lease programs with full-service installation and removal. This consumption shift is most visible in Sun Belt metropolitan areas where seasonal migration patterns concentrate demand spikes.
Portable Basketball Hoops Market Segmentation
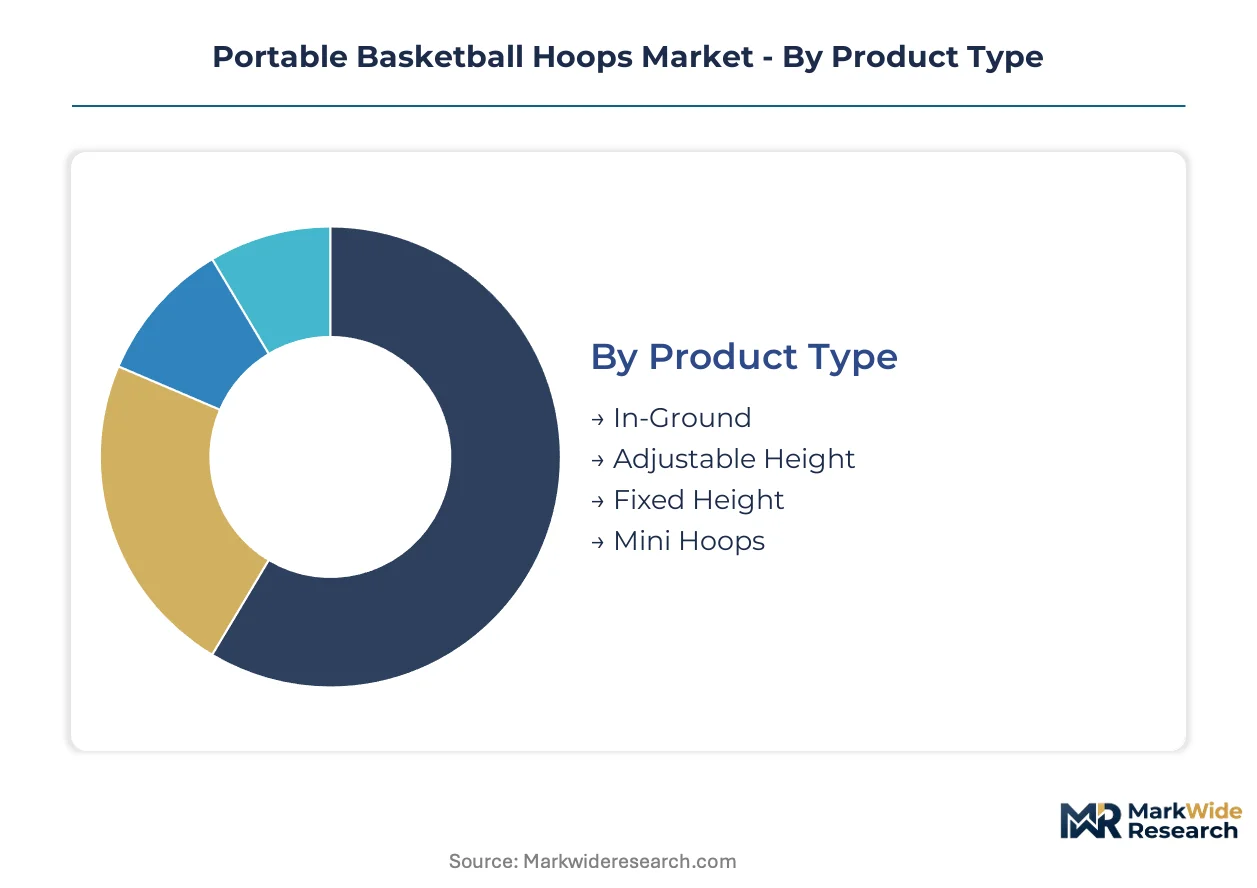
Portable basketball hoop segmentation reveals distinct replacement cycles across product tiers, with residential systems turning over every 5-7 years while institutional installations persist for 15-plus years. Understanding these temporal patterns enables inventory planning and margin optimization across manufacturer portfolios.
Product Type:
Replacement velocity varies dramatically across portable configurations, with mini hoops cycling fastest due to child outgrowth and adjustable systems commanding the longest useful lives through height range adaptability.
- Adjustable Height:Steel-framed telescoping poles with 7.5 to 10-foot rim range dominate suburban driveway installations. Families in Texas and Florida prioritize these systems for multi-child households where height progression extends product utility across developmental stages.
- Mini Hoops:Door-mounted polycarbonate backboards with foam padding target apartment dwellers and children under age 10. Urban renters in Chicago and Seattle drive volume for this segment where outdoor space constraints eliminate full-size alternatives.
- In-Ground:Permanent cemented installations with anchor kits serve dedicated court builders seeking stability over portability.
- Fixed Height:Single-position systems with welded steel poles occupy budget tiers and light institutional use.
Adjustable height systems anchor the volume base while mini hoops gain share at the steepest rate.
Material:
Cost tier stratification separates commodity inputs from performance-grade alternatives, with raw material selection directly determining end-market positioning and warranty exposure.
- Steel:Cold-rolled and galvanized pole fabrication supports adjustable height mechanisms and base frames. ASTM F1882 compliance mandates specific gauge thicknesses for tip-over resistance, elevating specification requirements across North American production.
- Acrylic:Cell-cast polymer backboards deliver glass-like rebound response at reduced weight and shatter risk. Premium residential buyers in California and New Jersey accept price premiums for rebound fidelity exceeding polycarbonate alternatives.
- Aluminum:Extruded and cast components reduce shipping weight for direct-to-consumer fulfillment channels.
- Polypropylene:Rotational-molded base reservoirs and backboard substrates dominate mass-market price tiers.
Steel construction captures the revenue core while acrylic backboards command the widest margin spreads.
Target Audience:
Procurement authority and budget cycle timing diverge sharply across customer types, with institutional buyers operating on fiscal year constraints and residential purchases tracking seasonal weather patterns.
- Home Use:Individual household purchases through big-box retail and Amazon channels concentrate in April through June installation windows. Suburban municipalities with active youth leagues show correlated demand spikes in Texas and Ohio markets.
- Schools:District-level procurement governed by capital equipment budgets and safety certification requirements. California and New York school districts increasingly require ASTM documentation as a bid precondition.
- Recreational:Municipal parks departments and community centers with grant-funded acquisition cycles.
- Professional:Training facilities and semi-pro organizations with performance-specification requirements.
Home use generates the transaction volume while schools drive specification upgrading across manufacturer portfolios.
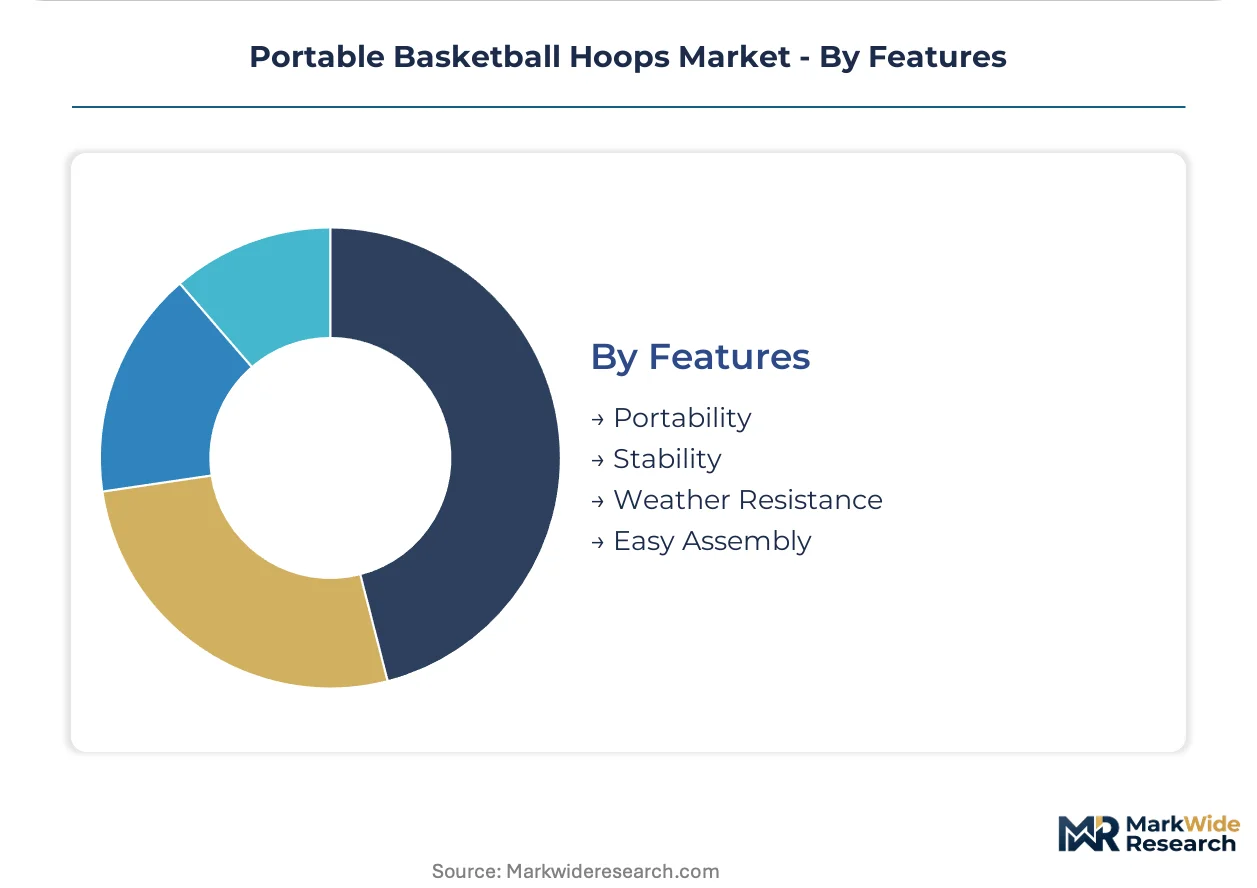
Features:
Engineering priority trade-offs separate convenience-focused residential buyers from safety-mandated institutional purchasers, with feature bundling strategies varying by channel.
- Stability:Anti-tip base designs with water or sand ballast compartments and weighted ground plates. ASTM F1882 testing protocols now require documented resistance metrics, pushing engineering investment toward certification compliance.
- Portability:Wheel casters and fillable base designs enabling single-person repositioning. Families in seasonal climates prioritize this feature for winter storage in garages and sheds.
- Weather Resistance:UV-stabilized backboard materials and powder-coated steel finishes for coastal and high-humidity exposure.
- Easy Assembly:Pre-drilled components and tool-minimized installation targeting direct-to-consumer fulfillment.
Stability engineering absorbs the greatest R&D allocation while portability features expand fastest among online-first brands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Premium pricing power concentrates in the United States while European markets absorb elevated compliance costs. ASTM certification requirements in North America create specification barriers that sustain margin structures. REACH-mandated material substitutions in Germany and France compress realized pricing through elevated sourcing overhead.
United States
Suburban driveway installation density in Texas and Florida sustains replacement cycles for adjustable-height systems. ASTM F1882 compliance documentation now functions as a bid precondition for school district procurement in California and New York. The Dallas-Fort Worth metroplex anchors mass-market distribution through big-box retail concentration.
Germany
Municipal park budgets in Bavaria and North Rhine-Westphalia drive institutional demand for certified stability systems. ECHA REACH restrictions on polypropylene additives elevate material sourcing costs for European-bound inventory. Stuttgart's manufacturing cluster hosts rotational molding specialists serving mass-market base production.
China
Export-oriented fabrication in Guangdong and Zhejiang provinces supplies global demand for steel-framed adjustable systems. GB standards for product safety create parallel certification requirements for domestic versus export production. The Pearl River Delta concentrates polyethylene rotational molding capacity for base reservoir manufacturing.
Canada
Seasonal storage patterns in Ontario and Quebec prioritize portability features for winter garage stowage. Health Canada product safety protocols align with ASTM frameworks for cross-border inventory efficiency. The Greater Toronto Area channels distribution through home improvement retailer networks.
United Kingdom
Youth league participation in the Midlands and North England sustains institutional procurement for school and community center installations. The UK's Product Safety and Metrology Authority enforces stability documentation requirements mirroring ASTM protocols. Manchester's logistics infrastructure supports direct-to-consumer fulfillment channel expansion.
Portable Basketball Hoops Market Competitive Landscape
Mass-market manufacturers and premium-system specialists split the market into divergent margin structures. The competitive landscape exhibits tiered concentration with three to four dominant participants in each price band. Strategic archetypes include polyethylene rotational molders serving big-box retail, welded-steel fabricators dominating dealer networks, and institutional-contract specialists leveraging compliance certification. Capacity expansion in rotational molding and backward integration into steel pole fabrication represent the primary competitive moves reshaping cost positions.
Within the mass-market tier, Lifetime Products exemplifies polyethylene-based production scaled through home improvement retailer relationships. Goalrilla occupies a position among premium welded-steel specialists emphasizing dealer network distribution and adjustable-system engineering. Spalding anchors the institutional-contract archetype, leveraging historical sporting goods relationships to sustain school and municipal procurement volume despite consumer-tier price compression.
| Leading Market Players |
|---|
| Spalding |
| Lifetime Products |
| Goalsetter |
| Bison |
| First Team Inc. |
| Goaliath |
| Barbarian Basketball Systems |
| Goalrilla |
| Huffy |
| Others |
Value Network & Pricing Analysis
Guangdong Province's rotational molding clusters command disproportionate leverage over mass-market base pricing, with polyethylene reservoir capacity expansion in Zhongshan and Foshan directly compressing realized margins for export-bound inventory. The Pearl River Delta's dominance in steel pole fabrication and polymer base production creates geographic pricing power that downstream distributors cannot easily arbitrage.
Pricing Analysis
Configured-to-order pricing spreads of 40-60 percent above standard SKUs capture family buyers seeking ASTM-certified stability documentation and acrylic backboard upgrades. Three-tier pricing structure across premium, standard, and economy levels separates welded-steel adjustable systems from polyethylene mass-market lines and fixed-height budget tiers. Cost compression in the economy segment intensifies because Chinese contract manufacturers are absorbing steel input volatility to maintain volume commitments. School districts exhibit the lowest price sensitivity due to safety certification preconditions, while apartment-dwelling mini-hoop buyers demonstrate acute elasticity to shipping cost fluctuations.
Supply Chain Analysis
Contract manufacturing concentrates among rotational molding specialists in Guangdong and Zhejiang provinces, with Lifetime Products and Goalrilla sourcing base reservoirs from overlapping supplier pools. Cold-rolled steel pole fabrication draws from Hebei mill complexes, while acrylic backboard extrusion rests on petrochemical feedstock from Singapore and South Korean resin suppliers. Single-source vulnerability in ASTM-certified third-party laboratory testing creates bottleneck risk for new product launches. Distribution runs through big-box retail concentration in Dallas-Fort Worth and direct-to-consumer fulfillment via Amazon's North American logistics network.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Portable basketball hoop demand tracks suburban housing construction cycles and youth league enrollment patterns, positioning the market for cyclical recovery as municipal infrastructure bonds and family recreation spending rebound from recent troughs.
For Market Incumbents: Insulate margin structures by securing captive polyethylene rotational molding capacity in Guangdong before raw material pass-through clauses expire. Deepen ASTM certification relationships with third-party laboratories to compress competitor launch windows. Defensive consolidation around welded-steel pole fabrication in Hebei mills offsets emerging hybrid polymer-steel substitute threats from coastal United States buyers.
For New Entrants and Emerging Players: Build out door-mounted mini-hoop fulfillment infrastructure targeting Chicago and Seattle apartment corridors where outdoor space constraints eliminate full-size alternatives. Capture white-space volume among urban renters through Amazon Marketplace storefronts with tool-minimized assembly positioning. Prioritize polycarbonate backboard sourcing from domestic rotational molders to bypass REACH compliance overhead that burdens European-bound competitors.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors welded-steel specialists with established dealer networks over polyethylene mass-market players facing margin compression. Long-term viability over the next decade hinges on backward integration into ASTM-certified testing relationships rather than raw material scale. Watch municipal park budget appropriations as the inflection signal—grant-funded procurement cycles in Texas and Florida typically lead consumer replacement demand by 12-18 months.
| Strategic Initiative | Industry Significance |
|---|---|
| ASTM Certification Pre-Positioning | Third-party laboratory relationships accelerate school district procurement cycles in California and New York. |
| Backward Integration into Steel Pole Fabrication | Hebei mill partnerships reduce exposure to cold-rolled steel price volatility and scrap metal availability. |
| Direct-to-Consumer Channel Expansion | Amazon Marketplace storefronts capture margin and customer data unavailable through sporting goods retail. |
| Acrylic Backboard Performance Tiering | Rebound quality differentiation justifies price steps above polycarbonate in California and New Jersey markets. |
| Seasonal Rental Model Piloting | Summer lease programs in Sun Belt metros align with transient suburban family migration patterns. |
Research Methodology
A spread of perspectives from rotational molding plant managers, big-box retail category buyers, school district procurement officers, and ASTM laboratory directors converged on the working assumptions. Primary fieldwork combined structured interviews with these stakeholders alongside secondary validation through customs records, SEC 10-K filings of sporting goods manufacturers, and municipal budget appropriation databases. Bottom-up unit shipment estimates from Guangdong and Zhejiang export data were triangulated against top-down spending projections derived from suburban housing construction permits and youth league enrollment statistics.
Demand-supply balance modeling across the analysis window incorporated product type segmentation by adjustable height, mini hoop, and fixed height configurations alongside material tier stratification and regional regulatory cluster differences. CAGRs were derived from regression analysis of historical replacement cycles and forward projection of driveway installation density in Texas and Florida. Forecast inputs included municipal infrastructure bond issuance trajectories and REACH compliance cost pass-through assumptions for European-bound inventory.
Stress conditions across steel price volatility, ASTM certification timeline compression, and REACH polypropylene additive restrictions were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about suburban development patterns and school district capital equipment budget cycles. Quarterly review of municipal park grant allocations and rotational molding capacity utilization in Guangdong is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sports Equipment
Global Sports Bicycle Market
Sports Equipment
Baseball Sliding Mitts Market
Sports Equipment
Medicine Balls Market
Sports Equipment
Cleat Market
Sports Equipment
Synthetic Ice Skating Rink Market
Sports Equipment
Equestrian Equipment Market
Sports Equipment
Riding Gear Market
Sports Equipment
US Sports Flooring Market
Sports Equipment
Europe Running Gear Market
Sports Equipment
Cricket Equipment Market
Sports Equipment
Water Polo Suits Market
Sports Equipment
Football Market
Sports Equipment
Padel Balls Market
Sports Equipment
Bicycle Drivetrain Cassette Market
Sports Equipment
Athletic Mask Market
Sports Equipment
Surfboard Market