
 Trail Shoes Market | 2026-2036
Trail Shoes Market Size, Share, and Industry Trends Forecast 2026-2036
Trail Shoes Market Analytics
Buyer concentration in the trail shoes category is restructuring as specialty running shops lose ground to direct-to-consumer platforms and mass sporting goods chains. Nike, Inc. leverages its digital ecosystem and SNKRS platform to control premium releases and capture data on trail runner preferences. Adidas AG anchors its trail portfolio through TERREX sub-brand investments in Continental rubber outsole technology. Salomon Group specializes in technical mountain running footwear, competing primarily through European alpine heritage and precise fit systems developed at its Annecy design center.
Trail shoes are purpose-built footwear engineered with lugged rubber outsoles, reinforced toe caps, and water-resistant membranes to protect against uneven terrain, moisture ingress, and abrasive surfaces during off-road locomotion. Manufacturing integrates injection-molded EVA midsoles, welded synthetic overlays, and multi-directional tread patterns tested on variable substrates from granite scree to muddy singletrack. Cushioned trail running models now command the largest revenue pool as marathon road runners migrate to softer surfaces, while waterproof configurations sustain higher unit economics through Gore-Tex licensing fees and seasonal pricing power. Minimalist designs occupy a narrowing but defensible niche among biomechanical purists seeking ground feel and reduced heel-to-toe drop.
California's Proposition 65 mandates warning labels on products containing phthalates or heavy metals, forcing reformulation of synthetic leather components and adhesive systems. The EU REACH regulation restricts per- and polyfluoroalkyl substances in durable water repellent coatings, compelling suppliers to accelerate fluorocarbon-free chemistry transitions. ISO 20344 puncture resistance standards shape safety expectations for technical hiking variants sold through European outdoor retailers. Stakeholders must monitor how biodegradable midsole foams and recycled polyester uppers evolve from marketing claims to certified performance benchmarks that determine shelf placement.
Market Dynamics
Weekend trail runners now dominate volume flows, forcing manufacturers to recalibrate cushioning platforms and aesthetic positioning away from elite technical specifications toward comfort-first designs that accommodate irregular usage patterns.
Growth Catalysts
- REACH chemical standards:European ECHA enforcement is accelerating fluorocarbon-free durable water repellent transitions, creating first-mover advantages for suppliers with certified alternative chemistries.
- National park visitation:United States federal trail system investments are expanding accessible terrain, directly stimulating replacement purchase cycles among casual outdoor participants.
- Injection-molded EVA midsoles:Advanced foam densities now deliver road-running energy return in lugged configurations, erasing performance gaps that previously segmented trail and road buyer pools.
Market Restraints
- Continental rubber supply concentration:Premium outsole compound sourcing clusters with German specialty chemical producers, exposing brands to input cost volatility and allocation constraints.
- Gore-Tex licensing fees:Waterproof membrane certification requirements sustain elevated unit economics that compress margin flexibility in mid-tier price bands.
- California Proposition 65:Phthalate disclosure mandates force reformulation of synthetic leather components and adhesive systems, extending product development timelines.
Strategic Opportunities
- Biodegradable midsole foams:Certified compostable cushioning platforms offer shelf placement differentiation as European outdoor retailers implement sustainability scoring.
- Direct-to-consumer platforms:Nike's SNKRS model demonstrates data capture potential for trail runner preference mapping, bypassing specialty retail margin extraction.
- Recycled polyester uppers:Post-consumer waste stream integration addresses ESG procurement criteria emerging among institutional outdoor recreation buyers.
Industry Challenges
- ISO 20344 puncture resistance certification:European safety standard testing protocols create compliance timeline friction for technical hiking variants targeting multi-terrain positioning.
- Welded synthetic overlay integration:Legacy stitching equipment reconfiguration demands capital expenditure that mid-cap manufacturers struggle to amortize across limited SKU counts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Trail Shoes Market |
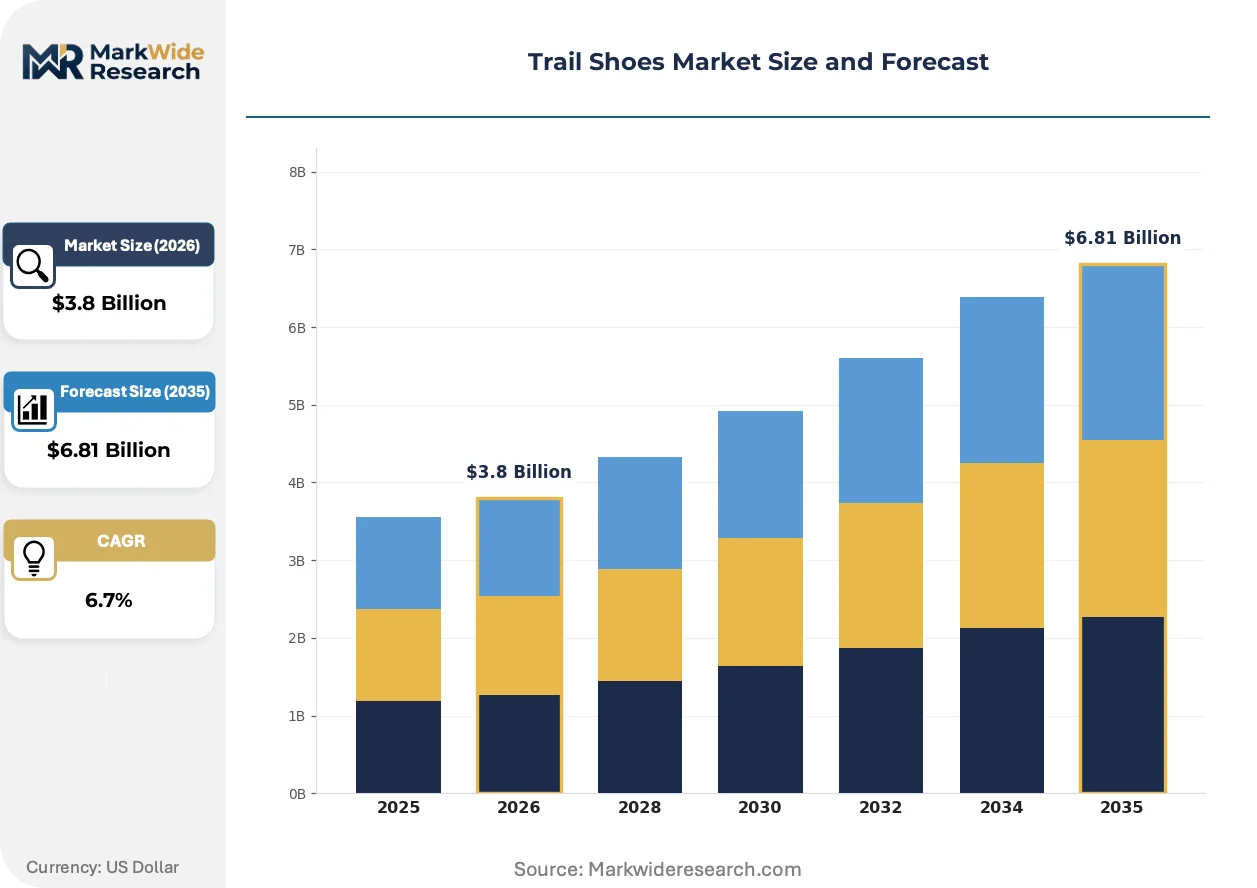
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Minimalist, Cushioned, Waterproof, Trail Running Target Audience: Runners, Hikers, Casual Users, Competitive Athletes Material: Synthetic, Mesh, Rubber, Leather Performance Feature: Traction, Stability, Breathability, Support |
| Companies Covered | Nike, Inc., Adidas AG, Salomon Group, Hoka One One, Brooks Sports, Inc., Asics Corporation, New Balance Athletics Inc., Deckers Brands, Skechers USA Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Trail Shoes Market Evolving Landscape
Material science convergence with regulatory chemistry mandates is compressing traditional development cycles, forcing simultaneous performance validation and compliance certification before commercialization.
Peba-based supercritical foam is absorbing impact energy previously managed through heavier TPU stabilizers. Marathon road runners migrating to trail surfaces demand this compound's density-to-resilience ratio. Weekend trail runners now expect road-running responsiveness in lugged configurations, collapsing the technical segmentation that previously separated product categories.
ECHA REACH restrictions on per- and polyfluoroalkyl substances are eliminating legacy durable water repellent chemistries from European supply chains. Footwear manufacturers must reformulate coating systems without performance degradation. Waterproof trail configurations face the steepest reformulation burden as seasonal pricing power depends on verified moisture protection claims.
Buyer concentration is fragmenting across channel types as specialty running shops cede ground to mass sporting goods chains and brand-owned digital platforms. Weekend trail runners increasingly research online before purchasing through lowest-friction fulfillment options. United States national park gateway communities exhibit the most pronounced channel shift, with mobile-optimized direct purchase displacing pre-trip specialty retail visits.
Trail Shoes Market Segmentation
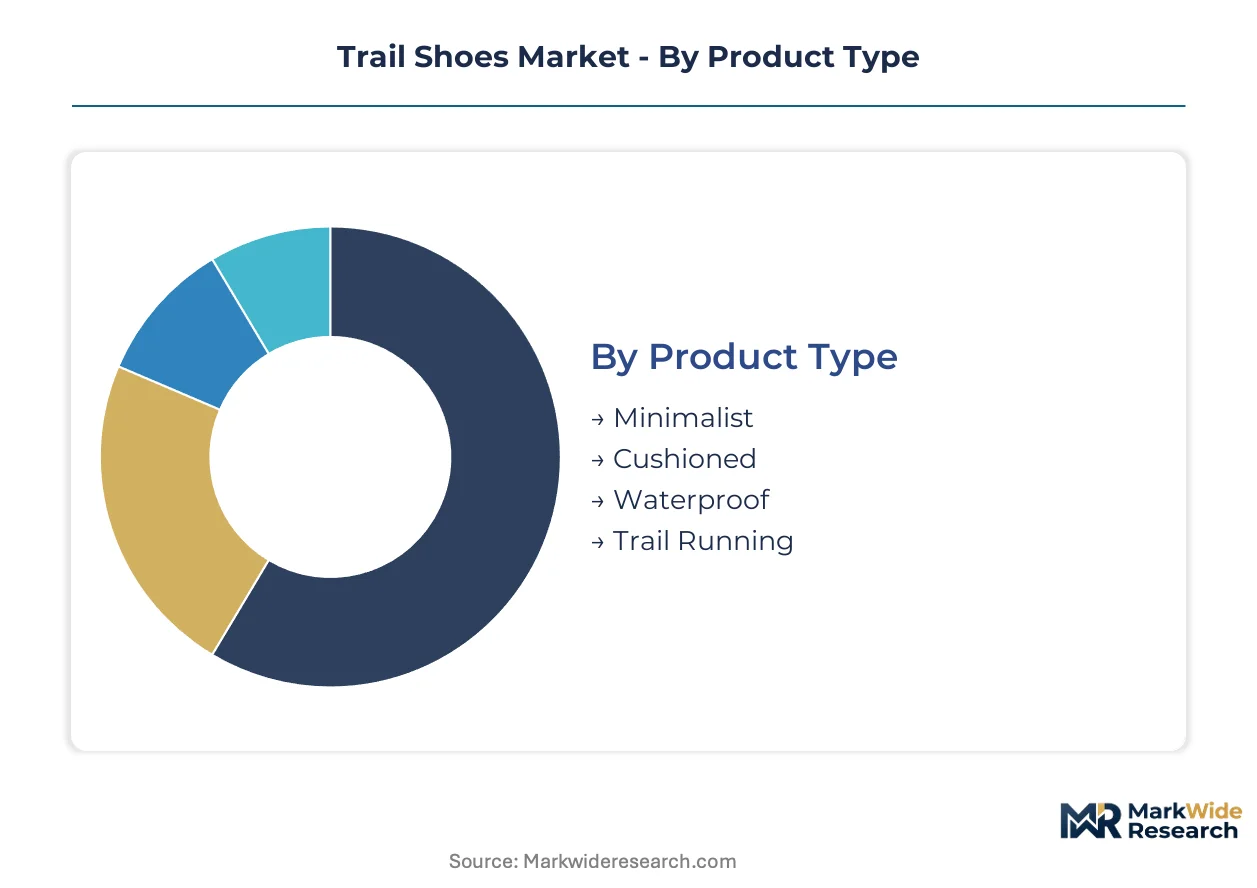
Trail shoes segment along functional purpose, user intensity, and material construction—each axis governing distinct replacement cadences and margin profiles. Manufacturers calibrate platform investments across these dimensions to capture upgrade cycles from weekend runners while defending technical credibility among alpine specialists.
Product Type:
Replacement cycles vary sharply by construction philosophy, with cushioning platforms demanding refresh every 300-500 miles versus waterproof membranes aging through seasonal wear patterns.
- Cushioned:Injection-molded EVA or Peba-based supercritical foam midsoles absorb impact energy across extended distances. United States national park gateway communities concentrate demand as marathon road runners migrate to softer surfaces and irregular trail geometries.
- Waterproof:Gore-Tex or eVent membrane laminates block moisture ingress while sacrificing breathability. European alpine regions sustain premium pricing through verified weather protection claims despite ECHA REACH fluorocarbon chemistry transitions.
- Minimalist:Zero-drop platforms with thin rubber outsoles prioritize ground feel and proprioceptive feedback. Biomechanical purists in Pacific Northwest trail clusters sustain this narrowing niche.
- Trail Running:Hybrid constructions balancing responsiveness with lugged traction for variable substrates. Weekend runners in Colorado Front Range and California Sierra Nevada foothills drive volume through multi-terrain versatility.
Volume placements concentrate in Cushioned configurations; the faster expansion belongs to Trail Running as category boundaries dissolve between road and off-road disciplines.
Target Audience:
User intensity tiers dictate pricing tolerance and feature complexity, with competitive segments demanding ISO-certified precision while casual buyers prioritize aesthetic flexibility.
- Runners:Cadence-optimized geometries with 4-8mm heel-to-toe drop and rock plates for stone bruise protection. United States trail racing participation growth concentrates demand in cushioned platforms with road-running energy return.
- Hikers:Stiffened midsoles and aggressive lug patterns for load-bearing stability on technical ascents. European outdoor retailers enforce ISO 20344 puncture resistance certification for this segment's safety positioning.
- Casual Users:Comfort-first designs accommodating irregular usage without performance degradation. California Proposition 65 compliance costs compress margin flexibility in this price-sensitive tier.
- Competitive Athletes:Sub-250 gram constructions with precise fit systems for alpine skyrunning and vertical kilometer events. Annecy-design-center heritage brands anchor technical credibility here.
Revenue concentration sits with Runners; Competitive Athletes deliver the steepest per-unit margins despite smaller absolute volumes.
Material:
Supply chain geography and regulatory chemistry mandates increasingly determine material selection, with recycled content thresholds influencing procurement decisions.
- Synthetic:Welded polyurethane overlays and TPU stabilizers deliver structural integrity without stitching weight penalties. REACH-compliant phthalate-free formulations now dominate European sourcing.
- Mesh:Engineered polyester weaves balance breathability against debris intrusion. Post-consumer recycled fiber integration addresses ESG scoring criteria among institutional outdoor recreation buyers.
- Rubber:Continental or Vibram outsole compounds provide multi-directional traction across granite scree and muddy singletrack. German specialty chemical producers control premium compound allocation.
- Leather:Full-grain or nubuck uppers for durability in extended backpacking contexts. California Proposition 65 heavy metal disclosure mandates force tannery certification verification.
Procurement weight shifts toward Mesh as recycled content mandates harden; Rubber maintains irreplaceable performance positioning despite supply concentration risks.
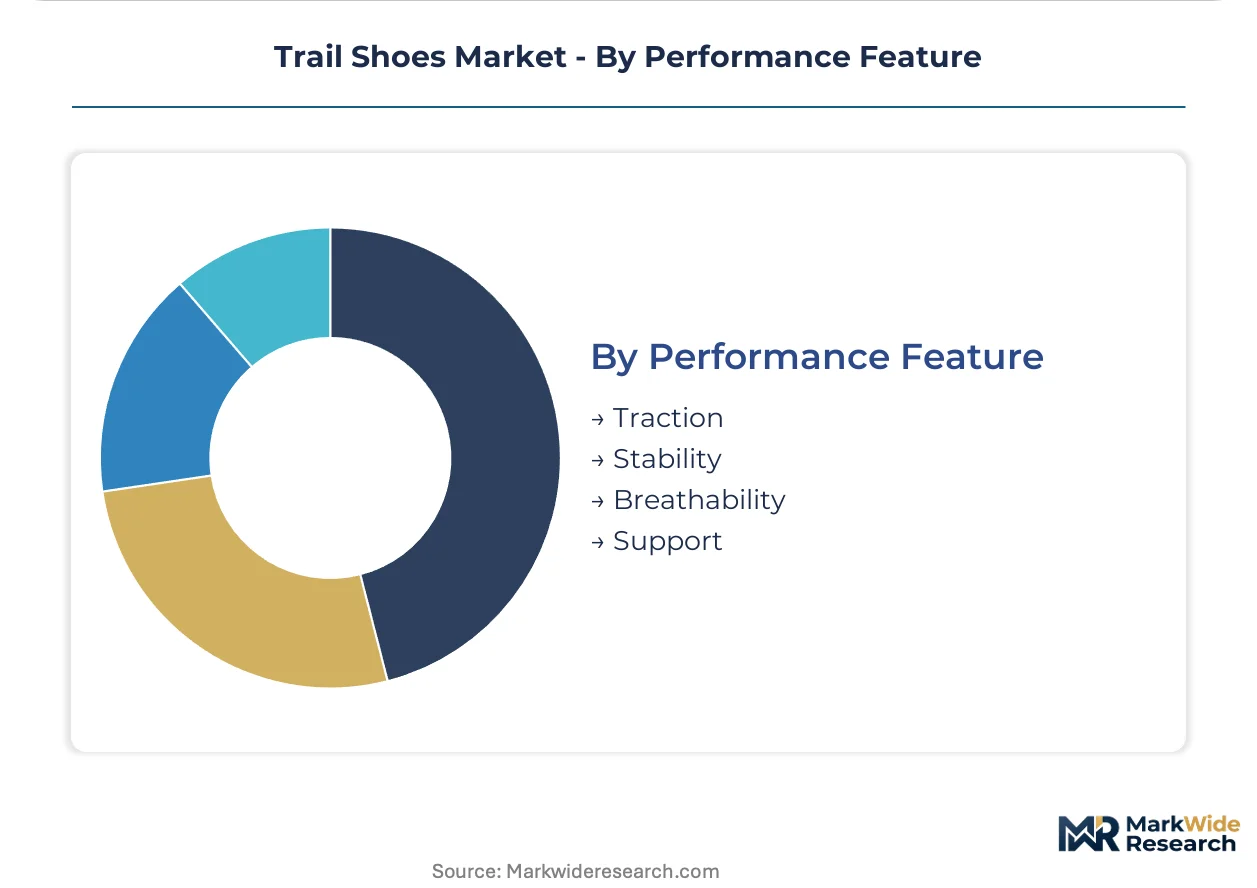
Performance Feature:
Feature prioritization reflects terrain specificity and injury history, with traction and stability commanding development resources over breathability optimization.
- Traction:Multi-directional lug geometries and sticky rubber compounds calibrated for wet granite and loose scree. Pacific Northwest rainforest trails and Scottish Highlands peat bogs demand aggressive tread patterns.
- Stability:Medial posting and TPU heel counters controlling pronation across uneven surfaces. Heavier pack loads in European Alpine hut-to-hut routes sustain this feature's relevance.
- Breathability:Perforated mesh panels and moisture-wicking linings managing thermal load during high-output efforts. Desert Southwest trail systems in Arizona and Utah prioritize this attribute.
- Support:Arch contours and structured midfoot wraps accommodating flat-footed biomechanics. Physical therapist recommendations in United States metropolitan markets drive segment loyalty.
Engineering resources pool around Traction; Support features gain share fastest as trail running mainstreams among previously sedentary demographics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States national park visitation and trail system investments concentrate demand for cushioned and trail running configurations, while European regulatory chemistry mandates reshape supplier qualification requirements across multiple jurisdictions.
United States
National Park Service visitation data drives replacement purchase cycles in gateway communities from Moab to Asheville. California's Proposition 65 enforces phthalate disclosure on synthetic leather components sold through retail channels. Colorado's Front Range cluster anchors weekend trail runner volume, with Boulder and Denver metro areas exhibiting pronounced channel shift toward mobile-optimized direct purchase.
Germany
Continental rubber compound sourcing concentrates with specialty chemical producers in Leverkusen and Krefeld, exposing brands to input allocation constraints. ECHA REACH enforcement accelerates fluorocarbon-free durable water repellent transitions across footwear supply chains. Bavaria's Alpine regions sustain technical hiking demand through ISO 20344 puncture resistance certification requirements enforced by outdoor retailers.
France
Alpine skyrunning and vertical kilometer events concentrate competitive athlete demand in Annecy and Chamonix design centers. EU Green Deal procurement criteria harden recycled content thresholds for institutional outdoor recreation buyers. Auvergne-Rhône-Alpes manufacturing clusters specialize in precise fit systems developed for technical mountain running footwear.
Japan
METI standards for footwear safety and labeling shape import requirements for trail shoes entering domestic distribution. Kansai region manufacturing clusters integrate welded synthetic overlay production for lightweight trail running configurations. Osaka-based retail networks prioritize breathability optimization for humid subtropical trail conditions.
United Kingdom
Scottish Highlands peat bog terrain demands aggressive multi-directional tread patterns from specialized manufacturers. Post-Brexit UKCA marking requirements replace CE conformity assessment for footwear sold through British outdoor retailers. Lake District trail running communities concentrate demand for hybrid constructions balancing responsiveness with lugged traction.
Trail Shoes Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue technical specialization and sustainability certification as differentiation vectors. The vendor base arranges across three maturity tiers: global sportswear conglomerates with digital ecosystem control, European alpine heritage specialists with design center proximity, and regional comfort-first brands serving price-sensitive casual users. Strategic archetypes include platform owners leveraging data capture, compound technology licensors, and recycled material integrators. Competitive moves center on direct-to-consumer channel expansion and fluorocarbon-free chemistry transitions.
Among Oregon-based sportswear conglomerates, Nike, Inc. exemplifies platform-driven market control through digital ecosystem investments. Adidas AG, organized as a German Aktiengesellschaft, anchors technical credibility through sub-brand specialization in rubber outsole technology. Salomon Group represents Annecy-design-center heritage positioning for alpine technical footwear. These three entities occupy distinct competitive vectors: data-capture platform ownership, compound technology licensing, and mountain sports heritage specialization.
| Leading Market Players |
|---|
| Nike, Inc. |
| Adidas AG |
| Salomon Group |
| Hoka One One |
| Brooks Sports, Inc. |
| Asics Corporation |
| New Balance Athletics Inc. |
| Deckers Brands |
| Skechers USA Inc. |
| Others |
Value Network & Pricing Analysis
Weekend trail runner procurement preferences for comfort-first designs are forcing manufacturers to absorb higher input costs from certified fluorocarbon-free chemistries and recycled polyester uppers, compressing margin flexibility in mid-tier price bands while premium waterproof configurations retain pricing power through Gore-Tex licensing leverage.
Pricing Analysis
Volume placements concentrate in cushioned trail running configurations where road-running energy return expectations have collapsed technical segmentation, while waterproof variants sustain premium positioning through membrane certification costs. Price differentiation hinges on REACH-compliant chemistry tiers and Continental rubber outsole sourcing. Cost compression in casual user tiers intensifies because California Proposition 65 reformulation expenses flow through synthetic leather components. Competitive athletes exhibit least price sensitivity; casual users in gateway communities demonstrate highest elasticity.
Supply Chain Analysis
Single-source vulnerability sits with German specialty chemical producers in Leverkusen and Krefeld controlling premium Continental rubber compound allocation. Manufacturing draws from China for welded synthetic overlay production, Vietnam for mesh upper assembly, and Germany for outsole chemistry. Tariff exposure on finished footwear imports into the United States creates margin pressure. Distribution runs through mass sporting goods chains, direct-to-consumer platforms, and declining specialty running shops.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story where ECHA REACH fluorocarbon restrictions erect barrier-to-entry moats favoring incumbents with certified alternative chemistry portfolios and established European supplier relationships.
For Market Incumbents: To counter direct-to-consumer platform erosion of specialty retail, secure backward integration into fluorocarbon-free durable water repellent chemistry development and expand Annecy or Bavaria design center capacity for technical hiking certification. Channel control through SNKRS-style data capture ecosystems defends against mass sporting goods chain commoditization. For New Entrants and Emerging Players: The mid-tier price gap between premium Gore-Tex configurations and economy synthetic alternatives offers white-space entry through biodegradable midsole foam certification targeting European outdoor retailer sustainability scoring. Weekend trail runners in United States national park gateway communities represent the most penetrable segment. Go-to-market execution prioritizes mobile-optimized direct purchase bypassing legacy retail margin extraction. For Investors and Strategic Acquirers: The window for entry favors compound technology licensors with certified REACH-compliant chemistry portfolios and regional comfort-first brands with recycled polyester integration capabilities. Long-term viability centers on sustainability certification moats widening over the projection horizon. Watch for fluorocarbon-free chemistry transition completion rates as inflection indicator for supplier qualification consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Fluorocarbon-Free Chemistry Transition | ECHA REACH enforcement accelerates supplier qualification consolidation among compliant compound developers. |
| Direct-to-Consumer Platform Expansion | Nike's SNKRS model demonstrates data capture potential for trail runner preference mapping bypassing retail. |
| Biodegradable Midsole Certification | Certified compostable cushioning platforms secure shelf placement differentiation at European outdoor retailers. |
| Recycled Polyester Integration | Post-consumer waste stream integration addresses ESG procurement criteria among institutional outdoor recreation buyers. |
| Continental Rubber Supply Agreement | Long-term compound allocation contracts with German specialty chemical producers mitigate input cost volatility. |
Research Methodology
Document review covered customs and trade data, SEC footwear sector filings, and ECHA chemical registration databases, complemented by interviews with trail shoe brand product managers, European outdoor retailer category buyers, United States national park concession procurement officers, and specialty running shop owners. Secondary validation drew from Nielsen retail audit data, national park visitation statistics, and ISO certification registries. Bottom-up SKU-level volume builds were triangulated against top-down category expenditure estimates.
Market size outputs across the projection horizon reflect segmentation by product type, target audience intensity tier, material construction, and performance feature prioritization. CAGRs were derived from replacement cycle analysis calibrated to mileage-based refresh rates and seasonal purchasing patterns. Key forecast inputs incorporated ECHA REACH enforcement timelines and United States federal trail system investment flows.
Inputs from primary stakeholder interviews were available through the study window; gaps in forward-looking fluorocarbon-free chemistry performance validation introduce uncertainty bands around waterproof segment projections. Forecasts reflect documented assumptions on regulatory enforcement intensity and casual user segment expansion. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sports Equipment
Global Stand-Up Paddleboard Market
Sports Equipment
Carbon Fiber Badminton Racket Market
Sports Equipment
Middle East and Africa Stand-Up Paddleboard Market
Sports Equipment
Windsurf Masts Market
Sports Equipment
Surface Water Sports Equipment Market
Sports Equipment
Quad Skate Market
Sports Equipment
Boxing Equipment Market
Sports Equipment
Global Golf Rangefinders Market
Sports Equipment
Skydiving Equipment Market
Sports Equipment
Golf Equipment Market
Sports Equipment
Equestrian Equipment Market
Sports Equipment
United States Running Gear Market
Sports Equipment
Clay Pigeon Thrower Market
Sports Equipment
Sports and Athletic Insoles Market
Sports Equipment
Kung Fu Uniform Market
Sports Equipment
Cross Training Shoes Market