
 North America Spice and Herb Extracts Market | 2026-2036
North America Spice and Herb Extracts Market Size, Share, and Industry Trends Forecast 2026-2036
North America Spice and Herb Extracts Market Analytics
Mexico's Yucatan Peninsula is narrowing its historic supply gap for certified organic vanilla and annatto extracts through cooperative processing investments. McCormick & Company leverages its integrated sourcing network across three continents to secure raw material consistency for North American flavor houses. Kerry Group anchors its botanical platform in Wisconsin and Illinois facilities, competing on clean-label extraction technologies that reduce solvent residues. Givaudan differentiates through biotechnology-derived rare spice molecules that bypass agricultural volatility.
Spice and herb extracts comprise concentrated bioactive compounds—essential oils, oleoresins, and standardized polyphenols—recovered through supercritical CO2 extraction, solvent percolation, or steam distillation, typically standardized to marker compound percentages for batch consistency. These extracts serve primarily as flavor modulators, natural preservatives, and functional actives in formulated consumer products. Liquid extracts dominate volume flows into beverage and sauce applications where solubility drives formulation ease, while powdered extracts command premium positioning in nutraceutical capsules and dry seasoning blends where shelf stability and dosing precision determine procurement decisions. The organic form segment exhibits the steepest trajectory as CPG brands reformulate around USDA Organic and Non-GMO Project verification requirements.
FDA GRAS self-affirmation and USDA Organic certification govern ingredient acceptance timelines and label claim legitimacy across the United States, while Health Canada's Natural Health Product Directorate imposes distinct monograph compliance for cross-border nutraceutical sales. The EPA's evolving stance on residual solvent limits in extraction processes is forcing capital retooling among mid-scale processors. Stakeholders must monitor how Mexico's COFEPRIS alignment with US pharmacopeial standards reshapes nearshoring economics for botanical raw material finishing.
Market Dynamics
Clean-label reformulation mandates from CPG brands are compressing extraction technology upgrade cycles, forcing processors to retire solvent-heavy infrastructure before depreciation schedules allow.
Growth Catalysts
- USDA Organic certification thresholds:Reformulation deadlines for legacy seasoning portfolios are pulling forward contract volumes for certified oleoresin suppliers.
- Supercritical CO2 extraction:Equipment cost curves and solvent residue compliance are accelerating adoption among mid-scale Wisconsin and Illinois processors.
- California functional food corridor:Beverage and plant-based meat formulators are consolidating procurement around single-source botanical extract partnerships.
Market Restraints
- Vanilla bean price volatility:Madagascar supply interruptions and speculative commodity positions are compressing margin predictability for natural flavor houses.
- GRAS notification backlog:FDA's expanded documentation requirements for novel botanical actives are extending time-to-market for innovation pipelines.
- Steam distillation energy intensity:Natural gas price exposure in extraction operations is creating cost disadvantages versus synthetic alternatives.
Strategic Opportunities
- Mexico Yucatan cooperative infrastructure:Organic vanilla and annatto processing investments are narrowing certification gaps for nearshored raw material finishing.
- Biotechnology-derived rare molecules:Fermentation platforms for saffron and vanilla compounds are bypassing agricultural yield constraints and price cycles.
- EPA residual solvent rulemaking:Anticipated tightening of ethylene dichloride limits is creating first-mover advantage for supercritical CO2 equipment installers.
Industry Challenges
- Extraction chemist talent scarcity:Supercritical CO2 and enzyme-assisted extraction expertise concentrates in food science programs with limited annual output.
- Dual certification complexity:Simultaneous USDA Organic and FDA GRAS self-affirmation timelines require parallel documentation streams that strain quality assurance bandwidth.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Spice and Herb Extracts Market |
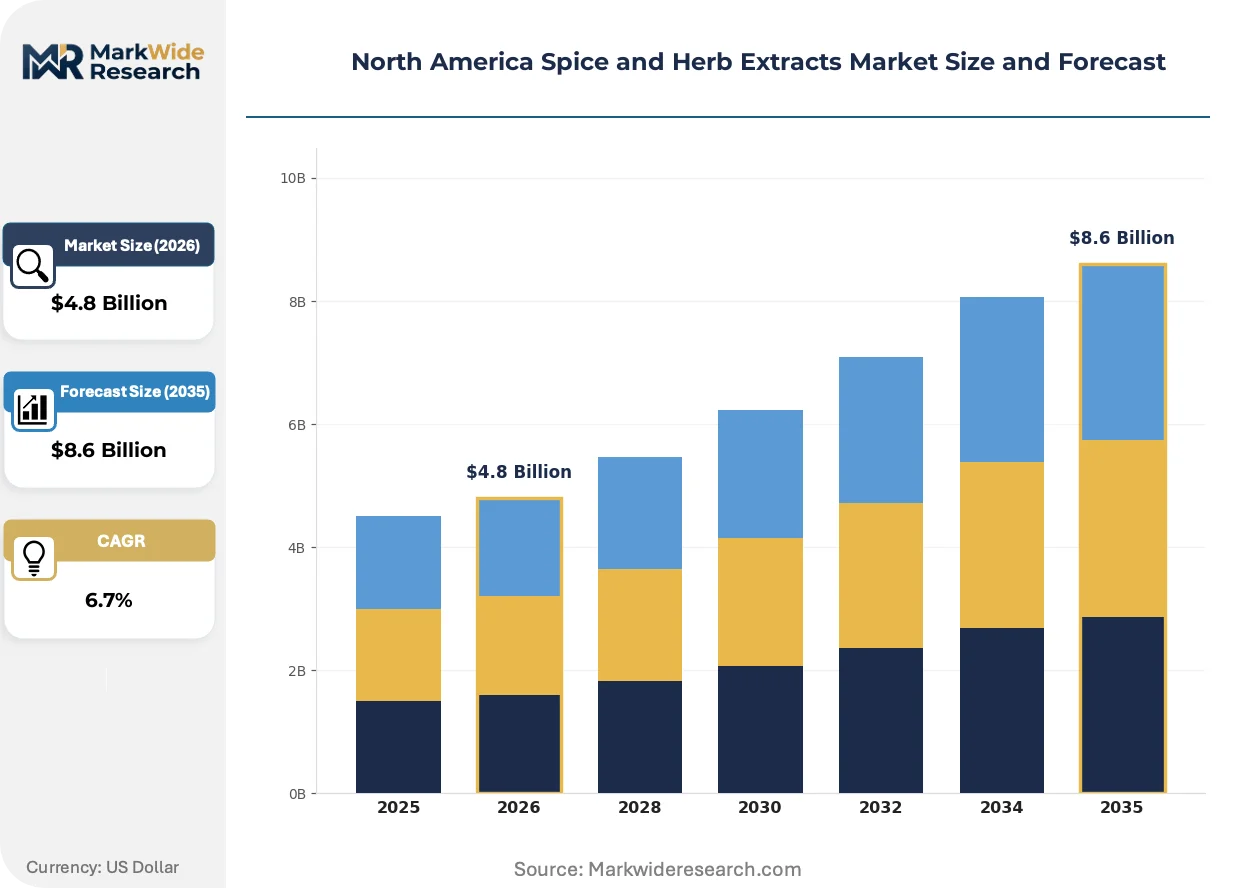
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid Extracts, Powdered Extracts, Solid Extracts, Tinctures End User: Food Industry, Pharmaceutical Sector, Cosmetic Industry, Nutraceuticals Application: Flavoring, Preservation, Coloring, Nutritional Enhancement Form: Organic, Conventional, Freeze-Dried, Concentrated |
| Companies Covered | McCormick & Company, Kerry Group, Givaudan, Dohler GmbH, Firmenich SA, Olam International, Sensient Technologies, International Flavors & Fragrances, Kemin Industries, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Spice and Herb Extracts Market Evolving Landscape
Extraction technology convergence with biotechnology platforms is fragmenting competitive advantage sources away from agricultural sourcing relationships toward controlled-environment production systems.
Supercritical CO2 extraction systems with integrated real-time composition monitoring are digitizing batch consistency assurance for high-value spice oleoresins. Premium sauce and beverage formulators in California are specifying these systems in supplier qualification protocols. The technology is digitizing quality control labor costs while compressing rejection rates for off-specification deliveries.
EPA's evolving residual solvent enforcement posture under the Toxic Substances Control Act is retooling capital allocation across mid-scale processors. Enforcement discretion letters and consent decree patterns are signaling preference for aqueous and supercritical methods. Illinois and Wisconsin extraction facilities are responding with accelerated equipment replacement schedules ahead of formal rule finalization.
Direct procurement contracts between CPG brands and single-origin cooperatives are shortening traditional distributor intermediation layers in vanilla and annatto supply chains. Mexican Yucatan processing clusters are capturing margin previously absorbed by layered trading relationships. This disintermediation is most visible in California functional food manufacturing where traceability requirements favor verified origin documentation.
North America Spice and Herb Extracts Market Segmentation
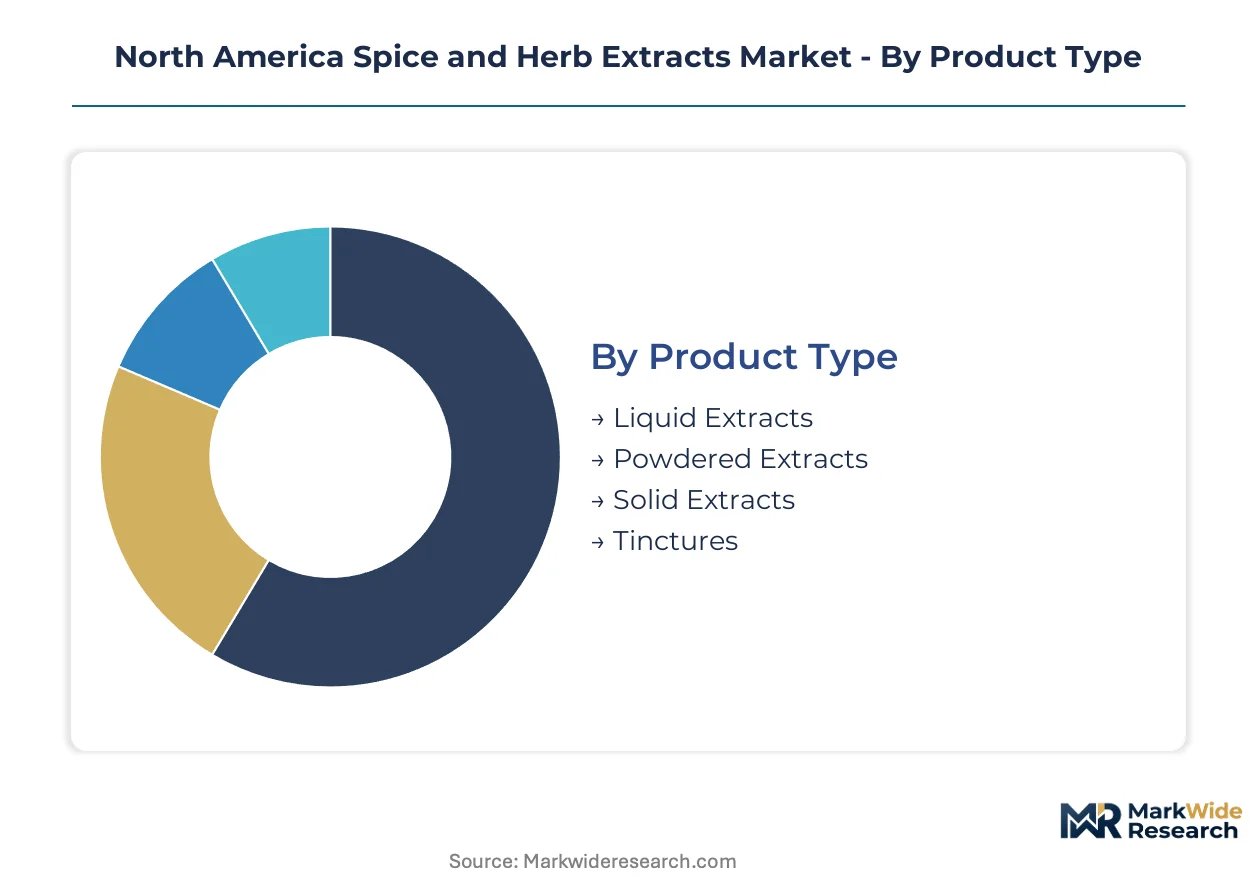
Segmentation in the North America spice and herb extracts market reflects divergent technical requirements across formulation types and end-use specifications. Procurement patterns vary sharply between beverage manufacturers seeking solubility and nutraceutical brands prioritizing shelf stability.
Product Type:
After-sales service intensity concentrates in liquid extract systems requiring calibration support for dosing equipment and filtration maintenance.
- Liquid Extracts:These comprise hydroalcoholic or glycerin-based solutions standardized to specific gravities and marker compound percentages. California beverage formulators and sauce manufacturers in Illinois specify liquid formats for rapid dispersion in aqueous matrices, driving procurement around solubility certificates and cold-chain integrity documentation.
- Powdered Extracts:Spray-dried or vacuum-dried concentrates with carrier substrates for flowability. Nutraceutical capsule manufacturers in Wisconsin and dry seasoning blenders prioritize these for dosing precision and extended shelf stability, with organic certification commanding sourcing premiums.
- Solid Extracts:Viscous pastes or semi-solid concentrates produced through vacuum concentration. Bakery and confectionery applications in Mexico favor these for intense flavor impact in reduced-moisture formulations.
- Tinctures:Alcohol-based preparations with defined herb-to-menstruum ratios. Health product manufacturers in Canada specify these for natural health product monograph compliance.
Liquid extracts hold the largest share; momentum sits with powdered extracts.
End User:
Cost tier stratification separates commodity seasoning houses from premium pharmaceutical extract buyers on specification stringency and certification burden.
- Food Industry:Sauce, snack, and ready-meal manufacturers procuring oleoresins and essential oils for flavor modulation. Clean-label reformulation deadlines in California and Illinois are accelerating contract volumes for certified organic suppliers.
- Pharmaceutical Sector:Formulators requiring USP-grade extracts with documented marker compound consistency and heavy metal testing. FDA GRAS self-affirmation timelines govern acceptance protocols for novel botanical actives.
- Cosmetic Industry:Personal care brands specifying standardized polyphenol extracts for antioxidant claims. EPA residual solvent compliance is retooling supplier qualification criteria.
- Nutraceuticals:Dietary supplement manufacturers driving demand for clinically dosed standardized extracts. Health Canada's Natural Health Product Directorate imposes distinct monograph requirements for cross-border sales.
Food industry procurement dominates volume; nutraceuticals are climbing the fastest on functional positioning premiums.
Application:
Volume concentration aligns with preservation applications where natural alternatives displace synthetic additives in processed foods.
- Flavoring:Essential oil and oleoresin deployment across beverage, savory, and confectionery matrices. Vanilla and capsicum extracts anchor procurement in California's functional food corridor.
- Preservation:Rosemary and oregano extracts with documented antimicrobial activity replacing benzoates and sorbates. USDA Organic certification thresholds are pulling forward contract volumes for compliant suppliers.
- Coloring:Annatto, turmeric, and paprika extracts providing stable natural hues. Mexican Yucatan processing investments are narrowing certification gaps for nearshored annatto finishing.
- Nutritional Enhancement:Standardized polyphenol and terpenoid extracts for functional positioning. Supercritical CO2 extraction adoption is accelerating among mid-scale Wisconsin processors serving this segment.
Flavoring commands the greatest procurement volume; nutritional enhancement shows the steepest expansion trajectory on functional food convergence.
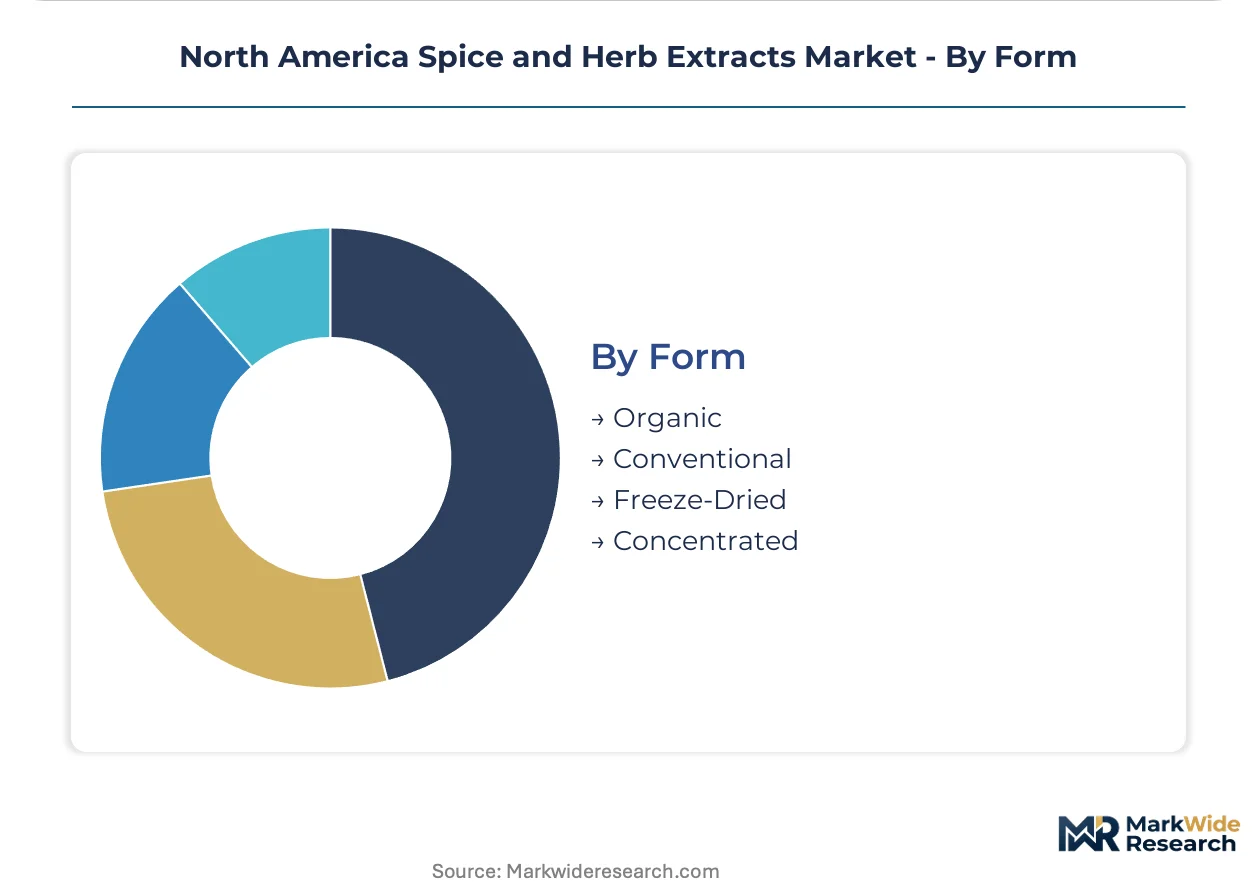
Form:
Supply concentration in organic certification is reshaping procurement relationships toward verified-origin cooperatives with full traceability documentation.
- Organic:USDA Organic and Non-GMO Project verified extracts commanding sourcing premiums. CPG brands across California and Illinois are reformulating legacy portfolios around these specifications.
- Conventional:Standardized extracts without organic certification serving cost-sensitive seasoning and industrial flavor applications. Price volatility in vanilla bean supply is compressing margin predictability for natural flavor houses in this tier.
- Freeze-Dried:Low-temperature dehydrated extracts preserving volatile aromatic compounds. Premium culinary and specialty beverage applications specify these for sensory fidelity.
- Concentrated:High-potency extracts with reduced water content for freight efficiency and storage economy. Mexico's herbal processing clusters are capturing margin through direct procurement contracts with CPG brands.
Conventional forms retain volume leadership; organic certification is gaining share fastest on clean-label mandate compliance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Veracruz's refrigerated cargo terminals anchor Mexico's role in vanilla and annatto transshipment, while Interstate 80's logistics spine connects Illinois and Wisconsin processing clusters to California formulation demand.
United States
California's functional food corridor drives procurement concentration for beverage and plant-based meat formulators seeking single-source botanical partnerships. FDA GRAS notification requirements for novel botanical actives are extending supplier qualification timelines. Wisconsin and Illinois extraction facilities are accelerating supercritical CO2 equipment replacement ahead of anticipated EPA residual solvent rulemaking.
Mexico
Yucatan Peninsula cooperatives are narrowing historic supply gaps for certified organic vanilla and annatto through pooled processing investments. COFEPRIS alignment with US pharmacopeial standards is reshaping nearshoring economics for botanical raw material finishing. Veracruz and Mérida processing clusters are capturing margin previously absorbed by layered distributor intermediation.
Canada
Health Canada's Natural Health Product Directorate imposes distinct monograph compliance requirements that govern cross-border nutraceutical extract sales. British Columbia and Ontario formulation facilities are consolidating procurement around USDA Organic-verified suppliers to serve dual certification demands. Vancouver's port infrastructure supports Pacific Rim botanical raw material intake for western Canadian processing.
North America Spice and Herb Extracts Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream on extraction technology and raw material sourcing. The vendor base organizes around three tiers: multinational flavor houses with integrated sourcing networks, mid-scale regional processors competing on clean-label extraction credentials, and biotechnology platforms bypassing agricultural volatility. Consolidation pressure concentrates among mid-scale processors facing capital retooling demands from EPA enforcement signals. Dominant competitive moves include backward integration into cooperative sourcing relationships and technology licensing for supercritical CO2 systems.
Among North American headquartered operators, McCormick & Company and Kerry Group exemplify the integrated sourcing archetype, while Givaudan occupies a position representing biotechnology-derived molecule platforms. These three anchors illustrate the competitive divergence between agricultural supply chain control and controlled-environment production systems.
| Leading Market Players |
|---|
| McCormick & Company |
| Kerry Group |
| Givaudan |
| Dohler GmbH |
| Firmenich SA |
| Olam International |
| Sensient Technologies |
| International Flavors & Fragrances |
| Kemin Industries |
| Others |
Value Network & Pricing Analysis
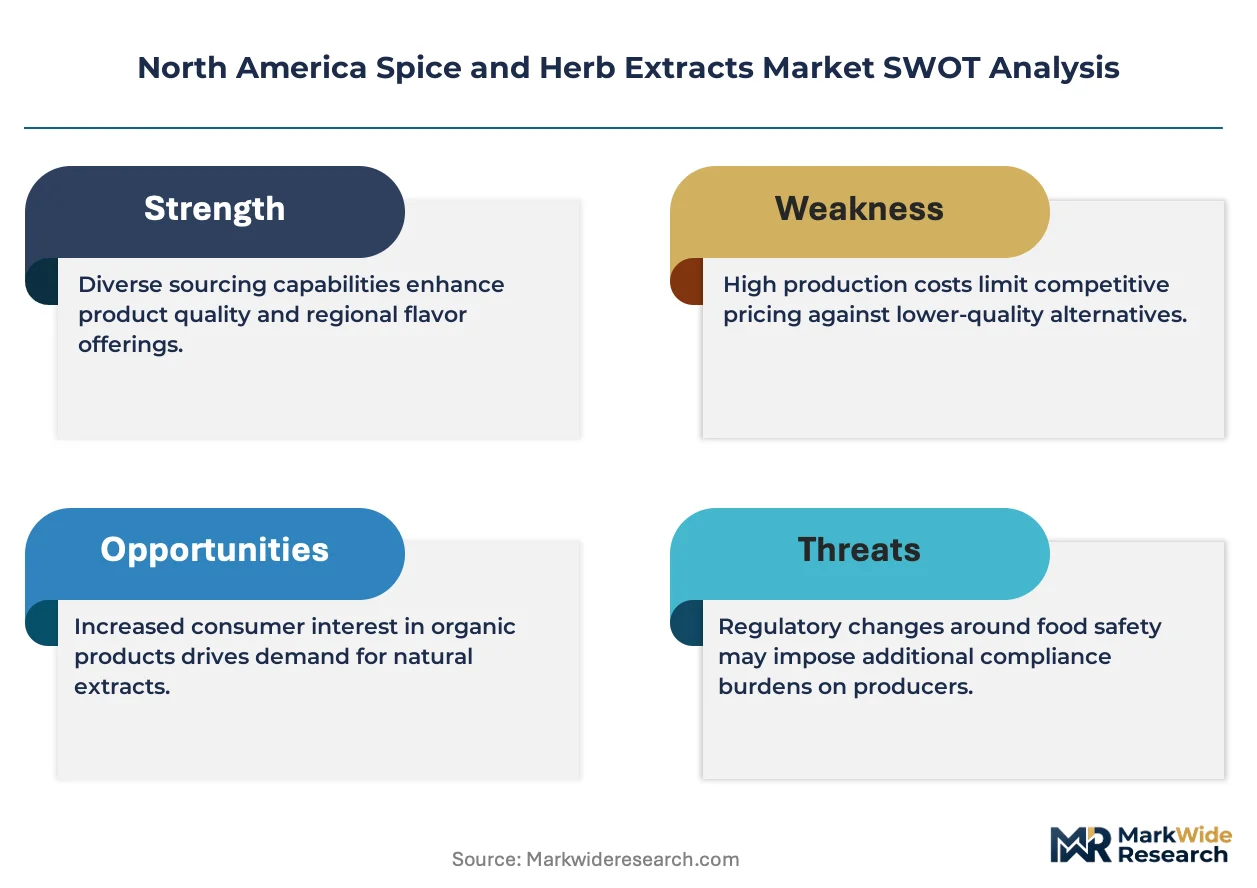
Madagascar's vanilla bean harvest concentration funnels margin capture toward certified organic processors in Mexico's Yucatan and California's functional food corridor, leaving commodity-grade traders exposed to spot price erosion. USDA Organic certification creates a dual-track market where verified-origin extracts command sourcing premiums while conventional grades face cost compression from synthetic alternatives.
Pricing Analysis
FDA GRAS notification requirements dictate the pricing tier structure across natural flavor houses, separating premium-positioned suppliers with validated novel actives from commodity oleoresin traders. Three-tier pricing structure across premium, standard, and economy levels reflects certification burden, with USDA Organic and Non-GMO Project verification driving top-tier procurement. Cost compression in conventional vanilla extracts is intensifying because fermentation-derived molecules bypass agricultural yield constraints. Nutraceutical capsule manufacturers show least price sensitivity due to dosing precision requirements, while industrial sauce blenders face acute margin pressure from reformulation deadlines.
Supply Chain Analysis
Tariff exposure between Mexico and the United States dominates nearshoring economics for botanical raw material finishing. Madagascar, Indonesia, and Mexico anchor vanilla and spice supply, drawing from agricultural cooperatives with limited processing infrastructure. Single-source vulnerability concentrates in Madagascar's vanilla belt, where climate disruption and speculative commodity positions create supply interruption risk. Distribution runs through Veracruz refrigerated terminals for transshipment to Illinois and Wisconsin extraction clusters, with California's functional food corridor absorbing finished extracts via Interstate 80 logistics spine.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Supercritical CO2 extraction expertise scarcity constrains mid-scale processor expansion, creating acquisition premiums for qualified technical teams and installed clean-label capacity. The market rewards backward integration into cooperative sourcing relationships and technology licensing partnerships that bypass agricultural volatility.
For Market Incumbents: Build certification moats around simultaneous USDA Organic and FDA GRAS self-affirmation capabilities to lock out mid-scale competitors facing quality assurance bandwidth constraints. Deepen upstream control over Yucatan cooperative processing infrastructure before COFEPRIS alignment with US pharmacopeial standards completes. Accelerate supercritical CO2 equipment replacement ahead of EPA residual solvent rulemaking to capture first-mover positioning in clean-label supply contracts. For New Entrants and Emerging Players: Mid-market nutraceutical capsule manufacturers in Wisconsin and Illinois represent the most penetrable entry point, where dosing precision requirements favor new suppliers with real-time composition monitoring technology. Biotechnology-derived rare spice molecules offer a defensible wedge against agricultural commodity cycles, with fermentation platforms for saffron and vanilla compounds bypassing yield constraints. Lead with EPA compliance credentials and solvent-free extraction guarantees to displace legacy solvent-heavy processors. For Investors and Strategic Acquirers: Capital is best deployed toward mid-scale extraction facilities with installed supercritical CO2 capacity and established cooperative sourcing relationships in Mexico's Yucatan. Long-term viability hinges on controlled-environment production systems that decouple from agricultural volatility. Watch for EPA enforcement discretion letters and consent decree patterns as early signals of regulatory-driven consolidation windows favoring clean-label infrastructure owners.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cooperative Sourcing | Yucatan processing clusters capture margin previously absorbed by layered distributor intermediation in vanilla supply chains. |
| Supercritical CO2 Equipment Replacement | Illinois and Wisconsin facilities respond to EPA enforcement signals with accelerated capital retooling ahead of formal rule finalization. |
| Biotechnology Platform Licensing | Fermentation-derived rare molecules bypass Madagascar supply interruptions and speculative commodity positions in natural flavor houses. |
| Dual Certification Investment | Simultaneous USDA Organic and FDA GRAS capabilities strain quality assurance bandwidth for mid-scale processors lacking parallel documentation streams. |
| Direct Procurement Contracting | California functional food formulators consolidate sourcing around single-origin botanical partnerships with verified traceability documentation. |
Research Methodology
A standing panel of extraction technology directors, cooperative sourcing managers, CPG procurement leads, and EPA compliance officers provided ongoing calibration across primary fieldwork and secondary validation. FDA GRAS notification databases, USDA Organic certification registries, COFEPRIS alignment documentation, and customs trade flows for botanical raw materials anchored quantitative baselines. Bottom-up contract volume analysis with top-down market sizing triangulation verified segment-level estimates.
Scenario-bracketing around regulatory enforcement intensity and biotechnology adoption curves shaped projections across the analysis window. Segmentation dimensions modeled include product type, end-user industry, application function, and certification tier, with geographic production cluster and extraction technology type as cross-cutting variables. CAGRs derived from fitted growth curves incorporating clean-label reformulation deadlines, supercritical CO2 equipment cost trajectories, and cooperative processing investment cycles in Mexico.
Practitioners should monitor EPA residual solvent rulemaking progress and COFEPRIS harmonization milestones for early signals of competitive repositioning. Forecasts reflect assumptions around GRAS notification backlog resolution and fermentation platform scale-up timelines. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Spices and Seasonings
Mullein Leaf Market
Spices and Seasonings
Cinnamon Market
Spices and Seasonings
Celery Seed Extract Powder Market
Spices and Seasonings
Organic Spices and Herbs Market
Spices and Seasonings
Ginger Market
Spices and Seasonings
Jalapeno Salt Market
Spices and Seasonings
Europe Spice and Herb Extracts Market
Spices and Seasonings
Pumpkin Pie Spices Market
Spices and Seasonings
Egypt Herbs and Spices Market
Spices and Seasonings
Peppermint Extract Market
Spices and Seasonings
Cardamom Market
Spices and Seasonings
Pepper Market
Spices and Seasonings
Lemon Salt Market
Spices and Seasonings
Boswellia Extract Market
Spices and Seasonings
Dried Spices Market
Spices and Seasonings
Dill Oil Market