
 Asafoetida Market | 2026-2036
Asafoetida Market Size, Share, and Industry Trends Forecast 2026-2036
Asafoetida Market Insights
A capital-intensity divergence between artisanal harvesters and modern processors is rotating competitive dynamics in the asafoetida supply chain. DS Group leverages its integrated spice distribution network across Indian metropolitan markets. Everest Masala anchors premium branded positioning through consistent quality grading systems. Laljee Godhoo sustains multi-generational sourcing relationships with Afghan gum resin collectors.
Asafoetida is a dried latex oleo-gum-resin extracted from Ferula assa-foetida roots, containing sulfur compounds that impart a pungent aroma and digestive properties. Powdered asafoetida dominates retail volumes due to convenience and standardized dosing in culinary applications, while liquid asafoetida captures institutional food processing demand for uniform flavor dispersion. The pharmaceutical end-use segment draws on documented carminative and antispasmodic properties, with nutraceutical applications emerging around gut health positioning.
India's FSSAI mandates strict labeling and purity standards for compounded asafoetida, while BIS certification governs export-grade resin quality parameters. Afghanistan's export controls on raw gum resin shape supply availability and pricing volatility for downstream processors. Stakeholders must monitor regulatory harmonization between Indian food safety frameworks and emerging Middle Eastern import standards as distribution channels expand beyond traditional South Asian consumer bases.
Market Dynamics
Afghanistan's export controls on raw Ferula gum resin concentrate supply leverage among Indian processors, creating pricing volatility that ripples through downstream compounded asafoetida production.
Growth Catalysts
- FSSAI purity mandates:India's food safety regulator enforces strict labeling standards for compounded asafoetida, elevating quality barriers that favor organized processors over informal suppliers.
- Pharmaceutical extraction demand:Documented carminative and antispasmodic properties drive pharmaceutical-grade resin offtake for digestive health formulations.
- Middle Eastern culinary adoption:Expanding South Asian diaspora populations in Saudi Arabia and the UAE generate new import demand for authentic asafoetida in regional cuisine applications.
Market Restraints
- Raw resin supply concentration:Afghan gum resin collectors control upstream supply, exposing Indian processors to harvest variability and border logistics disruptions.
- Wheat flour dilution standards:FSSAI-mandated compounding requirements limit pure resin content in retail products, constraining premium positioning.
- Synthetic flavor substitution:Laboratory-produced sulfur compounds offer cost advantages in mass-market food processing, threatening traditional asafoetida volume.
Strategic Opportunities
- PLI scheme alignment:India's production-linked incentive framework for food processing supports capital investment in automated resin cleaning and grading equipment.
- Nutraceutical gut health positioning:Fermented food trends create white space for asafoetida-derived prebiotic supplements in North American and European wellness markets.
- E-commerce direct distribution:Platform penetration into tier-2 and tier-3 Indian cities bypasses traditional spice mandi intermediaries, capturing margin expansion.
Industry Challenges
- Artisanal collector retention:Multi-generational gum resin harvesting knowledge faces attrition as younger Afghan labor migrates to urban wage employment.
- BIS certification timelines:Export-grade quality parameter testing creates extended lead times for European and North American market entry.
- Climate-sensitive cultivation:Ferula assa-foetida root maturation requires specific altitude and precipitation conditions vulnerable to shifting weather patterns in Hindu Kush growing zones.
Report Scope
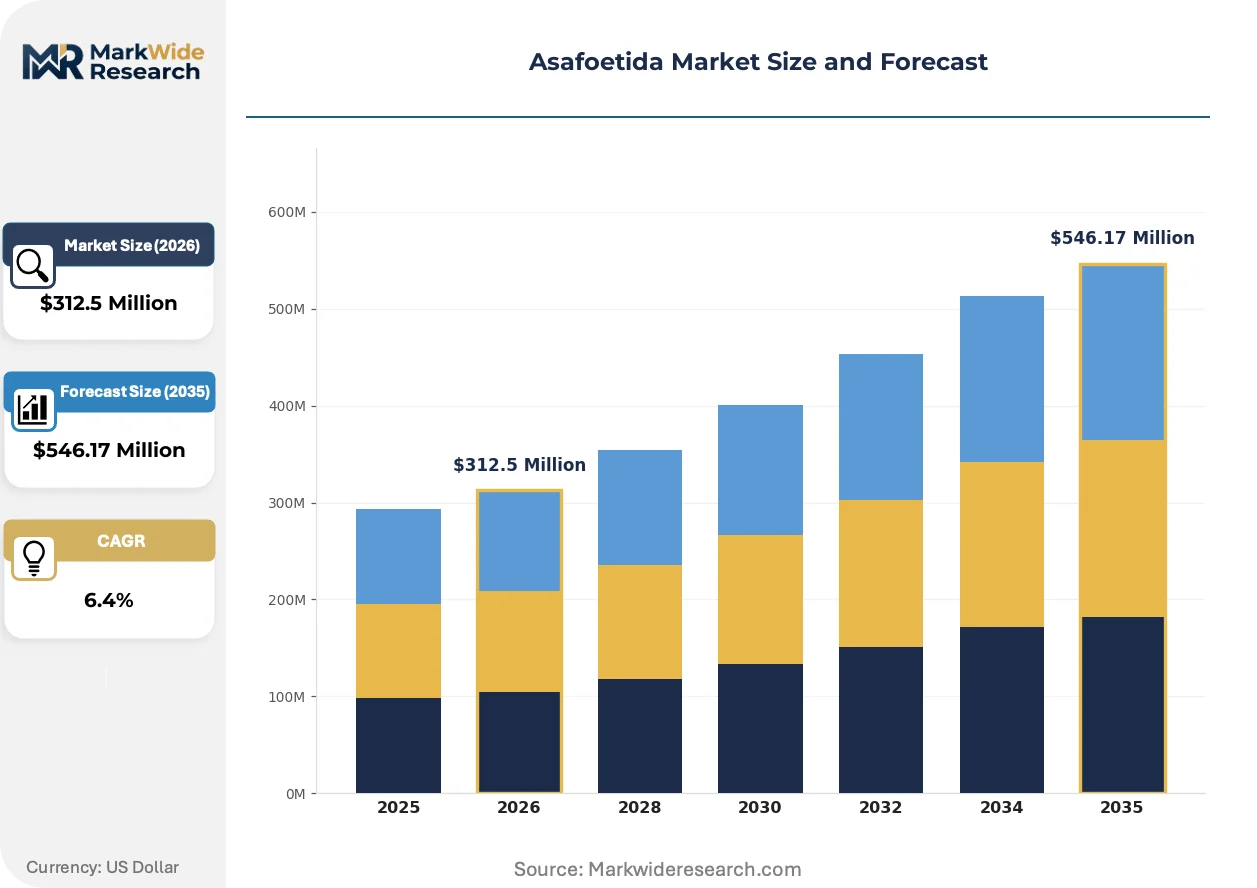
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asafoetida Market |
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $546.17 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Raw Asafoetida, Powdered Asafoetida, Granulated Asafoetida, Liquid Asafoetida Packaging Type: Bottles, Pouches, Jars, Bulk Packaging Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Distributors End Use: Food Industry, Pharmaceutical, Nutraceutical, Cosmetics |
| Companies Covered | DS Group, Everest Masala, Laljee Godhoo, MVM Asafoetida, Anu Foods, G P And Company, S.S. Pandian & Sons, MDH Spices, Patanjali Ayurved Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asafoetida Market Trends and Innovations
Processing technology and distribution infrastructure are compressing traditional supply chain layers while regulatory frameworks harden quality differentiation between artisanal and industrial production tiers.
Encapsulation technology is miniaturizing asafoetida oleo-gum-resin into microsphere formats for controlled-release pharmaceutical applications. Nutraceutical manufacturers in Western Europe adopt these formats for digestive health supplements. This miniaturization enables precise sulfur compound dosing that raw resin compounding cannot achieve.
REACH registration requirements for imported botanical resins are tightening analytical documentation standards for European market access. Indian exporters must now submit comprehensive Ferula species authentication and heavy metal testing protocols. Small-scale processors lacking in-house laboratory capabilities face exclusion from this geography.
Restaurant procurement through specialized spice distributors is consolidating buyer power in Indian metropolitan markets. Institutional food service accounts negotiate directly with branded processors, bypassing traditional wholesale mandi channels. This concentration is most visible in Mumbai and Delhi NCR cloud kitchen supply chains.
Asafoetida Market Segmentation
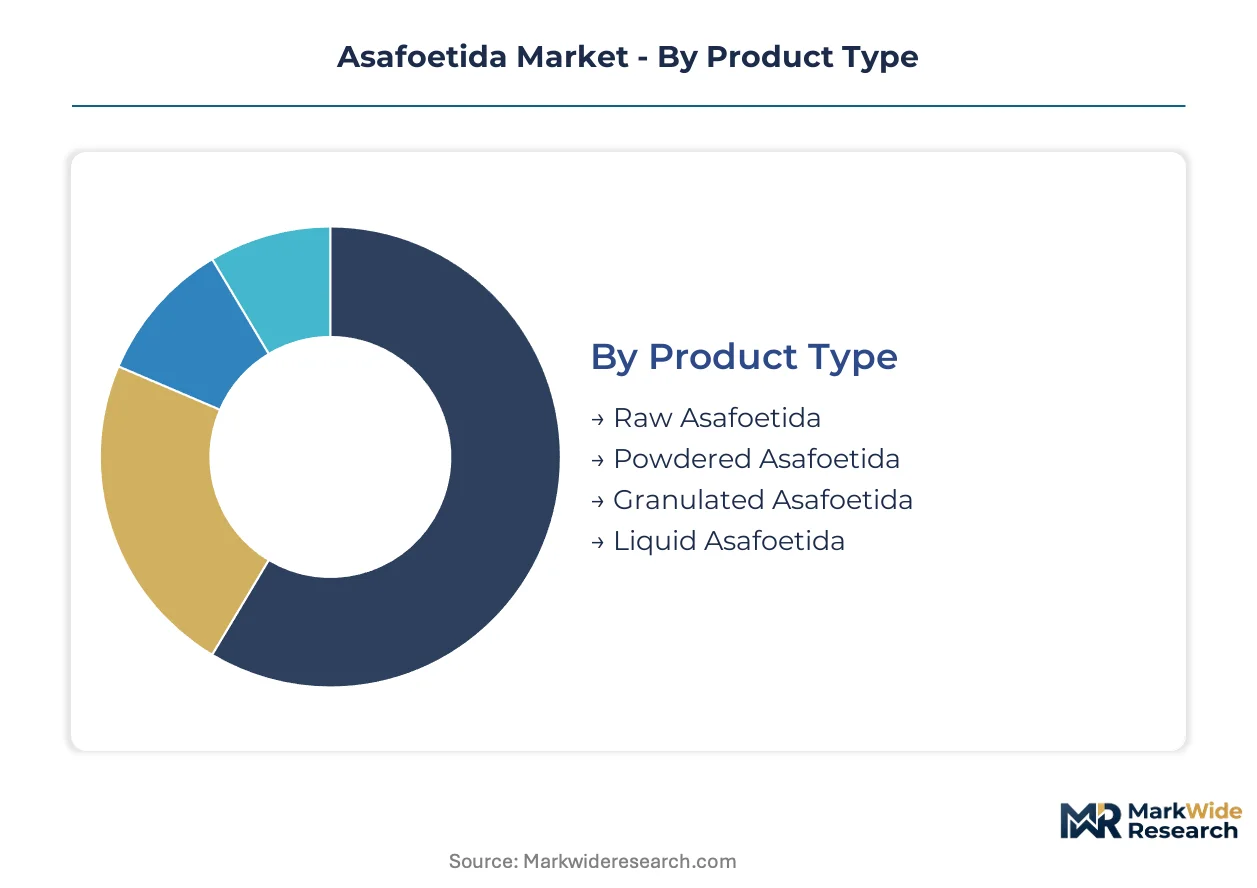
Asafoetida's value chain fragments across resin extraction, compounding, and final formulation stages, each commanding distinct margin structures. Segmentation reveals where quality premiums concentrate versus where volume commoditization pressures margins.
Product Type:
Powdered and liquid formats capture the deepest margin pools through processing value-add and institutional contract pricing power.
- Powdered Asafoetida:Wheat-flour compounded resin ground to standardized mesh sizes for direct culinary use. Indian household consumption and restaurant procurement in Mumbai and Delhi NCR drive volume concentration, though FSSAI-mandated dilution ratios cap pure resin content and premium positioning.
- Liquid Asafoetida:Alcohol or oil suspension of oleo-gum-resin enabling uniform flavor dispersion in industrial food processing. Institutional accounts in Saudi Arabia and UAE food manufacturing represent the steepest demand expansion trajectory as Middle Eastern South Asian diaspora populations scale.
- Raw Asafoetida:Unprocessed Ferula gum resin lumps requiring grinding and compounding by downstream processors. Afghan export controls concentrate supply leverage among collectors, creating price volatility that ripples through value chains.
- Granulated Asafoetida:Coarse resin particles for specific traditional cooking applications in regional Indian cuisines. Limited commercial scale relative to powder formats.
The dominant share belongs to powdered asafoetida, while liquid asafoetida is closing the gap fastest.
Packaging Type:
Consumer-facing formats separate premium branded positioning from commodity bulk flows through shelf visibility and convenience premiums.
- Bottles:Glass or PET containers with shaker tops dominating Indian retail shelves. Everest Masala and DS Group leverage bottle real estate for brand recognition in metropolitan kirana stores and modern trade outlets.
- Pouches:Flexible laminate sachets at price-accessible entry points for rural and semi-urban penetration. E-commerce platform bundling in tier-2 and tier-3 Indian cities is displacing traditional mandi procurement.
- Jars:Wide-mouth containers for institutional food service and restaurant kitchens. Cloud kitchen supply chains in Bangalore and Hyderabad negotiate direct procurement bypassing wholesale intermediaries.
- Bulk Packaging:Industrial drums and cartons for pharmaceutical extraction and food processing input. BIS certification requirements for export-grade resin create documentation barriers for small-scale processors.
Bottles command the largest volume position, though pouches are gaining share fastest through digital channel penetration.
Distribution Channel:
Channel selection determines margin capture versus reach tradeoffs, with direct platforms compressing traditional intermediary layers.
- Supermarkets:Organized retail chains in Indian metropolitan markets providing quality-assured branded placement. Modern trade accounts negotiate slotting fees that favor scaled processors with FSSAI-compliant documentation.
- Online Retail:Platform-direct sales enabling margin expansion by bypassing spice mandi intermediaries. Amazon India and Flipkart penetration into secondary cities is rotating procurement patterns toward packaged branded formats.
- Specialty Stores:Ethnic grocery outlets serving South Asian diaspora communities in Saudi Arabia, UAE, and North America. Authenticity signaling through Afghan-sourced resin claims supports premium pricing.
- Distributors:Traditional wholesale networks linking Afghan gum resin collectors to Indian compounding facilities. Border logistics disruptions and harvest variability expose processors to supply uncertainty.
Supermarkets retain the dominant channel position, while online retail is expanding most quickly through platform infrastructure investment.
End Use:
Application segmentation separates mature culinary demand from emerging pharmaceutical and nutraceutical value pools with distinct regulatory pathways.
- Food Industry:Culinary applications across Indian cuisine, Middle Eastern adaptations, and processed food manufacturing. FSSAI labeling mandates and wheat flour compounding standards shape product formulation constraints.
- Pharmaceutical:Carminative and antispasmodic extract applications in digestive health formulations. Encapsulation technology enabling microsphere controlled-release formats is opening Western European supplement markets.
- Nutraceutical:Prebiotic and gut health positioning in fermented food trend alignment. North American wellness market entry requires REACH registration and comprehensive heavy metal testing protocols.
- Cosmetics:Sulfur compound applications in traditional skincare formulations. Limited commercial scale relative to ingestible applications.
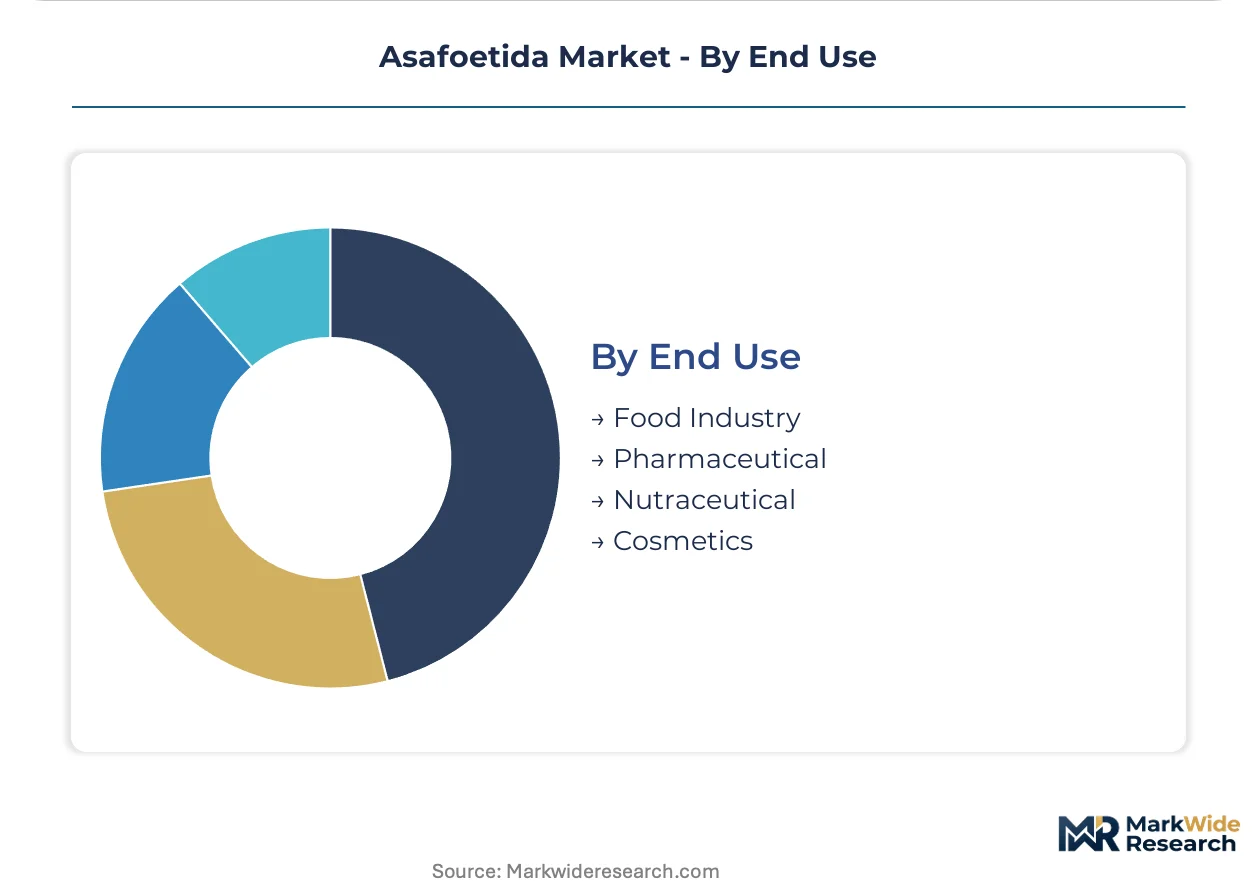
The food industry holds the dominant share, while nutraceutical applications are climbing the fastest through wellness trend alignment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Indian processors command downstream pricing power while Afghan collectors retain upstream supply leverage, creating a structural asymmetry that concentrates margin capture in Mumbai and Delhi NCR compounding facilities. This geographic split shapes procurement risk profiles across the value chain.
India
Mumbai and Delhi NCR house the dominant compounding infrastructure, with FSSAI purity mandates elevating quality barriers that favor organized processors over informal suppliers. India's PLI scheme for food processing supports capital investment in automated resin cleaning equipment. The Maharashtra-Gujarat industrial corridor anchors pharmaceutical-grade extraction capacity for digestive health formulations.
Afghanistan
Hindu Kush growing zones supply raw Ferula gum resin through multi-generational collector networks facing labor attrition as younger workers migrate to urban wage employment. Export controls on raw gum resin concentrate supply leverage among collectors, creating harvest variability that ripples through Indian downstream production. Border logistics disruptions near Kabul-Jalalabad corridors expose processors to supply uncertainty.
United Arab Emirates
Dubai and Abu Dhabi serve as re-export hubs for Middle Eastern South Asian diaspora demand, with MOHAP import standards beginning to shape documentation requirements for compounded asafoetida. Specialty ethnic grocery outlets in Deira and Al Barsha negotiate authenticity signaling through Afghan-sourced resin claims. Cloud kitchen supply chains in Dubai South consolidate procurement power through direct processor relationships.
Saudi Arabia
Riyadh and Jeddah generate institutional food manufacturing demand for liquid asafoetida formats, with SFDA regulatory harmonization efforts aligning with Indian FSSAI frameworks. Food processing clusters in King Abdullah Economic City scale import volumes for uniform flavor dispersion applications. South Asian diaspora population concentration in Eastern Province drives retail format diversification.
Germany
REACH registration requirements for imported botanical resins tighten analytical documentation standards, with ECHA protocols mandating comprehensive Ferula species authentication and heavy metal testing. Western European nutraceutical manufacturers in Bavaria adopt microsphere encapsulation formats for controlled-release digestive health supplements. Small-scale Indian processors lacking in-house laboratory capabilities face market exclusion from this geography.
Asafoetida Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with automated resin cleaning and grading equipment separating scaled processors from artisanal compounders. The market structures around three tiers: integrated spice conglomerates with metropolitan distribution networks, multi-generational family operations with Afghan sourcing relationships, and emerging Ayurvedic wellness brands leveraging e-commerce penetration. Consolidation pressures favor organized processors with FSSAI-compliant documentation, while raw resin supply concentration sustains collector leverage. Dominant competitive moves include backward integration into Afghan sourcing relationships and platform-direct distribution bypassing traditional mandi intermediaries.
Among heritage-anchored family operations, Laljee Godhoo exemplifies multi-generational sourcing relationships with Afghan gum resin collectors, while Everest Masala occupies a position consistent with premium branded positioning through quality grading systems. DS Group represents the integrated conglomerate archetype, leveraging metropolitan distribution networks across Indian retail channels. These three players illustrate how competitive advantage stratifies across sourcing depth, brand equity, and channel control rather than manufacturing scale alone.
| Leading Market Players |
|---|
| DS Group |
| Everest Masala |
| Laljee Godhoo |
| MVM Asafoetida |
| Anu Foods |
| G P And Company |
| S.S. Pandian & Sons |
| MDH Spices |
| Patanjali Ayurved Ltd. |
| Others |
Pricing and Supply Chain Analysis
Capacity utilization at automated resin cleaning facilities in Mumbai and Delhi NCR generates scale economies that compress unit costs while elevating quality barriers. This concentration of processing infrastructure shapes price floors across compounded asafoetida tiers and concentrates margin capture among organized processors with FSSAI-compliant documentation.
Pricing Analysis
The customization-premium spread between pharmaceutical-grade microsphere encapsulation and standard wheat-flour compounded powder separates value capture tiers. Pricing stratifies across premium, standard, and economy tiers based on resin purity certification and FSSAI compliance grade. Cost compression in economy-tier retail pouches is intensifying because synthetic sulfur compound substitutes undercut traditional resin-based production. Institutional food manufacturers in Saudi Arabia and the UAE demonstrate lowest price sensitivity due to formulation consistency requirements, while rural Indian household consumers in tier-3 cities show highest sensitivity to per-gram pricing.
Supply Chain Analysis
Afghanistan supplies raw Ferula gum resin through Hindu Kush collector networks, while India anchors downstream compounding and pharmaceutical extraction capacity. The value chain draws from Afghan gum resin lumps, Indian wheat flour compounding agents, and European encapsulation technology inputs. Single-source vulnerability concentrates in Afghan export controls and border logistics disruptions near Kabul-Jalalabad corridors. Distribution runs through traditional spice mandi wholesale networks, though e-commerce platforms and direct processor relationships are displacing intermediary layers in metropolitan Indian markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Multi-generational harvesting knowledge attrition in Afghanistan and FSSAI documentation requirements in India create capability scarcity that favors players with embedded sourcing relationships and laboratory infrastructure.
For Market Incumbents: Secure backward integration into Afghan collector networks to lock in resin supply amid labor migration trends. Invest in automated grading equipment aligned with India's PLI scheme to defend margin position against informal compounders. Prioritize BIS certification capacity to maintain European market access as REACH requirements tighten. For New Entrants and Emerging Players: Differentiate on nutraceutical gut health positioning in North American wellness markets where fermented food trends create white space. Target e-commerce direct distribution in tier-2 and tier-3 Indian cities where platform penetration is rotating procurement toward packaged branded formats. Pursue authenticity signaling through Afghan-sourced resin claims in Middle Eastern ethnic grocery channels. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among processors with institutional pharmaceutical extraction contracts and long-term supply agreements with Saudi and UAE food manufacturers. Over the medium-term horizon, prioritize acquisition targets with captive Afghan sourcing relationships and in-house heavy metal testing capabilities. Monitor FSSAI harmonization efforts with Middle Eastern import standards as the inflection signal for geographic expansion viability.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Afghan Sourcing | Captive resin supply locks in raw material access amid export control volatility. |
| Automated Resin Cleaning Equipment Investment | PLI scheme alignment reduces capital burden while elevating FSSAI compliance capacity. |
| Pharmaceutical Microsphere Encapsulation Development | Controlled-release formats open Western European nutraceutical contract manufacturing demand. |
| E-commerce Platform Direct Distribution | Bypassing mandi intermediaries captures margin expansion in tier-2 and tier-3 Indian cities. |
| BIS Certification and REACH Registration Completion | Analytical documentation compliance maintains European market access as ECHA protocols tighten. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FSSAI regulatory filings, Afghan export control documentation, and Indian customs trade data. Primary interviews engaged resin cleaning equipment manufacturers, gum resin collectors in Hindu Kush zones, pharmaceutical extraction facility managers, and spice mandi wholesale distributors. Secondary validation drew from BIS certification records, CDSCO pharmaceutical ingredient databases, and Saudi SFDA regulatory harmonization publications. Bottom-up demand modeling across food industry, pharmaceutical, and nutraceutical end uses triangulated against top-down supply-side capacity assessments.
Segmentation dimensions modeled include product type tier, packaging format, distribution channel structure, and end-use application across the projection horizon. CAGRs were derived from volume trajectory analysis incorporating FSSAI purity mandate compliance rates and Middle Eastern diaspora population scaling. Industry-specific forecast inputs encompassed Afghan harvest variability patterns and encapsulation technology adoption curves in Western European nutraceutical manufacturing.
Material uncertainties — Afghan border logistics disruptions, FSSAI regulatory amendments, and synthetic flavor substitution rates — sit outside the modeled envelope. Forecasts reflect assumptions around collector labor retention and climate stability in Hindu Kush growing zones. Recalibration cycles align with material shifts in Afghan export policy and Indian food safety framework harmonization efforts.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Spices and Seasonings
Spices Market
Spices and Seasonings
Global Spices and Stimulants Market
Spices and Seasonings
Savoury Seasoning Market
Spices and Seasonings
Myrrh Gum Market
Spices and Seasonings
Mint Oils Market
Spices and Seasonings
Blended Spices Market
Spices and Seasonings
Lemon Salt Market
Spices and Seasonings
Sriracha Market
Spices and Seasonings
Oregano Seasoning Market
Spices and Seasonings
BBQ Seasoning Market
Spices and Seasonings
Europe Seasoning and Spices Market
Spices and Seasonings
Organic Saffron Market
Spices and Seasonings
Cardamom Market
Spices and Seasonings
Green Pepper Market
Spices and Seasonings
Spice Grinders Market
Spices and Seasonings
Herb Oil Market