
 South America Seasoning and Spices Market | 2026-2036
South America Seasoning and Spices Market Size, Share, and Industry Trends Forecast 2026-2036
South America Seasoning and Spices Market Analytics
Consolidation among Brazilian and Argentine foodservice chains is realigning procurement volumes toward fewer, larger contract holders. McCormick & Company leverages its blending facilities in Brazil to serve quick-service restaurant networks across Mercosur. Kerry Group Plc anchors its position through specialized savory flavor systems tailored to regional meat-processing customers. Unilever Plc competes via retail brand strength in urban supermarket channels throughout Colombia and Chile.
Seasoning and spices encompass dried botanical derivatives, oleoresins, and compounded flavor preparations used to enhance taste, preserve, or color food products, typically processed through grinding, extraction, or spray-drying to achieve specific particle sizes and volatile oil retention. The primary commercial purpose centers on standardizing sensory profiles across processed food, foodservice, and retail cooking applications. Spice Mixes command substantial margin pools due to formulation complexity and customer stickiness in food manufacturing, while Salt Substitutes represent the fastest-growing category as sodium reduction mandates intensify across South American processed food sectors. Ground and granulated forms dominate volume throughput owing to compatibility with industrial dosing equipment and extended shelf stability.
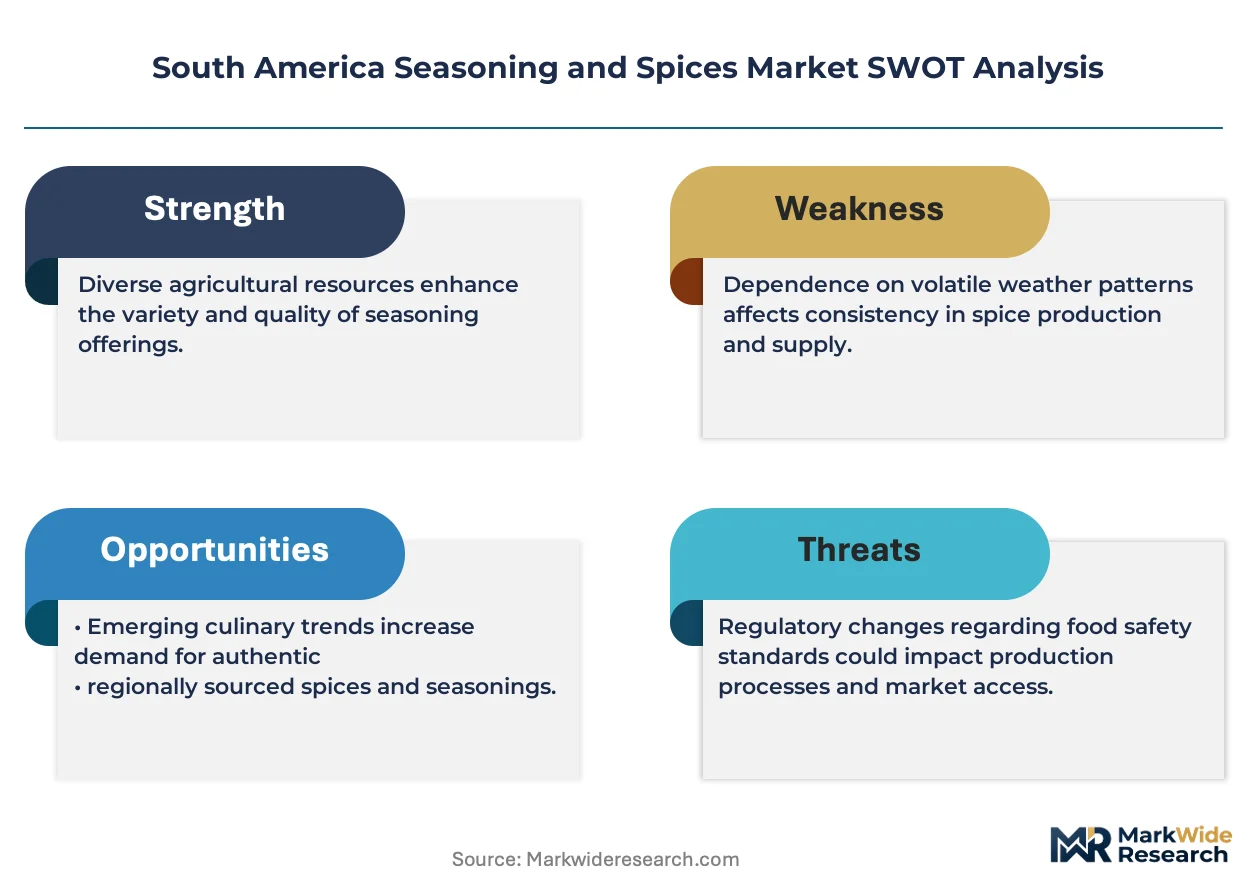
ANVISA in Brazil enforces maximum residue limits and labeling requirements that directly determine which imported spice lots gain market access, while Argentina's national food code and Chile's Ministry of Health standards create a patchwork of compliance obligations for cross-border suppliers. These regulatory frameworks elevate testing costs but simultaneously privilege established players with in-house analytical capabilities. Stakeholders must monitor pending Mercosur harmonization proposals and ANVISA's anticipated updates to natural flavorant classifications, as these will reshape sourcing strategies and product formulation priorities across the value chain.
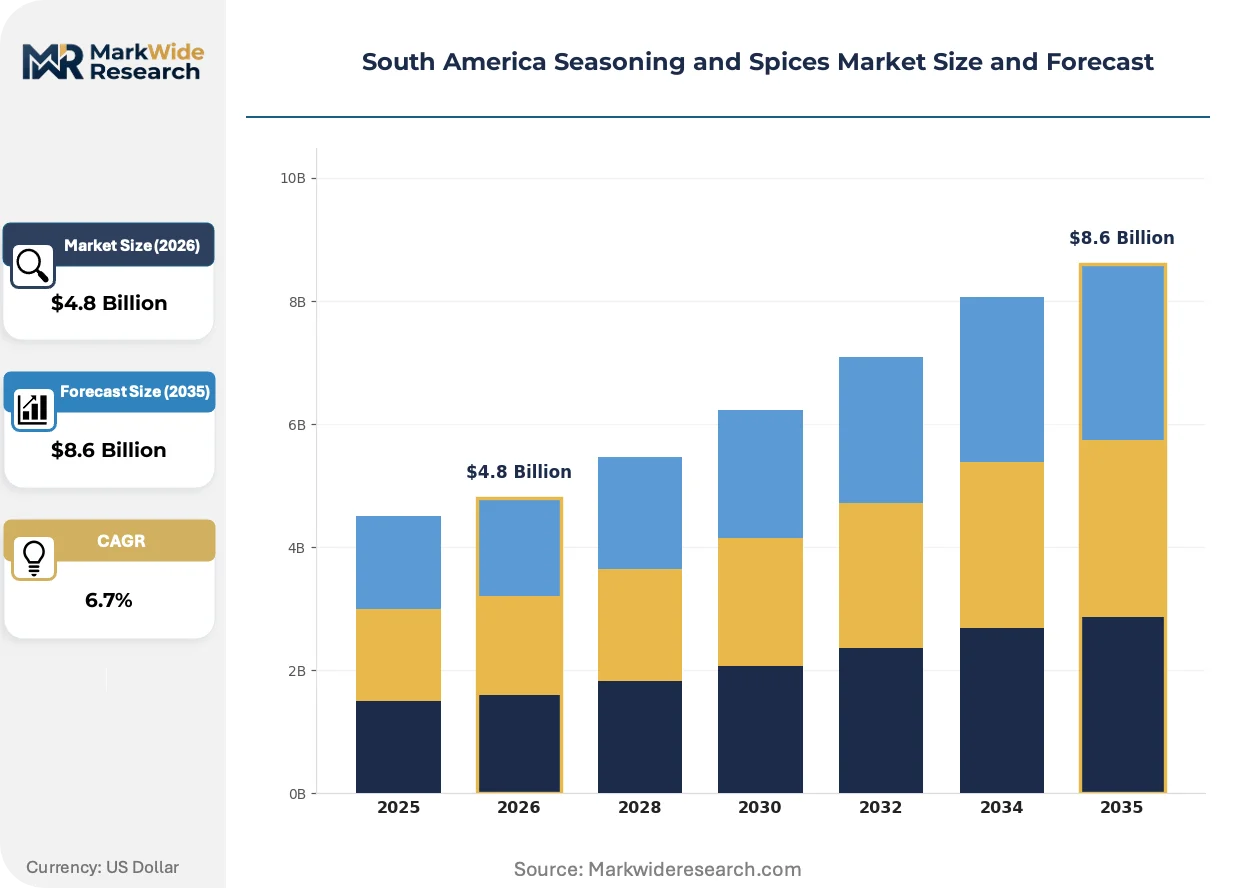
Market Dynamics
ANVISA's tightening purity standards for imported seasonings are compressing market access for cross-border suppliers while privileging domestic blenders with in-house analytical capabilities.
Growth Catalysts
- Clean-label procurement:Foodservice operators across Brazil and Argentina are expanding volumes of additive-free spice blends to meet consumer transparency demands.
- Sodium reduction mandates:Processed food manufacturers throughout Mercosur are reformulating recipes with salt substitutes to comply with evolving national health codes.
- Southeastern manufacturing corridor concentration:São Paulo-based processors supply retail chains throughout the trade bloc, creating economies of scale in grinding and spray-drying infrastructure.
Market Restraints
- Import testing cost escalation:ANVISA's maximum residue limit enforcement elevates laboratory verification expenses for foreign seasoning lots entering Brazilian ports.
- Raw material supply concentration:Black pepper and oregano sourcing clusters in specific Brazilian and Argentine agricultural zones create weather-dependent vulnerability.
- Oleoresin extraction technical limitations:Volatile oil retention rates in heat-sensitive botanicals constrain shelf-stable product development for tropical distribution.
Strategic Opportunities
- Colombian retail channel expansion:Urban supermarket penetration in Bogotá and Medellín remains underdeveloped for premium spice mix portfolios relative to Brazilian benchmarks.
- Chilean foodservice digitization:Direct-to-kitchen ordering platforms for restaurant chains are bypassing traditional distributor markups in Santiago's metropolitan area.
- Mercosur harmonization tailwind:Pending regulatory alignment proposals would streamline cross-border labeling compliance for multi-country product lines.
Industry Challenges
- Sensory analyst talent scarcity:Qualified flavor chemists capable of standardizing volatile oil profiles across batch variations command premium compensation in São Paulo's competitive labor market.
- Legacy equipment integration friction:Automated dosing systems for ground spices require retrofitting of existing grinding lines, extending capital deployment timelines for mid-scale processors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South America Seasoning and Spices Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Herbs, Spice Mixes, Seasonings, Salt Substitutes End User: Food Processing, Retail, Foodservice, Household Packaging Type: Bags, Jars, Boxes, Tins Form: Ground, Whole, Liquid, Granulated |
| Companies Covered | McCormick & Company, Inc., Kerry Group Plc, Sensient Technologies Corp, DohlerGroup, Ajinomoto Co Inc, Olam International, Associated British Foods Plc, Unilever Plc, Frontier Co-op, Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South America Seasoning and Spices Market Evolving Landscape
Microencapsulation and blockchain traceability are restructuring how South American processors preserve volatile compounds and verify supply chain integrity from farm to formulation.
Encapsulation technology using modified starch matrices is extending shelf stability of heat-sensitive oleoresins in tropical climates. Brazilian meat processors are adopting these systems at accelerating rates to maintain consistent flavor profiles across refrigerated distribution chains. This advancement is modularizing the traditional separation between spice production and end-use manufacturing, enabling just-in-time compounding at processing facilities.
ANVISA's anticipated updates to natural flavorant classifications will recategorize extraction-derived ingredients against synthetic alternatives. Brazilian formulators are preemptively adjusting ingredient declarations to maintain clean-label positioning ahead of enforcement. The regulatory revision most directly affects retail spice mix producers competing on ingredient transparency in São Paulo's supermarket channels.
Quick-service restaurant chains are consolidating procurement through centralized tender processes rather than regional distributor relationships. This concentration is compressing supplier margins while demanding customized savory flavor systems tailored to proprietary menu specifications. The behavioral shift is most visible in Brazil's southeastern corridor where McDonald's and Burger King franchise networks dominate foodservice spice volumes.
South America Seasoning and Spices Market Segmentation
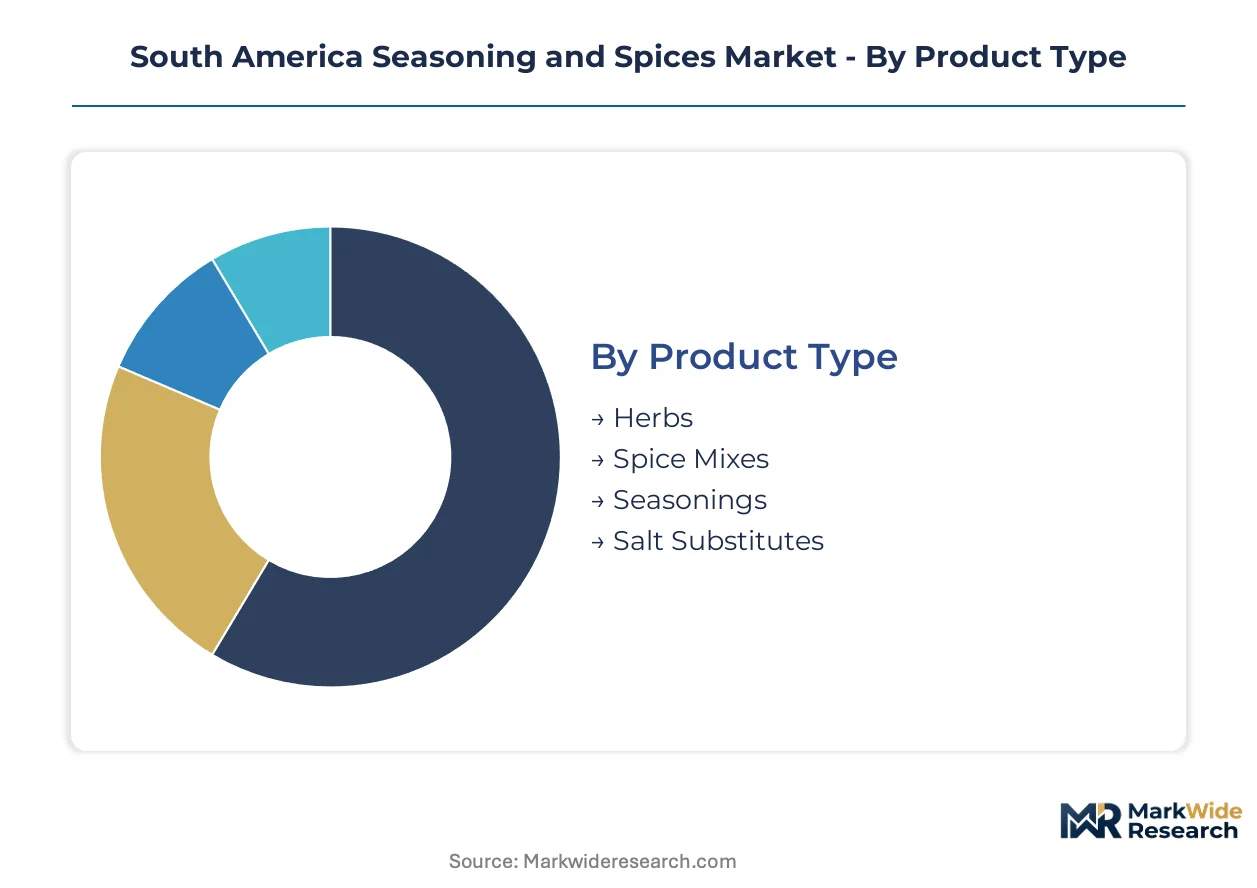
Segmentation in South America's seasoning and spices market reveals how procurement priorities diverge between industrial scale and consumer convenience. Understanding these splits allows suppliers to align grinding capacity, packaging formats, and regulatory documentation with the specific compliance and logistics requirements of each buyer tier.
Product Type:
Volume throughput concentrates in standardized grinding operations, while premium margins accumulate in proprietary formulations that lock in food manufacturing contracts.
- Spice Mixes:Compounded blends of ground botanicals, salt carriers, and anti-caking agents formulated to precise Scoville or volatile oil specifications. São Paulo-based meat processors purchase these in bulk to standardize chorizo and linguiça flavor profiles across Mercosur distribution. Clean-label reformulation is compressing synthetic additive tolerance in these contracts.
- Salt Substitutes:Potassium chloride and yeast extract-based sodium replacers enhanced with umami compounds. Brazilian processed food manufacturers facing ANVISA sodium reduction guidelines are expanding procurement of these systems for canned soups and snack seasonings. Reformulation complexity elevates technical service requirements from suppliers.
- Herbs:Dried leaf materials from oregano, basil, and cilantro retaining specified essential oil content. Argentine agricultural zones supply raw material to grinding facilities in Córdoba.
- Seasonings:Single-spice or simple binary blends without complex carrier systems. Retail channels in Colombia distribute these in value-tier packaging.
Today's leader: Spice Mixes. Tomorrow's challenger: Salt Substitutes.
End User:
Procurement scale and specification rigor separate industrial buyers from fragmented household purchasing.
- Food Processing:Industrial buyers requiring batch-certified volatile oil content and microbial documentation for HACCP compliance. Brazilian meatpackers in the southeastern corridor source tonnage quantities of standardized paprika and black pepper oleoresins. ANVISA residue testing mandates elevate supplier qualification barriers for imported lots.
- Foodservice:Restaurant chains and institutional kitchens purchasing medium-grind formats compatible with commercial kitchen dosing. Quick-service networks in Santiago are consolidating procurement through centralized tender platforms rather than regional distributors.
- Retail:Supermarket and hypermarket channels stocking consumer-packaged formats with Portuguese and Spanish labeling for Mercosur compliance. Bogotá and Medellín penetration remains underdeveloped relative to Brazilian benchmarks.
- Household:Individual consumers purchasing small-format units through traditional markets and convenience stores. Price sensitivity dominates substitution behavior in this tier.
Food Processing commands the volume. Foodservice is gaining specification influence fastest.
Packaging Type:
Moisture protection and shelf-life extension drive format selection across humid tropical distribution corridors.
- Jars:Glass containers with hermetic seals preserving volatile oil retention in ground products. Premium retail lines in São Paulo supermarkets utilize this format for transparent ingredient visibility. Higher unit economics support logistics costs to distant Mercosur markets.
- Bags:Multi-layer polymer laminates with oxygen barrier properties for industrial-scale food processing procurement. Brazilian meatpackers receive bulk shipments in this format for production-line integration.
- Tins:Metal containers offering impact resistance and light protection for export-oriented gift segments. Chilean retail channels favor this format for premium positioning.
- Boxes:Paperboard secondary packaging for multi-unit retail configurations. Colombian supermarkets utilize this format for promotional bundling.
Jars dominate premium positioning. Bags capture the tonnage.
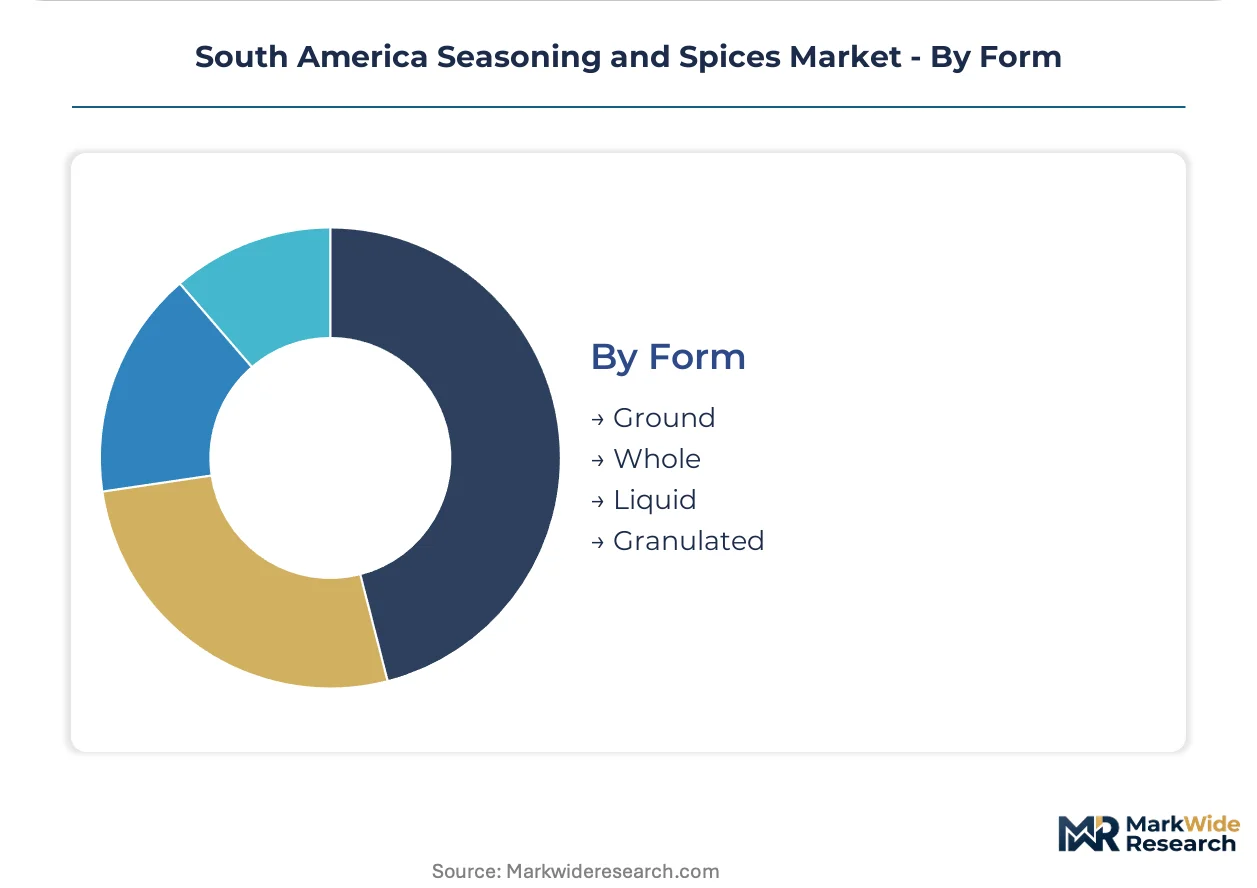
Form:
Particle size and extraction method determine compatibility with industrial dosing equipment and tropical shelf stability.
- Ground:Milled particles passing specified mesh screens for uniform dispersion in processed food matrices. São Paulo grinding facilities supply this format to retail chains throughout Mercosur. Automated dosing equipment in Brazilian meat plants requires precise particle size distribution.
- Granulated:Agglomerated particles with enhanced flow properties for high-speed packaging lines. Salt substitute formulations utilize this structure to prevent caking in humid climates.
- Whole:Intact botanical units for grinding at point of use or visual quality verification. Traditional markets in Argentina maintain demand for this format.
- Liquid:Oleoresin extracts and compounded flavor systems delivered in bulk tote or drum formats. Brazilian processors are adopting microencapsulated variants for refrigerated distribution chains.
Ground forms anchor current volume. Liquid extracts are climbing fastest on encapsulation advances.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil commands procurement volumes that dwarf Argentine foodservice demand, yet Chile's retail premiumization outpaces both neighbors in per-capita spice spending. This divergence shapes how suppliers configure grinding capacity, packaging formats, and regulatory documentation across the continent.
Brazil
ANVISA's tightened maximum residue limits for imported seasonings are compressing market access for foreign suppliers while privileging domestic blenders with in-house analytical capabilities. São Paulo's southeastern manufacturing corridor anchors grinding and spray-drying infrastructure that supplies retail chains throughout Mercosur. Foodservice operators in Rio de Janeiro and Belo Horizonte are expanding clean-label procurement volumes to meet consumer transparency demands.
Argentina
The national food code creates compliance obligations that elevate testing costs for cross-border suppliers entering through Buenos Aires ports. Córdoba's agricultural zones supply raw oregano and other dried leaf materials to regional grinding facilities. Meat processors in the Pampas region are reformulating chorizo and linguiça recipes with standardized spice blends to maintain flavor consistency across export markets.
Chile
The Ministry of Health's sodium reduction guidelines are accelerating procurement of salt substitute formulations among Santiago-based processed food manufacturers. Urban supermarket channels in the metropolitan area favor premium tin packaging for gift-oriented spice segments. Direct-to-kitchen ordering platforms for restaurant chains are bypassing traditional distributor markups in the capital's foodservice sector.
Colombia
Urban supermarket penetration in Bogotá and Medellín remains underdeveloped for premium spice mix portfolios relative to Brazilian benchmarks. Retail channels distribute value-tier seasonings in paperboard box formats for promotional bundling. The country's food processing sector is expanding import volumes of standardized paprika oleoresins for snack seasoning applications.
South America Seasoning and Spices Market Competitive Landscape
Brazilian producers anchor one tier; European and North American specialists hold formulation-intensive positions through regional blending facilities. The market structure concentrates around three to five integrated processors capable of batch-certified volatile oil documentation, with mid-scale grinders occupying price-sensitive niches. Strategic archetypes include clean-label blenders, savory flavor system specialists, and retail brand owners with supermarket channel dominance. Competitive moves center on centralized tender participation for quick-service restaurant networks and preemptive regulatory compliance ahead of ANVISA classification updates.
Among diversified multinationals with regional blending infrastructure, McCormick & Company, Inc. and Kerry Group Plc exemplify distinct competitive positions. McCormick occupies a role defined by foodservice network penetration across Mercosur quick-service restaurant channels. Kerry Group Plc represents the savory flavor system specialization tailored to meat-processing customers. Unilever Plc anchors retail brand strength in urban supermarket channels throughout Colombia and Chile. These three entities collectively illustrate how geographic footprint and customer segment focus determine competitive differentiation in procurement consolidation environments.
| Leading Market Players |
|---|
| McCormick & Company, Inc. |
| Kerry Group Plc |
| Sensient Technologies Corp |
| DohlerGroup |
| Ajinomoto Co Inc |
| Olam International |
| Associated British Foods Plc |
| Unilever Plc |
| Frontier Co-op |
| Others |
Value Network & Pricing Analysis
Black pepper and oregano sourcing clusters in Brazilian and Argentine agricultural zones transmit weather-driven volatility directly into spice blend pricing tiers. São Paulo-based processors absorb these input swings through contract structures that pass premium grades to food manufacturing buyers while compressing margins on standard retail lines.
Pricing Analysis
Capacity additions in Brazil's southeastern manufacturing corridor are reshaping price floors for ground spice formats. Three-tier pricing structure across premium, standard, and economy levels separates batch-certified volatile oil specifications from commodity-grade retail offerings. Price differentiation hinges on ANVISA compliance documentation and clean-label formulation complexity. Pricing pressure stems from centralized tender processes at quick-service restaurant chains. Household consumers in traditional markets exhibit highest price sensitivity; meat processors in the Pampas region show least sensitivity due to flavor consistency requirements.
Supply Chain Analysis
Direct-to-foodprocessor channels handle industrial-scale demand for bulk oleoresins and standardized spice mixes. Supply concentrates in Brazil, Argentina, and Chile, with Córdoba's agricultural zones feeding raw leaf materials to regional grinding facilities. The chain draws from black pepper cultivation clusters, oregano harvest zones, and imported paprika oleoresin streams. Single-source vulnerability in tropical oleoresin extraction creates shelf-stability risks for heat-sensitive botanicals. Distribution runs through São Paulo-based blending facilities serving Mercosur retail chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The South America seasoning and spices market functions as a geographic-arbitrage play between Brazil's stringent ANVISA compliance costs and Colombia's underdeveloped premium retail infrastructure. Suppliers can exploit this differential by positioning mid-tier certified products in Bogotá and Medellín at Brazilian standard-tier price points.
For Market Incumbents: Acquire in-house analytical laboratories to preempt ANVISA's anticipated natural flavorant classification updates. Secure backward integration into Córdoba agricultural zones to control oregano supply amid weather-dependent harvest volatility. Consolidate grinding capacity in São Paulo's southeastern corridor to capture economies of scale threatening mid-scale processors. For New Entrants and Emerging Players: Microencapsulation technology offers entry into refrigerated distribution chains serving Brazilian meat processors seeking volatile oil retention. Target Colombia's urban supermarket channels where premium spice mix penetration lags Brazilian benchmarks by substantial margins. Deploy direct-to-kitchen digital platforms in Santiago's foodservice sector to bypass traditional distributor markups. For Investors and Strategic Acquirers: Consolidation pressure builds where mid-scale grinders lack batch-certified documentation for ANVISA residue testing mandates. Long-term viability favors processors with integrated analytical capabilities and Mercosur-wide labeling compliance systems. Target acquisition archetype: São Paulo-based blenders with established quick-service restaurant network contracts. Signal to watch: ANVISA harmonization proposals with Mercosur partners that would streamline cross-border product line expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Agricultural Zones | Cordoba oregano supply control reduces weather-dependent raw material volatility for processors. |
| Microencapsulation Technology Deployment | Brazilian meat processors adopt modified starch matrices for tropical shelf-stable oleoresin distribution. |
| Direct-to-Kitchen Platform Launch | Santiago restaurant chains bypass distributor markups through centralized digital procurement channels. |
| Clean-Label Reformulation Investment | São Paulo supermarket channels reward additive-free spice mix transparency with premium positioning. |
| ANVISA Pre-Compliance Certification | In-house analytical capabilities privilege domestic blenders over import-dependent competitors under tightened purity standards. |
Research Methodology
Coverage spans Brazil, Argentina, Chile, and Colombia, with primary inputs from each market informing cross-border dynamics. The approach combines structured interviews with spice blend formulators, meat processor procurement directors, retail category buyers, ANVISA regulatory consultants, and agricultural cooperative managers with secondary validation. Secondary sources include ANVISA regulatory filings, Mercosur trade documentation, Brazilian customs records, and industry association production surveys. Bottom-up grinding capacity estimates triangulate against top-down food processing demand projections.
Rate-of-change decomposition separates volume growth from price evolution across product type, end user, packaging format, and form dimensions. The analytical framework models spice mix, salt substitute, herb, and seasoning categories against food processing, foodservice, retail, and household demand tiers. CAGRs derive from trend extrapolation of clean-label procurement volumes and sodium reduction mandate compliance timelines. Forecast inputs include ANVISA regulatory implementation schedules and microencapsulation technology adoption curves in Brazilian meat processing.
The model holds under continued ANVISA enforcement of maximum residue limits and stable Mercosur trade arrangements; deviation in regulatory harmonization timelines or agricultural harvest shocks would shift trajectory. Forecasts reflect documented assumptions about foodservice consolidation rates and clean-label premium persistence. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Spices and Seasonings
Turkey Flavors Market
Spices and Seasonings
Africa Spice and Herb Extracts Market
Spices and Seasonings
Kosher Salt Market
Spices and Seasonings
Global Spices and Stimulants Market
Spices and Seasonings
Nutmeg Oil Market
Spices and Seasonings
Cajun Seasoning Market
Spices and Seasonings
Oregano Oil Market
Spices and Seasonings
Africa Seasoning and Spices Market
Spices and Seasonings
North America Seasonings Market
Spices and Seasonings
Pink Himalayan Salt Market
Spices and Seasonings
Boutique Salt Market
Spices and Seasonings
Wasabi Market
Spices and Seasonings
Carthamus Yellow Market
Spices and Seasonings
Dried Spices Market
Spices and Seasonings
Asafoetida Market
Spices and Seasonings
Savoury Seasoning Market