
 Basil Essential Oil Market | 2026-2036
Basil Essential Oil Market Size, Share, and Industry Trends Forecast 2026-2036
Basil Essential Oil Market Outlook
ISO 9001 quality management certification is bifurcating the competitive landscape into qualified suppliers and marginal producers. Robertet Group leverages its integrated botanical supply chain from Grasse to secure premium raw material streams. Young Living Essential Oils anchors its position through proprietary Seed to Seal sourcing protocols across multiple continents. NOW Foods competes aggressively on analytical transparency, publishing third-party gas chromatography results for every batch.
Basil essential oil comprises volatile aromatic compounds extracted primarily from Ocimum basilicum, with linalool and methyl chavicol constituting the dominant terpene profile that determines olfactory character and therapeutic grade. Steam distillation of flowering tops yields between 0.1% and 1.0% essential oil by weight, making harvest timing and cultivar selection critical to commercial viability. Organic product type commands premium positioning as clean-label mandates tighten across European and North American retail channels. Aromatherapy end user segments attract the fastest volume expansion, while Food & Beverage applications sustain mature, price-sensitive procurement patterns with thinner margin pools.
FDA oversight of cosmetic and dietary supplement claims constrains how basil essential oil marketers communicate therapeutic benefits in the United States. ECHA REACH registration requirements for imported botanical substances create compliance barriers for non-European suppliers seeking European market access. USDA organic certification and EU organic regulation diverge on allowable processing aids, forcing dual-track documentation for global suppliers. Stakeholders must monitor evolving pharmacovigilance frameworks as basil essential oil crosses deeper into pharmaceutical-grade applications.
Market Dynamics
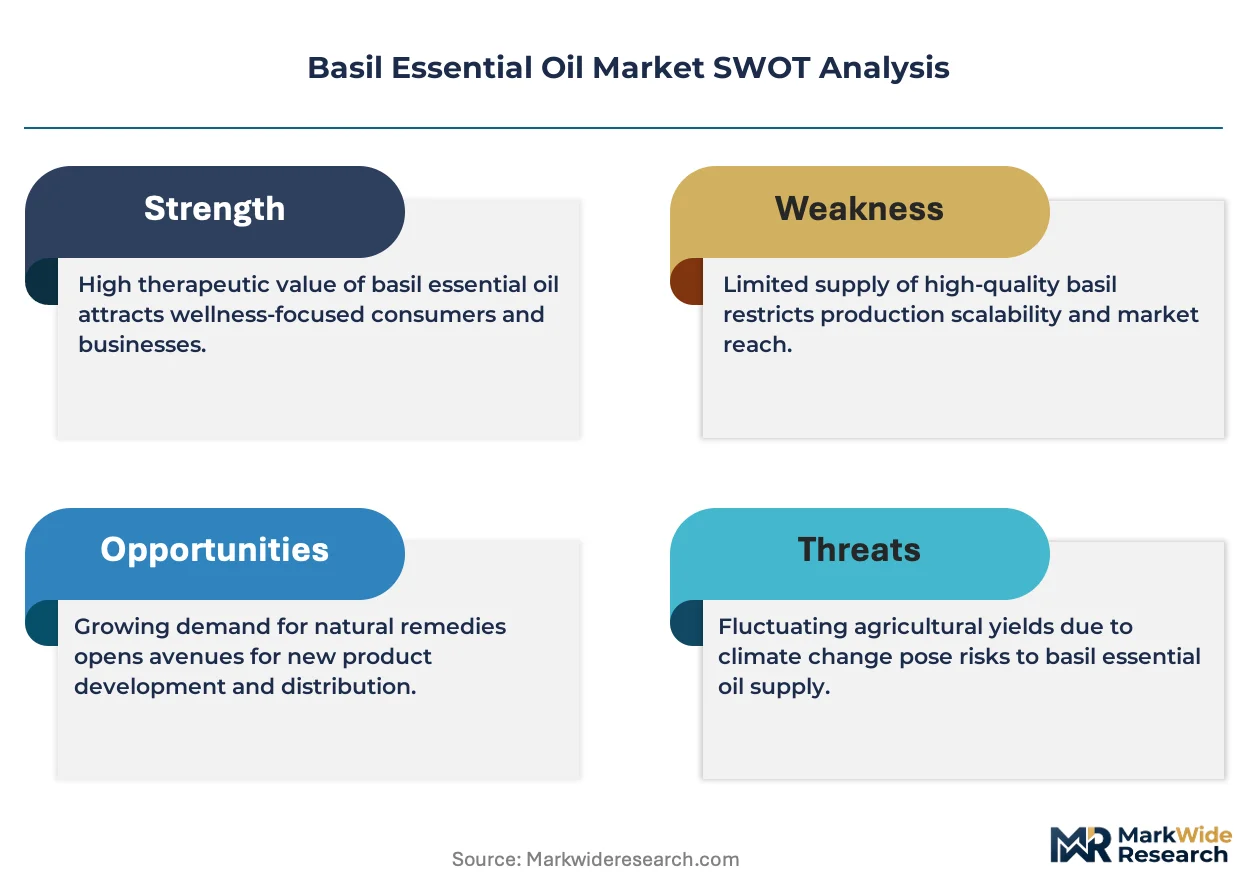
The basil essential oil market is being reshaped by the bifurcation between ISO 9001-certified suppliers and marginal producers, as quality management certification becomes a non-negotiable entry ticket for European and North American procurement channels.
Growth Catalysts
- Wellness center aromatherapy adoption:Spa chains and integrative health clinics across Germany, the United Kingdom, and California are standardizing basil essential oil in treatment protocols, creating institutional demand pull.
- USDA organic certification expansion:Retailers in the United States and Canada are mandating organic documentation for shelf placement, accelerating farm-level conversion in India and Madagascar.
- Steam distillation yield optimization:Harvest timing analytics and cultivar selection protocols are improving extraction efficiency from Ocimum basilicum flowering tops, lowering unit production costs for qualified processors.
Market Restraints
- Raw material concentration risk:Over seventy percent of commercial Ocimum basilicum cultivation clusters in Uttar Pradesh and Karnataka face monsoon variability and pest pressure, creating supply volatility.
- ECHA REACH registration barriers:Non-European suppliers face compliance documentation costs and testing timelines that exclude small-batch distillers from European market access.
- Synthetic linalool substitution:Fragrance compound manufacturers in China and Switzerland are deploying petrochemical-derived alternatives that undercut natural basil essential oil on price in mass-market applications.
Strategic Opportunities
- Pharmaceutical-grade pharmacovigilance frameworks:Emerging therapeutic applications in anxiety and antimicrobial protocols are creating pathways for basil essential oil to enter prescription-adjacent channels in France and Japan.
- Direct-to-practitioner distribution:Aromatherapy educators and certified clinical practitioners in Australia and South Korea are bypassing traditional retail, building recurring subscription volumes with verified suppliers.
- EU Green Deal bioeconomy incentives:Sustainable extraction investments and carbon-negative distillation upgrades qualify for preferential financing, rewarding early movers in Portugal and Greece.
Industry Challenges
- Gas chromatography analytical capacity gaps:Third-party batch verification requires specialized laboratory infrastructure that remains scarce in traditional cultivation regions, creating bottlenecks for transparency claims.
- Dual-track organic documentation:Suppliers serving both United States and European Union markets must maintain parallel compliance systems due to divergent processing aid allowances, inflating administrative overhead.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Basil Essential Oil Market |
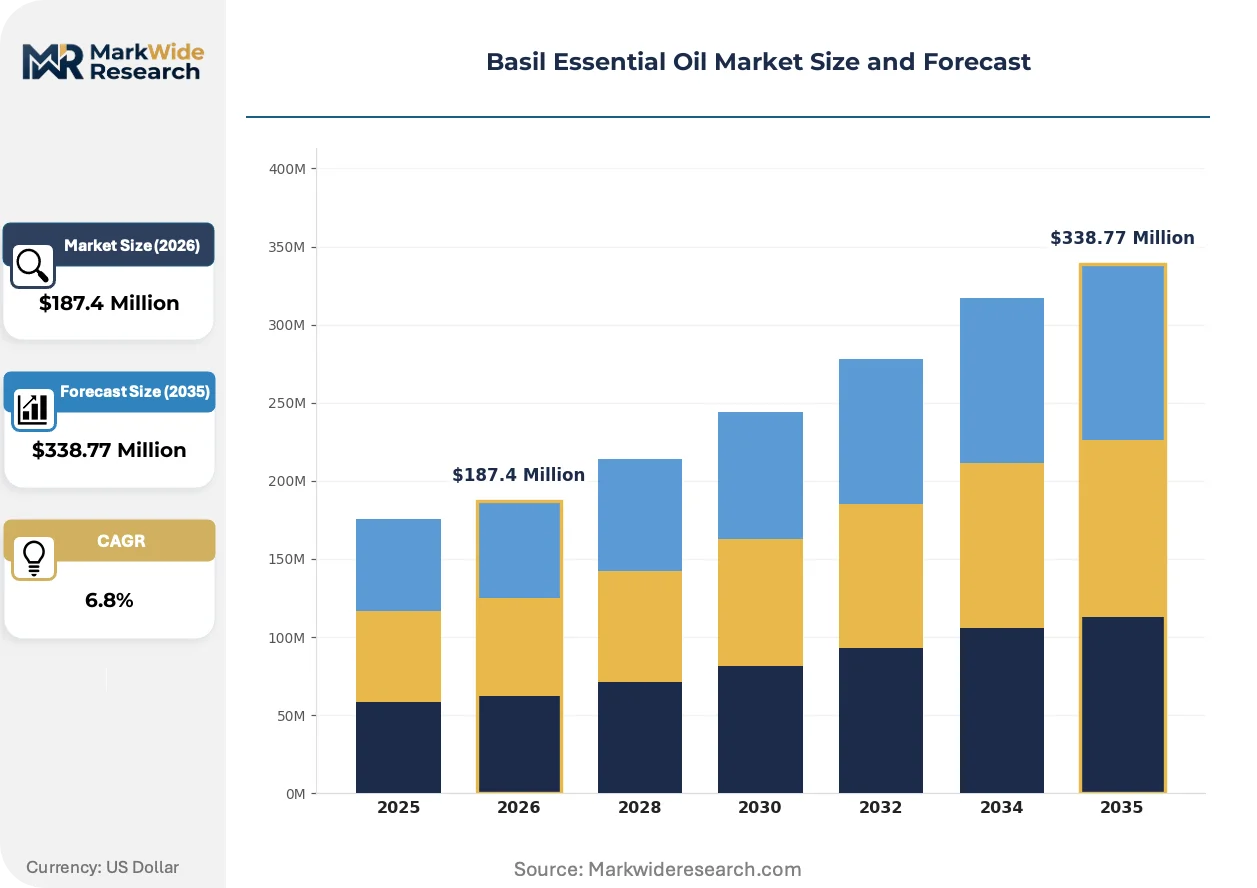
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Conventional, Organic, Steam Distilled, Cold Pressed End User: Personal Care, Food & Beverage, Aromatherapy, Pharmaceuticals Distribution Channel: Online Retail, Specialty Stores, Hypermarkets, Direct Sales Application: Perfumes, Culinary, Medical, Household |
| Companies Covered | doTERRA International, Young Living Essential Oils, NOW Foods, Plant Therapy Essential Oils, Edens Garden, Robertet Group, Givaudan, Mountain Rose Herbs, Rocky Mountain Oils, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Basil Essential Oil Market Strategic Shifts
Supercritical CO2 extraction and molecular distillation are displacing conventional steam methods, while blockchain traceability and AI-driven harvest forecasting are compressing the information asymmetry between field and buyer.
Microwave-assisted extraction technology is miniaturizing distillation footprints for smallholder cooperatives in India and Vietnam. Rural processing units near cultivation sites are adopting these systems to reduce transport losses of volatile aromatic compounds. The technology is miniaturizing capital requirements for village-level value capture, fragmenting production geography away from centralized factory models.
ECHA REACH registration deadlines for botanical substances are tightening substance documentation requirements for importers into the European Union. Downstream formulators are shifting supplier portfolios toward pre-registered European distributors to avoid compliance liability. Cosmetic and fragrance houses in France and Germany are responding by demanding full dossier transparency from Indian and Egyptian origin sources.
Certification-driven preference shifts are restructuring procurement evaluation criteria for basil essential oil buyers. Wellness retail chains and professional aromatherapy distributors are prioritizing Seed to Seal and organic verification over price in supplier selection. This behavior is most visible in California, British Columbia, and New South Wales, where consumer-facing brands face clean-label mandates from parent retailers.
Basil Essential Oil Market Segmentation
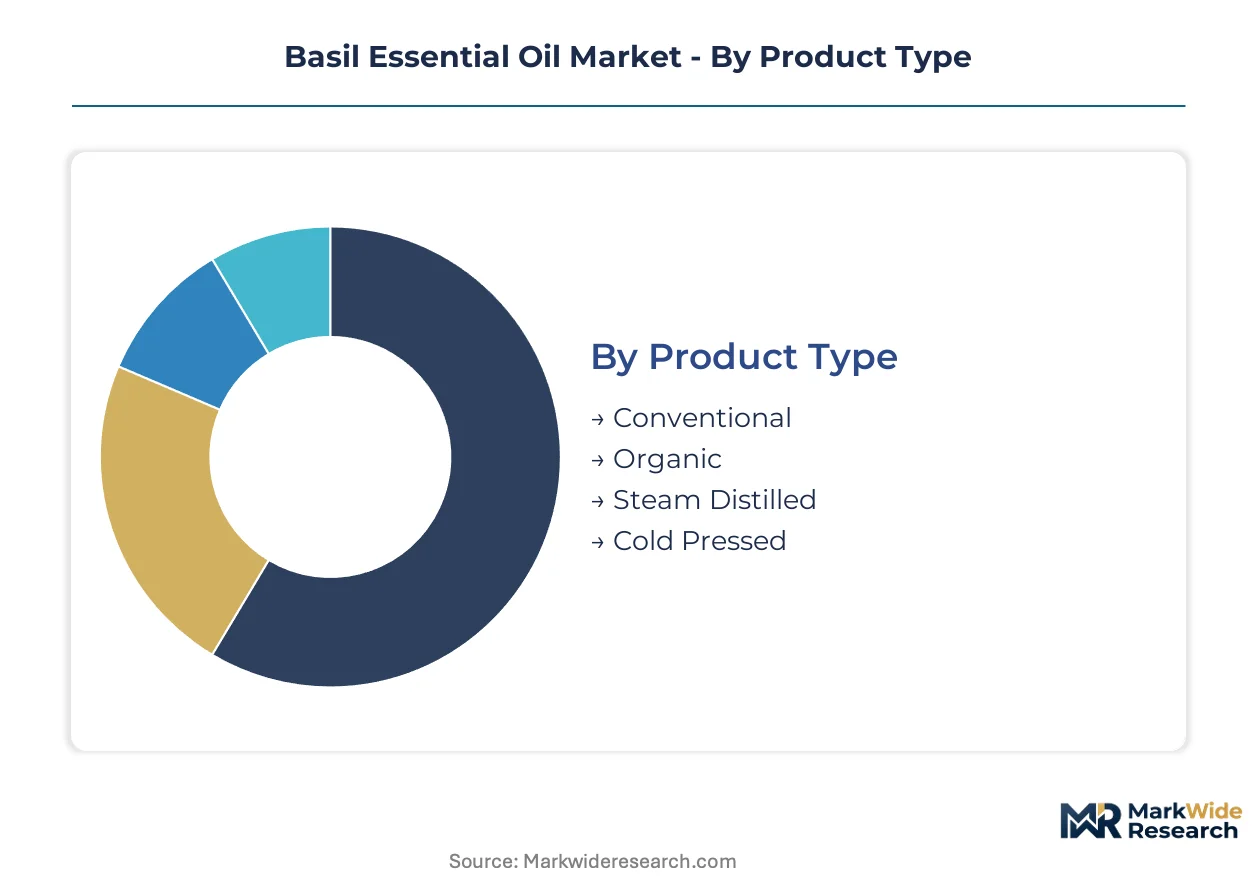
Basil essential oil procurement flows through distinct quality tiers that separate pharmaceutical-grade buyers from commodity fragrance houses. Certification requirements and extraction method preferences fragment supplier eligibility across end-use channels.
Product Type:
USDA organic and EU organic regulations impose divergent processing aid standards that reshape supplier documentation burdens.
- Conventional:Harvested from standard Ocimum basilicum cultivars without certified organic protocols. Price-sensitive fragrance manufacturers in China and mass-market personal care formulators in India absorb the majority of conventional volumes.
- Organic:Farm-level conversion in Uttar Pradesh and Madagascar accelerates as North American retailers mandate USDA documentation. EU organic regulation divergence forces dual-track compliance systems for suppliers serving both Atlantic markets.
- Steam Distilled:Dominant extraction method yielding 0.1% to 1.0% essential oil by weight from flowering tops. Traditional distillers in Karnataka and Grasse maintain capacity leadership for aromatherapy-grade output.
- Cold Pressed:Preservation of heat-sensitive volatile compounds attracts niche pharmaceutical and premium skincare applications. Limited commercial scale restricts availability to specialized distributors in Japan and Switzerland.
Established volume favors Conventional; emerging adoption favors Organic.
End User:
Margin structures diverge sharply between institutional wellness protocols and mature food ingredient procurement.
- Personal Care:Cosmetic formulators in France and Germany demand REACH-registered supply chains with full dossier transparency. Clean-label mandates from parent retailers in California and British Columbia accelerate organic specification.
- Food & Beverage:Mature procurement patterns with thinner margin pools dominate culinary applications. FSSAI compliance in India and FDA oversight in the United States constrain therapeutic claim communication.
- Aromatherapy:Spa chains across Germany and integrative health clinics in California standardize basil oil in treatment protocols. Certified clinical practitioners in Australia and South Korea build recurring subscription volumes.
- Pharmaceuticals:Emerging anxiety and antimicrobial applications create prescription-adjacent pathways in France and Japan. Pharmacovigilance frameworks from ANSM and PMDA impose evolving documentation requirements.
Food & Beverage anchors current volume; Aromatherapy climbs the fastest.
Distribution Channel:
Channel selection determines batch traceability depth and analytical transparency access.
- Online Retail:Direct-to-consumer platforms enable gas chromatography result publication and Seed to Seal verification storytelling. Wellness educators bypass traditional retail to build practitioner communities.
- Specialty Stores:Professional aromatherapy distributors in New South Wales and British Columbia prioritize certified organic inventory. Staff training requirements limit mass-market penetration.
- Hypermarkets:Price-driven procurement favors conventional grades with simplified documentation. Shelf placement mandates from parent retailers accelerate organic conversion pressures.
- Direct Sales:Subscription volumes with verified suppliers bypass intermediary markups for clinical practitioners. Relationship-based purchasing dominates pharmaceutical-grade procurement.
Hypermarkets capture mass volume; Direct Sales gains share fastest among premium tiers.
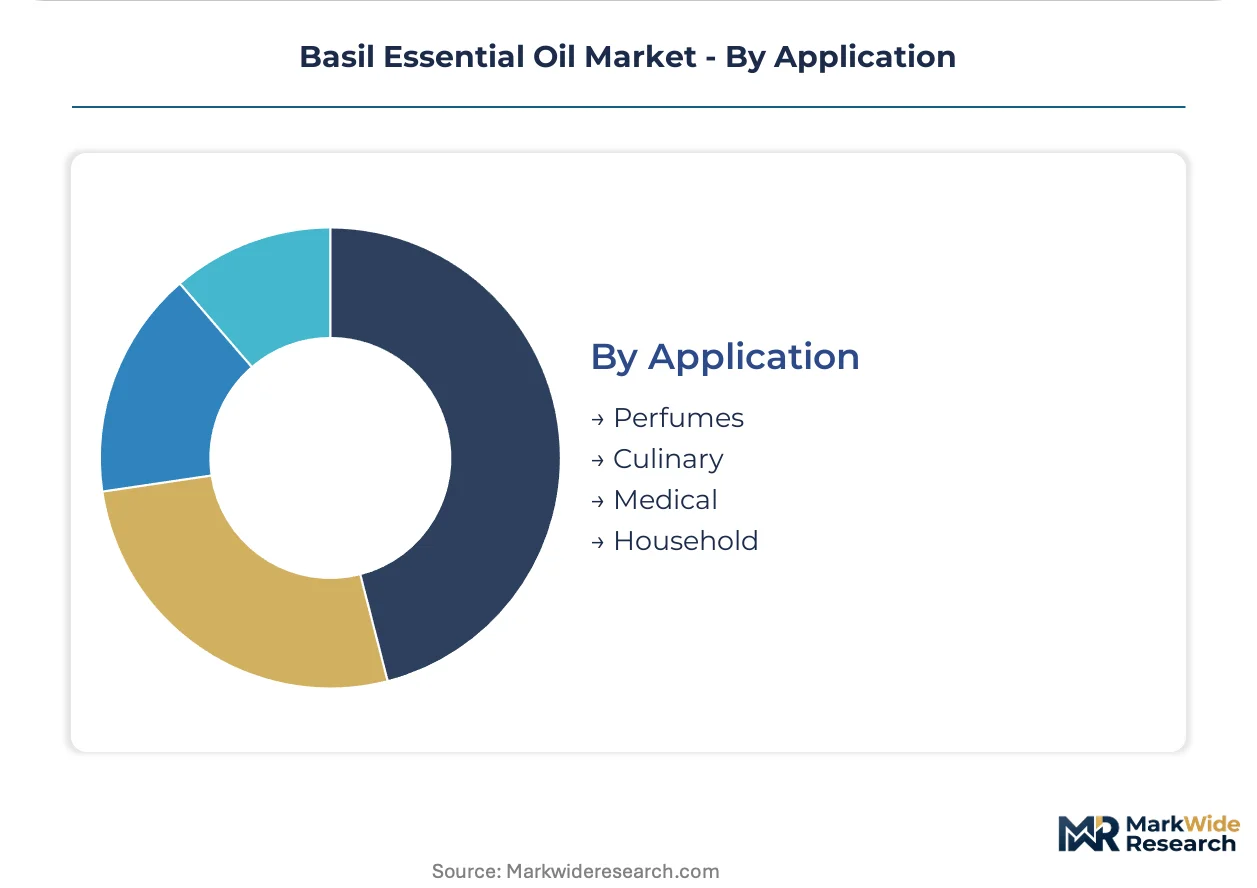
Application:
Performance specifications and regulatory exposure vary dramatically across end-use contexts.
- Perfumes:Synthetic linalool substitution from Chinese and Swiss manufacturers undercuts natural basil on price in mass-market fragrance. Premium niche houses in Grasse maintain natural specification for olfactory complexity.
- Culinary:Food-grade certification from FSSAI and FDA constrains harvest timing and post-distillation handling. Standardized procurement from established Indian suppliers dominates institutional food manufacturing.
- Medical:Prescription-adjacent applications require pharmacovigilance compliance with ANSM and PMDA frameworks. Clinical trial documentation gaps limit near-term penetration.
- Household:Surface antimicrobial claims face EPA and ECHA scrutiny for botanical substances. Clean-label positioning attracts premium home care formulators in North America.
Culinary sustains mature demand; Medical represents the steepest expansion trajectory pending regulatory clarity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Professional aromatherapy distributors in California, wellness retail chains in Germany, and integrative health clinics across Australia represent the dominant buyer archetypes shaping regional demand patterns for basil essential oil.
United States
Spa chains and integrative health clinics in California standardize basil essential oil in treatment protocols, creating institutional demand pull. FDA oversight constrains therapeutic claim communication for cosmetic and dietary supplement applications. Young Living Essential Oils anchors its Seed to Seal sourcing protocols from headquarters in Utah, securing premium raw material streams across multiple continents.
Germany
Wellness center aromatherapy adoption accelerates as spa chains across Bavaria and North Rhine-Westphalia institutionalize basil oil in treatment menus. ECHA REACH registration requirements create compliance barriers for non-European suppliers seeking market access. Fragrance houses in Hamburg demand full dossier transparency from Indian and Egyptian origin sources to avoid downstream liability.
India
Traditional distillation infrastructure in Uttar Pradesh and Karnataka supplies the largest commercial Ocimum basilicum cultivation clusters worldwide. FSSAI compliance constrains harvest timing and post-distillation handling for food-grade certification. Farm-level conversion to organic protocols accelerates as North American retailers mandate USDA documentation for export eligibility.
France
Premium niche fragrance houses in Grasse maintain natural basil specification for olfactory complexity despite synthetic linalool substitution pressure. ANSM pharmacovigilance frameworks impose evolving documentation requirements for prescription-adjacent therapeutic applications. Robertet Group leverages its integrated botanical supply chain from Grasse to secure premium raw material streams for European formulators.
Australia
Certified clinical practitioners in New South Wales and Victoria build recurring subscription volumes through direct-to-practitioner distribution channels. TGA oversight shapes therapeutic claim boundaries for botanical substances entering pharmaceutical-grade applications. Professional aromatherapy distributors in Sydney and Melbourne prioritize certified organic inventory with gas chromatography batch verification.
Basil Essential Oil Market Competitive Environment
Player mix skews toward vertically integrated botanical specialists and direct-to-consumer wellness brands, with tiered competitive positioning separating ISO 9001-certified suppliers from marginal producers. Strategic archetypes include integrated supply chain operators controlling cultivation through retail, transparency-focused brands publishing third-party analytical results, and commodity fragrance houses competing on volume scale. Dominant competitive moves encompass backward integration into captive raw material sourcing and geographic diversification of distillation assets across multiple cultivation zones.
Within the integrated supply chain tier, Robertet Group exemplifies the Grasse-based botanical specialist archetype, while Young Living Essential Oils anchors the direct-to-consumer wellness brand position through proprietary sourcing protocols. NOW Foods occupies the transparency-focused mass-market tier, competing aggressively on analytical disclosure. These three entities represent the dominant strategic vectors: upstream control over raw material streams, practitioner-direct relationship building, and batch-level verification publishing.
| Leading Market Players |
|---|
| doTERRA International |
| Young Living Essential Oils |
| NOW Foods |
| Plant Therapy Essential Oils |
| Edens Garden |
| Robertet Group |
| Givaudan |
| Mountain Rose Herbs |
| Rocky Mountain Oils |
| Others |
Value Chain & Pricing Dynamics
Steam distillation yield optimization at 0.1% to 1.0% extraction rates compresses margins for small-batch processors while concentrating pricing power among ISO 9001-certified operators with harvest timing analytics. Scale economies in Uttar Pradesh and Karnataka create floor prices that marginal producers cannot match, forcing supply consolidation toward integrated botanical specialists.
Pricing Analysis
Cost-plus contracts with linalool content indexation dominate procurement between Indian distillers and European fragrance houses. Three-tier pricing structure across pharmaceutical-grade, certified organic, and conventional commodity tiers separates buyers by documentation depth and analytical transparency requirements. Pricing pressure stems from synthetic linalool substitution by Chinese and Swiss manufacturers undercutting natural basil in mass-market fragrance applications. Food and beverage processors exhibit highest price sensitivity due to mature procurement patterns with thinner margin pools, while pharmaceutical-grade buyers prioritize batch verification over unit cost.
Supply Chain Analysis
India and Madagascar anchor commercial Ocimum basilicum cultivation, with Uttar Pradesh and Karnataka clusters supplying over seventy percent of global raw material volumes. Steam distillation infrastructure draws from flowering tops harvests, glass distillation equipment, and fuelwood or biomass energy inputs. Single-source vulnerability concentrates in monsoon-dependent cultivation zones facing pest pressure and climate variability. Distribution runs through Grasse-based botanical specialists for European pharmaceutical and fragrance channels, direct-to-practitioner subscriptions for Australian and South Korean clinical aromatherapy markets, and hypermarket procurement for North American retail shelf placement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The basil essential oil market is recovering from synthetic substitution pressure as wellness center aromatherapy adoption creates institutional demand pull for verified natural supply chains.
For Market Incumbents: Consolidate backward integration into captive cultivation clusters in Karnataka and Madagascar to secure raw material streams against monsoon volatility. Deepen ISO 9001 certification penetration to exclude marginal producers from European and North American procurement channels. Prioritize gas chromatography analytical capacity investments to defend transparency claims against NOW Foods and other disclosure-focused competitors. For New Entrants and Emerging Players: Lead with direct-to-practitioner distribution in Australia and South Korea where certified clinical practitioners build recurring subscription volumes outside traditional retail markups. Target pharmaceutical-grade applications in France and Japan where ANSM and PMDA pharmacovigilance frameworks create documentation barriers that favor specialized entrants over commodity suppliers. Deploy microwave-assisted extraction technology to miniaturize capital requirements for village-level value capture in Vietnam and Indonesia. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among direct-to-practitioner distributors with verified organic supply chains and gas chromatography batch transparency. Long-term viability over a five-to-ten year window favors acquisition targets with dual-track USDA and EU organic documentation capabilities. Monitor ECHA REACH registration deadline compliance as the critical inflection signal separating pre-registered European distributors from excluded small-batch distillers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cultivation | Captive supply from Karnataka and Madagascar clusters secures raw material streams against climate volatility. |
| ISO 9001 Certification Investment | Quality management documentation becomes non-negotiable entry ticket for European and North American buyers. |
| Gas Chromatography Analytical Capacity | Third-party batch verification infrastructure supports transparency claims in pharmaceutical-grade and premium aromatherapy tiers. |
| Dual-Track Organic Documentation | Parallel USDA and EU organic compliance systems enable access to both Atlantic retail markets without regulatory exclusion. |
| Microwave-Assisted Extraction Deployment | Rural processing miniaturization fragments production geography toward village-level value capture in secondary cultivation zones. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with aromatherapy educators, certified clinical practitioners in Australia and South Korea, distillery operators in Uttar Pradesh and Karnataka, and procurement managers at European fragrance houses. Secondary validation drew from ECHA REACH registration databases, FSSAI food-grade certification records, USDA organic handler listings, and trade flow documentation through Indian customs authorities. Bottom-up cultivation area estimates and top-down end-use consumption models were triangulated to anchor volume projections.
Across the analysis window, the forecasting framework modeled segmentation by product type (conventional, organic, steam distilled, cold pressed), end user (personal care, food and beverage, aromatherapy, pharmaceuticals), and distribution channel (online retail, specialty stores, hypermarkets, direct sales). CAGRs were derived from fitted growth curves calibrated to aromatherapy adoption rates in wellness centers and organic certification conversion timelines in Indian and Madagascar cultivation clusters. Linalool and methyl chavicol content specifications shaped pharmaceutical-grade premium tier assumptions.
The analysis sits within stated boundaries; outcomes outside sustained wellness center institutionalization, stable monsoon patterns in South Asia, and continued synthetic linalool price competitiveness would require recalibration. Forecasts reflect documented assumptions on harvest timing optimization, REACH registration compliance rates, and dual-track organic documentation adoption. Recalibration cycles align with material shifts in ECHA regulatory deadlines, FDA cosmetic claim enforcement patterns, and EU Green Deal bioeconomy incentive disbursements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Spices and Seasonings
Savoury Seasoning Market
Spices and Seasonings
Cardamom Oil Market
Spices and Seasonings
Middle East and Africa Botanical Extract Market
Spices and Seasonings
Europe Seasoning Market
Spices and Seasonings
Nutmeg Oil Market
Spices and Seasonings
Gourmet Seaweed Seasoning Market
Spices and Seasonings
Cajun Spice Market
Spices and Seasonings
Sriracha Market
Spices and Seasonings
Asia-Pacific Spice and Herb Extracts Market
Spices and Seasonings
Habanero Salt Market
Spices and Seasonings
Incense Sticks (Agarbatti) Market
Spices and Seasonings
Malaysia Spices and Seasonings Market
Spices and Seasonings
Moringa Leaves Powder Market
Spices and Seasonings
Egypt Herbs and Spices Market
Spices and Seasonings
Celery Seed Extract Powder Market
Spices and Seasonings
Spice Grinders Market