
 Global Ketone Supplements Market | 2026-2036
Global Ketone Supplements Market Size, Share, and Industry Trends Forecast 2026-2036
Global Ketone Supplements Market Foresight
A capital-intensity divergence between in-house fermentation capacity and outsourced blending operations is redrawing competitive boundaries. Pruvit Ventures, Inc. leverages its direct-to-consumer channel infrastructure to sustain recurring revenue pools. HVMN Inc. anchors its position through ketone ester R&D depth and clinical validation partnerships. Perfect Keto competes on formulation accessibility, dominating mid-tier ketone salt pricing.
Ketone supplements comprise exogenous compounds—primarily beta-hydroxybutyrate salts and esters—delivering 10–12 grams of bioavailable ketones per serving to induce nutritional ketosis without carbohydrate restriction. Manufacturers employ either chemical synthesis or microbial fermentation to achieve stereoselective BHB production for human metabolic utilization. Ketone esters command premium positioning due to faster blood ketone elevation, while ketone salts occupy volume leadership through lower production costs and broader palatability. Endurance sports applications are outpacing weight management in growth velocity, though cognitive enhancement retains the highest per-unit margin structure.
FDA New Dietary Ingredient notifications govern novel ketone ester introductions in the United States, while EFSA health claim assessments constrain marketing language across European markets. BfR toxicity evaluations in Germany and FSSAI nutraceutical licensing in India create divergent compliance cost structures that filter market entrants by capital depth. Stakeholders must monitor evolving pharmacovigilance requirements for synthetic ketone analogues as regulators scrutinize chronic exposure thresholds.
Market Dynamics
Metabolic efficiency research is reconfiguring demand composition across endurance sports, cognitive performance, and clinical nutrition verticals. This scientific validation wave is compressing the gap between ketone ester premium positioning and ketone salt volume accessibility.
Growth Catalysts
- FDA New Dietary Ingredient pathway:The notification framework for novel ketone esters provides regulatory clarity that accelerates product entry timelines in the United States. Manufacturers leverage this structure to differentiate ester formulations from legacy salt products.
- Endurance sports institutionalization:Professional cycling teams and marathon training programs are integrating exogenous ketones into periodized nutrition protocols. This institutional adoption creates recurring demand pools with lower customer acquisition costs.
- Germany BfR guidance alignment:The Federal Institute for Risk Assessment's toxicity evaluations support premium positioning of exogenous ketones within European sports nutrition frameworks. German market concentration validates quality standards that export to adjacent EU markets.
Market Restraints
- Input cost volatility:Stereoselective beta-hydroxybutyrate production relies on specialty fermentation substrates and chiral catalysts. Price swings in these biochemical inputs compress margin predictability for mid-tier manufacturers.
- Palatability engineering constraints:Ketone esters exhibit inherent bitterness profiles that resist conventional flavor masking technologies. This sensory limitation restricts serving-size scalability and repeat purchase rates in consumer segments.
- Supply concentration in fermentation capacity:Commercial-scale microbial BHB production clusters among contract manufacturers with GMP-certified facilities. This supplier geography concentration creates queueing risk during demand surges.
Strategic Opportunities
- India FSSAI nutraceutical licensing:The Food Safety and Standards Authority of India's formalized nutraceutical category creates regulatory infrastructure for ketone supplement import and domestic formulation. Early entrants capture sports nutrition shelf space in metro pharmacy chains.
- Cognitive enhancement application expansion:Silicon Valley technology workers and financial trading floors are adopting micro-dosed ketone protocols for sustained mental acuity. This white-collar vertical commands per-unit margins above athletic applications.
- Direct-to-consumer channel infrastructure:Subscription-based replenishment models bypass traditional sports nutrition retail markups. Brands owning customer data capture lifetime value multiples exceeding wholesale distribution economics.
Industry Challenges
- Clinical validation timeline compression:Peer-reviewed efficacy studies require 18-36 month publication cycles that lag marketing claim velocity. Brands face regulatory scrutiny when promotional language outpaces published data.
- Formulation stability under variable storage:Ketone ester hydrolysis susceptibility demands cold-chain integrity through last-mile distribution. Temperature excursion risk elevates insurance and replacement cost burdens.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Ketone Supplements Market |
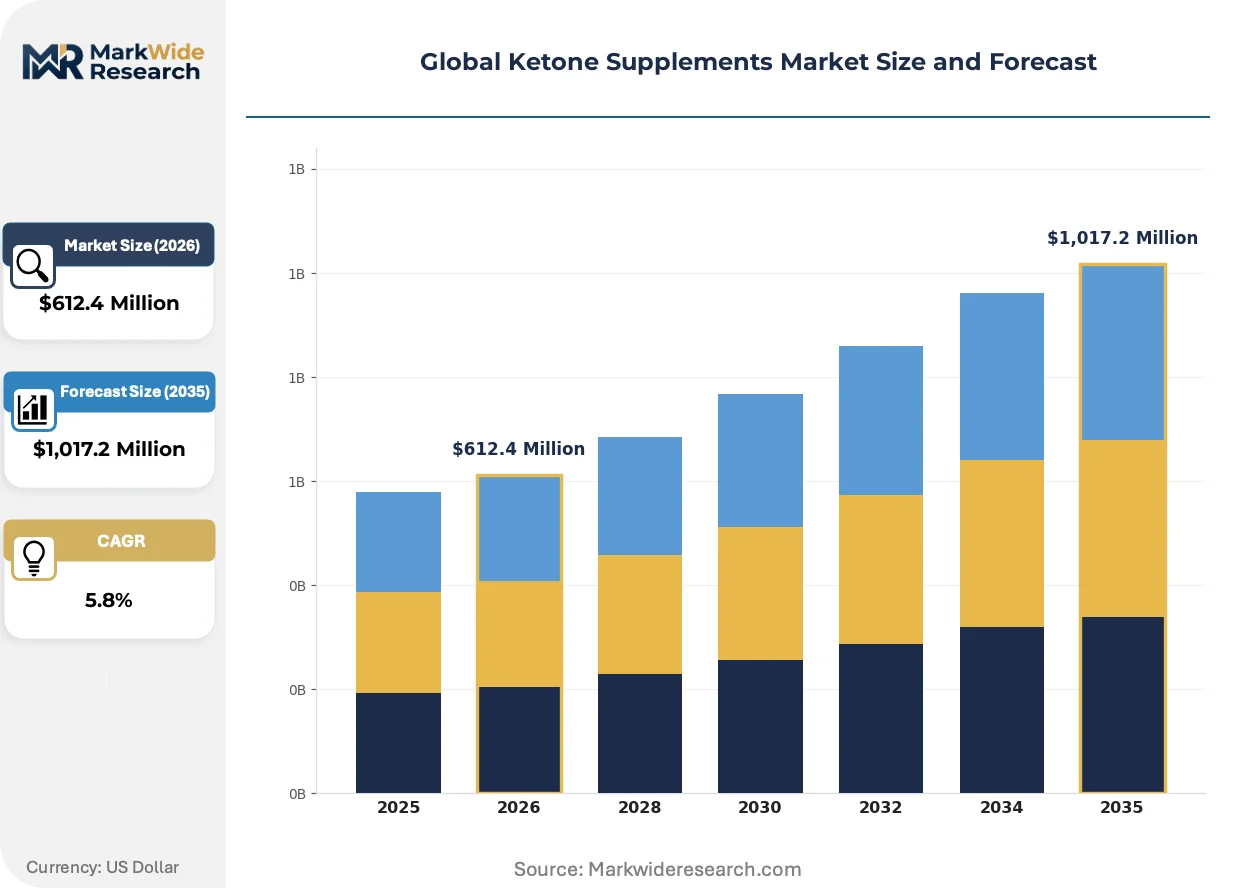
| Market Size in 2026 | $612.4 Million |
| Market Size in 2035 | $1,017.2 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Exogenous Ketones, Ketone Esters, Ketone Salts, Ketogenic Powders, Ketone Capsules Application: Weight Management, Cognitive Enhancement, Endurance Sports, Therapeutic Nutrition, Anti-Aging End User: Fitness Enthusiasts, Professional Athletes, Nutritional Therapists, Wellness Clinics, Aging Population Distribution Channel: Online Retailers, Specialty Stores, Pharmacies, Health Food Stores, Direct-to-Consumer Sales |
| Companies Covered | Perfect Keto, HVMN Inc., Pruvit Ventures, Inc., Ketologic, KetoneAid, Zhou Nutrition, BPI Sports, Ancient Nutrition, Compound Solutions Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Ketone Supplements Market Shifts & Advancements
Bioprocess engineering advances and regulatory harmonization efforts are converging to reshape competitive differentiation mechanisms. These forces are elevating clinical validation from marketing accessory to market access prerequisite.
Microbial fermentation platforms utilizing engineered yeast strains are achieving stereoselective beta-hydroxybutyrate yields that match chemical synthesis purity. Contract manufacturers in Germany and the Netherlands are scaling these bioreactor systems to commercial tonnage. This biological production route is supplanting petrochemical-derived chiral synthesis for premium ketone ester feedstock, compressing capital intensity barriers for new market entrants.
REACH registration requirements for novel synthetic ketone analogues are expanding toxicological data obligations across European manufacturing. EFSA health claim assessments now constrain marketing language for metabolic efficiency assertions in 27 member states. Sports nutrition brands are responding by funding investigator-initiated trials that generate publishable efficacy data ahead of regulatory submission deadlines.
Subscription replenishment models are displacing single-transaction retail purchases among recurring users in North American and Australian markets. Direct-to-consumer platforms capture consumption-pattern data that enables personalized dosing algorithms and flavor rotation. This channel migration concentrates customer lifetime value with vertically integrated brands while eroding wholesale margin pools for legacy sports nutrition distributors.
Global Ketone Supplements Market Segmentation
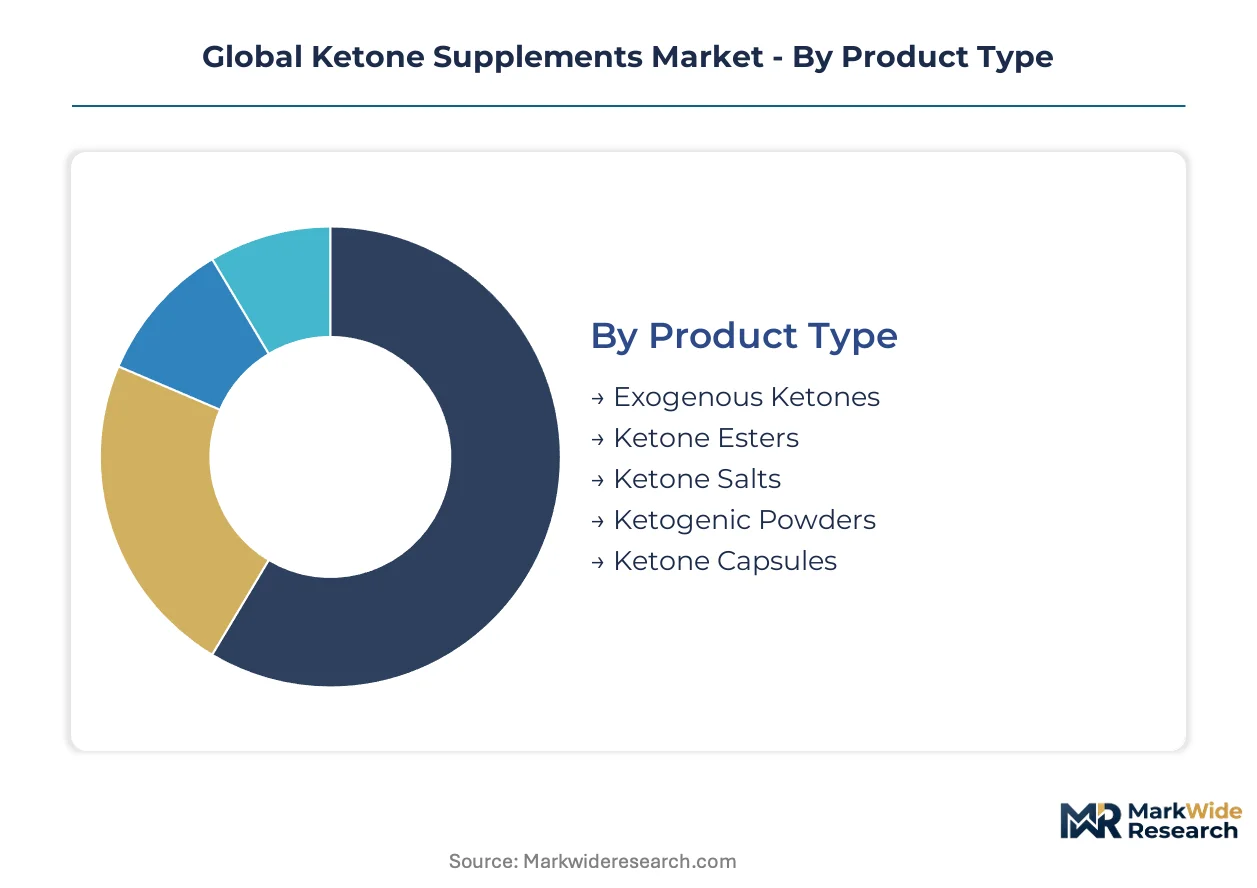
Ketone supplement segmentation reveals divergent commercial logics across formulation chemistry, performance application, and channel economics. Manufacturers must align R&D investment and regulatory strategy to the specific margin structures and compliance pathways of each segment cluster.
Product Type:
Domestic formulation dominates ketone salts and ketogenic powders, while ketone esters rely on export-led demand from German and Dutch bioreactor facilities.
- Ketone Esters:These compounds deliver racemic or enantiopure beta-hydroxybutyrate esterified to butanediol or glycerol, achieving blood ketone elevation within 15-30 minutes of ingestion. Demand concentrates in professional cycling teams and military performance programs across Germany and the Netherlands, constrained by EFSA health claim limitations on metabolic efficiency marketing.
- Ketone Salts:Mineral-bound BHB—typically sodium, potassium, or calcium salts—provides 10-12 grams bioavailable ketones per serving with improved palatability over ester alternatives. Volume leadership rests with North American direct-to-consumer brands, though margin compression from input cost volatility in chiral catalysts pressures mid-tier producers.
- Exogenous Ketones:Broad category encompassing all non-endogenous ketone delivery formats, with demand fragmentation across experimental nootropic communities and clinical research protocols.
- Ketogenic Powders:Multi-ingredient formulations combining BHB with MCT oil and electrolytes, positioned for meal-replacement convenience in weight management verticals.
- Ketone Capsules:Encapsulated BHB salts offering portable dosing precision, gaining traction among Silicon Valley technology workers pursuing cognitive enhancement protocols.
Ketone salts command the established base. The steepest expansion runs through ketone esters.
Application:
Cost tier stratification separates premium clinical nutrition from mass-market weight management, with endurance sports occupying the intermediate value band.
- Endurance Sports:Periodized ketone loading protocols for marathon runners and triathletes require validated dosing regimens with documented glycogen-sparing effects. Institutional adoption by professional cycling teams in Italy and Spain creates recurring procurement contracts with lower customer acquisition expenditure.
- Cognitive Enhancement:Micro-dosed ketone protocols targeting sustained mental acuity command per-unit margins exceeding athletic applications by substantial multiples. Demand concentrates among quantitative trading floors in London and technology engineering clusters in San Francisco, constrained by limited peer-reviewed efficacy data for non-athletic populations.
- Weight Management:Ketone supplements positioned as appetite suppression adjuncts compete within crowded functional nutrition shelves, with differentiation relying on flavor engineering and subscription retention mechanics.
- Therapeutic Nutrition:Medical-grade ketone formulations for epilepsy adjunct therapy and neurodegenerative condition management require FDA New Dietary Ingredient notification or EMA medical food classification.
- Anti-Aging:Longevity-focused positioning leverages NAD+ pathway research and mitochondrial health claims, with regulatory scrutiny from FTC and national advertising standards authorities.
Cognitive enhancement captures premium pricing. Endurance sports delivers volume scalability.
End User:
Customer type concentration varies sharply between institutional procurement channels and individual replenishment behaviors.
- Professional Athletes:Teams and individual competitors with dedicated nutrition staff demand batch-tested, contaminant-free formulations with WADA compliance documentation. Procurement runs through sports science departments rather than personal purchase decisions.
- Fitness Enthusiasts:Recreational exercisers pursuing ketogenic dietary adherence represent the volume foundation, with purchase decisions driven by palatability and social media influencer endorsement rather than clinical validation.
- Nutritional Therapists:Licensed practitioners prescribing ketone supplements for metabolic health protocols require professional education support and patient monitoring tools from manufacturers.
- Wellness Clinics:Concierge medical practices integrating exogenous ketones into longevity and performance optimization programs demand white-label formulation flexibility and practice management software integration.
- Aging Population:Seniors targeting cognitive preservation and metabolic flexibility represent an emerging segment with distinct flavor preference and packaging accessibility requirements.
Fitness enthusiasts anchor current revenue. Professional athletes structure future contract value.
Distribution Channel:
Channel migration from wholesale retail to captive digital infrastructure is redrawing margin capture and customer data ownership.
- Direct-to-Consumer Sales:Subscription replenishment models bypass traditional sports nutrition retail markups of 40-60 percent, enabling personalized dosing algorithms and flavor rotation based on consumption-pattern data. Vertically integrated brands in North America and Australia concentrate lifetime value multiples exceeding wholesale economics.
- Online Retailers:Amazon and specialized sports nutrition e-commerce platforms provide discovery reach for emerging brands, though algorithm-dependent visibility creates customer acquisition cost volatility.
- Specialty Stores:Dedicated sports nutrition retail in Germany and the UK offers educated staff consultation, supporting premium positioning for ketone esters with complex dosing protocols.
- Pharmacies:Metro pharmacy chains in India following FSSAI nutraceutical licensing expansion provide regulated shelf space for imported formulations targeting early-adopter segments.
- Health Food Stores:Natural products retailers emphasize clean-label positioning and organic certification, with ketone salt formulations competing against established MCT oil and collagen products.
Direct-to-consumer sales is gaining share fastest. Specialty stores defend premium positioning.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import flows in ketone supplements favor German and Dutch bioreactor output feeding North American direct-to-consumer demand, while Indian formulation capabilities emerge as a counterweight to concentrated European fermentation supply. This trade geometry shapes regulatory compliance investments and distribution infrastructure decisions across manufacturing hubs.
United States
FDA New Dietary Ingredient notifications govern novel ketone ester market entry timelines, creating a structured pathway that legacy salt products bypass. The notification framework demands toxicological dossiers that filter capital-light entrants from premium formulation competitors. San Francisco technology clusters and Los Angeles sports nutrition markets drive cognitive enhancement and endurance sports demand respectively.
Germany
Federal Institute for Risk Assessment toxicity evaluations under BfR guidance validate premium exogenous ketone positioning for export throughout EU markets. German sports nutrition regulation permits specific metabolic efficiency claims unavailable under stricter EFSA jurisdictions. Contract manufacturing clusters in Bavaria and North Rhine-Westphalia scale microbial fermentation to commercial tonnage for ketone ester feedstock.
Netherlands
REACH registration requirements for synthetic ketone analogues expand toxicological data obligations for manufacturers serving European demand. Rotterdam logistics infrastructure and Eindhoven bioprocessing engineering centers concentrate formulation and distribution capabilities. Dutch contract manufacturers supply stereoselective BHB to UK and Scandinavian markets navigating post-Brexit regulatory divergence.
India
FSSAI nutraceutical licensing formalization creates regulatory infrastructure for ketone supplement import and domestic formulation expansion. Metro pharmacy chains in Mumbai and Delhi capture early-adopter sports nutrition demand previously served through informal channels. Domestic blending operations in Gujarat and Maharashtra target cost-optimized ketone salt production for price-sensitive fitness segments.
Australia
TGA therapeutic goods frameworks classify high-dose ketone formulations according to intended use claims, separating sports nutrition from medical food categories. Subscription-based direct-to-consumer penetration exceeds North American rates, concentrating customer lifetime value with vertically integrated brands. Sydney and Melbourne wellness clinic networks integrate exogenous ketones into longevity optimization protocols.
Global Ketone Supplements Market Competitive Landscape
Concentration sits with direct-to-consumer specialists and clinical validation anchors rather than diversified nutrition conglomerates. The competitive map reveals a bifurcated structure: premium ketone ester players depend on fermentation partnerships and peer-reviewed efficacy data, while volume ketone salt competitors compete on flavor engineering and subscription retention mechanics. Strategic archetypes include vertically integrated DTC platforms, R&D-heavy ester specialists, and outsourced-blending price competitors. Dominant competitive moves encompass subscription infrastructure buildout and investigator-initiated trial funding to preempt regulatory marketing constraints.
Within the clinical validation tier, HVMN Inc. exemplifies ketone ester research depth through academic partnership structures. Pruvit Ventures, Inc. occupies the direct-to-consumer platform position with recurring revenue infrastructure. Perfect Keto represents formulation accessibility archetypes competing on mid-tier ketone salt pricing and flavor accessibility. These three anchors illustrate the strategic divergence between premium ester positioning and volume salt accessibility that defines competitive boundaries.
| Leading Market Players |
|---|
| Perfect Keto |
| HVMN Inc. |
| Pruvit Ventures, Inc. |
| Ketologic |
| KetoneAid |
| Zhou Nutrition |
| BPI Sports |
| Ancient Nutrition |
| Compound Solutions Inc. |
| Others |
Supply & Pricing Matrix
Commercial-scale fermentation capacity utilization above 85 percent in Bavarian and North Rhine-Westphalian facilities compresses per-unit BHB production costs while elevating price floors for mid-tier entrants lacking captive bioreactor access. This scale concentration concentrates pricing power with contract manufacturers serving premium ketone ester demand, while outsourced-blending operators absorb margin volatility from chiral catalyst and specialty substrate markets.
Pricing Analysis
Professional cycling teams and military procurement programs anchor a three-tier pricing structure across premium, standard, and economy levels. Price differentiation rests on enantiomeric purity certification and cold-chain integrity guarantees, with ester formulations commanding substantial premiums over salt alternatives. Cost compression in mid-tier ketone salts is intensifying because Chinese fermentation substrate exports face EU REACH registration friction. Fitness enthusiasts pursuing direct-to-consumer subscriptions exhibit highest price sensitivity; institutional buyers with WADA compliance requirements show lowest.
Supply Chain Analysis
Just-in-time inventory preferences dominate professional sports team procurement with periodized loading protocols, while strategic stockpiling characterizes German and Dutch contract manufacturers managing fermentation campaign cycles. Geographic supply concentration centers on Germany, the Netherlands, and India. Raw material dependencies draw from corn-derived fermentation feedstock, chiral catalyst precursors, and pharmaceutical-grade mineral salts. Single-source vulnerability in stereoselective BHB fermentation strains elevates supply chain risk. Distribution runs through direct-to-consumer subscription platforms and specialty sports nutrition retail.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The ketone supplements market exhibits cyclical recovery characteristics as post-pandemic endurance sports institutionalization restores demand velocity previously disrupted by event cancellations. This recovery is anchored in professional team procurement normalization and military performance program expansion.
For Market Incumbents: Shield formulation margins by securing captive fermentation capacity in GMP-certified German or Dutch facilities before queueing risk intensifies. Defend against mid-tier price erosion by accelerating FDA New Dietary Ingredient notification timelines for novel ester derivatives. Prioritize clinical validation partnerships that preempt EFSA marketing constraint expansion.
For New Entrants and Emerging Players: Anchor in India's FSSAI-regulated pharmacy channel expansion, where formalized nutraceutical licensing creates first-mover shelf access in Mumbai and Delhi metro chains. Target cognitive enhancement applications among Silicon Valley technology clusters, where micro-dosed protocols command premium positioning with limited incumbent penetration. Pursue white-label partnerships with wellness clinics seeking practice management software integration.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors vertically integrated direct-to-consumer platforms with proprietary subscription infrastructure and consumption-pattern data assets. Long-term viability rests on brands capturing customer lifetime value multiples exceeding wholesale distribution economics. The acquisition target archetype combines clinical validation depth with captive fermentation partnerships. Watch for FDA enforcement action on unsubstantiated metabolic efficiency claims as inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA New Dietary Ingredient Notification | Accelerates premium ester market entry timelines with regulatory clarity unavailable to legacy salt competitors. |
| Microbial Fermentation Scale-Up | Engineered yeast strain deployment in German bioreactors achieves stereoselective BHB yields matching chemical synthesis purity. |
| Direct-to-Consumer Platform Buildout | Subscription replenishment models bypass 40-60 percent retail markups while capturing personalized dosing algorithm data. |
| Investigator-Initiated Trial Funding | Generates publishable efficacy data ahead of EFSA health claim assessment deadlines constraining marketing language. |
| Cold-Chain Distribution Partnership | Secures temperature integrity through last-mile delivery for hydrolysis-susceptible ketone ester formulations. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with sports science directors at professional cycling teams, contract manufacturing facility managers in Bavaria and North Rhine-Westphalia, regulatory affairs leads navigating FDA notification pathways, and direct-to-consumer brand operators managing subscription infrastructure. Secondary validation drew from FDA New Dietary Ingredient notification databases, EFSA health claim assessment registers, FSSAI nutraceutical licensing records, and customs trade flow data. Bottom-up segment sizing triangulated against top-down market value reconstruction.
Across the analysis window, the forecasting framework modeled volume and value trajectories through segmentation by formulation chemistry, performance application, end user archetype, and distribution channel structure. CAGRs were derived from trend extrapolation adjusted for regulatory timeline impacts and institutional adoption S-curves. Industry-specific forecast inputs incorporated endurance sports procurement cycle normalization and cognitive enhancement white-collar vertical penetration rates.
Decision-makers should treat outputs as directional under assumptions of sustained professional team institutionalization and stable fermentation substrate pricing; material deviation would warrant model refresh. Forecasts embed assumptions regarding FDA notification pathway continuity and EFSA marketing constraint evolution. Revision becomes warranted when regulatory enforcement intensity on metabolic efficiency claims crosses thresholds observed in adjacent sports nutrition categories.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sports Nutrition
North America Protein Based Sports Drinks Market
Sports Nutrition
Creatine Monohydrate Market
Sports Nutrition
Africa Sports Drink Market
Sports Nutrition
China Sports Drink Market
Sports Nutrition
United States Weight Management Market
Sports Nutrition
Hydration Supplement Market
Sports Nutrition
Europe Sports Nutrition Market
Sports Nutrition
North America Sports Drink Market
Sports Nutrition
ACF Supplements Market
Sports Nutrition
Hydroxymethylbutyrate Supplement Market
Sports Nutrition
Sports Supplement Market
Sports Nutrition
Brazil Sports Drinks Market
Sports Nutrition
Caloric Supplements Market
Sports Nutrition
GCC Sports Nutrition Market
Sports Nutrition
UK Sports Nutrition Market
Sports Nutrition
Europe Weight Management Supplement Market