
 Dog Carrier Bags Market | 2026-2036
Dog Carrier Bags Market Size, Share, and Industry Trends Forecast 2026-2036
Dog Carrier Bags Market Analytics
Pet product design talent shortages in Southeast Asian manufacturing hubs is unwinding cost advantages for basic nylon carriers. Sleepypod leverages in-house crash-testing protocols to anchor premium positioning in automotive-grade safety. Pet Gear competes through mass-market channel control across big-box pet retail. Kurgo specializes in adventure-travel functionality with reinforced harness integration.
Dog carrier bags are portable containment systems constructed from woven synthetics, natural fibers, or hybrid laminates, engineered with ventilation apertures, structural framing, and closure mechanisms to transport canines in transit environments. Manufacturing employs heat-sealed seam bonding for waterproof grades and die-cut foam panels for structural backpacks. The backpack segment leads volume due to commuter convenience in dense urban transit systems, while the mesh material category captures expanding share as breathability standards tighten. Eco-friendly feature variants represent the fastest-growing margin pool as EU Green Deal procurement criteria penetrate retail buyer specifications.
FDA Center for Veterinary Medicine guidelines influence carrier safety claims in US interstate commerce, while REACH compliance from ECHA governs chemical disclosures for European textile imports. California's Proposition 65 enforcement creates de facto national labeling standards for US-bound production. Stakeholders must monitor evolving airline cabin dimensional restrictions as carriers become the decisive purchase trigger for frequent-traveling pet owners.
Market Dynamics
Airline cabin dimensional restrictions are compressing product development cycles as frequent-traveling pet owners demand dimensional precision that matches carrier-specific under-seat measurements. Manufacturers now engineer around evolving FAA guidance and individual airline policies rather than static size categories.
Growth Catalysts
- REACH textile chemical compliance:EU ECHA disclosure mandates are filtering unsafe suppliers from European import channels, creating procurement advantages for certified manufacturers.
- Urban millennial pet ownership density:Metropolitan corridors in the United States concentrate demand for commuter-compatible backpack carriers with transit-system integration.
- Crash-testing protocol adoption:Automotive-grade safety validation is migrating from pet automotive products into carrier design specifications.
Market Restraints
- Polyester and nylon input volatility:Petrochemical feedstock price swings compress margin predictability for woven synthetic carriers.
- Southeast Asian design talent scarcity:Basic nylon carrier production faces unwinding cost advantages as technical pattern-making skills concentrate elsewhere.
- California Proposition 65 enforcement:Chemical labeling requirements create compliance friction for US-bound textile imports without harmonized federal standards.
Strategic Opportunities
- Eco-friendly feature variants:EU Green Deal procurement criteria penetrating retail buyer specifications open margin pools in sustainable material laminates.
- Mesh material category expansion:Breathability standard tightening creates white space for ventilation-engineered products.
- Direct-to-consumer channel development:Precision sizing tools and airline compatibility databases bypass traditional retail markup structures.
Industry Challenges
- Pattern-making technical talent gaps:Soft-sided carrier engineering requires specialized skills in heat-sealed seam bonding and die-cut foam integration.
- Multi-jurisdiction certification timelines:Simultaneous FDA Center for Veterinary Medicine, ECHA REACH, and state-level compliance creates launch delays.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dog Carrier Bags Market |
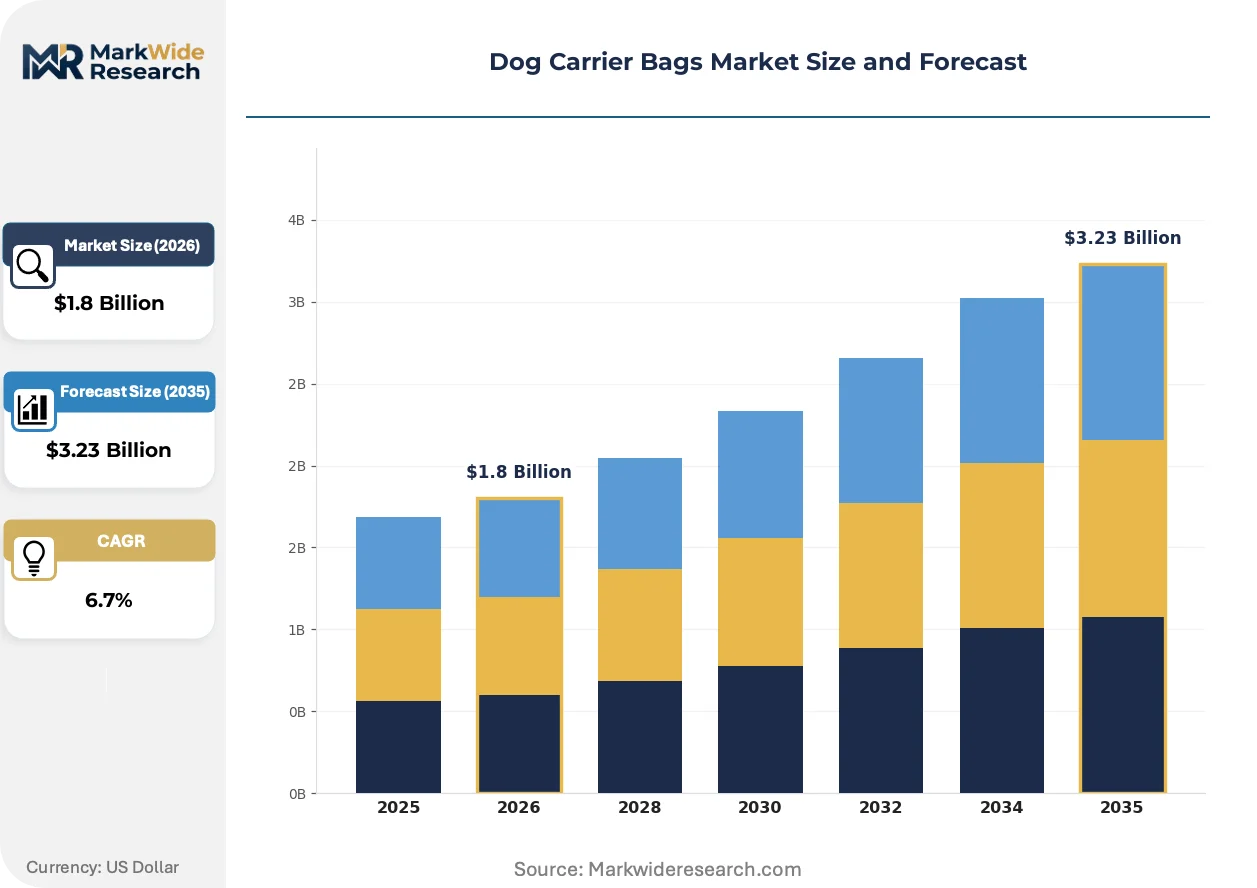
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Backpack, Sling, Rolling, Tote Material: Nylon, Canvas, Leather, Mesh Size: Small, Medium, Large, Extra Large Feature: Waterproof, Breathable, Foldable, Eco-Friendly |
| Companies Covered | Sleepypod, Petmate, Pet Gear, Texsens, U-Pet, ALEKO Products, Pawaboo, Sturdi Products, Kurgo, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dog Carrier Bags Market Evolving Landscape
Material science convergence with regulatory chemistry disclosure is reshaping how carriers are specified, tested, and sourced. Three distinct vectors are compressing traditional development timelines.
Structural foam panel technology is miniaturizing. Die-cut EVA and closed-cell foam configurations now deliver automotive-grade impact protection in sub-kilogram carrier architectures. Frequent-flying pet owners in dense urban transit corridors are adopting these reinforced designs fastest. The technology is miniaturizing safety features previously reserved for rigid crates into soft-sided formats.
ECHA REACH Annex XVII restrictions on phthalates and heavy metals in textile articles are tightening chemical disclosure requirements for European imports. Manufacturers must reformulate coating adhesives and dye fixatives to maintain market access. Backpack and soft-sided segments face the steepest reformulation costs due to surface-area-to-mass ratios.
Airline-specific dimensional databases are replacing generic size categories in purchase decisions. Buyers now cross-reference carrier measurements against cabin-by-cabin seat pitch specifications before purchase. This behavior concentrates demand in direct channels with interactive sizing tools. United States metropolitan markets with highest pet ownership density show the sharpest shift toward specification-driven selection.
Dog Carrier Bags Market Segmentation
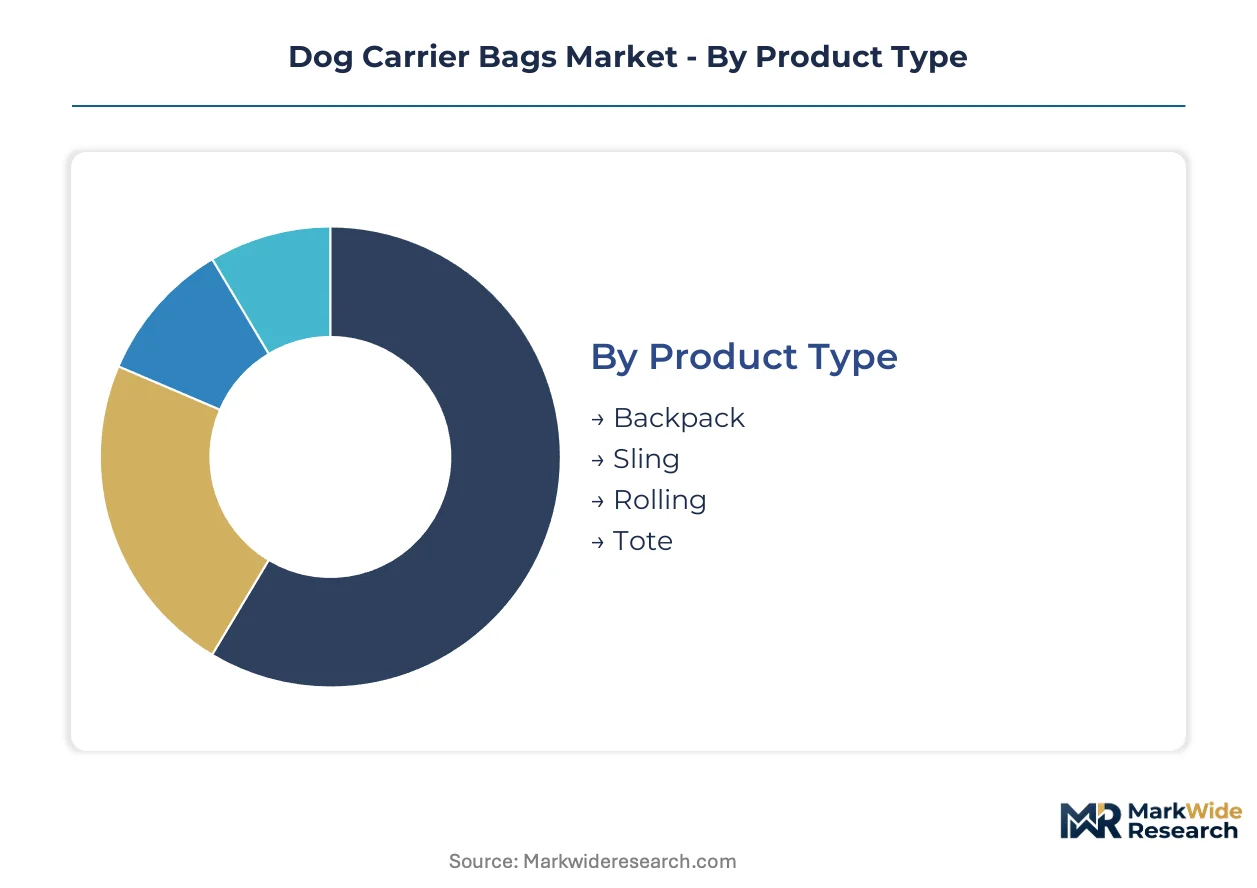
Carrier architecture and material composition determine regulatory compliance pathways, airline compatibility, and margin structures. Segmentation reveals how technical specifications map to distinct customer workflows and procurement criteria.
Product Type:
REACH textile chemical mandates from ECHA and FAA dimensional guidance reshape how structural formats enter European and US channels.
- Backpack:Dual-strap load distribution systems with ventilated back panels and sternum stabilization. Commuter corridors in New York, Los Angeles, and Chicago concentrate demand where subway and bus integration matters. Urban millennial ownership density in these metropolitan clusters drives specification around under-seat dimensional compliance.
- Sling:Single-shoulder asymmetrical designs with cross-body weight distribution and quick-access side apertures. Compact breed owners in dense Japanese and South Korean urban centers favor this format for short-distance veterinary and retail transit where minimal footprint matters.
- Rolling:Telescoping handle and wheelbase configurations with rigid bottom platforms. Airport terminals and intercity rail stations in Germany and France drive adoption among frequent-traveling owners managing larger breeds across extended distances.
- Tote:Open-top or zippered rectangular enclosures with reinforced base panels. Casual urban errands and boutique retail environments in London and Milan favor this format for toy breeds and fashion-forward positioning.
Backpack handles the majority of throughput; Sling is expanding most quickly on share among compact-breed owners in East Asian metropolitan markets.
Material:
Cost tier stratification separates commodity synthetics from certified laminates with full chemical disclosure documentation.
- Nylon:Woven polyamide 6,6 with polyurethane coating layers and denier-rated tear resistance. Baseline volume production concentrates in Vietnamese and Cambodian manufacturing hubs where petrochemical feedstock volatility compresses margin predictability for undifferentiated grades.
- Canvas:Cotton duck or hemp-blend natural fibers with waxed or acrylic weatherproofing treatments. Heritage-positioned brands and EU Green Deal procurement channels favor this material for biodegradability credentials and chemical transparency.
- Leather:Full-grain or top-grain bovine hides with vegetable tanning and reinforced stitching. Premium positioning in Milan, Paris, and Tokyo targets fashion-conscious owners where durability signaling justifies price multiples over synthetic alternatives.
- Mesh:Polyester or nylon monofilament ventilation panels with hexagonal or square aperture patterns. Breathability standard tightening from veterinary and airline regulators drives specification upgrades in warm-climate markets across Spain, Italy, and Australia.
Nylon handles the majority of throughput; Mesh is gaining share fastest as thermal comfort regulations tighten across transit authorities.
Size:
Application-driven dimensional brackets map to breed weight classes and airline under-seat measurement databases.
- Small:Under 10 pound capacity with sub-17 inch length specifications. Chihuahua, Yorkshire Terrier, and Pomeranian owners in Tokyo, Seoul, and Singapore drive volume where apartment density and airline restrictions converge.
- Medium:10-20 pound capacity with 17-19 inch length envelopes. French Bulldog, Corgi, and Dachshund ownership in New York, London, and Berlin concentrates demand for commuter-compatible formats with structural reinforcement.
- Large:20-40 pound capacity with 19-22 inch length specifications. Beagle, Cocker Spaniel, and Border Collie transport requirements favor automotive-grade safety validation and crash-tested frame architectures.
- Extra Large:Over 40 pound capacity exceeding standard airline cabin allowances. Ground transport and veterinary emergency applications in suburban and rural corridors dominate, with limited airline compatibility driving channel concentration in direct-to-consumer specialty retailers.
Medium handles the majority of throughput; Small is climbing the fastest as compact breed ownership concentrates in dense Asian metropolitan markets.
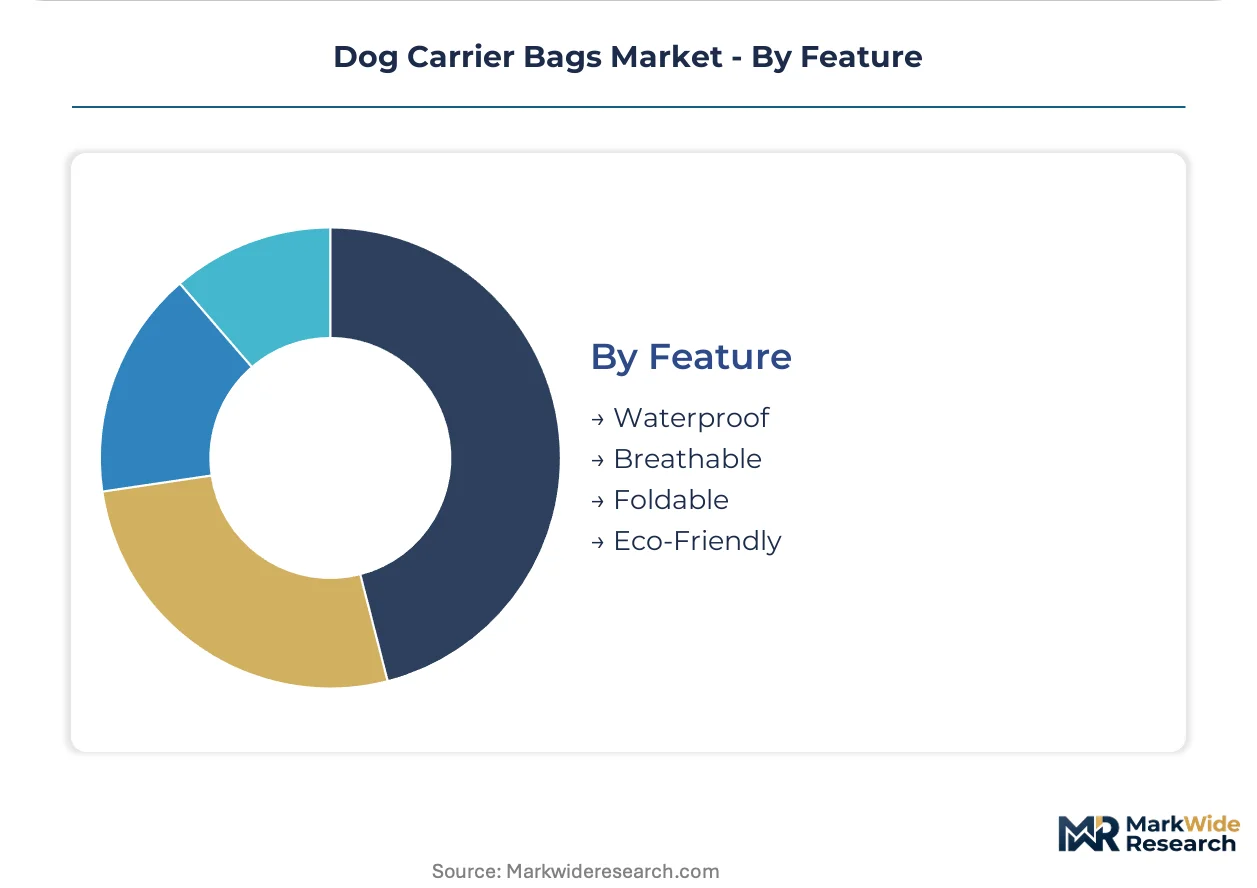
Feature:
Margin concentration shifts toward certified functional attributes with regulatory documentation and procurement specification alignment.
- Waterproof:Heat-sealed seam bonding and laminated membrane barriers with hydrostatic head ratings. Rain-intensive climates in Seattle, Manchester, and Amsterdam drive specification where moisture protection preserves interior comfort and hygiene.
- Breathable:Engineered ventilation apertures with airflow-per-square-inch metrics and thermal regulation testing. Veterinary guidance and airline cargo hold safety standards in California, Texas, and Florida favor this specification for heat-sensitive brachycephalic breeds.
- Foldable:Collapsible frame architectures with quick-release mechanisms and compressed storage volumes. Apartment-dwelling owners in Hong Kong, Singapore, and Vancouver prioritize this feature where space constraints dominate purchase criteria.
- Eco-Friendly:Recycled polyester, organic cotton, or bio-based polyurethane with cradle-to-cradle or GRS certification. EU Green Deal procurement criteria penetrating retail buyer specifications in Germany, Netherlands, and Scandinavia open premium margin pools for documented sustainable laminates.
Breathable handles the majority of throughput; Eco-Friendly shows the steepest expansion trajectory as European public sector and corporate procurement mandates tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply by geography. United States buyers prioritize airline-compliant dimensional precision for frequent cabin travel. European procurement channels emphasize chemical disclosure documentation under ECHA mandates. East Asian metropolitan corridors favor compact formats for dense transit integration.
United States
Urban millennial pet ownership concentrates in New York, Los Angeles, and Chicago metropolitan corridors. FAA dimensional guidance and individual airline under-seat policies shape product development cycles. California's Proposition 65 enforcement creates de facto national labeling standards for textile imports.
Germany
Frequent rail transit across Frankfurt, Munich, and Berlin corridors drives rolling carrier adoption for larger breeds. EU Green Deal procurement criteria penetrate retail buyer specifications for sustainable material laminates. REACH Annex XVII chemical restrictions filter supplier access to European import channels.
Japan
Compact breed ownership in Tokyo, Osaka, and Yokohama apartment districts favors sling and backpack formats with minimal footprint. METI product safety standards influence regional design specifications. Kansai manufacturing clusters specialize in precision foam panel integration for structural carriers.
United Kingdom
Rain-intensive climates in Manchester and Glasgow drive waterproof specification demand with heat-sealed seam bonding. Veterinary guidance from the Royal College of Veterinary Surgeons shapes breathability standards for brachycephalic breed transport. London retail corridors concentrate fashion-forward tote positioning for toy breeds.
South Korea
Seoul Capital Area density drives commuter-compatible backpack carrier specification for subway and bus integration. MFDS animal transport safety guidelines influence product testing protocols. Busan-Ulsan manufacturing hubs face technical pattern-making talent scarcity as design skills concentrate elsewhere.
Dog Carrier Bags Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in the dog carrier bags market. The upper tier commands premium positioning through proprietary safety validation protocols and direct channel control. Specialist players compete on format-specific engineering and regional regulatory alignment. Strategic moves concentrate on automotive-grade certification acquisition and sustainable material supply chain development.
Among North American specialists, Sleepypod exemplifies the premium safety archetype through in-house crash-testing protocols. Pet Gear occupies a position in mass-market channel control across big-box retail networks. Kurgo anchors the adventure-travel specialization with reinforced harness integration expertise.
| Leading Market Players |
|---|
| Sleepypod |
| Petmate |
| Pet Gear |
| Texsens |
| U-Pet |
| ALEKO Products |
| Pawaboo |
| Sturdi Products |
| Kurgo |
| Others |
Value Network & Pricing Analysis
Mesh material substitution for solid nylon panels is redrawing manufacturing geography toward Vietnam and Indonesia while compressing price premiums on breathable variants. This input shift simultaneously elevates chemical compliance costs for REACH certification and concentrates bargaining power with certified laminate suppliers.
Pricing Analysis
Contract structures favor annual offtake agreements between Vietnamese manufacturers and US retail buyers, with spot purchasing limited to emergency replenishment. Three-tier pricing structure across premium, standard, and economy levels separates crash-tested automotive-grade carriers from basic commuter backpacks and undifferentiated nylon totes. Pricing pressure stems from polyester and nylon feedstock volatility as petrochemical costs swing unpredictably. Mass-market big-box buyers exhibit highest price sensitivity, while frequent-flying pet owners in dense metropolitan corridors absorb premiums for dimensional precision.
Supply Chain Analysis
Vietnam, Cambodia, and Bangladesh anchor woven synthetic carrier production, with Kansai-region Japanese manufacturers specializing in precision foam panel integration. Raw material sourcing draws from Chinese petrochemical complexes for nylon 6,6 filament, Taiwanese coating adhesive suppliers, and German dye fixative specialists. Single-source vulnerability concentrates in REACH-certified laminate suppliers where ECHA disclosure documentation creates bottleneck conditions. Distribution runs through big-box pet retail networks, direct-to-consumer channels with airline compatibility databases, and European specialty retailers emphasizing Green Deal procurement criteria.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution pressure from rigid pet crate manufacturers miniaturizing automotive safety features into soft-sided formats. Defense requires securing proprietary validation protocols and tightening supply chain control over certified material inputs.
For Market Incumbents: Secure exclusive partnerships with ECHA REACH-certified laminate suppliers to lock in chemical disclosure documentation ahead of competitor procurement cycles. Consolidate pattern-making technical talent in Kansai-region engineering clusters before Southeast Asian design scarcity intensifies further. Backward integration into die-cut EVA foam panel production preserves margin on automotive-grade safety tier offerings. For New Entrants and Emerging Players: Differentiate on eco-friendly feature variants with GRS-certified recycled polyester laminates targeting EU Green Deal procurement channels in Germany, Netherlands, and Scandinavia. Penetrate the mesh material category expansion white space with veterinary-validated thermal regulation metrics for brachycephalic breed owners in California, Texas, and Florida. Launch through direct-to-consumer channels with interactive airline dimensional databases to bypass established retail markup structures. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed pet product platforms that consolidated basic nylon carrier manufacturing in Vietnamese hubs but lack REACH certification depth. Five-to-ten year viability hinges on regulatory chemistry disclosure capabilities rather than cost position alone. Monitor ECHA Annex XVII restriction expansion as the decisive inflection signal for supplier filtering intensity.| Strategic Initiative | Industry Significance |
|---|---|
| REACH Certification Acquisition | ECHA disclosure documentation unlocks European retail procurement channels and filters undifferentiated competitors. |
| Direct-to-Consumer Channel Development | Precision sizing tools and airline compatibility databases bypass traditional retail margin extraction. |
| Sustainable Material Supply Chain Development | GRS-certified recycled polyester laminates capture EU Green Deal procurement premium pools. |
| Automotive-Grade Safety Validation | In-house crash-testing protocols anchor premium positioning against rigid crate substitution threats. |
| Technical Pattern-Making Talent Consolidation | Kansai-region foam panel engineering skills concentrate as Southeast Asian design scarcity unwinds cost advantages. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with product development executives at carrier manufacturers, regulatory affairs specialists at ECHA and FDA, category buyers at big-box pet retailers, and airline cargo safety officers; and secondary validation through customs trade records, ECHA REACH registration databases, SEC 10-K filings of listed pet product companies, and airline under-seat dimensional policy repositories. Bottom-up volume estimates from segmented production capacity triangulated against top-down demand modeling from pet ownership density and travel frequency surveys.
Across the analysis window, forecasts applied a multi-dimensional segmentation framework spanning carrier architecture, material composition, size capacity brackets, and functional feature certification. CAGRs derived from regression analysis of historical volume trajectories against petrochemical input cost indices, regulatory enforcement intensity metrics, and airline policy evolution patterns. Industry-specific inputs incorporated FAA dimensional guidance revision schedules and EU Green Deal procurement penetration rates.
The analysis sits within stated boundaries; outcomes outside sustained urban millennial pet ownership growth, stable REACH enforcement trajectories, or continued airline cabin pet accommodation policies would require recalibration. Forecasts reflect documented assumptions about material science convergence timelines and pattern-making talent migration patterns. Recalibration cycles align with material shifts in ECHA chemical restriction expansions and airline under-seat measurement standardization initiatives.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pet Care Products
Dog Sunglasses Market
Pet Care Products
Cat Accessories Market
Pet Care Products
Saudi Arabia Dog Food Market
Pet Care Products
Dog Pen Market
Pet Care Products
Smart Pet Supply Market
Pet Care Products
Pet Grooming Products Market
Pet Care Products
Dog Bed Covers Market
Pet Care Products
Bird Cages and Accessories Market
Pet Care Products
GCC Cat Food Market
Pet Care Products
North America Cat Food Market
Pet Care Products
Pet GPS Tracker Market
Pet Care Products
North America Functional Pet Treat Market
Pet Care Products
Smart Pet Kennel Market
Pet Care Products
Small Dog Harness Market
Pet Care Products
Outdoor Pet Backpack Market
Pet Care Products
Natural Cat Litter Products Market