
 Raw Meat Pet Food Market | 2026-2036
Raw Meat Pet Food Market Size, Share, and Industry Trends Forecast 2026-2036
Raw Meat Pet Food Market Insights
North American co-manufacturing capacity for human-grade raw pet food is realigning toward USDA-inspected facilities with HACCP certification. Stella & Chewy's leverages its vertically integrated freeze-drying infrastructure to anchor premium shelf positioning across specialty channels. Primal Pet Foods competes through direct farm partnerships that sustain traceability claims from source to bowl. Instinct Pet Food dominates the mass-market raw frozen segment through national retail distribution controls.
Raw meat pet food comprises uncooked muscle tissue, organ meats, and edible bone ground or formed into diets with minimal thermal processing, typically maintained at temperatures below 40°F through cold chain distribution to preserve enzymatic activity and amino acid integrity. The category serves commercial purposes by addressing consumer demand for biologically appropriate feeding models that mirror ancestral canine and feline nutritional patterns. Raw frozen formulations occupy the largest volume position due to established cold chain logistics and lower per-unit processing costs, while raw freeze-dried products command premium margin pools through shelf stability and travel convenience. Fresh raw delivery subscriptions represent the fastest-growing structural segment, though wholesale distribution through veterinary clinics retains the highest customer lifetime value channel profile.
FDA Center for Veterinary Medicine oversight of Salmonella contamination in raw pet food, combined with AAFCO model bill compliance requirements for nutritional adequacy statements, elevates barrier costs for new entrants and forces ongoing pathogen-testing investments across production networks. USDA FSIS jurisdiction over human-grade facilities adds a secondary compliance layer that shapes facility capital allocation and geographic siting decisions. Stakeholders must monitor evolving state-level raw feeding bans and veterinary board position statements that could restrict channel access or reshape consumer messaging frameworks.
Market Dynamics
Human-grade cold chain infrastructure investment is compressing spoilage rates and expanding retail distribution radius for raw frozen formulations. This capital reallocation is reshaping competitive entry barriers and margin structures across production tiers.
Growth Catalysts
- FDA Center for Veterinary Medicine pathogen testing mandates:Regulatory enforcement elevates quality signaling for compliant producers and accelerates consumer trust formation in premium segments.
- Urban millennial household pet humanization:Demographic concentration in dense metropolitan clusters sustains subscription-based fresh delivery model economics and repeat purchase velocity.
- Freeze-drying technology adoption:Shelf-stable processing preserves enzymatic bioavailability while eliminating frozen distribution cost burdens for travel and emergency feeding applications.
Market Restraints
- USDA FSIS facility certification requirements:Human-grade processing standards impose seven-figure capital barriers that constrain small-producer scaling and geographic expansion.
- Protein input cost volatility:Beef, poultry, and organ meat commodity price swings compress margin predictability for fixed-price subscription contracts.
- Veterinary board position statement friction:State-level professional association skepticism toward raw feeding limits clinic channel endorsement and referral network access.
Strategic Opportunities
- Veterinary clinic channel underpenetration:Therapeutic diet positioning and practitioner education investments unlock high customer lifetime value segments resistant to price elasticity.
- AAFCO nutritional adequacy statement optimization:Complete-and-balanced formulation claims enable mass retail placement beyond supplemental feeding restrictions.
- Direct-to-consumer subscription technology convergence:AI-driven portion customization and predictive logistics reduce churn and elevate per-subscriber revenue capture.
Industry Challenges
- HACCP plan development and validation:Hazard analysis critical control point documentation demands specialized food safety expertise scarce in traditional pet food manufacturing.
- Cold chain integrity maintenance:Last-mile temperature monitoring and liability allocation across third-party logistics networks create operational complexity and insurance cost escalation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Raw Meat Pet Food Market |
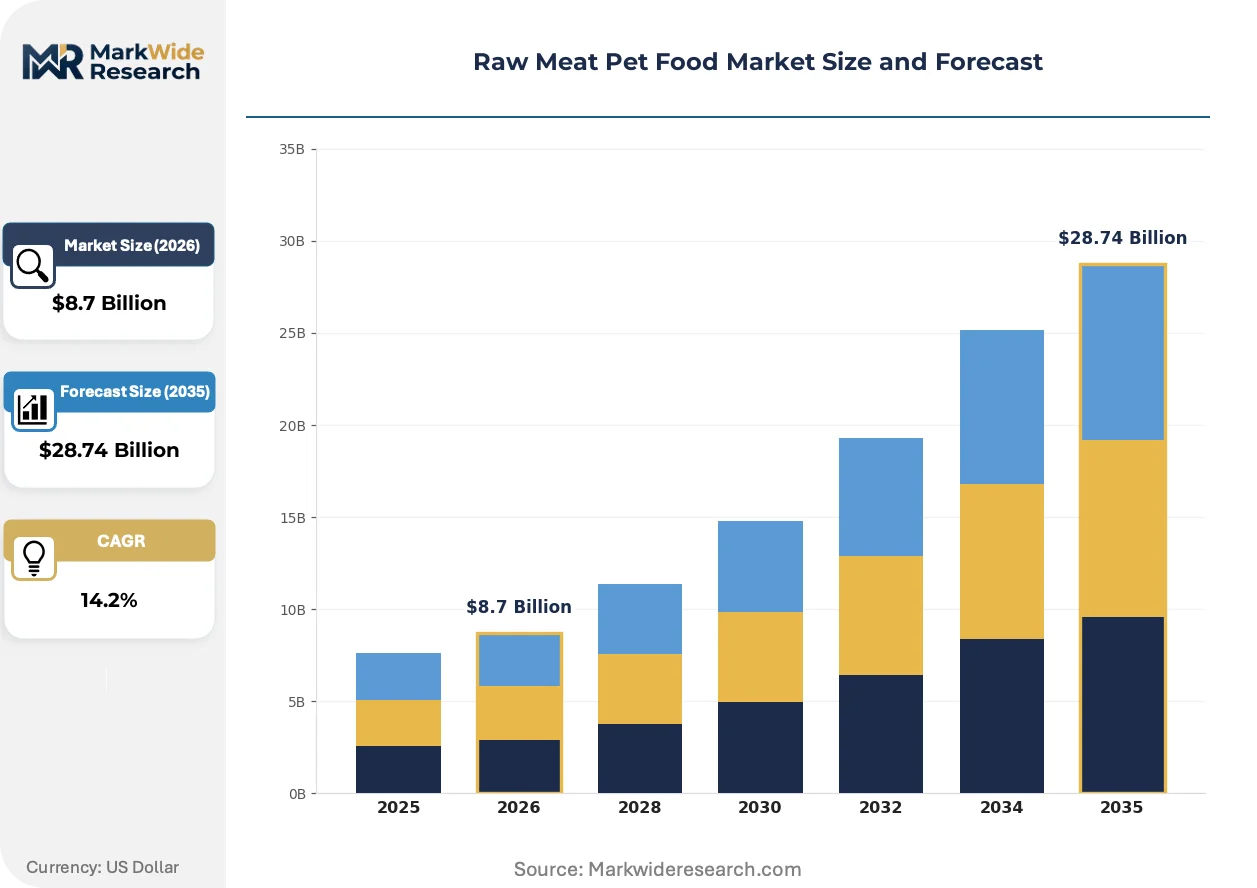
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $28.74 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Raw Freeze-Dried, Raw Frozen, Raw Dehydrated, Fresh Raw End User: Pet Owners, Pet Stores, Veterinary Clinics, Online Retailers Distribution Channel: Supermarkets, Specialty Stores, E-Commerce, Wholesale Packaging Type: Bulk Containers, Vacuum-Sealed Bags, Cans, Pouches |
| Companies Covered | Stella & Chewy's, Primal Pet Foods, Instinct Pet Food, Vital Essentials, Steve's Real Food, Northwest Naturals, Bravo Pet Foods, Darwin's Natural Pet Products, Answers Pet Food, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Raw Meat Pet Food Market Trends and Innovations
Processing technology convergence with human food safety standards is elevating product positioning while compressing traditional quality-tier boundaries. These developments are restructuring capital deployment priorities and channel access patterns.
High-pressure processing equipment is modularizing raw pet food safety validation workflows. Mid-tier co-manufacturers are adopting HPP units to achieve log reduction guarantees without thermal degradation of amino acid profiles. This capital-light pathogen control approach is modularizing entry barriers that previously required full USDA facility certification.
AAFCO model bill updates on raw pet food labeling are forcing nutritional adequacy statement reformulation across frozen and freeze-dried portfolios. Manufacturers must restructure packaging claims to distinguish between complete diets and supplemental feeding products. The specialty retail channel faces the most acute compliance timeline pressure as inventory turnover slows for label redesign cycles.
Subscription-based fresh raw delivery is displacing conventional retail replenishment patterns among urban pet owners. Direct-to-consumer platforms capture purchase data that enables predictive portion sizing and automated reorder triggers. This behavioral shift concentrates most visibly in United States metropolitan corridors where cold chain logistics density supports same-day or next-day fulfillment guarantees.
Raw Meat Pet Food Market Segmentation
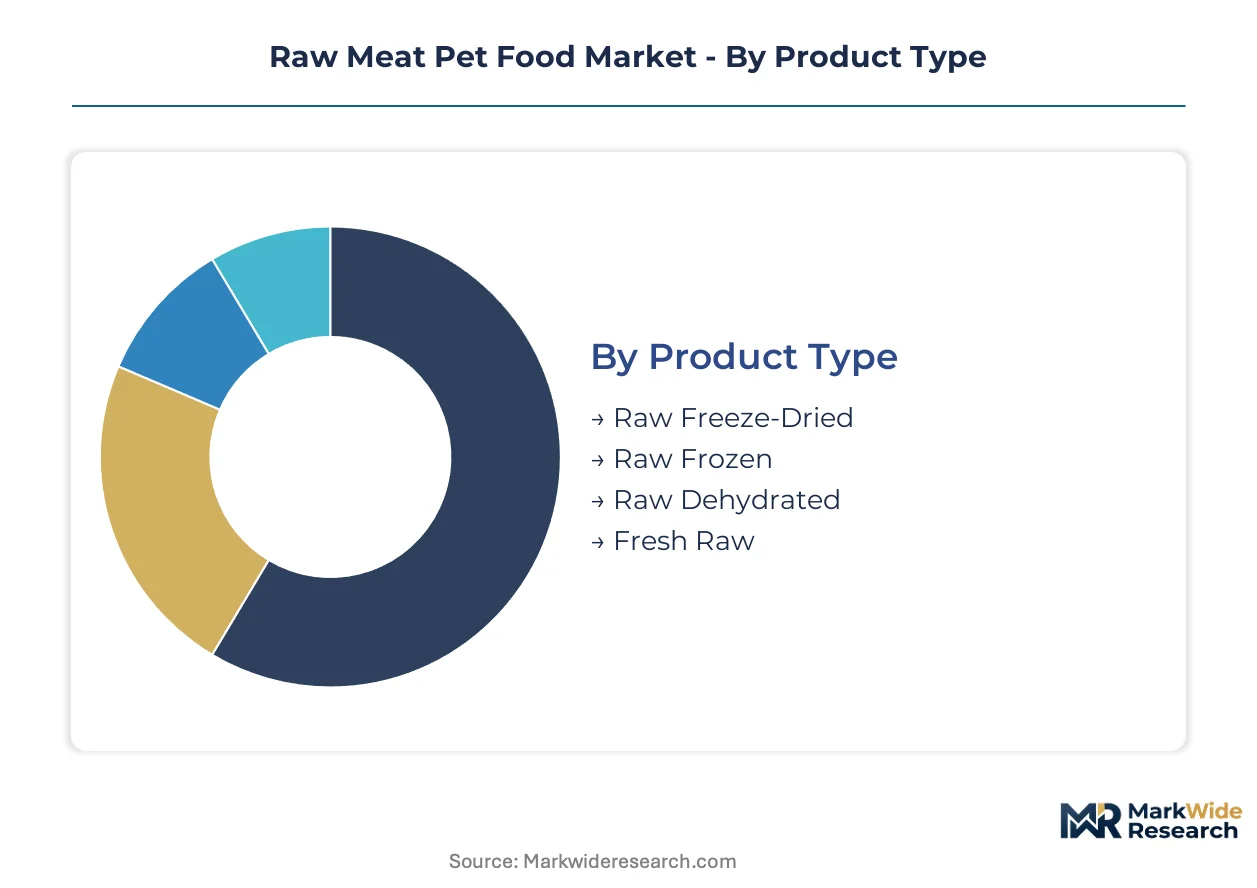
Raw meat pet food segmentation reveals how regulatory compliance burdens and cold chain economics concentrate margin capture across distinct product formats. Understanding these divides exposes where capital requirements filter competitive entry and where channel control determines pricing power.
Product Type:
FDA Center for Veterinary Medicine pathogen testing mandates apply differentially across thermal processing profiles, with frozen formulations facing the strictest cold chain documentation while freeze-dried products navigate shelf stability claims under AAFCO labeling rules.
- Raw Frozen:Uncooked muscle tissue, organ meats, and edible bone maintained below 40°F through HACCP-monitored distribution networks. United States metropolitan corridors concentrate demand for this format, driven by direct-to-consumer subscription economics and established last-mile cold chain density.
- Raw Freeze-Dried:Low-temperature dehydration preserves enzymatic activity while eliminating frozen logistics burdens. Urban millennial pet owners in dense coastal clusters favor this segment for travel convenience and pantry storage compatibility, accepting premium positioning for shelf-stable biologically appropriate nutrition.
- Raw Dehydrated:Moderate thermal processing reduces moisture content without full freeze-drying infrastructure investment. Small regional co-manufacturers dominate supply.
- Fresh Raw:Refrigerated distribution of minimally processed diets with shortest shelf windows. Same-day delivery platforms in major US cities anchor growth.
Raw Frozen sits at the top of the volume ranking, with Fresh Raw climbing the fastest.
End User:
Customer lifetime value diverges sharply across these segments, with institutional channels demanding therapeutic positioning and documentation while direct consumers prioritize convenience and ancestral feeding narratives.
- Pet Owners:Individual households purchasing for companion animal nutrition, segmented by urban density and subscription willingness. Subscription retention rates in United States metropolitan areas sustain the highest per-customer revenue capture.
- Veterinary Clinics:Professional channel requiring therapeutic diet positioning and practitioner education support. This segment commands premium pricing resilience due to clinical endorsement authority and patient-specific formulation requirements.
- Pet Stores:Specialty retail intermediaries curating premium assortment for educated consumers. Staff training investments differentiate performance.
- Online Retailers:Third-party marketplace platforms aggregating brand discovery and fulfillment. Logistics integration determines vendor selection.
Veterinary Clinics capture the highest margin per transaction, with Online Retailers expanding most quickly.
Distribution Channel:
Cold chain integrity requirements and inventory turnover velocity shape which channels can economically carry which product formats, compressing traditional retail participation in frozen segments.
- E-Commerce:Direct-to-consumer platforms with predictive logistics and automated replenishment. AI-driven portion customization in US subscription services reduces churn and elevates per-subscriber value.
- Specialty Stores:Curated retail environments with educated staff and premium positioning. Independent pet retailers in affluent suburbs concentrate assortment authority.
- Supermarkets:Mass retail placement requiring complete-and-balanced AAFCO claims and national distribution scale. Frozen case space competition limits raw category presence.
- Wholesale:Business-to-business supply to independent retailers and institutional buyers. Consolidator networks in regional cold chain hubs determine geographic reach.
E-Commerce leads channel growth velocity, with Specialty Stores retaining the strongest pricing power.
Packaging Type:
Material specifications and barrier properties must align with pathogen control validation and consumer convenience expectations across temperature-sensitive supply chains.
- Vacuum-Sealed Bags:Oxygen barrier films extending refrigerated shelf life and preventing freezer burn. Multi-layer coextrusion technology from human food packaging suppliers dominates supply.
- Pouches:Flexible formats for single-serve portions and travel applications. Stand-up pouch adoption in freeze-dried segments accelerates.
- Bulk Containers:Foodservice-scale packaging for multi-pet households and institutional buyers. Portioning hygiene requirements constrain adoption.
- Cans:Metal packaging for high-pressure processed raw diets achieving commercial sterility. Thermal processing trade-offs limit enzymatic preservation claims.
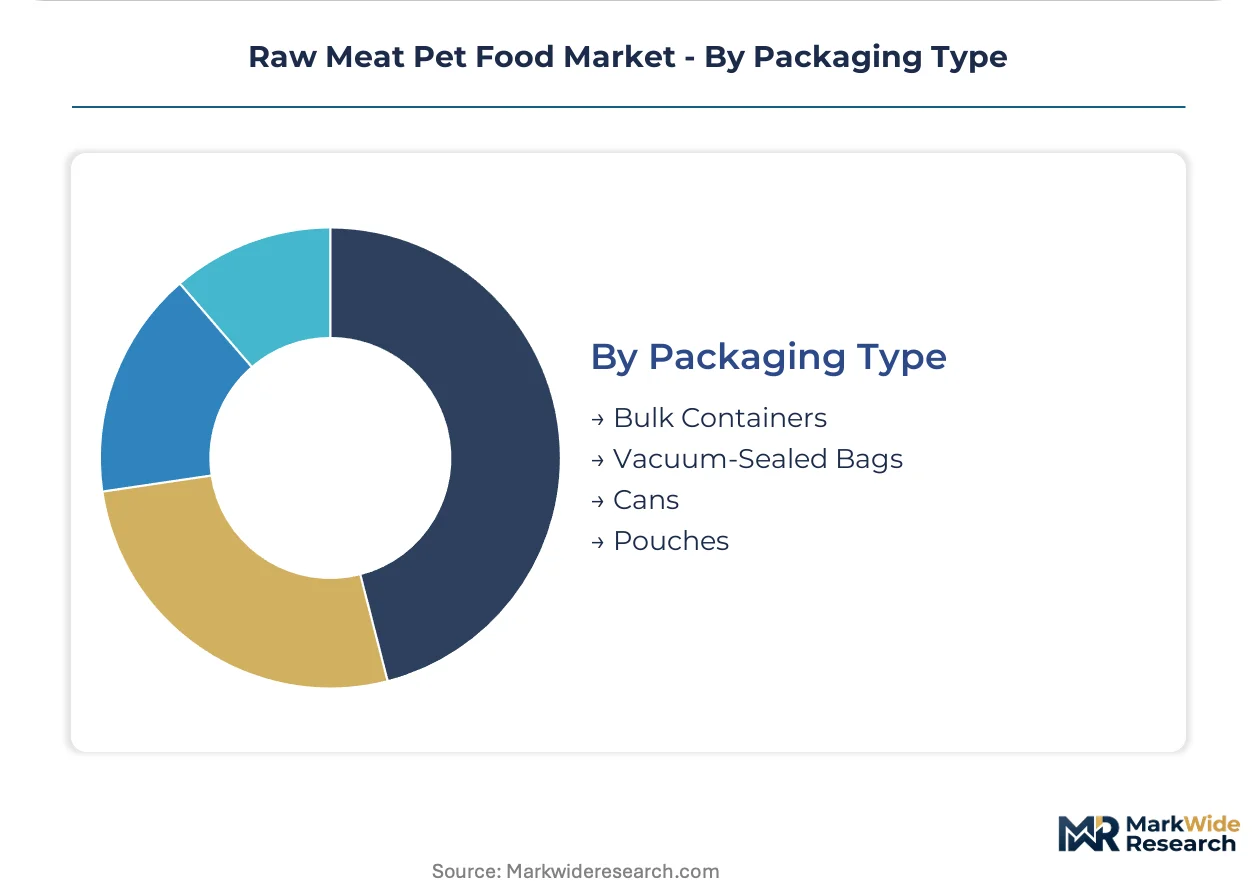
Vacuum-Sealed Bags hold the largest installed base, with Pouches gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States commands substantially higher per-capita raw pet food expenditure than Germany, though both markets exhibit divergent regulatory pathways shaping commercial access and formulation standards.
United States
Urban millennial households in metropolitan corridors sustain direct-to-consumer subscription velocity for fresh raw delivery. FDA Center for Veterinary Medicine pathogen testing mandates elevate compliance costs while simultaneously quality-signaling premium producers. Cold chain logistics density in New York, Los Angeles, and Chicago corridors enables same-day fulfillment guarantees that anchor customer retention economics.
Germany
EFSA oversight of pet food safety intersects with national veterinary association skepticism toward raw feeding protocols. The country's national pharmaceutical regulator maintains strict documentation requirements for therapeutic diet positioning. Industrial concentration in Bavaria and North Rhine-Westphalia supports co-manufacturing infrastructure serving private-label and branded portfolios across Central European distribution networks.
United Kingdom
Specialty retail channel expansion in Greater London and Southeast England clusters drives premium freeze-dried adoption among urban pet owners. The country's national veterinary regulator defers to FSA guidelines on raw pet food handling and consumer safety communication. Manchester and Birmingham logistics hubs facilitate cold chain radius extension for frozen formulations into secondary cities.
France
Île-de-France pet owner concentration supports subscription service experimentation with AI-driven portion customization. ANSM oversight of veterinary therapeutic products shapes clinic channel access for condition-specific raw diet positioning. Lyon and Marseille metropolitan areas anchor regional cold chain distribution nodes serving Rhône-Alpes and Provence-Alpes-Côte d'Azur demand clusters.
Australia
Biologically appropriate feeding narratives resonate strongly with companion animal owners in Sydney and Melbourne metropolitan zones. The country's national veterinary pharmaceutical regulator maintains position statement neutrality that preserves clinic channel access for educated practitioners. Brisbane and Perth cold chain infrastructure investments expand retail distribution radius for frozen formulations beyond coastal population centers.
Raw Meat Pet Food Market Competitive Landscape
United States producers anchor the premium freeze-dried and fresh subscription tiers; European specialists hold position in regulatory-compliant frozen formulations and private-label supply. Market structure exhibits moderate consolidation around vertically integrated mid-cap manufacturers with captive freeze-drying or HPP infrastructure, while regional co-manufacturers fragment across USDA-inspected and state-inspected facility tiers. Three archetypes dominate: human-grade facility operators with backward integration into protein sourcing, technology-forward direct-to-consumer platforms with predictive logistics, and veterinary-channel specialists with therapeutic positioning. Competitive moves concentrate on cold chain infrastructure expansion and AAFCO complete-and-balanced formulation certification acquisition.
Within the premium-tier vector, Stella & Chewy's occupies a position exemplifying vertically integrated freeze-drying infrastructure, while Primal Pet Foods represents archetypal direct farm partnership models sustaining traceability claims. Instinct Pet Food anchors mass-market raw frozen positioning through national retail distribution scale. These three entities collectively illustrate how facility certification tier and channel control determine margin capture across the category.
| Leading Market Players |
|---|
| Stella & Chewy's |
| Primal Pet Foods |
| Instinct Pet Food |
| Vital Essentials |
| Steve's Real Food |
| Northwest Naturals |
| Bravo Pet Foods |
| Darwin's Natural Pet Products |
| Answers Pet Food |
| Others |
Pricing and Supply Chain Analysis
Backward integration into USDA-inspected protein sourcing anchors both supply security and pricing power for human-grade raw pet food producers, compressing margin volatility for operators with captive farm partnerships while elevating entry barriers for outsourced competitors.
Pricing Analysis
Capacity additions in the United States are reshaping price floors for raw frozen formulations as HACCP-certified co-manufacturing expands. Three-tier pricing structure across premium freeze-dried, standard frozen, and economy dehydrated levels reflects certification grade and cold chain investment depth. Cost compression in the mass-market frozen tier is intensifying because protein input volatility squeezes fixed-price subscription economics. Veterinary clinics exhibit the least price sensitivity due to therapeutic positioning authority, while mass retail consumers demonstrate highest elasticity.
Supply Chain Analysis
Dual-sourcing requirements for human-grade beef and poultry inputs mandate multi-supplier qualification across United States, Australia, and New Zealand protein markets. Production draws from USDA-inspected facilities, EFSA-compliant European plants, and Australian export-certified processors. Single-source vulnerability concentrates in freeze-drying equipment supply, where European and North American OEMs dominate. Distribution runs through cold chain consolidator networks with last-mile temperature monitoring.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
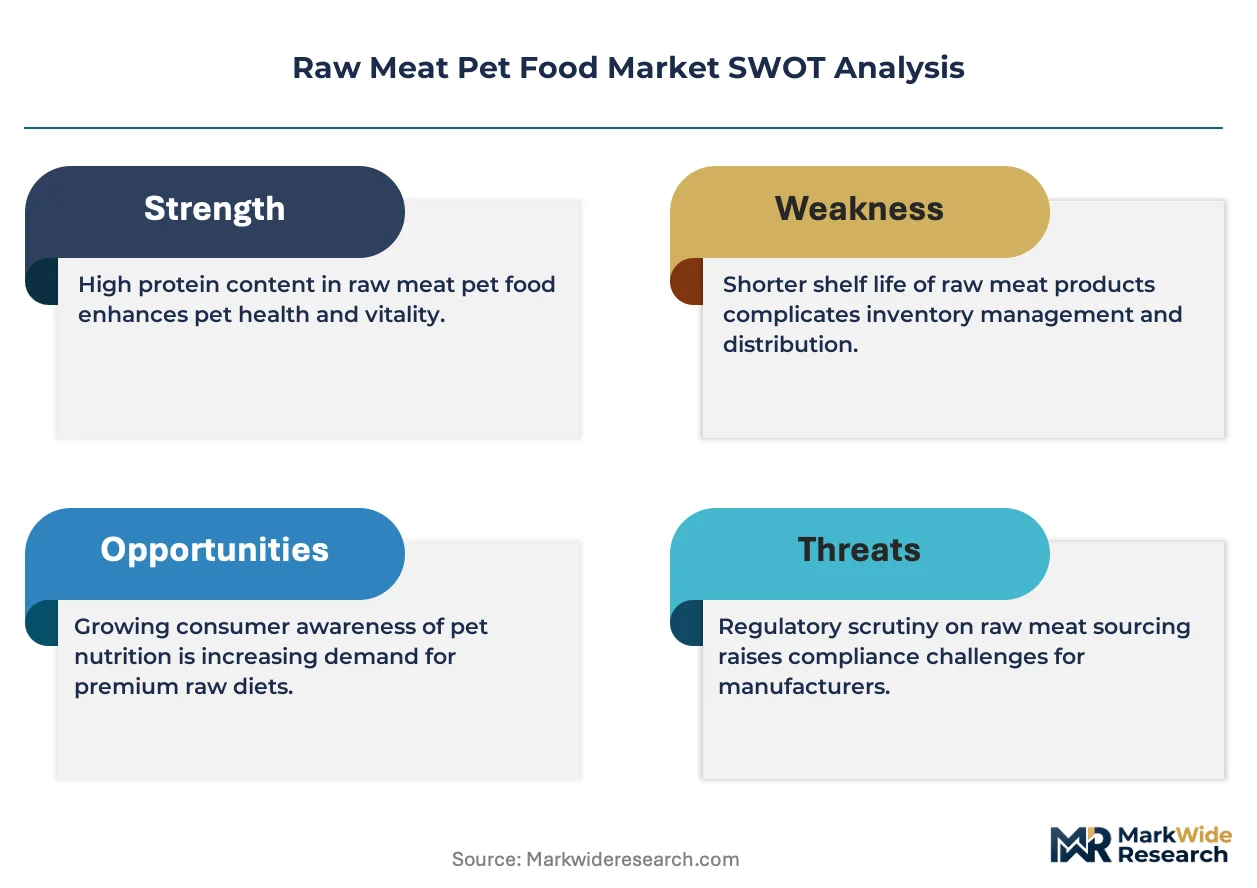
This market operates as a regulatory compounder where FDA pathogen testing mandates and AAFCO nutritional adequacy requirements continuously elevate quality signaling and premium capture.
For Market Incumbents: Anchor defensibility through HPP equipment modularization that achieves log reduction without full USDA facility certification, countering emerging mid-tier co-manufacturers. Deepen captive protein sourcing in the United States heartland to buffer commodity volatility threatening subscription margin structures. Prioritize AAFCO complete-and-balanced claim acquisition to unlock mass retail placement beyond supplemental feeding restrictions. For New Entrants and Emerging Players: Enter via veterinary clinic channel white space in secondary United States metropolitan corridors, where therapeutic diet positioning commands premium pricing resilience with minimal incumbent saturation. Target fresh raw delivery subscriptions in underserved inland cities where cold chain density gaps create fulfillment arbitrage. Deploy AI-driven portion customization as primary go-to-market differentiation against legacy subscription platforms. For Investors and Strategic Acquirers: Roll-up economics work for regional co-manufacturers with USDA-inspected facilities because human-grade certification scarcity creates acquisition currency for national platform assembly. Long-term viability hinges on operators with backward integration into protein sourcing and HACCP validation capabilities. Watch state veterinary board position statement trajectories as inflection indicators for clinic channel access expansion or constriction.| Strategic Initiative | Industry Significance |
|---|---|
| AAFCO Complete-and-Balanced Certification | Unlocks mass retail placement beyond supplemental feeding restrictions in United States supermarkets. |
| HPP Equipment Modularization | Enables mid-tier producers to achieve pathogen log reduction without full USDA facility capital burden. |
| Veterinary Clinic Channel Expansion | Captures highest customer lifetime value segments through therapeutic diet endorsement authority. |
| Direct Farm Partnership Development | Sustains traceability claims from source to bowl while buffering protein commodity price volatility. |
| AI-Driven Subscription Customization | Reduces churn through predictive portion sizing and automated replenishment triggers in urban corridors. |
Research Methodology
Direct dialogue with raw pet food manufacturing executives, veterinary nutrition specialists, cold chain logistics operators, and specialty retail category buyers grounded qualitative findings. Secondary validation drew from FDA Center for Veterinary Medicine enforcement records, AAFCO model bill documentation, USDA FSIS facility inspection databases, and customs trade data on protein ingredient flows. Bottom-up production capacity modeling triangulated against top-down expenditure estimates from subscription platform disclosures and retail scanner data.
Segment-level value outputs across the analysis window reflect product format, distribution channel, and end-user stratification combined with regional cold chain infrastructure maturity indices. CAGRs were derived from regression analysis against protein commodity price series, urban millennial household formation rates, and regulatory enforcement intensity proxies. Forecast inputs incorporated freeze-drying technology adoption curves and veterinary clinic channel penetration thresholds.
Inputs from FDA enforcement databases and AAFCO proceedings were available through the study window; gaps in real-time subscription churn metrics introduce uncertainty bands around direct-to-consumer growth trajectories. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pet Care Products
Smart Pet Camera Market
Pet Care Products
Japan Dog Food Market
Pet Care Products
GCC Dog Food Market
Pet Care Products
Dog Pillow Market
Pet Care Products
Paw Plunger Market
Pet Care Products
North America Cat Food Market
Pet Care Products
Dog Coats for Winter Market
Pet Care Products
DTC Pet Food Market
Pet Care Products
Poland Pet Food Market
Pet Care Products
Interactive Dog Toys Market
Pet Care Products
Italy Pet Food Market
Pet Care Products
GCC Cat Food Market
Pet Care Products
Aquarium Market
Pet Care Products
North America Functional Pet Treat Market
Pet Care Products
Dog Collars Market
Pet Care Products
Dog Supplement Market