
 Asia-Pacific Pet Clothing Market | 2026-2036
Asia-Pacific Pet Clothing Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Pet Clothing Market Insights
GB 18401 textile safety compliance is reorganizing competitive access across the Asia-Pacific Pet Clothing Market. Qingdao Weichong Pet Products leverages coastal manufacturing infrastructure to dominate export-oriented production. Zephyr Inc. (iDog & iCat) anchors premium positioning through specialized seasonal collections. Hangzhou Huayuan Pet Products differentiates via integrated design-to-retail capabilities serving domestic Chinese e-commerce channels.
Pet clothing encompasses functional and decorative garments engineered from woven or knitted textiles with specifications including GSM weight, seam strength, and skin-contact safety ratings for companion animals. Primary commercial purpose centers on thermoregulation, allergen reduction, and aesthetic expression for domestic pets. Cotton-based T-shirts and sweaters capture stable volume pools across temperate climates, while nylon rainwear and polyester fleece winter lines command margin premiums in seasonal markets. Costume segments concentrate demand spikes around cultural festivals, creating inventory velocity challenges for manufacturers.
China's SAMR enforces GB textile standards that restrict formaldehyde and azo dye content in pet-contact fabrics, while Japan's METI coordinates JIS quality benchmarks shaping import eligibility. India's BIS certification pathway for textile products creates incremental compliance costs for cross-border suppliers. Stakeholders must monitor evolving chemical safety thresholds and traceability requirements as regional regulators tighten consumer protection frameworks for pet products.
Market Dynamics
Pet humanization in Chinese megacities is compressing product lifecycles and forcing manufacturers to accelerate seasonal collection turnover while maintaining GB 18401 textile safety compliance.
Growth Catalysts
- Urban Millennial Demographics:Shanghai and Beijing pet owners now view companion animal apparel as essential lifestyle accessories, expanding addressable demand pools beyond functional necessity into discretionary fashion spend.
- GB 18401 Textile Safety Standards:China's SAMR enforcement of formaldehyde and azo dye restrictions is filtering out low-quality imports and creating protected market space for certified domestic producers.
- Seasonal Climate Variability:Monsoon-driven rainwear demand across Southeast Asian metropolitan zones and winter fleece requirements in northern China generate predictable revenue spikes that stabilize manufacturer capacity planning.
Market Restraints
- Cotton Price Volatility:Raw cotton futures traded on the Zhengzhou Commodity Exchange subject garment margins to agricultural commodity swings that synthetic-focused competitors avoid.
- Coastal Manufacturing Concentration:Qingdao and Ningbo production clusters create geographic vulnerability to port congestion and typhoon disruption for export-dependent suppliers.
- India's BIS Certification Pathway:Cross-border textile suppliers face incremental compliance timelines and testing costs that delay market entry for seasonal product launches.
Strategic Opportunities
- Vietnam's Underpenetrated Urban Markets:Ho Chi Minh City and Hanoi exhibit nascent pet humanization trends comparable to Shanghai circa 2018, offering first-mover positioning for design-forward entrants.
- Direct-to-Consumer E-Commerce Integration:Tmall, JD.com, and Douyin storefronts enable manufacturers to bypass tiered distributor margins and capture real-time demand signals for rapid style iteration.
- Japan's JIS Quality Premium Channel:METI-coordinated certification benchmarks create defensible pricing tiers for suppliers willing to absorb higher material and testing costs for import eligibility.
Industry Challenges
- Textile Chemist Talent Scarcity:Formulation expertise for skin-safe pet-contact dyes remains concentrated in legacy human apparel hubs, forcing pet-specialist manufacturers to compete for limited technical personnel.
- Seasonal Inventory Velocity Risk:Costume demand spikes around Lunar New Year and Golden Week create working capital intensity and obsolescence exposure for misforecasted styles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Pet Clothing Market |
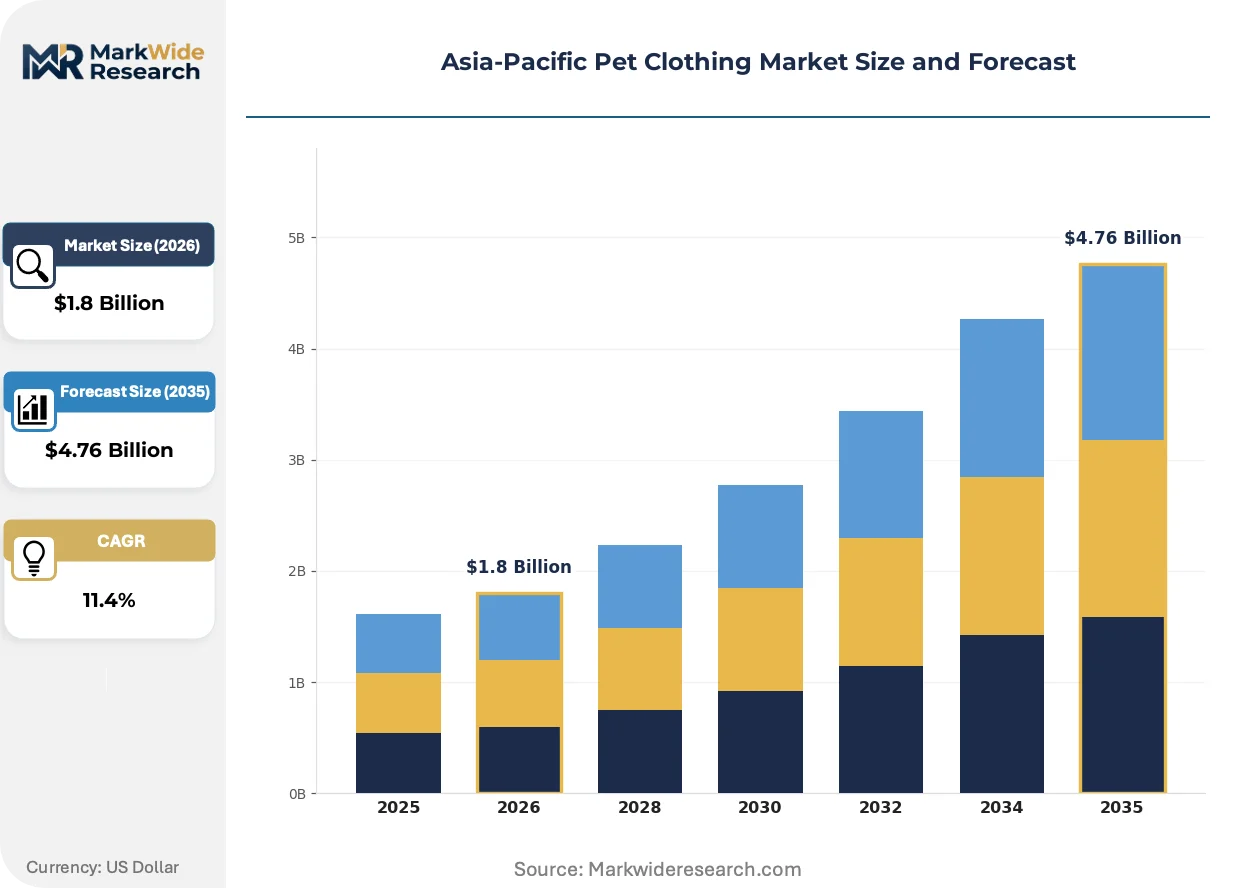
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: T-Shirts, Coats, Sweaters, Costumes Material: Cotton, Polyester, Nylon, Fleece End User: Pet Owners, Retail Stores, Online Shoppers, Veterinarians Season: Summer, Winter, Rainy, Festive |
| Companies Covered | Qingdao Weichong Pet Products, YiWu OuYe Accessories, Dongguan Hanyang Pet Products, Bestone Inc., Ruian Weihui Clothes, Zephyr Inc. (iDog & iCat), Hangzhou Huayuan Pet Products, OKEYPETS, Vixen Aim, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Pet Clothing Market Trends and Innovations
Material science breakthroughs and regulatory tightening are restructuring competitive advantage around chemical safety verification and thermal performance engineering rather than pure aesthetic differentiation.
Biodegradable PLA fiber blends engineered from corn starch derivatives are supplanting conventional polyester fleece in premium winter lines. Japanese specialty mills in Osaka prefecture pioneered commercial-scale production. Seoul-based pet boutiques now specify PLA content thresholds in procurement contracts, compressing margins for petroleum-based competitors unable to certify compostability claims.
Japan's METI revised JIS L 1902 antimicrobial testing protocols for pet-contact textiles in 2024. The updated standard mandates quantitative bacterial reduction rates for products marketed with hygiene claims. Osaka and Tokyo distributors now require third-party JIS certification documentation before listing seasonal collections, forcing Chinese exporters to retest legacy fabric stocks.
Subscription-based wardrobe rental services for companion animals are disrupting traditional retail channels in Shanghai and Shenzhen. Pet owners rotate seasonal sizes through platform-managed logistics rather than accumulating outgrown garments. This model concentrates demand among urban millennials in tier-one Chinese cities while compressing unit economics for manufacturers dependent on full-price sell-through.
Asia-Pacific Pet Clothing Market Segmentation
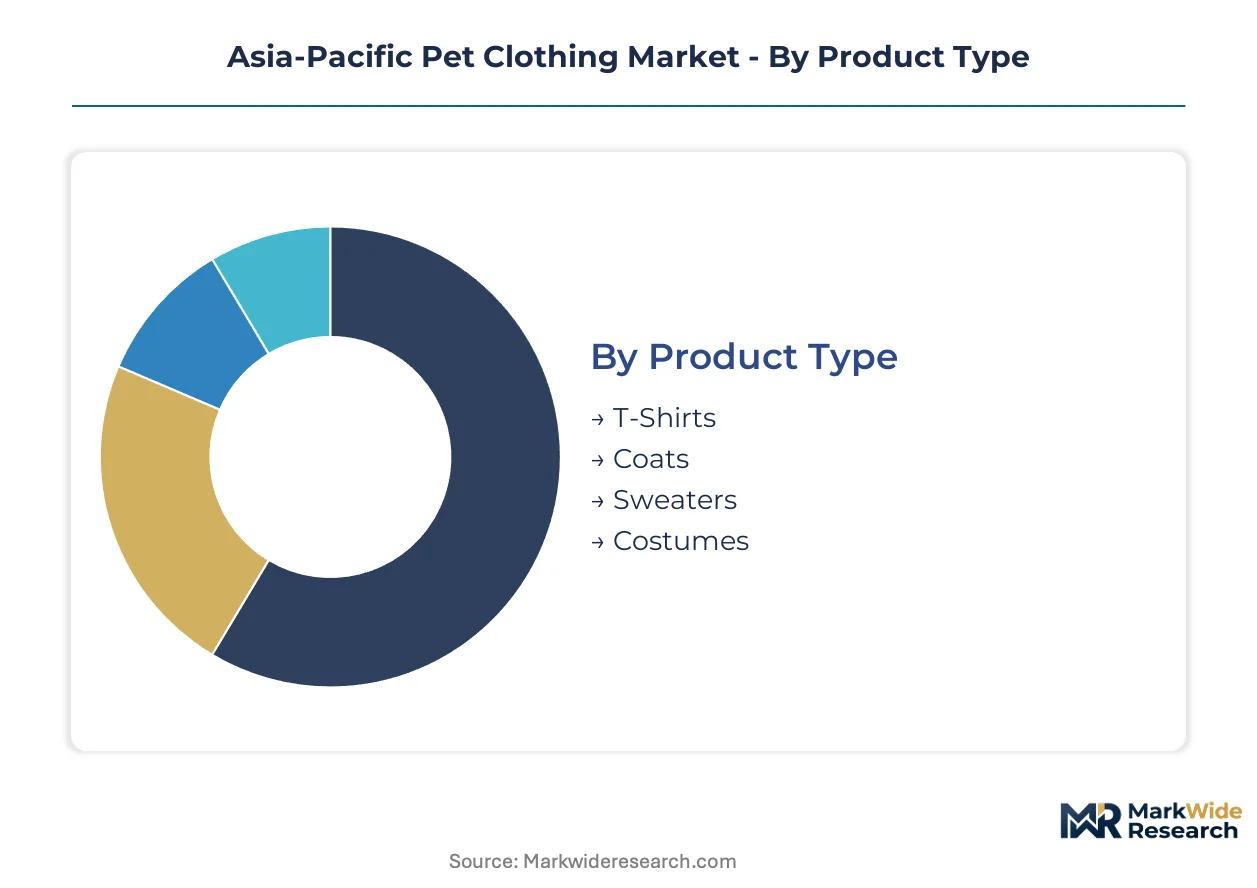
Segmentation in the Asia-Pacific Pet Clothing Market reveals how GB 18401 compliance costs and seasonal inventory velocity concentrate margin pressure across distinct product tiers. Material specifications and end-user channel dynamics determine which segments absorb regulatory testing burdens versus which capture pricing power.
Product Type:
Substitution pressure from human apparel cast-offs and DIY alternatives threatens low-complexity segments most severely, forcing branded manufacturers toward technical differentiation.
- T-Shirts:Cotton-jersey constructions at 180-220 GSM dominate baseline volume with minimal seam complexity. Shanghai pet owners treat these as disposable fashion items, compressing margins for undifferentiated suppliers while GB 18401 dye certification adds fixed cost per SKU.
- Coats:Multi-layer assemblies with waterproof membranes and adjustable closures command technical premiums. Beijing winters drive demand for insulated shells with reflective safety trim, creating protected positioning for manufacturers with in-house pattern engineering.
- Sweaters:Knitted acrylic and wool-blend constructions serve temperate climates across southern China and Southeast Asia. Hand-finish details and cable-knit patterns support modest premiums in tier-one city boutiques.
- Costumes:Novelty designs for Lunar New Year and Golden Week concentrate demand spikes with acute obsolescence risk. Inventory velocity challenges force working capital intensity on smaller manufacturers lacking demand forecasting partnerships with Tmall or JD.com storefronts.
T-Shirts retain volume leadership; Costumes hold the steepest expansion curve.
Material:
Cost tier stratification separates commodity synthetics from certified natural fibers and emerging biopolymers, with compliance burdens falling heaviest on skin-contact categories.
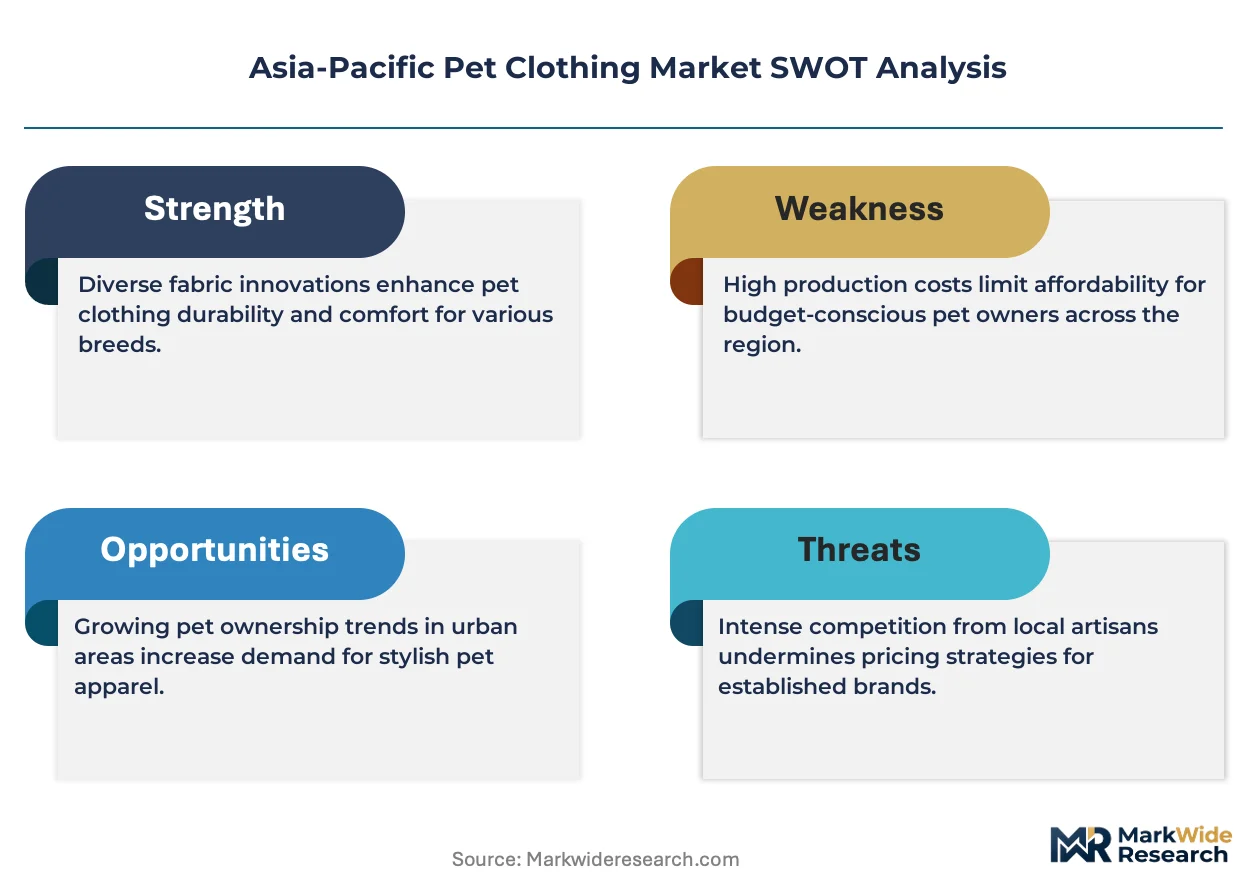
- Cotton:Ring-spun and combed varieties dominate direct-skin applications requiring GB 18401 Class A safety ratings. Zhengzhou Commodity Exchange price volatility subjects garment margins to agricultural commodity swings that polyester-focused competitors avoid.
- Polyester:Recycled PET filament yarns from Japanese and Korean suppliers support sustainability claims in premium channels. Osaka specialty mills now specify post-consumer content thresholds in procurement contracts.
- Nylon:High-tenacity filament constructions with DWR finishes serve monsoon rainwear across Ho Chi Minh City and Bangkok metropolitan zones. Abrasion resistance specifications exceed cotton alternatives for active outdoor use.
- Fleece:Brushed polyester and emerging PLA corn-starch blends compete for winter insulation share. Seoul-based pet boutiques increasingly specify biodegradable content, compressing margins for petroleum-based competitors unable to certify compostability.
Cotton retains volume leadership; PLA-enhanced Fleece holds the steepest expansion curve.
End User:
Channel concentration determines pricing power, with direct-to-consumer platforms capturing margin that wholesale-dependent segments forfeit to distributor tiers.
- Pet Owners:Millennial consumers in Shanghai and Beijing drive discretionary fashion spend through Tmall, JD.com, and Douyin storefronts. Real-time demand signals enable rapid style iteration for manufacturers with integrated design-to-retail capabilities.
- Retail Stores:Physical pet boutiques in Tokyo and Osaka require JIS L 1902 antimicrobial certification for hygiene claims, filtering out uncertified Chinese exporters. Third-party documentation delays create seasonal listing bottlenecks.
- Online Shoppers:Subscription-based wardrobe rental services in Shenzhen and Shanghai compress unit economics for traditional full-price sell-through models. Platform-managed logistics concentrate demand among urban millennials.
- Veterinarians:Post-surgical recovery garments and therapeutic compression wraps require medical-grade material specifications. SAMR oversight of veterinary device claims creates incremental compliance pathways distinct from general apparel.
Pet Owners retain volume leadership; Online Shoppers hold the steepest expansion curve.
Season:
Maturity gradients separate established temperate-climate staples from emerging climate-adaptive and occasion-driven categories with higher growth volatility.
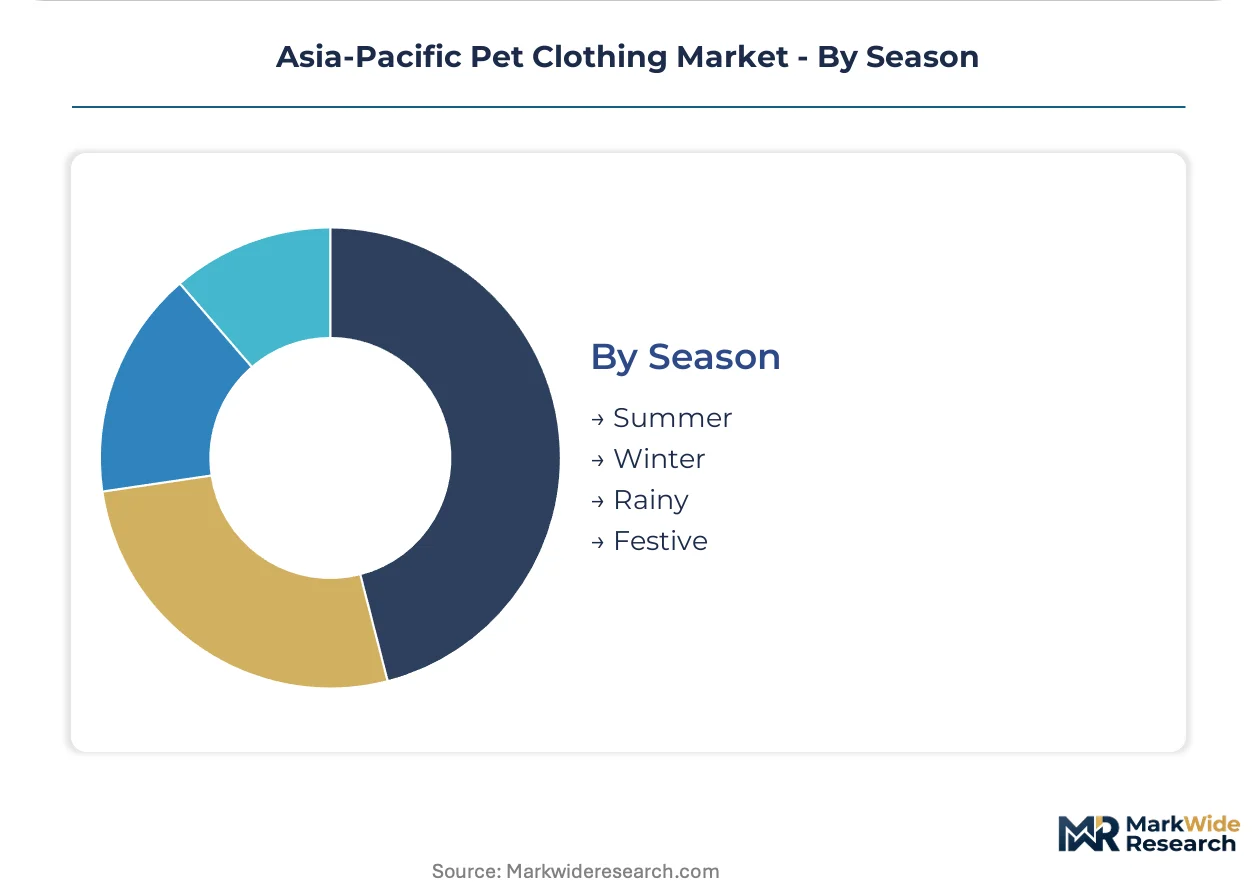
- Summer:Lightweight cotton-mesh cooling vests with evaporative properties address heat stress in Australian and Southeast Asian markets. Breathability specifications compete with simple shade-providing alternatives.
- Winter:Insulated coats and fleece layers generate predictable revenue spikes across northern China, Japan, and Korea. Thermal performance engineering now supersedes pure aesthetic differentiation as competitive advantage.
- Rainy:Nylon shell constructions with sealed seams serve monsoon climates across Vietnam, Thailand, and Philippines. Functional necessity limits price elasticity compared to discretionary fashion categories.
- Festive:Lunar New Year dragon costumes and Golden Week themed collections concentrate demand in compressed windows. Inventory misforecasting creates acute working capital exposure for manufacturers lacking demand-sensing partnerships.
Winter retains volume leadership; Festive holds the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Qingdao port complex anchors Asia-Pacific pet clothing export capacity, handling containerized textile shipments across the Yellow Sea corridor. Ningbo-Zhoushan and Shanghai Yangshan terminals supplement this maritime infrastructure for seasonal inventory cycles. Rail-sea intermodal links from interior manufacturing zones feed these coastal gateways.
China
Shanghai and Beijing millennial pet owners drive discretionary apparel spend through Tmall and Douyin storefronts. SAMR enforces GB 18401 textile safety standards restricting formaldehyde content in skin-contact fabrics. Qingdao Weichong Pet Products leverages Shandong province manufacturing density to dominate export-oriented production clusters.
Japan
Tokyo and Osaka pet boutiques demand JIS L 1902 antimicrobial certification for hygiene-claiming garments. METI coordinates quality benchmarks that filter uncertified Chinese imports from premium channels. Osaka specialty mills pioneered commercial-scale PLA fiber production for biodegradable winter lines.
South Korea
Seoul-based pet boutiques specify compostable content thresholds in procurement contracts for fleece garments. MFDS oversees textile safety notifications for imported pet-contact products. Busan-Ulsan manufacturing zones supply synthetic filament yarns to regional garment assemblers.
Vietnam
Ho Chi Minh City and Hanoi exhibit nascent pet humanization trends comparable to Shanghai circa 2018. The country's national standards body coordinates incremental compliance pathways for cross-border textile suppliers. Da Nang and Hai Phong port zones attract contract manufacturing investment from Chinese brands seeking tariff diversification.
Australia
Sydney and Melbourne pet owners generate cooling-vest demand addressing heat stress in companion animals. The TGA-equivalent national regulator monitors veterinary device claims for post-surgical recovery garments. Melbourne design studios source technical fabrics from regional Asian suppliers for climate-adaptive collections.
Asia-Pacific Pet Clothing Market Competitive Landscape
Listed leaders compete with private specialists across certification tier and channel access. Coastal Chinese manufacturers dominate export volume through Qingdao and Ningbo production density, while Japanese and Korean players anchor premium positioning through JIS and proprietary material standards. Three archetypes structure competition: vertically integrated fabricators controlling design-to-retail pipelines, specialized seasonal collection houses, and contract manufacturers serving private-label brands. Capacity expansion and direct-to-consumer platform integration represent the dominant competitive moves reshaping market access.
Among coastal Chinese fabricators, Qingdao Weichong Pet Products, Hangzhou Huayuan Pet Products, and Dongguan Hanyang Pet Products exemplify distinct strategic positioning. Qingdao Weichong occupies a scale-driven export archetype leveraging Shandong province manufacturing infrastructure. Hangzhou Huayuan represents the integrated design-to-retail model serving domestic e-commerce channels. Dongguan Hanyang sits within the Pearl River Delta contract manufacturing tier supplying seasonal volume to platform brands. Zephyr Inc. (iDog & iCat) anchors premium-tier positioning through specialized collection architecture. YiWu OuYe Accessories exemplifies the accessories-specialist archetype concentrated in Zhejiang province trading hubs.
| Leading Market Players |
|---|
| Qingdao Weichong Pet Products |
| YiWu OuYe Accessories |
| Dongguan Hanyang Pet Products |
| Bestone Inc. |
| Ruian Weihui Clothes |
| Zephyr Inc. (iDog & iCat) |
| Hangzhou Huayuan Pet Products |
| OKEYPETS |
| Vixen Aim |
| Others |
Pricing and Supply Chain Analysis
Biodegradable PLA fiber substitution for petroleum-based polyester fleece is simultaneously relocating procurement gravity toward Osaka specialty mills and compressing margin structures for manufacturers lacking compostability certification. This material transition reshapes both upstream sourcing patterns and downstream pricing power across the Asia-Pacific Pet Clothing Market.
Pricing Analysis
Volume-discount tiering structures separate Qingdao Weichong Pet Products' export-scale contracts from Hangzhou Huayuan's domestic e-commerce spot pricing. Three-tier pricing structure across premium JIS-certified, standard GB 18401-compliant, and economy non-certified levels captures quality differentiation. Pricing pressure stems from cotton futures volatility on the Zhengzhou Commodity Exchange. Tier-two city pet owners exhibit highest price sensitivity; Tokyo boutique buyers demonstrate lowest elasticity.
Supply Chain Analysis
Inventory velocity compression around Lunar New Year and Golden Week costume demand spikes forces working capital intensity on manufacturers lacking demand-sensing partnerships. Manufacturing concentrates in China's Shandong and Zhejiang provinces, with Japanese Osaka mills supplying specialty PLA fibers. Raw material dependencies center on Zhengzhou cotton futures, Korean recycled PET filament, and corn-starch PLA derivatives. Single-source vulnerability concentrates in Osaka's biodegradable fiber production. Distribution runs through Qingdao and Ningbo port complexes feeding Tmall and JD.com fulfillment networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Asia-Pacific Pet Clothing Market sits in cyclical recovery as seasonal inventory cycles normalize following pandemic-era demand distortions. Monsoon-driven rainwear demand across Southeast Asian metropolitan zones provides predictable revenue baselines stabilizing manufacturer capacity planning.
For Market Incumbents: Compound defensive positioning through backward integration into Shandong province textile dyeing facilities and captive GB 18401 certification laboratories. Accelerate seasonal collection turnover velocity to match Shanghai millennial pet owner fashion-cycle expectations. Absorb textile chemist talent scarcity by establishing partnerships with legacy human apparel hub technical institutes.
For New Entrants and Emerging Players: GB 18401 fast-track certification partnerships with Qingdao testing laboratories enable rapid market entry ahead of seasonal collection windows. Penetrate Vietnam's Ho Chi Minh City and Hanoi urban markets where pet humanization trends mirror Shanghai circa 2018. Launch direct-to-consumer Douyin storefronts bypassing tiered distributor margins.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed coastal Chinese fabricators controlling Qingdao-Ningbo export infrastructure. Five-to-ten year viability hinges on certification-tier migration toward JIS and emerging biodegradable standards. Monitor PLA fiber procurement contract volumes as inflection indicator for premium channel positioning.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Dyeing Facilities | Shandong province captive GB 18401 compliance reduces third-party testing delays and margin leakage. |
| Direct-to-Consumer Platform Launch | Tmall and Douyin storefronts capture real-time demand signals from Shanghai millennial pet owners. |
| JIS Certification Investment | Osaka and Tokyo boutique channel access commands defensible pricing premiums for compliant suppliers. |
| Biodegradable Material Transition | PLA fiber adoption aligns with Seoul pet boutique procurement specifications and compostability claims. |
| Vietnam Market Entry | Ho Chi Minh City first-mover positioning captures nascent pet humanization comparable to Shanghai 2018. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across primary interview programs with pet apparel brand managers, e-commerce platform category buyers, textile compliance officers at SAMR-registered laboratories, and Osaka specialty mill procurement directors. Secondary validation drew from Chinese customs textile export records, JD.com and Tmall category transaction data, JIS L 1902 antimicrobial testing protocol documentation, and Zhengzhou Commodity Exchange cotton futures disclosures. Bottom-up SKU-level demand modeling and top-down regional consumption estimates were triangulated to ensure consistency.
Across the projection horizon, the analytical framework segmented volume and value outputs by product type, material specification, end-user channel, and seasonal demand pattern. CAGRs were derived from regression analysis against pet ownership density, urban disposable income trends, and regulatory compliance cost trajectories. Forecast inputs incorporated monsoon rainfall patterns for Southeast Asian rainwear demand and Lunar New Year calendar positioning for costume inventory cycles.
Decision-makers should treat outputs as directional under assumptions of stable GB 18401 enforcement intensity and continued millennial pet humanization in tier-one Chinese cities; material deviation in regulatory timelines or consumer sentiment would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pet Care Products
Pet Collar Market
Pet Care Products
Dog Litter Boxes Market
Pet Care Products
Cat Scratchers and Trees Market
Pet Care Products
Germany Pet Training Services Market
Pet Care Products
Plant-Based Dog Food Market
Pet Care Products
Pet Dental Health Market
Pet Care Products
South Korea Pet Food Market
Pet Care Products
Disposable Absorbent Pet Pad Market
Pet Care Products
Kitten Milk Replacer and Formula Market
Pet Care Products
Pet Oral Care Market
Pet Care Products
Dog Safety Leash Market
Pet Care Products
Pet Car Seat Market
Pet Care Products
Dog Seat Belt Market
Pet Care Products
North America Pet Food Market
Pet Care Products
Pet Grooming Gloves Market
Pet Care Products
North America Pet Treats Market